
 Middle-East and Africa Paper Cups Market | 2026-2036
Middle-East and Africa Paper Cups Market Size, Share, and Industry Trends Forecast 2026-2036
Middle-East and Africa Paper Cups Market Foresight
Food-grade polyethylene-lined specification tiers is bifurcating the Middle-East and Africa paper cups landscape into performance-differentiated supply layers. Hotpack Packaging Industries LLC leverages integrated converting and printing capabilities across its UAE manufacturing footprint to secure institutional catering contracts. Huhtamaki Oyj anchors its regional position through cold-chain compatible cup designs that sustain beverage integrity during Gulf summer distribution. Detpak South Africa specializes in quick-turn custom print runs that dominate the Cape Town and Johannesburg event circuits.
Middle-East and Africa paper cups are cylindrical liquid-holding containers fabricated from bleached or unbleached kraft paperboard, typically laminated with polyethylene or polylactic acid barriers to prevent leakage and maintain thermal performance across temperature differentials exceeding sixty degrees Celsius. Hot cups and cold cups represent the dominant product type categories, with double-wall constructions capturing expanding margin pools in premium café channels across Dubai and Riyadh. Application segmentation clusters heavily around restaurants and cafes, where takeaway volume growth and dine-in restriction legacies have permanently shifted consumption patterns toward disposable serviceware.
Saudi Food and Drug Authority packaging contact-material standards, UAE Ministry of Climate Change and Environment circular economy directives, and South Africa's extended producer responsibility regulations collectively reshape material compliance requirements across the value chain. Biodegradable paper and coated paper material segments face divergent certification burdens that filter market access for smaller converters. Stakeholders must monitor evolving compostability labeling mandates and polymer-ban schedules to align capacity investments with enforceable compliance timelines rather than voluntary sustainability pledges.
Market Dynamics
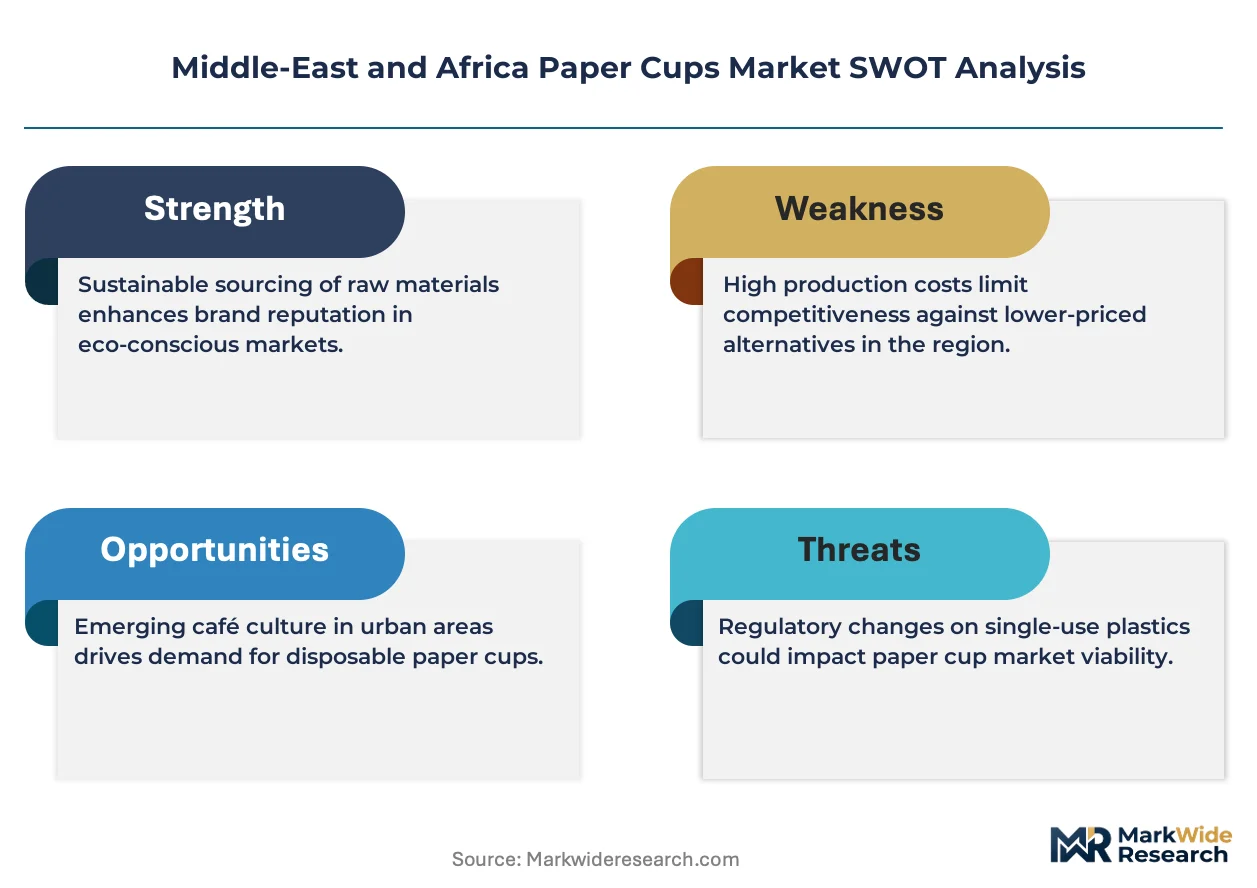
Single-use plastic prohibitions across Gulf Cooperation Council jurisdictions and South Africa are forcing food-service operators to re-source liquid containment formats, compressing substitution timelines for fiber-based alternatives.
Growth Catalysts
- Extended Producer Responsibility mandates:South Africa's Department of Forestry, Fisheries and the Environment has tightened enforcement timelines, redirecting institutional procurement toward certified fiber serviceware.
- Quick-service restaurant cold-beverage expansion:Drive-through and takeaway formats across Saudi Arabia and UAE are absorbing disproportionate volumes of polyethylene-lined cold cups.
- Event-grade branded cup demand:Saudi Arabia's entertainment sector growth is generating concentrated orders for custom-print, double-wall constructions.
Market Restraints
- Pulp and polymer input cost volatility:Bleached kraft paperboard and food-grade polyethylene resin prices fluctuate with energy benchmarks, squeezing converter margins.
- Converter concentration in UAE industrial zones:A disproportionate share of regional converting capacity clusters in Dubai and Sharjah free zones, creating geographic supply risk.
- Compostable barrier performance gaps:Polylactic acid linings exhibit inferior thermal stability above sixty degrees Celsius, limiting hot-beverage application scope.
Strategic Opportunities
- Nigeria and Kenya quick-service penetration:Underdeveloped cold-chain takeaway infrastructure in Sub-Saharan Africa presents first-mover positioning for insulated cup formats.
- UAE Ministry of Climate Change and Environment circular economy directives:Mandatory recycled-content thresholds create preferential market access for converters with integrated recycling streams.
- Digital print-on-demand integration:Short-run variable printing is collapsing minimum order quantities for event and hospitality segments.
Industry Challenges
- Food-contact certification timeline compression:Saudi Food and Drug Authority approval cycles for new barrier formulations lag capacity investment decisions.
- Skilled converting technician scarcity:High-speed flexographic press operation and precision die-cutting expertise concentrate in UAE and South Africa, constraining expansion elsewhere.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle-East and Africa Paper Cups Market |
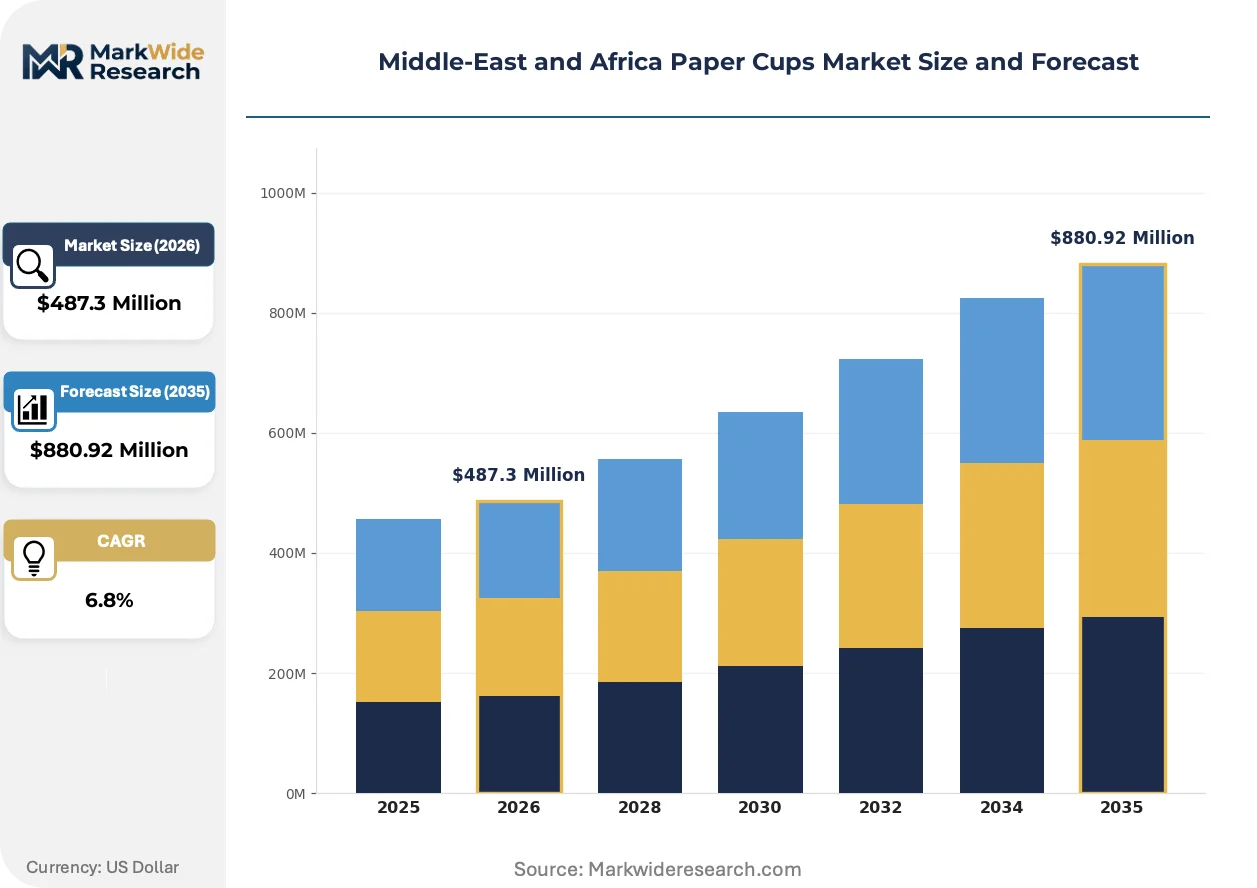
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $880.92 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hot Cups, Cold Cups, Double Wall Cups, Paper Lids Application: Cafes, Restaurants, Events, Retail Outlets Material: Coated Paper, Recycled Paper, Biodegradable Paper, Composite Materials End User: Food Service, Catering, Event Management, Retail |
| Companies Covered | Hotpack Packaging Industries LLC, Huhtamaki Oyj, Graphic Packaging International LLC, Detpak South Africa (Pty) Ltd, Gulf East Paper & Plastic Industries LLC, ENPI, Golden Paper Cups Manufacturing LLC, Maimoon Papers Industry LLC, SAQR Pack, Others |
| Regions Covered | Africa: South Africa, Nigeria, Egypt, Kenya, Morocco, Ethiopia, Ghana, Algeria, Rest of Africa |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle-East and Africa Paper Cups Market Shifts & Advancements
Barrier material evolution and regulatory compliance automation are compressing product development cycles while fragmenting specification tiers across temperature-performance requirements.
Water-based barrier coatings are bifurcating the hot-cup segment into performance-differentiated supply layers. Quick-service chains in Dubai and Riyadh are piloting aqueous-coated double-wall constructions for beverages exceeding seventy degrees Celsius. This technology is bifurcating procurement into premium thermal-performance tiers versus standard polyethylene-lined specifications.
UAE Ministry of Climate Change and Environment extended producer responsibility frameworks now mandate blockchain-tracked recycling certificates for imported paperboard. Converters must integrate digital compliance documentation into supply chain workflows. Hot-cup categories face the steepest certification burden due to multi-layer barrier complexity.
Centralized procurement consolidation among Gulf hospitality groups is displacing fragmented distributor purchasing. Large hotel operators in Saudi Arabia and UAE now contract directly with converting facilities for custom-branded event inventory. This pattern concentrates volume with integrated printing-converting operations in Sharjah and Johannesburg industrial corridors.
Middle-East and Africa Paper Cups Market Segmentation
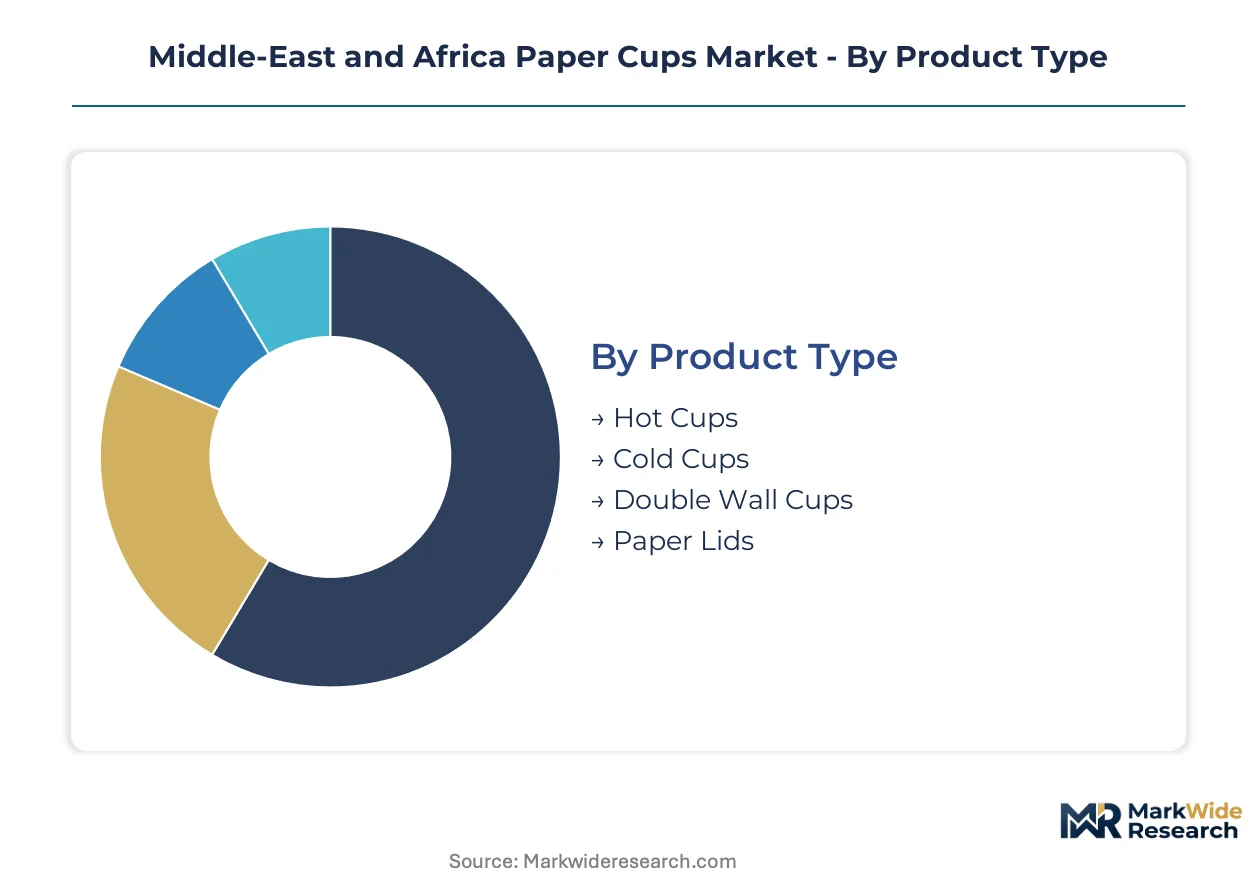
Paper cup procurement across the Middle-East and Africa fragments across temperature performance requirements, regulatory compliance tiers, and branded versus generic volume channels. Specification differentiation determines converter capability requirements and margin capture potential.
Product Type:
Domestic consumption concentrates in hot and cold single-wall formats across Saudi Arabia and UAE food courts, while double-wall exports serve premium hospitality contracts in European and Asian markets.
- Hot Cups:Single-wall constructions with polyethylene or aqueous barrier coatings handle beverages exceeding sixty degrees Celsius. Saudi quick-service chains absorb the bulk of regional volume as dine-in restrictions have permanently shifted consumption patterns toward takeaway formats.
- Cold Cups:Thinner caliper paperboard with high-grade polyethylene linings prevents condensation leakage during Gulf summer distribution. UAE drive-through beverage expansion has compressed substitution timelines from plastic to fiber-based alternatives.
- Double Wall Cups:Insulated air-gap constructions command premium positioning in Dubai and Riyadh café channels.
- Paper Lids:Emerging specification tier facing fit-compatibility standardization challenges across cup diameter variations.
Hot cups command the established base. The steepest expansion runs through double-wall formats.
Application:
Cost-tier stratification separates high-volume institutional contracts from event-grade custom print specifications with radically different margin profiles.
- Cafes:Premium double-wall and custom-print single-wall specifications dominate Dubai's specialty coffee corridor, where branded cup visibility functions as mobile advertising.
- Restaurants:Quick-service chains across Saudi Arabia and UAE standardize on polyethylene-lined cold cups for drive-through beverage programs. Procurement consolidation among Gulf hospitality groups has displaced fragmented distributor purchasing.
- Events:Short-run custom print requirements concentrate in Johannesburg and Cape Town corporate circuits.
- Retail Outlets:Generic unbranded specifications serve convenience store and petrol station channels.
Restaurant channels anchor volume scale. The fastest volume gains are materializing in event applications.
Material:
Regulatory burden divergence across South Africa's extended producer responsibility framework and UAE circular economy directives is filtering market access by certification tier.
- Coated Paper:Polyethylene-laminated kraft paperboard remains the workhorse specification across hot and cold applications. Saudi Food and Drug Authority contact-material standards impose the steepest compliance burden on multi-layer barrier constructions.
- Recycled Paper:UAE Ministry of Climate Change and Environment mandates blockchain-tracked recycling certificates for imported paperboard, favoring converters with integrated recycling streams.
- Biodegradable Paper:Polylactic acid linings face thermal stability constraints above sixty degrees Celsius.
- Composite Materials:Emerging barrier formulations await Saudi Food and Drug Authority approval cycle completion.
Coated paper retains the volume base. The certification-driven transition is accelerating most quickly through recycled-content specifications.
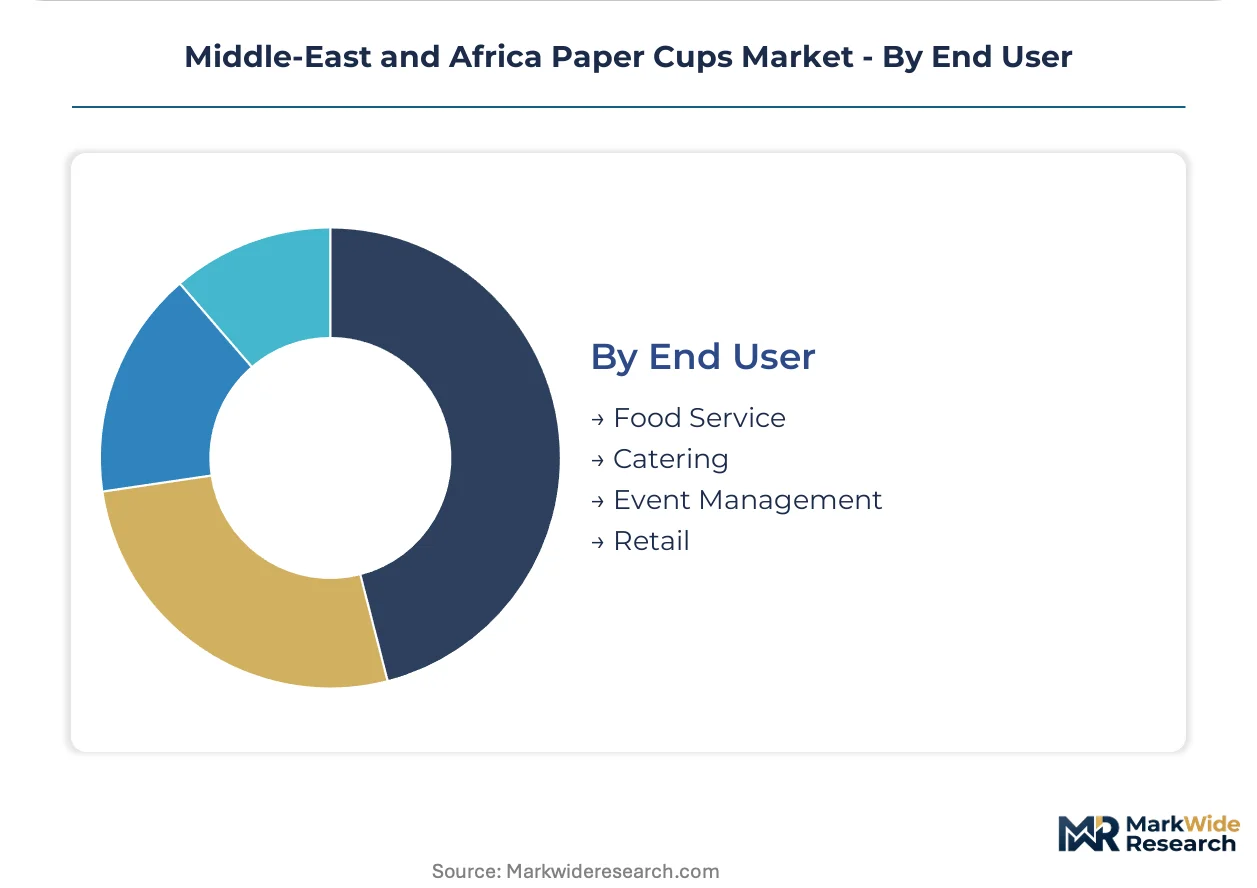
End User:
Customer-type concentration determines order frequency, minimum run lengths, and printing complexity requirements across the converting base.
- Food Service:High-frequency, standardized specifications dominate procurement across Saudi and UAE quick-service chains. Centralized contracting with integrated printing-converting operations in Sharjah industrial corridors has concentrated volume.
- Catering:Institutional contracts in South Africa redirect toward certified fiber serviceware under Department of Forestry, Fisheries and the Environment enforcement tightening.
- Event Management:Short-run variable printing requirements dominate Cape Town and Johannesburg circuits.
- Retail:Low-margin, high-volume generic specifications serve supermarket and convenience channels.
Food service commands the established procurement base. Event management is climbing the fastest as Saudi entertainment sector expansion generates concentrated orders for custom-print inventory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Import dependency for bleached kraft paperboard concentrates purchasing leverage among UAE and Saudi converters, while South Africa's integrated pulp operations supply neighboring markets with coated grades. Export flows from Sharjah industrial corridors reach East African quick-service chains, though logistics costs erode margin capture.
Saudi Arabia
Entertainment sector expansion at Riyadh Boulevard and Jeddah Season generates concentrated demand for custom-print double-wall event cups. The Saudi Food and Drug Authority enforces strict packaging contact-material standards that filter barrier formulation approvals. Converting capacity clusters in Riyadh's Second Industrial City where integrated printing operations serve hospitality procurement consolidation.
United Arab Emirates
Dubai's specialty coffee corridor and Abu Dhabi drive-through beverage expansion absorb disproportionate cold-cup volumes during summer distribution peaks. The Ministry of Climate Change and Environment mandates blockchain-tracked recycling certificates for imported paperboard. Sharjah free zones host the region's densest converting concentration, with flexographic press operations supplying Gulf Cooperation Council quick-service chains.
South Africa
Cape Town and Johannesburg event circuits dominate short-run custom print requirements for corporate hospitality. The Department of Forestry, Fisheries and the Environment has accelerated extended producer responsibility enforcement timelines. Durban's paperboard import terminals feed converting operations in Gauteng industrial corridors that redirect institutional procurement toward certified fiber serviceware.
Nigeria
Lagos quick-service penetration and underdeveloped cold-chain takeaway infrastructure create first-mover positioning for insulated cup formats. The country's national environmental regulator is drafting single-use plastic restriction frameworks modeled on South African precedents. Apapa port congestion forces converters to maintain higher paperboard safety stocks, elevating working capital requirements.
Kenya
Nairobi's café culture expansion and Mombasa hospitality investment generate demand for premium double-wall specifications. The National Environment Management Authority enforces plastic bag prohibitions that signal fiber-based substitution pathways. Industrial converting capacity concentrates in Athi River special economic zone where logistics connectivity serves East African distribution.
Middle-East and Africa Paper Cups Market Competitive Landscape
Listed leaders compete with private specialists across integrated converting-printing capabilities, creating tiered competitive dynamics. Gulf-based family-owned operations anchor volume contracts through proximity to hospitality procurement consolidation, while Nordic-listed multinationals supply cold-chain compatible specifications. Two strategic archetypes dominate: integrated converting-printing facilities capturing event-grade custom work, and scale-driven polyethylene-lined volume producers serving quick-service standardization. Capacity expansion and direct hospitality contracting represent the dominant competitive moves, displacing fragmented distributor intermediation.
Within the integrated converting tier, Hotpack Packaging Industries LLC and Gulf East Paper & Plastic Industries LLC exemplify UAE-based private specialists leveraging Sharjah industrial corridor positioning. Huhtamaki Oyj represents the listed multinational archetype with Nordic-origin structure. Detpak South Africa occupies a position bridging custom print specialization with Cape Town-Johannesburg event circuit proximity.
| Leading Market Players |
|---|
| Hotpack Packaging Industries LLC |
| Huhtamaki Oyj |
| Graphic Packaging International LLC |
| Detpak South Africa (Pty) Ltd |
| Gulf East Paper & Plastic Industries LLC |
| ENPI |
| Golden Paper Cups Manufacturing LLC |
| Maimoon Papers Industry LLC |
| SAQR Pack |
| Others |
Supply & Pricing Matrix
UAE Ministry of Climate Change and Environment blockchain-tracked recycling certificates gate both supplier qualification and price differentiation simultaneously, compressing market access for uncertified converters while rewarding integrated operators with preferential contract terms. This certification layer bifurcates procurement into premium verified-content tiers versus standard polyethylene-lined specifications.
Pricing Analysis
Industrial OEM buyers anchor a contract-based pricing structure across food-service procurement channels. Price differentiation rests on certification grade and volume scale, with blockchain-verified recycled-content specifications commanding measurable premiums over standard grades. Cost compression in single-wall commodity tiers is intensifying because bleached kraft paperboard and polyethylene resin prices fluctuate with energy benchmarks. Quick-service chains exhibit the highest price sensitivity, while event-grade hospitality buyers prioritize custom-print capabilities over unit economics.
Supply Chain Analysis
Strategic stockpile preferences dominate converter behavior given Apapa port congestion and seasonal pulp price volatility, elevating working capital requirements above just-in-time norms. Geographic supply concentration centers on UAE, Saudi Arabia, and South Africa, with Sharjah free zones hosting the densest converting capacity. Raw material dependencies draw from bleached kraft paperboard imports, food-grade polyethylene resin, and aqueous barrier coating formulations. Single-source vulnerability concentrates in UAE industrial zones where a disproportionate share of regional converting capacity clusters. Distribution runs through direct hospitality contracting that displaces fragmented distributor intermediation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents an early-cycle expansion story driven by Gulf Cooperation Council single-use plastic prohibitions redirecting food-service procurement toward fiber-based alternatives with permanent consumption pattern shifts.
For Market Incumbents: Fortify integrated converting-printing capabilities in Sharjah and Johannesburg industrial corridors against emerging aqueous-coated barrier specialists. Backward integration into blockchain-tracked recycling streams secures preferential UAE Ministry of Climate Change and Environment compliance positioning. Capacity addition in Riyadh's Second Industrial City captures Saudi entertainment sector procurement consolidation. For New Entrants and Emerging Players: Lead with insulated double-wall formats targeting Nigeria and Kenya quick-service penetration where cold-chain takeaway infrastructure remains underdeveloped. Sub-Saharan African markets present the most penetrable geography given first-mover positioning for thermal-performance specifications. A direct contracting model with Gulf hospitality groups bypasses distributor intermediation entirely. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across aqueous barrier coating technology adoption, favoring scaled operators with R&D absorption capacity. Long-term viability across the analysis window hinges on certification-automation infrastructure rather than commoditized polyethylene-lined volume. Acquisition targets should display integrated recycling streams and digital compliance documentation workflows. The signal to watch is Saudi Food and Drug Authority approval cycle compression for novel barrier formulations.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Recycling Streams | Blockchain-tracked certificates secure preferential UAE circular economy compliance positioning. |
| Aqueous Barrier Coating Scale-Up | Thermal-performance differentiation captures premium quick-service procurement in Dubai and Riyadh. |
| Direct Hospitality Contracting | Centralized procurement consolidation displaces fragmented distributor intermediation across Gulf markets. |
| Digital Print-on-Demand Integration | Short-run variable printing collapses minimum order quantities for event and hospitality segments. |
| Sub-Saharan African Market Entry | First-mover positioning in Nigeria and Kenya quick-service channels leverages infrastructure gaps. |
Research Methodology
Desk research of customs and trade data, industry association filings, and regulatory gazettes preceded structured interviews with converting facility operations managers, quick-service chain procurement directors, hospitality group sustainability officers, and paperboard import terminal logistics coordinators. Primary fieldwork combined with secondary validation from Saudi Food and Drug Authority packaging standards documentation, UAE Ministry of Climate Change and Environment circular economy directives, and South Africa Department of Forestry, Fisheries and the Environment enforcement timelines. Bottom-up volume modeling and top-down value reconciliation provided cross-check triangulation.
Variance decomposition across the projection horizon isolates segment-specific growth contributions from temperature-performance requirements, regulatory compliance tiers, and branded versus generic volume channels. The analytical framework models product type, application, material certification grade, and end-user concentration dimensions throughout the forecast period. CAGRs derive from trend-line extrapolation adjusted for policy inflection points and adoption curve positioning. Forecast inputs incorporate seasonal pulp price volatility patterns and entertainment sector event calendar concentration.
Forecasts assume regulatory continuity in Saudi Food and Drug Authority contact-material standards, UAE circular economy directives, and South Africa extended producer responsibility frameworks; material policy shifts would require re-modeling. Specific risk factors include compostable barrier performance gaps above sixty degrees Celsius and converter concentration geographic supply risk. Revision becomes warranted when polylactic acid thermal stability thresholds or blockchain certification mandate timelines cross implementation thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Containers
Food Grade Bottles Market
Packaging Containers
North America Food Cans Market
Packaging Containers
VCI Bags Market
Packaging Containers
Tamper Evident Pots and Tubs Market
Packaging Containers
Bottles Market
Packaging Containers
Europe Punnet Trays Market
Packaging Containers
Child Resistant Bottles Market
Packaging Containers
Clamshell Packaging Market
Packaging Containers
Mini Refillable Spray Dispenser Market
Packaging Containers
Chalk Boxes Market
Packaging Containers
Pillow Pack Packaging Market
Packaging Containers
Snap Single Dose Dispensers Market
Packaging Containers
Double Seam Bowl Market
Packaging Containers
Middle East and Africa Aerosol Cans Market
Packaging Containers
Custom Boxes Market
Packaging Containers
Dispensing Trays Market