
 Membrane Boxes Market | 2026-2036
Membrane Boxes Market Size, Share, and Industry Trends Forecast 2026-2036
Membrane Boxes Market Foresight
Polypropylene is broadening its addressable role in membrane box construction as manufacturers phase out legacy polyvinyl chloride formulations to meet stricter halogen-free mandates. Placon leverages captive extrusion capabilities to control resin grade consistency across its North American plants. Gel-Pak anchors its position through membrane elasticity patents that reduce die breakage during automated pick-and-place operations. Ted Pella specializes in anti-static surface treatments for electron microscopy specimen transport, a niche where technical specification rigor commands premium positioning.
Membrane boxes are precision-engineered containers employing elastomeric films suspended within rigid frames to immobilize delicate components against shock and particulate contamination during handling and shipment; typical constructions specify membrane thickness between 0.3 mm and 1.2 mm with Shore A hardness ratings of 40–60 to balance retention force against release ease. Multi-layer membrane configurations currently lead unit economics due to their adaptability across varying component geometries, while customized formats represent the fastest-expanding margin pool as aerospace OEMs demand lot-traceable, cleanroom-certified packaging protocols. Electronics end users sustain the largest volume absorption, though automotive qualification timelines for electric powertrain chips are compressing and pulling forward membrane box specification upgrades.
EPA hazardous substance labeling requirements and OSHA workplace exposure limits govern material selection and worker handling protocols for membrane box manufacturing facilities in the United States, while REACH substance restrictions in Europe constrain phthalate plasticizer use across imported packaging. China's GB standards for electronic product packaging, administered by SAMR, increasingly reference IEC moisture sensitivity level classifications that membrane box suppliers must validate through preconditioning cycle testing. Stakeholders should monitor how dual carbon goals in China and the EU Green Deal's packaging waste directives converge to mandate recycled content thresholds that could disqualify conventional virgin polymer supply chains.
Market Dynamics
Semiconductor packaging roadmaps are compressing qualification cycles for contamination-controlled transport, forcing membrane box suppliers to synchronize product development with foundry tape-out schedules rather than traditional packaging procurement timelines.
Growth Catalysts
- Domestic chip fabrication expansion:China's SAMR-administered GB standards for electronic product packaging are accelerating procurement of IEC-validated membrane boxes as local foundries scale advanced node production.
- REACH substance restrictions:ECHA-mandated phthalate plasticizer bans across Europe are pulling demand toward halogen-free polypropylene membrane formulations that suppliers with captive extrusion capabilities can certify.
- Electric powertrain chip qualification:Automotive OEMs are compressing membrane box specification timelines to match faster electric vehicle powertrain semiconductor validation cycles.
Market Restraints
- Resin grade consistency requirements:Virgin polymer supply chains face disqualification risk as China's dual carbon goals and the EU Green Deal's packaging waste directives converge on recycled content thresholds.
- Specialized elastomer film supply:Membrane elasticity patents held by incumbent suppliers create concentrated control over Shore A hardness specifications between 40 and 60.
- Preconditioning cycle testing costs:IEC moisture sensitivity level validation requirements impose capital-intensive equipment burdens on smaller membrane box manufacturers.
Strategic Opportunities
- Anti-static surface treatment specialization:Electron microscopy specimen transport represents a premium niche where technical specification rigor commands pricing power above standard electronics packaging.
- Lot-traceable cleanroom certification:Aerospace OEM procurement protocols are creating margin pools for membrane box suppliers that can document chain-of-custody through cleanroom-certified production.
- Automated pick-and-place integration:Die breakage reduction through membrane elasticity optimization is opening specification windows with semiconductor assembly equipment manufacturers.
Industry Challenges
- Halogen-free formulation transitions:Manufacturers phasing out legacy polyvinyl chloride face reformulation timelines that must align with customer qualification schedules.
- Multi-layer membrane customization complexity:Adaptability across varying component geometries requires flexible production lines that strain capex planning for mid-cap suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Membrane Boxes Market |
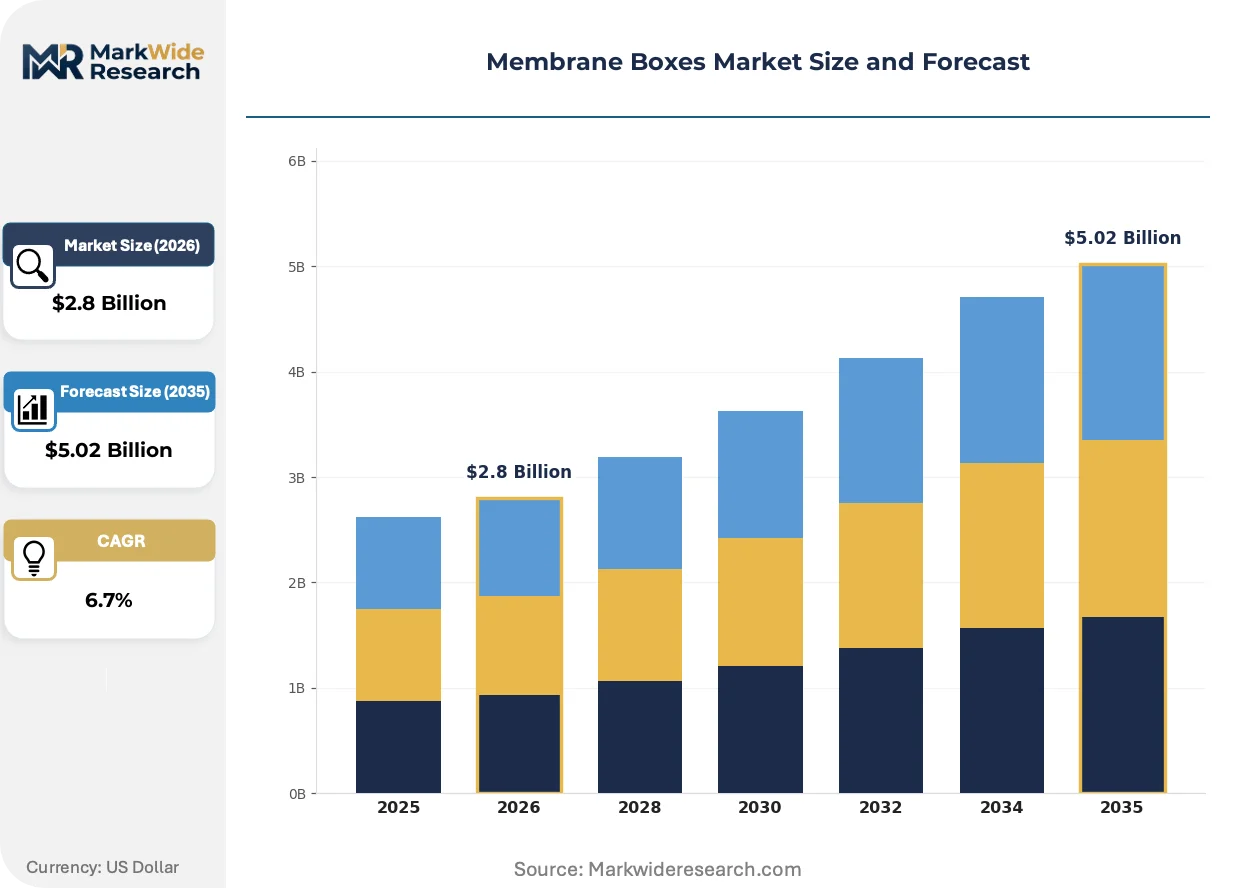
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.02 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-Layer, Multi-Layer, Hybrid, Customized Material: Polypropylene, Polyvinyl Chloride, Polyester, Polystyrene End User: Manufacturing, Automotive, Electronics, Aerospace Distribution Channel: Online, Direct Sales, Distributors, Retail |
| Companies Covered | Placon, 3M, Ted Pella, Gel-Pak, SST International, GilPak, Teca-Print, SPI Supplies, Structure Probe, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Membrane Boxes Market Shifts & Advancements
Membrane box engineering is pivoting from standardized catalog formats toward application-specific configurations that embed traceability and environmental compliance into the product architecture itself.
Multi-layer membrane configurations are decentralizing procurement patterns across semiconductor packaging supply chains. Advanced node foundries in Taiwan and South Korea are specifying custom membrane thickness gradients between 0.3 mm and 1.2 mm to match die fragility profiles. This specification fragmentation is decentralizing volume concentration away from single-source catalog suppliers toward regional contract manufacturers with rapid lamination capabilities.
REACH substance restrictions are tightening material standards for electronic component transport across European import channels. ECHA's evolving candidate list for Substances of Very High Concern is forcing reformulation of plasticizer systems in membrane elastomers. Electronics end users with EU distribution exposure are responding by auditing supplier certificates of compliance before contract renewal.
Automotive qualification timelines are compressing membrane box development cycles from historical packaging procurement norms. Electric powertrain chip suppliers are bypassing traditional distributor channels to engage membrane box manufacturers directly for co-development programs. This pattern is most visible in Germany and China where automotive OEMs have established dedicated semiconductor packaging engineering teams.
Membrane Boxes Market Segmentation
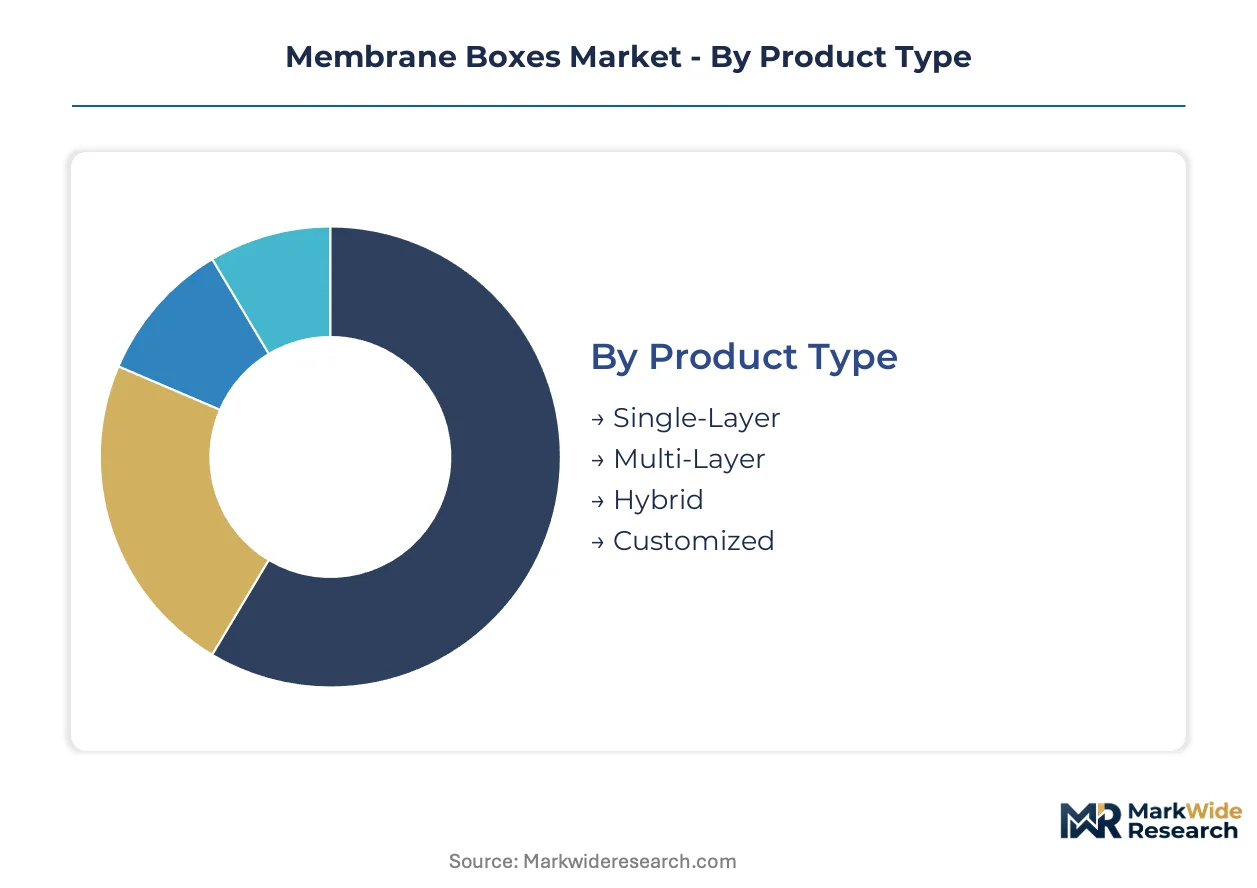
Membrane box segmentation reflects divergent technical requirements across semiconductor packaging, automotive qualification, and aerospace traceability protocols. Specification fragmentation is accelerating as foundries demand customized membrane thickness gradients matched to die fragility profiles.
Product Type:
Membrane layer architecture determines retention force calibration and release mechanics for automated handling systems.
- Multi-Layer:Laminated elastomeric films with graduated Shore A hardness enable adaptable retention across varying component geometries. Electronics manufacturers in Taiwan and South Korea specify custom thickness gradients between 0.3 mm and 1.2 mm for advanced node die handling.
- Customized:Lot-traceable configurations with cleanroom-certified production protocols command premium positioning. Aerospace OEM procurement in Germany and the United States mandates chain-of-custody documentation through qualified membrane box suppliers.
- Single-Layer:Standardized 0.5 mm membrane constructions serve catalog procurement for legacy semiconductor packaging.
- Hybrid:Composite frames combining rigid structural elements with localized elastomeric suspension zones.
Multi-Layer leads on scale; Customized leads on momentum.
Material:
Polymer selection balances halogen-free compliance mandates against extrusion consistency requirements.
- Polypropylene:Captive extrusion capabilities enable resin grade consistency certification for REACH-compliant supply chains. European electronics distributors audit supplier certificates of compliance before contract renewal under ECHA-mandated phthalate restrictions.
- Polyvinyl Chloride:Legacy formulations face phase-out timelines as manufacturers reformulate to meet halogen-free mandates. Reformulation schedules must synchronize with customer qualification cycles.
- Polyester:Anti-static surface treatment compatibility supports electron microscopy specimen transport applications.
- Polystyrene:Rigid frame integration for cost-sensitive catalog formats in standard semiconductor packaging.
Polypropylene captures expanding share; Polyester climbs fastest in premium niches.
End User:
Application-specific qualification protocols fragment procurement patterns across membrane box specifications.
- Electronics:Semiconductor packaging roadmaps compress contamination-controlled transport qualification cycles. Foundry tape-out schedules now govern membrane box development timelines rather than traditional packaging procurement norms.
- Automotive:Electric powertrain chip suppliers engage membrane box manufacturers directly for co-development programs. OEM engineering teams in Germany and China bypass distributor channels to accelerate validation cycles.
- Aerospace:Cleanroom-certified production with lot traceability commands specification premiums above standard electronics packaging.
- Manufacturing:General industrial component handling with standardized catalog formats and volume pricing.
Electronics dominates volume absorption; Automotive gains share fastest.
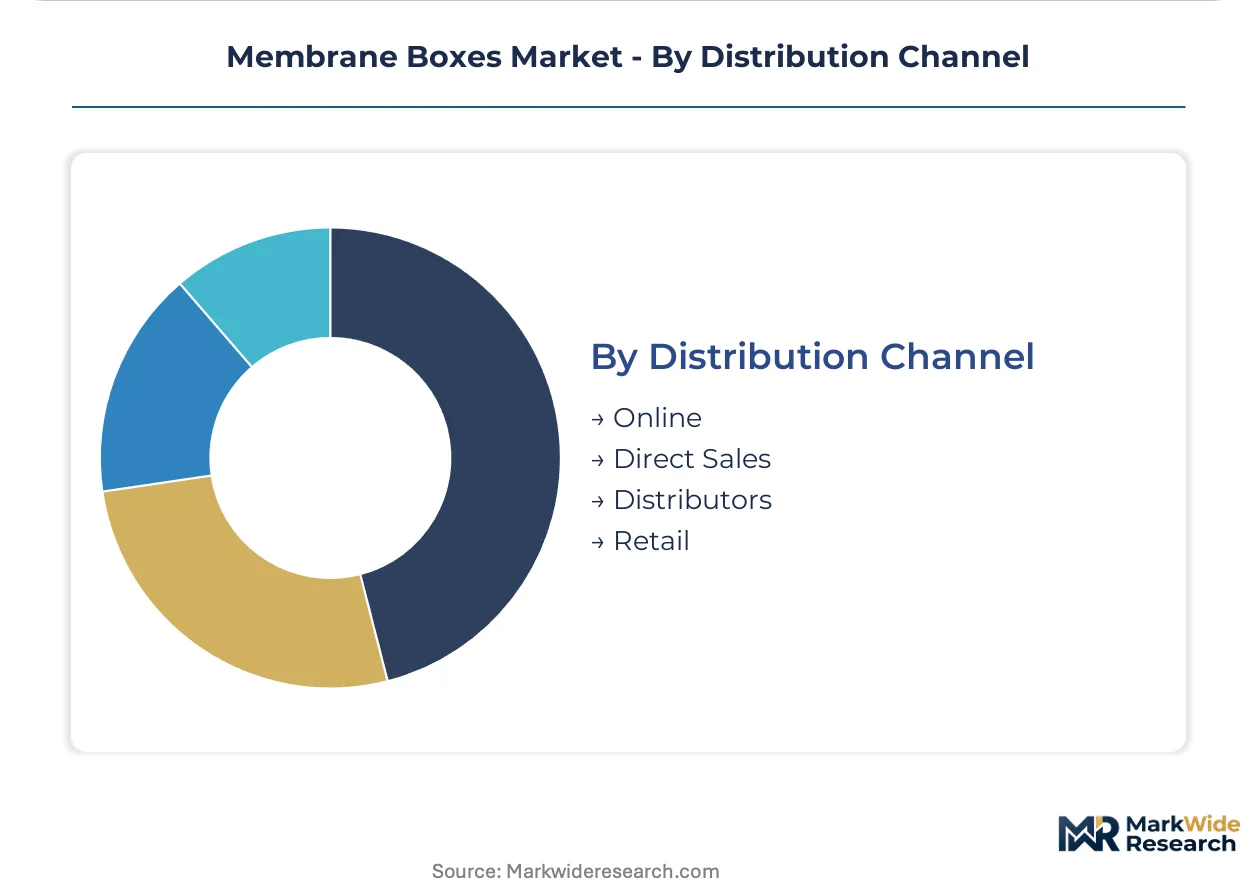
Distribution Channel:
Channel configuration reflects specification complexity and qualification timeline compression.
- Direct Sales:Co-development programs with automotive and aerospace OEMs require technical specification collaboration. Engineering teams in Germany and China establish direct supplier relationships for electric powertrain and satellite component programs.
- Distributors:Catalog procurement for standard semiconductor packaging with established IEC moisture sensitivity level validations.
- Online:Specification-grade procurement for research laboratory and electron microscopy applications.
- Retail:Limited penetration for general-purpose component handling with minimal technical specification requirements.
Direct Sales commands margin expansion; Distributors maintain volume throughput.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's Yangtze River Delta anchors membrane box procurement as domestic foundries scale advanced node production. SAMR-administered GB standards for electronic product packaging accelerate IEC-validated membrane box adoption. Shanghai and Suzhou industrial clusters concentrate procurement of contamination-controlled shipping solutions for local chip fabrication expansion.
United States
Semiconductor packaging roadmaps in Arizona and Texas compress qualification cycles for contamination-controlled transport. EPA hazardous substance labeling requirements and OSHA workplace exposure limits govern material selection and worker handling protocols. Greater Phoenix and Austin metro areas concentrate electric powertrain chip qualification programs with direct supplier engagement.
Germany
Automotive OEM engineering teams in Stuttgart and Munich bypass distributor channels for membrane box co-development programs. REACH substance restrictions constrain phthalate plasticizer use across imported packaging, pulling demand toward halogen-free formulations. Bavaria's automotive semiconductor packaging teams establish dedicated engineering groups for faster validation cycles.
South Korea
Advanced node foundries in Gyeonggi Province specify custom membrane thickness gradients between 0.3 mm and 1.2 mm. MFDS and METI-aligned standards influence regional quality protocols for electronics transport packaging. Suwon and Pyeongtaek industrial corridors decentralize volume concentration toward regional contract manufacturers with rapid lamination capabilities.
Japan
Electron microscopy specimen transport applications command premium positioning through anti-static surface treatment specialization. METI and JIS standards govern precision component handling protocols for research laboratory procurement. Tokyo and Osaka metropolitan clusters sustain specification-grade procurement for semiconductor assembly equipment integration.
Membrane Boxes Market Competitive Landscape
Global majors compete with regional champions across membrane elasticity patents and captive extrusion capabilities. The supplier base stratifies between catalog-format providers and application-specific configuration specialists. Three archetypes dominate: integrated polymer processors controlling resin grade consistency, membrane elasticity patent holders reducing die breakage, and cleanroom-certified specialists documenting lot traceability. Competitive moves concentrate on halogen-free formulation transitions and automated pick-and-place integration partnerships.
Among North American material processors, Placon exemplifies captive extrusion capabilities across multiple plant locations. Gel-Pak occupies a position within the membrane elasticity tier, while Ted Pella anchors the anti-static surface treatment specialization segment for electron microscopy applications. These three represent distinct competitive vectors—resin grade control, mechanical retention optimization, and premium niche technical specification—rather than overlapping market positions.
| Leading Market Players |
|---|
| Placon |
| 3M |
| Ted Pella |
| Gel-Pak |
| SST International |
| GilPak |
| Teca-Print |
| SPI Supplies |
| Structure Probe |
| Others |
Supply & Pricing Matrix
Polypropylene resin index fluctuations cascade through membrane box supply chains into three-tier pricing structure across premium, standard, and economy levels, with REACH-compliant formulations commanding spreads over legacy PVC alternatives as European electronics distributors audit certificates before contract renewal.
Pricing Analysis
Input-cost pass-through from elastomer film and rigid frame materials stratifies pricing across certification tiers. Price differentiation hinges on IEC moisture sensitivity level validation status and cleanroom certification grade, with unvalidated catalog formats absorbing cost compression from virgin polymer supply chain disqualification risks. Aerospace procurement teams in Germany and the United States exhibit lowest price sensitivity due to lot-traceability mandates, while standard electronics distributors face margin tightening from halogen-free reformulation timelines.
Supply Chain Analysis
Workforce availability constraints in Shanghai, Suzhou, and Gyeonggi Province manufacturing clusters are pulling lamination capacity toward regional contract manufacturers with rapid format-switching capabilities. Raw material sourcing draws from Saudi Arabian polypropylene feedstock, South Korean elastomer film specialists, and Chinese rigid frame extruders. Single-source vulnerability concentrates in membrane elasticity patent holders controlling Shore A hardness specifications. Distribution runs through direct sales channels for automotive co-development programs and established electronics distributors for catalog procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a regulatory compounder where ECHA-mandated phthalate restrictions and China's dual carbon goals are accelerating procurement of certified contamination-controlled transport solutions.
For Market Incumbents: To counter regional contract manufacturers with rapid lamination capabilities, deepen captive extrusion control over resin grade consistency and accelerate halogen-free formulation certification ahead of customer qualification cycles. Prioritize cleanroom certification investment to defend aerospace margin pools against emerging specialty suppliers.
For New Entrants and Emerging Players: Launch via online specification-grade channels targeting electron microscopy specimen transport, the most penetrable premium niche where anti-static surface treatment technical rigor commands pricing power above standard electronics packaging. Pursue automated pick-and-place integration partnerships with semiconductor assembly equipment manufacturers as the primary go-to-market angle.
For Investors and Strategic Acquirers: Asymmetric upside sits with membrane elasticity patent holders and cleanroom-certified specialists documenting lot traceability, archetypes positioned for sustained viability as foundry tape-out schedules compress packaging procurement timelines. Watch for IEC validation backlog clearance rates as the inflection signal indicating qualification capacity expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| Halogen-Free Formulation Certification | ECHA REACH compliance unlocks European electronics distributor contract renewals under phthalate restrictions. |
| Cleanroom Certification Investment | Aerospace OEM procurement protocols in Germany and the United States mandate chain-of-custody documentation premiums. |
| Captive Extrusion Capacity Expansion | Resin grade consistency control defends against regional contract manufacturers with rapid lamination capabilities. |
| Automated Pick-and-Place Integration | Die breakage reduction through Shore A hardness optimization opens specification windows with assembly equipment manufacturers. |
| IEC Moisture Sensitivity Validation | Preconditioning cycle testing certification qualifies suppliers for advanced node foundry procurement in Taiwan and South Korea. |
Research Methodology
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region combining interviews with membrane box procurement managers at semiconductor foundries, automotive OEM packaging engineers, aerospace supply chain directors, and cleanroom certification auditors, validated against secondary sources including ECHA substance restriction updates, SAMR GB standard publications, IEC moisture sensitivity testing protocols, and SEC filings from listed packaging material processors, with bottom-up volume triangulation against top-down value estimates.
Granularity-level modeling disaggregates projections across membrane layer architecture, polymer material compliance tier, end-user qualification protocol, and distribution channel complexity throughout the forecast period. CAGRs derive from segment-specific adoption curves calibrated to foundry tape-out schedules, automotive powertrain chip validation timelines, and aerospace lot-traceability mandate implementation across the analysis window. Industry-specific inputs include preconditioning cycle testing capacity expansion rates and halogen-free formulation certification timelines.
Forecast precision tightens around the base case; tail outcomes carry wider variance under sudden REACH substance list expansion or dual carbon goal acceleration in China. Projections reflect assumptions regarding semiconductor packaging roadmap stability and automotive qualification timeline compression. Material deviation in elastomer film patent expiry schedules or cleanroom certification backlog clearance warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Containers
Monobloc Aerosol Cans Market
Packaging Containers
Thermoform Cups Market
Packaging Containers
Self - Locking Trays Market
Packaging Containers
Shipping Mailers Market
Packaging Containers
Gable Top Liquid Cartons Market
Packaging Containers
Insulated Food Containers Market
Packaging Containers
Gable Boxes Market
Packaging Containers
Clamshell Packaging Market
Packaging Containers
Automotive Parts Packaging Market
Packaging Containers
Middle-East and Africa Paper Cups Market
Packaging Containers
Portion Packs Market
Packaging Containers
Roll-On Bottles Market
Packaging Containers
Trigger Spray Bottle Market
Packaging Containers
Food Grade Bottles Market
Packaging Containers
Can Holders Market
Packaging Containers
Candle Box Market