
 Telescope Box Market | 2026-2036
Telescope Box Market Size, Share, and Industry Trends Forecast 2026-2036
Telescope Box Market Analytics
Asset-light leasing models for automated box-making equipment are reshaping competitive entry in the telescope box sector. International Paper leverages its North American pulp integration to sustain cost advantages across bulk rigid formats. DS Smith anchors European supply through recycled-content specialization, while WestRock competes via broad folding box portfolios serving retail display channels.
A telescope box consists of a separate lid and tray that slide together telescopically, typically manufactured from corrugated fiberboard between 200–350 GSM with double-wall construction for stacking strength, designed to protect elongated or fragile goods during transit and storage. Rigid boxes dominate industrial machinery shipments where dimensional stability prevents corner crush, while customized packaging captures premium margins from branded unboxing experiences in consumer electronics. Folding boxes occupy high-volume retail replenishment where storage efficiency offsets lower per-unit protection.
FDA guidelines on sanitary transport packaging influence food-contact telescope box specifications in the United States, while EPA recycled-content mandates shape material sourcing decisions for domestic producers. The EU Green Deal and REACH chemical restrictions are tightening substrate compliance requirements for exporters serving European industrial buyers. Stakeholders must monitor evolving extended producer responsibility frameworks to anticipate pass-through cost structures and qualification timelines.
Market Dynamics
EU Packaging and Packaging Waste Regulation mandates are compressing material recovery timelines for telescope box producers, forcing accelerated substrate redesign and reverse-logistics investment across European supply chains.
Growth Catalysts
- E-commerce fulfillment expansion:Industrial machinery exporters in Germany are standardizing rigid telescope formats for oversized component shipping, creating sustained order flow for double-wall corrugated specifications.
- REACH chemical restrictions:EU substrate compliance requirements are filtering non-compliant Asian suppliers, consolidating qualified vendor relationships for European industrial buyers.
- Recycled-content specialization:DS Smith's captive paper mills are converting post-consumer fiber into 350 GSM grades suitable for premium unboxing experiences in consumer electronics.
Market Restraints
- Old corrugated container price volatility:OCC spot markets in North America swung 34% between 2022-2024, compressing margin visibility for independent box converters without pulp integration.
- Supplier concentration in Nordic kraft pulp:Three producers control 60% of bleached kraft supply to European board mills, creating input bottleneck risk for high-GSM rigid formats.
- Substitute rigid formats:Molded fiber trays with integrated lids are capturing shelf-stable food applications previously served by telescope constructions.
Strategic Opportunities
- India precision manufacturing exports:PLI scheme incentives for machinery and electronics are generating first-time demand for ISPM-15 compliant telescope boxes in Gujarat and Tamil Nadu industrial corridors.
- Digital print convergence with structural design:HP Indigo and EFI Nozomi presses are enabling run-length-one customization for branded unboxing without die-change downtime.
- Asset-light equipment leasing:Bobst and EFI are offering per-unit pricing on box-making lines, lowering capital barriers for regional entrants serving fragmented e-commerce fulfillment networks.
Industry Challenges
- Structural engineer talent scarcity:Corrugated board compression modeling and BCT (box compression test) optimization require specialized training that packaging programs have deprioritized since 2019.
- Extended producer responsibility compliance timelines:Germany's VerpackG registration and France's Citeo eco-modulation are creating overlapping qualification burdens for multi-market suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Telescope Box Market |
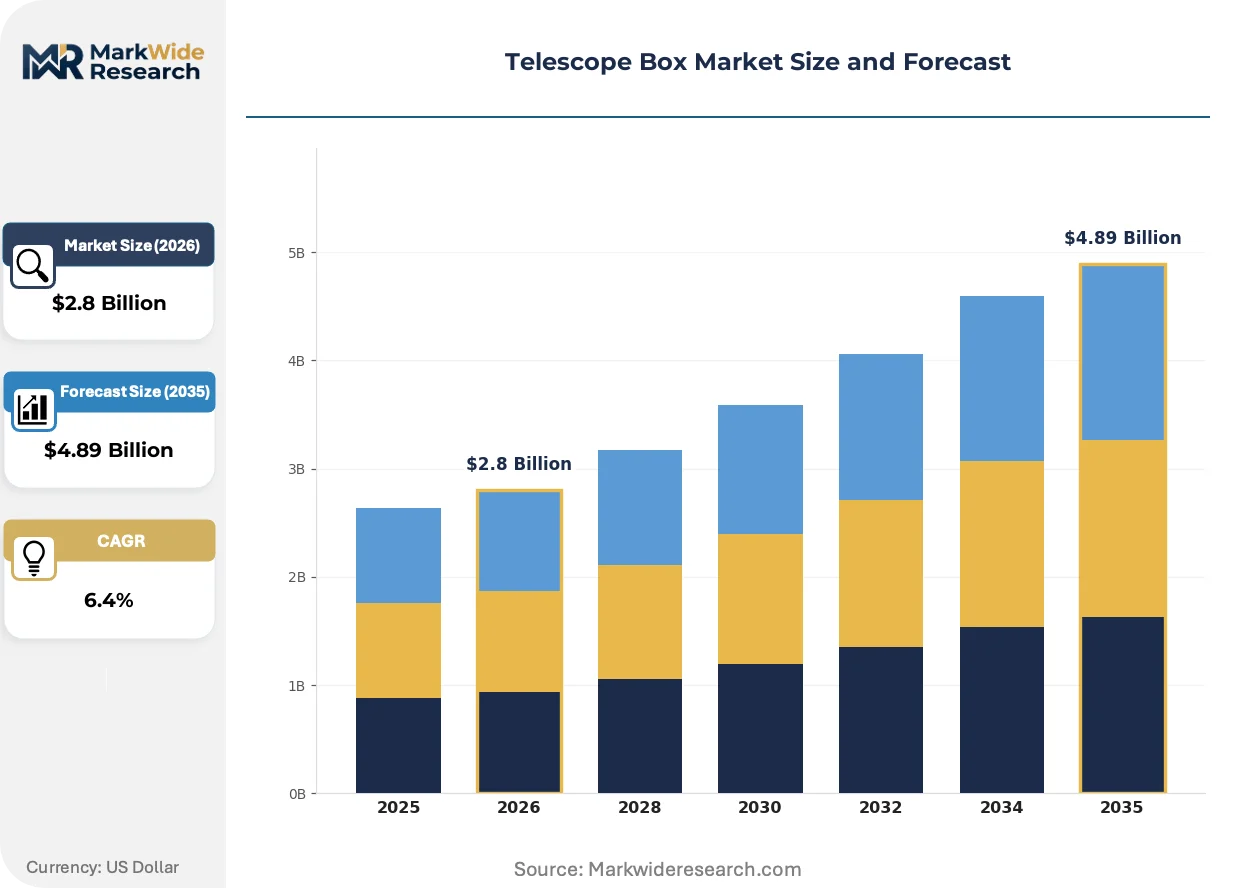
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.89 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rigid Boxes, Folding Boxes, Customized Packaging, Specialty Boxes Material: Cardboard, Plastic, Wood, Metal Size: Small, Medium, Large, Extra Large Closure Type: Snap, Magnetic, Tape, Locking |
| Companies Covered | International Paper, DE-Tech Packaging, Packsize International, Green Bay Packaging, WestRock, DS Smith, Ebro Color GmbH, Stronghaven Inc., Trident PBI, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Telescope Box Market Evolving Landscape
Digital workflow integration is collapsing design-to-delivery cycles in telescope box production, while regulatory chemistry restrictions and buyer consolidation are rewriting material qualification protocols across industrial supply chains.
Finite element analysis software is virtualizing structural prototyping for telescope box designs, replacing physical sample iterations with simulation-based compression and drop-test validation. Industrial machinery shippers in Stuttgart and Milwaukee are adopting these tools to qualify custom formats without tooling lead times. This capability is virtualizing the traditional mold-and-test cycle that previously consumed 6-8 weeks in new product introduction timelines.
EU Green Deal packaging waste targets are mandating 70% recyclable content thresholds by 2030, with ECHA REACH restrictions simultaneously limiting certain coating chemistries for food-contact applications. Dual-wall corrugated producers are responding with water-based barrier coatings that maintain grease resistance without fluorinated compounds. Premium consumer electronics packaging in Amsterdam and Milan is most affected, with brands accelerating supplier audits to preempt 2027 compliance deadlines.
Consolidated procurement by Amazon, Zalando, and Otto Group is compressing supplier bases for standardized telescope formats, displacing fragmented regional converters with multi-facility producers capable of pan-European fulfillment. German e-commerce fulfillment centers are driving this concentration, demanding identical board specifications across Rotterdam, Leipzig, and Warsaw distribution nodes. Vendor reduction programs have eliminated mid-tier suppliers lacking FSC chain-of-custody certification or automated glue-line quality systems.
Telescope Box Market Segmentation
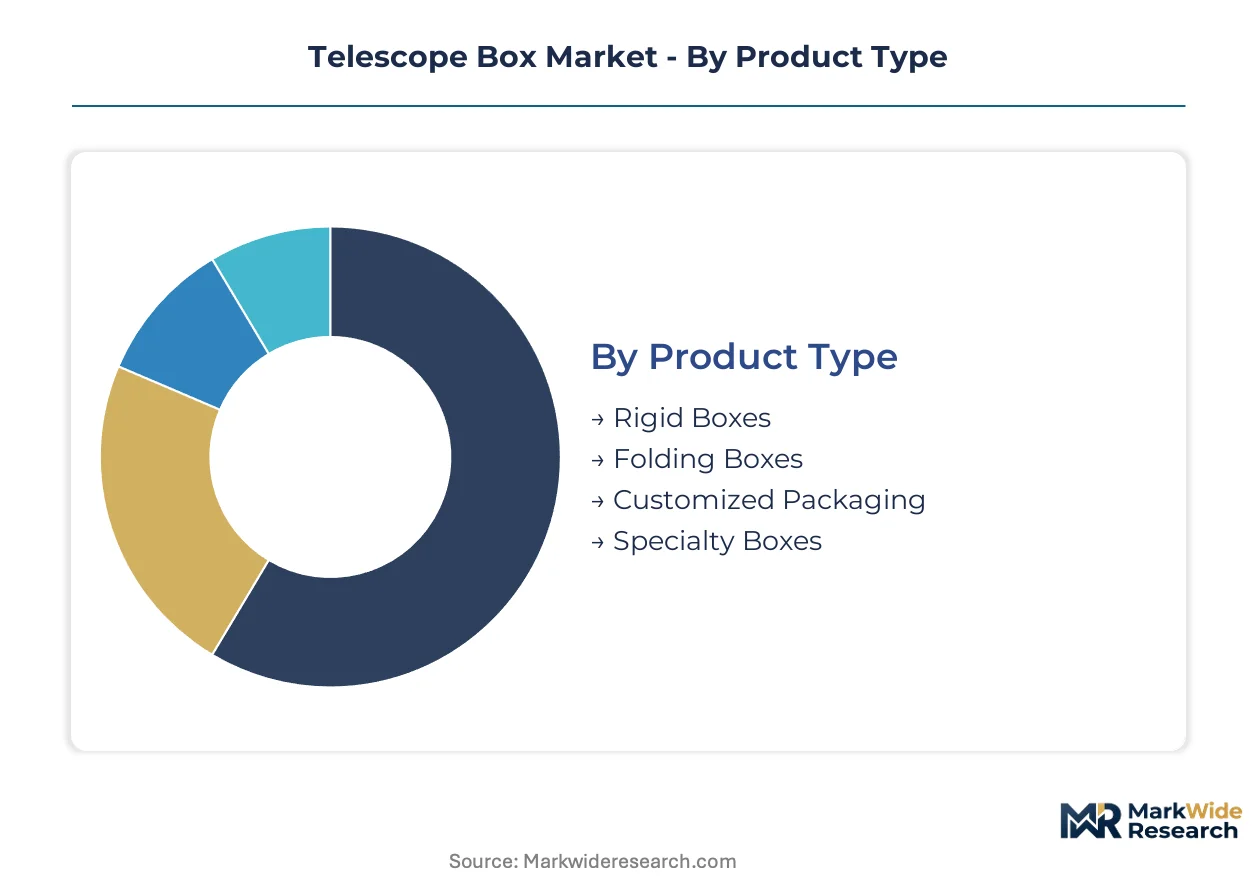
Telescope box segmentation reveals distinct performance tiers across construction formats and material substrates. Product architecture and closure mechanics determine suitability for industrial machinery versus consumer electronics end-uses, with material selection governing compliance thresholds for cross-border shipments.
Product Type:
Mature formats dominate industrial logistics while emerging configurations capture premium unboxing experiences in direct-to-consumer channels.
- Rigid Boxes:Double-wall corrugated fiberboard between 200–350 GSM delivers dimensional stability against corner crush during stacked transit. German precision machinery exporters in Stuttgart and Munich specify rigid formats for oversized component shipments to North American and Asian assembly plants.
- Folding Boxes:Single-wall construction with creased score lines enables flat-packed storage and rapid assembly at fulfillment nodes. E-commerce replenishment networks in Rotterdam and Leipzig prioritize folding formats for storage density, though per-unit protection remains inferior to rigid alternatives.
- Customized Packaging:Bespoke structural designs with integrated print finishes serve branded unboxing sequences in consumer electronics.
- Specialty Boxes:Hybrid constructions incorporating foam inserts or anti-static coatings address semiconductor and optical instrument shipments.
Rigid boxes handle the majority of throughput; customized packaging is expanding most quickly on share as electronics brands invest in unboxing differentiation.
Material:
Cost tiers separate commodity substrates from specialized alternatives with regulatory compliance burdens.
- Cardboard:Post-consumer recycled fiber dominates volume production, with 350 GSM grades from captive paper mills serving premium applications. EU Packaging and Packaging Waste Regulation mandates are accelerating substrate redesign toward water-based barrier coatings that maintain grease resistance without fluorinated compounds.
- Plastic:Polypropylene and PET constructions offer moisture resistance for food-contact and pharmaceutical applications. REACH chemical restrictions are filtering non-compliant Asian suppliers from European procurement bases.
- Wood:ISPM-15 compliant hardwood frames support heavy machinery shipments requiring nail-resistant corners.
- Metal:Aluminum and steel corner reinforcements protect high-value optical equipment against impact damage.
Cardboard commands the volume base; plastic faces the steepest compliance cost escalation.
Size:
Application requirements scale from individual component protection to full machinery enclosure.
- Small:Precision instrument and consumer electronics packaging with crush-resistant specifications for air freight.
- Medium:Standard industrial component dimensions align with pallet optimization for truckload consolidation.
- Large:Elongated machinery subassemblies require telescoping lid-tray engagement depths exceeding 300 millimeters.
- Extra Large:Full equipment enclosures with integrated lifting points and forklift entry slots.
Medium sizes absorb the highest shipment frequency; extra large formats carry the steepest per-unit margin premiums.
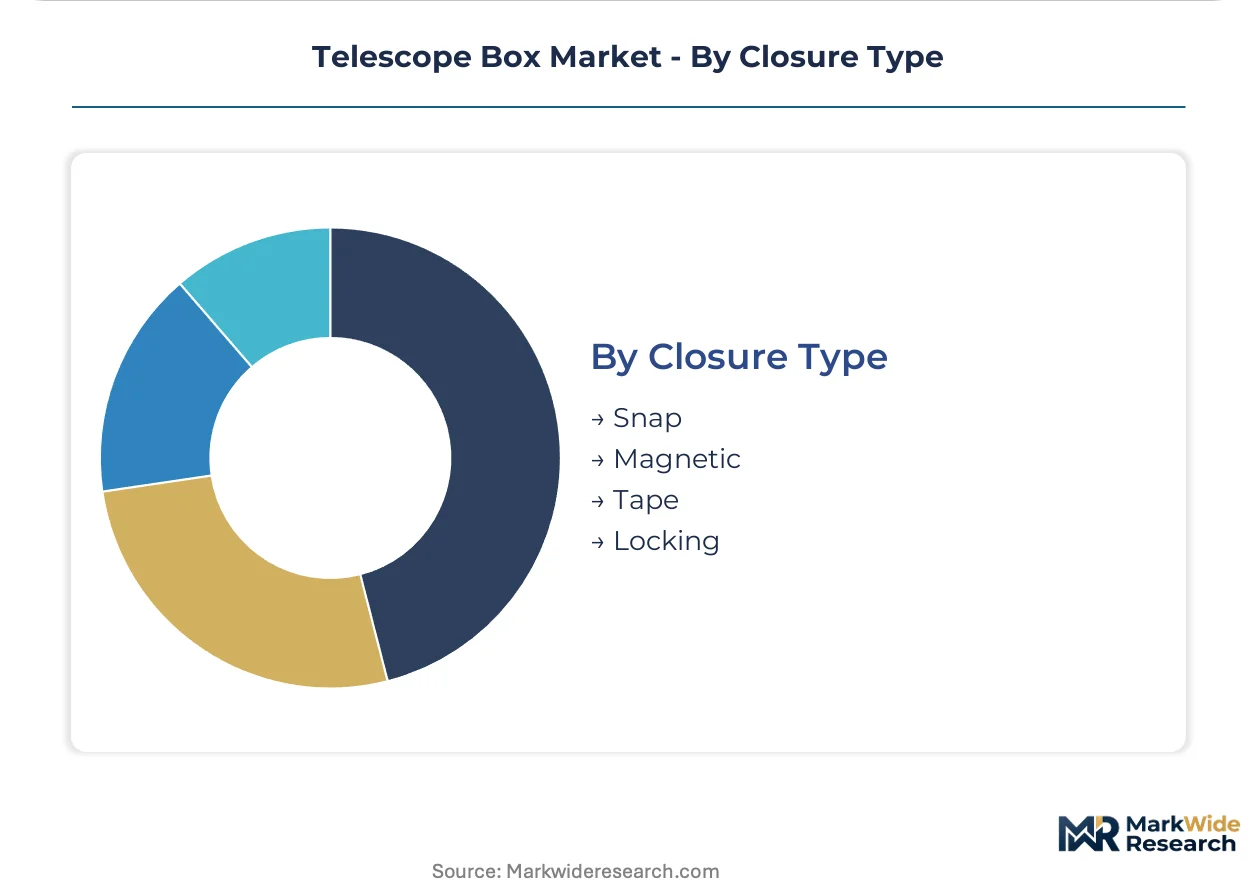
Closure Type:
Security and reopening convenience trade off across mechanical and adhesive alternatives.
- Snap:Integral die-cut tabs engage tray slots without secondary materials, enabling rapid assembly at high-velocity fulfillment centers.
- Magnetic:Embedded ferrite strips enable premium unboxing experiences with satisfying closure feedback.
- Tape:Pressure-sensitive adhesive strips provide tamper-evident sealing for pharmaceutical and food-contact shipments.
- Locking:Mechanical latches secure high-value contents against unauthorized access during extended transit.
Snap closures dominate e-commerce throughput; magnetic variants command the strongest price premiums in gift and electronics channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German precision machinery exporters anchor telescope box procurement volumes, while e-commerce fulfillment networks in the Netherlands and United States drive standardized format adoption. Regulatory compliance requirements fragment supplier qualification across major consumption zones.
Germany
Stuttgart and Munich machinery clusters generate sustained demand for rigid double-wall formats shipping oversized components to North American and Asian assembly plants. The country's VerpackG extended producer responsibility framework mandates registration timelines that compress supplier onboarding cycles. Bavarian industrial corridors concentrate specification authority with exporters standardizing ISPM-15 compliant hardwood-reinforced constructions.
United States
FDA sanitary transport guidelines shape food-contact telescope box specifications for pharmaceutical and perishable shipments. EPA recycled-content mandates drive material sourcing decisions among domestic converters serving e-commerce fulfillment networks. Chicago and Milwaukee industrial packaging clusters adopt finite element analysis software to virtualize structural prototyping without physical sample iterations.
Netherlands
Rotterdam distribution nodes prioritize folding box formats for storage density across pan-European replenishment networks. EU Green Deal packaging waste targets mandate 70% recyclable content thresholds by 2030, accelerating substrate redesign toward water-based barrier coatings. Amsterdam premium electronics brands audit suppliers to preempt 2027 REACH compliance deadlines for fluorinated compound restrictions.
India
PLI scheme incentives for machinery and electronics generate first-time demand for ISPM-15 compliant telescope boxes in Gujarat and Tamil Nadu industrial corridors. The country's national packaging regulator enforces quality standards that filter non-compliant domestic converters. Mumbai and Chennai precision manufacturing exporters specify rigid formats for semiconductor and optical instrument shipments.
China
Dual carbon goals and GB standards tighten substrate compliance for exporters serving European industrial buyers. MIIT industrial policy directs capacity consolidation among corrugated board producers. Shenzhen and Dongguan electronics manufacturing clusters demand customized packaging with integrated print finishes for branded unboxing sequences in direct-to-consumer channels.
Telescope Box Market Competitive Landscape
Channel-controlling players compete with product-specialist players across tiered market positions. Consolidated procurement by major e-commerce platforms compresses supplier bases toward multi-facility producers capable of pan-regional fulfillment. Three archetypes dominate: integrated paper-to-box converters with captive pulp supply, regional specialists in premium customized formats, and asset-light equipment-leasing entrants serving fragmented fulfillment networks. Competitive moves center on M&A for geographic coverage and strategic partnerships for digital print convergence.
Among integrated North American producers, International Paper exemplifies the pulp-integrated archetype with cost advantages across bulk rigid formats. DS Smith occupies a position within European recycled-content specialization, converting post-consumer fiber into premium grades. WestRock sits within the broad folding box portfolio segment serving retail display channels with diversified substrate capabilities.
| Leading Market Players |
|---|
| International Paper |
| DE-Tech Packaging |
| Packsize International |
| Green Bay Packaging |
| WestRock |
| DS Smith |
| Ebro Color GmbH |
| Stronghaven Inc. |
| Trident PBI |
| Others |
Value Network & Pricing Analysis
OCC spot market volatility determines both margin compression in commodity grades and the geographic shape of supply chain consolidation. Producers without captive pulp integration face pricing tier spreads that widen when recovered fiber costs swing, forcing reliance on Nordic kraft pulp suppliers for dimensional stability in rigid formats.
Pricing Analysis
Cost-plus contracts with Old Corrugated Container indexation dominate procurement between converters and machinery exporters in Germany. Three-tier pricing structure across premium customized, standard rigid, and economy folding levels separates ISPM-15 certified hardwood-reinforced constructions from single-wall commodity grades. Pricing pressure stems from Amazon and Otto Group vendor reduction programs compressing regional converter margins. E-commerce fulfillment centers exhibit highest price sensitivity due to volume scale requirements, while precision machinery exporters in Stuttgart prioritize dimensional stability over per-unit cost.
Supply Chain Analysis
Contract manufacturing concentration rests with International Paper's North American pulp integration, DS Smith's European recycled-content mills, and WestRock's folding box specialty operations. Raw material dependencies draw from Nordic bleached kraft pulp, post-consumer OCC streams, and water-based barrier coating chemistries. Supply chain risk centers on single-source vulnerability from three Nordic producers controlling bleached kraft supply to European board mills. Distribution runs through pan-European fulfillment nodes in Rotterdam, Leipzig, and Warsaw demanding identical board specifications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Telescope box markets function as service-attach opportunities where design-to-delivery workflow contracts and ISPM-15 compliance management expand faster than commodity box production. Recurring revenue from structural engineering retainers and automated equipment leasing outpaces hardware margins.
For Market Incumbents: Build captive pulp integration moats through backward control over recovered fiber streams and Nordic kraft supply agreements. Consolidate regional converter capacity in Germany and the Netherlands to defend against asset-light entrants offering Bobst per-unit equipment pricing. Prioritize FSC chain-of-custody certification investments that Amazon vendor reduction programs now mandate. For New Entrants and Emerging Players: Pursue white-space targets in India PLI scheme corridors where ISPM-15 compliance expertise remains scarce among domestic converters. Gujarat and Tamil Nadu precision manufacturing exports offer first-mover positioning before established European suppliers localize production. Lead with digital print convergence using HP Indigo run-length-one capabilities to bypass die-change cost barriers. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors multi-facility producers with pan-regional fulfillment capabilities over single-site specialists. Long-term viability hinges on structural engineering talent pipelines and automated glue-line quality systems that vendor reduction programs filter for. Monitor Citeo eco-modulation and VerpackG registration timeline acceleration as inflection signals for qualification cost pass-through structures.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Recovered Fiber Streams | Captive OCC supply insulates margin visibility from spot market swings affecting independent converters. |
| Digital Print Convergence Partnership | HP Indigo and EFI Nozomi integration enables run-length-one customization without die-change downtime penalties. |
| Asset-Light Equipment Leasing Model | Bobst per-unit pricing lowers capital barriers for regional entrants serving fragmented e-commerce networks. |
| ISPM-15 Compliance Service Layer | Hardwood-reinforced certification management captures recurring revenue from machinery exporters in Stuttgart and Munich. |
| Pan-European Fulfillment Footprint Expansion | Multi-facility presence satisfies Amazon and Otto Group vendor reduction programs demanding identical specifications across Rotterdam, Leipzig, and Warsaw. |
Research Methodology
The analysis maps rigid box, folding box, customized packaging, and specialty format sub-sectors, each validated through corrugated plant managers, OEM procurement teams at machinery exporters, e-commerce fulfillment center supply planners, and aftermarket service heads. Secondary validation draws from EU Packaging and Packaging Waste Regulation filings, EPA recycled-content mandate disclosures, customs trade data for OCC and kraft pulp flows, and SEC 10-K filings from integrated paper-to-box converters. Bottom-up volume builds from facility-level capacity assessments triangulate against top-down demand segmentation from end-use industries.
Assumption sets held regulatory compliance timelines and e-commerce fulfillment center expansion rates fixed while varying OCC price volatility scenarios and Nordic kraft pulp supply disruption probabilities across the projection horizon. Segmentation dimensions modeled include construction format, material substrate, closure type, and geographic regulatory cluster. CAGRs derive from elasticity-adjusted demand curves incorporating machinery export order flows and consumer electronics unboxing investment cycles.
Sensitivities concentrate around EU Green Deal packaging waste target acceleration and REACH chemical restriction expansion that could compress substrate redesign timelines. Forecasts reflect documented assumptions on pulp integration prevalence and vendor reduction program penetration. Quarterly review of OCC spot market spreads, VerpackG registration velocity, and Amazon supplier certification audits is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Containers
Hinged Food Containers Market
Packaging Containers
Single Serve Packaging Market
Packaging Containers
Correx Trays Market
Packaging Containers
Trigger Spray Bottle Market
Packaging Containers
Africa Flexitank Market
Packaging Containers
Foldable Mailer Box Market
Packaging Containers
Pillow Pack Packaging Market
Packaging Containers
Global Food Re Close Pack Market
Packaging Containers
Latin America Aerosol Cans Market
Packaging Containers
Gable Top Liquid Cartons Market
Packaging Containers
VCI Bags Market
Packaging Containers
Self - Locking Trays Market
Packaging Containers
Insulated Storage Vessel Market
Packaging Containers
Wide Mouth Bottles Market
Packaging Containers
Plasma Bottle Market
Packaging Containers
Sanitizer Bottles Market