
 North America Food Cans Market | 2026-2036
North America Food Cans Market Size, Share, and Industry Trends Forecast 2026-2036
North America Food Cans Market Insights
Multi-source aluminum procurement is repositioning how North American food can makers manage input volatility. Crown Holdings Inc leverages captive metal supply agreements to sustain margin stability across volatile commodity cycles. Ball Corporation anchors its food can portfolio through recycling-loop partnerships with regional beverage operations, capturing closed-loop aluminum flows. Silgan Containers LLC competes through deep specialization in steel can formats for shelf-stable proteins, occupying a defensible niche in Midwest meatpacking corridors.
North America food cans are cylindrical metal or composite containers, typically constructed from tinplate steel or aluminum alloy with internal lacquer coatings between 4-12 microns, designed to provide hermetic sealing and thermal sterilization compatibility for shelf-stable food preservation. Steel cans retain dominant share in vegetable and meat applications where puncture resistance and extended shelf life justify higher unit weight, while aluminum cans gain ground in fruit segments where lightweighting and chill-speed advantages align with retail logistics priorities. Composite cans, featuring paperboard bodies with metal ends, carve fastest-growing share in premium dry goods and organic lines where differentiation and sustainability signaling command shelf price premiums.
The FDA governs food contact substance compliance under 21 CFR regulations, while the EPA oversees volatile organic compound emissions from can coating operations, and OSHA mandates worker exposure limits in metal forming facilities. These overlapping frameworks elevate capital requirements for coating technology upgrades and air-quality controls, effectively filtering smaller converters from sustained participation. Stakeholders must monitor evolving state-level extended producer responsibility proposals, as California and New York advance packaging fee structures that would redistribute cost burdens across brand owners and converters alike.
Market Dynamics
Midwest manufacturing corridor concentration around Ohio and Indiana can plants is locking in supply-side efficiency advantages while FDA traceability mandates force simultaneous capital deployment toward smart labeling infrastructure.
Growth Catalysts
- Food Safety Modernization Act traceability mandates:FDA requirements for lot-level tracking are accelerating converter investment in digital printing and embedded sensor technologies across U.S. can lines.
- Aluminum lightweighting in fruit logistics:Retail grocery distribution networks are prioritizing chill-speed and transport efficiency, pulling aluminum can formats into shelf-stable fruit segments previously dominated by steel.
- Midwest protein processing clusters:Proximity between Indiana can manufacturing and Illinois-Iowa meatpacking operations is compressing outbound freight costs and enabling just-in-time supply contracts with institutional food service buyers.
Market Restraints
- Steel input cost volatility:Tinplate steel pricing swings tied to global iron ore markets are compressing margin predictability for vegetable and meat can specialists locked into annual supply contracts.
- EPA coating emission controls:Volatile organic compound limits on can lining operations are forcing smaller converters into costly thermal oxidizer installations or contract manufacturing dependence.
- Flexible pouch substitution in ready-to-eat segments:Retortable pouch formats are capturing shelf-stable meal volume from metal cans in food service channels where microwave convenience outweighs shelf-life premiums.
Strategic Opportunities
- California extended producer responsibility frameworks:Advancing packaging fee structures are creating first-mover advantage for converters with verified closed-loop aluminum recovery systems and post-consumer content certification.
- Composite can premium dry goods positioning:Paperboard-body formats with metal ends are opening organic and specialty grain segments where sustainability signaling commands retail price premiums unavailable to conventional metal.
- Smart label-food safety convergence:Integration of temperature-logging sensors with QR-traceable packaging is enabling subscription-based freshness verification services for direct-to-consumer meal kit channels.
Industry Challenges
- Coating chemist talent scarcity:Formulation expertise for BPA-non-intent epoxy alternatives is concentrating among a narrow cohort of suppliers, extending R&D timelines for compliant interior lacquer development.
- Legacy line retrofit complexity:Converting steel-optimized forming equipment for aluminum gauge ranges requires mechanical rebuilds that idle capacity for 8-14 month commissioning windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Food Cans Market |
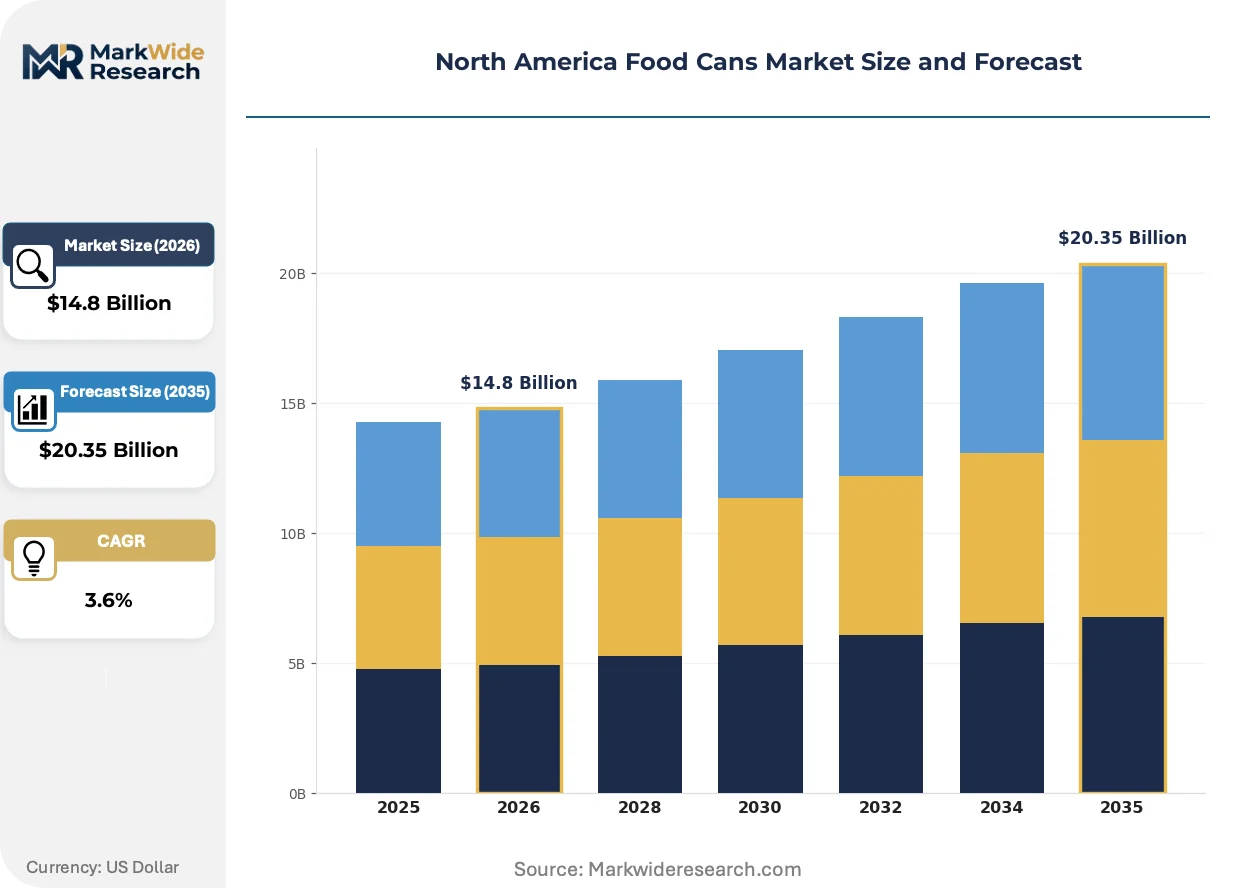
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $20.35 Billion |
| CAGR (2026 – 2036) | 3.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Steel Cans, Aluminum Cans, Composite Cans, Glass Jars Application: Canned Vegetables, Canned Fruits, Canned Meat, Canned Soups End User: Retail Stores, Food Service, Households, Food Manufacturers Distribution Channel: Online Retail, Supermarkets, Convenience Stores, Wholesale |
| Companies Covered | Ardagh Group, Allstate Can Corporation, Ball Corporation, Novelis, Independent Can Company, Crown Holdings Inc, Trivium Packaging, Sonoco Products Company, Silgan Containers LLC, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Food Cans Market Trends and Innovations
Active coating chemistry reformulation and digital traceability integration are compressing product development cycles while opening differentiation vectors beyond traditional material cost competition.
Water-based interior coating systems are electrifying can lining operations across U.S. vegetable processing contracts. Midwest tomato and corn packers are adopting these formulations ahead of 2025 compliance milestones. The technology is electrifying competitive positioning by eliminating thermal oxidizer capital burdens that had filtered smaller converters from regional bidding.
OSHA metal forming facility exposure limits are tightening particulate monitoring requirements in Indiana and Ohio can plants. Enforcement patterns are elevating automated material handling investment priorities above manual quality inspection stations. Steel can lines serving institutional meatpacking accounts are absorbing the bulk of ventilation upgrade capex.
Direct procurement relationships between retail grocery chains and regional can converters are displacing traditional broker-mediated supply arrangements. Volume commitments now flow through category manager negotiations rather than distributor intermediaries. This pattern is most visible in U.S. private-label shelf-stable soup contracts where Kroger and Albertsons have consolidated supplier panels.
North America Food Cans Market Segmentation
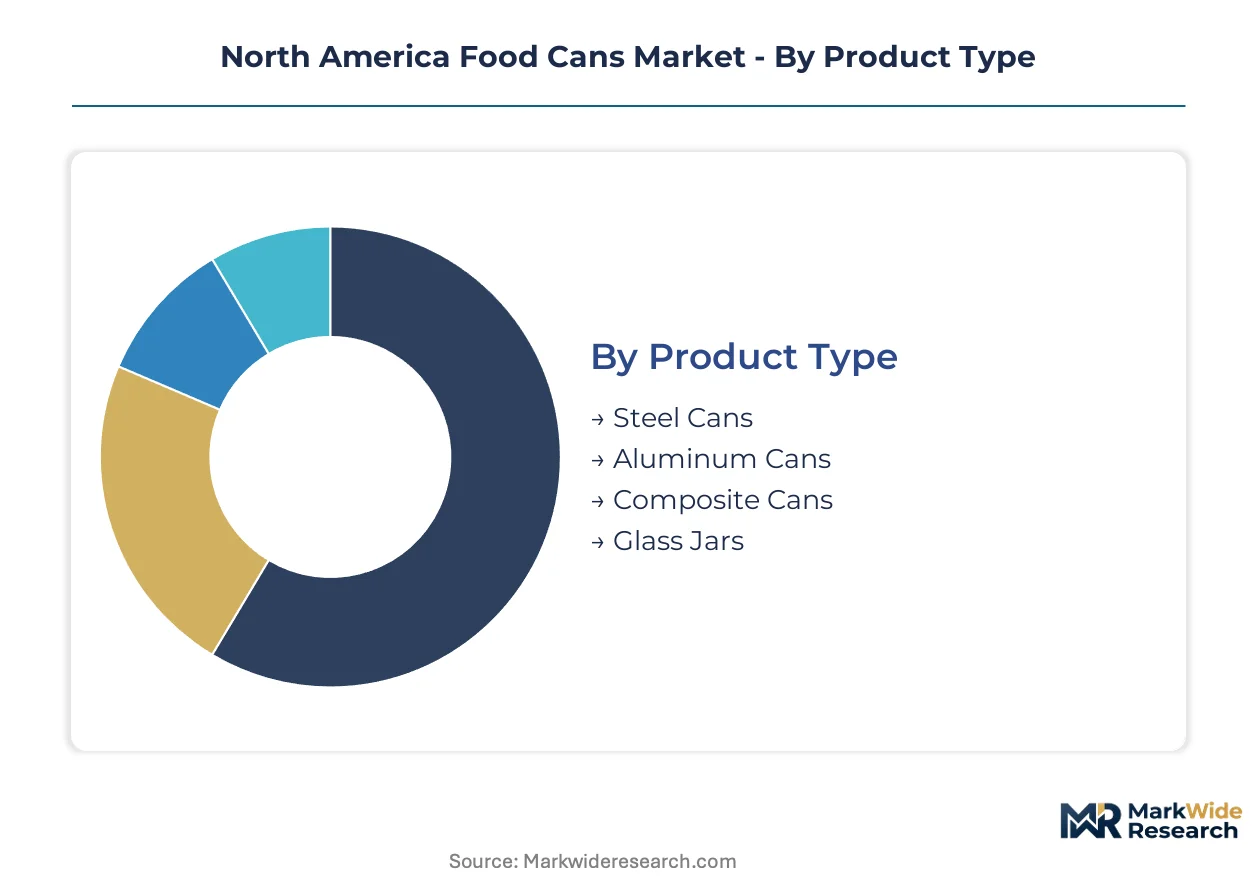
Food can segmentation in North America tracks divergent supply chain economics across material substrates and channel formats. Midwest manufacturing clusters and FDA compliance timelines create distinct competitive arenas within each category.
Product Type:
Material selection separates buyers by shelf-life requirements, freight economics, and coating compliance burdens.
- Steel Cans:Tinplate construction with 4-12 micron interior lacquer coatings delivers puncture resistance for institutional meatpacking contracts. Indiana and Ohio plants supply Illinois-Iowa protein processors under just-in-time arrangements compressed by outbound freight advantages.
- Aluminum Cans:Lightweight alloy formats enable chill-speed efficiency in retail grocery distribution networks. Ball Corporation's recycling-loop partnerships with regional beverage operations capture closed-loop aluminum flows serving fruit canning lines.
- Composite Cans:Paperboard bodies with metal ends command shelf price premiums in organic dry goods where sustainability signaling differentiates retail positioning.
- Glass Jars:Premium visibility packaging for specialty sauces and preserves occupies niche segments outside metal can economies.
Steel cans lead volumes today; aluminum formats are gaining share fastest in fruit logistics channels.
Application:
Thermal sterilization compatibility and shelf stability requirements shape converter specialization across food categories.
- Canned Vegetables:Water-based interior coating adoption accelerates across Midwest tomato and corn packers ahead of EPA compliance milestones. Crown Holdings leverages captive metal supply agreements to sustain margin stability through volatile commodity cycles.
- Canned Meat:Hermetic sealing demands concentrate procurement around Indiana can plants adjacent to Illinois-Iowa meatpacking corridors. Silgan Containers occupies defensible steel can niches through deep specialization in shelf-stable proteins.
- Canned Fruits:Lightweight aluminum penetration climbs in segments where retail distribution prioritizes transport efficiency over puncture resistance.
- Canned Soups:Volume concentration among food service operators pulls format standardization toward institutional pack sizes.
Canned vegetables anchor current production; canned meat applications show steepest expansion trajectory from protein processing cluster proximity.
End User:
Procurement scale and specification authority separate direct converters from broker-mediated supply arrangements.
- Food Service:Kroger and Albertsons category manager negotiations displace distributor intermediaries in private-label shelf-stable soup contracts.
- Retail Stores:Direct procurement relationships compress supplier panels through volume commitment consolidation.
- Food Manufacturers:Co-packing arrangements with Midwest can plants enable just-in-time supply contracts for institutional buyers.
- Households:Consumer pull-through demand follows retail assortment decisions rather than direct converter relationships.
Food service channels concentrate procurement volume; retail direct relationships are expanding most quickly.
Distribution Channel:
Logistics infrastructure and inventory velocity determine format compatibility across channel tiers.
- Supermarkets:Full-case and split-case distribution capabilities align with steel can palletization standards in shelf-stable vegetable and meat segments.
- Wholesale:Institutional volume flows through compressed supplier panels serving food service operators in Midwest protein processing corridors.
- Online Retail:Direct-to-consumer meal kit channels integrate smart label temperature-logging sensors for subscription-based freshness verification.
- Convenience Stores:Smaller pack sizes and grab-and-go positioning favor lightweight formats with reduced shelf-space footprints.
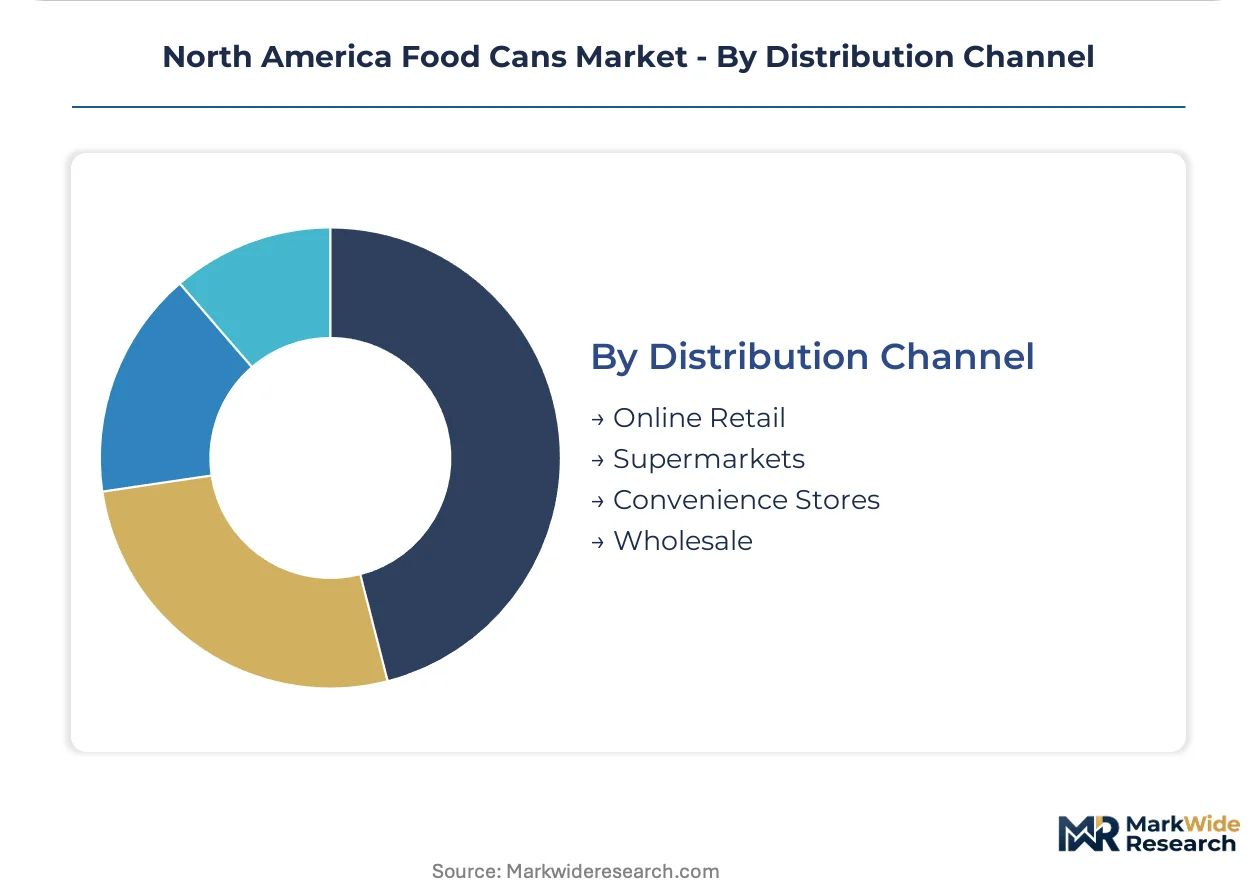
Supermarkets dominate current channel volumes; online retail infrastructure is climbing the fastest from digital traceability integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Ohio-Indiana manufacturing corridor anchors North American food can production through dense clustering of steel and aluminum forming capacity adjacent to Midwest agricultural processing.
United States
Midwest meatpacking and vegetable processing clusters drive concentrated demand from Illinois-Iowa protein corridors and Indiana tomato packers. FDA Food Safety Modernization Act traceability mandates are accelerating digital printing adoption across Ohio can lines. Cleveland and Columbus plants supply institutional food service operators under compressed freight contracts.
Canada
Ontario food manufacturing and Prairie grain processing sustain steady can demand for shelf-stable agricultural exports. Health Canada packaging regulations align with FDA standards while maintaining distinct bilingual labeling requirements. Toronto-area converters serve Quebec vegetable processors through cross-provincial supply arrangements.
Mexico
Bajío Region tomato and fruit processing expansion is pulling aluminum can investment for North American export logistics. NOM-051 labeling regulations govern nutritional disclosure while SEMARNAT oversees coating emission standards. Guanajuato can forming capacity is scaling to capture duty-advantaged supply to U.S. retail chains.
North America Food Cans Market Competitive Landscape
Global majors compete with regional champions across material specialization and captive supply arrangements, producing a tiered structure where scale-driven aluminum recyclers, steel-focused protein specialists, and composite format innovators occupy distinct competitive zones. Three archetypes dominate: integrated metal suppliers with backward control over aluminum flows, steel-can specialists defending Midwest meatpacking corridors, and sustainability-positioned composite developers. Capacity consolidation and recycling-loop partnerships represent the dominant competitive moves reshaping procurement relationships.
Within the integrated metal tier, Crown Holdings Inc and Ball Corporation exemplify scale-driven positioning through captive aluminum supply management and closed-loop recovery systems. Silgan Containers LLC occupies the steel specialization archetype, anchoring defensible positioning in shelf-stable protein formats. Ardagh Group sits within the diversified-format category, spanning multiple substrate technologies across regional production networks.
| Leading Market Players |
|---|
| Ardagh Group |
| Allstate Can Corporation |
| Ball Corporation |
| Novelis |
| Independent Can Company |
| Crown Holdings Inc |
| Trivium Packaging |
| Sonoco Products Company |
| Silgan Containers LLC |
| Others |
Pricing and Supply Chain Analysis
Water-based interior coating electrification across Midwest can lines is compressing capital requirements for EPA compliance while simultaneously concentrating procurement leverage among converters with pre-installed thermal oxidizer infrastructure. This technology transition rewards early adopters with bid eligibility on vegetable processing contracts that filter smaller competitors from regional sourcing panels.
Pricing Analysis
Input-cost pass-through from tinplate steel and aluminum alloy volatility governs contract structures across annual supply agreements with institutional meatpackers and retail grocery chains. Price differentiation separates steel-can specialists serving puncture-resistant protein formats from aluminum lightweighting plays in fruit logistics, with coating compliance tier and captive metal supply anchoring premium positioning. Pricing pressure stems from flexible pouch substitution in ready-to-eat segments where microwave convenience outweighs shelf-life premiums. Food service operators show highest price sensitivity through consolidated supplier panels, while organic dry goods channels absorb sustainability premiums with lower elasticity.
Supply Chain Analysis
Direct-to-food-manufacturer channels handle institutional volume flows from Indiana and Ohio can plants adjacent to Illinois-Iowa meatpacking corridors. Geographic supply concentrates in the United States Midwest, Canada Ontario, and Mexico Bajío Region where tomato and fruit processing expansion pulls aluminum investment. Raw material dependencies rest on tinplate steel from global iron ore markets, aluminum alloy from regional recycling loops, and epoxy-based interior lacquers from concentrated coating chemist suppliers. Tariff exposure on cross-border aluminum flows between Mexico and U.S. retail chains presents structural supply chain risk. Distribution runs through compressed supplier panels serving Kroger and Albertsons category managers rather than traditional broker intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North America Food Cans Market operates as a stable compounder anchored by FDA traceability mandates that perpetuate replacement demand for smart labeling infrastructure across existing can lines.
For Market Incumbents: Anchor defensible positioning through backward integration into captive aluminum recycling partnerships and steel supply agreements that buffer commodity volatility. Invest in water-based coating capacity ahead of EPA compliance milestones to capture vegetable processing contracts filtering smaller converters. Defend against flexible pouch substitution by embedding temperature-logging sensors into institutional food service formats where freshness verification commands contract loyalty. For New Entrants and Emerging Players: Begin with composite can formats targeting organic dry goods segments where sustainability signaling supports shelf price premiums unavailable to conventional metal. Focus white-space capture on direct-to-consumer meal kit channels integrating QR-traceable packaging with subscription-based freshness verification services. Pursue co-packing arrangements with underutilized Midwest can lines to bypass legacy equipment retrofit burdens. For Investors and Strategic Acquirers: Roll-up economics work for regional steel-can specialists with deep meatpacking corridor relationships because FDA compliance timelines and coating talent scarcity prevent rapid new entrant replication. Target acquisition candidates with verified closed-loop aluminum recovery systems positioned for California extended producer responsibility frameworks. Watch for inflection where state-level packaging fee structures redistribute cost burdens toward brand owners with certified post-consumer content.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Captive Metal Supply | Crown Holdings leverages aluminum agreements to sustain margin stability through volatile commodity cycles. |
| Water-Based Coating Capacity Expansion | Midwest tomato packers adopt electrified lining ahead of EPA volatile organic compound limits. |
| Smart Label-Food Safety Convergence | Temperature-logging sensors enable subscription freshness verification for direct-to-consumer meal kits. |
| Recycling-Loop Partnership Formation | Ball Corporation captures closed-loop aluminum flows from regional beverage operations. |
| Composite Can Premium Positioning | Paperboard-body formats with metal ends command organic grain segment shelf price premiums. |
Research Methodology
Multiple input streams — primary interviews with can plant operations managers, coating technology specialists, and retail category buyers; secondary validation through FDA 21 CFR filings, EPA emission compliance databases, and SEC 10-K disclosures from packaging converters; plus customs and trade flow data — were reconciled through bottom-up and top-down triangulation.
Historical volume trajectories were cross-referenced against panel input from procurement directors at Kroger, Albertsons, and institutional food service operators to anchor growth assumptions across the analysis window. Segmentation modeling tracked material substrate, application category, and end-user channel dynamics with CAGRs derived from curve-fitting against input cost indices and regulatory compliance timelines. Forecast inputs included aluminum recycling loop penetration rates and water-based coating adoption curves across Midwest vegetable processing contracts.
Caveats apply where steel input cost volatility, EPA enforcement pattern shifts, or California extended producer responsibility implementation timing could materially shift the outlook. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Containers
Pump Dispenser Market
Packaging Containers
Single Serve Packaging Market
Packaging Containers
Africa Flexitank Market
Packaging Containers
Wrist Watch Packaging Market
Packaging Containers
Middle East and Africa Aerosol Cans Market
Packaging Containers
Eyewear Packaging Market
Packaging Containers
Packing Boxes Market
Packaging Containers
Shipping Mailers Market
Packaging Containers
Trigger Spray Bottle Market
Packaging Containers
Thermoform Cups Market
Packaging Containers
Global Acrylic Airless Bottle Market
Packaging Containers
Membrane Boxes Market
Packaging Containers
Plasma Bottle Market
Packaging Containers
Pillow Pack Packaging Market
Packaging Containers
Double Seam Bowl Market
Packaging Containers
Inverted Squeeze Bottle Market