
 Label Printing Machines Market | 2026-2036
Label Printing Machines Market Size, Share, and Industry Trends Forecast 2026-2036
Label Printing Machines Market Analysis
High-definition 600 dpi print resolution is unwinding legacy specifications across pharmaceutical and food packaging lines. HP Inc. leverages its thermal inkjet arrays to dominate variable-data pharmaceutical runs. Zebra Technologies Corp. anchors industrial-grade barcode labeling through its North American service network. SATO Holdings Corporation specializes in RFID-enabled print engines for Japanese automotive logistics.
Label printing machines apply text, graphics, barcodes, and variable data onto substrates including paper, film, and synthetic stocks at speeds reaching hundreds of meters per minute, serving compliance, traceability, and brand communication requirements. Digital printing technology is displacing flexographic units in short-run personalized packaging where job-change downtime carries steep opportunity cost. Thermal transfer retains margin concentration in durable asset-labeling applications exposed to chemicals and abrasion.
The FDA's Unique Device Identification rule and the EU Falsified Medicines Directive enforce machine-readable serialization that only certified digital systems satisfy. China's SAMR implements comparable drug traceability codes through NMPA-aligned technical standards. REACH and RoHS substance restrictions in Europe filter substrate and ink chemistries accessible to equipment OEMs. Stakeholders must weigh total cost of ownership against compliance-certification breadth when selecting platform architectures.
Market Dynamics
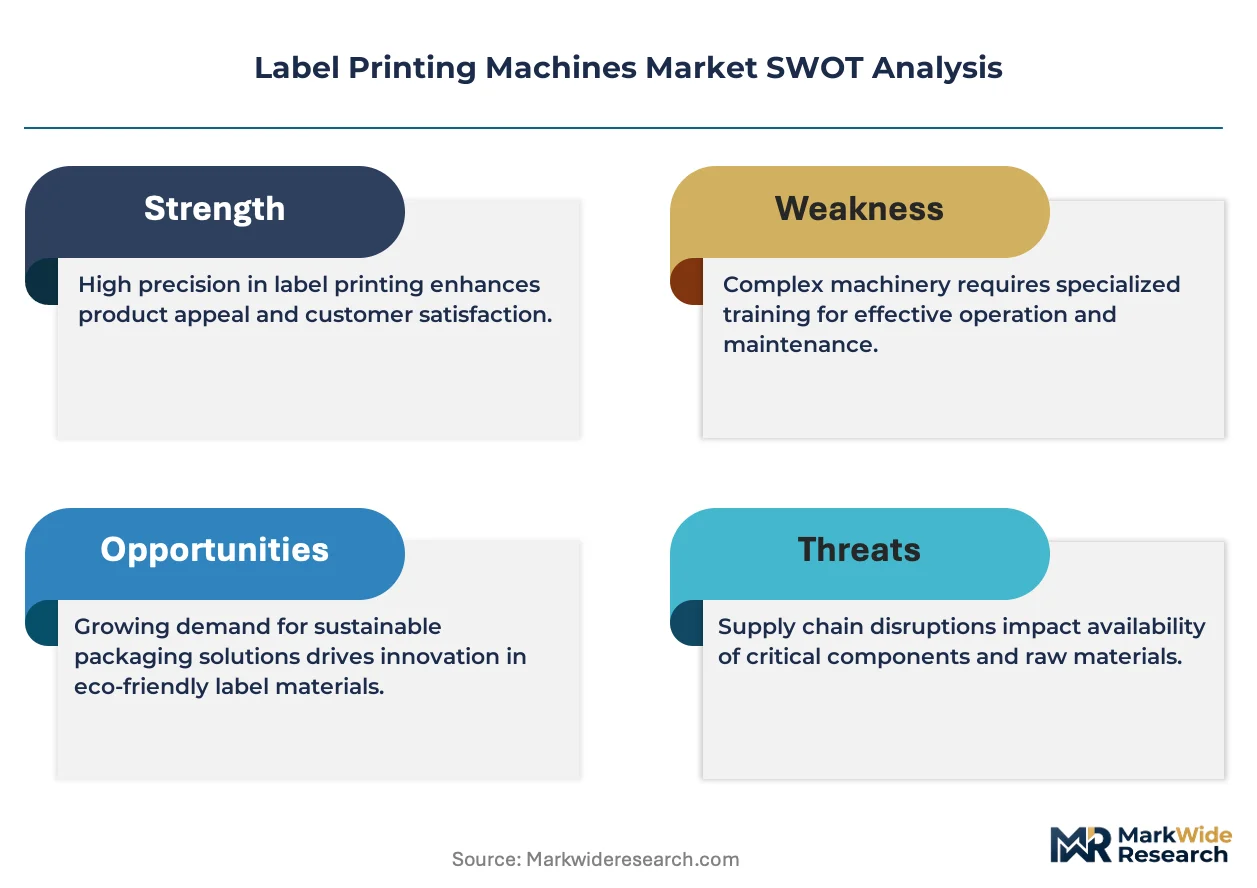
The transition from mechanical flexographic systems to digital inkjet architectures is compressing equipment replacement cycles across pharmaceutical and food packaging lines, forcing OEMs to reconfigure service revenue models around predictive maintenance and remote diagnostics.
Growth Catalysts
- EU Falsified Medicines Directive:Serialization mandates for unit-level traceability are accelerating pharmaceutical manufacturer procurement of high-speed digital printing systems capable of variable-data encoding at line speeds.
- Thermal inkjet arrays:These printheads now achieve pharmaceutical-grade 600 dpi resolution with aqueous inks, eliminating solvent handling infrastructure and reducing cleanroom compliance costs for sterile packaging environments.
- China's SAMR food traceability codes:National standards for QR-encoded provenance tracking are concentrating demand among domestic equipment suppliers with NMPA-aligned certification pathways.
Market Restraints
- Piezoelectric printhead supply concentration:Japanese and German component suppliers control nozzle array manufacturing, exposing OEMs to lead time volatility and foreign exchange-driven cost fluctuations.
- REACH substance restrictions:ECHA limitations on UV-curable ink photoinitiators and pigment chemistries are forcing formulation reformulations that degrade print durability on synthetic substrates.
- Legacy flexographic asset base:Decades of installed rotary letterpress and flexo equipment in North American and European label converters creates sunk-cost resistance to digital platform migration despite total-cost-of-ownshp advantages.
Strategic Opportunities
- RFID-thermal hybrid engines:Convergence of UHF inlay encoding with on-demand barcode printing opens pharmaceutical cold-chain authentication where temperature excursion logging is mandatory.
- India's PLI scheme for packaging machinery:Production-linked incentives for domestic manufacturing are creating localized assembly opportunities for mid-speed digital systems serving export-oriented pharmaceutical clusters in Hyderabad and Ahmedabad.
- Direct-to-shape inkjet modules:Integration of cylindrical printing capabilities onto existing bottling lines addresses beverage and cosmetic markets currently served by pre-printed label application.
Industry Challenges
- Mechatronics talent scarcity:Cross-functional expertise combining fluid dynamics, motion control, and color science is concentrated among aging workforces in German and Japanese industrial clusters, constraining OEM expansion.
- FDA UDI certification timelines:Validation protocols for Unique Device Identification systems extend equipment qualification periods, delaying revenue recognition and straining working capital for system integrators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Label Printing Machines Market |
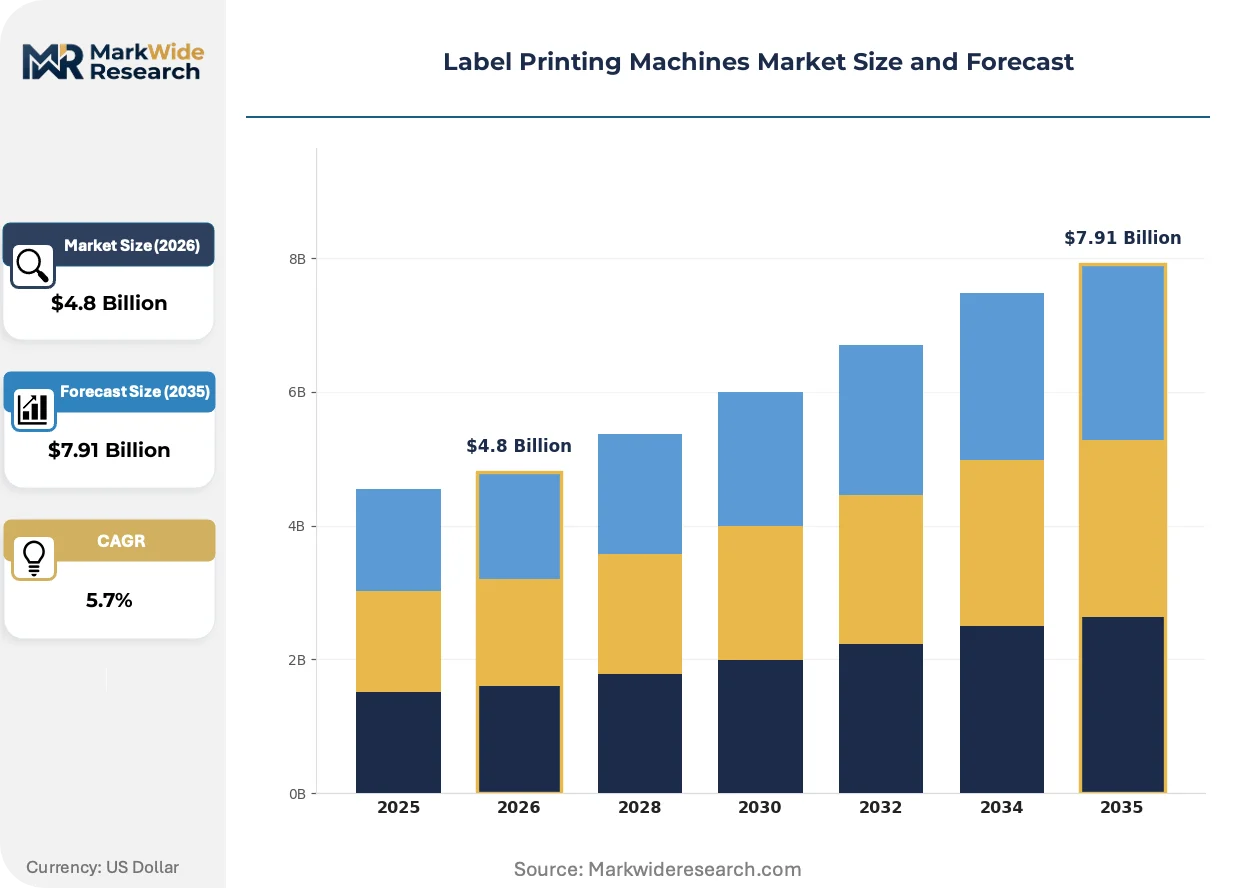
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Thermal Transfer, Direct Thermal, Inkjet, Laser Technology: Digital Printing, Flexographic Printing, Lithographic Printing, Gravure Printing End User: Food & Beverage, Pharmaceuticals, Cosmetics, Logistics Application: Barcode Labeling, RFID Tagging, Variable Data Printing, Identification Labels |
| Companies Covered | Zebra Technologies Corp., HP Inc., Brother Industries, Ltd., SATO Holdings Corporation, Mark Andy, Inc., Bobst Group SA, TSC Auto ID Technology Co., Ltd, Xeikon NV, cab Produkttechnik GmbH & Co. KG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Label Printing Machines Market Emerging Trajectories
Digital printing architectures are fragmenting the traditional equipment supply hierarchy, enabling modular subsystem sourcing that decouples print engine performance from mechanical frame engineering and rewinds legacy vendor lock-in strategies.
Single-pass inkjet arrays with fixed printbar configurations are decomposing the conventional web-fed label press into discrete, swappable modules. Pharmaceutical contract packagers in Germany and Switzerland are adopting these architectures to compress job-change intervals from hours to minutes. The decomposition of monolithic mechanical systems into software-defined print zones is enabling line integrators to source print engines, substrate transport, and curing subsystems from independent suppliers rather than single-source OEMs.
REACH Annex XVII expansions targeting per- and polyfluoroalkyl substances are eliminating fluorinated substrate coatings previously essential for alcohol-resistant pharmaceutical labeling. European labelstock manufacturers are accelerating migration to silicone-based release liners and top-coated papers that satisfy ECHA compliance without sacrificing adhesive anchorage. The regulatory pressure is concentrating procurement among substrate suppliers with certified alternative chemistries, compressing margins for converters dependent on legacy coated stocks.
Equipment-as-a-service contracting is displacing capital purchase models among mid-size North American food processors facing margin pressure from private-label competition. Monthly subscription arrangements covering hardware, consumables, and remote monitoring are transferring obsolescence risk to OEMs while locking in multi-year consumable commitments. The shift is most pronounced in protein and dairy packaging verticals where seasonal volume fluctuations make fixed-capacity investments economically unattractive.
Label Printing Machines Market Segmentation
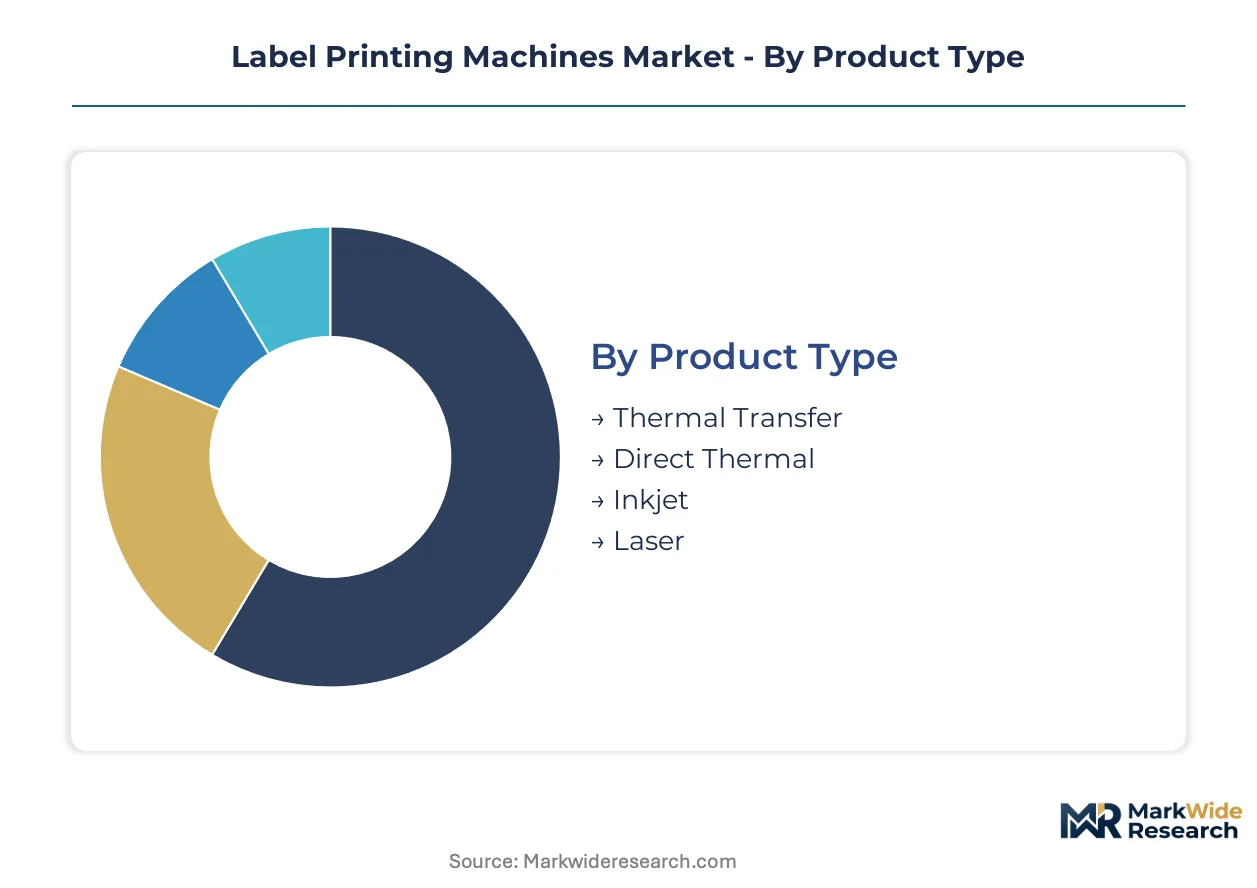
Segmentation reveals how technology choice maps to compliance intensity and substrate requirements across pharmaceutical serialization, food traceability, and logistics authentication use cases. Equipment specifications diverge sharply between sterile packaging environments and industrial asset-tracking applications.
Product Type:
Domestic production concentrates thermal transfer and direct thermal systems in Japan and Germany, while inkjet arrays flow from concentrated component suppliers in those same markets. Export-led demand for laser systems originates from North American aerospace and medical device manufacturers.
- Inkjet:Single-pass thermal inkjet arrays achieve pharmaceutical-grade 600 dpi resolution with aqueous inksets, eliminating solvent handling infrastructure in sterile packaging environments. Demand concentrates among German and Swiss contract packagers facing EU Falsified Medicines Directive serialization mandates.
- Thermal Transfer:Wax-resin and full-resin ribbon systems produce durable asset labels resistant to chemical exposure and abrasion in industrial logistics. Procurement runs through North American automotive and defense contractors requiring MIL-STD-129 compliance.
- Direct Thermal:Chemically treated substrates darken under heated printheads for short-life applications in retail and logistics.
- Laser:CO2 and fiber laser ablation systems etch permanent marks onto synthetic stocks and metalized films for aerospace component tracking.
Inkjet commands the established base. The steepest expansion runs through thermal transfer as durable labeling requirements spread beyond traditional industrial verticals.
Technology:
Cost tier separation is pronounced: digital systems carry premium capital outlays but compress job-change economics, while flexographic and gravure platforms dominate volume-scale commodity production.
- Digital Printing:Inkjet and toner-based systems enable variable-data encoding with zero plate-change downtime, critical for pharmaceutical serialization lots as small as 1,000 units. Adoption concentrates among European and North American converters serving compliance-driven verticals.
- Flexographic Printing:Rotary letterpress architectures with photopolymer plates sustain cost leadership in high-volume food and beverage label runs exceeding 100,000 linear meters.
- Lithographic Printing:Offset platforms deliver photographic image quality on paper stocks for premium cosmetic and spirit labeling applications.
- Gravure Printing:Engraved cylinder systems achieve unmatched ink density and consistency for long-run flexible packaging applications.
Flexographic platforms anchor installed capacity across mature markets. Digital architectures are climbing the fastest as regulatory serialization requirements proliferate.
End User:
Application maturity varies sharply: pharmaceutical and food verticals operate under active regulatory expansion, while cosmetics and logistics follow cost-optimization procurement patterns.
- Pharmaceuticals:Unit-level serialization mandates under FDA Unique Device Identification and EU Falsified Medicines Directive require certified digital systems with audit trail capabilities. Equipment qualification protocols extend procurement cycles and concentrate demand among validated OEMs.
- Food & Beverage:QR-encoded provenance tracking under China's SAMR standards and comparable FDA traceability rules are forcing converter upgrades. Domestic equipment suppliers with NMPA-aligned certification pathways capture concentrated procurement in East Asian markets.
- Cosmetics:Short-run personalization for limited-edition product launches favors digital platforms with rapid job-change capability.
- Logistics:High-speed barcode and RFID encoding for parcel sorting centers prioritizes throughput reliability and 99.9% read-rate compliance.
Food and beverage represents the volume anchor. Pharmaceutical verticals are gaining share fastest as serialization mandates tighten across major economies.
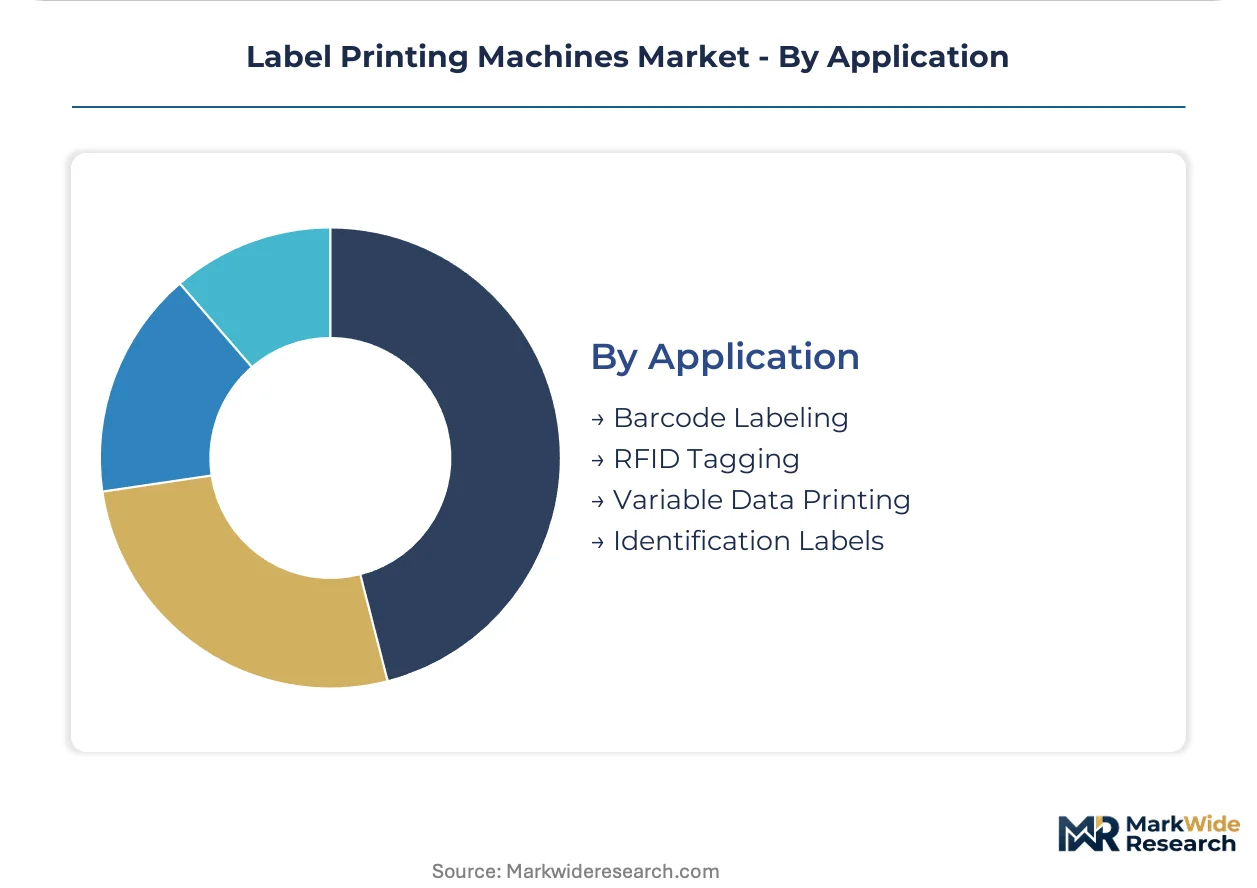
Application:
Customer type bifurcation separates compliance-driven procurement with extended validation requirements from operational-efficiency purchasing focused on total cost per thousand labels.
- Variable Data Printing:Real-time serialization, expiration dating, and lot encoding require digital architectures with database integration and vision-system verification. Deployment concentrates in pharmaceutical packaging lines across Germany, Switzerland, and the United States.
- RFID Tagging:UHF inlay encoding combined with human-readable barcode printing enables cold-chain authentication with temperature excursion logging. Adoption runs through Japanese automotive logistics and North American pharmaceutical distribution networks.
- Barcode Labeling:Linear and 2D symbology printing dominates asset tracking and retail compliance applications.
- Identification Labels:Durable nameplates and safety markings serve industrial equipment and electrical component markets.
Barcode labeling holds the installed base. Variable data printing is expanding most quickly as regulatory serialization requirements multiply across jurisdictions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity varies sharply across geographies. German and Swiss pharmaceutical packagers prioritize compliance certification over capital cost, while Indian and Brazilian converters remain acutely price-sensitive in mid-speed equipment procurement.
Germany
Contract packagers serving EU Falsified Medicines Directive mandates drive premium digital system demand. ECHA REACH restrictions on ink photoinitiators force substrate chemistry reformulations. The Baden-Württemberg industrial cluster hosts specialized OEMs developing aqueous inkjet arrays for sterile packaging environments.
United States
FDA Unique Device Identification rules compress equipment replacement cycles among medical device labelers. USDA traceability requirements for protein processors expand thermal transfer procurement. The Minneapolis-St. Paul corridor concentrates mid-market converters adopting equipment-as-a-service contracting models.
China
SAMR national standards for QR-encoded food provenance accelerate domestic equipment sourcing. NMPA-aligned certification pathways filter foreign supplier access. The Yangtze River Delta pharmaceutical hub in Jiangsu and Zhejiang provinces concentrates high-speed serialization system deployment.
India
PLI scheme incentives for packaging machinery attract localized assembly investments. CDSCO drug traceability expansions mirror European serialization requirements. The Hyderabad-Ahmedabad pharmaceutical corridor drives mid-speed digital system procurement for export-oriented contract manufacturing.
Japan
PMDA pharmaceutical serialization enforcement matches EU directive stringency. METI industrial automation subsidies support RFID-thermal hybrid engine adoption. The Aichi Prefecture automotive logistics cluster anchors demand for temperature-excursion-enabled cold-chain authentication systems.
Label Printing Machines Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes, creating a tiered competitive structure. The market fragments across digital print engine specialists, industrial barcode equipment fabricators, and legacy flexographic press manufacturers. Three archetypes dominate: compliance-certified system integrators serving pharmaceutical verticals, scale-driven producers of industrial-grade hardware, and modular subsystem suppliers decoupling print engines from mechanical frames. Dominant competitive moves include geographic expansion through localized assembly partnerships and portfolio diversification into RFID-thermal hybrid architectures.
Within the digital print engine tier, HP Inc. and Xeikon NV occupy positions exemplifying variable-data specialization. Among industrial-grade fabricators, Zebra Technologies Corp. and SATO Holdings Corporation anchor the durable asset-labeling segment. The German precision engineering cluster includes cab Produkttechnik GmbH & Co. KG representing modular subsystem sourcing trends.
| Leading Market Players |
|---|
| Zebra Technologies Corp. |
| HP Inc. |
| Brother Industries, Ltd. |
| SATO Holdings Corporation |
| Mark Andy, Inc. |
| Bobst Group SA |
| TSC Auto ID Technology Co., Ltd |
| Xeikon NV |
| cab Produkttechnik GmbH & Co. KG |
| Others |
Supply Flow & Price Mechanics
Capacity utilization at Japanese and German printhead foundries shapes both component scarcity premiums and OEM price floors across digital label printing architectures. Scale concentration in piezoelectric nozzle manufacturing forces equipment assemblers to absorb forex-driven cost volatility or pass through to pharmaceutical packagers facing non-negotiable compliance deadlines.
Pricing Analysis
EU Falsified Medicines Directive and FDA Unique Device Identification rules dictate the pricing tier structure across pharmaceutical-grade digital systems. Three-tier pricing structure across premium, standard, and economy levels separates FDA-validated serialization platforms from mid-speed food traceability units and entry-level logistics barcode printers. Cost compression in mid-speed inkjet tiers is intensifying because domestic Chinese suppliers with NMPA-aligned certification are undercutting European OEMs in Asia-Pacific procurement. Pharmaceutical contract packagers in Germany and Switzerland exhibit the lowest price sensitivity due to compliance-driven procurement mandates, while Indian and Brazilian converters remain acutely responsive to capital outlay differentials.
Supply Chain Analysis
Piezoelectric printhead manufacturing chokepoints in Japan and Germany expose OEMs to lead time volatility when semiconductor-grade ceramic substrate allocation tightens. Component sourcing draws from Kyocera and Ricoh nozzle arrays, Fujifilm Dimatix ink formulations, and BASF photoinitiator chemistries. Single-source vulnerability concentrates in MEMS fabrication for thermal inkjet arrays, where foundry capacity expansion lags demand acceleration from pharmaceutical serialization mandates. Distribution runs through authorized system integrators serving validated verticals, with direct OEM relationships reserved for multinational pharmaceutical and food conglomerates with centralized procurement functions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Label printing machines occupy an early-cycle expansion phase as regulatory serialization mandates proliferate beyond pharmaceutical origins into food traceability and medical device verticals. Equipment-as-a-service contracting models are accelerating penetration among margin-constrained mid-market processors unwilling to absorb fixed-capital risk.
For Market Incumbents: Fortify compliance certification breadth across FDA, EMA, and NMPA pathways to defend against modular subsystem suppliers decoupling print engines from mechanical frames. Deepen backward integration into aqueous ink formulation capabilities to offset REACH Annex XVII restrictions degrading third-party supply reliability. Capacity addition in India's PLI-subsidized manufacturing zones anchors cost competitiveness for export-oriented pharmaceutical clusters.
For New Entrants and Emerging Players: Anchor in RFID-thermal hybrid architectures serving Japanese automotive cold-chain authentication, where temperature excursion logging requirements outpace incumbent platform development cycles. India's Hyderabad-Ahmedabad pharmaceutical corridor offers the most penetrable geography for mid-speed digital systems with CDSCO-aligned validation protocols. Go-to-market execution should emphasize equipment-as-a-service contracting to bypass capital-purchase resistance among seasonal protein and dairy processors.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors compliance-certified system integrators with validated pharmaceutical footprints over scale-driven industrial hardware fabricators. Long-term viability hinges on software-defined print zone architectures that decouple hardware refresh cycles from mechanical frame longevity. The signal to watch is NMPA certification timeline acceleration for domestic Chinese suppliers, which would compress margin premiums currently enjoyed by validated Western OEMs in Asia-Pacific markets.
| Strategic Initiative | Industry Significance |
|---|---|
| RFID-Thermal Hybrid Engine Development | Convergence of UHF inlay encoding with barcode printing addresses pharmaceutical cold-chain mandates under PMDA and FDA rules. |
| Equipment-as-a-Service Contracting | Subscription models transfer obsolescence risk to OEMs while locking multi-year consumable commitments from protein processors. |
| REACH-Compliant Ink Formulation | Silicone-based release liners and aqueous photoinitiator alternatives satisfy ECHA restrictions without sacrificing adhesive anchorage. |
| Localized Assembly Partnerships | India's PLI scheme incentives enable cost-competitive mid-speed system production for export-oriented pharmaceutical clusters. |
| Single-Pass Printbar Modularization | Fixed array configurations decompose conventional web-fed presses into swappable software-defined zones. |
Methodological Framework
Two parallel data streams informed the analysis: structured primary interviews with label converter operations directors, pharmaceutical packaging engineers, OEM product managers, and aftermarket service heads; and secondary validation against SEC 10-K filings, ECHA substance restriction databases, FDA UDI guidance documents, and NMPA technical standard releases. Bottom-up equipment shipment triangulation across technology type, end-use vertical, and regional regulatory cluster anchored volume estimates, while top-down market sizing cross-checked against consumables flow analysis.
Across the analysis window, the forecasting framework modeled segmentation dimensions spanning print technology, substrate compatibility class, compliance certification tier, and geographic regulatory cluster. CAGRs derived from equipment replacement cycle compression analysis and regulatory mandate phase-in schedules. Industry-specific inputs included pharmaceutical serialization lot size distributions, food traceability QR code adoption curves, and RFID inlay encoding penetration in automotive logistics.
Material uncertainties — tariff escalation on Japanese printhead components, REACH Annex XVII expansion timelines, and NMPA certification pathway acceleration for domestic Chinese suppliers — sit outside the modeled envelope. Practitioners should keep alternative scenarios live as regulatory harmonization negotiations between FDA, EMA, and NMPA evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Printing
LAMEA Label Printing Software Market
Packaging Printing
Qatar Printing and Packaging Market
Packaging Printing
Label Printers Market
Packaging Printing
Hot Foil Printing Machines Market
Packaging Printing
Rotogravure Printing Cylinder Market
Packaging Printing
Flexographic Printing Machine Market
Packaging Printing
Laser Coders Market
Packaging Printing
Digital Label Printing Market
Packaging Printing
Flexographic Printing Market
Packaging Printing
Flex Banner Market
Packaging Printing
Printed Boxes Market
Packaging Printing
Pre-Printed Liners Market
Packaging Printing
Rotogravure Printing Machine Market
Packaging Printing
North America Print Label Market
Packaging Printing
Global Pre Print Flexo Press Market
Packaging Printing
Pigment Hot Stamping Foil Market