
 Italy Disposable Tableware Market | 2026-2036
Italy Disposable Tableware Market Size, Share, and Industry Trends Forecast 2026-2036
Italy Disposable Tableware Market Foresight
Catering demand is shifting toward premium compostable tableware as Italian event planners and corporate hospitality buyers prioritize sustainability credentials alongside operational convenience. Huhtamaki SpA leverages its European fiber-molding expertise to supply branded biodegradable plates across northern Italian trade corridors. Dopla SpA anchors its position through deep penetration of the restaurant channel with polypropylene and paper hybrid lines. IMI Industria Monouso Italian Spa dominates domestic manufacturing with vertically integrated extrusion and thermoforming operations near Veneto.
Italy disposable tableware encompasses single-use serving and eating implements manufactured from thermoformed plastics, molded fibers, pressed bamboo, or bagasse pulp, typically designed for one to three hours of food contact before discard. These products serve commercial foodservice, institutional catering, and household occasions where washing infrastructure is unavailable or cost-prohibitive. Paper-based plates and cups lead volume due to compatibility with Italy's organic waste collection streams and consumer familiarity. Sugarcane bagasse lines represent the fastest-expanding material category as converters respond to EUDR-aligned sourcing requirements and foodservice procurement mandates. Plastic segments retain share in liquid-heavy applications where barrier properties remain unmatched by fiber alternatives.
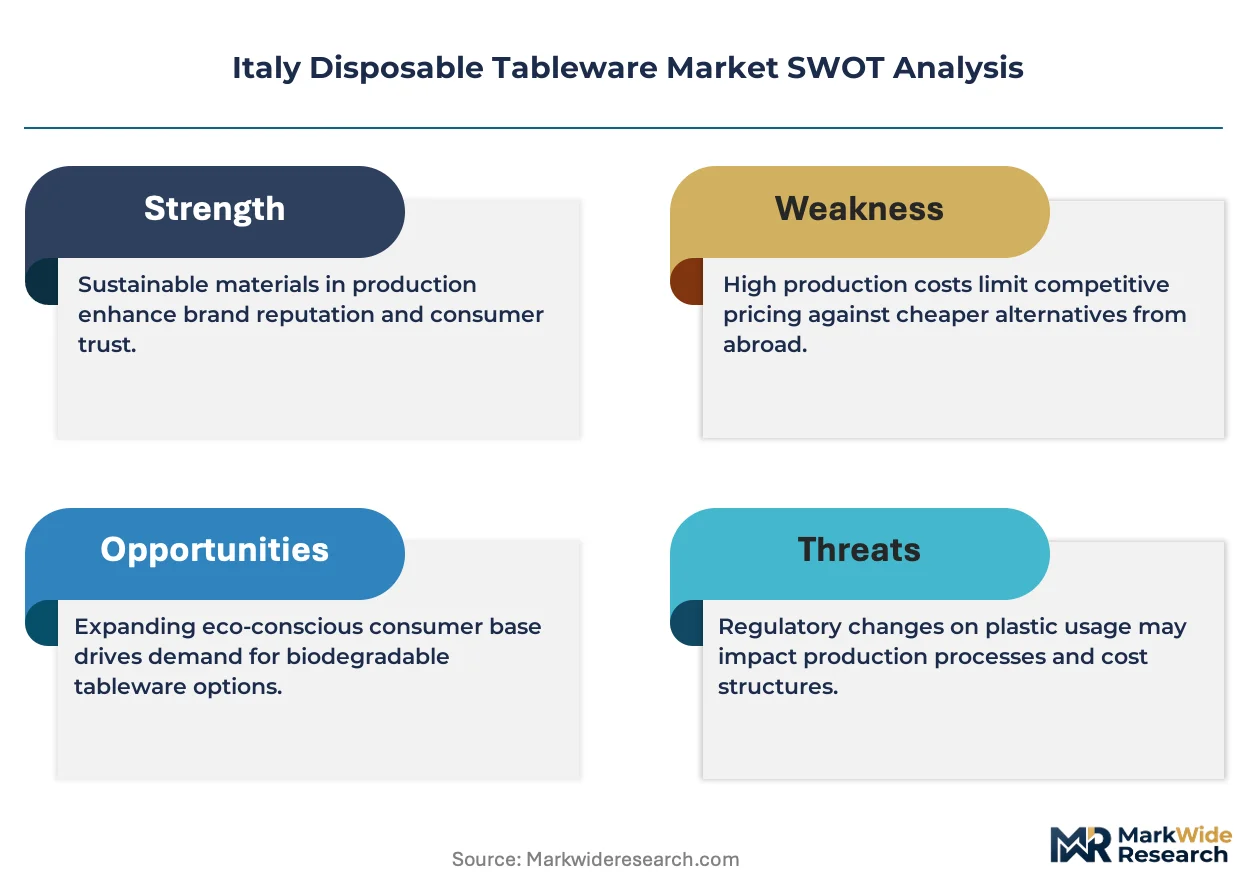
Italy's Legislative Decree 116/2020 transposing the EU Single-Use Plastics Directive bans expanded polystyrene food containers and oxo-degradable formulations, compelling reformulation toward certified compostable substrates. BIS-equivalent conformity assessments under UNI EN 13432 govern industrial compostability claims and shape product development roadmaps for domestic manufacturers. ECHA substance restrictions on intentional microplastic additives further narrow formulation freedom for conventional polymer suppliers. Stakeholders must monitor MASE circular economy tender criteria and regional waste management infrastructure readiness before committing capacity to novel biomaterial platforms.
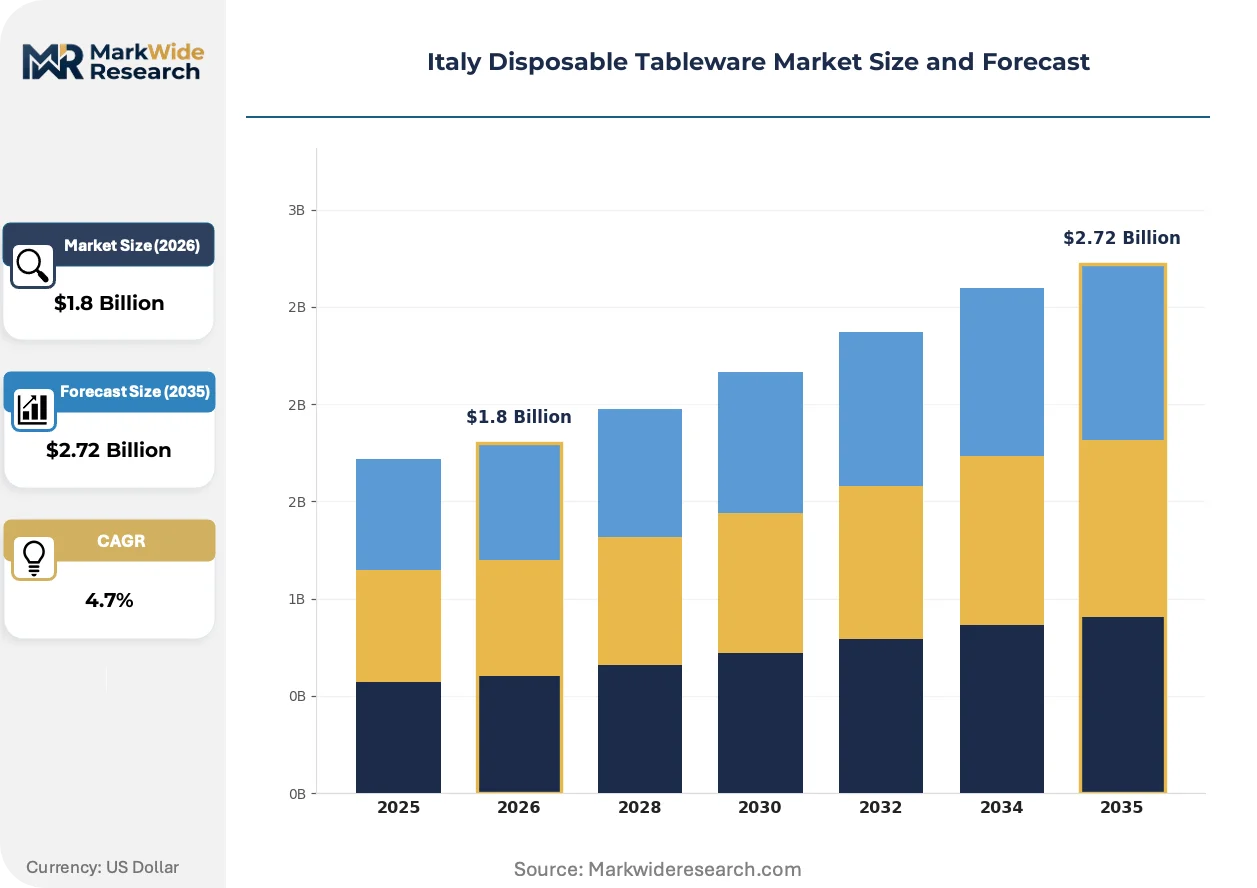
Market Dynamics
Italy's SUP decree restricting single-use plastics is redirecting material choices toward fiber-based alternatives, compressing polystyrene capacity while expanding compostable substrate investments across Veneto and Lombardy manufacturing clusters.
Growth Catalysts
- Lombardy foodservice density:Corporate catering procurement in Milan's metropolitan zone prioritizes certified compostable serveware to meet municipal waste diversion targets. Event infrastructure expansion drives premium bagasse plate volumes.
- UNI EN 13432 compliance:Industrial compostability certification under this framework unlocks preferential tender access for converters supplying public sector institutional buyers. Regional waste management operators coordinate collection logistics.
- Sugarcane bagasse molding:Fiber-forming technology advances enable barrier-coated plates that withstand hot liquids without plastic linings. Southern Italian converters retrofit thermoforming lines for pulp-based production.
Market Restraints
- Pulp fiber input volatility:European bagasse supply concentrates among Spanish and Portuguese agricultural processors, exposing Italian molders to freight cost fluctuations and harvest-season availability constraints.
- Barrier performance gaps:Fiber alternatives lack the grease resistance and structural rigidity of polypropylene in extended-duration catering applications, limiting penetration of premium banquet segments.
- ECHA microplastic restrictions:Intentional additive bans narrow formulation options for conventional polymer suppliers seeking to maintain share in liquid-heavy disposable cup categories.
Strategic Opportunities
- Emilia-Romagna agritourism channel:Farm-to-table event venues in Bologna and Modena provinces represent underpenetrated demand for branded compostable tableware matching regional culinary identity.
- MASE circular economy tenders:Ministry of Environment procurement criteria favor suppliers with verified bio-based content and regional supply chain documentation, creating preferential access for domestic manufacturers.
- Digital print customization:On-demand branding technology converges with short-run fiber molding to enable personalized serveware for wedding and corporate event planners seeking differentiation.
Industry Challenges
- UNI EN 13432 certification timelines:Third-party laboratory testing and documentation requirements delay product launches by four to six months, compressing revenue realization windows for seasonal demand cycles.
- Thermoformer retooling costs:Legacy polystyrene equipment requires substantial capital modification to process bagasse pulp, stranding mid-scale converters between material transition commitments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Italy Disposable Tableware Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Plastic, Paper, Bamboo, Sugarcane Product Type: Plates, Cups, Cutlery, Bowls End Use: Household, Restaurants, Events, Catering Sales Channel: Online Retail, Grocery Stores, Wholesale, Supermarkets |
| Companies Covered | Fabbrica Pinze Schio Srl, IMI Industria Monouso Italian Spa, Dopla SpA, CA. DIS, Aristea Srl, Huhtamaki SpA, Giano Plastica Srl, Flo SpA, Duni AB, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Italy Disposable Tableware Market Shifts & Advancements
Fiber-molding technology advances and regulatory compliance frameworks are compressing traditional plastic formats while opening premium positioning for certified bio-based alternatives across Italian foodservice procurement channels.
Barrier-coated bagasse pulp technology is unifying structural performance with compostability credentials. Large-scale catering operators in Milan and Rome are adopting these formats for corporate hospitality contracts previously served by laminated paper. The convergence of grease resistance and industrial compostability is unifying procurement specifications across previously segmented premium and standard serveware tiers.
Italy's Legislative Decree 116/2020 transposes EU Single-Use Plastics Directive prohibitions into national enforcement frameworks. Expanded polystyrene food container bans and oxo-degradable formulation restrictions compel immediate material reformulation for domestic manufacturers. Northern Italian converters are responding with accelerated UNI EN 13432 certification investments to maintain public sector tender eligibility.
Event planner buying committees now mandate sustainability documentation alongside unit economics in vendor selection criteria. Traditional distributor relationships face displacement from direct manufacturer partnerships offering batch-level compostability traceability. This behavioral shift concentrates most visibly in Tuscany and Veneto wedding venue procurement, where certified serveware commands measurable price premiums over conventional alternatives.
Italy Disposable Tableware Market Segmentation
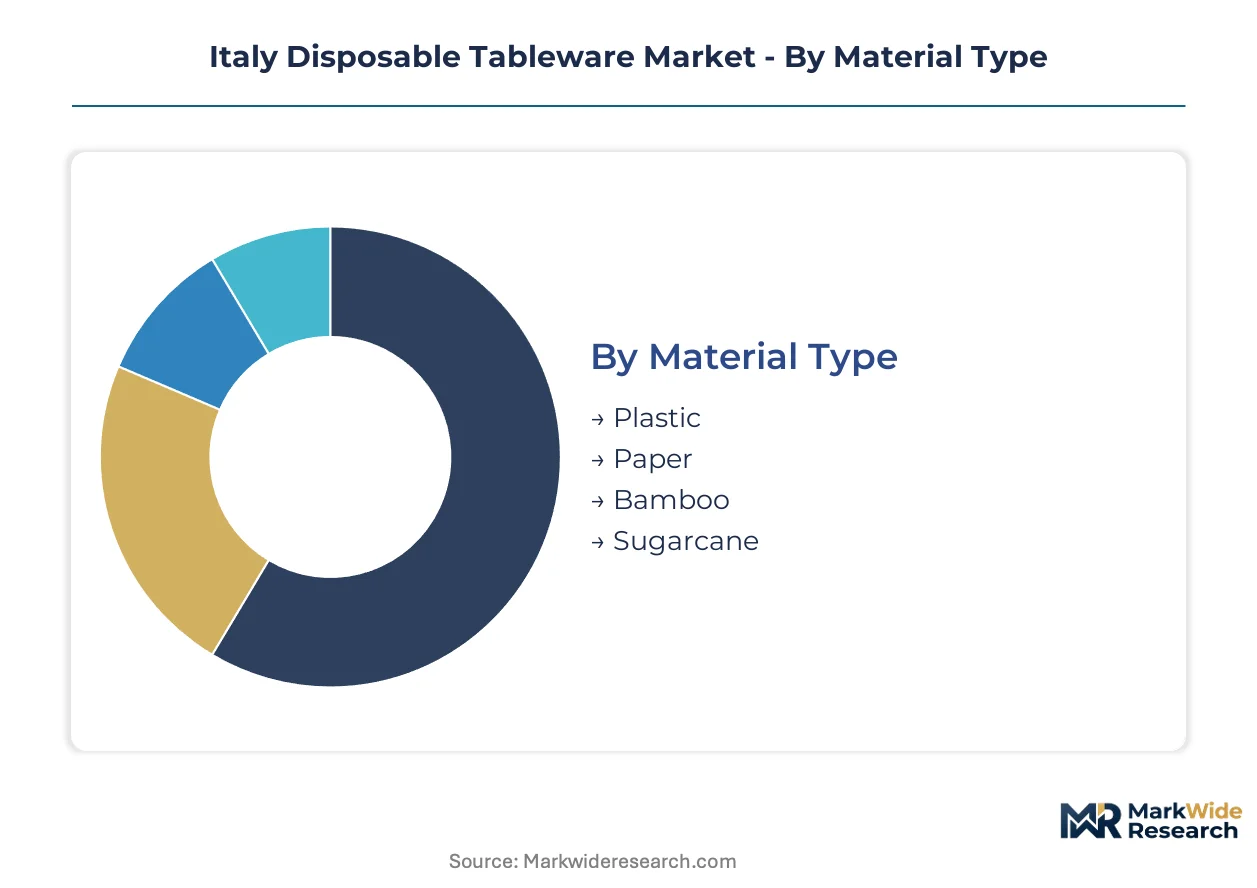
Material composition and end-use application patterns determine procurement specifications and compliance pathways across Italian disposable tableware. Segmentation reveals where regulatory pressure concentrates demand and where traditional formats retain operational necessity.
Material Type:
Paper dominates unit volume through compatibility with municipal organic waste streams, while sugarcane bagasse captures premium positioning.
- Plastic:Polypropylene and polystyrene formulations retain share in liquid-heavy applications requiring unmatched barrier properties. Legislative Decree 116/2020 compresses expanded polystyrene capacity while conventional polymers adapt to ECHA microplastic additive restrictions.
- Paper:Molded fiber and pressed pulp plates lead procurement volumes across Lombardy and Emilia-Romagna foodservice corridors. Compatibility with Italy's organic waste collection infrastructure and established consumer familiarity sustain baseline demand.
- Bamboo:Laminated bamboo fiber serves premium agritourism venues in Tuscany seeking regional culinary identity alignment. Veneto converters develop specialized pressing capabilities for this niche.
- Sugarcane:Bagasse pulp molding expands most quickly as converters retrofit thermoforming lines for EUDR-aligned sourcing requirements. Southern Italian manufacturers coordinate with Iberian agricultural processors for fiber supply.
Today's leader: Paper. Tomorrow's challenger: Sugarcane.
Product Type:
Structural performance requirements vary sharply between solid-food and liquid-contact applications, shaping material selection and certification priorities.
- Plates:Flat and compartmentalized formats concentrate procurement volume across corporate catering and institutional foodservice. Bagasse and molded fiber variants displace laminated paper in Milan metropolitan zone contracts.
- Cups:Hot and cold beverage containers demand barrier coatings where fiber alternatives compete with polypropylene structural integrity. Extended-duration catering applications expose performance gaps in unlined pulp formats.
- Cutlery:Polylactic acid and CPLA biopolymer formulations gain share in premium compostable sets for wedding and corporate event planners. Weight and rigidity specifications challenge fiber-based alternatives.
- Bowls:Deep-drawn fiber molding serves soup and pasta applications where grease resistance and liquid tolerance converge. UNI EN 13432 certification unlocks public sector tender access for compliant suppliers.
Plates and cups together anchor procurement volume; cutlery commands the steepest premium differentiation.
End Use:
Channel-specific compliance requirements and operational constraints fragment demand across household, commercial, and institutional buyers.
- Household:Occasional-use purchases concentrate in supermarkets and grocery stores, prioritizing unit economics over certification documentation. Consumer familiarity with paper-based formats sustains repeat purchase patterns.
- Restaurants:Quick-service and casual dining operators balance cost controls with municipal waste diversion mandates. Polypropylene retains share in delivery and takeaway applications where durability outweighs compostability.
- Events:Wedding venues and corporate hospitality buyers in Tuscany and Veneto now mandate batch-level sustainability documentation. Direct manufacturer partnerships displace traditional distributor relationships.
- Catering:Large-scale operators in Milan and Rome adopt barrier-coated bagasse for contracts previously served by laminated paper. UNI EN 13432 compliance enables preferential access to institutional procurement.
Events and catering drive premium format adoption; restaurants and households sustain volume throughput.
Sales Channel:
Procurement behavior diverges between immediate-need retail purchasing and planned commercial sourcing with documentation requirements.
- Online Retail:E-commerce platforms aggregate specialty compostable formats for event planners and sustainability-conscious consumers. Digital customization capabilities enable short-run branded serveware.
- Grocery Stores:Supermarket and hypermarket chains stock paper-based plates and cups for household occasion purchasing. Private label penetration concentrates in price-sensitive segments.
- Wholesale:Foodservice distributors supply restaurants and catering operators with volume-tiered pricing and consolidated logistics. Technical specification support and certification documentation differentiate supplier relationships.
- Supermarkets:Large-format retail captures baseline household demand through prominent shelf placement and promotional pricing. Regional waste management infrastructure compatibility influences format selection.
Wholesale retains commercial volume dominance; online retail captures premium customization growth.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage across Italian sub-regions is accelerating capacity migration toward zones with mature organic waste infrastructure and streamlined UNI EN 13432 certification pathways. Manufacturers face divergent compliance costs between northern industrial clusters with established composting networks and southern regions still building collection logistics.
Lombardy
Milan's metropolitan catering procurement drives premium bagasse plate volumes as corporate hospitality buyers mandate certified compostable serveware. Municipal waste diversion targets under regional environmental directives pressure operators toward documented bio-based sourcing. Manufacturing activity clusters around Brescia and Bergamo thermoforming corridors where converters retrofit legacy lines for pulp-based production.
Emilia-Romagna
Farm-to-table event venues in Bologna and Modena provinces generate underpenetrated demand for branded compostable tableware matching regional culinary identity. MASE circular economy tender criteria favor suppliers with verified bio-based content and supply chain documentation. Industrial molders near Parma coordinate with agricultural processors for fiber input security.
Veneto
Vertically integrated extrusion and thermoforming operations anchor domestic manufacturing capacity near Treviso and Vicenza. IMI Industria Monouso Italian Spa exemplifies this concentration through captive production of polypropylene and fiber hybrid lines. Regional waste management operators pilot batch-level compostability traceability systems for public sector procurement.
Tuscany
Wedding venue procurement in Florence and Siena provinces concentrates premium sustainability demand where certified serveware commands measurable price premiums. Event planner buying committees now mandate documentation alongside unit economics in vendor selection. Agritourism operators drive laminated bamboo fiber adoption for regional identity alignment.
Lazio
Rome's large-scale catering operators adopt barrier-coated bagasse for contracts previously served by laminated paper formats. Institutional procurement through MASE frameworks unlocks preferential tender access for UNI EN 13432 compliant suppliers. Southern converters face freight cost disadvantages for Iberian bagasse fiber supply.
Italy Disposable Tableware Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with premium compostable formats consolidating around certified domestic producers while commodity paper lines fragment among regional converters. Three archetypes dominate: vertically integrated thermoformers with captive pulp supply, fiber-molding specialists leveraging European agricultural waste networks, and distributor-branded importers competing on unit economics. Capacity expansion and certification investments constitute the dominant competitive moves as players reposition for post-SUP decree procurement.
Among Italian-based manufacturers, IMI Industria Monouso Italian Spa and Dopla SpA occupy positions within the integrated production tier, while Huhtamaki SpA represents the European fiber-molding specialist archetype with cross-border supply capabilities. Fabbrica Pinze Schio Srl exemplifies regional contract manufacturing concentration. These entities anchor competitive dynamics without dictating specific strategic postures.
| Leading Market Players |
|---|
| Fabbrica Pinze Schio Srl |
| IMI Industria Monouso Italian Spa |
| Dopla SpA |
| CA. DIS |
| Aristea Srl |
| Huhtamaki SpA |
| Giano Plastica Srl |
| Flo SpA |
| Duni AB |
| Others |
Supply & Pricing Matrix
Corporate hospitality procurement in Milan's metropolitan zone concentrates purchasing power among large-scale catering operators, forcing a contract-based pricing structure where UNI EN 13432 certification unlocks preferential tender access and volume-tiered discounts.
Pricing Analysis
Distributor margins compress pricing elasticity for mid-scale converters serving the restaurant channel, while direct manufacturer partnerships with event planners capture premium positioning. Three-tier pricing structure across premium compostable, standard fiber, and economy plastic levels reflects certification grade and barrier performance differentiation. Cost compression in the polystyrene segment intensifies as Legislative Decree 116/2020 bans force capacity write-downs. Quick-service restaurant chains exhibit highest price sensitivity; wedding venue buyers prioritize sustainability documentation over unit economics.
Supply Chain Analysis
Direct-to-catering channels handle hyperscale buyer demand in Lombardy and Lazio, bypassing traditional wholesale intermediaries for certified compostable formats. Raw material supply draws from Spanish and Portuguese bagasse processors, with Italian molders dependent on seasonal harvest cycles and freight cost exposure. Pulp fiber input volatility and single-source vulnerability for barrier coating additives concentrate risk in southern converter operations. Distribution runs through foodservice wholesalers for restaurant and institutional segments, while online retail platforms aggregate specialty formats for event planners.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Italy's disposable tableware market operates as a regulatory compounder where Legislative Decree 116/2020 transposing the EU Single-Use Plastics Directive continuously redirects procurement specifications toward certified compostable substrates.
For Market Incumbents: Acquire pulp molding equipment and captive fiber supply agreements to defend against Iberian converter entry. Backward integration into bagasse sourcing from Spanish agricultural processors secures input cost stability. UNI EN 13432 certification investments preserve public sector tender eligibility as MASE circular economy criteria tighten. For New Entrants and Emerging Players: Enter via the Emilia-Romagna agritourism channel where farm-to-table venues seek branded compostable tableware matching regional culinary identity. Digital print customization capabilities enable short-run personalized serveware for wedding planners. Direct manufacturer partnerships displace traditional distributor relationships in Tuscany and Veneto event procurement. For Investors and Strategic Acquirers: European fiber-molding specialists with EUDR-aligned sourcing networks are the most active acquirer in this space, consolidating mid-scale Italian converters. Long-term viability hinges on composting infrastructure buildout across southern regions. Monitor MASE tender criteria evolution as the inflection signal for certification premium sustainability.| Strategic Initiative | Industry Significance |
|---|---|
| UNI EN 13432 Certification Investment | Unlocks preferential access to MASE circular economy tenders and institutional procurement channels. |
| Backward Integration into Fiber Supply | Captive bagasse sourcing from Iberian agricultural processors reduces freight cost volatility exposure. |
| Digital Print Customization Capability | On-demand branding technology enables personalized serveware for wedding and corporate event planners. |
| Thermoformer Line Retrofitting | Pulp-based production adaptation responds to Legislative Decree 116/2020 polystyrene capacity compression. |
| Direct-to-Event-Planner Partnership | Bypasses wholesale intermediaries to capture sustainability documentation premiums in Tuscany and Veneto. |
Research Methodology
Direct dialogue with thermoforming plant managers, foodservice procurement leads at catering operators, regional waste management coordinators, and MASE tender specification officers grounded qualitative insights. Secondary validation drew from UNI EN 13432 certification registries, MASE circular economy procurement databases, EUDR compliance documentation, and Italian customs trade records. Bottom-up converter capacity estimates and top-down foodservice demand modeling were triangulated to cross-verify volume assumptions.
Bottom-up analysis segmented the market by material type, product format, end-use channel, and regional waste infrastructure maturity across the projection horizon. CAGRs were derived from regression analysis against regulatory milestone timing and composting capacity buildout trajectories. Modeled inputs included fiber input cost indices, certification penetration rates by region, and municipal waste diversion target compliance schedules.
Inputs from MASE tender databases and UNI EN 13432 certification bodies were available through the study window; gaps in southern regional composting infrastructure deployment timelines introduce uncertainty bands around bagasse adoption forecasts. Periodic stress-testing of base assumptions against ECHA microplastic restriction enforcement and Iberian harvest yield variability is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Foodservice Packaging
France Disposal Tableware Market
Foodservice Packaging
Food Service Packaging (FSP) Market
Foodservice Packaging
Foodservice Disposable Packaging Market
Foodservice Packaging
Canada Foodservice Packaging Market
Foodservice Packaging
Bar and Prep Faucets Market
Foodservice Packaging
United States Disposable Tableware Market
Foodservice Packaging
Foodservice Paper Bags Market
Foodservice Packaging
Compostable Food Service Packaging Market
Foodservice Packaging
North America Foodservice Packaging Market
Foodservice Packaging
Compostable Food Service Tray Market