
 Corrugated Plastic Trays Market | 2026-2036
Corrugated Plastic Trays Market Size, Share, and Industry Trends Forecast 2026-2036
Corrugated Plastic Trays Market Outlook
China is narrowing its cost advantage in corrugated polypropylene tray extrusion as domestic resin prices converge with import parity. ORBIS Corporation leverages captive resin compounding to sustain margin stability across North American automotive contract accounts. Inteplast Group anchors its position through vertical sheet extrusion capacity in Texas and New Jersey. Berry Global differentiates via antimicrobial additive integration for food-contact tray specifications.
Corrugated plastic trays are twin-wall or triple-wall extruded polymer sheets thermoformed or die-cut into rigid, lightweight containers designed for multi-trip material handling and protective shipping. Polypropylene formulations dominate food-grade and cleanroom applications due to moisture resistance and steam-cleaning tolerance; high-density polyethylene variants compete in cold-chain and chemical-exposure environments. Nestable tray geometries command volume share in closed-loop distribution systems where empty return freight cost dictates total cost of ownership. Customized tray configurations capture premium positioning in electronics and medical device sectors where component-specific cavity design prevents transit damage.
FDA food-contact regulations and EU REACH substance restrictions govern resin additive packages and recycling content claims across major demand centers. EPA industrial emissions guidelines and OSHA workplace material handling standards influence tray specification in US manufacturing and warehousing operations. Stakeholders must monitor evolving extended producer responsibility frameworks and recycled content mandates that will reshape supplier qualification criteria and resin sourcing strategies.
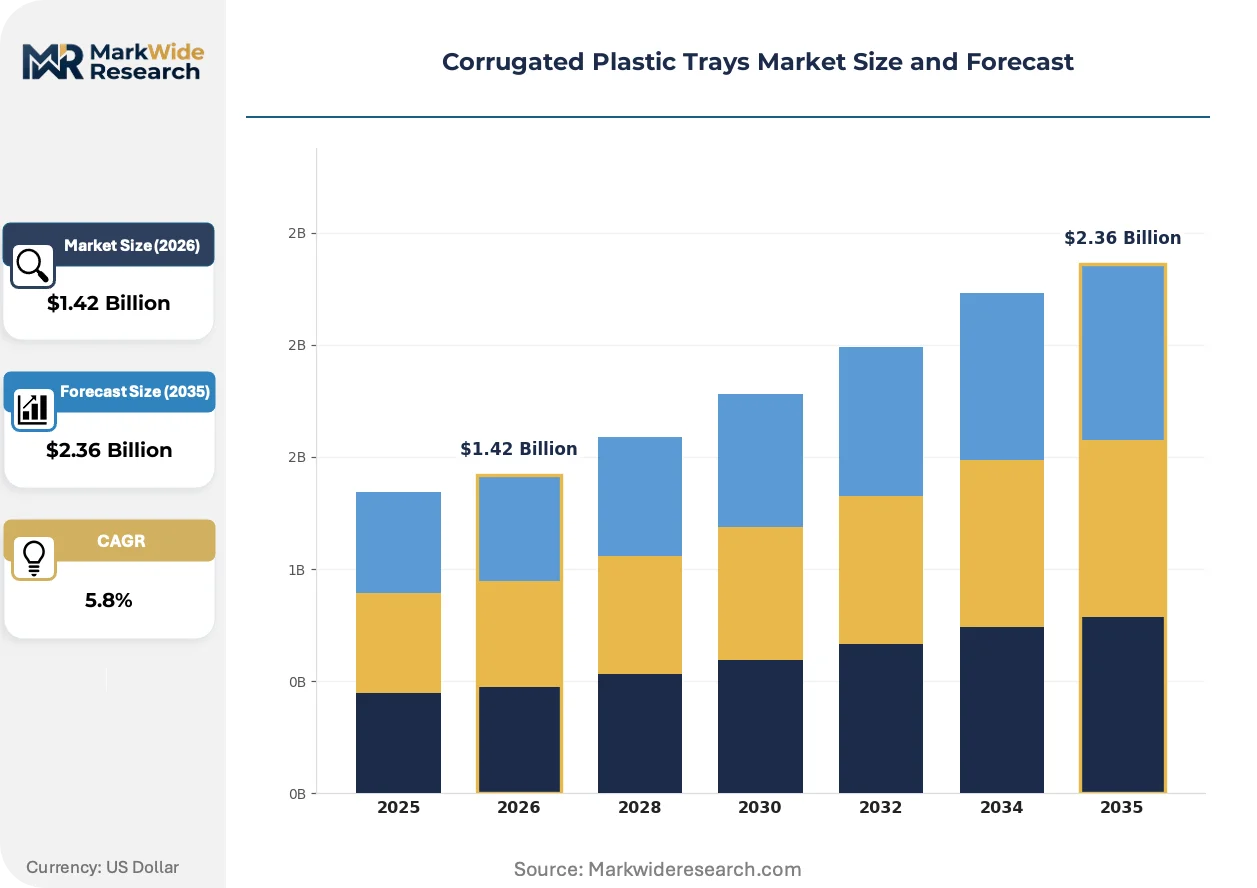
Market Dynamics
Closed-loop logistics economics are compressing total cost-of-ownership calculations for reusable transit packaging, forcing procurement officers to weigh empty-return freight efficiency against single-use alternatives. California agricultural operators and Bavarian automotive suppliers now mandate nestable tray geometries in supplier qualification protocols.
Growth Catalysts
- EU Packaging and Packaging Waste Regulation:Material traceability mandates are accelerating replacement of opaque single-use containers with certified reusable formats in cross-border produce distribution.
- Polypropylene steam-cleaning protocols:Food-grade processors in Germany's meatpacking sector specify moisture-resistant twin-wall trays for automated wash-and-return systems.
- California Central Valley cluster:Agricultural logistics operators are expanding captive tray fleets to eliminate cardboard disposal costs in seasonal harvest cycles.
Market Restraints
- Propylene resin price convergence:Chinese domestic resin costs are narrowing the historical cost advantage that favored Asian extrusion supply.
- Recycled content verification:EU REACH substance restrictions create compliance friction for additive packages claiming circular material content.
- Expanded polystyrene substitution:Cold-chain operators in temperature-sensitive pharmaceutical distribution retain insulated foam formats despite handling inefficiencies.
Strategic Opportunities
- Antimicrobial additive integration:FDA food-contact pathway approvals enable premium positioning in ready-to-eat meal kit packaging segments.
- Texas and New Jersey sheet extrusion hubs:Captive resin compounding capacity supports margin stability for North American automotive contract accounts.
- Electronics cavity customization:Component-specific tray design for semiconductor wafer shipping commands price premiums in cleanroom logistics.
Industry Challenges
- Extended producer responsibility compliance:Divergent state-level recycling mandates in the US fragment tray qualification requirements for national distributors.
- Multi-material separation:Adhesive-bonded label and RFID tag removal complicates mechanical recycling streams for end-of-life trays.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Corrugated Plastic Trays Market |
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.36 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stackable Trays, Nestable Trays, Folding Trays, Customized Trays End User: Agriculture, Food Packaging, Electronics, Retail Material Type: High-Density Polyethylene, Polypropylene, Recycled Plastic, Others Distribution Channel: Direct Sales, Online Retail, Distributors, wholesalers |
| Companies Covered | DS Smith Plc, Smurfit Kappa Group, WestRock Company, International Paper Company, Berry Global, Inc., Inteplast Group Corporation, ORBIS Corporation, Sealed Air Corporation, Sonoco Products Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Corrugated Plastic Trays Market Strategic Shifts
Material science advances and regulatory stringency are converging to redefine performance specifications across food-contact, automotive, and electronics verticals. Tray geometry optimization and additive integration now determine competitive positioning more than base resin cost.
High-density polyethylene formulations are migrating from cold-chain dairy distribution into chemical-exposure industrial applications. Chemical processors in Texas refineries specify HDPE trays for solvent-handling operations where polypropylene exhibits stress-cracking vulnerability. This material shift is compressing the historical dominance of polypropylene in general-purpose industrial logistics.
EU REACH substance restrictions are tightening additive package approvals for recycled content claims in food-contact applications. ECHA evaluation of antioxidant and UV stabilizer chemistries is extending compliance timelines for circular material certifications. German packaging suppliers are responding by segregating food-grade and non-food tray production lines to isolate regulatory risk.
Buyer consolidation among third-party logistics providers is concentrating procurement decisions for reusable packaging fleets. Regional 3PL operators in the US Midwest are standardizing on nestable tray footprints to maximize cube utilization in backhaul lanes. This specification convergence favors tray manufacturers with modular die-cutting capabilities over custom-molded specialists.
Corrugated Plastic Trays Market Segmentation
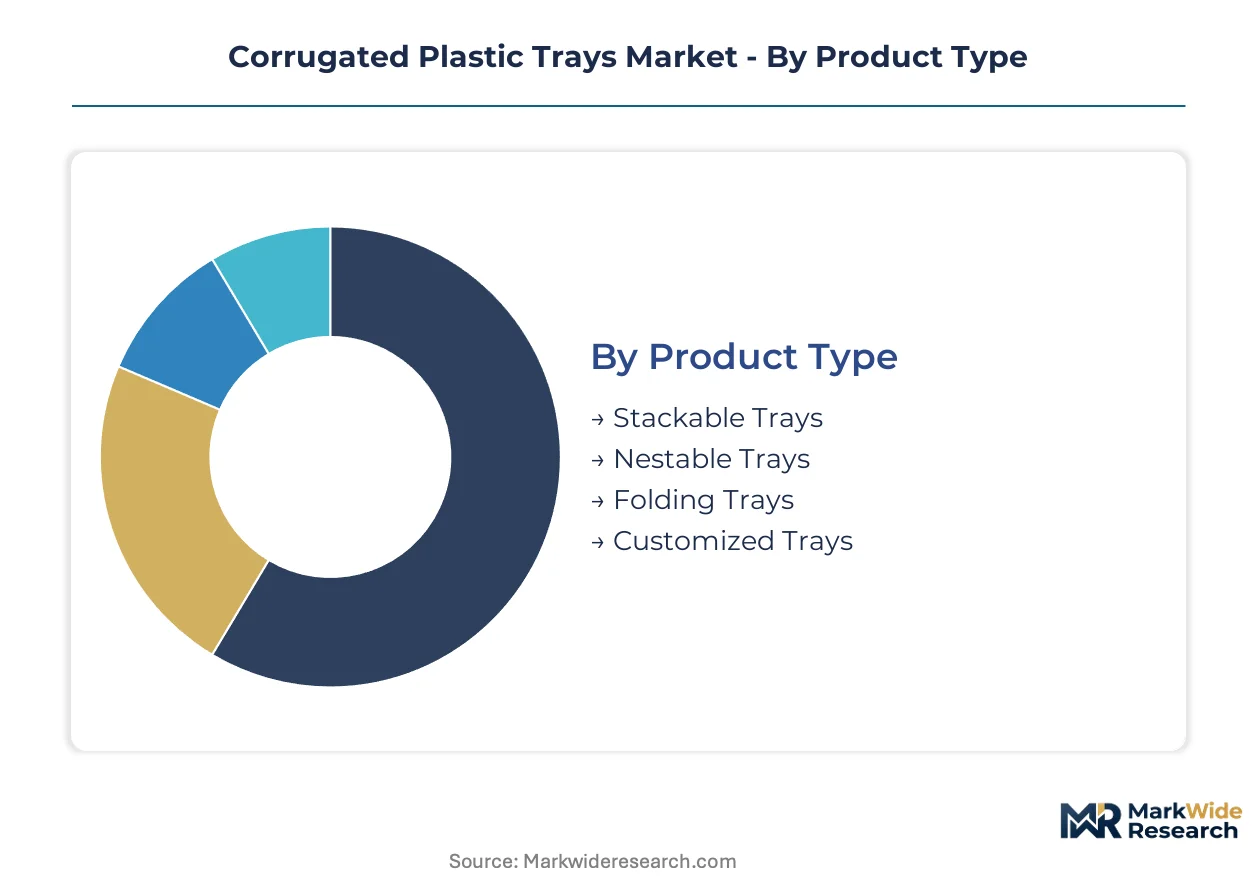
Corrugated plastic tray manufacturers differentiate offerings across four structural dimensions that directly determine service intensity, margin profiles, and customer retention economics. Product geometry governs logistics efficiency in closed-loop systems. End-use verticals impose divergent regulatory and performance specifications. Material chemistry shapes recycling pathways and compliance burden. Channel configuration dictates technical support requirements and account management investment.
Product Type:
After-sales-service intensity escalates sharply with product complexity, as nestable and folding geometries require fleet optimization consulting and wash-system compatibility engineering that stackable commodity formats rarely demand.
- Nestable Trays:Twin-wall polypropylene sheets thermoformed with tapered sidewalls enable vertical nesting ratios of 4:1 to 6:1, minimizing empty-return freight cube. California agricultural logistics operators and Bavarian automotive suppliers now mandate nestable footprints in supplier qualification protocols to maximize backhaul density.
- Customized Trays:Component-specific cavity designs for semiconductor wafer shipping and medical device protection require collaborative design iteration, prototype validation, and cleanroom certification support. Electronics manufacturers in Germany's Saxony cluster and Texas semiconductor corridors drive specification complexity.
- Stackable Trays:Rigid rectangular formats with flat bases and reinforced corners serve general-purpose industrial applications where standardization outweighs return-logistics optimization.
- Folding Trays:Hinged or collapsible geometries reduce empty storage volume for seasonal agricultural harvest cycles and event-driven retail distribution.
Nestable trays hold the largest share; momentum sits with customized configurations.
End User:
Application-driven specification divergence creates distinct margin tiers, with electronics and food packaging commanding premium positioning against agricultural commodity procurement.
- Food Packaging:FDA food-contact regulations and EU REACH substance restrictions govern resin additive packages for meatpacking automation in Germany and ready-to-eal meal kit distribution in US coastal markets. Steam-cleaning tolerance and antimicrobial additive integration differentiate supplier positioning.
- Electronics:Cleanroom logistics for semiconductor wafer shipping and medical device protection require ESD-safe formulations and particle-count certification. Component-specific cavity design prevents transit damage in high-value supply chains.
- Agriculture:Seasonal harvest cycles in California's Central Valley drive demand for moisture-resistant twin-wall formats that eliminate cardboard disposal costs.
- Retail:Point-of-sale display and reverse logistics applications favor lightweight nestable geometries with printed branding surfaces.
Food packaging commands the largest volume position; electronics delivers the steepest expansion trajectory.
Material Type:
Resin chemistry determines regulatory compliance burden, mechanical recycling feasibility, and performance boundaries across temperature and chemical exposure environments.
- Polypropylene:Dominates food-grade and cleanroom applications due to moisture resistance, steam-cleaning tolerance, and broad FDA food-contact approvals. Twin-wall extrusions serve automated wash-and-return systems in German meatpacking operations.
- High-Density Polyethylene:Competes in cold-chain dairy distribution and chemical-exposure industrial applications where polypropylene exhibits stress-cracking vulnerability. Texas refinery operators specify HDPE for solvent-handling operations.
- Recycled Plastic:Post-industrial and post-consumer content claims face EU REACH verification friction for additive package approvals in food-contact applications.
- Others:Specialty formulations including conductive polymers and flame-retardant compounds serve niche electronics and aerospace logistics requirements.
Polypropylene retains dominant share; recycled content formulations are climbing fastest amid ESG procurement mandates.
Distribution Channel:
Channel selection reflects customer scale, technical complexity, and geographic concentration, with direct sales capturing strategic accounts and distributors serving fragmented regional demand.
- Direct Sales:Captive engineering resources support collaborative design for automotive tier-1 suppliers and multinational food processors requiring fleet optimization consulting and wash-system integration.
- Distributors:Regional inventory positioning and technical support serve mid-sized agricultural cooperatives and independent electronics contract manufacturers.
- Wholesalers:Volume aggregation and price-focused procurement serve commodity industrial applications with minimal customization requirements.
- Online Retail:Standardized catalog formats with rapid fulfillment serve small-batch prototyping, replacement fleet expansion, and emergency stockout coverage.
Direct sales holds the largest revenue concentration; distributor relationships are expanding most quickly in agricultural verticals.
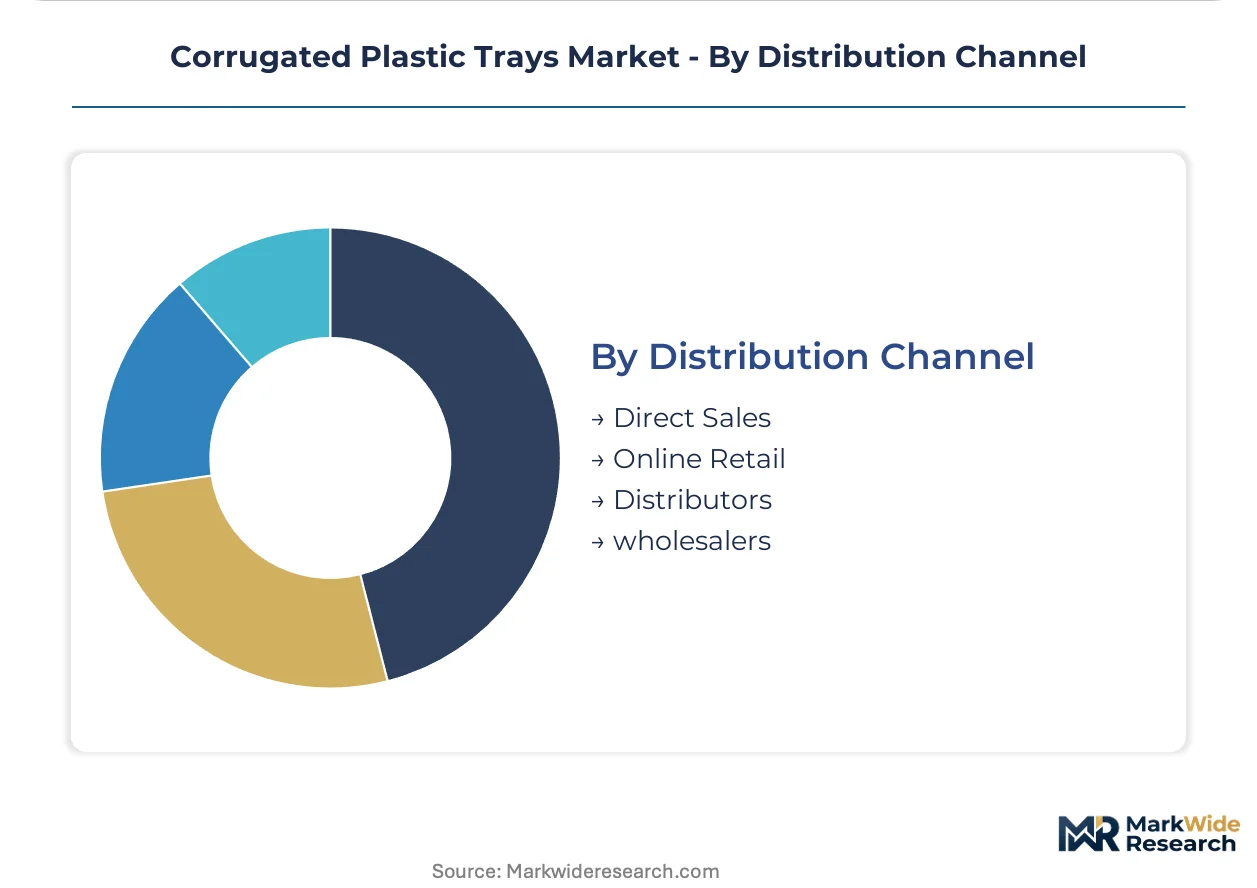
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA food-contact regulations anchor the United States as the dominant geography, with California agricultural logistics and Texas chemical processing driving specification divergence across material types and tray geometries.
United States
California Central Valley agricultural operators are expanding captive reusable tray fleets to eliminate seasonal cardboard disposal costs. EPA industrial emissions guidelines influence tray specification in manufacturing and warehousing operations. Texas refinery operators in the Houston Ship Channel cluster specify high-density polyethylene trays for solvent-handling operations where polypropylene exhibits stress-cracking vulnerability.
Germany
EU REACH substance restrictions govern resin additive packages and recycling content claims for food-contact applications. ECHA evaluation of antioxidant and UV stabilizer chemistries extends compliance timelines for circular material certifications. Bavarian automotive component suppliers in the Munich-Stuttgart corridor standardize on nestable returnable packaging formats to maximize backhaul density in supplier qualification protocols.
China
Domestic propylene resin prices are converging with import parity, narrowing the historical cost advantage that favored Asian extrusion supply. SAMR material traceability requirements tighten compliance for cross-border produce distribution. Yangtze River Delta manufacturing clusters are upgrading sheet extrusion capacity to serve electronics and automotive contract accounts with customized tray configurations.
Japan
METI cleanroom logistics standards drive specification complexity for semiconductor wafer shipping applications. JIS certification requirements for ESD-safe formulations create qualification barriers for imported tray suppliers. Kyushu electronics manufacturing corridors demand component-specific cavity designs that prevent transit damage in high-value supply chains.
India
FSSAI food-contact regulations govern resin additive approvals for meatpacking and ready-to-eal meal kit distribution. BIS standards for reusable transit packaging are evolving under industrial logistics modernization programs. Maharashtra agricultural cooperatives in the Nashik-Pune belt are piloting moisture-resistant twin-wall formats to replace corrugated cardboard in seasonal harvest cycles.
Corrugated Plastic Trays Market Competitive Environment
Capability concentration sits with customized tray specialists; scale advantage sits with integrated resin compounders and sheet extruders. The vendor base organizes around three strategic archetypes: captive resin compounders with backward integration into polymer supply, modular die-cutting specialists serving fragmented regional demand, and cleanroom-certified fabricators targeting electronics and medical device verticals. Dominant competitive moves include geographic expansion through distributor partnerships and portfolio diversification into antimicrobial additive integration for food-contact specifications.
Among North American integrated manufacturers, ORBIS Corporation, Inteplast Group Corporation, and Berry Global, Inc. exemplify distinct strategic positions. ORBIS Corporation represents the captive resin compounding archetype with margin stability across automotive contract accounts. Inteplast Group Corporation anchors the regional sheet extrusion tier through Texas and New Jersey manufacturing presence. Berry Global, Inc. occupies a position emphasizing antimicrobial additive integration for food-contact tray specifications and FDA pathway compliance.
| Leading Market Players |
|---|
| DS Smith Plc |
| Smurfit Kappa Group |
| WestRock Company |
| International Paper Company |
| Berry Global, Inc. |
| Inteplast Group Corporation |
| ORBIS Corporation |
| Sealed Air Corporation |
| Sonoco Products Company |
| Others |
Value Chain & Pricing Dynamics
California's Central Valley agricultural freight corridors compress empty-return logistics costs for reusable tray fleets, concentrating procurement power among operators with dedicated backhaul networks and forcing price differentiation between nestable geometries and commodity stackable formats.
Pricing Analysis
Geographic price spreads between North American and Asian extrusion supply have narrowed as Chinese domestic propylene resin costs converge with import parity. Contract-based long-term offtake agreements dominate automotive and food-processor accounts, while spot procurement serves seasonal agricultural demand. Price differentiation rests on certification tier (FDA food-contact versus industrial-grade) and customization depth, with electronics cavity specifications commanding substantial premiums. Cost compression in standard nestable formats is intensifying due to captive resin compounding at integrated manufacturers, rendering mid-tier suppliers most price-sensitive while cleanroom-certified fabricators retain pricing power.
Supply Chain Analysis
Upstream propylene and ethylene feedstock supply concentrates in the United States Gulf Coast, Saudi Arabia, and China, with resin compounding capacity clustering in Texas, New Jersey, and the Yangtze River Delta. Tray manufacturing draws from twin-wall sheet extrusion, additive masterbatch supply, and die-cutting tooling as critical inputs. Single-source vulnerability in specialized antimicrobial additive packages creates compliance risk for food-contact certification claims. Distribution runs through direct sales for automotive tier-1 accounts and regional distributors serving fragmented agricultural cooperatives.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU Packaging and Packaging Waste Regulation material traceability mandates constitute a regulatory inflection that disrupts incumbent single-use container positions and accelerates reusable format substitution across produce distribution networks.
For Market Incumbents: Insulate automotive contract margins through backward integration into captive resin compounding capacity in Texas and New Jersey, while isolating food-grade production lines to contain EU REACH additive compliance risk from industrial tray operations. Threat substitution from expanded polystyrene cold-chain formats demands antimicrobial additive R&D investment to penetrate ready-to-eal meal kit segments.
For New Entrants and Emerging Players: Establish a beachhead in Maharashtra agricultural cooperatives piloting moisture-resistant twin-wall formats, where corrugated cardboard replacement cycles create fleet expansion demand without incumbent lock-in. Electronics contract manufacturers in India's Nashik-Pune belt represent penetrable white-space for cleanroom-certified customized tray configurations. Go-to-market leverage rests on distributor partnerships with regional logistics providers standardizing nestable footprints.
For Investors and Strategic Acquirers: EU extended producer responsibility frameworks reshape the acquisition landscape toward modular die-cutting specialists with rapid customization capabilities over custom-molded capital-intensive positions. Long-term viability favors targets with segregated food-grade production infrastructure and SAMR traceability compliance for China cross-border access. Signal concentration sits with ECHA antioxidant and UV stabilizer evaluation timelines as circular certification inflection indicators.
| Strategic Initiative | Industry Significance |
|---|---|
| Captive Resin Compounding Expansion | Margin stability for ORBIS Corporation across North American automotive contract accounts. |
| Antimicrobial Additive Integration | Premium positioning for Berry Global in FDA food-contact ready-to-eat meal kit specifications. |
| Modular Die-Cutting Capacity Addition | Flexibility capture for mid-tier specialists serving 3PL procurement standardization in the US Midwest. |
| Cleanroom Certification Investment | Barrier creation against imports for Japan METI ESD-safe semiconductor wafer shipping applications. |
| Regional Distributor Partnership | Channel depth for agricultural vertical penetration in California Central Valley captive fleet expansions. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of regulatory filings, trade customs data, and industry association disclosures to establish resin price convergence patterns and tray fleet deployment metrics. Primary interviews engaged procurement officers at California agricultural logistics operators, Bavarian automotive tier-1 supplier packaging engineers, and German meatpacking automation specialists. Secondary validation drew from EPA industrial emissions guidelines, EU ECHA substance restriction evaluations, and SAMR material traceability requirements. Bottom-up demand modeling across end-use verticals triangulates against top-down resin consumption estimates from extrusion capacity analysis.
Forecast inputs include polypropylene versus high-density polyethylene substitution rates, nestable geometry adoption curves in closed-loop logistics, and antimicrobial additive approval timelines through FDA food-contact pathways. Segmentation dimensions span product geometry complexity, end-use regulatory tier, material chemistry compliance burden, and channel technical support intensity. CAGRs derive from elasticity-adjusted volume projections across the analysis window, with scenario weighting for EU extended producer responsibility implementation pace and China resin price parity convergence.
Sensitivities concentrate around ECHA additive package evaluation delays, propylene feedstock price volatility from Gulf Coast supply disruptions, and 3PL buyer consolidation altering procurement concentration. Cross-checking against FAO produce trade flow data and automotive production registration databases is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Plastic Packaging
Conductive Plastic Boxes Market
Plastic Packaging
Polyethylene Mailers Market
Plastic Packaging
Plastic Carboy Market
Plastic Packaging
Plant-Based Plastic Packaging Market
Plastic Packaging
Disposable Straw Market
Plastic Packaging
Middle East and Africa Plastic Bottles Market
Plastic Packaging
Canada Plastic Bottles Market
Plastic Packaging
Global Plastic Straps Market
Plastic Packaging
Recycled Plastic Envelope Market
Plastic Packaging
FFS Rigid Films Market
Plastic Packaging
Global Single Use Plastic Packaging Market
Plastic Packaging
Plastic Films Market
Plastic Packaging
United States Plastic Packaging Films Market
Plastic Packaging
E-Commerce Plastic Packaging Market
Plastic Packaging
Global Stretch Films Market
Plastic Packaging
Nigeria Plastic Bottles Market