
 Pillow Pack Packaging Market | 2026-2036
Pillow Pack Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Pillow Pack Packaging Market Analytics
Capital-intensity divergence between high-throughput film extruders and regional converters is bifurcating competitive tiers in pillow pack packaging. Amcor leverages integrated resin-to-pouch operations across multiple continents. Mondi Group anchors European demand through kraft-paper hybrid lines. Sealed Air differentiates via automated fulfillment-ready formats.
Pillow pack packaging denotes a flexible pouch formed from two flat film webs sealed on three edges, typically produced through horizontal form-fill-seal (HFFS) or vertical form-fill-seal (VFFS) processes at speeds exceeding 200 units per minute. The format serves primary containment for dry goods, liquids, and flowable products requiring barrier protection against moisture and oxygen. Plastic material commands volume leadership due to cost-efficient multilayer coextrusion, though paper substrates are gaining structural share as brand owners pursue fiber-based alternatives. Food packaging applications generate the dominant revenue pool, while pharmaceuticals represent the fastest-expanding end-use segment driven by unit-dose compliance requirements.
EMA guidelines on primary packaging materials, FDA food contact substance notifications, and EU REACH restrictions on per- and polyfluoroalkyl substances collectively reshape material selection and migration testing protocols for pillow pack suppliers. The EU Green Deal's packaging recyclability mandates are accelerating design-for-recycling investments across the value chain. Stakeholders must monitor evolving extended producer responsibility schemes and decide between retrofitting existing lines or greenfield investment in mono-material-compatible equipment.
Market Dynamics
EU REACH restrictions on per- and polyfluoroalkyl substances are forcing pillow pack converters to accelerate mono-material redesigns ahead of recyclability mandates, compressing development timelines by half while raising qualification costs.
Growth Catalysts
- Snack Food Single-Serve Expansion:Convenience retailers are scaling pillow pack formats for portion-controlled nuts, chips, and confectionery, with HFFS lines running at 400 units per minute to match throughput demands.
- EU Packaging and Packaging Waste Regulation:Material recovery targets are tightening to 70% by 2030, pulling investment into compatible sealing technologies and post-consumer recycled resin integration.
- Pharmaceutical Unit-Dose Compliance:EMA guidelines on primary packaging materials are driving demand for barrier pillow packs with child-resistant features and tamper-evident seals.
Market Restraints
- Resin Price Volatility:Ethylene and propylene feedstock swings are compressing converter margins, with multilayer coextrusion lines requiring 40% more working capital than mono-material alternatives.
- Film Extruder Concentration:High-throughput blown film capacity clusters in Germany's Hamburg-Düsseldorf corridor, creating geographic supply risk for regional converters lacking backward integration.
- Migration Testing Burden:FDA food contact substance notifications demand 18-month qualification cycles for new barrier coatings, freezing material innovation pipelines.
Strategic Opportunities
- India Pharmaceutical Export Growth:CDSCO packaging regulations are harmonizing with ICH standards, opening pillow pack demand for contract manufacturers supplying regulated markets.
- Paper-Plastic Hybrid Convergence:Kraft-paper barrier laminates are penetrating premium dry goods segments where fiber-based claims command shelf price premiums.
- Automated Fulfillment Formats:E-commerce-ready pillow packs with tear-notches and reseal zippers are capturing direct-to-consumer snack subscription channels.
Industry Challenges
- Mono-Material Equipment Retrofit Costs:Existing VFFS lines require €2-4 million upgrades to handle sealant-layer variations without compromising 200+ unit-per-minute speeds.
- Migration Testing Talent Scarcity:Analytical chemists with combined polymer science and regulatory submission expertise are concentrated in Basel and Boston, driving compensation premiums.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pillow Pack Packaging Market |
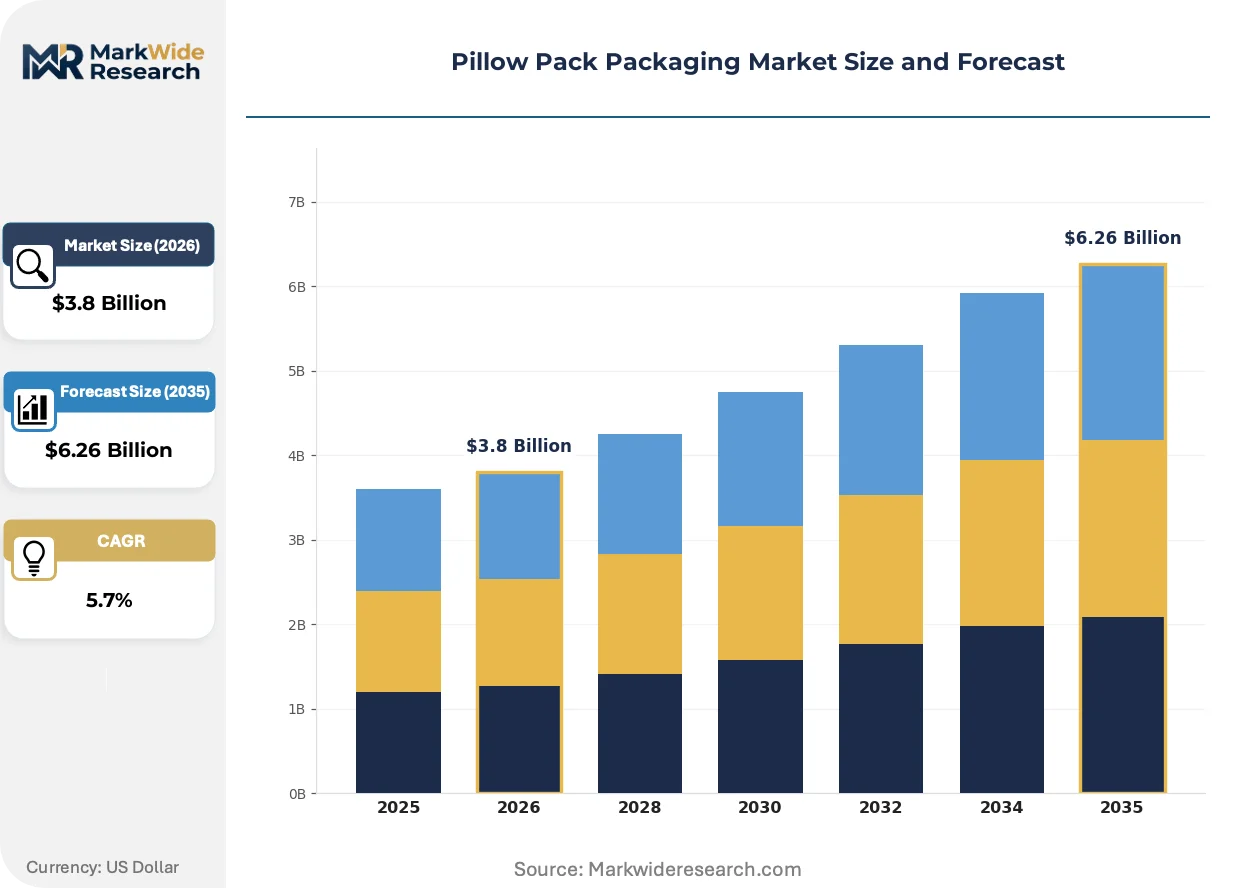
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Food Packaging, Personal Care, Pharmaceuticals, Electronics Material: Plastic, Paper, Aluminium Foil, Composite End User: Manufacturers, Retailers, Distributors, E-Commerce Size: Small, Medium, Large, Custom |
| Companies Covered | Amcor, Mondi Group, Sealed Air, Berry Global, Huhtamaki, ProAmpac, Constantia Flexibles, WestRock Company, Printpack, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pillow Pack Packaging Market Evolving Landscape
Active redesign of material stacks and sealing architectures is compressing development cycles while expanding addressable applications beyond traditional dry goods containment.
Water-based barrier coatings are supplanting solvent-based adhesives and fluorinated treatments in mid-barrier applications. Snack food brand owners in Germany and the Netherlands are qualifying these coatings at 18-month replacement cycles. The shift is compressing incumbent chemical suppliers' formulation revenue while enabling paper substrate penetration.
EU Green Deal packaging recyclability mandates are accelerating design-for-recycling investments across the value chain. Mono-material polyethylene structures are displacing multilayer nylon-EVOH constructions in oxygen-sensitive applications. Pharmaceutical contract packagers in Ireland and Denmark are piloting these structures for solid oral dose products ahead of 2030 extended producer responsibility thresholds.
Brand owner procurement teams are consolidating supplier panels around integrated resin-to-pouch capabilities. Regional converters without captive film extrusion are losing share to competitors with in-house blown film and metallization. The consolidation is most visible in France and Italy, where mid-size food brands are reducing qualified supplier bases from twelve to four vendors.
Pillow Pack Packaging Market Segmentation
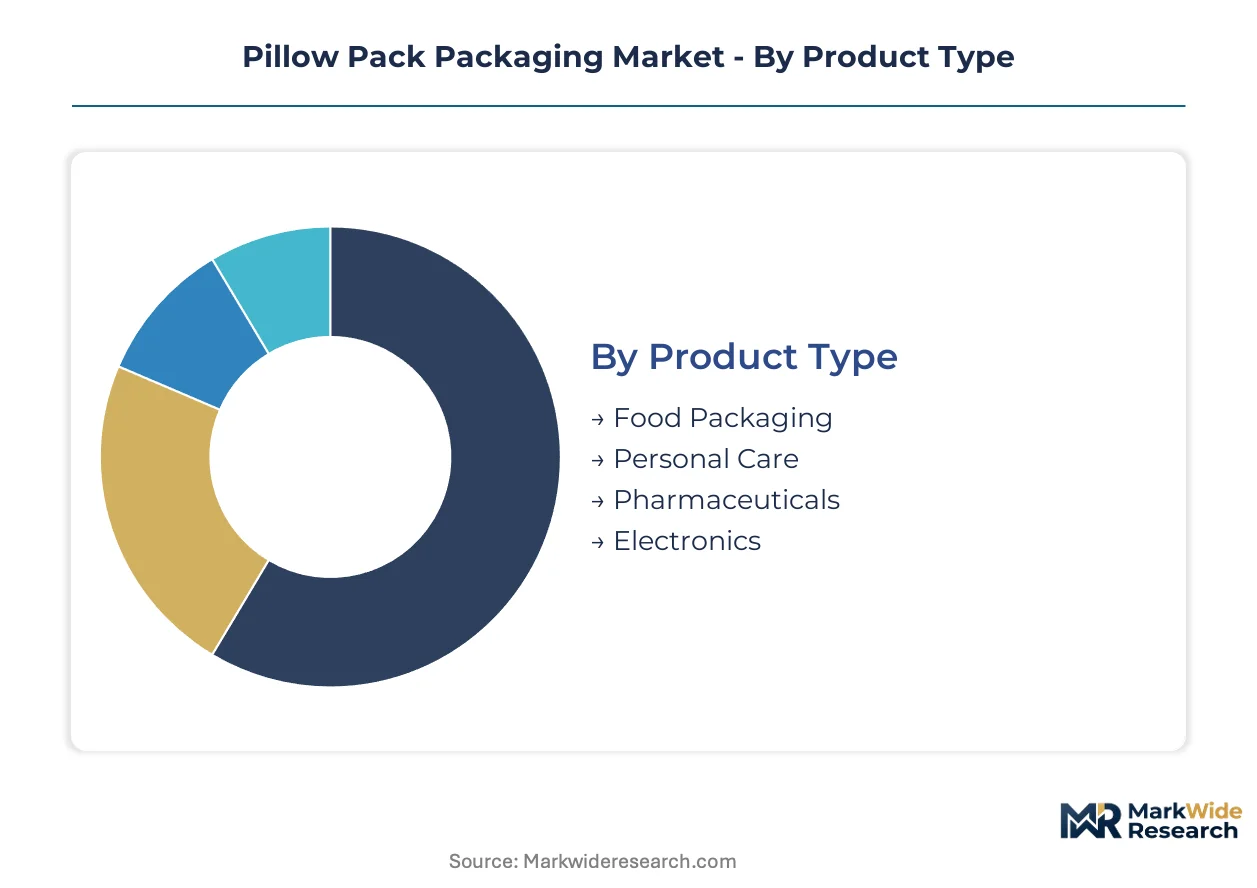
Pillow pack packaging serves divergent performance requirements across food safety, pharmaceutical barrier, and consumer convenience applications. Segmentation reveals where material substitution pressures and regulatory compliance burdens concentrate most intensely.
Product Type:
Substitution pressure from rigid formats and alternative flexible structures varies sharply across end-use applications, with food and pharma facing the most intense redesign mandates.
- Food Packaging:Multilayer coextruded structures dominate dry goods, snacks, and confectionery containment. EU REACH restrictions on fluorinated barriers are forcing German and Dutch brand owners toward water-based coatings at 18-month replacement cycles.
- Pharmaceuticals:Unit-dose barrier packs with child-resistant closures and tamper-evident seals serve solid oral dose compliance. EMA guidelines on primary packaging materials are driving fastest expansion in Ireland and Denmark contract packaging facilities.
- Personal Care:Sachet and sample formats for lotions and serums utilize metallized films for aesthetic shelf presence.
- Electronics:Static-dissipative films protect sensitive components during distribution, with moisture barrier requirements lower than pharmaceutical grades.
Food packaging anchors the volume base while pharmaceuticals gains share at the steepest rate.
Material:
Cost tier stratification separates commodity resin converters from premium substrate specialists, with recyclability mandates compressing the middle ground.
- Plastic:Polyethylene and polypropylene multilayer constructions deliver cost-efficient oxygen and moisture barriers through coextrusion. Hamburg-Düsseldorf corridor extruders supply high-throughput blown film to European converters facing 70% material recovery targets.
- Paper:Kraft-paper barrier laminates penetrate premium dry goods where fiber-based claims command shelf price premiums. Mondi Group anchors European supply through integrated pulp-to-pouch operations.
- Aluminium Foil:Ultra-high barrier metallized layers serve pharmaceutical unit-dose and sensitive electronics applications.
- Composite:Hybrid paper-plastic constructions balance sustainability messaging with functional barrier performance for mid-tier food brands.
Plastic retains the dominant cost position while paper climbs fastest toward structural share gains.
End User:
Customer type determines order scale, customization depth, and qualification burden, with manufacturers and e-commerce platforms pulling format innovation in opposite directions.
- Manufacturers:Food and pharmaceutical producers demand high-volume HFFS and VFFS compatibility with line speeds exceeding 200 units per minute. FDA food contact substance notifications impose 18-month qualification cycles that freeze material innovation pipelines.
- E-Commerce:Direct-to-consumer snack subscription channels require automated fulfillment formats with tear-notches and reseal zippers. Sealed Air differentiates via fulfillment-ready designs capturing this channel.
- Retailers:Private-label programs consolidate supplier panels around integrated resin-to-pouch capabilities, squeezing regional converters without captive extrusion.
- Distributors:Inventory-holding intermediaries serve smaller manufacturers lacking direct converter relationships, adding margin layers to low-volume orders.
Manufacturers anchor procurement volume while e-commerce expands most quickly as a demand channel.
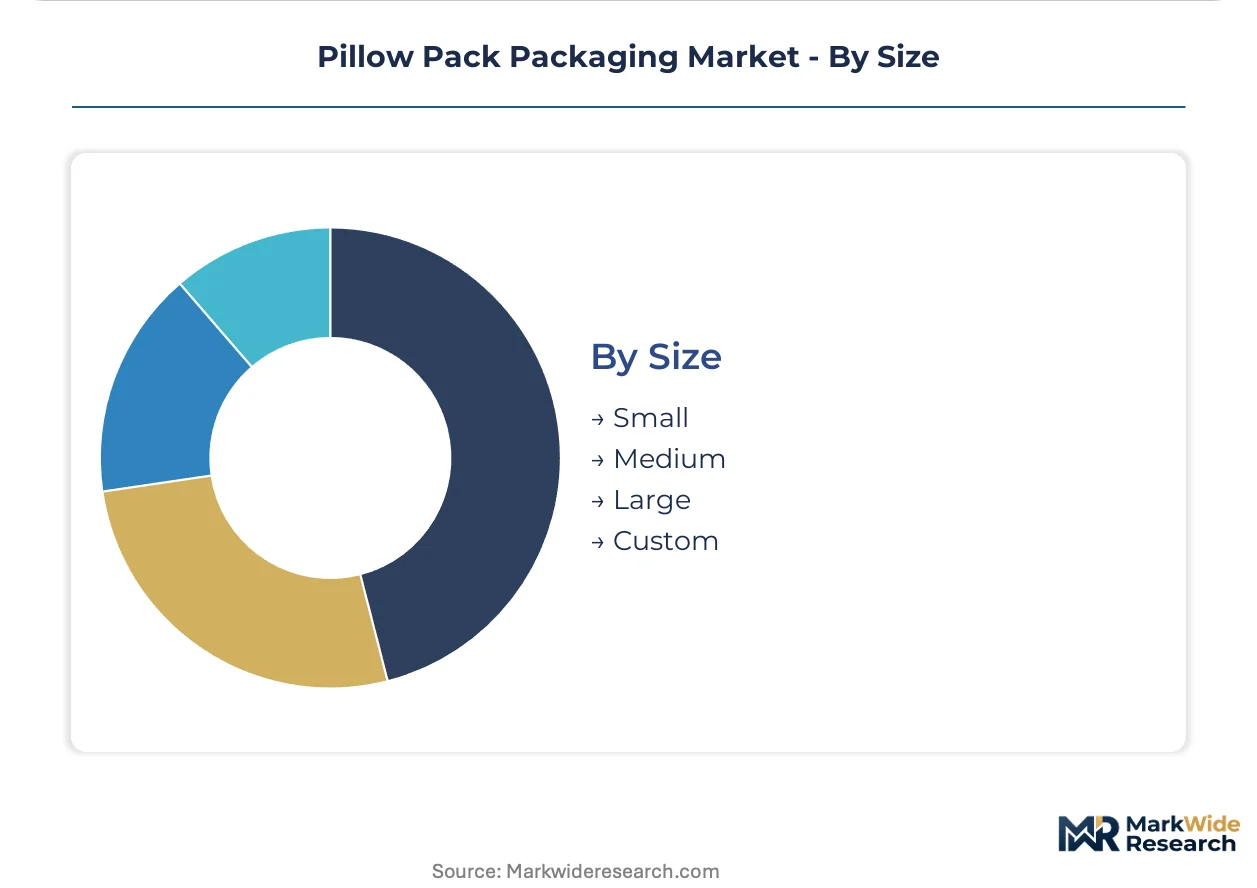
Size:
Volume scale drives equipment utilization and margin structure, with custom formats commanding premium pricing but disrupting production efficiency.
- Small:Single-serve portions for nuts, chips, and confectionery run on HFFS lines at 400 units per minute. Convenience retailers in Germany and the Netherlands are scaling this format most aggressively.
- Medium:Standard household sizes balance shelf presence with consumption velocity for mainstream dry goods brands.
- Large:Club-store and food-service formats prioritize cost-per-unit efficiency over premium aesthetics.
- Custom:Irregular dimensions for promotional packs and seasonal SKUs require frequent changeovers that compress converter throughput.
Small formats anchor volume throughput while custom sizes command the widest margin spreads.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German converters command 15-20% price premiums over Indian competitors due to integrated film extrusion capabilities. US manufacturers offset higher labor costs through automation density. Chinese suppliers compete on resin sourcing proximity but face escalating compliance burdens.
United States
Snack food brand owners in California and Texas are scaling single-serve pillow pack formats for convenience retail channels. FDA food contact substance notifications impose 18-month qualification cycles that freeze material innovation pipelines. Chicago and Atlanta host contract packaging clusters where HFFS lines run at 400 units per minute.
Germany
The EU Packaging and Packaging Waste Regulation is pulling investment into 70% material recovery targets by 2030. Hamburg and Düsseldorf anchor Europe's flexible packaging corridor with high-throughput blown film capacity. Mondi Group operates kraft-paper hybrid lines serving premium dry goods segments.
India
Pharmaceutical contract manufacturers in Maharashtra and Gujarat are expanding pillow pack output for export markets. CDSCO packaging regulations are harmonizing with ICH standards, opening demand for barrier unit-dose formats. Mumbai-Pune belt facilities serve European and North American regulated markets.
China
Domestic snack brands are adopting automated fulfillment-ready pillow packs for e-commerce subscription channels. NMPA guidelines on pharmaceutical packaging materials are tightening barrier performance requirements. Yangtze River Delta converters supply both domestic food brands and export-oriented pharmaceutical contract manufacturers.
Netherlands
Water-based barrier coating adoption is accelerating ahead of EU REACH restrictions on fluorinated treatments. Rotterdam and Amsterdam host pilot facilities for mono-material polyethylene structures displacing multilayer nylon-EVOH constructions. Dutch brand owners are qualifying these coatings at 18-month replacement cycles.
Pillow Pack Packaging Market Competitive Landscape
Concentration sits with integrated resin-to-pouch operators possessing captive film extrusion and metallization capabilities. Regional converters without backward integration face margin compression as procurement panels consolidate supplier bases. Three archetypes dominate: multinational integrated players, European kraft-paper specialists, and North American automation-focused fabricators. Competitive moves center on mono-material equipment retrofits and design-for-recycling partnerships with brand owners.
Within the integrated multinational tier, Amcor leverages resin-to-pouch operations across multiple continents. Mondi Group anchors European demand through pulp-to-pouch kraft-paper capabilities. Sealed Air occupies a position in automated fulfillment-ready formats capturing direct-to-consumer channels. These three exemplify the capability sets—geographic scale, fiber-based substrates, and e-commerce optimization—that procurement panels are consolidating around.
| Leading Market Players |
|---|
| Amcor |
| Mondi Group |
| Sealed Air |
| Berry Global |
| Huhtamaki |
| ProAmpac |
| Constantia Flexibles |
| WestRock Company |
| Printpack |
| Others |
Value Network & Pricing Analysis
Long-term resin offtake contracts with Hamburg-Düsseldorf corridor extruders lock in polyethylene supply visibility and buffer German converters against ethylene feedstock swings while compressing margin flexibility for regional competitors lacking backward integration.
Pricing Analysis
The customization-premium spread separates standard multilayer coextrusion pricing from configured-to-order mono-material structures with water-based barrier coatings. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and volume scale, with FDA food contact qualification tiers commanding widest spreads. Cost compression in standard plastic tiers is intensifying because brand owner procurement panels are consolidating supplier bases. E-commerce direct-to-consumer channels exhibit lowest price sensitivity due to fulfillment-ready format premiums, while commodity snack food manufacturers drive hardest bargain negotiations.
Supply Chain Analysis
Germany and China anchor high-throughput blown film production for pillow pack substrates, with Hamburg-Düsseldorf corridor extruders supplying European converters and Yangtze River Delta facilities serving domestic and export pharmaceutical contract manufacturers. The supply chain draws from ethylene and propylene feedstocks, metallized film layers, and water-based coating chemistries. Single-source vulnerability concentrates in fluorinated barrier chemistries facing EU REACH phase-out timelines. Distribution runs through converter-direct relationships with multinational food and pharmaceutical brand owners, bypassing inventory-holding intermediaries for volume accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward consolidated procurement panels at multinational food and pharmaceutical brand owners, squeezing regional converters without captive film extrusion capabilities.
For Market Incumbents: Shield market position by accelerating mono-material equipment retrofits ahead of EU Green Deal recyclability mandates, and deepen upstream control over blown film capacity in the Hamburg-Düsseldorf corridor to defend against resin price volatility. The priority lever sits with qualification speed for water-based barrier coatings as fluorinated treatments face regulatory phase-out. For New Entrants and Emerging Players: Anchor in Indian pharmaceutical contract manufacturing clusters around Maharashtra and Gujarat, where CDSCO harmonization with ICH standards is opening barrier unit-dose demand for export markets. The most penetrable segment combines automated fulfillment-ready formats for direct-to-consumer snack subscription channels. Go-to-market execution should emphasize rapid FDA food contact qualification cycles to bypass 18-month incumbent pipelines. For Investors and Strategic Acquirers: Capital is best deployed toward integrated resin-to-pouch operators with captive film extrusion and metallization capabilities, as procurement panel consolidation favors geographic scale and fiber-based substrate diversification. Long-term viability hinges on design-for-recycling partnerships with brand owners ahead of extended producer responsibility thresholds. The signal to watch is equipment retrofit commitment rates among mid-tier European converters.| Strategic Initiative | Industry Significance |
|---|---|
| Mono-Material Equipment Retrofit | Enables EU Green Deal compliance while preserving HFFS line speeds above 200 units per minute. |
| Water-Based Barrier Coating Qualification | Replaces fluorinated treatments facing EU REACH restrictions with 18-month replacement cycles at Dutch pilot facilities. |
| Backward Integration into Film Extrusion | Captures margin compression from resin price volatility and defends against procurement panel consolidation. |
| Automated Fulfillment Format Development | Captures direct-to-consumer snack subscription channels with tear-notches and reseal zippers. |
| Pharmaceutical Unit-Dose Certification Investment | Aligns with EMA guidelines on primary packaging materials and CDSCO-ICH harmonization for export markets. |
Research Methodology
Operator-level perspectives from HFFS line engineers, procurement leads at snack food brand owners, regulatory affairs specialists managing FDA food contact notifications, and technical directors at film extrusion facilities anchored the qualitative base. Primary interview insights combined with secondary validation from EU REACH substance restriction databases, EMA packaging guideline documents, SEC 10-K filings of listed packaging converters, and customs trade data on polyethylene film imports. Bottom-up equipment capacity assessments and top-down end-use demand estimates underwent cross-triangulation to reconcile volume figures.
Sensitivity analysis tested forecast robustness against resin price volatility scenarios and regulatory timeline acceleration for fluorinated barrier phase-outs. Segmentation dimensions modeled include product type, material substrate, end-user channel, and format size across the projection horizon. CAGRs derived from equipment installation rates, brand owner procurement panel consolidation patterns, and pharmaceutical contract manufacturing expansion trajectories. Industry-specific inputs incorporated EU Packaging and Packaging Waste Regulation material recovery target compliance costs and mono-material equipment retrofit investment cycles.
Decision-makers should treat outputs as directional under sustained EU regulatory enforcement and stable ethylene-propylene feedstock pricing; material deviation would warrant model refresh. Forecasts reflect these assumptions alongside pharmaceutical export growth trajectories from Indian contract manufacturers. Recalibration cycles align with material shifts in EU extended producer responsibility scheme implementations and water-based barrier coating adoption rates at German and Dutch brand owners.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Containers
North America Food Cans Market
Packaging Containers
Packing Boxes Market
Packaging Containers
Can Holders Market
Packaging Containers
Glass Vape Cartridge Market
Packaging Containers
Europe Punnet Trays Market
Packaging Containers
Self - Locking Trays Market
Packaging Containers
Plasma Bottle Market
Packaging Containers
Wide Mouth Bottles Market
Packaging Containers
Wrist Watch Packaging Market
Packaging Containers
Membrane Boxes Market
Packaging Containers
Mini Refillable Spray Dispenser Market
Packaging Containers
Insulated Storage Vessel Market
Packaging Containers
Correx Trays Market
Packaging Containers
Sanitizer Bottles Market
Packaging Containers
Acrylic Boxes Market
Packaging Containers
VCI Bags Market