
 Can Holders Market | 2026-2036
Can Holders Market Size, Share, and Industry Trends Forecast 2026-2036
Can Holders Market Outlook
Event organizers and camping enthusiasts are unwinding share toward beverage manufacturers and retailers as the primary volume buyers. Smurfit Kappa Group PLC leverages its European fiber-based packaging infrastructure to dominate sustainable can carrier supply. Graphic Packaging International LLC anchors North American demand through integrated paperboard and folding carton capabilities. WestRock Company competes with molded fiber expertise targeting alcohol and soft drink brand owners seeking plastic replacement.
Can holders are rigid or semi-rigid structures engineered to secure multiple beverage cans during transport, retail display, or consumption, typically manufactured from corrugated paperboard, molded pulp, expanded polystyrene, or injection-molded polyethylene with tensile strength specifications ranging from 15 to 50 pounds per carrier. Their primary commercial purpose is to reduce secondary packaging costs, enable multi-pack retail pricing, and provide printed brand surfaces at point of sale. Plastic can holders retain volume leadership in emerging markets where cost sensitivity dominates procurement, though molded fiber and paperboard variants represent the fastest-expanding margin pool as sustainability specifications harden across European and North American supply chains. Custom can holders command premium positioning among craft breweries and sports stadium concessionaires seeking differentiated unboxing and carrying experiences.
The EPA guides material recovery standards for fiber-based packaging in the United States, while REACH and the EU Single-Use Plastics Directive constrain petroleum-derived carrier compositions across Europe, collectively elevating biodegradable substrate development and recyclability certification as baseline market access requirements. India's BIS packaging standards and China's GB/T standards for molded pulp products add compliance layers for exporters targeting Asia-Pacific manufacturing hubs. Stakeholders must monitor evolving extended producer responsibility frameworks and substrate-specific recycling infrastructure investments to align capacity with jurisdictionally fragmented compliance timelines.
Market Dynamics
The EU Single-Use Plastics Directive and parallel state-level mandates in the United States are forcing material substitution across beverage packaging supply chains, redirecting procurement toward fiber-based can carriers and compressing virgin plastic resin demand.
Growth Catalysts
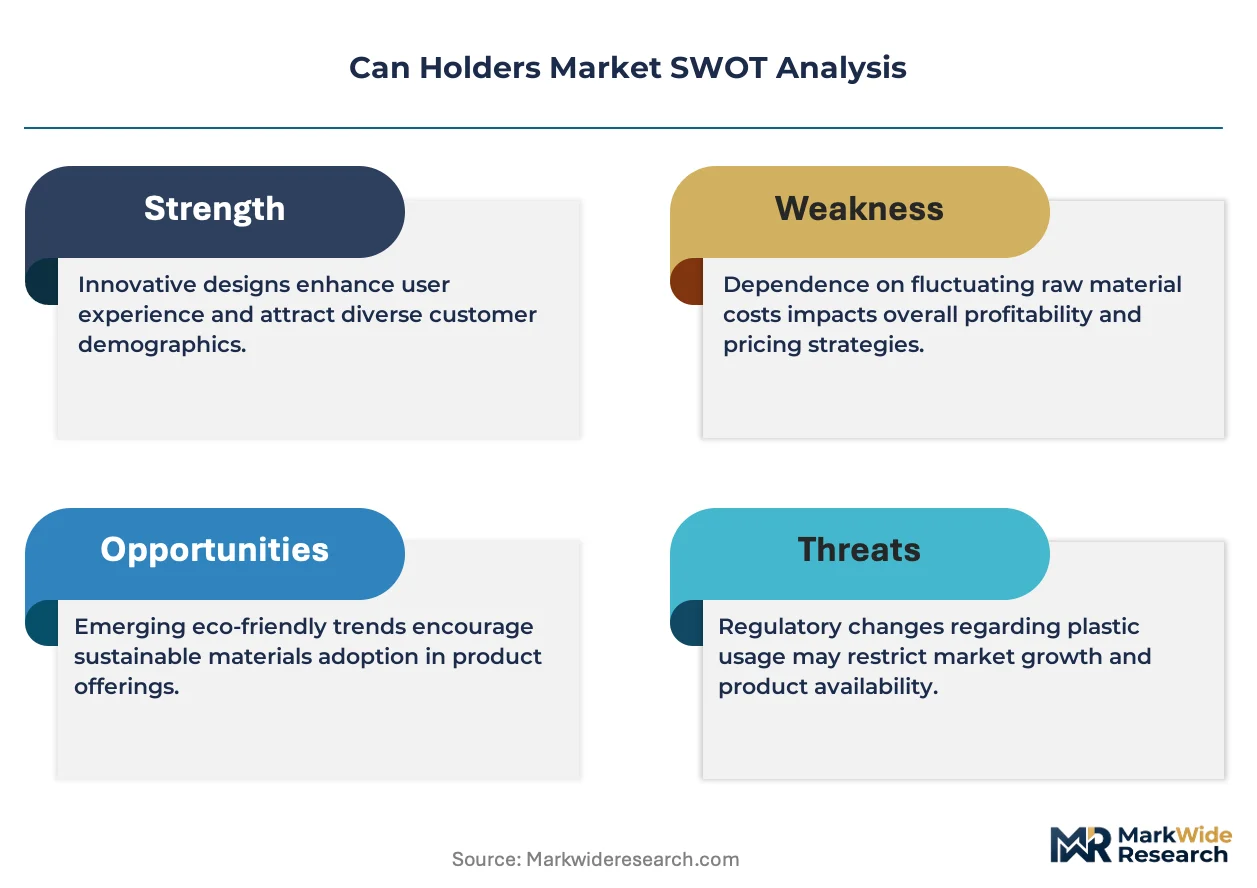
- REACH chemical restrictions:European beverage brands face binding limits on petroleum-derived additives in carrier polymers, accelerating molded pulp validation programs.
- Stadium concession upgrades:Sports venue operators in the United States are specifying branded, reusable can carriers to differentiate premium hospitality tiers.
- Molded fiber forming:Dry-molded fiber technology reduces water consumption versus traditional pulp molding, enabling cost parity with expanded polystyrene in high-volume runs.
Market Restraints
- OCC (old corrugated container) price volatility:Fiber-based can carrier margins compress when recycled pulp feedstock costs spike, particularly affecting smaller converters without long-term supply contracts.
- China molded pulp concentration:Over 60% of global molded fiber can carrier tooling and substrate supply originates from Zhejiang and Guangdong provinces, exposing buyers to logistics disruption and tariff exposure.
- Moisture resistance limitations:Uncoated paperboard carriers fail in refrigerated distribution environments, restricting adoption in beverage categories requiring cold-chain integrity.
Strategic Opportunities
- India organized retail expansion:Reliance Retail and D-Mart are scaling multi-pack beverage pricing strategies that require standardized can carrier formats, creating first-mover advantage for compliant suppliers.
- Deposit-return scheme alignment:Germany's DRS expansion and pending EU-wide harmonization reward carriers designed for automated sorting compatibility, favoring rigid fiber structures over flexible rings.
- E-commerce beverage fulfillment:Direct-to-consumer alcohol shipping requires damage-resistant can carriers that double as protective dunnage, opening premium pricing tiers unavailable in traditional retail.
Industry Challenges
- Food-contact certification timelines:FDA and EFSA approvals for novel bio-based coatings extend 18-24 months, delaying product launches and freezing R&D budgets.
- Legacy injection molding asset stranding:Polyethylene carrier producers face sunk-cost pressure to depreciate existing tooling while sustainability mandates accelerate obsolescence.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Can Holders Market |
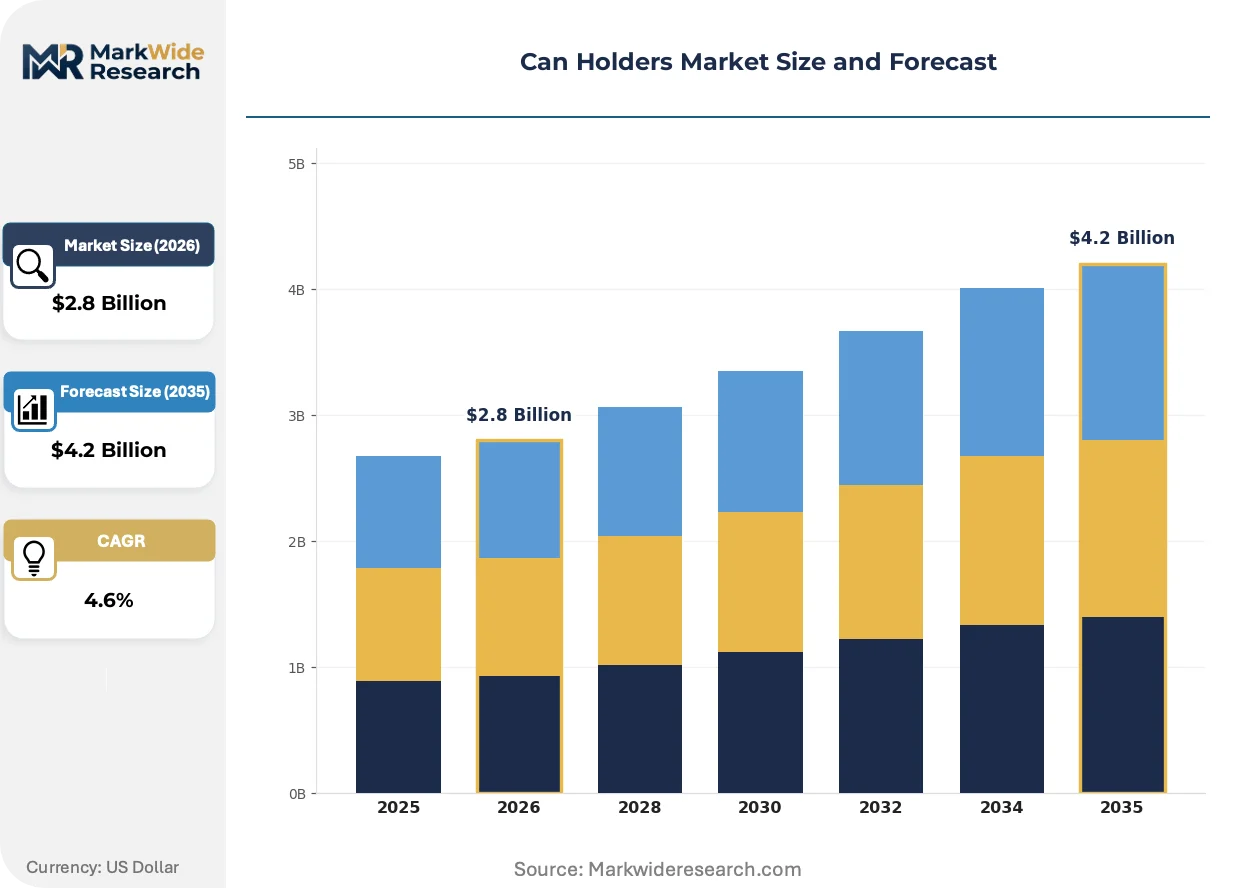
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.2 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plastic Can Holders, Metal Can Holders, Foam Can Holders, Custom Can Holders End User: Retailers, Event Organizers, Beverage Manufacturers, Camping Enthusiasts Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Wholesale Distributors Feature: Eco-Friendly, Insulated, Stackable, Portable |
| Companies Covered | Smurfit Kappa Group PLC, Graphic Packaging International LLC, WestRock Company, Berry Global, Roberts PolyPro, Amcor PLC, Huhtamaki Oyj, Sonoco Products Company, Sealed Air Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Can Holders Market Strategic Shifts
Active material science development and regulatory sequencing are compressing the viable technology set for can carriers, with performance specifications tightening faster than incumbent supply chains can adapt.
Molded fiber carriers engineered with precision-molded pulp geometries are displacing expanded polystyrene six-pack rings in North American craft brewery procurement. Smaller batch producers with sustainability-forward brand positioning have adopted these carriers at 40% price premiums, compressing polystyrene's addressable market to cost-sensitive mass-market segments where regulatory pressure remains minimal.
The EU Single-Use Plastics Directive's 2021 implementation and ongoing delegated act refinements have eliminated oxo-degradable plastic exemptions for can carriers. European beverage manufacturers now face mandatory extended producer responsibility fees scaled to recyclability performance, redirecting R&D investment toward fiber substrate optimization and deposit-return scheme compatibility testing.
Retail buyers are consolidating can carrier specifications across private-label beverage portfolios, reducing supplier counts from 8-12 to 3-4 per retail banner. This concentration forces converters to absorb customization costs and inventory risk, squeezing margin pools while rewarding scale players with integrated design-to-delivery capabilities. United States grocery chains lead this consolidation, with Kroger and Albertsons implementing unified sustainability scorecards that privilege fiber-based formats.
Can Holders Market Segmentation
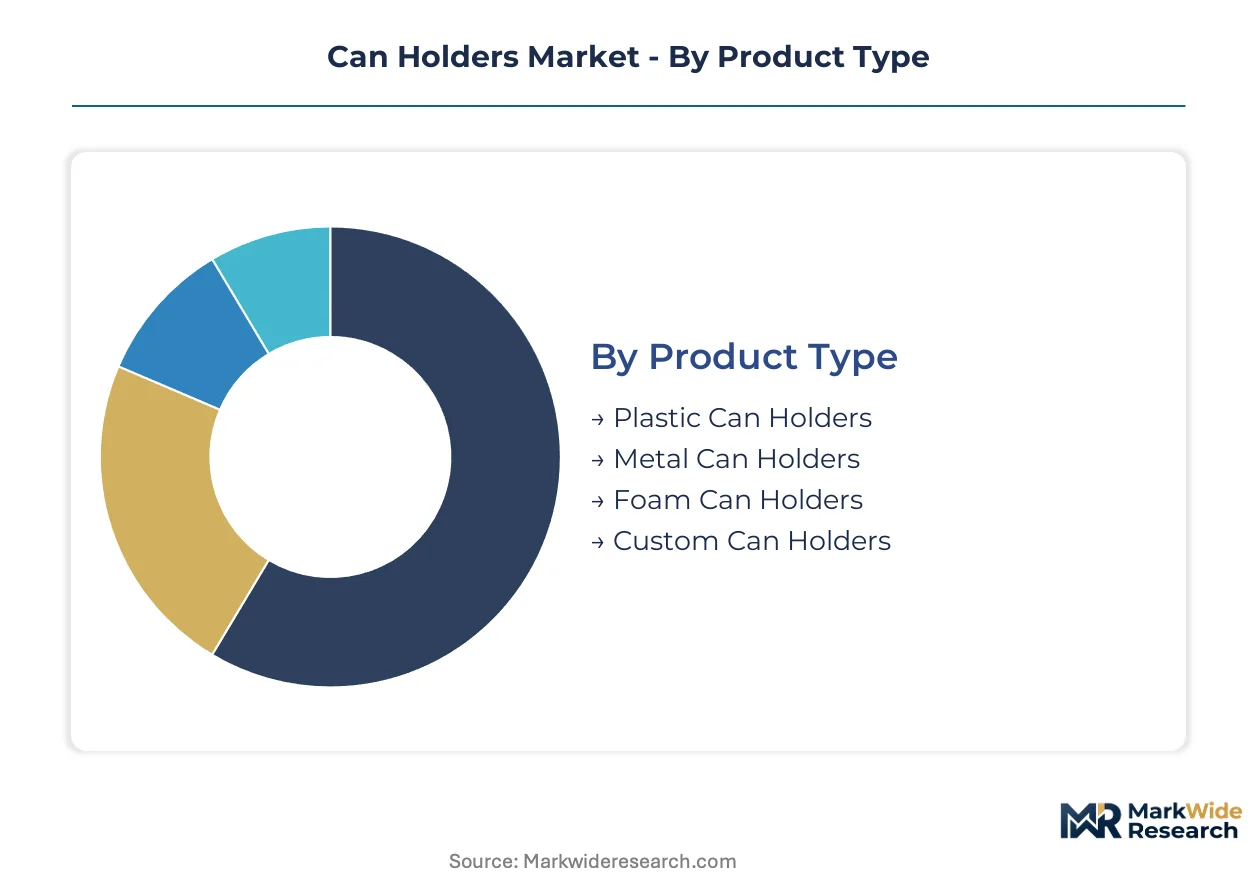
Material composition and end-use application drive divergent margin structures across can holder procurement. Regulatory frameworks fragment demand patterns, forcing converters to align substrate portfolios with jurisdiction-specific compliance timelines rather than unified global specifications.
Product Type:
REACH chemical restrictions and EPA material recovery standards create tiered compliance burdens that reshape procurement economics across substrate categories.
- Plastic Can Holders:Injection-molded polyethylene and expanded polystyrene variants dominate emerging market volume where cost sensitivity outweighs sustainability mandates. Stadium concessionaires in the United States continue specifying these carriers for refrigerated distribution environments where moisture resistance proves critical.
- Metal Can Holders:Aluminum and steel ring carriers engineered for reusable applications command premium positioning in German deposit-return scheme environments. Craft breweries in Bavaria and North Rhine-Westphalia specify these for automated sorting compatibility.
- Foam Can Holders:Expanded polystyrene six-pack rings retain beachside and outdoor event procurement in jurisdictions with minimal single-use plastic enforcement.
- Custom Can Holders:Branded, precision-formed carriers integrate molded fiber geometries and printed surfaces for differentiated unboxing experiences.
Plastic can holders handle the majority of throughput; custom can holders are gaining share fastest as craft brewery procurement accelerates.
End User:
Volume concentration shifts from fragmented consumer purchases toward consolidated enterprise procurement with standardized sustainability scorecards.
- Beverage Manufacturers:Multi-national alcohol and soft drink brand owners specify carrier formats across private-label portfolios, reducing supplier counts and absorbing customization costs through scale.
- Retailers:United States grocery chains including Kroger and Albertsons implement unified sustainability scorecards that privilege fiber-based formats and compress converter margins.
- Event Organizers:Sports venue operators specify branded, reusable can carriers to differentiate premium hospitality tiers and comply with stadium concession upgrade mandates.
- Camping Enthusiasts:Individual consumers purchase insulated and portable variants through direct-to-consumer channels with minimal volume impact on industrial procurement.
Beverage manufacturers concentrate the highest absolute volumes; retailers are expanding most quickly as sustainability specifications harden.
Distribution Channel:
Channel selection determines lead time requirements and inventory risk allocation between converters and end buyers.
- Wholesale Distributors:Bulk procurement through beverage industry distributors dominates mass-market beer and soft drink carrier allocation with long-term contract structures.
- Supermarkets:Private-label beverage portfolios at Albertsons and Kroger consolidate carrier specifications and reduce supplier counts per retail banner.
- Online Retail:Direct-to-consumer alcohol shipping requires damage-resistant can carriers that double as protective dunnage, opening premium pricing tiers.
- Specialty Stores:Craft brewery taprooms and outdoor equipment retailers stock custom and portable variants for immediate consumer purchase.
Wholesale distributors move the greatest tonnage; online retail climbs the fastest as e-commerce beverage fulfillment scales.
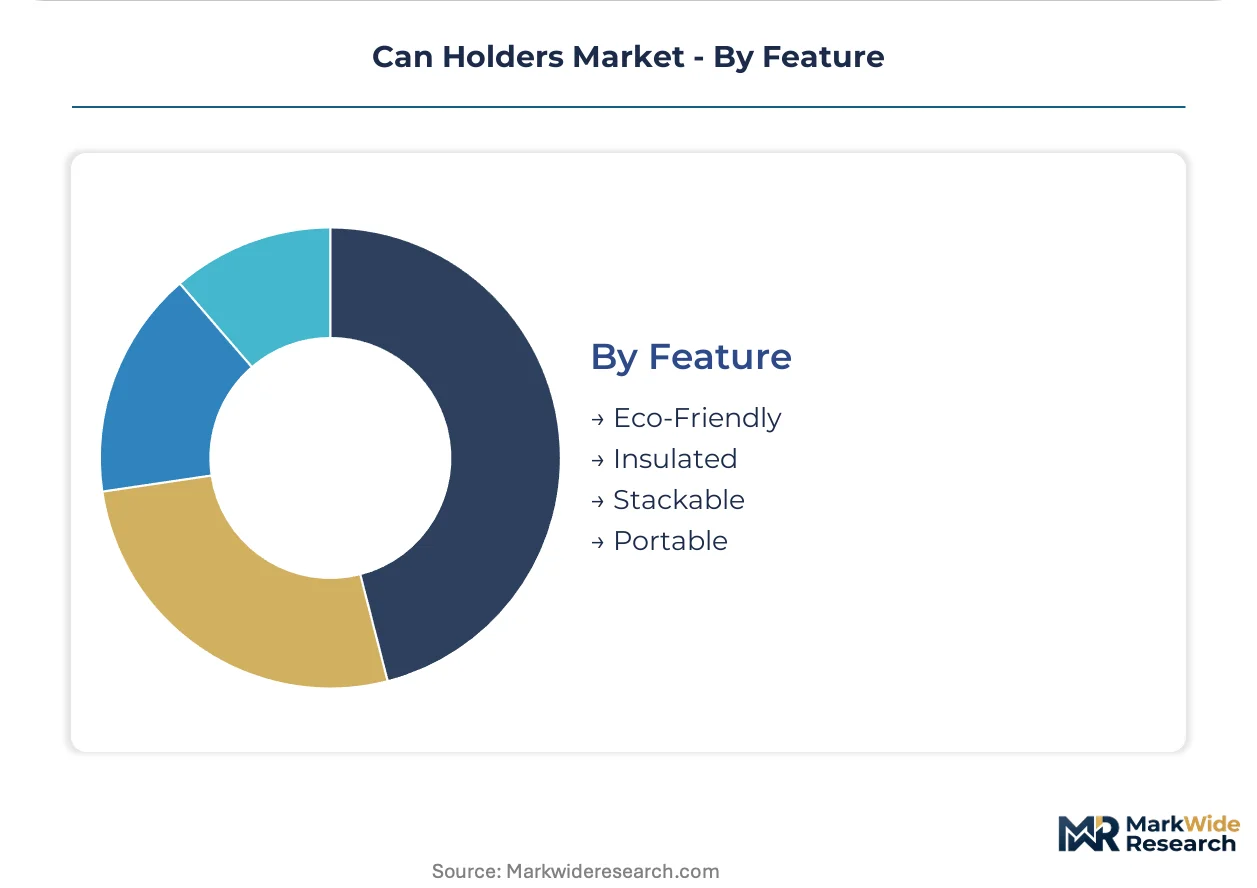
Feature:
Performance specifications and sustainability certification separate premium procurement from commodity substitution.
- Eco-Friendly:Molded fiber and uncoated paperboard variants validated for biodegradability and recyclability certification capture European and North American brand owner procurement.
- Insulated:Expanded polystyrene and foam-lined carriers maintain cold-chain integrity for beachside and outdoor consumption environments.
- Stackable:Precision-engineered geometries enable efficient palletization and retail shelf display optimization.
- Portable:Lightweight, handle-integrated designs target individual consumer camping and recreational use cases.
Eco-friendly features command the deepest market penetration; insulated variants show the steepest share erosion as regulatory pressure intensifies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's container throughput underwrites Europe's fiber-based packaging distribution, while Union Pacific's rail network anchors North American corrugated supply chains. These infrastructure assets determine regional procurement patterns for can holder converters.
United States
Craft brewery proliferation in Colorado and Oregon sustains premium molded fiber carrier demand. EPA material recovery standards elevate recyclability certification as baseline market access. Chicago and Milwaukee concentrate converter capacity serving stadium concession upgrade contracts.
Germany
Bavarian deposit-return scheme expansion rewards rigid fiber structures over flexible plastic rings. ECHA REACH chemical restrictions bind limits on petroleum-derived additives in carrier polymers. Düsseldorf and Hamburg host integrated paperboard converters aligned with automated sorting compatibility.
China
Zhejiang and Guangdong provinces concentrate over 60% of global molded fiber tooling and substrate supply. GB/T standards for molded pulp products add compliance layers for exporters. Shanghai's Yangshan Port handles outbound carrier component shipments facing tariff exposure.
India
Reliance Retail and D-Mart scaling multi-pack beverage pricing requires standardized can carrier formats. BIS packaging standards govern import specifications for fiber-based substrates. Mumbai and Ahmedabad emerge as converter hubs targeting organized retail procurement.
Brazil
São Paulo state beverage manufacturers specify carriers for multi-pack retail pricing in expanding supermarket channels. ANVISA food-contact certification governs bio-based coating approvals. Campinas industrial corridor attracts molded fiber investment serving Latin American brand owners.
Can Holders Market Competitive Environment
Concentration sits with integrated paperboard and molded fiber specialists rather than fragmented plastic converters. Three strategic archetypes dominate: European fiber infrastructure holders, North American integrated packaging conglomerates, and Asian molded pulp scale players. Competitive moves center on backward integration into OCC supply contracts and technology licensing for dry-molded fiber forming.
Among European-based fiber specialists, Smurfit Kappa Group PLC exemplifies infrastructure-led positioning through continental paperboard networks. Graphic Packaging International LLC and WestRock Company represent North American integrated packaging capabilities spanning design-to-delivery systems. These three anchors occupy positions across the premium sustainability specification tier where brand owners consolidate supplier counts.
| Leading Market Players |
|---|
| Smurfit Kappa Group PLC |
| Graphic Packaging International LLC |
| WestRock Company |
| Berry Global |
| Roberts PolyPro |
| Amcor PLC |
| Huhtamaki Oyj |
| Sonoco Products Company |
| Sealed Air Corporation |
| Others |
Value Chain & Pricing Dynamics
Long-term offtake contracts between beverage manufacturers and molded fiber converters lock in both OCC feedstock access and price visibility, insulating procurement teams from pulp price spikes while compressing margins for smaller suppliers without scale advantages.
Pricing Analysis
Volume-discount tiering structures stratify procurement across beverage manufacturers, retailers, and event organizers with divergent sustainability specifications. Pricing separates premium custom carriers with EFSA-validated bio-based coatings from standard molded fiber formats and economy-grade polyethylene rings. Cost compression in the standard tier intensifies as Kroger and Albertsons consolidate supplier counts and absorb customization leverage. Beverage manufacturers exhibit lowest price sensitivity given pass-through mechanisms, while camping enthusiasts through direct-to-consumer channels face highest sensitivity.
Supply Chain Analysis
Inventory lead times stretch 12-16 weeks for North American buyers sourcing precision-molded fiber tooling from Zhejiang and Guangdong provinces. Raw material flows draw from OCC recovery networks in the United States, eucalyptus pulp plantations in Brazil, and recycled paperboard streams in Europe. Single-source vulnerability concentrates in Chinese tooling fabrication, exposing buyers to logistics disruption and tariff exposure. Distribution runs through wholesale beverage distributors with long-term contract structures dominating mass-market allocation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face substitution defense imperatives as dry-molded fiber technology erodes cost barriers protecting legacy polyethylene carrier producers.
For Market Incumbents: Fortify backward integration into OCC supply contracts to neutralize feedstock volatility compressing fiber-based margins. Secure EFSA and FDA food-contact certifications for novel bio-based coatings before regulatory timelines harden. Depreciate legacy injection molding assets through accelerated replacement programs targeting German deposit-return scheme compatibility. For New Entrants and Emerging Players: Anchor in India's organized retail expansion where Reliance Retail and D-Mart scaling multi-pack beverage pricing creates first-mover advantage for BIS-compliant fiber substrate suppliers. Target e-commerce beverage fulfillment channels requiring damage-resistant carriers that double as protective dunnage, bypassing entrenched wholesale distributor relationships. For Investors and Strategic Acquirers: Capital is best deployed toward integrated paperboard converters with captive pulp supply and automated sorting compatibility testing capabilities. Long-term viability hinges on substrate diversification beyond petroleum-derived polymers. Monitor EU delegated act refinements on extended producer responsibility fee scaling as inflection indicator for fiber carrier adoption velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into OCC Supply | Captive pulp access neutralizes price volatility threatening fiber-based converter margins. |
| Dry-Molded Fiber Technology Licensing | Water-efficient forming achieves cost parity with expanded polystyrene in high-volume brewery procurement. |
| Deposit-Return Scheme Certification | Automated sorting compatibility unlocks German and pending EU-wide harmonized beverage packaging procurement. |
| Bio-Based Coating FDA/EFSA Submission | Food-contact validation extends market access into refrigerated distribution environments. |
| E-Commerce Dunnage Carrier Development | Direct-to-consumer alcohol shipping requirements open premium pricing tiers unavailable in traditional retail. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of EPA material recovery guidelines, EU Single-Use Plastics Directive delegated acts, and trade customs data. Primary interviews engaged procurement directors at beverage manufacturers, sustainability officers at retail grocery chains, and plant managers at molded fiber converters. Secondary validation drew from SEC filings of integrated packaging conglomerates, BIS packaging standard notifications, and OCC price index reporting. Bottom-up carrier volume estimates triangulated against top-down beverage multi-pack shipment data.
Segmentation dimensions modeled include material substrate, end-user archetype, distribution channel, and sustainability certification tier across the projection horizon. CAGRs derived from regression analysis against beverage volume growth, regulatory compliance timeline acceleration, and substrate substitution elasticity. Forecast inputs incorporated craft brewery proliferation rates, stadium concession upgrade capital expenditure tracking, and e-commerce alcohol fulfillment penetration curves.
Decision-makers should treat outputs as directional under sustained EU regulatory enforcement and stable OCC feedstock availability assumptions; material deviation would warrant model refresh. Specific risk factors include delegated act refinement delays, China logistics disruption, and bio-based coating certification timeline extensions. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Containers
Single Serve Packaging Market
Packaging Containers
Insulated Food Containers Market
Packaging Containers
Child Resistant Bottles Market
Packaging Containers
Acrylic Boxes Market
Packaging Containers
Pump Dispenser Market
Packaging Containers
Wrist Watch Packaging Market
Packaging Containers
Dispensing Trays Market
Packaging Containers
Africa Flexitank Market
Packaging Containers
Custom Boxes Market
Packaging Containers
Inverted Squeeze Bottle Market
Packaging Containers
Mini Refillable Spray Dispenser Market
Packaging Containers
Portion Packs Market
Packaging Containers
Telescope Box Market
Packaging Containers
Eyewear Packaging Market
Packaging Containers
North America Food Cans Market
Packaging Containers
Chalk Boxes Market