
 Molded Fiber End Caps Market | 2026-2036
Molded Fiber End Caps Market Size, Share, and Industry Trends Forecast 2026-2036
Molded Fiber End Caps Market Foresight
Direct procurement channels between molded fiber converters and original equipment manufacturers is tilting as large buyers consolidate supplier rosters. Huhtamaki Oyj leverages its European production footprint to anchor supply contracts with beverage and food equipment makers. Brødrene Hartmann A/S sustains cost leadership through integrated pulp sourcing and thermoforming operations across Nordic mills. UFP Technologies competes in North America with specialized medical and electronics packaging grades.
Molded fiber end caps are rigid protective closures formed from recycled paper pulp or bagasse through vacuum thermoforming or press-molding, typically achieving wall thicknesses of 2-5 mm and designed to absorb impact and stabilize cylindrical or irregular product geometries during transit. Their primary purpose is to replace expanded polystyrene and plastic counterparts in protective packaging for fragile industrial goods. Standard caps dominate volume production for commodity applications, while custom caps capture premium margin pools from electronics and automotive clients requiring dimensional precision. Eco-friendly caps are gaining fastest in segments where brand owners face Scope 3 emissions disclosure requirements.
The EPA promotes recycled content standards through Sustainable Materials Management programs, while the EU Green Deal and REACH restrict fossil-based packaging across member states, directly redirecting procurement toward fiber-based alternatives. California's extended producer responsibility laws and China's GB standards on packaging recyclability add compliance layers for exporters. Stakeholders must monitor how fragmented national labeling requirements for compostability reshape product development roadmaps and cross-border certification costs.
Market Dynamics
Consolidation among electronics and automotive OEMs is compressing supplier rosters and demanding higher-performance molded fiber grades that match expanded polystyrene's dimensional tolerance at scale.
Growth Catalysts
- EU Green Deal packaging mandates:REACH restrictions on single-use plastics redirect procurement budgets toward fiber-based protective closures across German automotive and precision engineering clusters.
- Electronics shipment volumes:Fragile component manufacturers in semiconductor and display sectors specify molded fiber end caps for impact absorption during intercontinental logistics.
- Bagasse fiber processing:Agricultural residue pulping advances reduce reliance on recycled paper fiber and lower raw material cost volatility for thermoformed protective packaging.
Market Restraints
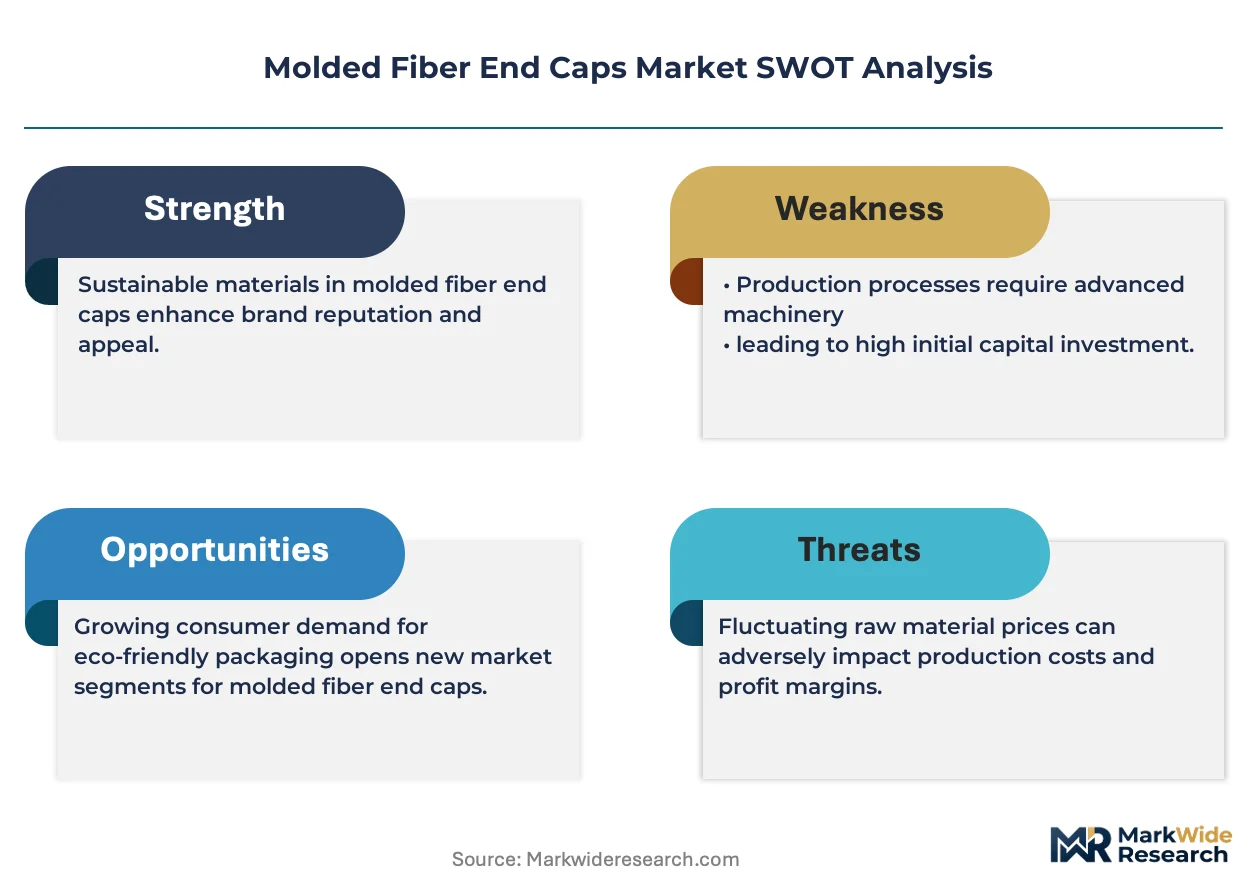
- Pulp price volatility:Recycled paper fiber costs fluctuate with municipal collection rates and export demand from Asian packaging converters, squeezing converter margins unpredictably.
- Dimensional precision gaps:Molded fiber wall thickness tolerances of 2-5 mm fail to match expanded polystyrene's sub-millimeter consistency for micron-sensitive optical components.
- Composting infrastructure scarcity:Industrial composting facility coverage remains patchy across North American and Asian logistics corridors, limiting end-of-life claims for eco-friendly cap grades.
Strategic Opportunities
- India electronics manufacturing:PLI scheme incentives for semiconductor and mobile device assembly create virgin demand for protective packaging in Mumbai and Bengaluru industrial corridors.
- Medical device sterilization compatibility:Gamma-stable molded fiber formulations penetrate surgical instrument and diagnostic equipment packaging previously locked in Tyvek and rigid plastic.
- Direct-to-plant converter relationships:Bypassing distributor networks lets fiber molders capture specification influence and secure multi-year automotive platform contracts.
Industry Challenges
- Thermoforming tooling lead times:Custom aluminum mold fabrication for precision end caps extends 12-16 weeks, delaying automotive program launches and requiring advance capacity commitments.
- Cross-border compostability certification:Fragmented national labeling requirements for industrial versus home compostability multiply testing costs and create non-tariff barriers for exporters serving EU, US, and Japanese markets simultaneously.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Molded Fiber End Caps Market |
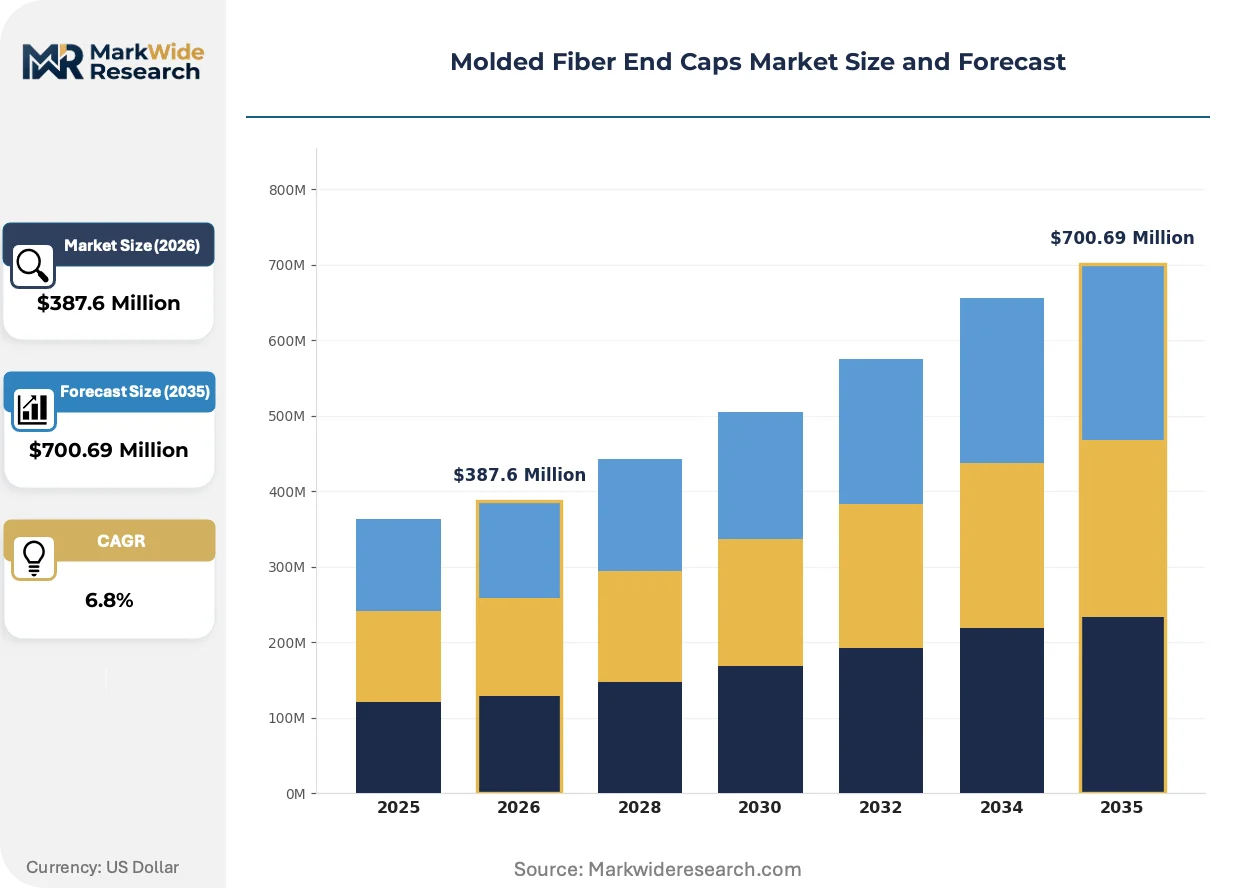
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $700.69 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Caps, Custom Caps, Eco-Friendly Caps, Insulated Caps Application: Packaging, Agriculture, Electronics, Automotive End User: Manufacturers, Retailers, Distributors, Exporters Distribution Channel: Online Sales, Direct Sales, Retail Stores, Wholesalers |
| Companies Covered | Huhtamaki Oyj, UFP Technologies, Brødrene Hartmann A/S, Sabert Corporation, EnviroPAK, Sonoco Products Company, Pactiv Evergreen, PulPac, Tanbark Molded Fiber Products, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Molded Fiber End Caps Market Shifts & Advancements
Manufacturing technology and procurement specifications are converging to elevate molded fiber from commodity substitute to engineered protective solution with certified performance metrics.
Precision press-molding with heated aluminum tooling is migrating from artisan batch production to automated continuous lines serving automotive tier-one suppliers. BMW and Bosch procurement teams now specify Cpk values above 1.33 for critical dimension stability, forcing fiber converters to adopt statistical process control systems previously foreign to pulp-based manufacturing. This capability upgrade is migrating from premium custom caps toward standard product lines as equipment amortization spreads across higher volumes.
California's extended producer responsibility laws impose packaging recyclability disclosure requirements on any product sold in the state, compelling exporters from China and Europe to certify fiber content percentages and end-of-life pathways. The state's Department of Resources Recycling and Recovery audits create compliance friction for molded fiber shipments lacking BPI or OK Compost INDUSTRIAL marks. Electronics brands with California distribution centers are responding by pre-qualifying converters with dual US-EU certification coverage.
Consolidated buyer procurement is compressing specification cycles and demanding consolidated supplier responsibility for protective packaging performance. Amazon's frustration-free packaging mandates and similar retailer programs eliminate redundant secondary boxing, placing structural load requirements directly on primary molded fiber end caps. German industrial distributors now stock only fiber-based protective lines for cylindrical goods, having delisted expanded polystyrene alternatives from catalogs serving Bavarian and Baden-Württemberg manufacturing belts.
Molded Fiber End Caps Market Segmentation
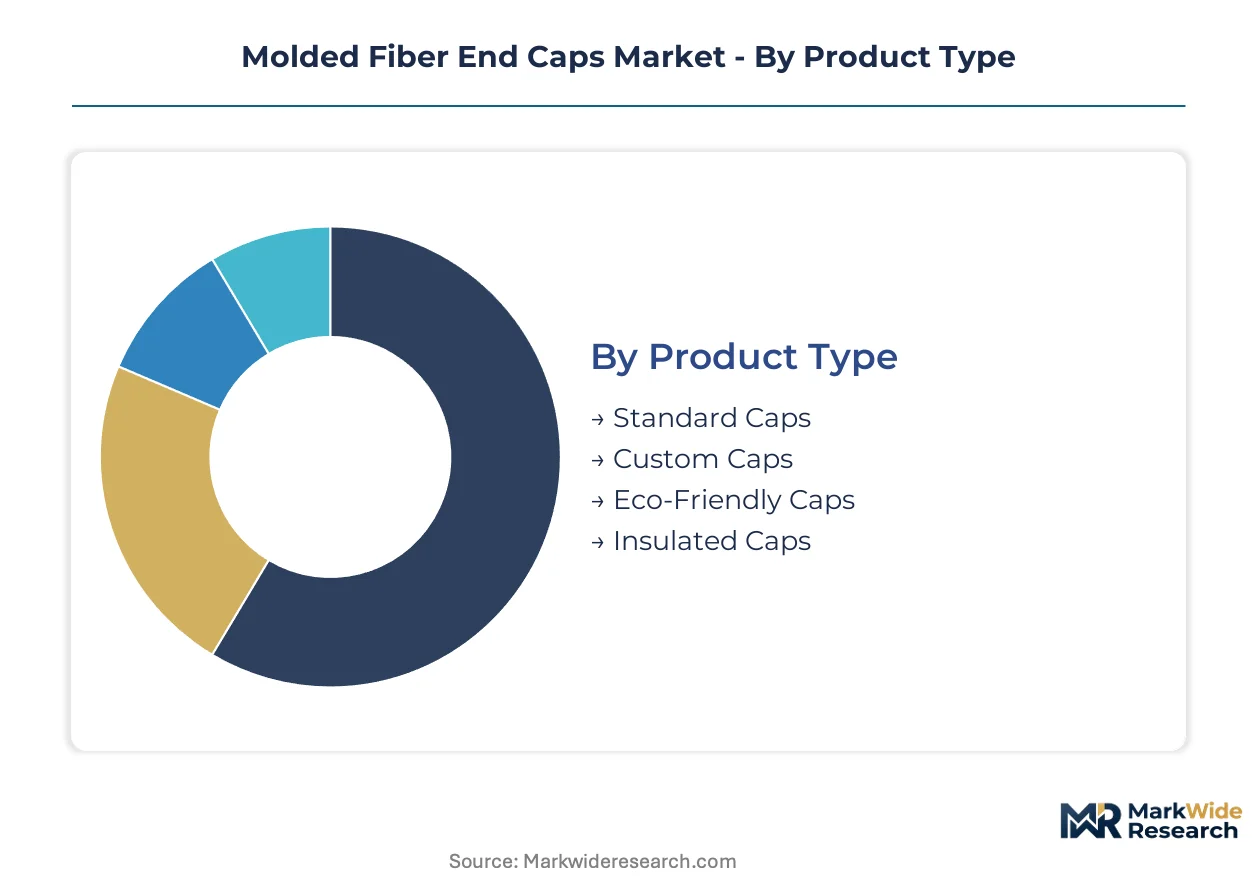
Molded fiber end caps serve divergent procurement cycles across product tiers and end-use verticals. Specification complexity and certification requirements fragment supplier relationships differently by segment.
Product Type:
Standard caps rotate inventory fastest through commodity procurement channels, while custom and eco-friendly grades extend specification cycles through validation and certification phases.
- Standard Caps:Vacuum-formed from recycled paper pulp with 2-5 mm wall thickness for general cylindrical protection. German automotive tier-one suppliers specify these for non-critical shaft and bearing shipments where dimensional tolerance permits ±1 mm variance.
- Custom Caps:Engineered through heated aluminum press-molding to achieve Cpk values above 1.33 for micron-sensitive geometries. Bosch and BMW procurement teams mandate these for precision component platforms requiring statistical process control documentation.
- Eco-Friendly Caps:Bagasse fiber formulations target Scope 3 emissions disclosure requirements in EU and California distribution networks.
- Insulated Caps:Multi-layer constructions with thermal barriers for temperature-sensitive pharmaceutical and diagnostic equipment transit.
Standard caps anchor the volume base while eco-friendly caps gain share at the steepest rate.
Application:
Cost tiers separate high-volume commodity protection from precision-engineered solutions where failure carries platform-level liability.
- Packaging:General protective closures for industrial cylindrical goods with minimal performance certification. Amazon frustration-free packaging mandates redirect procurement toward fiber-based alternatives for secondary elimination.
- Electronics:Semiconductor and display manufacturers specify molded fiber for intercontinental fragile component logistics. California's extended producer responsibility laws compel BPI or OK Compost INDUSTRIAL certification for any product sold through state distribution centers.
- Agriculture:Nursery and propagation applications utilizing bagasse fiber for biodegradable pot and container protection.
- Automotive:Precision shaft, bearing, and sensor protection requiring dimensional stability across temperature and humidity ranges.
Packaging commands the highest shipment volumes while electronics climbs the fastest on regulatory displacement of expanded polystyrene.
End User:
Customer type determines whether procurement flows through distributor markups or direct converter relationships with specification influence.
- Manufacturers:OEMs and tier-one suppliers with direct converter contracts for multi-year platform commitments. German precision engineering clusters in Bavaria and Baden-Württemberg consolidate supplier rosters to three approved fiber molders per commodity category.
- Distributors:Industrial supply houses curating catalog offerings based on regional regulatory compliance. German distributors have delisted expanded polystyrene alternatives from cylindrical goods lines serving manufacturing belts.
- Retailers:Big-box and specialty chains with private-label packaging specifications for consumer-facing products.
- Exporters:Cross-border shippers navigating fragmented national compostability labeling requirements multiplying testing costs for simultaneous EU, US, and Japanese market access.
Manufacturers dominate value capture through direct relationships while exporters face the steepest compliance cost escalation.
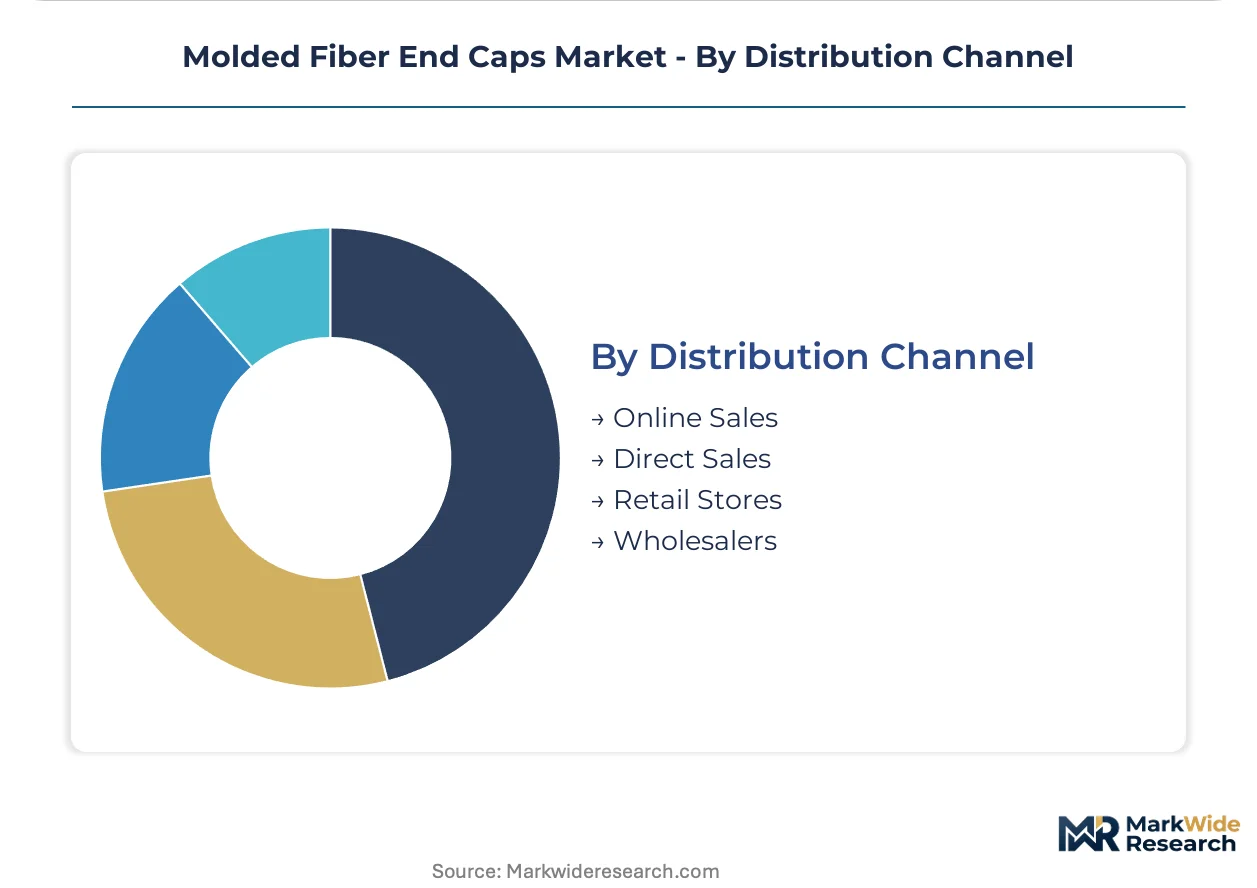
Distribution Channel:
Channel selection reflects buyer scale and specification complexity, with digital procurement gaining traction in standardized grades.
- Direct Sales:Converter-to-OEM relationships bypassing distributor networks for automotive and electronics platform contracts. Huhtamaki Oyj leverages its European production footprint to anchor supply contracts through direct specification development.
- Online Sales:Digital procurement portals for standardized cap dimensions with immediate availability. Small and mid-sized manufacturers in India's PLI scheme corridors utilize these channels for initial protective packaging trials.
- Wholesalers:Volume aggregation for commodity applications with limited customization requirements.
- Retail Stores:Limited local availability for immediate replacement and small-batch agricultural applications.
Direct sales secure the margin premium while online channels expand most quickly among new market entrants.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power in Germany outstrips that in India by a factor of three, reflecting divergent regulatory enforcement and specification intensity across automotive supply chains. The EU Green Deal's packaging mandates concentrate procurement budgets in Northern European manufacturing belts while Asian converters compete on throughput scale.
United States
Amazon's frustration-free packaging mandates redirect procurement toward fiber-based protective closures for cylindrical goods shipped through California distribution centers. The EPA's Sustainable Materials Management programs promote recycled content standards that electronics brands must document for interstate commerce. Precision engineering clusters in Greater Boston and the Pacific Northwest specify molded fiber end caps for semiconductor equipment logistics.
Germany
BMW and Bosch procurement teams mandate Cpk values above 1.33 for precision component platforms, forcing statistical process control adoption across fiber converters. REACH restrictions on single-use plastics redirect automotive supply chain budgets toward fiber-based alternatives. Bavarian and Baden-Württemberg manufacturing belts have consolidated supplier rosters to three approved fiber molders per commodity category.
China
GB standards on packaging recyclability impose compliance layers on exporters serving EU and US markets simultaneously. Dual carbon goals accelerate bagasse fiber processing investments to reduce reliance on imported recycled paper pulp. Yangtze River Delta electronics assemblers specify molded fiber end caps for display and semiconductor shipments to European automotive tier-ones.
India
PLI scheme incentives for semiconductor and mobile device assembly create virgin demand for protective packaging in Mumbai and Bengaluru industrial corridors. BIS certification requirements for packaging materials add testing costs for converters serving export markets. Gujarat and Tamil Nadu manufacturing zones attract fiber molders establishing direct-to-plant relationships with electronics OEMs.
Japan
METI's resource circulation policies prioritize fiber-based packaging for precision equipment exports to EU markets. JIS standards on dimensional tolerance create specification barriers for imported molded fiber products. Kansai industrial corridors around Osaka maintain stringent supplier qualification protocols for automotive component protection.
Molded Fiber End Caps Market Competitive Landscape
Pan-regional converters and regional specialists split the market along capability and proximity axes. Consolidation among electronics and automotive OEMs compresses supplier rosters to converters demonstrating statistical process control and multi-year platform commitment capacity. Three archetypes dominate: integrated pulp-to-mold operators with captive fiber supply, precision thermoforming specialists serving automotive tier-ones, and commodity volume producers competing on cycle time. Capacity expansion and direct specification development with OEM procurement teams represent the dominant competitive moves.
Among Nordic integrated operators, Brødrene Hartmann A/S exemplifies the pulp-captive archetype through thermoforming operations anchored to regional mill networks. Huhtamaki Oyj occupies a pan-regional position leveraging European production footprints to anchor supply contracts with beverage and food equipment makers. UFP Technologies represents the precision-specialist tier competing in North American medical and electronics packaging grades. These three named entities illustrate how geographic integration, regional scale, and application focus stratify competitive positioning.
| Leading Market Players |
|---|
| Huhtamaki Oyj |
| UFP Technologies |
| Brødrene Hartmann A/S |
| Sabert Corporation |
| EnviroPAK |
| Sonoco Products Company |
| Pactiv Evergreen |
| PulPac |
| Tanbark Molded Fiber Products |
| Others |
Supply & Pricing Matrix
Pulp price volatility in recycled paper fiber markets determines both the premium spread for custom-engineered caps and the geographic shape of converter supply networks. Buyers facing municipal collection rate fluctuations and Asian export demand spikes must choose between absorbing cost pass-throughs or consolidating supplier rosters for volume leverage.
Pricing Analysis
The customization-premium spread separates configured-to-order press-molded caps from vacuum-formed standard grades. Contract-based long-term offtake dominates automotive platform procurement, while spot purchasing persists for commodity packaging applications. Price differentiation rests on certification grade—BPI or OK Compost INDUSTRIAL marks command 15-20% premiums in California distribution corridors—and dimensional precision measured by Cpk values. Cost compression in standard grades is intensifying because bagasse fiber processing investments are lowering raw material thresholds. Small electronics assemblers in India's PLI corridors exhibit highest price sensitivity; German automotive tier-ones demonstrate lowest sensitivity due to platform-level liability considerations.
Supply Chain Analysis
Supplier-financing terms extending 90-120 days are becoming standard for automotive platform contracts, with supply-chain finance facilities emerging among Nordic integrated operators. Geographic supply concentrates in Germany, China, and India—Germany for precision thermoforming serving BMW and Bosch specifications, China for bagasse fiber processing and Yangtze River Delta electronics logistics, India for PLI-scheme electronics manufacturing corridors. Raw material dependencies draw from recycled paper pulp, bagasse agricultural residue, and aluminum tooling for heated press-molds. Single-source vulnerability runs through German precision engineering clusters where three approved molders per commodity category create thin redundancy. Distribution runs through direct converter-to-OEM relationships for platform contracts and digital procurement portals for standardized grades.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward consolidated automotive and electronics OEMs compressing supplier rosters to three approved fiber molders per category in German manufacturing belts. This consolidation demands converters demonstrate statistical process control and multi-year platform commitment capacity or face delisting.
For Market Incumbents: Harden specification influence through captive pulp supply integration and heated aluminum tooling investments that achieve Cpk values above 1.33. Bagasse fiber processing capabilities defend against recycled paper pulp price volatility while securing automotive platform contracts against emerging precision thermoforming specialists. For New Entrants and Emerging Players: Build out sterilization-compatible formulations for surgical instrument packaging previously locked in Tyvek and rigid plastic. India's PLI scheme electronics corridors offer the most penetrable white-space, with direct-to-plant converter relationships bypassing distributor markups as the critical go-to-market angle. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors integrated pulp-to-mold operators with statistical process control documentation. Long-term viability over the next decade hinges on converters securing multi-year automotive platform commitments and dual US-EU certification coverage. Watch for REACH packaging mandate enforcement intensity as the inflection signal for fiber-based displacement of expanded polystyrene.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bagasse Fiber Supply | Captive agricultural residue pulping reduces raw material cost volatility for thermoformed caps. |
| Heated Aluminum Tooling Investment | Precision press-molding achieves Cpk values above 1.33 for BMW and Bosch procurement specifications. |
| Dual US-EU Certification Coverage | BPI and OK Compost INDUSTRIAL marks unlock California distribution center access for electronics brands. |
| Direct-to-Plant Converter Relationships | Bypassing distributor networks secures multi-year automotive platform contracts with specification influence. |
| Gamma-Stable Formulation Development | Penetrates surgical instrument and diagnostic equipment packaging previously locked in Tyvek barriers. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of trade association filings, customs data, and regulatory disclosure databases. Conversations with fiber converter plant managers, automotive tier-one procurement leads, electronics packaging engineers, and industrial distributor category buyers inform operational and commercial dynamics. Secondary validation draws from EPA Sustainable Materials Management documentation, ECHA REACH restriction registers, and California Department of Resources Recycling and Recovery audit protocols. Bottom-up shipment data triangulates against top-down procurement budget estimates across German automotive, US electronics, and Indian PLI scheme corridors.
Forecast inputs include product type segmentation across standard, custom, eco-friendly, and insulated grades; application segmentation across packaging, electronics, agriculture, and automotive; and end-user segmentation across manufacturers, distributors, retailers, and exporters. CAGRs derive from regression analysis of historical procurement volumes against regulatory mandate implementation timelines and OEM platform launch cycles. Bagasse fiber processing capacity expansion, REACH single-use plastic restriction enforcement, and Amazon frustration-free packaging mandate adoption serve as industry-specific demand drivers.
The forecast holds incumbent behavior within observed patterns; aggressive capacity additions by Nordic integrated operators or rapid bagasse fiber technology licensing would shift outcomes. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Caps and Closures
Aerosol Caps Market
Caps and Closures
Metal Closures Market
Caps and Closures
United Arab Emirates Plastic Caps and Closures Market
Caps and Closures
Middle East and Africa Plastic Caps and Closures Market
Caps and Closures
Europe Plastic Caps and Closures Market
Caps and Closures
Tear Tab Cap Market
Caps and Closures
Sterile Lids Market
Caps and Closures
Cap Liner Market
Caps and Closures
IV Infusion Bottle Seals and Caps Market
Caps and Closures
Foam End Caps Market
Caps and Closures
Twist-Off Metal Caps Market
Caps and Closures
Ribbed Closures Market
Caps and Closures
Mexico Plastic Caps and Closures Market
Caps and Closures
Dispensing Caps Market
Caps and Closures
Aerosol Valves Market
Caps and Closures
Elastomeric Closures Market