
 Portion Packs Market | 2026-2036
Portion Packs Market Size, Share, and Industry Trends Forecast 2026-2036
Portion Packs Market Analytics
Aftermarket sustainability consulting is reconfiguring how converters monetize compliance-driven redesign cycles. Mondi leverages its integrated fiber-paperboard operations to anchor European quick-service supply chains with certified recyclable formats. Turpack competes through high-speed form-fill-seal specialization for single-serve condiment and sauce applications. Elite Portion Pack sustains niche dominance in premium hospitality sachets through tight control over short-run customization workflows.
Portion packs are single-unit containment formats engineered from laminated films, coated papers, or thin-gauge aluminum, typically sealed through heat or ultrasonic welding to preserve shelf stability and portion accuracy for foodservice and retail distribution. The primary commercial purpose is to eliminate over-portioning waste while enabling brand-controlled consumption experiences in away-from-home settings. Single-serve beverage packs and condiment packs capture divergent margin structures, with beverage formats requiring barrier-layer complexity that elevates material costs and technical entry barriers. Snack packs in paper substrates are gaining structural momentum as quick-service chains phase out conventional plastic under operational pressure from the EU Single-Use Plastics Directive.
The EU Single-Use Plastics Directive and FDA food-contact substance notifications jointly shape material legitimacy and cross-border market access for portion pack suppliers serving multinational foodservice accounts. EFSA migration limit standards for paper coatings and Germany's national packaging ordinance create layered compliance obligations that filter out uncertified converters. REACH chemical restrictions on perfluorinated compounds further constrain barrier-coating options, pushing R&D investment toward mineral-based or polysaccharide alternatives. Stakeholders must monitor how divergent U.S. state-level extended producer responsibility legislation and EU harmonized packaging waste rules will reshape cost allocation between converters and their foodservice brand customers.
Market Dynamics
Material substitution pressure from the EU Single-Use Plastics Directive is forcing converters to rebuild substrate portfolios around certified paper and bio-based barriers, compressing legacy plastic film demand while elevating technical qualification costs across European quick-service supply chains.
Growth Catalysts
- Foodservice automation:Quick-service restaurants in Germany are deploying high-speed dispensing systems that require precision-calibrated single-serve formats, pulling demand for pre-portioned condiment and sauce packs.
- REACH chemical restrictions:Perfluorinated compound limitations under EU chemical policy are redirecting R&D investment toward mineral-based barrier coatings, creating first-mover advantages for certified converters.
- Paper substrate certification:EFSA migration limit standards for paper coatings are legitimizing fiber-based formats for hot-fill applications, expanding addressable market share within beverage and condiment segments.
Market Restraints
- Bio-polymer cost volatility:Agricultural feedstock dependency for polylactic acid and starch-based resins exposes converters to crop price swings that compress margin stability versus petroleum-derived alternatives.
- German converter concentration:Certified fiber-paperboard supply chains cluster around integrated pulp-to-packaging operations in Central Europe, creating bottleneck risk for non-integrated market entrants.
- Barrier performance gaps:Current mineral-based coatings fail to match aluminum-laminate oxygen transmission rates for shelf-stable dairy and retort applications, limiting material substitution scope.
Strategic Opportunities
- Indian quick-service expansion:Western fast-food chains are penetrating Tier-2 and Tier-3 Indian cities where portion-controlled formats reduce operational complexity for franchise operators managing inconsistent supply chains.
- Extended producer responsibility tailwinds:Divergent U.S. state-level EPR legislation is creating compliance service revenue streams for converters offering packaging-as-a-service models with take-back logistics.
- Ultrasonic welding convergence:Integration of ultrasonic sealing with high-speed form-fill-seal lines is collapsing changeover times between SKUs, enabling economic production of micro-lot custom hospitality formats.
Industry Challenges
- Migration testing timelines:EFSA novel food-contact substance approval cycles extend 18-24 months for innovative bio-based barriers, delaying product launches and freezing capital in qualification inventory.
- Legacy equipment retrofit costs:Converters running thermal sealing lines face six-figure capital outlays to handle heat-sensitive bio-substrates, straining mid-tier balance sheets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Portion Packs Market |
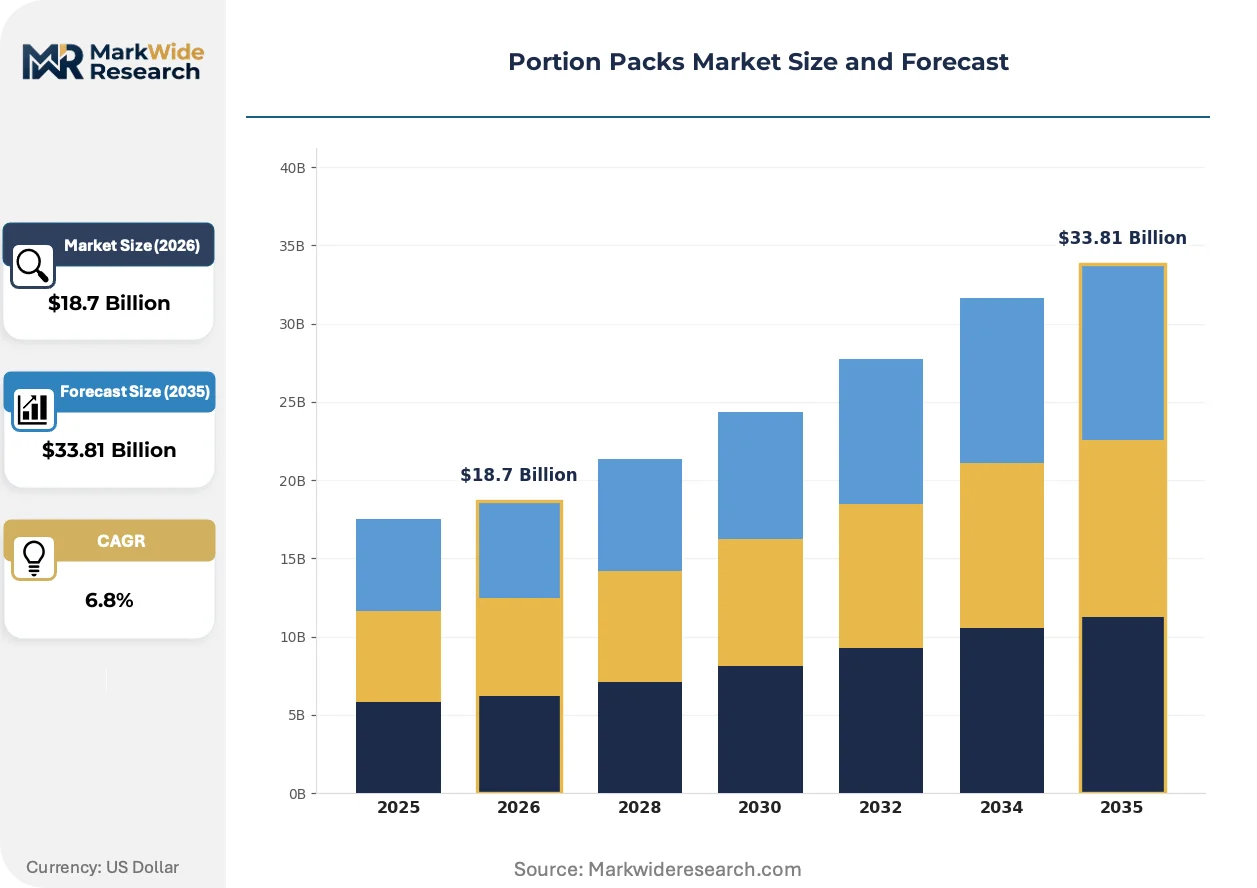
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single Serve, Snack Packs, Condiment Packs, Beverage Packs End User: Restaurants, Cafés, Catering Services, Retail Outlets Material: Plastic, Paper, Aluminum, Glass Distribution Channel: Online Retail, Supermarkets, Convenience Stores, Vending Machines |
| Companies Covered | HELLMA, Elite Portion Pack, SAES, Alba, Single Source Limited, Turpack, Alcoa, Mondi, Van Oordt, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Portion Packs Market Evolving Landscape
Active material science breakthroughs are collapsing the performance gap between fiber-based and plastic barrier technologies, while regulatory divergence between EU and U.S. jurisdictions is fragmenting compliance architectures and forcing dual-track qualification strategies.
Mineral-based barrier coatings incorporating kaolin and precipitated calcium carbonate are collapsing the oxygen transmission rate differential against conventional metallized films. German quick-service chains operating automated condiment dispensers are qualifying these formats at accelerated pace to meet EU Single-Use Plastics Directive deadlines. The structural consequence is collapsing premium pricing power for aluminum-laminate specialists as paper alternatives achieve technical parity in ambient shelf-stable applications.
REACH restrictions on perfluorinated alkyl substances are eliminating legacy grease-resistant chemistries from European food-contact applications. Industrial consequence includes forced formulation transitions for condiment sachet converters serving pan-European quick-service accounts, with EFSA migration testing backlogs extending qualification timelines. Hot-fill sauce segments in France and Italy are responding by accelerating polysaccharide-based coating trials to secure Q3 2025 menu commitments.
Centralized procurement by multinational quick-service brands is compressing supplier rosters and demanding consolidated sustainability reporting across substrate categories. Regional converters in Spain and Poland are losing shelf space to integrated fiber-paperboard operators offering certified recyclable formats with embedded carbon accounting. This concentration is most visible in Germany, where foodservice automation mandates and packaging ordinance compliance intersect to favor suppliers with captive pulp operations and in-house coating capabilities.
Portion Packs Market Segmentation
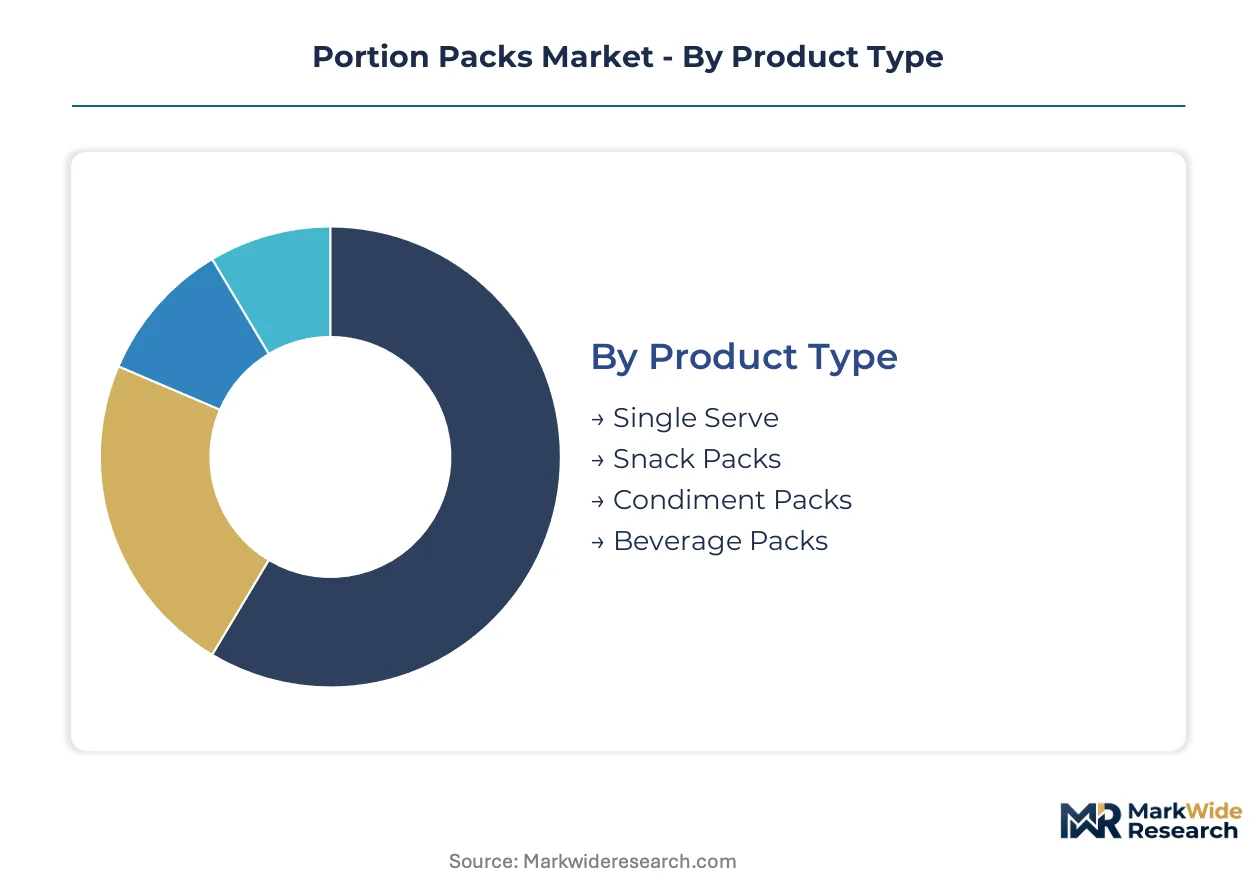
Portion pack segmentation reflects divergent technical requirements across foodservice automation, retail shelf stability, and regulatory compliance. Substrate selection and format geometry vary sharply by end-use velocity and barrier performance needs.
Product Type:
Use cases span from high-velocity condiment dispensing to extended-shelf beverage protection, with automation compatibility driving format standardization.
- Condiment Packs:Heat-sealed laminated films or coated paper sachets calibrated for precision dispensing in quick-service automation systems. German chains are qualifying mineral-coated paper alternatives under EU Single-Use Plastics Directive timelines, compressing demand for legacy plastic films.
- Beverage Packs:Multi-layer barrier constructions incorporating aluminum oxide or ethylene vinyl alcohol to prevent oxygen ingress in ambient distribution. EFSA migration testing for novel bio-based barriers is extending qualification cycles for converters serving hot-fill juice and dairy segments.
- Single Serve:Unit-dose formats for sauces, dressings, and spreads with tear-notch accessibility for away-from-home consumption.
- Snack Packs:Portion-controlled dry goods containment with modified atmosphere compatibility for extended shelf life.
The dominant share belongs to Condiment Packs, while Beverage Packs is closing the gap fastest.
End User:
Procurement patterns split between high-volume contractual supply to multinational chains and fragmented spot purchasing by independent operators.
- Restaurants:Quick-service and full-service establishments demanding SKU consolidation and embedded sustainability reporting for scope 3 emissions tracking. Centralized procurement by Western fast-food brands is compressing supplier rosters toward integrated fiber-paperboard operators with certified recyclable formats.
- Catering Services:Event and institutional foodservice requiring short-run customization for menu-matched portion geometry and private-label branding. Micro-lot production economics are improving through ultrasonic welding integration with form-fill-seal lines.
- Cafés:Coffee-focused formats emphasizing sugar, creamer, and stir-stick portion control with counter-space efficiency.
- Retail Outlets:Grab-and-go and home-meal-replacement segments with shelf-appeal and resealability requirements.
Restaurants command the largest procurement volumes, though Catering Services is expanding most quickly as event-based foodservice recovers and institutional contracts consolidate.
Material:
Cost tiers stratify by barrier complexity and regulatory certification burden, with fiber-based formats gaining structural momentum against legacy substrates.
- Paper:Coated fiber-paperboard with mineral or polysaccharide barrier layers replacing metallized films in ambient shelf-stable applications. German integrated pulp-to-packaging operations are capturing share through captive coating capabilities and embedded carbon accounting.
- Plastic:Conventional polyethylene and polypropylene films facing substitution pressure from EU Single-Use Plastics Directive mandates. Bio-polymer alternatives including polylactic acid remain exposed to agricultural feedstock price volatility.
- Aluminum:Thin-gauge foil laminates retaining dominance in retort and extended-shelf dairy where oxygen transmission rates below 0.1 cc/m²/day are mandatory.
- Glass:Premium condiment and single-serve beverage formats with reuse and refill program compatibility in hospitality segments.
Paper is climbing the fastest as quick-service chains accelerate plastic phase-out, while Aluminum defends premium positioning in high-barrier applications.
Distribution Channel:
Channel economics vary by order fragmentation, logistics integration, and sustainability data requirements.
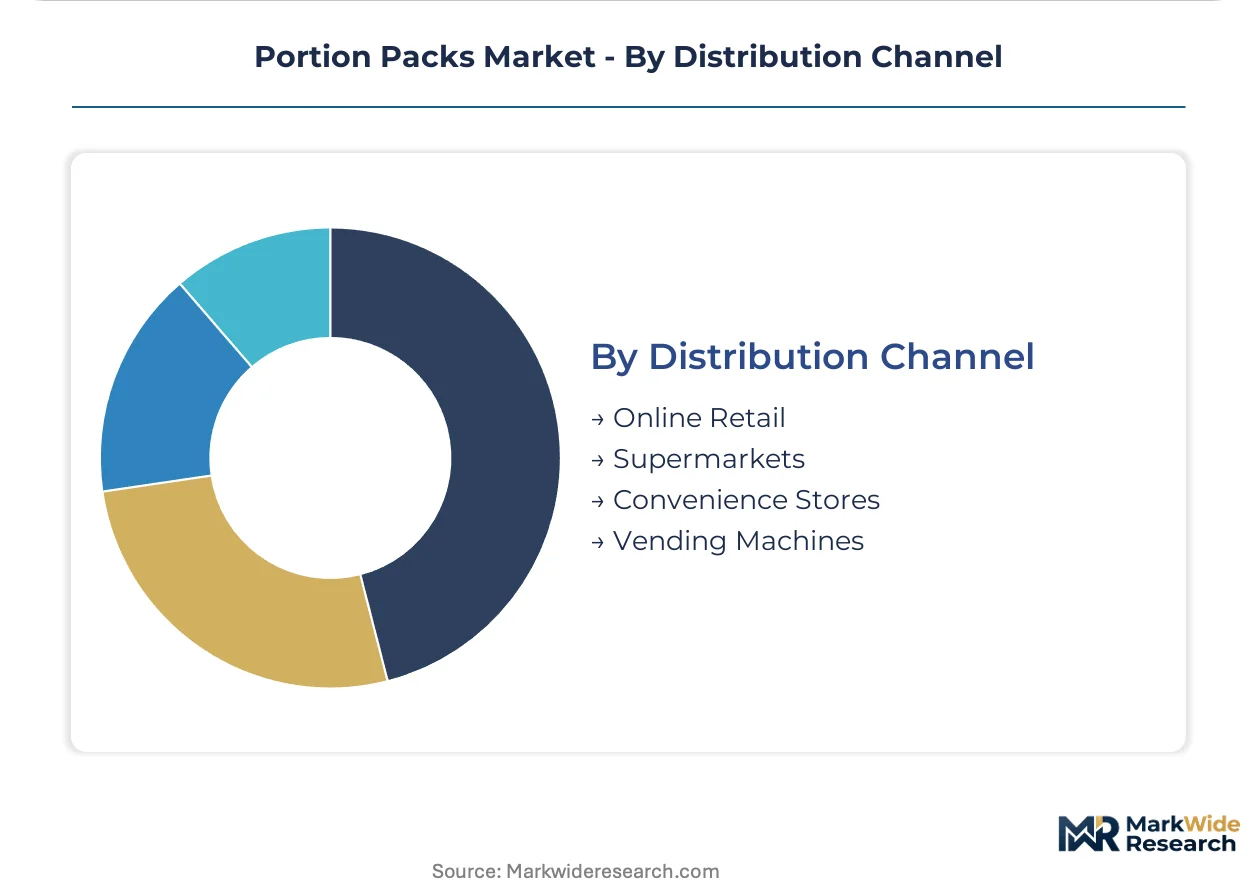
- Supermarkets:Multi-SKU palletized distribution to retail grocery with standardized case counts and traceability documentation. German packaging ordinance compliance is filtering supplier rosters toward certified converters with harmonized waste-sorting instructions.
- Online Retail:Direct-to-operator and direct-to-consumer fulfillment with reduced case minimums and sustainability credential transparency. EPR legislation in multiple U.S. states is creating packaging-as-a-service revenue opportunities with take-back logistics.
- Convenience Stores:High-velocity replenishment of grab-and-go formats with space-optimized merchandising.
- Vending Machines:Automated dispensing compatibility requiring precise dimensional tolerances and mechanical robustness.
Supermarkets retain the deepest penetration, though Online Retail is gaining share fastest as procurement digitization and sustainability verification converge.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany deploys portion packs for automated quick-service dispensing at scale, while India adopts them to reduce operational complexity in fragmented franchise networks. The United States leverages extended producer responsibility frameworks to reshape converter-brand cost allocation. China integrates bio-based barriers into centralized foodservice procurement.
Germany
Quick-service automation and packaging ordinance compliance intersect most aggressively here. The national packaging ordinance and EU Single-Use Plastics Directive jointly filter supplier rosters toward certified converters. Integrated pulp-to-packaging operations in Baden-Württemberg and North Rhine-Westphalia capture share through captive coating capabilities and embedded carbon accounting.
United States
State-level extended producer responsibility legislation in California and New York is creating compliance service revenue streams. FDA food-contact substance notifications shape material legitimacy for multinational foodservice accounts. Midwestern converters near Chicago and Minneapolis-St. Paul are retrofitting thermal sealing lines to handle heat-sensitive bio-substrates.
India
Western fast-food chains penetrating Tier-2 and Tier-3 cities deploy portion-controlled formats to reduce franchise operational complexity. FSSAI food safety standards and evolving packaging waste rules create layered compliance obligations. Maharashtra and Karnataka host the fastest-growing converter clusters as procurement digitization accelerates.
China
Centralized procurement by multinational quick-service brands demands consolidated sustainability reporting across substrate categories. SAMR food-contact regulations and dual carbon goals redirect R&D investment toward mineral-based barriers. Yangtze River Delta integrated fiber-paperboard operators are qualifying certified recyclable formats for pan-Asian supply chains.
France
Hot-fill sauce segments in Lyon and Marseille are accelerating polysaccharide-based coating trials to secure menu commitments. ANSM migration limit standards and EU REACH restrictions on perfluorinated compounds eliminate legacy grease-resistant chemistries. Auvergne-Rhône-Alpes converters face EFSA testing backlogs extending qualification timelines for novel bio-based barriers.
Portion Packs Market Competitive Landscape
Capability concentration sits with integrated fiber-paperboard operators; scale advantage sits with high-speed form-fill-seal specialists. The vendor base stratifies across three tiers: multinational integrated pulp-to-packaging groups, regional high-velocity converters, and niche hospitality customization shops. Dominant competitive moves include M&A to secure captive coating capabilities and strategic partnerships to anchor multinational quick-service supply chains.
Among integrated European operators, Mondi exemplifies the certified recyclable format archetype through its fiber-paperboard operations. Turpack occupies a position within the high-speed form-fill-seal specialization tier for single-serve applications. Elite Portion Pack represents the premium hospitality sachet segment through its focus on short-run customization workflows.
| Leading Market Players |
|---|
| HELLMA |
| Elite Portion Pack |
| SAES |
| Alba |
| Single Source Limited |
| Turpack |
| Alcoa |
| Mondi |
| Van Oordt |
| Others |
Value Network & Pricing Analysis
Overcapacity in European fiber-paperboard coating operations is compressing margin structures for non-integrated converters while amplifying pricing leverage for captives with in-house mineral-barrier capabilities. German quick-service procurement teams exploit this utilization asymmetry to extract sustainability-linked cost concessions from suppliers lacking certified recyclable formats.
Pricing Analysis
Long-term offtake agreements dominate procurement between multinational quick-service brands and integrated fiber-paperboard operators, with spot purchasing confined to fragmented catering and independent restaurant segments. Pricing stratifies across premium, standard, and economy tiers based on EFSA migration certification status and embedded carbon accounting transparency. Cost compression in standard-grade plastic-alternative substrates is intensifying because REACH-compliant mineral coating R&D has collapsed technical differentiation among mid-tier converters. Quick-service chains with centralized procurement exhibit lowest price sensitivity, while independent cafés and event caterers face acute margin pressure from minimum order quantity thresholds.
Supply Chain Analysis
EU export-control restrictions on perfluorinated alkyl substance manufacturing equipment limit technology transfer to non-European coating operations, constraining barrier-coating capacity expansion outside integrated European pulp-to-packaging hubs. Raw material flows draw from Swedish pulp operations, German kaolin deposits, and Italian polysaccharide resin production. Single-source vulnerability concentrates in mineral-coated paperboard supply chains clustered around Baden-Württemberg and North Rhine-Westphalia. Distribution runs through palletized direct-to-warehouse fulfillment for multinational chains, with smaller operators purchasing via distributor networks with sustainability documentation add-ons.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
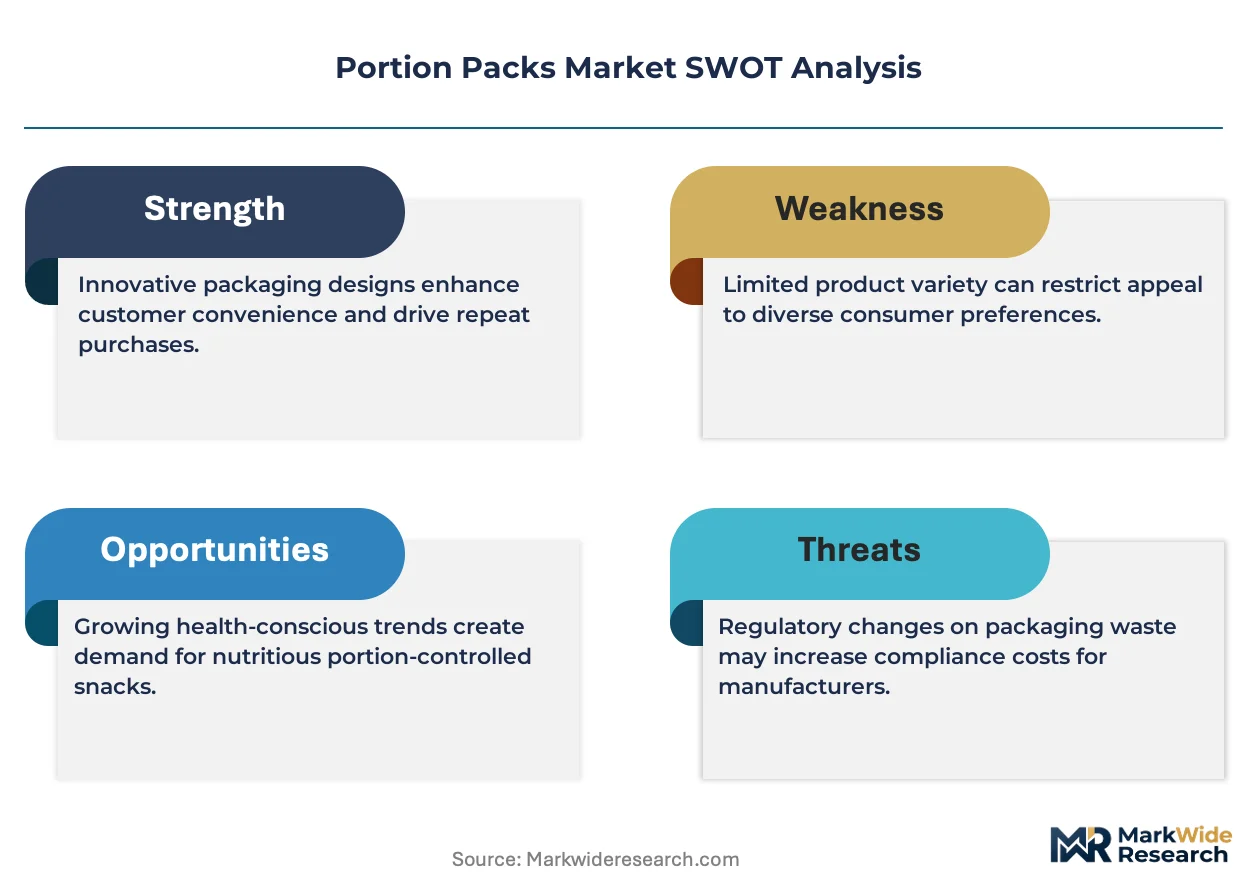
Certified barrier-coating capabilities have become the constraining asset in this market, with EFSA approval timelines and REACH-compliant formulation expertise separating viable suppliers from commodity converters. The capability gap widens as quick-service automation mandates accelerate demand for precision-calibrated formats that only integrated operators can deliver at scale.
For Market Incumbents: Build regulatory-certification moats by accelerating EFSA novel food-contact substance filings for mineral-based barrier innovations before testing backlogs extend further. Defend against emerging Asian converters by securing long-term pulp supply agreements with Nordic suppliers and embedding ultrasonic welding capabilities into existing form-fill-seal lines to collapse changeover economics for micro-lot hospitality orders.
For New Entrants and Emerging Players: Build out white-space positions in Indian Tier-2 and Tier-3 quick-service supply chains where Western fast-food franchise expansion outpaces local converter qualification speed. Target catering services automation compatibility as the most penetrable segment, leveraging ultrasonic welding convergence to offer SKU-flexible production economics that integrated giants disdain. Go-to-market through packaging-as-a-service models with embedded take-back logistics to capture extended producer responsibility compliance revenue streams.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across bio-based barrier coating R&D as EFSA migration testing timelines extend and equipment retrofit costs for heat-sensitive substrates escalate. Five-to-ten year viability favors converters with captive pulp operations and in-house coating capabilities over asset-light traders. Acquisition targets include regional German fiber-paperboard operators with pending EFSA certifications and Indian converters with established FSSAI compliance track records. Monitor EFSA approval velocity as the critical inflection signal—accelerated clearances would compress first-mover premiums; further delays would entrench integrated operator pricing power.
| Strategic Initiative | Industry Significance |
|---|---|
| EFSA Novel Substance Filing Acceleration | Secures 18-24 month regulatory lead over mineral-barrier competitors in German quick-service supply chains. |
| Ultrasonic Welding Line Integration | Collapses SKU changeover times to enable economic micro-lot production for hospitality customization segments. |
| Captive Pulp Supply Agreement | Insulates margin stability from Nordic fiber price volatility and packaging ordinance compliance cost spikes. |
| Indian Tier-2 Distribution Partnership | Anchors Western fast-food franchise expansion with localized FSSAI-compliant portion pack supply. |
| Packaging-as-a-Service Model Launch | Captures extended producer responsibility revenue streams from U.S. state-level EPR legislation divergence. |
Research Methodology
The analysis maps condiment pack, beverage pack, single-serve, and snack pack sub-sectors, each validated through procurement directors at multinational quick-service chains, plant managers at integrated fiber-paperboard operations, regulatory affairs leads at coating chemical suppliers, and sustainability officers at foodservice brands. Primary interview intelligence triangulates against EFSA migration limit databases, EU Single-Use Plastics Directive implementation timelines, REACH restriction updates, and customs trade data for pulp and mineral coating inputs. Bottom-up volume builds from SKU-level procurement patterns reconcile with top-down market sizing derived from quick-service outlet expansion forecasts.
Assumptions regarding EU regulatory enforcement consistency, bio-polymer feedstock price stability, and quick-service automation adoption curves were held fixed across scenarios while Indian franchise penetration rates and U.S. EPR legislation progression were varied. Segmentation models incorporate product type, end user, material substrate, and distribution channel dimensions alongside regional regulatory cluster differentiation. CAGRs emerge from fitted growth curves applied to base-year consumption estimates, with cross-validation against foodservice automation capex disclosures and packaging machinery order backlogs.
Stress conditions across EFSA approval timeline extensions, REACH perfluorinated compound restriction tightening, and Nordic pulp supply disruptions were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect these bounded assumptions and documented stakeholder input. Material shifts in EU harmonized packaging waste rule implementation schedules or breakthrough polysaccharide barrier performance would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Containers
Correx Trays Market
Packaging Containers
Cooler Box Market
Packaging Containers
Eyewear Packaging Market
Packaging Containers
Food Portion Pack Market
Packaging Containers
Europe Punnet Trays Market
Packaging Containers
Logistics Packaging Market
Packaging Containers
Hinged Food Containers Market
Packaging Containers
Middle East and Africa Aerosol Cans Market
Packaging Containers
Double Seam Bowl Market
Packaging Containers
Membrane Boxes Market
Packaging Containers
Mini Refillable Spray Dispenser Market
Packaging Containers
Gable Top Liquid Cartons Market
Packaging Containers
Telescope Box Market
Packaging Containers
Insulated Icebox Market
Packaging Containers
Chalk Boxes Market
Packaging Containers
Dosage Cups Market