
 Custom Boxes Market | 2026-2036
Custom Boxes Market Size, Share, and Industry Trends Forecast 2026-2036
Custom Boxes Market Analysis
Subscription-based design tooling is repositioning how custom box vendors capture recurring revenue beyond unit sales. Packlane leverages proprietary online configurators to reduce proofing cycles for mid-market retailers. EcoEnclose anchors its position through certified sustainable material sourcing that appeals to direct-to-consumer brands. Refine Packaging dominates food-safe folding carton production with in-house die-cutting capacity that controls turnaround times.
Custom boxes are structurally engineered paperboard or corrugated fiberboard enclosures, typically manufactured through die-cutting, scoring, and adhesive bonding processes to precise dimensional tolerances, serving primarily to protect, present, and differentiate goods during distribution and retail display. Corrugated boxes lead volume due to e-commerce shipping intensity, while rigid boxes command premium margin pools in cosmetics and luxury retail channels where structural rigidity signals product value. Kraft boxes represent the fastest-growing material trajectory as brands eliminate plastic laminates to meet retailer sustainability scorecards.
The EPA guides recycled content standards for paperboard packaging in the United States, while the EU Packaging and Packaging Waste Regulation mandates extended producer responsibility and recyclability thresholds that reshape converter material choices. FDA compliance for food-contact substrates determines market access for folding carton suppliers serving grocery and meal-kit segments. Stakeholders must monitor how state-level packaging EPR laws in California and New York diverge from federal frameworks, as compliance fragmentation will determine regional manufacturing investment priorities.
Market Dynamics
E-commerce fulfillment velocity is compressing proofing cycles and forcing converters to absorb design iteration costs previously borne by brands, restructuring margin capture across the value chain.
Growth Catalysts
- EU Packaging and Packaging Waste Regulation:Extended producer responsibility mandates are accelerating fiber-based substrate substitution for plastic laminates in export-bound production.
- Meal-kit subscription fulfillment:Direct-to-consumer food delivery channels require specification-grade folding cartons with FDA-compliant food-contact barriers.
- China export manufacturing clusters:High-volume corrugated demand from coastal production zones is pulling specification investment toward automated die-cutting lines.
Market Restraints
- Old corrugated container price volatility:Recycled fiber input costs swing with municipal collection rates, compressing converter margins on fixed-price annual contracts.
- Adhesive supply concentration:Water-based bonding chemistry relies on specialized resin suppliers concentrated in Gulf Coast petrochemical corridors.
- Dimensional tolerancing limits:High-speed flexographic printing on recycled kraft substrates constrains registration accuracy for premium cosmetic applications.
Strategic Opportunities
- India domestic e-commerce expansion:BIS certification pathways for corrugated packaging are opening as Flipkart and Amazon India localize fulfillment infrastructure.
- RFID-embedded smart packaging:Convergence of printed electronics with fiberboard substrates enables inventory tracking for pharmaceutical cold-chain distribution.
- California SB 54 implementation:State-level extended producer responsibility creates first-mover advantage for converters with verified post-consumer recycled content systems.
Industry Challenges
- Structural design engineering talent:Shortage of CAD specialists fluent in ArtiosCAD and Esko workflows limits converter capacity to execute complex retail-ready displays.
- FDA food-contact notification timelines:Novel barrier coatings face 180-day review cycles that delay market entry for meal-kit and prepared food segments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Custom Boxes Market |
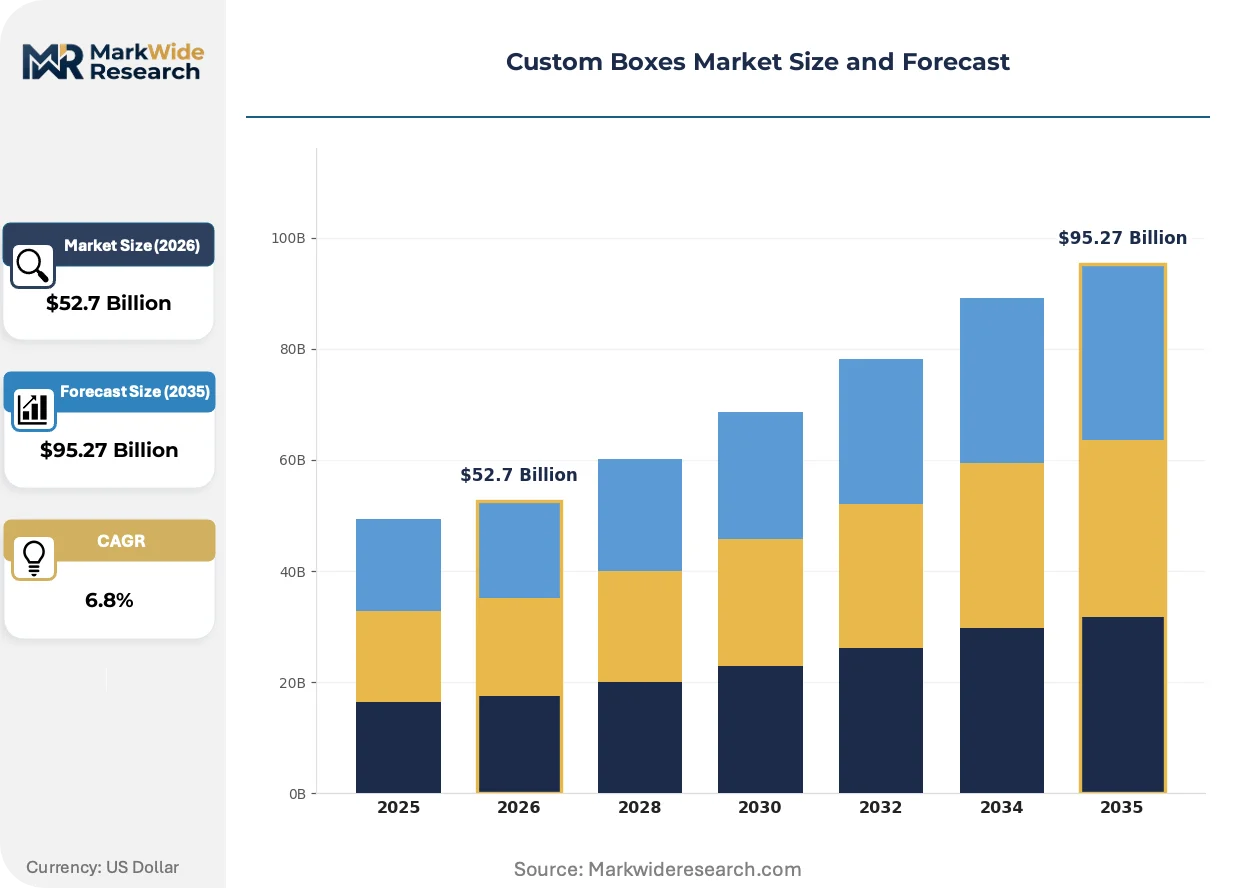
| Market Size in 2026 | $52.7 Billion |
| Market Size in 2035 | $95.27 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Folding Boxes, Rigid Boxes, Corrugated Boxes, Kraft Boxes Material: Cardboard, Paper, Plastic, Wood Application: Food Packaging, Retail Packaging, Pharmaceutical Packaging, Cosmetics Packaging Size: Small, Medium, Large, Custom Sizes |
| Companies Covered | Refine Packaging, Fantastapack, CustomBoxes.io, EcoEnclose, CompanyBox, Arka, PakFactory, The Custom Boxes, Packlane, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Custom Boxes Market Emerging Trajectories
Digital production workflows are collapsing the traditional separation between design, proofing, and manufacturing, enabling batch-size-one economics previously unattainable in corrugated conversion.
Water-based flexographic ink systems with extended color gamut capabilities are rewriting quality benchmarks for branded unboxing experiences. Cosmetic and luxury retailers in France and Germany are adopting these systems for short-run seasonal packaging. The technology is compressing minimum order quantities from ten thousand units to sub-thousand thresholds.
The EPA's recycled content guidelines for paperboard packaging are tightening procurement specifications across United States retail channels. Major grocery chains now require third-party verification of post-consumer fiber percentages. Folding carton suppliers serving private-label segments are requalifying substrate inventories to maintain shelf placement.
Subscription-based packaging design platforms are fragmenting traditional agency relationships. Mid-market retailers in the United States and United Kingdom are bypassing conventional design firms for self-service configurators. Direct-to-consumer brands in cosmetics and nutraceuticals demonstrate the highest adoption velocity, compressing concept-to-production timelines from weeks to days.
Custom Boxes Market Segmentation
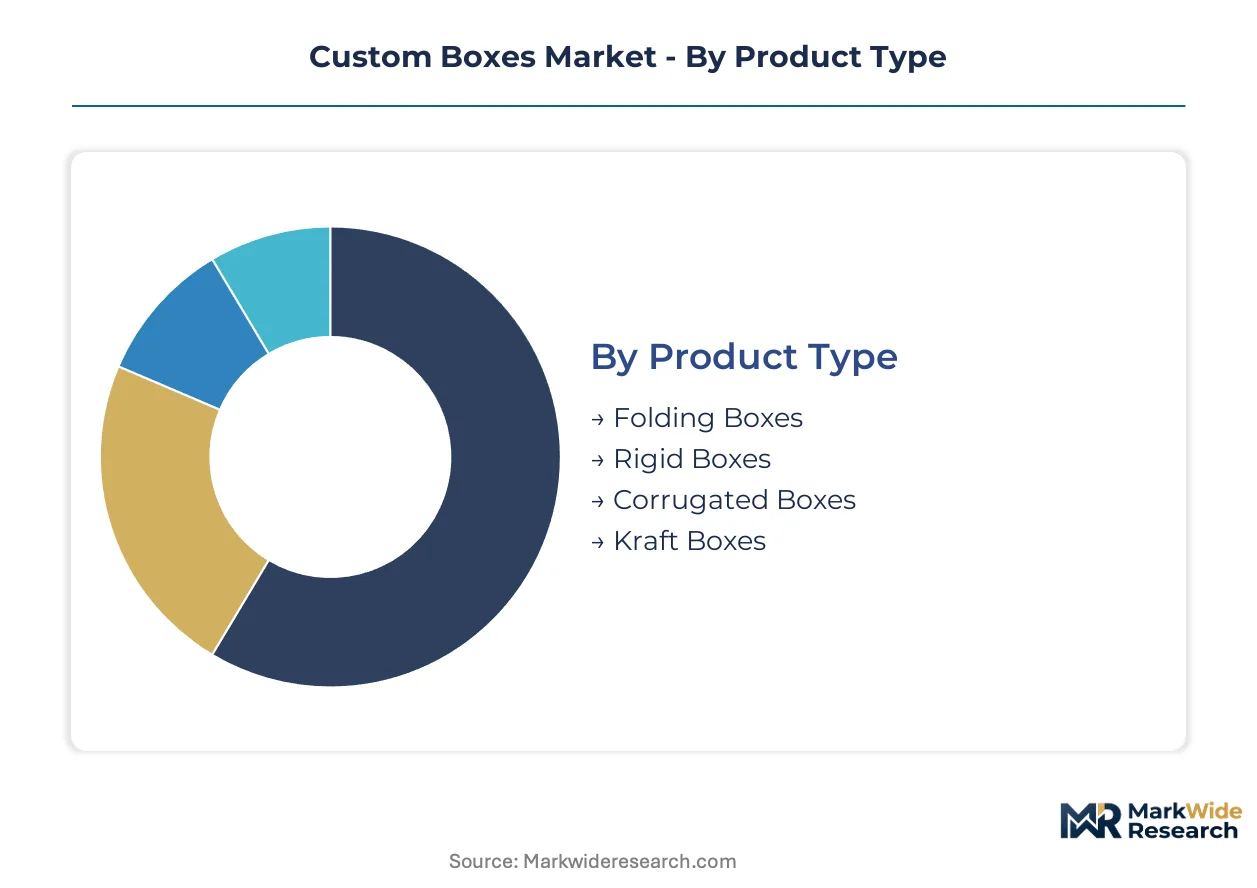
Segmentation in custom boxes determines capital allocation priorities for converters, as die-cutting automation, barrier coating lines, and design tooling investments vary dramatically across substrate types and end-use specifications. Understanding where margin pools concentrate versus where volume scales enables targeted capacity deployment.
Product Type:
Corrugated and rigid box production demand the heaviest upfront capital, with automated rotary die-cutters and rigid board laminators representing multi-million dollar line investments that shape competitive moats.
- Corrugated Boxes:Fluted fiberboard structures manufactured through single- or double-wall corrugation processes, with edge crush test ratings determining stackability for palletized distribution. E-commerce fulfillment centers in the United States absorb the majority of specification-grade volume, driven by Amazon, Walmart, and Target vendor compliance programs that mandate burst strength and box compression test thresholds. The EU Packaging and Packaging Waste Regulation is accelerating fiber-based substitution for plastic shipping mailers in export-bound production.
- Rigid Boxes:Thick paperboard enclosures built on wrapped rigid setups with turned edges, delivering structural rigidity for premium unboxing experiences. Demand concentrates in French and German cosmetics retail channels, where structural packaging signals product value and justifies price positioning. Setup box production requires manual assembly stations or specialized rigid box lines with lower throughput than corrugated alternatives.
- Folding Boxes:Lightweight paperboard cartons scored and glued for flat shipment and retail shelf assembly, dominating grocery and pharmaceutical blister pack applications.
- Kraft Boxes:Unbleached recycled fiber enclosures with natural aesthetic appeal, gaining traction among direct-to-consumer brands eliminating plastic laminates to meet retailer sustainability scorecards.
Corrugated boxes absorb the bulk of installed capacity; kraft boxes are expanding most quickly.
Material:
Raw material selection governs converter supplier relationships, with virgin fiber, recycled pulp, and petroleum-derived substrates each anchoring distinct procurement and pricing dynamics.
- Cardboard:Multi-ply paperboard ranging from folding carton grades to corrugated medium, representing the dominant substrate by tonnage across all applications. FDA food-contact notification requirements for recycled content grades determine market access for meal-kit and prepared food segments.
- Paper:Lightweight printable substrates including coated and uncoated freesheet, serving as outer wraps and labels rather than structural elements. Specialty papers with extended color gamut capabilities are displacing conventional offset stocks in cosmetic short-run production.
- Plastic:PET, PP, and polystyrene enclosures for moisture barrier and transparent display applications, facing displacement pressure from fiber-based alternatives under EU extended producer responsibility mandates.
- Wood:Crating and specialty display applications requiring structural load-bearing capacity, concentrated in industrial equipment and fine art logistics segments with low volume but premium pricing.
Cardboard commands the deepest supplier integration; paper is climbing the fastest on digital print compatibility.
Application:
End-use specifications dictate regulatory compliance burdens, with food-contact and pharmaceutical applications imposing the steepest qualification barriers to entry.
- Food Packaging:Folding cartons and corrugated shipping containers with FDA-compliant food-contact barriers, grease resistance, and moisture vapor transmission controls. Meal-kit subscription fulfillment channels require specification-grade materials with 180-day notification timelines for novel coatings.
- Cosmetics Packaging:Rigid boxes and specialty folding cartons with premium finishing, embossing, and foil stamping for brand differentiation. French and German retailers are adopting water-based flexographic systems for short-run seasonal packaging, compressing minimum order quantities.
- Retail Packaging:Point-of-sale displays and shelf-ready packaging with structural design complexity for retail environment performance.
- Pharmaceutical Packaging:Cold-chain distribution enclosures with temperature stability and child-resistant compliance requirements, emerging as a testbed for RFID-embedded smart packaging convergence.
Food packaging absorbs the bulk of compliance investment; pharmaceutical packaging is gaining share fastest on track-and-trace mandates.
Size:
Dimensional range determines equipment flexibility requirements, with custom size capability separating job-shop converters from high-volume specialists.
- Small:Jewelry, electronics accessories, and sample-size cosmetics enclosures, typically produced on platen die-cutters with quick-change tooling for batch-size-one economics.
- Medium:Standard shipping cartons and retail shelf cartons, representing the volume core of corrugated converter output with established tooling libraries.
- Large:Appliance and furniture shipping containers requiring double-wall or triple-wall corrugation and specialized bundle-breaking equipment.
- Custom Sizes:Specification-driven dimensional tolerancing for dimensional weight optimization in parcel carrier networks, enabled by digital production workflows that collapse design-to-manufacturing timelines.
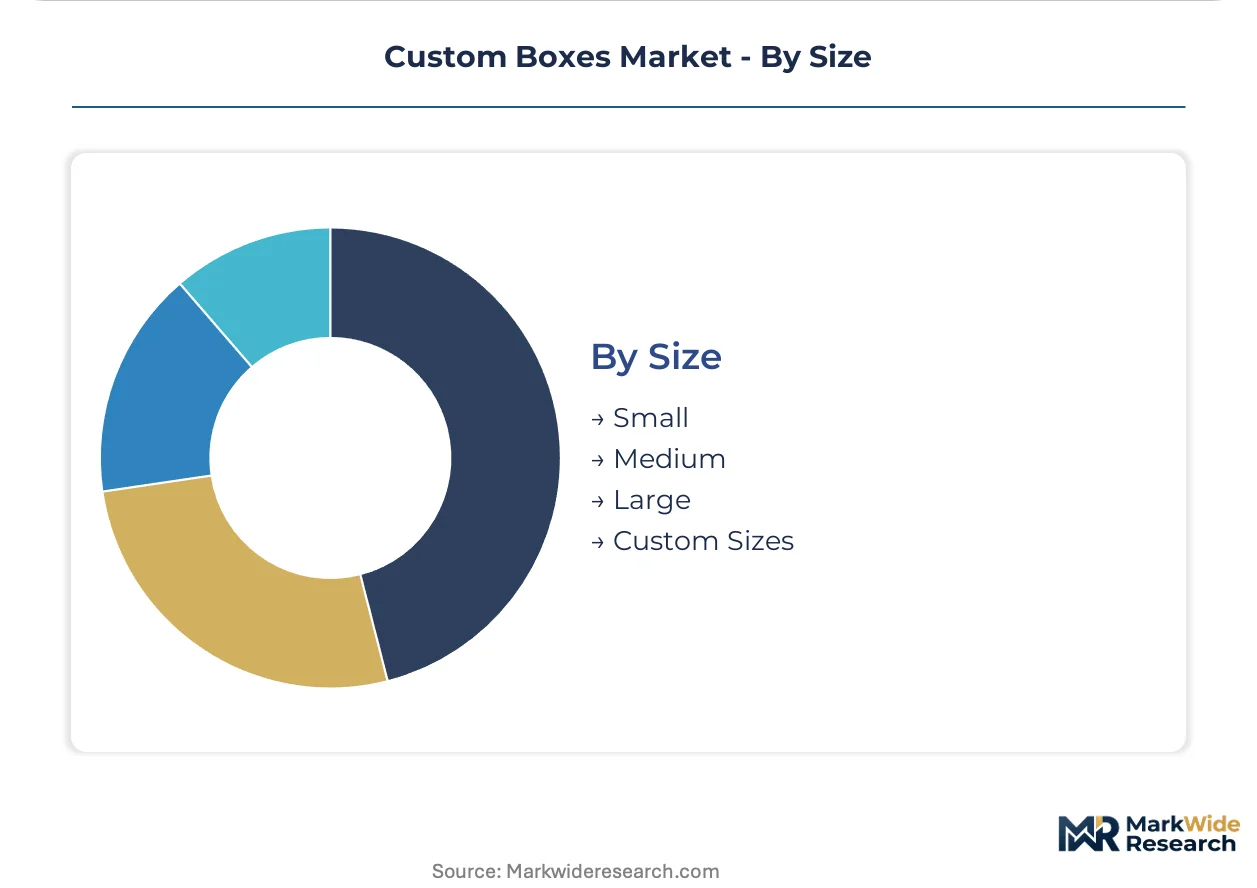
Medium sizes absorb the bulk of line utilization; custom sizes are expanding most quickly on e-commerce dimensional weight optimization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production clusters concentrate in export manufacturing zones while consumption pulls from e-commerce fulfillment centers in major consumer markets. This geographic split shapes converter investment patterns and regulatory compliance burdens.
United States
E-commerce fulfillment velocity from Amazon, Walmart, and Target vendor programs drives specification-grade corrugated demand. The EPA guides recycled content standards for paperboard packaging while FDA compliance governs food-contact substrates for meal-kit segments. Automated die-cutting lines in Chicago and Dallas-Fort Worth serve central distribution corridors with compressed proofing cycles.
China
Coastal export manufacturing clusters in Guangdong and Zhejiang provinces pull high-volume corrugated investment for specification-grade production. The country's national environmental regulator enforces dual carbon goals that reshape converter material choices toward fiber-based alternatives. Shenzhen and Dongguan house automated production lines serving electronics and consumer goods exporters.
Germany
Cosmetics and luxury retail channels in French and German markets command premium rigid box demand with structural rigidity requirements. The EU Packaging and Packaging Waste Regulation mandates extended producer responsibility and recyclability thresholds that reshape converter material selections. The Rhine-Ruhr industrial corridor hosts specialized rigid box production for European premium brands.
India
Domestic e-commerce expansion from Flipkart and Amazon India localization drives BIS certification pathways for corrugated packaging. The Bureau of Indian Standards governs quality benchmarks for packaging materials entering food-contact applications. Maharashtra and Karnataka states concentrate fulfillment infrastructure investment with specification-grade converter capacity.
United Kingdom
Mid-market retailers bypass conventional design firms for subscription-based packaging configurators with compressed timelines. The country's national environmental agency implements packaging waste regulations aligned with EU extended producer responsibility frameworks. London and Manchester clusters serve direct-to-consumer brands in cosmetics and nutraceuticals with digital production workflows.
Custom Boxes Market Vendor Landscape
Capital-heavy producers compete with asset-light designers across a structurally fragmented vendor base. Automated rotary die-cutters and rigid board laminators represent multi-million dollar line investments that separate high-volume specialists from job-shop converters. Three archetypes dominate: vertically integrated manufacturers with captive substrate supply, design-platform intermediaries capturing recurring SaaS revenue, and sustainability-certified specialists serving direct-to-consumer brands. Capacity expansion and strategic partnerships constitute the dominant competitive moves as converters absorb design iteration costs previously borne by brands.
Among United States-based platforms, Packlane and EcoEnclose exemplify divergent positioning archetypes. Packlane occupies the design-tooling tier with proprietary online configurators that compress proofing cycles for mid-market retailers. EcoEnclose anchors the sustainability-certified segment through verified post-consumer recycled content systems that appeal to direct-to-consumer brands. Refine Packaging represents the integrated production archetype with in-house die-cutting capacity controlling turnaround times for food-safe folding carton applications.
| Leading Market Players |
|---|
| Refine Packaging |
| Fantastapack |
| CustomBoxes.io |
| EcoEnclose |
| CompanyBox |
| Arka |
| PakFactory |
| The Custom Boxes |
| Packlane |
| Others |
Supply Flow & Price Mechanics
Digital production workflows collapsing design-to-manufacturing timelines simultaneously compress converter margins and concentrate supply among capital-intensive operators with automated rotary die-cutting capacity. The shift redraws competitive boundaries between asset-heavy producers absorbing iteration costs and design-platform intermediaries capturing recurring SaaS revenue.
Pricing Analysis
Cost-down pressure on specification-grade corrugated accelerates because e-commerce fulfillment centers demand compressed proofing cycles without compensatory price premiums. Three-tier pricing structure across premium rigid boxes, standard corrugated shipping cartons, and economy kraft mailers stratifies by certification grade and volume scale. Old corrugated container price volatility tightens margins on fixed-price annual contracts. Mid-market retailers exhibit highest price sensitivity, while cosmetics brands purchasing rigid boxes demonstrate lowest sensitivity due to structural packaging's role in signaling product value.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand from Amazon, Walmart, and Target vendor compliance programs, while self-service configurators serve direct-to-consumer brands with batch-size-one economics. Supply concentrates in China for high-volume corrugated, Germany for premium rigid box production, and the United States for specification-grade e-commerce fulfillment. Raw material dependencies draw from recycled fiber pulp, water-based adhesive resins, and specialty coated paperboard. Single-source vulnerability in Gulf Coast petrochemical corridors for adhesive chemistry represents the dominant structural risk.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Automated die-cutting line capacity constraints prop pricing power for converters with installed multi-million dollar equipment, creating supply-constrained conditions favoring incumbents with capital deployment capability.
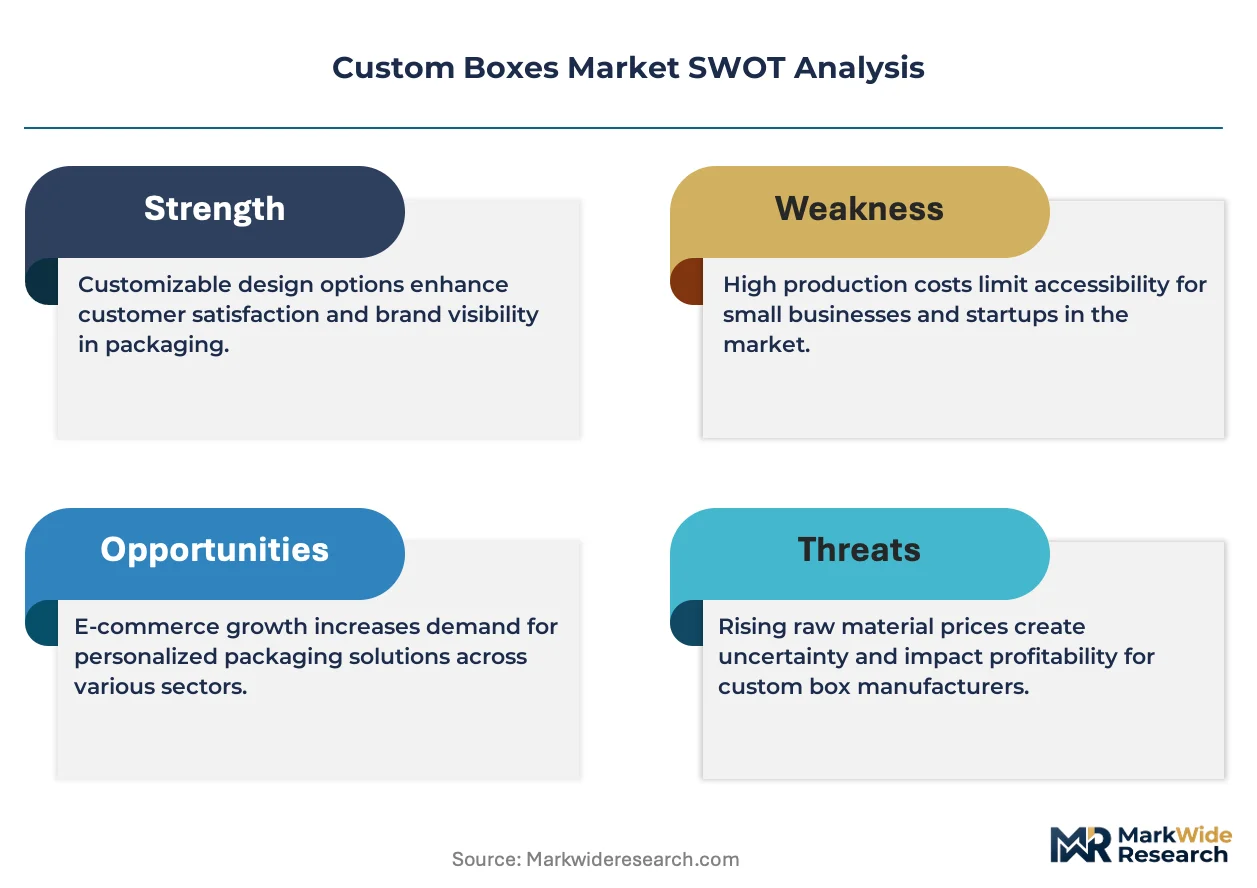
For Market Incumbents: To counter margin compression from absorbed design iteration costs, deepen backward integration into recycled fiber sourcing and expand rigid box laminator capacity in the Rhine-Ruhr corridor. Certification investment in FDA food-contact barrier systems secures meal-kit segment access against emerging entrants. For New Entrants and Emerging Players: Launch via subscription-based design configurators targeting mid-market cosmetics and nutraceuticals brands in the United Kingdom and United States. White-space concentrates in BIS-certified corrugated for Flipkart and Amazon India localization, with sustainability-verified kraft boxes offering the most penetrable entry angle. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by vertically integrated packaging conglomerates seeking digital workflow capabilities. Long-term viability favors converters with verified post-consumer recycled content systems and in-house die-cutting capacity. Monitor California SB 54 implementation timelines as the signal to watch for regional manufacturing investment inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Automated Die-Cutting Line Investment | Captures specification-grade volume from Amazon and Walmart vendor programs with compressed turnaround. |
| Backward Integration into Recycled Fiber | Insulates margin from old corrugated container price volatility on fixed-price contracts. |
| Subscription Design Platform Launch | Captures recurring SaaS revenue from mid-market retailers bypassing traditional agencies. |
| FDA Food-Contact Barrier Certification | Unlocks meal-kit and prepared food segments with 180-day notification compliance. |
| RFID-Embedded Smart Packaging Development | Enables pharmaceutical cold-chain track-and-trace for emerging regulatory mandates. |
Methodological Framework
Multi-period observation of converter capacity utilization, e-commerce fulfillment velocity, and regulatory compliance timelines anchored the trend analysis, supplemented by interviews with corrugated plant managers, rigid box production engineers, brand packaging directors at direct-to-consumer companies, and procurement leads at major retailers. Secondary validation drew from EPA recycled content guidelines, EU Packaging and Packaging Waste Regulation filings, FDA food-contact notification databases, and customs trade data. Bottom-up segmentation modeling and top-down macroeconomic triangulation reconciled volume estimates.
Input-output matrices structured demand drivers across product type, material substrate, end-use application, and dimensional specification through the projection horizon. CAGRs derived from regression analysis against e-commerce penetration rates and regulatory implementation timelines. Modeled variables included automated production line deployment, barrier coating qualification cycles, and sustainability certification adoption curves.
Old corrugated container price volatility, FDA notification timeline delays, and state-level EPR law fragmentation are the dominant revision risks to forecast assumptions. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Containers
Logistics Packaging Market
Packaging Containers
Roll-On Bottles Market
Packaging Containers
Packing Boxes Market
Packaging Containers
Sanitizer Bottles Market
Packaging Containers
Hinged Food Containers Market
Packaging Containers
Middle-East and Africa Paper Cups Market
Packaging Containers
Global Acrylic Airless Bottle Market
Packaging Containers
Inverted Squeeze Bottle Market
Packaging Containers
Acrylic Boxes Market
Packaging Containers
Child Resistant Bottles Market
Packaging Containers
Gable Boxes Market
Packaging Containers
Pump Dispenser Market
Packaging Containers
Euro Box Market
Packaging Containers
Cooler Box Market
Packaging Containers
North America Food Cans Market
Packaging Containers
Trigger Spray Bottle Market