
 Oxo Biodegradable Bags Market | 2026-2036
Oxo Biodegradable Bags Market Size, Share, and Industry Trends Forecast 2026-2036
Oxo Biodegradable Bags Market Analytics
Subscription-based compliance monitoring and additive replenishment programs is broadening how resin suppliers and converters monetize oxo-biodegradable formulations. Symphony Environmental Technologies PLC leverages its d2w additive licensing network to sustain recurring revenue across multiple polymer platforms. Novolex Holdings, LLC anchors North American production capacity through integrated film extrusion and bag conversion facilities. ProAmpac competes in food-service applications with specialized high-clarity formulations that meet retail branding requirements.
Oxo biodegradable bags incorporate pro-oxidant additives—typically metal salts such as cobalt or manganese stearates—into conventional polyethylene resins to accelerate fragmentation and subsequent biodegradation under oxidative and thermal stress, with primary commercial purpose being reduction of persistent plastic litter in open environments and compliance with extended producer responsibility frameworks. Shopping bags and trash bags dominate volume throughput, with trash bags commanding firmer unit economics due to municipal tender specifications and industrial procurement scale. LDPE and LLDPE material grades lead extrusion output, while additive-based compounds represent the fastest-growing margin pool as masterbatch suppliers consolidate intellectual property around transition-metal catalyst systems.
The EU REACH regulation and F-Gas Framework constrain additive chemistries permitted in European film applications, while the US EPA and state-level environmental agencies in California shape landfill-diversion targets that indirectly influence bag specification demand. India's BIS certification requirements for biodegradable plastics create additional compliance thresholds for export-oriented manufacturers. Stakeholders must monitor evolving standards from ISO and national regulators to determine whether fragmentation-rate claims satisfy emerging biodegradability verification protocols before committing capital to capacity expansion.
Market Dynamics
Extended producer responsibility frameworks across Germany, France, and California are forcing resin converters to reformulate conventional polyethylene with metal-salt pro-oxidant additives, compressing time-to-fragmentation specifications from decades to months in open-environment disposal scenarios.
Growth Catalysts
- EU Single-Use Plastics Directive:Member state transposition mandates oxo-biodegradable specifications for carrier bags in supermarket retail chains, creating pull-through demand for LDPE film extruders serving German and French distribution networks.
- Municipal waste tender programs:City procurement departments in California and New York specify fragmentation-rate compliance for bin liner contracts, locking in multi-year volume commitments with additive-integrated suppliers.
- Masterbatch catalyst innovation:Cobalt and manganese stearate compound advances reduce additive load rates while maintaining oxidative stress performance, improving converter margin structures on high-throughput blown film lines.
Market Restraints
- REACH additive constraints:ECHA scrutiny of transition-metal migration limits restricts cobalt stearate concentrations in food-contact film applications, forcing reformulation costs onto European compounders.
- LLDPE feedstock volatility:Ethylene price swings tied to naphtha cracking economics compress extruder margins when long-term municipal contracts fix bag pricing.
- Biodegradability verification gaps:ISO fragmentation protocols lack harmonization with soil biodegradation standards, creating liability exposure for producers claiming environmental performance in uncontrolled litter environments.
Strategic Opportunities
- India BIS certification pipeline:Export-oriented manufacturers capturing share in Maharashtra and Gujarat retail sectors as the Bureau of Indian Standards finalizes biodegradable plastics compliance thresholds.
- Agricultural mulch film conversion:Oxo-biodegradable polyethylene displacing conventional mulch in open-field vegetable production across Spain and Italy, where soil-plastic accumulation triggers regulatory scrutiny.
- Subscription additive replenishment:Licensing models for d2w and comparable pro-oxidant masterbatches generate recurring revenue streams independent of resin volume cyclicality.
Industry Challenges
- Transition-metal toxicology assessment:Toxicologists and polymer chemists with dual expertise in oxidative degradation pathways and environmental fate modeling command premium compensation, constraining R&D team scaling.
- Multi-jurisdiction certification sequencing:Parallel BIS, REACH, and FDA food-contact filings require 18-24 month compliance timelines before commercial shipment authorization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Oxo Biodegradable Bags Market |
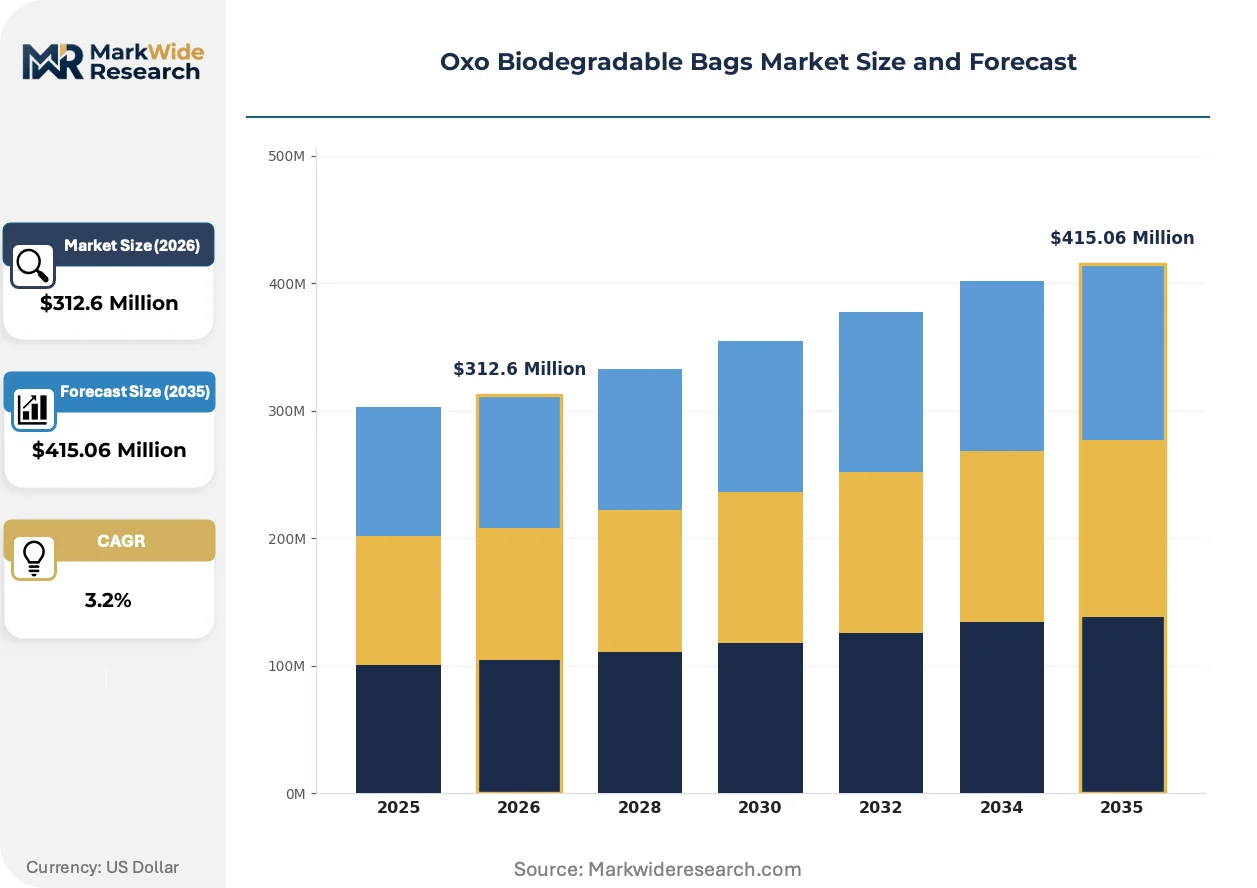
| Market Size in 2026 | $312.6 Million |
| Market Size in 2035 | $415.06 Million |
| CAGR (2026 – 2036) | 3.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Shopping Bags, Trash Bags, Food Storage Bags, Dog Waste Bags Material: LDPE, LLDPE, HDPE, Additive-Based Compounds Application: Retail, Food Services, Household, Industrial Distribution Channel: Online Stores, Supermarkets, Convenience Stores, Wholesale |
| Companies Covered | Novolex Holdings, LLC, ProAmpac, Symphony Environmental Technologies PLC, EarthAware, Airpack Systems, Natur-Tec, BioBag International AS, Neoteric Packaging, Amcor plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Oxo Biodegradable Bags Market Evolving Landscape
Fragmentation-rate verification technology and additive dosing precision are compressing the gap between pro-oxidant marketing claims and measurable environmental outcomes, reshaping how converters demonstrate compliance to procurement officers.
Next-generation metal-salt masterbatch formulations with encapsulated cobalt stearate is decentralizing additive manufacturing from centralized compounders to regional film extrusion facilities. Mid-scale converters in Poland and the Czech Republic now license on-site dosing systems, reducing freight costs and inventory carrying burdens. This technology is compressing supply chain tiers between additive IP holders and finished bag producers.
REACH F-Gas Framework amendments targeting fluorinated greenhouse gases are indirectly constraining alternative biodegradable film chemistries that rely on perfluorinated processing aids. European compounders face reformulation mandates across multiple polymer platforms simultaneously. Food-service bag specifications in France and Belgium now explicitly exclude fluorinated additive traces, redirecting R&D expenditure toward metal-salt oxidation pathways.
Retail chain sustainability scorecards now weight third-party fragmentation certification above unit cost in vendor selection algorithms. German supermarket procurement departments prioritize BPI and TÜV-validated oxo-biodegradable claims over unverified supplier assertions. This behavioral pivot concentrates contract awards among converters with in-house analytical laboratories capable of generating ISO-compliant test documentation.
Oxo Biodegradable Bags Market Segmentation
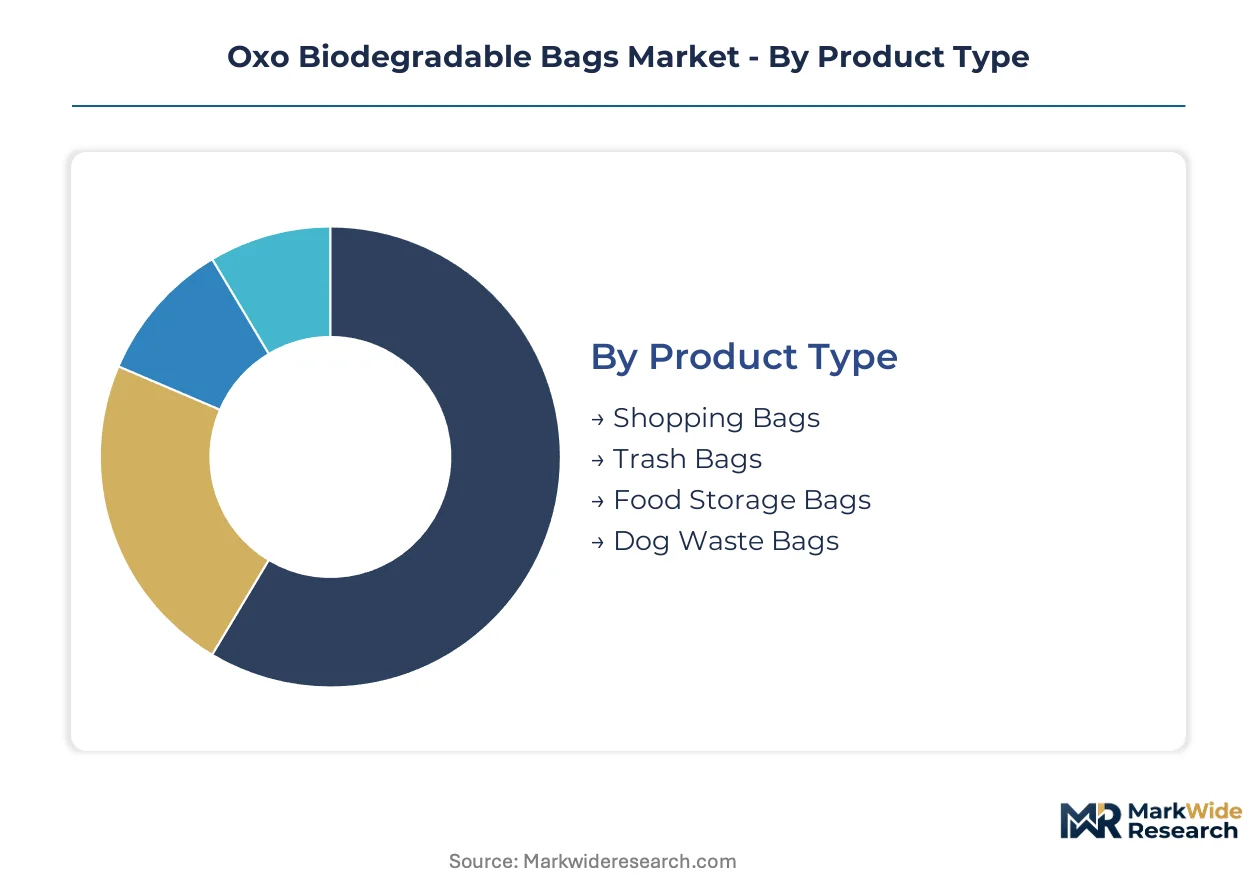
Segmentation in oxo-biodegradable bags reveals how capital deployment, regulatory compliance, and end-use specifications intersect. Procurement officers and resin converters use these categories to match additive formulations with performance requirements and certification thresholds.
Product Type:
Capital intensity varies sharply across bag formats, with municipal-scale contracts demanding extrusion lines capable of 24-hour continuous output and automated conversion.
- Shopping Bags:These carrier bags integrate pro-oxidant masterbatches at 1-2% load rates into LDPE film to meet EU Single-Use Plastics Directive fragmentation specifications. German supermarket chains now require TÜV-validated degradation claims, locking converters into multi-year certification investments.
- Trash Bags:Municipal tender programs in California and New York specify oxidative degradation timelines for bin liners, creating volume commitments that justify dedicated blown-film capacity. Industrial procurement scales compress unit economics below retail bag equivalents.
- Food Storage Bags:REACH-constrained metal-salt formulations limit cobalt stearate migration in food-contact applications, restricting supplier pools to compounders with ECHA-compliant masterbatch certifications.
- Dog Waste Bags:Compact roll formats for pet retail channels carry lower barrier-to-entry for regional converters, though fragmentation-rate verification remains mandatory for premium positioning.
Most installed capacity flows through Trash Bags. Expansion is steepest in Shopping Bags.
Material:
Feedstock selection determines additive compatibility, extrusion throughput, and compliance pathway complexity for converters serving regulated end-markets.
- LDPE:Low-density polyethylene dominates blown-film extrusion for carrier bags due to clarity and sealability, with cobalt stearate masterbatches dispersing uniformly at standard processing temperatures.
- LLDPE:Linear low-density grades command industrial trash bag specifications for puncture resistance, though ethylene price volatility tied to naphtha cracking economics compresses margins on fixed-price municipal contracts.
- HDPE:High-density formulations serve rigid-handle shopping bags and thicker gauge applications where stiffness outweighs film clarity requirements.
- Additive-Based Compounds:Encapsulated pro-oxidant masterbatches with manganese stearate catalysts represent the fastest-climbing margin pool as licensing models decentralize manufacturing to regional extruders.
Volume concentrates in LDPE. Margin expansion is sharpest in Additive-Based Compounds.
Application:
End-use specifications fragment demand across certification regimes, with food-contact and industrial segments imposing divergent additive chemistry constraints.
- Retail:German and French supermarket sustainability scorecards weight third-party fragmentation certification above unit cost, concentrating contract awards among converters with in-house ISO-compliant testing laboratories.
- Food Services:High-clarity formulations for branded takeout bags in France and Belgium exclude fluorinated processing aids under F-Gas Framework amendments, redirecting R&D toward metal-salt oxidation pathways.
- Household:Consumer bin liner demand clusters in private-label channels where price sensitivity limits premium positioning for verified biodegradability claims.
- Industrial:Agricultural mulch film applications in Spain and Italy displace conventional polyethylene in open-field vegetable production, where soil-plastic accumulation triggers regulatory scrutiny.
Procurement scale peaks in Industrial. Certification intensity is highest in Food Services.
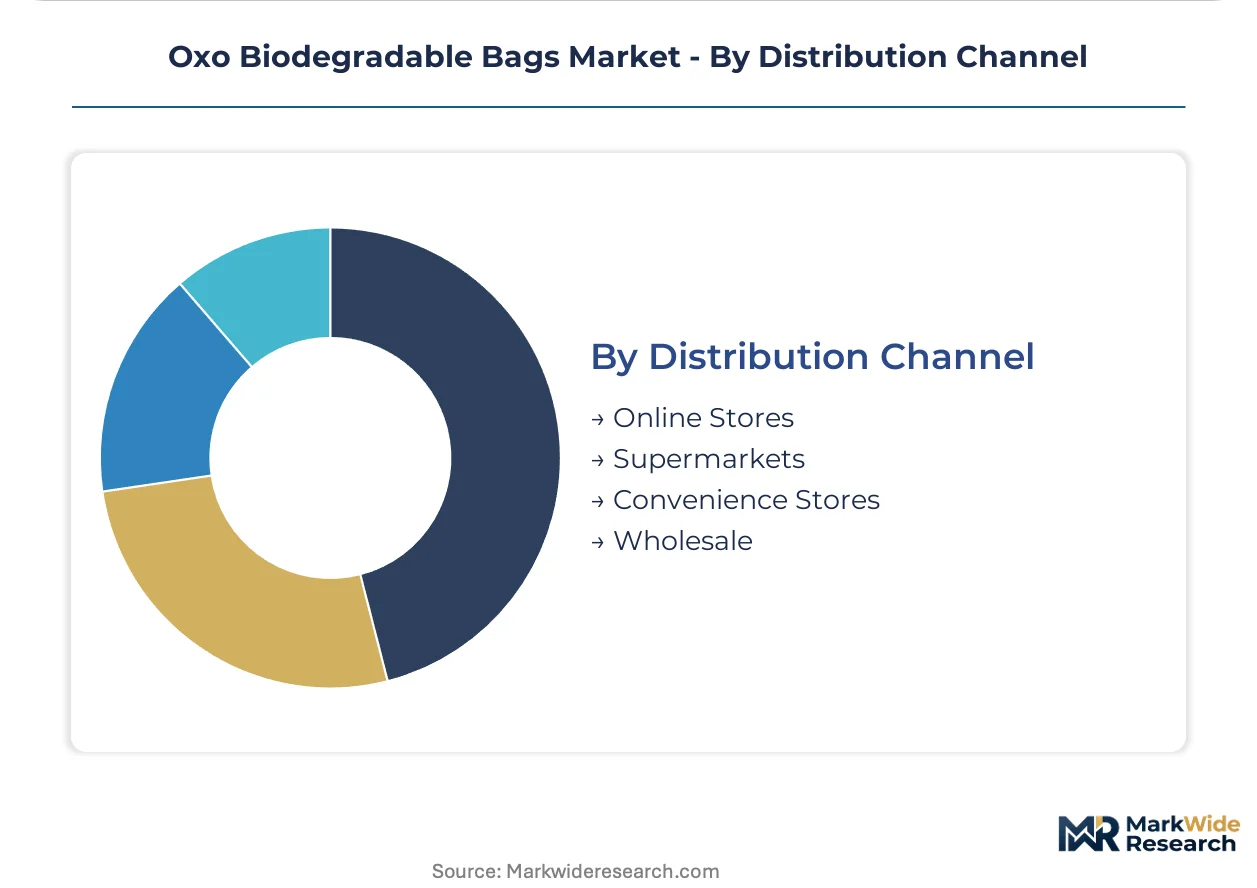
Distribution Channel:
Channel selection shapes inventory velocity, margin capture, and the feasibility of subscription-based additive replenishment programs.
- Online Stores:E-commerce direct-to-consumer channels for dog waste bags and household bin liners enable rapid SKU testing, though fragmentation verification documentation requirements limit marketplace seller pools.
- Supermarkets:German retail chains anchor volume throughput for shopping bags, with procurement departments mandating d2w-licensed additive integration and multi-year supply agreements.
- Convenience Stores:Impulse-purchase carrier bags in urban California and New York locations face state-level single-use plastic restrictions, accelerating oxo-biodegradable specification adoption.
- Wholesale:Industrial and municipal tender channels for trash bags concentrate demand through distributor networks capable of managing 18-24 month certification documentation cycles.
Contract value concentrates in Wholesale. Channel expansion is fastest in Online Stores.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Converters migrate production toward jurisdictions with harmonized additive approval pathways, exploiting compliance-cost differentials between REACH-constrained Europe and rapidly certifying Asian markets. This arbitrage reshapes extrusion capacity placement and masterbatch licensing geography.
Germany
Supermarket chains and municipal waste programs anchor European demand for oxo-biodegradable carrier bags and bin liners. The EU Single-Use Plastics Directive transposition mandates fragmentation-rate specifications, forcing converters into multi-year TÜV certification investments. The Rhine-Ruhr industrial corridor concentrates blown-film extrusion capacity serving French and Benelux retail networks.
United States
State-level mandates in California and New York accelerate specification shifts away from conventional polyethylene. EPA landfill-diversion targets and municipal tender programs in Los Angeles and New York City lock in volume commitments for additive-integrated suppliers. The Great Lakes region hosts integrated film extrusion and bag conversion facilities serving Midwest retail distribution.
India
Maharashtra and Gujarat retail sectors drive import demand as BIS certification requirements for biodegradable plastics near finalization. The Bureau of Indian Standards compliance thresholds create procurement preferences for export-oriented manufacturers with pre-certified masterbatch formulations. Mumbai-Pune industrial belt converters test d2w-licensed additive integration for domestic supermarket supply.
Spain
Agricultural mulch film applications displace conventional polyethylene in open-field vegetable production across Murcia and Almería. Soil-plastic accumulation triggers regional regulatory scrutiny under national transpositions of EU agricultural plastics regulations. Valencia packaging cluster extruders develop high-clarity formulations for food-service bag specifications excluding fluorinated processing aids.
Italy
Po Valley vegetable producers adopt oxo-biodegradable mulch to preempt stricter soil contamination enforcement. REACH F-Gas Framework amendments redirect compounder R&D expenditure toward metal-salt oxidation pathways. Bologna-Modena industrial district masterbatch suppliers consolidate intellectual property around encapsulated cobalt stearate catalyst systems.
Oxo Biodegradable Bags Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with additive IP holders capturing recurring licensing revenue while regional extruders compete on conversion economics. The vendor base concentrates around three strategic archetypes: masterbatch technology licensors with patent-protected catalyst systems, integrated film extruders with captive bag conversion capacity, and specialty compounders serving food-contact compliance niches. Dominant competitive moves include geographic licensing expansion and backward integration into additive manufacturing.
Within the technology-licensor tier, Symphony Environmental Technologies PLC and Novolex Holdings, LLC exemplify divergent scale-positioning strategies. Symphony anchors European additive IP monetization through decentralized dosing-system deployment, while Novolex occupies North American production-scale leadership through integrated extrusion-conversion assets. ProAmpac represents the specialty-formulation vector, competing in food-service applications where high-clarity specifications and retail branding requirements command premium positioning.
| Leading Market Players |
|---|
| Novolex Holdings, LLC |
| ProAmpac |
| Symphony Environmental Technologies PLC |
| EarthAware |
| Airpack Systems |
| Natur-Tec |
| BioBag International AS |
| Neoteric Packaging |
| Amcor plc |
| Others |
Value Network & Pricing Analysis
Ethylene spot price movements on the Rotterdam exchange cascade through LDPE and LLDPE resin tiers into three distinct pricing bands for finished oxo-biodegradable bags. Municipal procurement officers in Germany and California lock in contract rates that buffer converters from feedstock volatility, while spot-market buyers absorb margin compression during naphtha cracking cost spikes.
Pricing Analysis
Distributor margin layers separate compounders from end-users by 12-18 percentage points across European supply chains. Three-tier pricing structure across premium, standard, and economy levels reflects TÜV certification status, additive load rates, and volume commitment scale. Pricing pressure stems from ethylene cost pass-through limitations in fixed-price municipal contracts. Industrial trash bag buyers exhibit lowest price sensitivity due to tender-based procurement, while household private-label channels face acute cost competition.
Supply Chain Analysis
Pro-oxidant masterbatch supply rests on German and Italian specialty chemical producers with encapsulated cobalt stearate intellectual property. Cobalt stearate, manganese catalysts, and LLDPE resin constitute the critical input trinity. Single-source vulnerability concentrates in ECHA-compliant additive certification pathways. Distribution runs through converter-direct relationships with supermarket procurement departments and municipal tender boards, bypassing traditional wholesale intermediaries in certified product segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Converters exploit a geographic-arbitrage window between REACH-constrained European additive costs and India's emerging BIS certification pipeline, where compliance investment lags create 18-24 month margin advantages for pre-certified exporters.
For Market Incumbents: To counter cobalt stearate concentration limits under REACH amendments, Symphony Environmental Technologies PLC and comparable licensors must backward integrate into encapsulated catalyst manufacturing and secure multi-jurisdiction certification sequencing ahead of competitors. Captive additive production and parallel BIS-FDA filing pipelines represent the essential defensive levers. For New Entrants and Emerging Players: E-commerce direct-to-consumer channels for dog waste bags and household bin liners offer the most penetrable entry vector, with fragmentation-rate verification documentation requirements limiting marketplace seller pools and creating defensive moats for compliant entrants. Target premium pet retail segments with ISO-compliant certification marketing. For Investors and Strategic Acquirers: Asymmetric upside sits with regional European extruders with in-house TÜV testing laboratories and existing d2w licensing relationships, positioned for consolidation as certification costs rise. The long-term viability window favors additive-IP holders over commodity converters. Watch ECHA cobalt migration limit enforcement as the decisive inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Additive Manufacturing | Captive cobalt stearate production insulates margins from REACH supply constraints. |
| Multi-Jurisdiction Certification Sequencing | Parallel BIS, FDA, and ECHA filings compress 18-24 month commercialization timelines. |
| Subscription Additive Replenishment Licensing | Recurring revenue models decouple masterbatch suppliers from resin volume cyclicality. |
| Agricultural Mulch Film Conversion Partnerships | Spanish and Italian vegetable producer alliances displace conventional polyethylene in open-field applications. |
| In-House ISO Fragmentation Testing Laboratories | German supermarket procurement departments prioritize TÜV-validated claims in vendor scorecards. |
Research Methodology
Multiple input streams — primary interviews with blown-film extrusion plant managers, masterbatch R&D directors, and supermarket procurement officers; secondary validation through ECHA regulatory filings, BIS draft standards, and customs trade data; plus bottom-up capacity surveys and top-down demand modeling — were reconciled to construct market estimates. Primary fieldwork captured operational realities across German, Italian, and Indian production clusters. Secondary sources included EU Single-Use Plastics Directive transposition documents, REACH restriction proposals, and municipal tender databases from California and New York.
Data-stream reconciliation anchored volume projections to extrusion line throughput rates, additive load rate specifications, and certification penetration curves across the modeling period. Segmentation dimensions encompassed bag format, material grade, end-use application, and regional regulatory cluster. CAGRs derived from capacity utilization trends and procurement contract renewal cycles. Industry-specific forecast inputs included ethylene-naphtha cracking spreads and ECHA enforcement probability assessments.
The model assumes a particular technology adoption path; alternative pathways for metal-salt pro-oxidant additives would alter the outlook if enzymatic or bioplastic substitutes achieve cost parity. Forecasts reflect assumptions about REACH cobalt limit enforcement timing and BIS certification finalization. A small set of named triggers — ECHA restriction amendments, Indian standard promulgation, and California landfill-diversion mandate expansion — warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biodegradable Packaging
Biodegradable Water Bottles Market
Biodegradable Packaging
Bioplastic Packaging Market
Biodegradable Packaging
Bioadhesives for Packaging Market
Biodegradable Packaging
Biodegradable Meal Trays Market
Biodegradable Packaging
Europe Biodegradable Film Market
Biodegradable Packaging
Biodegradable Food Packaging Market
Biodegradable Packaging
Global Biodegradable Tableware Market
Biodegradable Packaging
Biodegradable Packing Peanuts Market
Biodegradable Packaging
North America Biodegradable Plastic Market
Biodegradable Packaging
Starch-Based Bioplastics Packaging Market
Biodegradable Packaging
Middle East and Africa Biodegradable Film Market
Biodegradable Packaging
North America Biodegradable Paper and Plastic Packaging Market
Biodegradable Packaging
Biodegradable Lidding Films Market
Biodegradable Packaging
Biopolymer Packaging Market
Biodegradable Packaging
Biodegradable Lids Market
Biodegradable Packaging
Biodegradable Packaging Materials Market