
 Asia Pacific Water Heater Market | 2026-2036
Asia Pacific Water Heater Market Size, Share, and Industry Trends Forecast 2026-2036
Asia Pacific Water Heater Market Analysis
Energy Star-equivalent and five-star efficiency tier upgrades is reorganizing procurement priorities across the Asia Pacific Water Heater Market. Midea Group leverages its captive compressor manufacturing to dominate heat pump cost curves. A.O. Smith Corporation anchors premium residential positioning through stainless-steel tank specialization. Panasonic Holdings Corporation competes on integrated inverter control systems for hybrid installations.
Asia Pacific water heaters are thermodynamic appliances designed to raise potable water temperature through electric resistance, combustion, or ambient heat transfer, typically achieving 50–75 degree Celsius setpoints with insulated storage or on-demand flow activation. Tankless electric units lead in Japanese urban retrofit applications where floor space commands premium pricing. Heat pump technology represents the fastest-expanding segment as coefficient-of-performance ratios exceed three-to-one under temperate ambient conditions. Solar thermal installations retain mature penetration across Australian residential rooftops but face margin compression from photovoltaic diversion.
China's Ministry of Ecology and Environment enforces escalating minimum energy performance standards that disqualify conventional resistance storage below threshold efficiency bands. India's Bureau of Indian Standards mandates star-label disclosure at point-of-sale, redirecting consumer selection toward higher-tier certified products. Australia's WaterMark certification scheme controls market access through plumbing code compliance. Stakeholders must monitor regulatory harmonization momentum between ASEAN member states as mutual recognition agreements reshape cross-border product registration requirements.
Market Dynamics
Heat pump water heater technology is bifurcating procurement priorities across Asia Pacific as coefficient-of-performance thresholds rewrite efficiency economics and compress conventional resistance storage margins.
Growth Catalysts
- China's dual carbon goals:Escalating minimum energy performance standards from the Ministry of Ecology and Environment are disqualifying low-efficiency resistance storage units and redirecting manufacturing capacity toward heat pump platforms.
- Residential construction in Vietnam's northern industrial provinces:Factory worker housing complexes are specifying centralized heat pump systems over individual electric units to meet corporate sustainability procurement mandates.
- India's BIS star-label disclosure:Point-of-sale energy labeling mandates are redirecting consumer selection toward five-star certified products and compressing sales velocity for unlabeled inventory.
Market Restraints
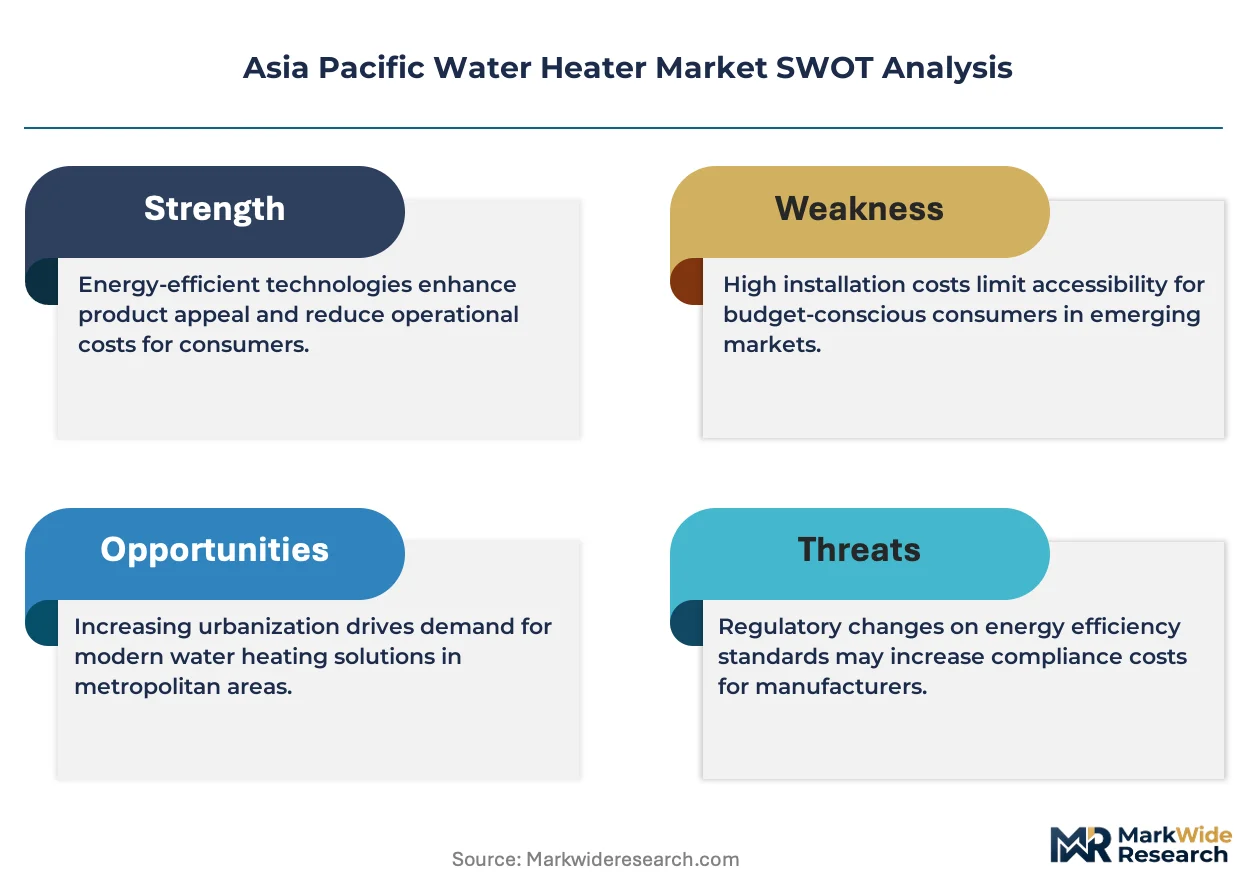
- Refrigerant input cost volatility:Heat pump manufacturing depends on fluorinated gas supplies subject to F-Gas Regulation phase-down schedules in Europe that ripple through Asian component pricing.
- Compressor supply concentration:Rotary and scroll compressor production clusters in eastern China create geographic single-point vulnerability for heat pump assembly lines across the region.
- Electrical infrastructure limitation:India's tier-two cities face distribution transformer capacity constraints that throttle simultaneous heat pump adoption at neighborhood scale.
Strategic Opportunities
- Underpenetrated Indonesian archipelago:Outside Java-Bali corridor, solar-thermal hybrid installations face limited competition and could capture remote island resort and fisheries processing demand.
- Philippines renewable portfolio standards:Utility-scale solar procurement mandates are creating daytime electricity price arbitrage that favors thermal storage water heaters with smart load-shifting controls.
- Smart home convergence:Integration of inverter-driven heat pumps with home energy management systems is opening premium retrofit segments in Japanese urban condominiums.
Industry Challenges
- Refrigerant handling certification timelines:Australia's ARCTICK licensing requirements for hydrocarbon and CO2 refrigerant systems are extending technician deployment schedules and inflating installation backlogs.
- Legacy electrical panel compatibility:Heat pump retrofits in aging Australian and New Zealand housing stock require service upgrade permits that stretch project timelines by eight to fourteen weeks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia Pacific Water Heater Market |
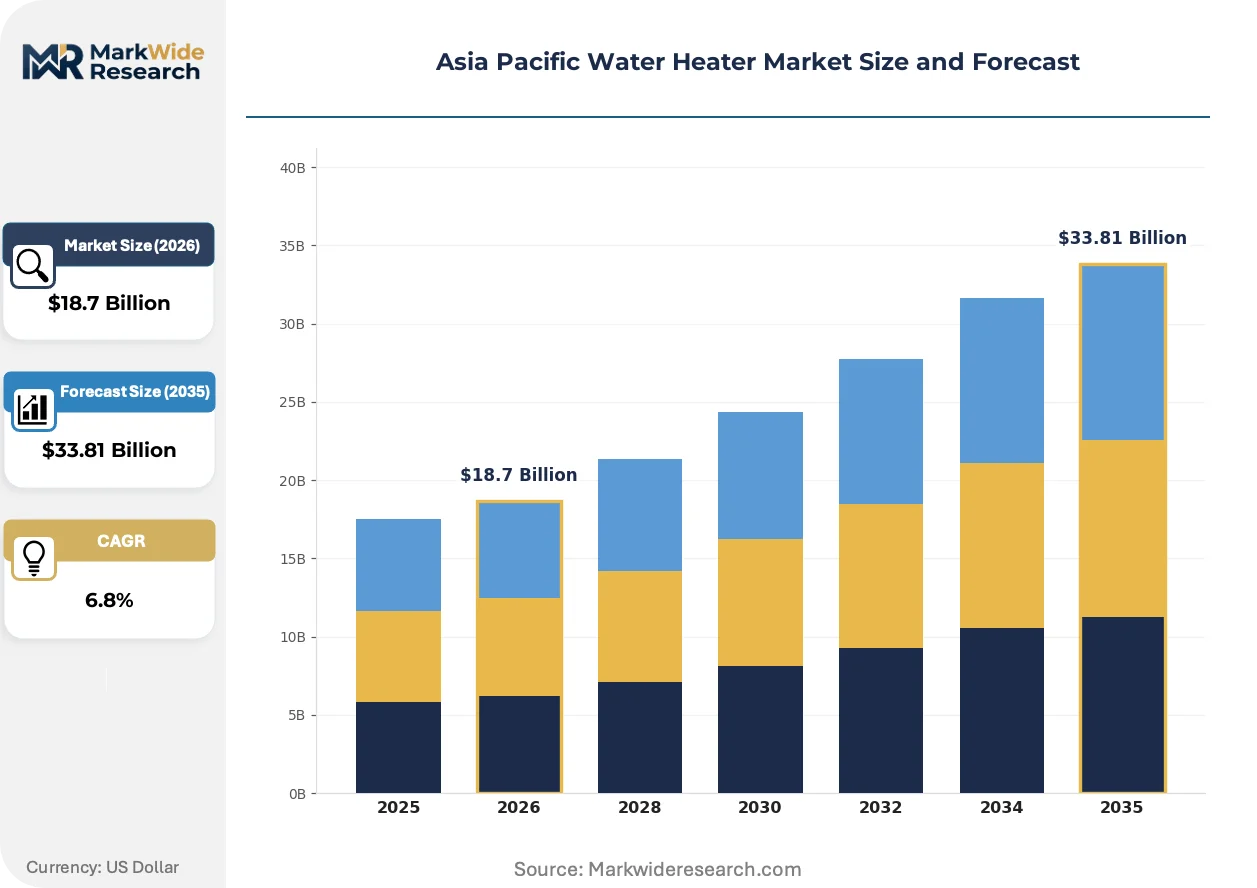
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tankless, Storage, Heat Pump, Solar End User: Residential, Commercial, Industrial, Institutional Technology: Electric, Gas, Hybrid, Biomass Installation Type: Wall-mounted, Stand-alone, Centralized, Portable |
| Companies Covered | Midea Group, Panasonic Holdings Corporation, A.O. Smith Corporation, Mitsubishi Electric Corporation, LG Electronics, Rinnai Corporation, Rheem Manufacturing Company, Daikin Industries Ltd., Haier Group Corporation, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia Pacific Water Heater Market Emerging Trajectories
Product architecture is splitting between premium integrated systems and modular component platforms as efficiency regulations harden and installation labor constraints intensify across metropolitan Southeast Asia.
Heat pump water heater technology is bifurcating the residential replacement market. These systems extract ambient thermal energy through vapor-compression cycles to achieve three-to-one coefficient-of-performance ratios. Japanese urban retrofit contractors are specifying compact outdoor units for condominium balcony installations where floor space commands premium valuations. The technology is bifurcating competitive positioning between integrated appliance specialists and HVAC contractors repurposing air-conditioning supply chains.
China's GB standards for water heater energy efficiency are tightening disqualification thresholds for conventional resistance storage below specified thermal performance bands. Manufacturers must redesign tank insulation specifications and heating element configurations to maintain market access. Heat pump and solar-thermal hybrid categories absorb displaced production capacity as Guangdong and Zhejiang factories retool assembly lines.
Builder procurement contracts are consolidating around packaged mechanical room specifications that bundle water heating with space conditioning and ventilation. Australian volume homebuilders are specifying single-vendor solutions to reduce site coordination friction and compress construction schedules. This specification consolidation is most visible in Melbourne and Sydney greenfield developments where NatHERS thermal performance ratings influence financing approvals.
Asia Pacific Water Heater Market Segmentation
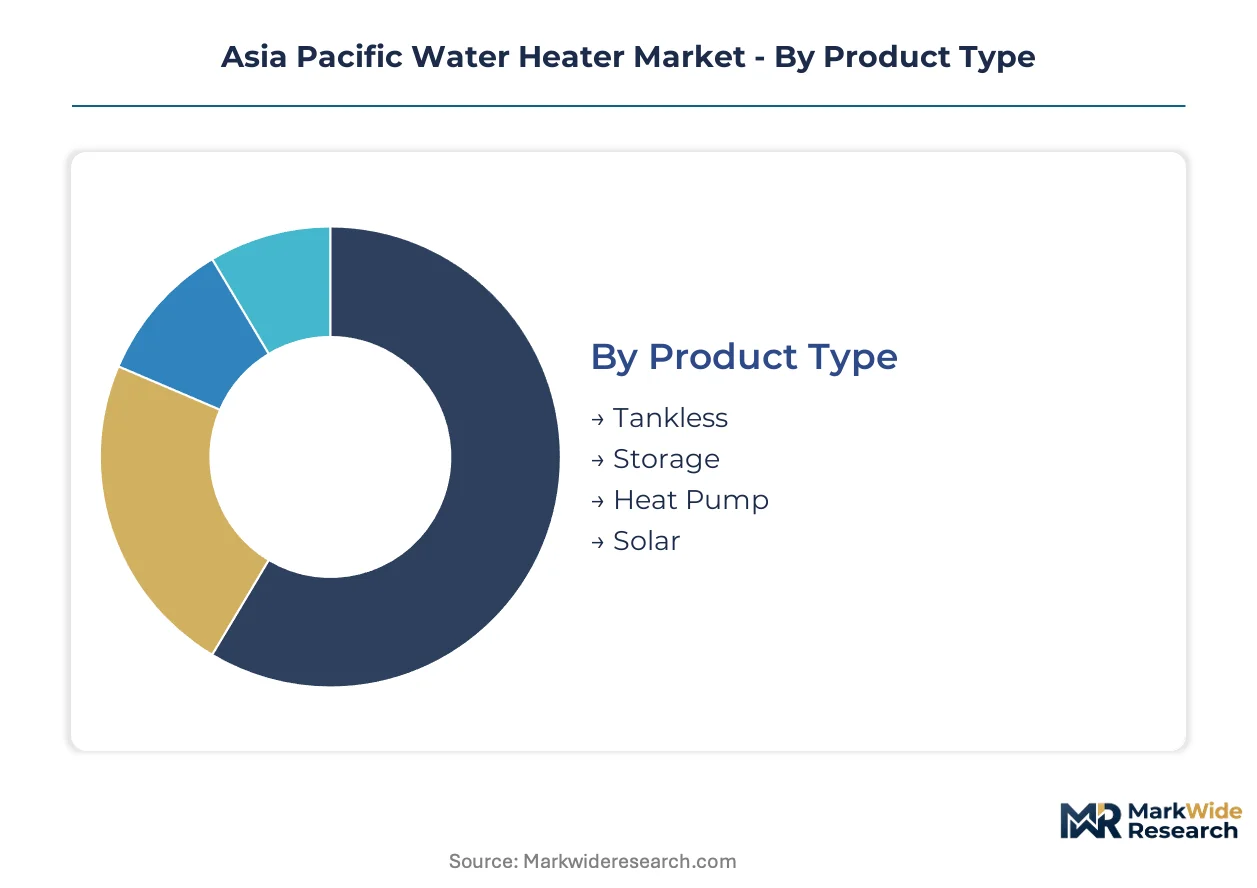
Channel strategy varies sharply across water heater categories in Asia Pacific. Tankless units flow through plumbing contractors in dense Japanese urban corridors, while heat pump systems require HVAC-specialized distribution networks. Procurement consolidation among Australian volume homebuilders is compressing vendor diversity in centralized mechanical room specifications.
Product Type:
Distribution channels diverge by thermal technology. Tankless and storage units move through traditional plumbing wholesale networks, while heat pump platforms require HVAC contractor channels with refrigerant handling certifications. Solar thermal systems often bypass conventional distribution entirely through direct-to-developer engineering contracts.
- Tankless:Compact gas-fired and electric units activate flow-triggered heating elements without storage volume. Japanese condominium retrofit contractors specify these for balcony installations where floor space commands premium valuations in Tokyo and Osaka metropolitan corridors.
- Heat Pump:Vapor-compression systems extract ambient thermal energy to achieve coefficient-of-performance ratios exceeding three-to-one. Vietnam's northern industrial provinces are specifying centralized heat pump systems for factory worker housing complexes to meet corporate sustainability procurement mandates.
- Storage:Insulated tank systems maintain heated water reserves for demand peaks. China's GB standards are tightening disqualification thresholds for conventional resistance storage below specified thermal performance bands.
- Solar:Rooftop thermal collectors circulate transfer fluid through storage tanks. Australian residential installations face margin compression from photovoltaic diversion as homeowners redirect capital to solar electricity generation.
By volume, storage units lead across emerging Asia. By growth pace, heat pump platforms are expanding most quickly as efficiency regulations harden.
End User:
Application context determines specification priority and procurement authority. Residential buyers prioritize first-cost and energy labeling visibility, while commercial and industrial purchasers emphasize lifecycle operating economics and corporate sustainability compliance.
- Residential:Individual household installations span single-family detached homes to high-rise apartment units. India's tier-two cities are redirecting consumer selection toward five-star BIS-certified products as point-of-sale labeling mandates compress sales velocity for unlabeled inventory.
- Commercial:Hospitality, healthcare, and retail facilities require reliable hot water supply for guest and patient services. Australian volume homebuilders are consolidating procurement around packaged mechanical room specifications that bundle water heating with space conditioning.
- Industrial:Manufacturing process heat and worker hygiene applications demand high-capacity centralized systems. Factory complexes in Vietnam's northern provinces specify heat pump platforms over individual electric units.
- Institutional:Schools, government facilities, and military installations operate under public procurement frameworks with extended replacement cycles. Indonesia's archipelago outside the Java-Bali corridor presents limited competition for solar-thermal hybrid specifications.
Residential channels dominate unit shipments. Commercial and industrial segments concentrate value through engineered system specifications.
Technology:
Energy source selection locks in operating cost structure and regulatory exposure for the product lifecycle. Electric resistance faces efficiency standard disqualification in multiple jurisdictions, while gas combustion confronts building electrification policy momentum.
- Electric:Resistance heating elements convert grid electricity to thermal energy with near-unity efficiency but poor source-to-end-use economics. China's Ministry of Ecology and Environment is disqualifying low-efficiency resistance storage units below threshold performance bands.
- Gas:Natural gas or LPG combustion achieves rapid temperature rise and operates independently of electrical infrastructure. Distribution transformer capacity constraints in India's tier-two cities throttle simultaneous heat pump adoption, preserving gas combustion relevance.
- Hybrid:Combined heat pump and resistance backup configurations optimize efficiency across ambient temperature ranges. Japanese urban retrofit applications favor these for condominium installations where inverter control systems enable smart home integration.
- Biomass:Combustion of agricultural residues or processed pellets provides thermal energy in rural off-grid contexts. Remote Indonesian island resorts and fisheries processing facilities present niche demand outside conventional fuel distribution networks.
Electric platforms retain installed base dominance. Hybrid configurations are gaining share fastest as efficiency thresholds rewrite procurement economics.
Installation Type:
Physical mounting configuration determines site preparation requirements, labor skill demands, and replacement pathway complexity. Urban density and construction methodology shape specification prevalence across metropolitan corridors.
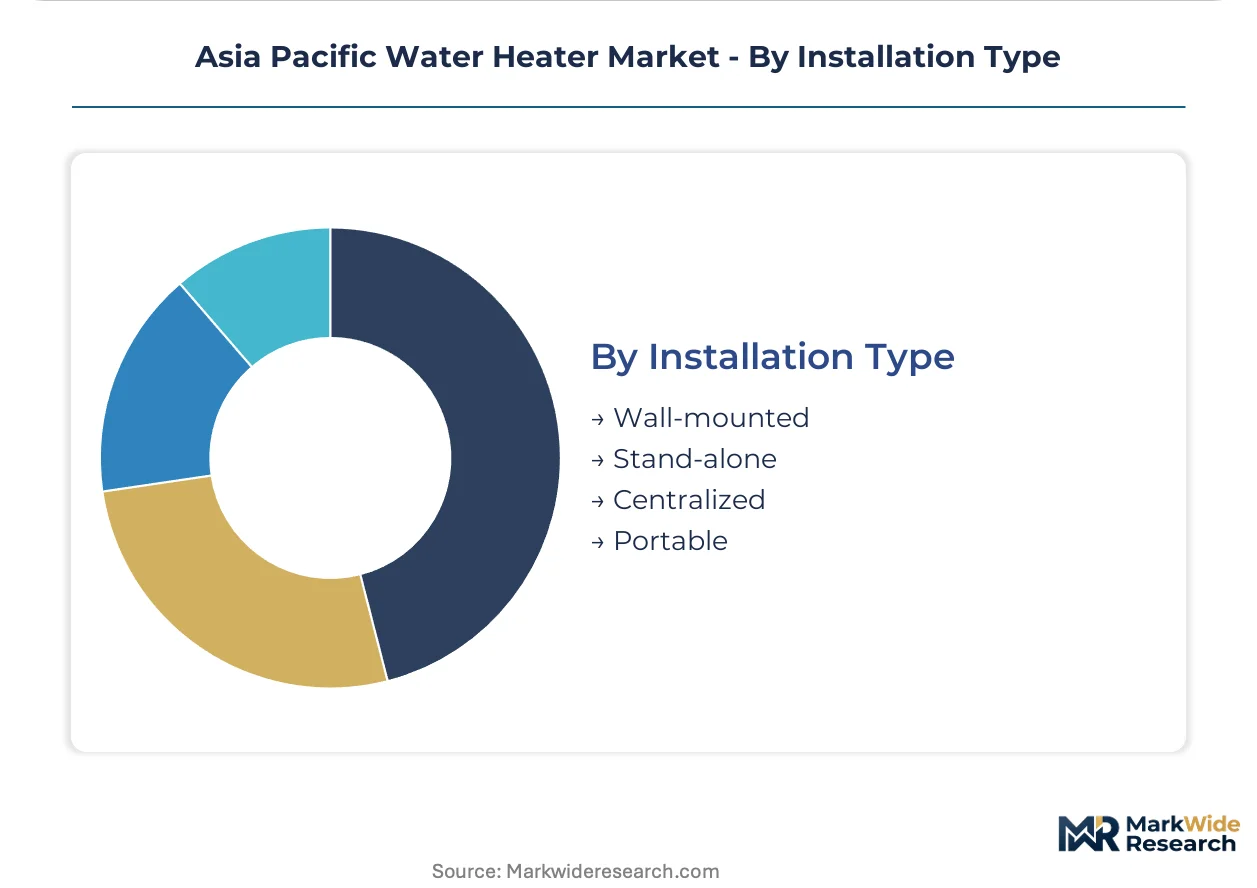
- Wall-mounted:Compact tankless and small storage units attach to structural surfaces, minimizing floor space consumption. Japanese contractors specify these for high-rise residential retrofits where spatial constraints command premium solutions.
- Stand-alone:Cylindrical storage tanks occupy dedicated utility space with gravity-fed or pressurized distribution. Aging Australian and New Zealand housing stock requires electrical service upgrade permits that stretch heat pump retrofit timelines.
- Centralized:Single large-capacity systems serve multiple dwelling units or process loads through insulated distribution loops. Melbourne and Sydney greenfield developments specify these as NatHERS thermal performance ratings influence financing approvals.
- Portable:Mobile units provide temporary or seasonal hot water supply without permanent installation. Remote construction camps and disaster relief operations generate episodic demand across Southeast Asian geographies.
Stand-alone units dominate replacement activity. Centralized specifications are climbing the fastest as builder procurement consolidates around packaged mechanical room solutions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Compressor and heat exchanger fabrication clusters in eastern China supply assembly lines across the region. Guangdong and Zhejiang provinces host captive component manufacturing that feeds OEM networks throughout Southeast Asia. Regulatory divergence between national energy labeling regimes creates compliance complexity for cross-border product registration.
China
Dual carbon targets from the Ministry of Ecology and Environment are accelerating heat pump adoption in residential retrofits. GB standards for water heater energy efficiency now disqualify conventional resistance storage below threshold performance bands. Guangdong factory complexes are retooling assembly lines toward vapor-compression platforms as export demand from European markets strengthens.
India
Tier-two cities are redirecting procurement toward five-star BIS-certified products as point-of-sale labeling mandates compress unlabeled inventory velocity. The Bureau of Indian Standards enforces star-label disclosure requirements that reshape consumer selection patterns. Distribution transformer capacity constraints in Uttar Pradesh and Madhya Pradesh throttle neighborhood-scale heat pump adoption, preserving gas combustion relevance in these corridors.
Japan
Urban condominium retrofits specify compact outdoor heat pump units where floor space commands premium valuations. METI efficiency standards and building electrification policies accelerate replacement cycles for aging resistance storage systems. Tokyo and Osaka metropolitan contractors favor tankless electric and hybrid configurations for high-rise residential installations with inverter control integration.
Vietnam
Northern industrial provinces are specifying centralized heat pump systems for factory worker housing complexes to meet corporate sustainability procurement mandates. Bac Ninh and Hai Phong manufacturing zones drive demand for high-capacity centralized installations over individual electric units. Provincial construction codes are tightening efficiency requirements for new industrial residential developments.
Australia
Volume homebuilders in Melbourne and Sydney greenfield developments consolidate procurement around packaged mechanical room specifications. NatHERS thermal performance ratings influence financing approvals and drive specification toward integrated water heating and space conditioning solutions. Legacy electrical panel compatibility issues in aging housing stock extend heat pump retrofit timelines through service upgrade permit requirements.
Asia Pacific Water Heater Market Vendor Landscape
Concentration sits with diversified appliance conglomerates that leverage captive compressor manufacturing and integrated distribution networks. The vendor base spans three tiers: scale-driven OEMs with full vertical control over heat pump components, specialized tank fabricators competing on material differentiation, and HVAC contractors repurposing air-conditioning supply chains for water heating installation. Strategic moves center on capacity expansion in eastern Chinese manufacturing zones and technology licensing agreements that transfer inverter control intellectual property across regional joint ventures.
Among Asia-domiciled appliance manufacturers, Midea Group, Haier Group Corporation, and Panasonic Holdings Corporation occupy positions that exemplify scale-driven and technology-integrated competitive archetypes. Midea leverages captive compressor production to anchor cost positioning in heat pump segments. Haier represents the diversified conglomerate model with cross-category appliance manufacturing integration. Panasonic exemplifies the technology-licensing pathway through inverter control system specialization. A.O. Smith Corporation and Rheem Manufacturing Company represent North American-headquartered specialists with regional manufacturing presence. Mitsubishi Electric Corporation, LG Electronics, and Daikin Industries Ltd. anchor the HVAC-to-water-heating extension archetype. Rinnai Corporation exemplifies the gas-appliance specialist pivoting toward hybrid configurations.
| Leading Market Players |
|---|
| Midea Group |
| Panasonic Holdings Corporation |
| A.O. Smith Corporation |
| Mitsubishi Electric Corporation |
| LG Electronics |
| Rinnai Corporation |
| Rheem Manufacturing Company |
| Daikin Industries Ltd. |
| Haier Group Corporation |
| Others |
Supply Flow & Price Mechanics
Guangdong and Zhejiang factory capacity utilization rates above eighty percent compress marginal production costs for heat pump assemblies while elevating price floors for smaller OEMs lacking captive compressor supply. Scale concentration in eastern China's manufacturing clusters translates directly into procurement leverage for volume buyers and margin pressure for regional assemblers sourcing components at spot rates.
Pricing Analysis
China's GB standards dictate the pricing tier structure across the Asia Pacific Water Heater Market. Three-tier pricing separates five-star certified heat pumps from three-star storage units from unlabeled resistance systems. Price differentiation rests on BIS certification grade and volume scale, with Australian volume homebuilders commanding steepest discounts through centralized mechanical room specifications. Cost compression in mid-tier storage is intensifying because Guangdong factories are disqualifying conventional resistance lines below threshold efficiency bands. Residential retrofit buyers in India's tier-two cities exhibit highest price sensitivity, while Japanese condominium developers prioritize floor-space efficiency over first cost.
Supply Chain Analysis
Container availability fluctuations on the Shanghai-Singapore and Shenzhen-Sydney lanes periodically extend inbound component lead times for Australian and Southeast Asian distributors. Compressor and heat exchanger fabrication concentrates in China, South Korea, and Japan, with rotary scroll production anchored in eastern Chinese industrial zones. Raw material dependencies span copper tubing, fluorinated refrigerants, and cold-rolled steel. Single-source vulnerability sits with Guangdong-based compressor clusters that feed heat pump assembly lines across Vietnam and Indonesia. Distribution runs through HVAC contractor networks for heat pump platforms and traditional plumbing wholesale for tankless and storage categories.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory fragmentation across national energy labeling regimes creates white-space opportunities for specialists capable of navigating multi-jurisdiction certification. Efficiency threshold escalation in China and India simultaneously compresses incumbent product lines and opens premium tiers for compliant entrants.
For Market Incumbents: Compound captive compressor advantages through backward integration into refrigerant handling and inverter control module production. Defend margin position against HVAC contractor channel encroachment by securing exclusive distribution agreements with Australian volume homebuilders and Vietnam's northern industrial province developers. Prioritize certification investment in Australia's WaterMark and India's BIS star-label tiers to maintain point-of-sale visibility as disclosure mandates harden. For New Entrants and Emerging Players: Differentiate on solar-thermal hybrid configurations for Indonesia's underpenetrated archipelago outside the Java-Bali corridor. Target remote island resort and fisheries processing applications where conventional fuel distribution networks fail. Penetrate Philippines renewable portfolio standard arbitrage opportunities through thermal storage water heaters with smart load-shifting controls engineered for utility-scale solar daytime price patterns. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors HVAC-to-water-heating extension specialists with established inverter control intellectual property and refrigerant handling certification infrastructure. Long-term viability hinges on heat pump platform transition completion before resistance storage disqualification thresholds tighten further. Acquisition target archetype: regional HVAC contractors with latent water heating installation capacity and METI or GB standards compliance track record. Signal to watch: ASEAN mutual recognition agreement momentum reshaping cross-border product registration requirements.| Strategic Initiative | Industry Significance |
|---|---|
| Heat Pump Platform Transition | Guangdong factory retooling toward vapor-compression systems captures displaced resistance storage capacity. |
| Refrigerant Handling Certification Investment | Australia's ARCTICK licensing requirements extend technician deployment schedules and inflate installation backlogs. |
| Centralized Mechanical Room Specification | Melbourne and Sydney volume homebuilders consolidate procurement around single-vendor bundled solutions. |
| Inverter Control System Integration | Japanese urban retrofit contractors specify compact outdoor units with smart home convergence capabilities. |
| Backward Integration into Compressor Manufacturing | Midea Group's captive production anchors cost positioning in heat pump coefficient-of-performance competition. |
Methodological Framework
A spread of perspectives from heat pump manufacturing executives, HVAC contractor network managers, Australian volume homebuilder procurement directors, and India's BIS certification auditors converged on the working assumptions. Primary interview insights combined with secondary validation from China's GB standards documentation, Australia's NatHERS thermal performance rating databases, Vietnam's provincial construction code filings, and ASEAN trade flow customs records. Bottom-up unit shipment modeling triangulated against top-down construction spend allocation across residential, commercial, and industrial end-use segments.
Product type, end-user application, energy source technology, and installation configuration dimensions structured the analytical framework across the projection horizon. CAGRs derived from segment-level growth rate reconciliation with macro construction indicators and regulatory phase-in schedules. Industry-specific forecast inputs incorporated India's distribution transformer capacity constraint maps and Japan's METI efficiency standard replacement cycle assumptions.
Material uncertainties — refrigerant input cost volatility from F-Gas Regulation phase-down schedules, electrical infrastructure upgrade timelines in India's tier-two cities, and ASEAN regulatory harmonization momentum — sit outside the modeled envelope. Forecasts reflect documented assumptions subject to revision from these structural drivers. Recalibration cycles align with material shifts in national energy performance standard enforcement and compressor supply concentration events.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Appliances
Microwave Market
Appliances
United Kingdom Compact Dishwasher Market
Appliances
Asia Pacific Household Side by Side Refrigerator Market
Appliances
Refrigerator Repair Service Market
Appliances
China Induction Hobs Market
Appliances
Asia-Pacific Tumble Dryers Market
Appliances
Hairdryer Market
Appliances
Household Side by Side Refrigerator Market
Appliances
Refrigerator Door Seal Market
Appliances
Smart Connected Washing Machine Market
Appliances
Global Massage Chairs Market
Appliances
Japan Massage Equipment Market
Appliances
United States Commercial Laundry Appliances Market
Appliances
Water Dispenser Market
Appliances
Portable Fridges Market
Appliances
Domestic Food Preparation Appliances Market