
 Refrigerator Repair Service Market | 2026-2036
Refrigerator Repair Service Market Size, Share, and Industry Trends Forecast 2026-2036
Refrigerator Repair Service Market Insights
North American appliance service networks are repositioning around predictive maintenance platforms. Sears Home Services leverages its legacy technician footprint to sustain residential coverage density. Mr. Appliance competes through franchise standardization that controls service quality across dispersed markets. LG Direct Service differentiates by anchoring proprietary parts distribution within its captive supply chain.
Refrigerator repair service encompasses the diagnosis, component replacement, refrigerant handling, and system restoration of vapor-compression cooling appliances operating between 1°C and 5°C in fresh compartments and -18°C in freezer sections, primarily preserving perishable inventory and extending capital equipment life. Emergency repair commands premium dispatch fees while maintenance service generates recurring revenue streams with higher technician utilization rates. Compressor repair and refrigerant recovery represent the most technically complex technology segments where specialized tooling creates margin concentration.
EPA Section 608 governs refrigerant handling certification in the United States, while the EU F-Gas Regulation phases down hydrofluorocarbon use in European service operations, and India's BIS standards mandate energy efficiency disclosures that affect repair-versus-replace economics. These frameworks elevate technician training costs but simultaneously restrict unlicensed competition. Stakeholders must monitor refrigerant chemistry transitions and regional technician pipeline development to calibrate capacity investments against compliance thresholds.
Market Dynamics
The refrigerator repair service market is undergoing structural compression as predictive maintenance platforms displace reactive dispatch models, forcing service networks to reconfigure technician deployment around uptime guarantees rather than per-incident billing.
Growth Catalysts
- EPA Section 608 Certification Expansion:The EPA's refrigerant management rules are tightening technician qualification requirements across the United States, restricting unlicensed competition and elevating authorized service provider margins.
- Commercial Refrigeration Uptime Contracts:Restaurant chains are expanding long-term service agreements for commercial refrigeration systems, converting transactional repair revenue into recurring maintenance streams with higher technician utilization.
- Urban India Appliance Density:Rising refrigerator ownership in Indian metropolitan areas is outpacing authorized service network expansion, creating concentrated demand pockets for trained technician deployment.
Market Restraints
- Refrigerant Chemistry Transition Costs:The phasedown of hydrofluorocarbons under the EU F-Gas Regulation and similar frameworks is forcing service operations to retool recovery equipment and retrain technicians on alternative chemistries.
- Specialized Tooling Capital Requirements:Compressor repair and refrigerant recovery operations require proprietary diagnostic equipment and recovery systems that concentrate margin capture among capitalized operators.
- Authorized Network Supply Constraints:Proprietary parts distribution through captive supply chains limits independent service provider access to critical components, compressing competitive alternatives.
Strategic Opportunities
- India's BIS Standards Compliance Services:India's Bureau of Indian Standards mandates energy efficiency disclosures that affect repair-versus-replace economics, creating advisory service revenue for technicians who can model lifecycle cost comparisons.
- Predictive Sensor Integration:IoT-enabled temperature and vibration monitoring is converging with field service management platforms to enable condition-based dispatch before system failure.
- Refrigerant Recovery Value Recovery:Regulatory mandates for refrigerant reclamation are creating secondary revenue streams from recovered material processing, particularly for operators with centralized reclamation infrastructure.
Industry Challenges
- EPA Section 608 Certification Pipeline:The technician certification timeline and examination requirements are constraining workforce expansion rates, particularly for universal certification covering all appliance categories and refrigerant types.
- Legacy System Integration Complexity:Older vapor-compression systems with obsolete refrigerants require specialized handling protocols that fragment technician training curricula and complicate service standardization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Refrigerator Repair Service Market |
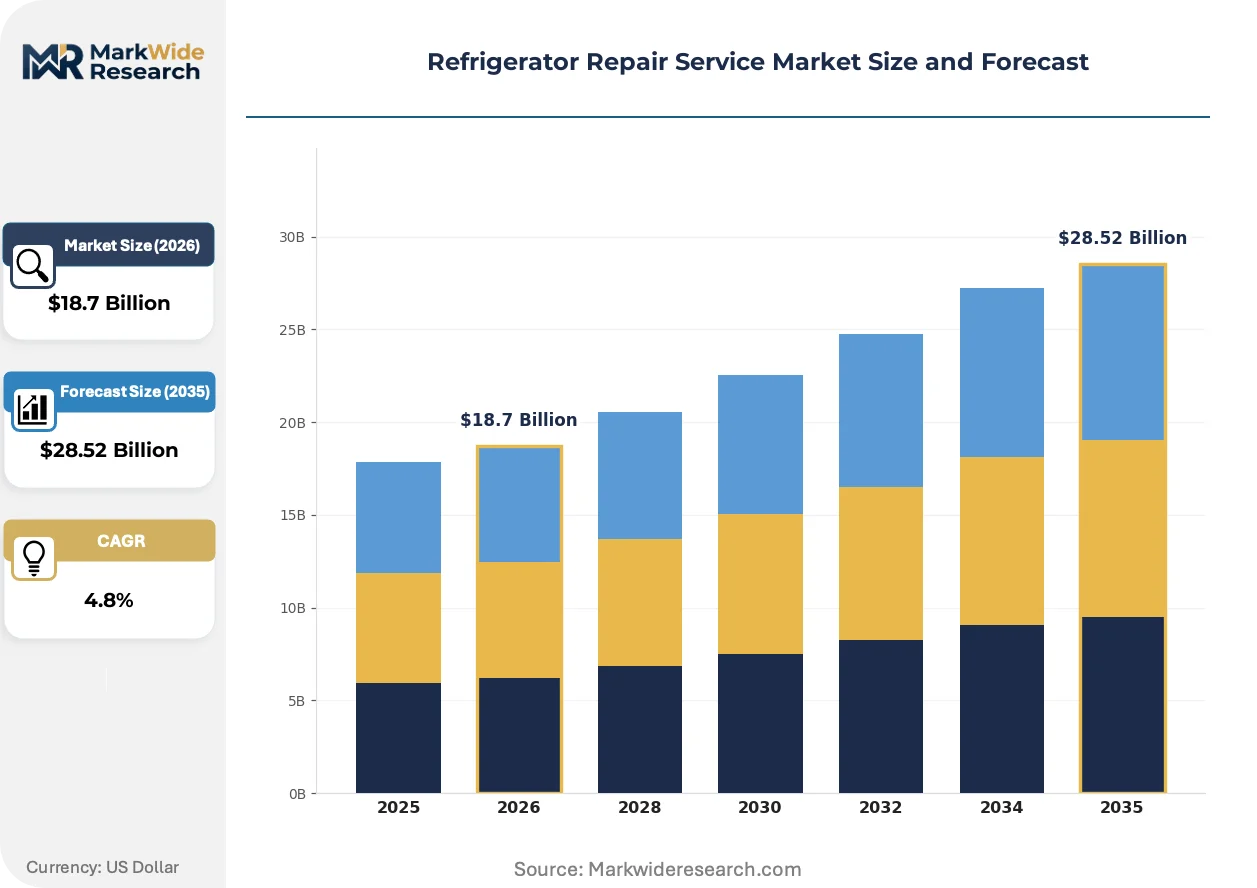
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $28.52 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Emergency Repair, Maintenance Service, Installation, Diagnostic Service End User: Residential Customers, Commercial Businesses, Restaurants, Supermarkets Technology: Refrigerant Recovery, Ice Maker Repair, Thermostat Replacement, Compressor Repair Product Type: Top Freezer Refrigerators, Side-by-Side Refrigerators, French Door Refrigerators, Compact Refrigerators |
| Companies Covered | Sears Home Services, Mr. Appliance, Puls, American Home Shield ProConnect, GE Appliances Factory Service, LG Direct Service, Samsung Repair Services, Whirlpool Service, Bosch Home Appliances Service, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Refrigerator Repair Service Market Trends and Innovations
Predictive maintenance platforms are actively restructuring how refrigerator service networks organize labor, shifting from incident-response dispatch to condition-monitoring subscription models that alter technician scheduling and revenue recognition.
IoT-enabled remote diagnostics is overtaking traditional on-site troubleshooting as the primary failure identification method. Commercial kitchen operators and facility managers are adopting sensor networks that transmit temperature anomalies and compressor vibration signatures to centralized monitoring centers. This technology is compressing emergency dispatch volumes while expanding scheduled maintenance contract penetration.
The EU F-Gas Regulation is accelerating hydrofluorocarbon phaseout timelines across European service operations. Technicians must now manage refrigerant reclamation quotas and quota trading mechanisms that complicate inventory planning. Cold chain logistics operators in Germany and France are responding by consolidating service contracts with reclamation-capable providers who can document regulatory compliance.
Service contract unbundling is fragmenting traditional warranty-extension offerings into component-specific coverage tiers. Restaurant operators are selecting compressor-only or sealed-system-only protection plans rather than comprehensive coverage, forcing service providers to price risk at subsystem granularity. This pattern is most visible in North American commercial foodservice procurement where operators prioritize capital protection over convenience features.
Refrigerator Repair Service Market Segmentation
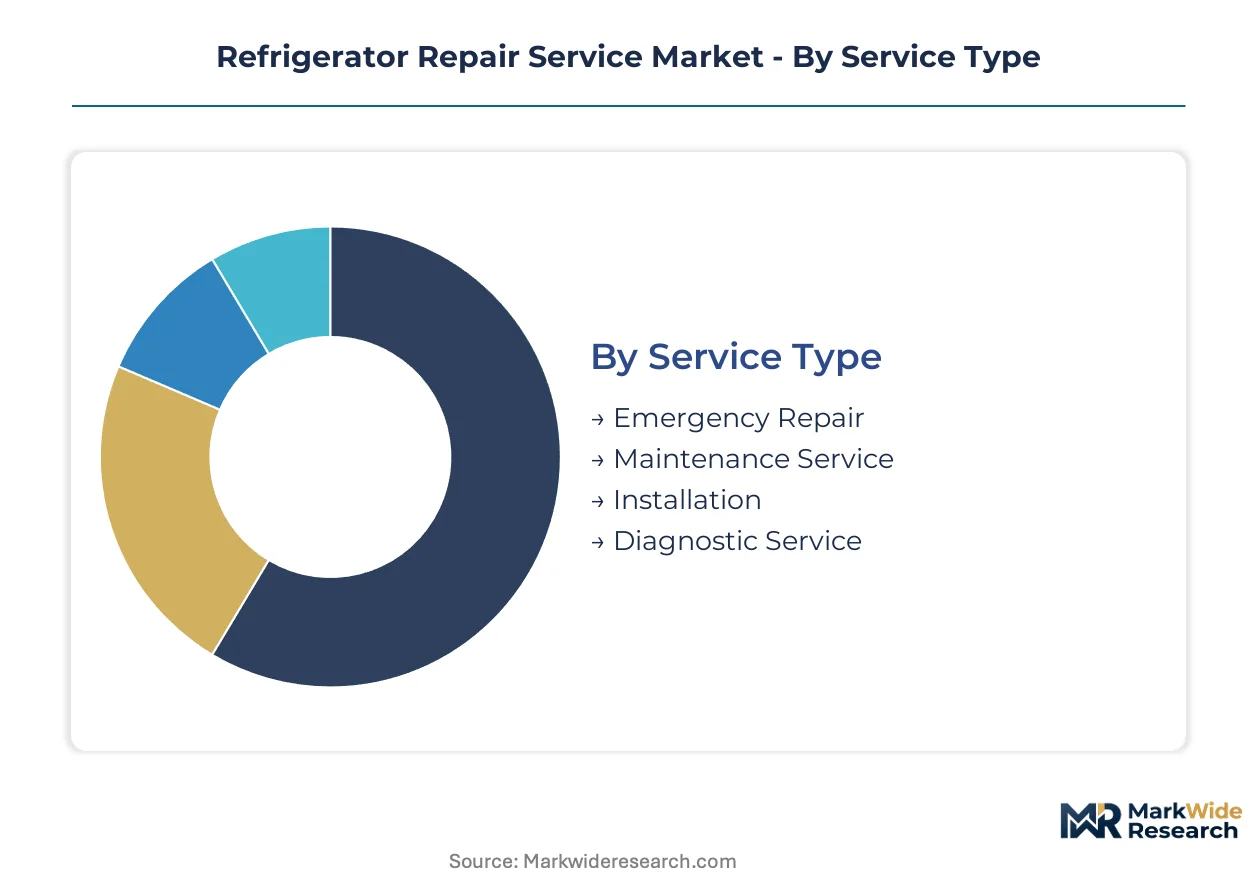
Refrigerator repair service segmentation reveals how service networks allocate technician capacity across incident urgency, customer sophistication, and equipment complexity. Distinct margin profiles emerge between reactive emergency dispatch and contracted preventive maintenance.
Service Type:
Customization intensity varies sharply across this spectrum, from standardized maintenance protocols to highly variable emergency interventions.
- Emergency Repair:Immediate response to system failures requiring rapid technician deployment and after-hours premium pricing. Demand concentrates in urban commercial corridors where restaurant refrigeration downtime triggers inventory loss, with EPA Section 608 certified technicians commanding dispatch priority.
- Maintenance Service:Scheduled preventive work including coil cleaning, seal inspection, and refrigerant level monitoring. Restaurant chains in North America are expanding these contracts to convert transactional revenue into recurring streams with higher technician utilization rates.
- Installation:New equipment commissioning and existing unit replacement requiring electrical and plumbing coordination.
- Diagnostic Service:Initial troubleshooting to isolate component failures before repair authorization.
Leading the category by volume: Maintenance Service. Growing fastest: Emergency Repair.
End User:
Customer scale determines service contract structure, from individual residential billing to enterprise-level uptime guarantees.
- Residential Customers:Individual homeowners seeking sporadic repair services with limited price elasticity for essential refrigeration function. Urban India shows concentrated demand where rising appliance ownership outpaces authorized service network expansion.
- Commercial Businesses:Small and mid-sized enterprises requiring reliable cold storage for inventory preservation.
- Restaurants:Foodservice operators with zero-tolerance downtime policies driving premium service tier adoption. These customers prioritize compressor-only protection plans over comprehensive coverage, forcing subsystem-specific risk pricing.
- Supermarkets:Large-format retail with centralized facility management and consolidated service procurement.
Highest contract penetration: Restaurants. Steepest expansion trajectory: Residential Customers in emerging urban clusters.
Technology:
Technical complexity stratifies technician specialization and capital equipment requirements.
- Refrigerant Recovery:Mandated reclamation processes under EPA Section 608 and EU F-Gas Regulation requiring specialized recovery systems. Cold chain logistics operators in Germany and France consolidate contracts with reclamation-capable providers who document regulatory compliance.
- Compressor Repair:The most technically complex segment involving sealed system work and proprietary diagnostic tooling. Specialized equipment creates margin concentration among capitalized operators with centralized infrastructure.
- Ice Maker Repair:Component-specific service addressing water line, valve, and mold assembly failures.
- Thermostat Replacement:Standardized control system service with lower barrier to technician entry.
Widest margin dispersion: Compressor Repair. Gaining share fastest: Refrigerant Recovery.
Product Type:
Equipment architecture dictates parts availability and technician training specialization.
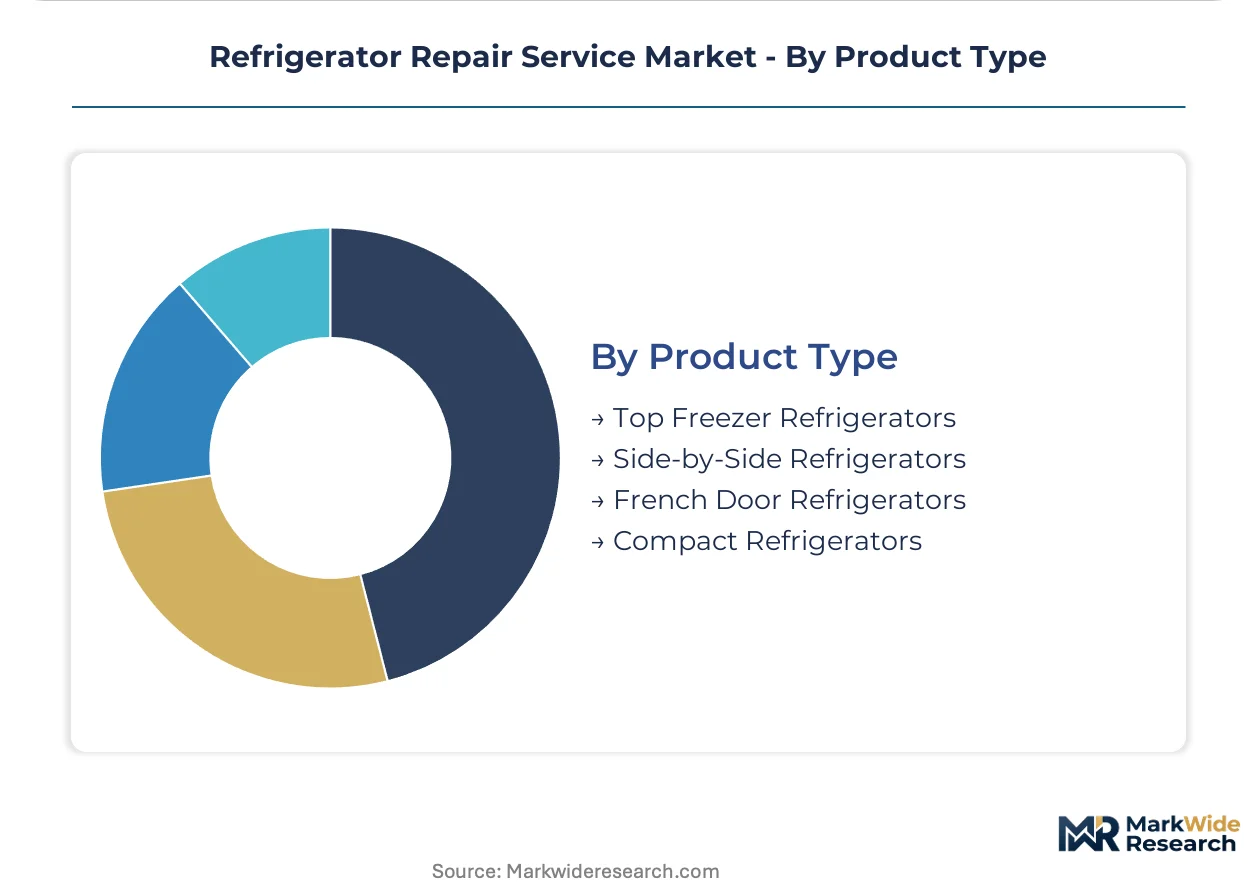
- French Door Refrigerators:Complex multi-zone cooling systems with electronic controls and through-door ice service. These units command higher repair premiums due to specialized component requirements and extended diagnostic protocols.
- Side-by-Side Refrigerators:Dual-compartment vertical configuration with integrated water dispensing systems common in North American residential installations.
- Top Freezer Refrigerators:Conventional single-compressor design with highest service volume and deepest parts availability.
- Compact Refrigerators:Small-capacity units with sealed systems limiting field repair options toward replacement economics.
Deepest installed base: Top Freezer Refrigerators. Climbing the fastest: French Door Refrigerators.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Technician certification requirements and refrigerant handling protocols anchor geographic differentiation across major service markets, with regulatory stringency determining competitive barriers and margin structures.
United States
Restaurant chains across Texas and California are consolidating commercial refrigeration contracts around uptime guarantees rather than per-incident billing. EPA Section 608 mandates universal technician certification for all appliance categories and refrigerant types, compressing unlicensed competition. The Dallas-Fort Worth corridor shows concentrated demand for emergency compressor repair as foodservice density outpaces authorized technician supply.
Germany
Cold chain logistics operators in the Rhine-Ruhr and Bavaria regions are prioritizing reclamation-capable service providers who document EU F-Gas Regulation compliance. The phasedown of hydrofluorocarbons forces recovery equipment retooling and alternative chemistry retraining. Hamburg's port-centered food distribution cluster is consolidating contracts with providers holding centralized reclamation infrastructure.
India
Rising refrigerator ownership in Mumbai and Delhi-NCR metropolitan areas exceeds authorized service network expansion, creating technician deployment bottlenecks. BIS standards mandate energy efficiency disclosures that reshape repair-versus-replace economics for consumers. Bangalore's appliance retail concentration is spawning third-party service aggregators bridging the gap between demand density and brand-authorized capacity.
Japan
Commercial kitchen operators in the Tokyo-Osaka corridor are adopting IoT-enabled predictive maintenance platforms that compress emergency dispatch volumes. METI efficiency standards elevate technician training requirements for next-generation refrigerant handling. Nagoya's manufacturing belt is generating specialized demand for legacy system integration as older vapor-compression units require obsolete refrigerant protocols.
United Kingdom
Facility managers in Greater London and the Midlands are unbundling service contracts into component-specific coverage tiers rather than comprehensive protection plans. Post-Brexit regulatory alignment with EU F-Gas frameworks maintains refrigerant phaseout timelines for cross-border cold chain operators. Manchester's foodservice hub is driving premium pricing for sealed-system specialists with proprietary diagnostic tooling.
Refrigerator Repair Service Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue predictive maintenance platform integration and IoT-enabled remote diagnostics. The market exhibits moderate concentration with legacy appliance manufacturers maintaining captive service networks alongside independent franchise operators and technology-enabled aggregators. Three archetypes dominate: manufacturer-direct service arms controlling proprietary parts distribution, franchise-standardized regional networks, and platform-based aggregators matching demand to certified technicians. Competitive moves center on predictive sensor integration partnerships and refrigerant reclamation infrastructure consolidation.
Among manufacturer-direct operators, Sears Home Services and LG Direct Service exemplify divergent strategic positions—one leveraging legacy technician footprint density, the other anchoring proprietary supply chain control. Mr. Appliance occupies the franchise-standardization archetype, representing quality control mechanisms across dispersed geographic markets. These three entities collectively illustrate how market participants are repositioning around technician certification pipelines and regulatory compliance capabilities rather than pure scale expansion.
| Leading Market Players |
|---|
| Sears Home Services |
| Mr. Appliance |
| Puls |
| American Home Shield ProConnect |
| GE Appliances Factory Service |
| LG Direct Service |
| Samsung Repair Services |
| Whirlpool Service |
| Bosch Home Appliances Service |
| Others |
Pricing and Supply Chain Analysis
Restaurant chains consolidating commercial refrigeration contracts around uptime guarantees command subscription-based pricing that displaces per-incident billing. EPA Section 608 certification scarcity elevates authorized technician premiums while proprietary parts distribution through captive supply chains restricts independent provider access.
Pricing Analysis
Warranty unbundling into component-specific coverage tiers fragments traditional comprehensive protection plans. Three-tier pricing structure across premium, standard, and economy levels separates compressor-only protection from sealed-system coverage and full-service plans. Certification grade and geographic delivery cost drive price differentiation. Cost compression in standard tiers intensifies because independent providers face proprietary parts access restrictions. Residential customers in emerging urban clusters exhibit highest price sensitivity, while restaurant operators with zero-tolerance downtime policies show least.
Supply Chain Analysis
Specialized refrigerant recovery equipment supply rests on German and Japanese precision engineering producers. Proprietary compressor components draw from South Korean and Chinese manufacturing hubs. Recovery systems, diagnostic tooling, and replacement compressors constitute critical input dependencies. Single-source vulnerability concentrates in EPA-certified refrigerant reclamation infrastructure. Distribution runs through manufacturer-direct service arms controlling captive parts networks alongside franchise-standardized regional operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Predictive maintenance platforms are displacing reactive dispatch models as IoT-enabled remote diagnostics overtakes traditional on-site troubleshooting. This technology transition compresses emergency dispatch volumes while expanding scheduled maintenance contract penetration.
For Market Incumbents: Acquire predictive sensor integration capabilities to anchor subscription revenue streams. Consolidate refrigerant reclamation infrastructure in metropolitan corridors where EPA Section 608 compliance requirements restrict unlicensed competition. Cold chain logistics operators in Germany and France already prioritize reclamation-capable providers who document regulatory compliance.
For New Entrants and Emerging Players: Urban India residential customers represent underserved demand where rising appliance ownership outpaces authorized service network expansion. Third-party service aggregators bridging brand-authorized capacity gaps in Bangalore's appliance retail concentration offer a proven go-to-market template. IoT-enabled temperature monitoring partnerships with facility managers provide differentiation against legacy dispatch models.
For Investors and Strategic Acquirers: The window for entry favors platform-based aggregators with technician certification pipeline access. Long-term viability hinges on regulatory compliance capabilities rather than pure scale expansion. Consolidation targets with centralized reclamation infrastructure and proprietary diagnostic tooling warrant priority attention. Watch EPA Section 608 certification expansion timelines as workforce constraint inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| Predictive Maintenance Platform Integration | IoT-enabled remote diagnostics compress emergency dispatch volumes for restaurant chains. |
| Refrigerant Reclamation Infrastructure Consolidation | Centralized recovery systems capture EU F-Gas Regulation compliance premiums in Germany. |
| Technician Certification Pipeline Investment | EPA Section 608 universal certification restricts unlicensed competition across United States. |
| Proprietary Parts Distribution Control | Captive supply chains limit independent provider access to critical compressor components. |
| Third-Party Service Aggregation | Platform models bridge demand density gaps in Mumbai and Delhi-NCR metropolitan corridors. |
Research Methodology
Independent corroboration across primary technician interviews, service network operator discussions, and regulatory compliance officer consultations underwrites the qualitative findings. Field service management platform developers, restaurant facility managers, and cold chain logistics operators provided operational perspective. EPA Section 608 certification databases, EU F-Gas Regulation quota tracking systems, and India's BIS energy efficiency disclosure records supplied secondary validation. Bottom-up technician deployment modeling and top-down service revenue aggregation triangulate market sizing.
Comparable historical reference periods spanning refrigerant chemistry transitions and certification regime changes anchored the forecast window. Segmentation dimensions modeled include service type, end user scale, technology complexity, and product architecture across the projection horizon. CAGRs derive from technician utilization rate trajectories, contract penetration curves, and regulatory compliance cost absorption patterns. Refrigerant phaseout timelines and predictive sensor adoption rates constitute industry-specific forecast inputs.
Revisions become necessary when refrigerant chemistry transitions accelerate beyond modeled timelines or technician certification pipeline constraints tighten unexpectedly. Forecasts reflect assumptions about regulatory enforcement consistency and IoT platform interoperability standards. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Appliances
Global Electric Water Heaters Market
Appliances
South Africa Laundry Appliances Market
Appliances
Turkey Washing Machine Market
Appliances
France Household Side by Side Refrigerator Market
Appliances
Microwave Market
Appliances
Electric Iron Market
Appliances
GCC Dishwashers Market
Appliances
North America Compact Dishwasher Market
Appliances
Europe Household Electric Grills Market
Appliances
Mobile Refrigerators Market
Appliances
Europe Garment Steamers Market
Appliances
Smart Massage Appliances Market
Appliances
UAE Gas Hobs Market
Appliances
China Washing Machine Market
Appliances
Electric Yogurt Maker Market
Appliances
French Door Refrigerator Market