
 Asia Pacific Household Side by Side Refrigerator Market | 2026-2036
Asia Pacific Household Side by Side Refrigerator Market Size, Share, and Industry Trends Forecast 2026-2036
Asia Pacific Household Side by Side Refrigerator Market Insights
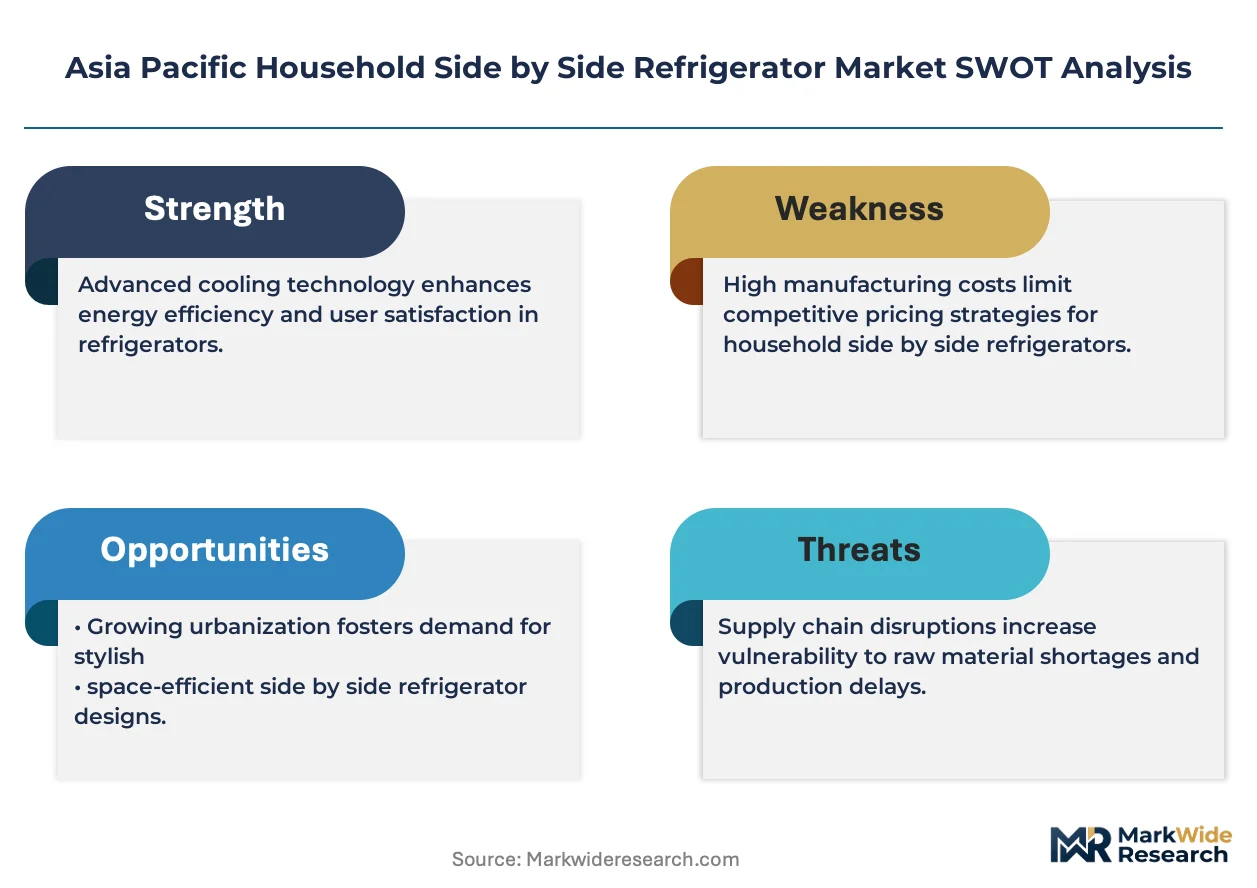
Capital-intensity divergence between Korean and Chinese manufacturers is rotating competitive dynamics across the region. Samsung Electronics leverages its semiconductor supply chain to sustain inverter module production in-house. Haier anchors its position through backward integration into compressor manufacturing and captive distribution networks in China and India.
A household side by side refrigerator consists of two vertical compartments with independent temperature zones, typically employing dual evaporator systems and inverter-driven compressors to maintain precise thermal control for fresh and frozen goods. The appliance serves residential kitchens requiring high-volume, organized food storage with minimal temperature fluctuation. Smart refrigerator variants command premium positioning as connectivity features and AI-based inventory management reshape buyer expectations. Energy-efficient models aligned with inverter technology attract regulatory preference and utility rebate eligibility across multiple jurisdictions. Standard configurations still occupy volume leadership in price-sensitive Southeast Asian markets where direct cool systems retain residual share.
China's SAMR enforces GB standards for energy consumption and refrigerant specifications, while India's BIS mandates compulsory star-labeling for household appliances. Japan's METI Top Runner program accelerates efficiency benchmarks, forcing regional exporters to harmonize product platforms across compliance regimes. Stakeholders must monitor evolving refrigerant phase-down schedules and carbon-border adjustment mechanisms as these frameworks reshape sourcing decisions and factory location strategy.
Market Dynamics
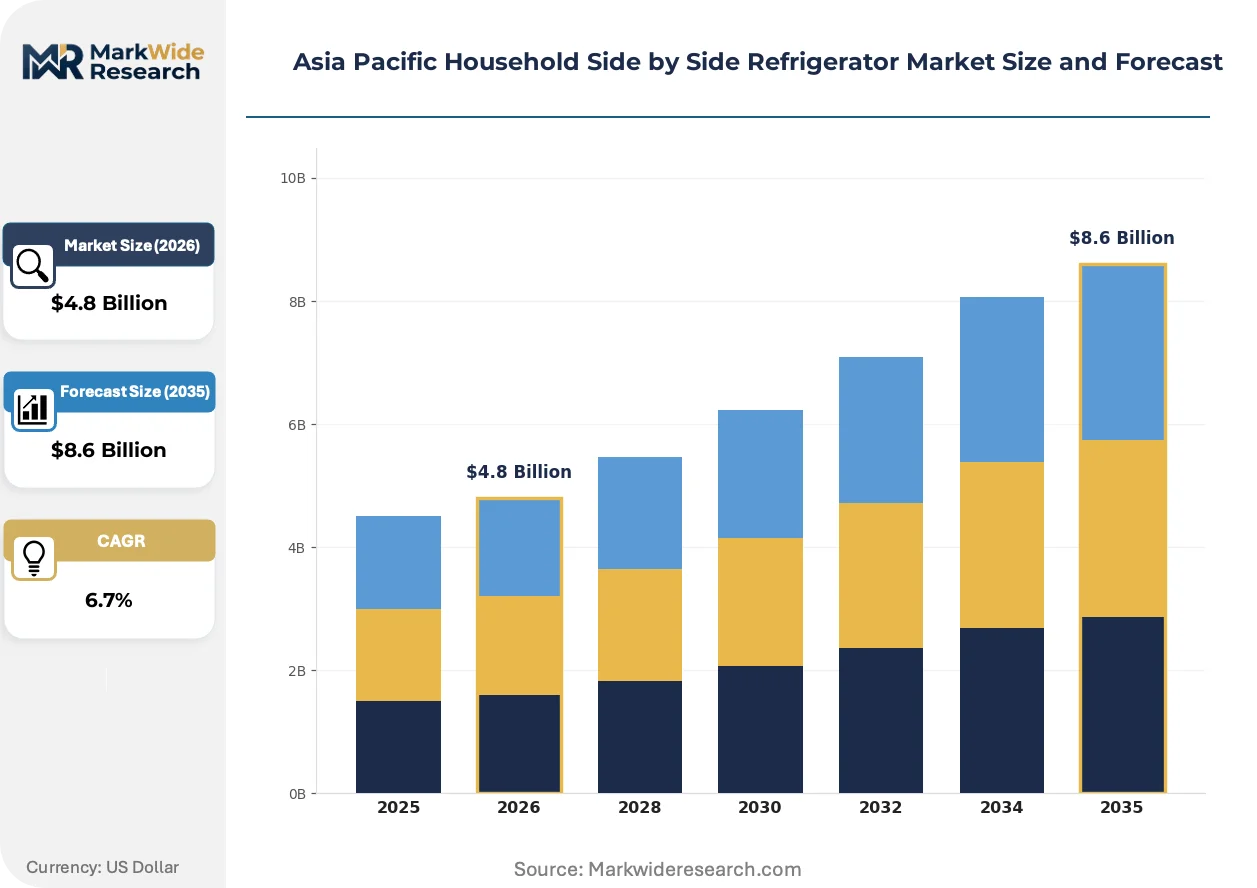
Inverter-driven compressor technology is compressing replacement cycles across Asia Pacific households as energy-efficiency mandates from China's SAMR and India's BIS force platform upgrades. Korean and Chinese manufacturers now compete on semiconductor supply chain control rather than assembly scale.
Growth Catalysts
- Dual carbon goals:China's MEE enforcement accelerates inverter adoption by penalizing fixed-speed compressor sales. Tier-one cities mandate minimum star ratings for new residential developments.
- Urban kitchen renovation:Metropolitan households in India and Southeast Asia prioritize side-by-side configurations during appliance upgrades. Organized retail expansion enables product visibility.
- AI-based inventory management:Smart refrigerator variants attract premium positioning as connected kitchens reshape buyer expectations. Voice integration and food-tracking algorithms differentiate positioning.
Market Restraints
- Copper-aluminum price volatility:Compressor winding materials face commodity swings that compress margin buffers. Manufacturers hedge through long-term supplier contracts.
- Refrigerant phase-down schedules:Japan's METI Top Runner program and China's GB standards force R-600a and R-290 transitions. Retrofitting production lines demands capital outlays.
- Direct cool residual share:Price-sensitive Southeast Asian markets retain single-door units for secondary refrigeration. Side-by-side penetration lags outside metropolitan corridors.
Strategic Opportunities
- Vietnam and Indonesia underpenetration:Emerging middle-class households in secondary cities lack exposure to side-by-side formats. Localized financing schemes unlock first-time buyers.
- Utility rebate eligibility:India's BIS star-labeling aligns with state-level energy efficiency incentives. Five-star rated models command preferential placement in retail.
- Convergence of inverter and IoT:Variable-speed compressors paired with predictive maintenance algorithms reduce service costs. Platform differentiation shifts from hardware to software.
Industry Challenges
- Semiconductor procurement bottlenecks:Inverter module controllers face allocation constraints from automotive and industrial demand. Appliance OEMs compete for foundry capacity.
- Harmonization across compliance regimes:Exporters must engineer single platforms satisfying Japan's METI, China's SAMR, and India's BIS simultaneously. Testing timelines extend product launch windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia Pacific Household Side by Side Refrigerator Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Refrigerator, Smart Refrigerator, Energy-Efficient Refrigerator, Mini Refrigerator End User: Residential Customers, Hospitality Sector, Food Service, Retail Stores Feature: Multi-Door, Built-In Water Dispenser, Ice Maker, Adjustable Shelves Technology: Inverter Technology, Conventional Cooling, Frost-Free Cooling, Direct Cool |
| Companies Covered | Samsung Electronics, LG Electronics, Haier, Whirlpool Corporation, Godrej, Midea, Hisense, Panasonic Corporation, Electrolux, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia Pacific Household Side by Side Refrigerator Market Trends and Innovations
Refrigeration technology is pivoting from thermal efficiency metrics to ecosystem integration, where compressor intelligence and connectivity layers redefine product architecture. Manufacturers now compete on data platform ownership rather than cooling performance alone.
Variable-speed inverter compressors is supplanting fixed-speed reciprocating units across mid-tier and premium segments. Urban households in China's tier-one cities and India's metropolitan corridors specify inverter technology for noise reduction and temperature stability. This transition compresses margin structures for assemblers lacking captive compressor supply.
China's SAMR enforcement of updated GB standards for energy consumption and refrigerant specifications accelerates platform consolidation. Manufacturers must redesign evaporator systems and insulation specifications to meet tightened thermal performance thresholds. Regional exporters to China face certification bottlenecks that favor domestic producers with established testing relationships.
Appliance procurement through direct-to-consumer channels and bundled home-builder contracts is fragmenting traditional dealer networks. Real estate developers in India and China specify refrigerator models at construction stage, bypassing retail entirely. This shift concentrates volume with project sales teams rather than distributor inventories.
Asia Pacific Household Side by Side Refrigerator Market Segmentation
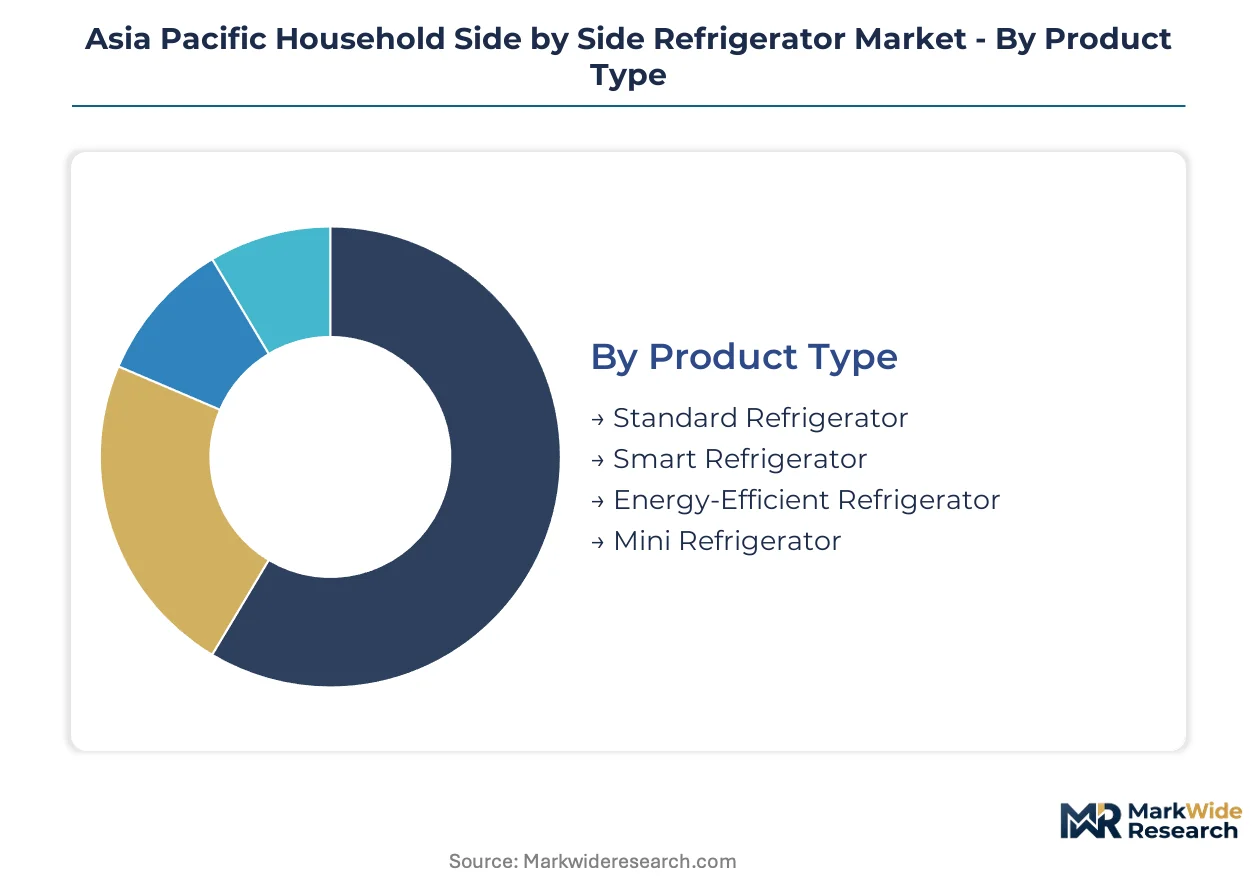
Side-by-side refrigerator segmentation across Asia Pacific reveals divergent margin pools between hardware commoditization and software-enabled premium tiers. Product architecture choices now determine whether manufacturers capture value through compressor technology licensing or recurring platform services.
Product Type:
Margin concentration sits with connected variants that transform one-time appliance sales into ongoing data relationships.
- Smart Refrigerator:AI-based inventory tracking and voice integration command pricing premiums in China's tier-one cities and India's metropolitan corridors. Samsung Electronics and Haier deploy proprietary software stacks to lock households into ecosystem subscriptions.
- Energy-Efficient Refrigerator:Inverter-driven compressors meeting China's SAMR GB standards and India's BIS five-star thresholds qualify for utility rebates and builder specification. Regulatory alignment creates procurement preference in new residential developments.
- Standard Refrigerator:Fixed-feature configurations dominate volume in Southeast Asian markets where organized retail penetration remains uneven.
- Mini Refrigerator:Compact side-by-side formats serve secondary refrigeration needs in premium Indian and Vietnamese households.
Smart refrigerator holds installed capacity. Energy-efficient refrigerator is rotating up the share rankings.
End User:
Volume distribution tilts toward direct household procurement, though project sales to developers are compressing traditional dealer margins.
- Residential Customers:Urban kitchen renovations in Beijing, Shanghai, Mumbai, and Delhi drive replacement cycles toward side-by-side formats. Metro households prioritize organized storage and temperature stability for fresh produce preservation.
- Hospitality Sector:Hotels and serviced apartments in Thailand and Indonesia specify built-in configurations for guest room minibars and back-of-house operations. Procurement runs through facility management contracts rather than retail channels.
- Food Service:Restaurants and catering operations in Vietnam and the Philippines adopt compact side-by-side units for ingredient staging.
- Retail Stores:Appliance showrooms and electronics chains in India and China maintain demonstration inventory for customer experience.
Residential customers anchor volume procurement. Hospitality sector is expanding most quickly in secondary city markets.
Feature:
Specification differentiation clusters around convenience interfaces that reduce friction in daily use patterns.
- Built-In Water Dispenser:Filtered dispensing systems with UV sterilization attract health-conscious households in Japan and South Korea. Manufacturers source filtration cartridges through recurring revenue models.
- Ice Maker:Automated ice production with multiple form factors serves entertaining-focused households in Australia's metropolitan markets. Climate-driven demand peaks during summer quarters.
- Multi-Door:Three and four-door configurations beyond standard two-door side-by-side layouts appeal to large-family households in India's tier-one cities.
- Adjustable Shelves:Modular interior architecture accommodates varying container dimensions across Asian cooking traditions.
Built-in water dispenser maintains specification leadership. Ice maker is climbing the fastest in tropical climate zones.
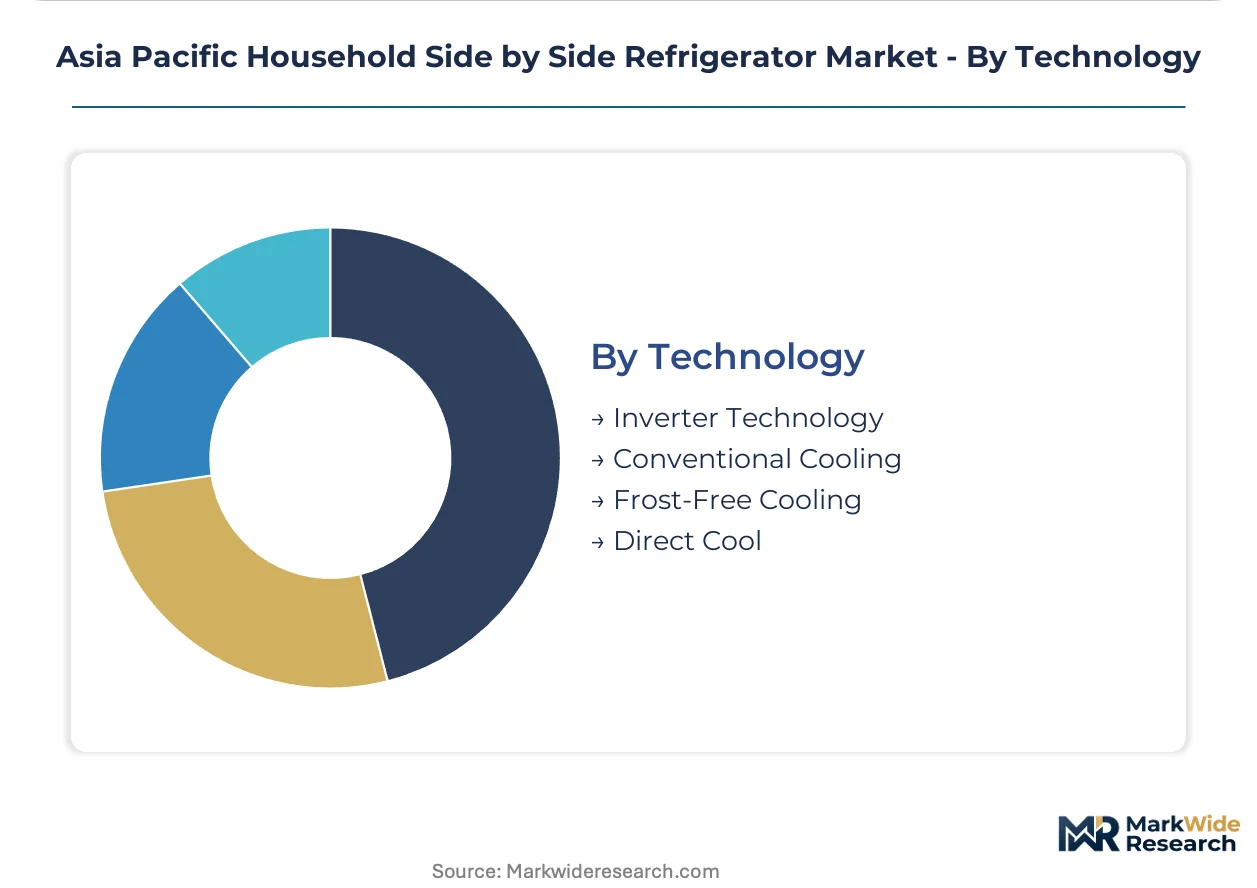
Technology:
Platform transitions are forcing capital redeployment as fixed-speed compressor lines face regulatory obsolescence.
- Inverter Technology:Variable-speed compressors reduce energy consumption by modulating cooling output against thermal load. China's MEE enforcement and India's BIS star-labeling mandate accelerate displacement of conventional alternatives.
- Frost-Free Cooling:Forced-air circulation eliminates manual defrosting requirements, addressing convenience expectations in Japan and South Korea. Evaporator design complexity raises manufacturing barriers for smaller assemblers.
- Conventional Cooling:Fixed-speed reciprocating compressors retain residual share in price-sensitive Indonesian and Philippine markets.
- Direct Cool:Single-evaporator systems persist in entry-tier configurations where cost minimization overrides performance specifications.
Inverter technology commands production priority. Frost-free cooling is gaining share fastest in premium tier rotations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity varies sharply across Asia Pacific. Southeast Asian buyers in Indonesia and Vietnam prioritize entry-tier configurations, while households in China's tier-one cities and India's metropolitan corridors absorb premium inverter-driven models without volume trade-offs.
China
Tier-one city households in Beijing, Shanghai, and Shenzhen specify side-by-side formats during kitchen renovations. SAMR enforces updated GB standards for energy consumption and refrigerant specifications, forcing platform redesigns. Manufacturing concentrates in the Yangtze River Delta and Pearl River Delta, where Haier and Midea anchor captive compressor production.
India
Metropolitan corridors in Mumbai, Delhi-NCR, and Bangalore drive replacement cycles toward organized storage solutions. BIS mandates compulsory star-labeling for household appliances, with five-star rated models qualifying for state-level utility rebates. Gujarat and Maharashtra host assembly operations serving western and northern demand clusters.
Japan
Health-conscious households in Tokyo and Osaka specify built-in water dispensers with UV sterilization. METI's Top Runner program accelerates efficiency benchmarks, forcing regional exporters to harmonize product platforms. Manufacturing clusters in the Chubu region around Nagoya supply precision compressor components.
Vietnam
Emerging middle-class households in Ho Chi Minh City and Hanoi lack exposure to side-by-side formats, creating first-time buyer pools. Localized financing schemes unlock penetration in secondary cities. Northern industrial zones near Hanoi attract Korean and Chinese OEM assembly investment.
Indonesia
Price-sensitive markets in Jakarta and Surabaya retain single-door units for secondary refrigeration needs. Side-by-side penetration lags outside metropolitan corridors where direct cool systems dominate. Java-based distributors struggle with organized retail visibility for premium formats.
Asia Pacific Household Side by Side Refrigerator Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier that competes on assembly scale and regional distribution reach. Korean and Chinese manufacturers now differentiate through semiconductor supply chain control rather than production volume. Three archetypes dominate: captive compressor producers with backward integration, smart platform operators with proprietary software stacks, and regional assemblers serving price-sensitive Southeast Asian markets. M&A activity targets distribution networks in India and Vietnam, while technology licensing agreements proliferate around inverter module controllers.
Among Korean chaebols, Samsung Electronics and LG Electronics occupy positions defined by in-house semiconductor capabilities and ecosystem integration. Chinese manufacturers Haier and Midea exemplify the backward-integrated archetype through captive compressor operations and project sales relationships with real estate developers. These four anchors represent divergent capital-intensity strategies now rotating competitive dynamics across the region.
| Leading Market Players |
|---|
| Samsung Electronics |
| LG Electronics |
| Haier |
| Whirlpool Corporation |
| Godrej |
| Midea |
| Hisense |
| Panasonic Corporation |
| Electrolux |
| Others |
Pricing and Supply Chain Analysis
Compressor manufacturing scale in China's Yangtze River Delta and Pearl River Delta anchors regional cost structures, concentrating inverter module production among vertically integrated OEMs while compressing margin buffers for assembly-dependent competitors. This concentration elevates price floors for five-star rated models in India and tier-one Chinese cities, where BIS and SAMR compliance costs filter through to metropolitan households.
Pricing Analysis
After-sales revenue from compressor warranties and IoT platform subscriptions now exceeds hardware margins for connected variants in China's tier-one cities. Three-tier pricing structure across premium smart, standard inverter, and economy fixed-speed levels stratifies by certification grade and connectivity bundle. Pricing pressure stems from copper-aluminum commodity volatility in compressor windings, forcing hedging costs into tier-two configurations. Price-sensitive Indonesian and Philippine households trade thermal performance for upfront savings, while Japanese buyers absorb UV-filtration premiums without volume elasticity.
Supply Chain Analysis
Strategic stockpiling of semiconductor inventory for inverter controllers has displaced just-in-time preferences as automotive and industrial demand competes for foundry allocation. Component sourcing concentrates in China, South Korea, and Japan, with compressor motors drawing from copper suppliers in Chile and Indonesia. Raw material exposure to refrigerant phase-down schedules under METI and SAMR frameworks threatens production line retrofit costs. Distribution runs through captive retail networks in India and project-sales channels with Chinese real estate developers, bypassing traditional dealer markups.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics now govern competitive returns as refrigerator OEMs monetize food-inventory data and predictive maintenance algorithms rather than thermal hardware alone. Interoperability with smart home ecosystems determines household lock-in and replacement-cycle compression.
For Market Incumbents: Consolidate inverter module supply through captive semiconductor procurement or long-term foundry agreements to offset allocation competition from automotive demand. Anchor distribution control in India's metropolitan corridors through exclusive retail partnerships that block challenger shelf space. Compressor backward integration remains essential as fixed-speed platforms face regulatory obsolescence under China's MEE enforcement.
For New Entrants and Emerging Players: BIS fast-track certification for five-star rated models unlocks utility rebate eligibility and preferential placement in Indian organized retail. Target Vietnam's secondary cities with localized financing schemes that address first-time buyer credit constraints. Pursue white-label manufacturing for Southeast Asian distributors lacking technical capabilities as the lowest-friction entry vector.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among smart platform operators with proprietary software stacks and ecosystem subscription attach rates. Five-to-ten year viability favors OEMs controlling compressor supply chains in China and India over pure-brand assemblers. Monitor inverter controller foundry allocation announcements as the inflection signal for margin compression or expansion across the competitive set.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Compressor Manufacturing | Captive supply of inverter modules insulates Haier and Midea from semiconductor allocation competition. |
| Smart Platform Ecosystem Development | Proprietary software stacks by Samsung Electronics and LG Electronics lock households into recurring data services. |
| Five-Star BIS Certification Investment | Qualification for state-level utility rebates in India concentrates procurement preference in organized retail. |
| Project Sales Channel Expansion | Direct contracts with Chinese and Indian real estate developers bypass distributor margins and inventory risk. |
| Localized Financing Scheme Deployment | Credit access programs in Vietnam and Indonesia unlock first-time penetration in underexposed secondary cities. |
Research Methodology
A standing panel of appliance manufacturing executives, inverter controller procurement leads, organized retail category managers, and real estate developer project sales directors provided ongoing calibration against shipment data and inventory positions. Primary interviews with these stakeholders combined with secondary validation from SAMR GB standard filings, BIS star-labeling databases, METI efficiency benchmark disclosures, and customs trade records for compressor component flows. Bottom-up unit shipment modeling and top-down value estimation triangulated across these sources.
Consistency checks against external production capacity announcements and foundry utilization reports validated volume and value outputs across the projection horizon. Segmentation dimensions modeled include product type, end user category, feature specification, and technology platform, with additional granularity on inverter versus fixed-speed compressor penetration. CAGRs derived from fitted growth curves applied to base-year observations, incorporating regulatory phase-in schedules and replacement-cycle compression assumptions specific to energy-efficiency mandate adoption patterns.
Decision-makers should treat outputs as directional under assumptions of continued SAMR and BIS enforcement without regulatory rollback; material deviation would warrant model refresh. Forecasts reflect these base conditions alongside assumed copper price bands and foundry allocation stability. Revision becomes warranted when semiconductor procurement bottlenecks for inverter controllers cross thresholds that force platform redesign or production suspension.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Appliances
Minibar Refrigerators Market
Appliances
Hairdryer Market
Appliances
Global Electric Water Heaters Market
Appliances
Small Appliances Market
Appliances
US Washing Machine Parts Market
Appliances
Conveyor Dishwasher Market
Appliances
Germany Compact Dishwasher Market
Appliances
Smart Ceiling Fan Market
Appliances
Europe Tumble Dryers Market
Appliances
Mobile Refrigerators Market
Appliances
United Kingdom Handheld Vacuum Cleaners Market
Appliances
Shared Shoe Washing Machine Market
Appliances
Washing Appliances Market
Appliances
Smart Microwave Oven Market
Appliances
Electric Iron Market
Appliances
Europe Household Electric Grills Market