
 China Induction Hobs Market | 2026-2036
China Induction Hobs Market Size, Share, and Industry Trends Forecast 2026-2036
China Induction Hobs Market Outlook
Fragmentation among high-rise residential developers is repositioning procurement channels away from traditional retail toward direct contractor relationships. Haier Electronics leverages its appliance ecosystem to bundle induction hobs with smart kitchen suites. Midea sustains manufacturing scale through captive component production in Guangdong. Supor competes on price-tier breadth across economy and mid-range segments.
Induction hobs are electric cooking appliances that generate heat through electromagnetic induction between a copper coil and ferromagnetic cookware, typically operating at power frequencies of 20-50 kHz and conversion efficiencies exceeding 80%. Built-in configurations dominate residential installations due to seamless countertop integration and space optimization in urban Chinese kitchens. Multi-zone technology captures premium margins as consumers upgrade from single-zone entry models. Commercial end users favor split configurations for flexible kitchen layouts in restaurants and central catering facilities.
MIIT enforces GB 4706 electromagnetic compatibility standards that constrain import designs and elevate local certification costs. SAMR product safety inspections and China's dual carbon goals from MEE tighten efficiency thresholds and phase out resistive coil alternatives. Stakeholders must monitor how municipal green building codes in tier-one cities reshape specification requirements for new residential developments.
Market Dynamics
MIIT energy-efficiency mandates and GB electromagnetic compatibility standards are accelerating replacement cycles across China's residential and commercial kitchen equipment base, compressing product lifecycles and elevating certification barriers for new entrants.
Growth Catalysts
- Shanghai Green Building Codes:Municipal efficiency specifications for new residential developments in tier-one cities mandate induction technology over resistive alternatives.
- Dual Carbon Goals:MEE efficiency thresholds phase out high-consumption coil designs and redirect procurement toward certified electromagnetic cooking systems.
- Multi-Zone Technology:Premium residential buyers upgrade from single-zone entry models to flexible cooking surfaces that optimize countertop utility in compact urban kitchens.
Market Restraints
- Copper Coil Input Volatility:Ferromagnetic cookware compatibility requirements and copper price fluctuations constrain margin stability for manufacturers without captive component supply.
- GB 4706 Certification Friction:SAMR electromagnetic compatibility testing protocols extend product launch timelines and elevate compliance costs for import designs.
- Gas Infrastructure Persistence:Existing piped gas networks in older residential stock delay full electrification of cooking equipment in tier-two and tier-three cities.
Strategic Opportunities
- Shenzhen Smart Kitchen Integration:IoT-enabled appliance ecosystems create attachment opportunities for induction hobs bundled with connected refrigeration and ventilation systems.
- Central Catering Facilities:Commercial split-configuration demand rises as restaurant chains and institutional food service operators prioritize flexible kitchen layouts.
- Beijing Renovation Cycles:Residential kitchen refurbishment waves in premium developments open direct contractor channels bypassing traditional retail markups.
Industry Challenges
- Electromagnetic Compatibility Testing Bottlenecks:SAMR inspection queue delays and retest requirements compress launch windows for seasonal product cycles.
- Legacy Gas Hookup Retrofit Complexity:Installer skill shortages and electrical capacity upgrades in older buildings slow residential conversion rates outside new construction.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Induction Hobs Market |
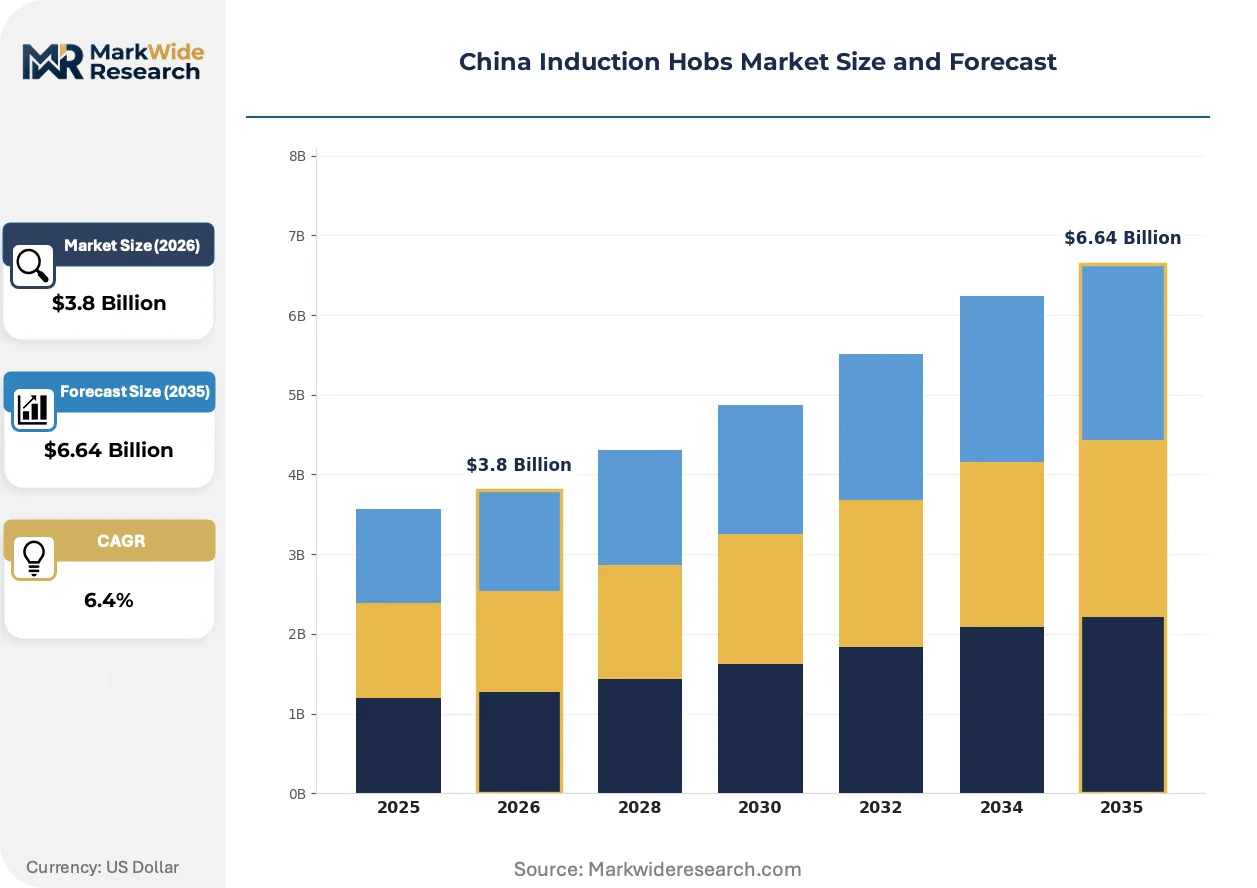
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.64 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable, Built-In, Split, Free-Standing End User: Residential, Commercial, Hospitality, Retail Technology: Single Zone, Double Zone, Multi Zone, Integrated Price Tier: Economy, Mid-Range, Premium, Luxury |
| Companies Covered | Electrolux AB, Samsung, Haier Electronics, Koninklijke Philips NV, Panasonic Corp, Midea, Philips, Smeg SpA, Supor, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Induction Hobs Market Strategic Shifts
Electromagnetic cooking technology is consolidating around higher-frequency power conversion and intelligent zone management, while regulatory pressure and procurement model evolution reshape how equipment reaches end users across China's urban residential markets.
Multi-zone induction surfaces with independent power control are consolidating kitchen footprint requirements for premium Shanghai and Beijing apartments. Developers of high-rise residential towers specify these systems to differentiate compact unit offerings. The technology is consolidating demand around fewer, higher-capability suppliers who can integrate zone management with building energy management systems.
MIIT enforcement of updated GB standards for electromagnetic emissions tightens design tolerances for all equipment sold in China. Manufacturers must retest existing platforms and modify coil geometries to maintain certification. Commercial kitchen operators in Shenzhen and Guangzhou face compressed equipment replacement timelines as older designs lose compliance eligibility.
Direct procurement relationships between residential developers and appliance manufacturers are displacing traditional distributor networks in tier-one cities. Contractor-led kitchen outfitting for new construction captures specification authority earlier in the project cycle. This pattern concentrates most visibly in Beijing's premium residential pipeline, where bundled smart kitchen packages lock in induction hob selection before consumer retail exposure.
China Induction Hobs Market Segmentation
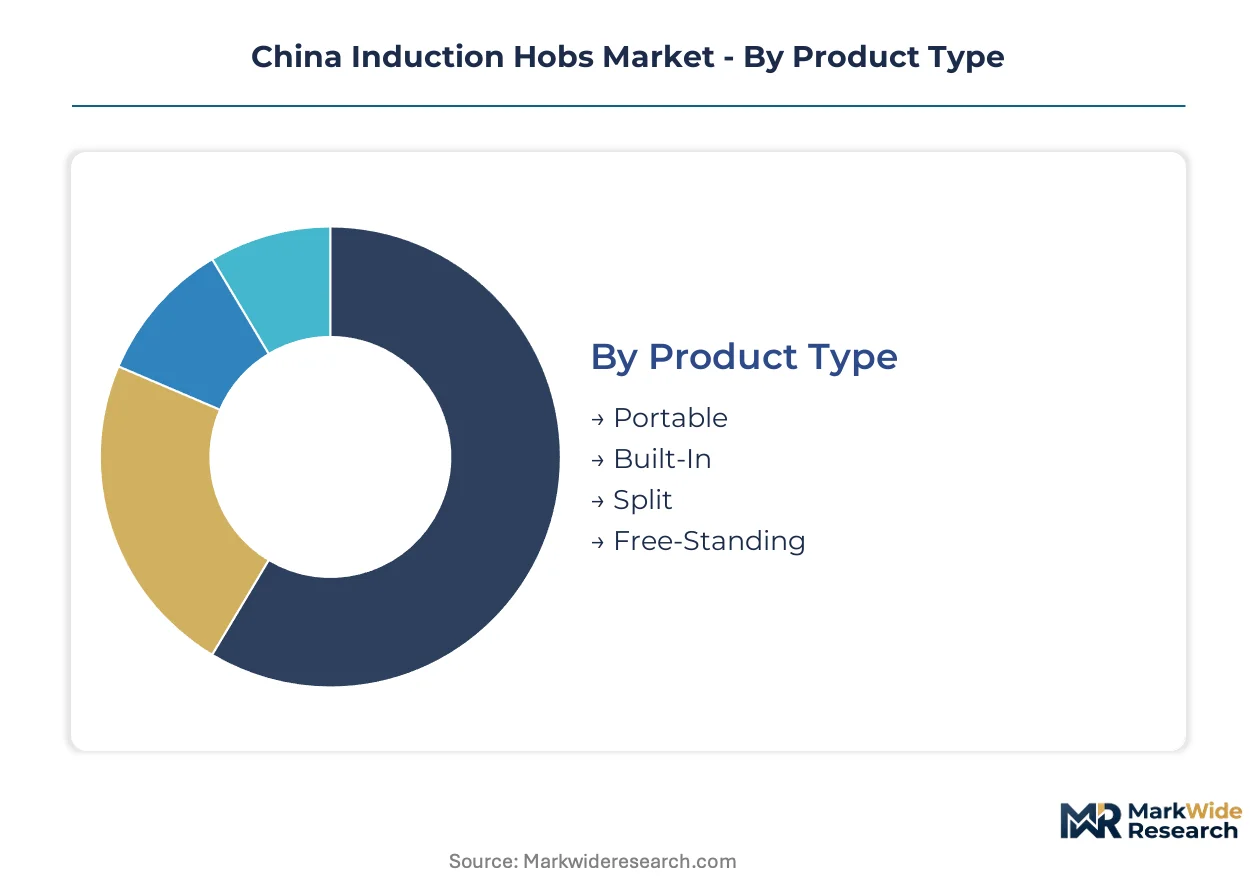
Segmentation in China's induction hobs market reveals how procurement channels, certification requirements, and urban kitchen constraints fragment demand across distinct technical and commercial categories. Each dimension carries regulatory and supply chain implications that reshape competitive positioning.
Product Type:
Volume concentrates in built-in configurations for new residential construction, while portable units address retrofit flexibility in older buildings.
- Built-In:Seamless countertop integration dominates tier-one city premium developments. Shanghai and Beijing developers specify these for space optimization in compact urban kitchens under MIIT efficiency mandates.
- Split:Modular configurations allow flexible kitchen layouts for commercial operators. Shenzhen restaurant chains and central catering facilities prioritize this format for equipment repositioning.
- Portable:Addresses electrical retrofit complexity in older residential stock without dedicated circuitry.
- Free-Standing:Serves rental markets and temporary food service installations with minimal installation requirements.
Today's leader: Built-In. Tomorrow's challenger: Split.
End User:
Residential procurement channels are displacing traditional retail through direct developer relationships, while commercial buyers prioritize operational flexibility.
- Residential:Kitchen renovation waves in Beijing and Shanghai premium developments drive specification authority earlier in project cycles. Contractor-led outfitting bypasses retail markups.
- Commercial:Restaurant chains and institutional operators in Guangzhou face compressed replacement timelines as older designs lose GB 4706 compliance eligibility.
- Hospitality:Hotel kitchen upgrades align with municipal green building codes mandating electromagnetic cooking over resistive alternatives.
- Retail:Traditional distributor networks retain relevance in tier-two and tier-three cities where direct procurement relationships remain underdeveloped.
Residential commands procurement volume. Commercial offers the steepest expansion trajectory as compliance deadlines accelerate.
Technology:
Zone density correlates directly with margin structure and integration complexity in building energy management systems.
- Multi Zone:Independent power control consolidates kitchen footprint for premium apartments. High-rise developers specify these to differentiate compact unit offerings in Shenzhen and Shanghai.
- Single Zone:Entry-level models face substitution pressure as residential buyers upgrade. Economy segment concentration here constrains manufacturer margins.
- Double Zone:Mid-market positioning balances functionality with cost for standard apartment configurations.
- Integrated:IoT-enabled systems bundled with smart kitchen suites create attachment opportunities for connected refrigeration and ventilation ecosystems.
Multi Zone captures premium positioning. Integrated systems are climbing the fastest as smart home penetration deepens.
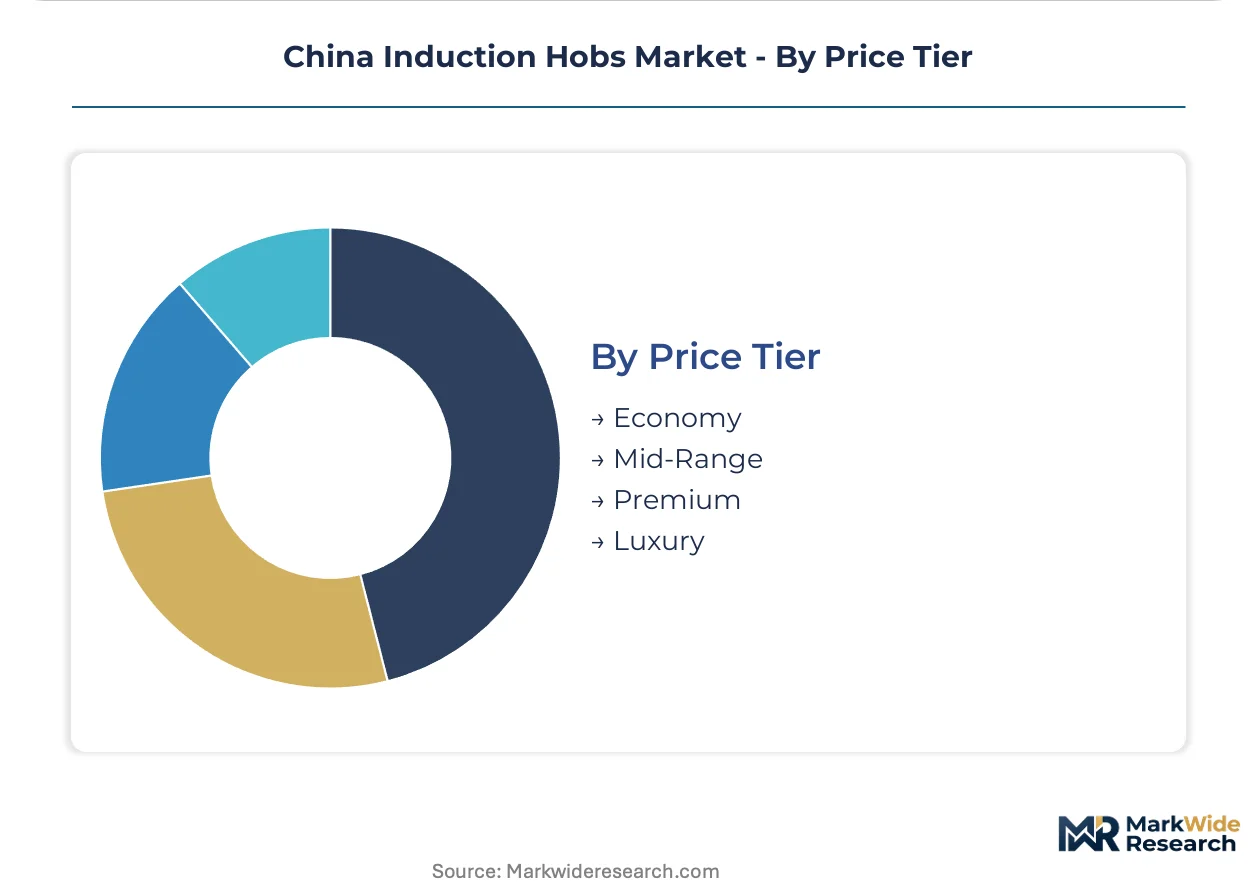
Price Tier:
Certification grade and zone technology separate tiers more than raw material cost, with MIIT mandates elevating baseline efficiency requirements economy-wide.
- Premium:Multi-zone configurations with GB 4706 certification and smart integration dominate Beijing and Shanghai new construction specifications.
- Economy:Single-zone portable and basic built-in units serve price-sensitive buyers in tier-two cities with persistent gas infrastructure.
- Mid-Range:Double-zone built-in models balance functionality with accessibility for standard residential developments.
- Luxury:Custom finishes and proprietary zone management systems target ultra-premium developments with building-level energy management integration.
Premium owns new construction specification. Economy retains volume in retrofit-constrained geographies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Engineering talent clusters in the Yangtze River Delta and Pearl River Delta anchor China's induction hob manufacturing base. These regions concentrate electromagnetic coil fabrication, power electronics assembly, and smart appliance integration expertise.
Shanghai
Green building codes mandate induction technology in new residential towers, displacing gas alternatives. MIIT efficiency standards accelerate equipment replacement in commercial kitchens. Pudong and Minhang districts host smart appliance R&D centers where manufacturers integrate IoT connectivity with zone management systems.
Beijing
Premium residential renovation cycles drive contractor-led procurement bypassing retail channels. SAMR electromagnetic compatibility inspections compress product launch timelines for non-compliant imports. Haidian and Chaoyang districts concentrate developer headquarters specifying bundled kitchen packages.
Shenzhen
Restaurant chains and central catering facilities demand split-configuration flexibility for kitchen layout optimization. Municipal dual carbon enforcement phases out resistive coil equipment in commercial food service. Nanshan and Longgang districts anchor smart home ecosystem integration with connected ventilation and refrigeration.
Guangzhou
Manufacturing scale advantages from captive component production in adjacent Foshan lower unit costs for mid-range built-in models. GB 4706 certification requirements elevate barriers for import designs lacking local testing relationships. Panyu and Nansha districts concentrate export-oriented appliance assembly.
Chengdu
Tier-two city kitchen electrification lags tier-one penetration due to persistent gas infrastructure in older residential stock. Provincial efficiency subsidies redirect procurement toward certified electromagnetic cooking in new construction. High-Tech West Zone attracts appliance manufacturers seeking lower labor costs than coastal centers.
China Induction Hobs Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across China's induction hob market. Haier Electronics and Midea leverage appliance ecosystem breadth to bundle induction hobs with smart kitchen suites, while Supor concentrates on price-tier coverage. The vendor base separates into three strategic archetypes: full-line appliance conglomerates, captive-component manufacturers, and specialist cooking equipment brands. Competitive moves center on backward integration into copper coil production and direct developer relationships that displace traditional distribution.
Among diversified appliance conglomerates, Haier Electronics occupies a position exemplifying ecosystem bundling strategy, while Midea represents manufacturing scale through upstream control over component supply. Supor sits within the specialist tier, anchoring price-competitive positioning across economy and mid-range segments. These three companies collectively illustrate how competitive advantage in China's induction hob market derives from either vertical integration depth, smart home platform attachment, or segment-focused cost discipline.
| Leading Market Players |
|---|
| Electrolux AB |
| Samsung |
| Haier Electronics |
| Koninklijke Philips NV |
| Panasonic Corp |
| Midea |
| Philips |
| Smeg SpA |
| Supor |
| Others |
Value Chain & Pricing Dynamics
Copper coil procurement from Guangdong and Zhejiang foundries flows through captive production networks into tiered product positioning, with raw material volatility compressing margins at the economy end while premium multi-zone configurations absorb cost fluctuations through specification lock-in with Beijing and Shanghai developers.
Pricing Analysis
Bundled smart kitchen packages versus unbundled standalone sales split the pricing architecture. Three-tier pricing structure across premium, standard, and economy levels separates certification-grade multi-zone systems from basic single-zone portables. Pricing pressure stems from SAMR electromagnetic compatibility testing costs elevating entry barriers. Economy buyers in tier-two cities exhibit highest price sensitivity, while premium residential developers in tier-one cities prioritize specification compliance over unit cost.
Supply Chain Analysis
Reverse-logistics flows for failed electromagnetic coils and power electronics modules remain underdeveloped, creating aftermarket service gaps. Manufacturing concentrates in China, with component sourcing from South Korea and Japan for high-frequency power semiconductors. Supply chains draw from copper cathode, ferrite cores, and IGBT modules as critical inputs. Single-source vulnerability sits with advanced power electronics imports. Distribution runs through direct developer relationships displacing traditional retail in tier-one cities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
China's induction hobs market compounds steadily as MIIT efficiency mandates and municipal green building codes enforce replacement cycles across residential and commercial kitchen equipment bases.
For Market Incumbents: Hedge against copper price volatility through backward integration into coil winding and ferrite core production in Guangdong. Secure direct procurement relationships with high-rise residential developers in Beijing and Shanghai before contractor-led outfitting consolidates specification authority. Invest in GB 4706 pre-certification testing capacity to compress SAMR inspection queue delays. For New Entrants and Emerging Players: Dual carbon goals in China open a window for split-configuration specialists targeting Shenzhen restaurant chains and central catering facilities underserved by residential-focused incumbents. White space concentrates in commercial retrofit segments where flexible kitchen layouts command premium positioning. Pursue municipal green building code compliance as the primary go-to-market credential. For Investors and Strategic Acquirers: Consolidation pressure builds where captive component supply and certification relationships concentrate procurement leverage among three to four diversified appliance conglomerates. Long-term viability favors targets with established MIIT testing relationships and direct developer channel access. Monitor SAMR electromagnetic compatibility inspection queue lengths as an inflection indicator for launch timeline risk.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Copper Coil Production | Captive supply of electromagnetic coils insulates margin stability against raw material volatility. |
| Smart Kitchen Platform Integration | IoT-enabled bundling with connected refrigeration and ventilation creates attachment stickiness in Shenzhen. |
| GB 4706 Pre-Certification Investment | In-house electromagnetic compatibility testing compresses SAMR inspection timelines for seasonal launches. |
| Direct Developer Relationship Expansion | Contractor-led procurement in Beijing and Shanghai bypasses retail markups and locks specifications early. |
| Split-Configuration Commercial Specialization | Modular formats address Shenzhen restaurant chains prioritizing flexible kitchen layout optimization. |
Study Parameters
Multiple input streams — executive interviews with appliance manufacturing leadership, regulatory affairs specialists at MIIT and SAMR, procurement directors at tier-one residential developers, and commercial kitchen operators — were reconciled against secondary validation from customs trade records, GB standards documentation, municipal green building code filings, and SEC disclosures from listed appliance conglomerates. Bottom-up unit shipment estimates triangulated against top-down market value reconstruction.
Data-stream reconciliation across the projection horizon employed product type, end user category, zone technology tier, and price positioning as segmentation dimensions. CAGRs derived from installed base replacement modeling and new construction penetration curves. Forecast inputs incorporated MIIT efficiency mandate phase-out schedules and municipal dual carbon enforcement timelines.
Revisions become necessary when copper price volatility exceeds historical bands, SAMR inspection queue delays extend beyond seasonal launch windows, or municipal green building code adoption accelerates in tier-two cities. Practitioners should monitor SAMR electromagnetic compatibility certification backlogs and tier-one city developer procurement consolidation for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Appliances
Cordless Vacuum Cleaner Market
Appliances
China Washing Machine Market
Appliances
Window Air Conditioners Market
Appliances
UAE Microwave Ovens Market
Appliances
Shared Shoe Washing Machine Market
Appliances
Saudi Arabia Gas Hobs Market
Appliances
North America Microwave Oven Market
Appliances
Hair Removal Appliances Market
Appliances
Egypt Microwave Ovens Market
Appliances
Consumer Appliances Market
Appliances
Smart Washing Machine Market
Appliances
Cooler Connected to the Mains Market
Appliances
Asia-Pacific Electric Rice Cooker Market
Appliances
Industrial Gas Stove Market
Appliances
Electric Rice Cooker Market
Appliances
Mexico Washing Machine Market