
 Refrigerator Door Seal Market | 2026-2036
Refrigerator Door Seal Market Size, Share, and Industry Trends Forecast 2026-2036
Refrigerator Door Seal Market Insights
Commercial foodservice operators is bifurcating refrigerator door seal procurement away from residential OEM channels. REHAU leverages its European extrusion footprint to sustain specification-grade EPDM supply for supermarket retrofit programs. Industrie Ilpea anchors Southern European aftermarket distribution through direct contractor relationships. Freudenberg Sealing Technologies differentiates via fluoropolymer-adjacent compounding expertise applied to low-temperature industrial freezer gaskets.
Refrigerator door seals are elastomeric compression gaskets, typically extruded from EPDM or PVC compounds with magnetic inserts, designed to maintain thermal isolation between refrigerated compartments and ambient environments. EPDM grades dominate material-type segmentation due to ozone resistance and operational range from minus forty to plus one hundred twenty degrees Celsius, while silicone occupies premium medical and laboratory refrigeration niches where FDA compliance is mandatory. Application-type segmentation tilts toward commercial refrigerators as quick-service restaurant chains and cold-storage logistics operators replace aging seals to meet escalating energy-code enforcement.
EPA energy-conservation standards and DOE commercial refrigeration test procedures shape North American product specifications, while REACH and RoHS constrain plasticizer chemistry across European supply chains. China's GB standards and evolving MEE enforcement on volatile organic compound emissions increasingly determine export-qualification protocols for Asian manufacturers. Stakeholders must monitor regulatory divergence between jurisdictions as compliance costs fragment sourcing strategies and compel regional formulation adjustments.
Market Dynamics
Energy-efficiency mandates across commercial refrigeration are compressing replacement cycles for door seals as operators face escalating compliance costs from EPA and DOE test procedures. This regulatory pressure is restructuring procurement toward specification-grade EPDM formulations that satisfy both thermal performance and chemical safety thresholds.
Growth Catalysts
- EPDM Material Transition:REACH and RoHS constraints on plasticizer chemistry are accelerating displacement of PVC compounds in European retrofit channels. EPDM's ozone resistance and minus-forty to plus-one-hundred-twenty Celsius operational range satisfy these tightened standards.
- Cold-Chain Infrastructure Buildout:Southeast Asian logistics operators are expanding refrigerated warehouse capacity. This construction wave generates aftermarket volume for compression gasket replacement as facilities reach operational maturity.
- Supermarket Energy Retrofit Programs:Commercial foodservice chains are executing systematic seal replacement to reduce thermal leakage. These programs specify magnetic-insert EPDM extrusions that meet utility rebate qualifications.
Market Restraints
- Petrochemical Feedstock Volatility:EPDM and silicone compound costs fluctuate with ethylene and propylene pricing. This input cost instability compresses margin predictability for extrusion manufacturers serving price-sensitive residential OEM segments.
- Chinese Supply Concentration:Bulk OEM demand concentrates in China's appliance manufacturing base. This geographic supply concentration creates vulnerability to export-qualification protocol shifts under evolving MEE volatile organic compound enforcement.
- Silicone Substitution Ceiling:Premium medical and laboratory refrigeration niches require FDA-compliant silicone formulations. EPDM cannot penetrate these segments due to biocompatibility certification barriers.
Strategic Opportunities
- Indian Cold-Chain Expansion:India's PLI scheme for food processing infrastructure is subsidizing refrigerated transport and storage buildout. This underpenetrated geography offers aftermarket volume as installed base ages.
- Fluoropolymer-Adjacent Compounding:Low-temperature industrial freezer applications demand advanced formulations. Convergence of fluoropolymer expertise with elastomer extrusion creates specification-grade product differentiation.
- Direct Contractor Distribution:Southern European aftermarket channels are consolidating around direct relationships with refrigeration service contractors. This channel innovation bypasses traditional wholesale intermediaries.
Industry Challenges
- Multi-Jurisdiction Formulation Complexity:Divergent GB standards, REACH restrictions, and EPA test procedures compel regional compound adjustments. Compliance teams must maintain parallel certification documentation across export markets.
- Magnetic Insert Integration Precision:Extrusion tolerances for magnetic strip embedding require specialized die engineering. Skill scarcity in precision extrusion tooling limits capacity expansion for specification-grade producers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Refrigerator Door Seal Market |
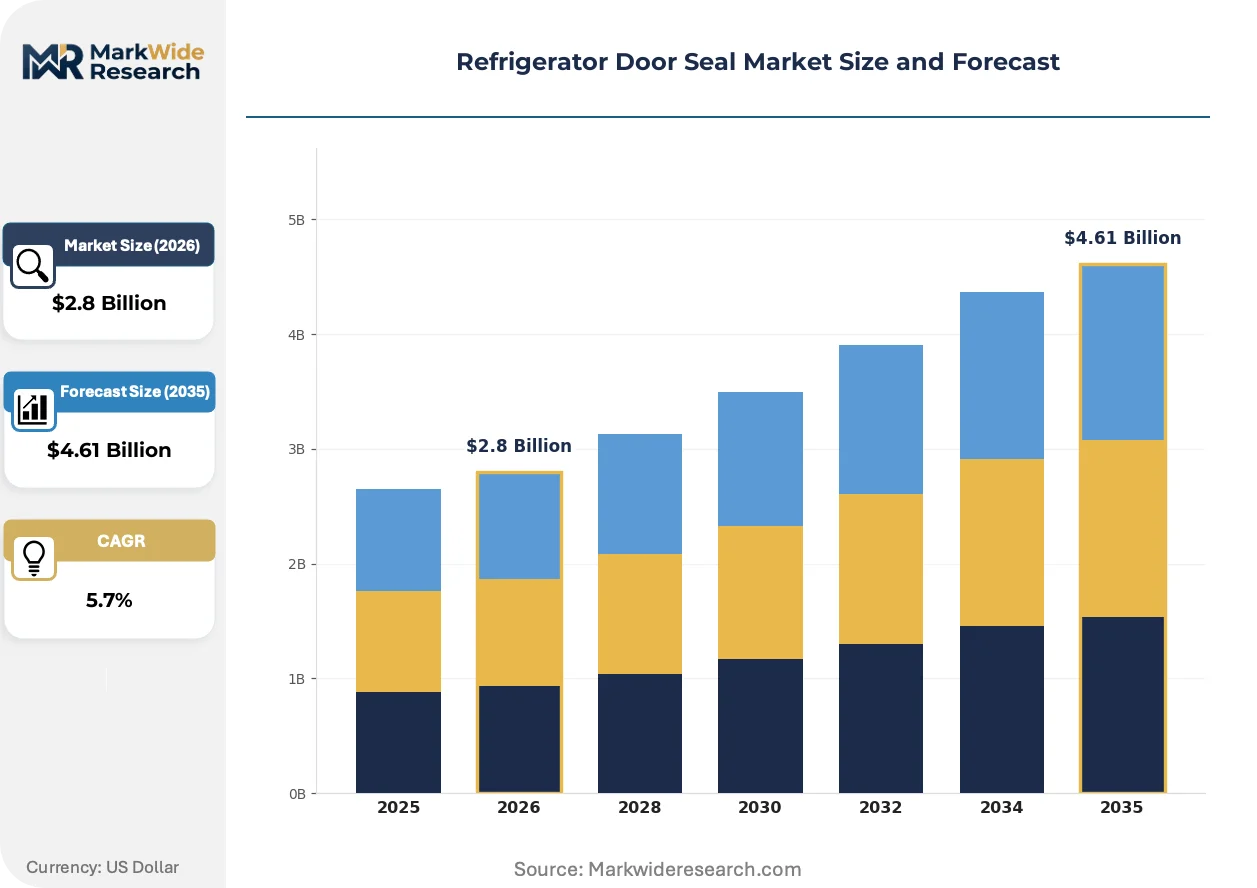
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.61 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: EPDM, PVC, Silicone, Neoprene Application Type: Domestic Refrigerators, Commercial Refrigerators, Industrial Freezers, Beverage Coolers Thickness: 5mm, 10mm, 15mm, 20mm Installation Method: Adhesive, Mechanical Fasteners, Snap Fit, Integral |
| Companies Covered | Industrie Ilpea, REHAU, Qingdao Qinke Engineering Plastics, Anhui Higasket Plastics, DSU, Anhe Enterprise, Qingdao Zhenxiong Mechanical Equipment, Freudenberg Sealing Technologies, Trelleborg Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Refrigerator Door Seal Market Trends and Innovations
Material science advances and regulatory chemistry constraints are converging to reshape elastomer formulation priorities. Extrusion technologies are adapting to serve bifurcated demand between mass-market OEM supply and precision aftermarket retrofit.
Co-extruded multi-layer gasket architectures are miniaturizing magnetic insert profiles while maintaining compression set resistance. Quick-service restaurant chains are adopting these reduced-section designs to accommodate thinner door constructions. This technology is miniaturizing seal cross-sections without sacrificing thermal isolation performance, enabling slimmer cabinet designs that reduce material costs.
EPA energy-conservation standards and DOE commercial refrigeration test procedures are tightening thermal leakage thresholds. These mandates are forcing specification updates across North American supermarket retrofit programs. Commercial operators in California and New York are responding by procuring certified EPDM formulations that satisfy utility rebate documentation requirements.
Foodservice procurement teams are consolidating vendor relationships around full-service gasket suppliers. Independent refrigeration contractors are losing specification influence as chain operators centralize procurement through approved vendor lists. This concentration is most visible in US quick-service restaurant networks where corporate facilities management now mandates seal replacement intervals.
Refrigerator Door Seal Market Segmentation
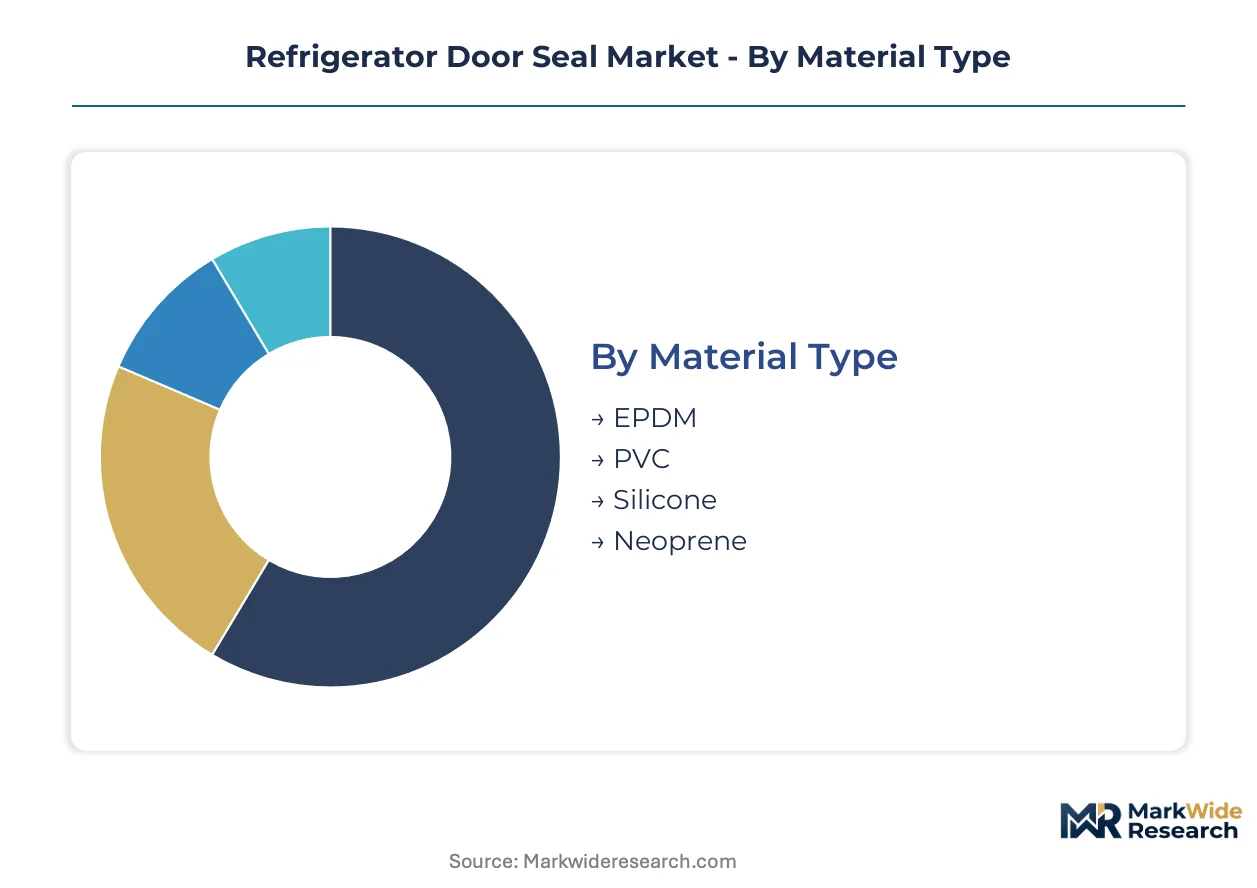
Segmentation in refrigerator door seals determines procurement channel access, formulation compliance requirements, and replacement cycle economics. Channel bifurcation between OEM supply and aftermarket retrofit creates distinct specification hierarchies that manufacturers must navigate simultaneously.
Material Type:
EPDM formulations flow primarily through commercial retrofit channels serving supermarket and cold-storage operators, while PVC compounds dominate residential OEM supply to appliance manufacturers. Silicone and neoprene occupy specialized industrial and medical niches with distinct certification pathways.
- EPDM:Extruded ethylene-propylene-diene monomer compounds incorporate ozone-resistant polymer matrices with magnetic strip integration. Supermarket energy retrofit programs in Germany and California specify these formulations to satisfy utility rebate documentation and REACH chemical safety thresholds.
- PVC:Polyvinyl chloride compounds with plasticizer additives offer lower material cost for mass-market residential refrigerator production. China's appliance manufacturing base concentrates bulk OEM demand, though REACH and RoHS constraints are accelerating displacement in European channels.
- Silicone:FDA-compliant formulations serve medical refrigeration and laboratory cold-chain applications where biocompatibility certification is mandatory.
- Neoprene:Chloroprene-based compounds provide moderate chemical resistance for beverage cooler applications in foodservice environments.
EPDM dominates installed base in commercial retrofit channels. PVC is where volume concentrates for OEM supply to residential manufacturers.
Application Type:
Application segmentation maps directly to replacement frequency and margin structure, with commercial operators facing accelerated seal replacement cycles under tightening energy codes.
- Commercial Refrigerators:Quick-service restaurant chains and cold-storage logistics operators execute systematic seal replacement programs to reduce thermal leakage. Corporate facilities management mandates are consolidating procurement through approved vendor lists, bypassing independent refrigeration contractors.
- Domestic Refrigerators:Residential OEM demand concentrates in China's manufacturing base, with replacement cycles extending to appliance end-of-life unless seal failure occurs.
- Industrial Freezers:Low-temperature applications demand advanced fluoropolymer-adjacent compounding expertise for compression gaskets operating below minus forty degrees Celsius.
- Beverage Coolers:Foodservice point-of-sale refrigeration units require frequent seal replacement due to high door-cycle frequency in retail environments.
Commercial refrigerators command premium specification requirements. Domestic refrigerators generate the highest unit volume.
Thickness:
Thickness selection correlates with cabinet construction era and thermal performance tier, with retrofit programs driving specification updates.
- 10mm:Standard cross-section for contemporary commercial refrigerator doors, balancing compression set resistance with magnetic closure force. Co-extruded multi-layer architectures are miniaturizing these profiles while maintaining thermal isolation performance.
- 15mm:Legacy commercial installations and heavy-duty industrial freezer applications specify thicker sections for extended compression durability.
- 5mm:Slim-line residential refrigerator designs and compact beverage cooler units.
- 20mm:Specialized cold-storage warehouse door seals for high-traffic logistics facilities.
10mm sections dominate current specification standards. 5mm profiles are climbing fastest as manufacturers reduce cabinet material costs.
Installation Method:
Installation segmentation determines contractor skill requirements and replacement labor economics, with channel preferences varying by geography and end-use.
- Mechanical Fasteners:Screw-retained gasket systems dominate commercial retrofit channels in North America, enabling field replacement without adhesive curing time. Refrigeration service contractors prefer this method for supermarket maintenance programs.
- Snap Fit:Press-in retention systems accelerate OEM assembly line throughput for residential refrigerator manufacturing in China and Southeast Asia.
- Adhesive:Bonded installations persist in legacy European equipment and specialized industrial applications requiring hermetic sealing.
- Integral:Factory-molded door frame integration serves premium appliance lines with extended warranty coverage.
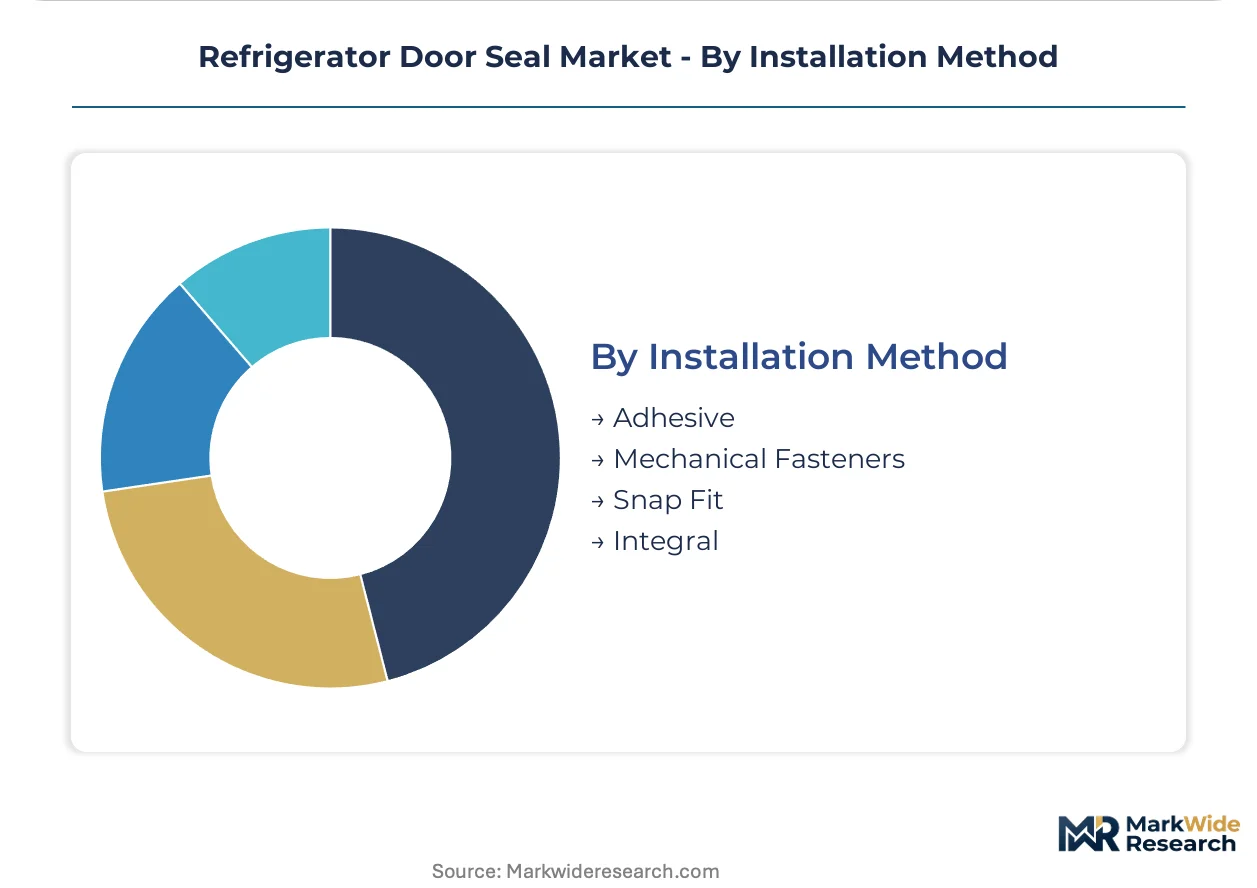
Mechanical fasteners anchor aftermarket service revenue. Snap fit is gaining share fastest in OEM supply chains seeking assembly efficiency.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's appliance manufacturing base concentrates bulk OEM demand for refrigerator door seals, while retrofit volume concentrates in North American and European commercial foodservice channels. Southeast Asian cold-chain buildouts are accelerating aftermarket replacement cycles. Regulatory divergence between EPA, REACH, and GB standards is fragmenting formulation strategies across export markets.
United States
Supermarket chains and quick-service restaurant operators are executing systematic seal replacement programs to satisfy utility rebate qualifications. EPA energy-conservation standards and DOE commercial refrigeration test procedures mandate thermal leakage thresholds that specification-grade EPDM formulations must meet. California and New York facilities management teams are consolidating procurement through approved vendor lists, bypassing independent refrigeration contractors.
Germany
REACH and RoHS constraints on plasticizer chemistry are accelerating displacement of PVC compounds in European retrofit channels. REHAU leverages its extrusion footprint to sustain specification-grade EPDM supply for supermarket energy retrofit programs. Bavaria-based fabricators anchor aftermarket distribution through direct contractor relationships serving commercial foodservice operators.
China
Appliance manufacturers in the Yangtze River Delta and Pearl River Delta concentrate bulk OEM demand for residential refrigerator production. GB standards and evolving MEE enforcement on volatile organic compound emissions determine export-qualification protocols. Qingdao and Zhengzhou industrial clusters host extrusion specialists serving both domestic appliance assembly and international aftermarket channels.
India
The PLI scheme for food processing infrastructure is subsidizing refrigerated transport and storage buildout across Maharashtra and Gujarat. Cold-chain operators in these states are generating aftermarket volume as installed base ages. Bangalore and Chennai logistics hubs are expanding warehouse capacity that will require systematic seal replacement programs within operational maturity cycles.
Italy
Southern European aftermarket channels are consolidating around direct relationships with refrigeration service contractors. Industrie Ilpea anchors this distribution innovation that bypasses traditional wholesale intermediaries. Milan and Turin industrial corridors maintain specification-grade EPDM supply for commercial retrofit programs serving supermarket chains.
Refrigerator Door Seal Market Competitive Landscape
Concentration sits with mid-cap extrusion specialists serving bifurcated demand between mass-market OEM supply and precision aftermarket retrofit. The vendor base spans European specification-grade formulators, Chinese volume manufacturers, and industrial sealing conglomerates with fluoropolymer-adjacent expertise. Three archetypes dominate: European retrofit specialists with direct contractor relationships, Chinese OEM suppliers with scale-driven cost positions, and diversified sealing technology groups with low-temperature compounding capabilities. Competitive moves center on backward integration into magnetic insert supply and geographic expansion into underpenetrated cold-chain markets.
Among European-based formulators, REHAU and Industrie Ilpea exemplify the retrofit-specialist archetype with established contractor channel access. Freudenberg Sealing Technologies occupies a position within the diversified industrial sealing tier, leveraging compounding expertise for low-temperature applications. Chinese fabricators including Qingdao Qinke Engineering Plastics and Anhui Higasket Plastics represent the volume-driven OEM supply segment concentrated in appliance manufacturing clusters.
| Leading Market Players |
|---|
| Industrie Ilpea |
| REHAU |
| Qingdao Qinke Engineering Plastics |
| Anhui Higasket Plastics |
| DSU |
| Anhe Enterprise |
| Qingdao Zhenxiong Mechanical Equipment |
| Freudenberg Sealing Technologies |
| Trelleborg Group |
| Others |
Pricing and Supply Chain Analysis
Long-term offtake agreements between EPDM compound suppliers and European extrusion specialists lock in magnetic strip feedstock access while insulating procurement teams from ethylene-propylene price swings. These contractual structures anchor cost visibility for specification-grade producers serving supermarket retrofit programs under tightening EPA and REACH compliance timelines.
Pricing Analysis
EPA energy-conservation standards and DOE commercial refrigeration test procedures dictate the pricing tier structure across North American commercial channels. Three-tier pricing structure across premium, standard, and economy levels separates FDA-compliant silicone formulations for medical refrigeration from specification-grade EPDM for supermarket retrofits and commodity PVC compounds for residential OEM supply. Cost compression in the PVC tier is intensifying because REACH and RoHS constraints are accelerating displacement toward EPDM in European channels. Quick-service restaurant chains exhibit the highest price sensitivity due to centralized procurement mandates, while laboratory cold-chain operators accept premium pricing for biocompatibility-certified silicone grades.
Supply Chain Analysis
Strategic stockpiling of magnetic ferrite powders and ethylene-propylene rubber distinguishes specification-grade producers from just-in-time operators serving price-sensitive residential OEM segments. Manufacturing concentration clusters in China, Germany, and Italy, with the Yangtze River Delta anchoring bulk extrusion capacity for appliance assembly and Bavaria hosting precision die engineering for European retrofit channels. Raw material dependencies center on petrochemical feedstocks, rare-earth magnetic powders, and specialized plasticizer chemistries. Single-source vulnerability sits with Chinese magnetic insert suppliers subject to evolving MEE volatile organic compound enforcement. Distribution runs through direct contractor relationships in Southern Europe and approved vendor lists in North American commercial foodservice networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory fragmentation across EPA, REACH, and GB standards is creating specialized formulation niches that reward focused technical capability over scale. This demand-side shift fragments procurement into jurisdiction-specific compliance tiers.
For Market Incumbents: Consolidate backward integration into magnetic insert supply to defend margin position against feedstock volatility. Secure captive EPDM compounding capacity in Germany or Italy to meet REACH documentation requirements without cross-border certification delays. Channel control through direct contractor relationships in Southern Europe offers defensive moats against wholesale intermediaries.
For New Entrants and Emerging Players: UL certification fast-track for EPA-compliant EPDM formulations opens specification-grade access to California and New York utility rebate programs. India's PLI-subsidized cold-chain buildout represents the most penetrable geography, with refrigerated warehouse operators in Maharashtra and Gujarat generating aftermarket volume as installed base ages. A go-to-market angle anchored in rapid-turnaround seal replacement services for quick-service restaurant chains bypasses entrenched approved vendor lists.
For Investors and Strategic Acquirers: Capital is best deployed toward mid-cap extrusion specialists with demonstrated fluoropolymer-adjacent compounding expertise for low-temperature industrial applications. Long-term viability hinges on regulatory chemistry capabilities that transcend commodity EPDM supply. The signal to watch is MEE enforcement intensity on volatile organic compound emissions, which would accelerate consolidation among Chinese suppliers unable to meet export-qualification protocol shifts.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Magnetic Insert Supply | Captive ferrite powder sourcing insulates margin from rare-earth price volatility under Chinese MEE enforcement. |
| EPDM Formulation Certification Investment | REACH and EPA dual compliance unlocks specification-grade access to European and North American retrofit channels. |
| Direct Contractor Distribution Expansion | Bypassing wholesale intermediaries in Southern Europe captures aftermarket service revenue from aging commercial installations. |
| Fluoropolymer-Adjacent Compounding Capacity | Low-temperature expertise below minus forty degrees Celsius differentiates supply for industrial freezer applications. |
| Geographic Expansion into Indian Cold-Chain | PLI-subsidized refrigerated warehouse buildout in Maharashtra generates systematic seal replacement demand. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with commercial refrigeration facilities managers, EPDM extrusion plant engineers, magnetic insert procurement leads, and refrigeration service contractors across North America, Europe, and Asia-Pacific. Secondary validation drew from EPA energy-conservation standard filings, ECHA REACH registration databases, Chinese GB standard documentation, customs trade records for ethylene-propylene rubber imports, and SEC filings from diversified sealing technology groups. Bottom-up unit economics for replacement cycle frequencies were triangulated against top-down market size estimates derived from appliance production data and cold-chain infrastructure investment tracking.
Across the analysis window, volume and value outputs reflect modeled segmentation across material type, application tier, thickness specification, and installation method, with regional regulatory clusters treated as distinct demand pools. CAGRs were computed from replacement cycle acceleration under energy-code enforcement, cold-chain infrastructure maturity curves, and material substitution dynamics between PVC and EPDM formulations. Industry-specific forecast inputs include utility rebate program qualification thresholds, MEE volatile organic compound enforcement trajectory, and quick-service restaurant chain procurement centralization rates.
The analysis sits within stated boundaries; outcomes outside sustained regulatory tightening on thermal leakage thresholds or petrochemical feedstock price stability would require recalibration. Forecasts reflect documented assumptions regarding replacement cycle compression and geographic demand migration. Revision becomes warranted when Chinese export-qualification protocol shifts or Indian cold-chain subsidy intensity crosses thresholds that alter installed base aging dynamics.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Appliances
Bahrain Microwave Ovens Market
Appliances
France Household Side by Side Refrigerator Market
Appliances
Asia-Pacific Electric Rice Cooker Market
Appliances
Smart Dishwasher Market
Appliances
Small Appliances Market
Appliances
Water Dispenser Market
Appliances
Saudi Arabia Gas Hobs Market
Appliances
Space Heaters Market
Appliances
United States Washing Machine Market
Appliances
Digital Showers Market
Appliances
Colombia Laundry Appliances Market
Appliances
Minibar Refrigerators Market
Appliances
Tumble Dryer Market
Appliances
Shared Shoe Washing Machine Market
Appliances
Large Cooking Appliance Market
Appliances
Bhutan and Nepal White Goods Market