
 Portable Fridges Market | 2026-2036
Portable Fridges Market Size, Share, and Industry Trends Forecast 2026-2036
Portable Fridges Market Analytics
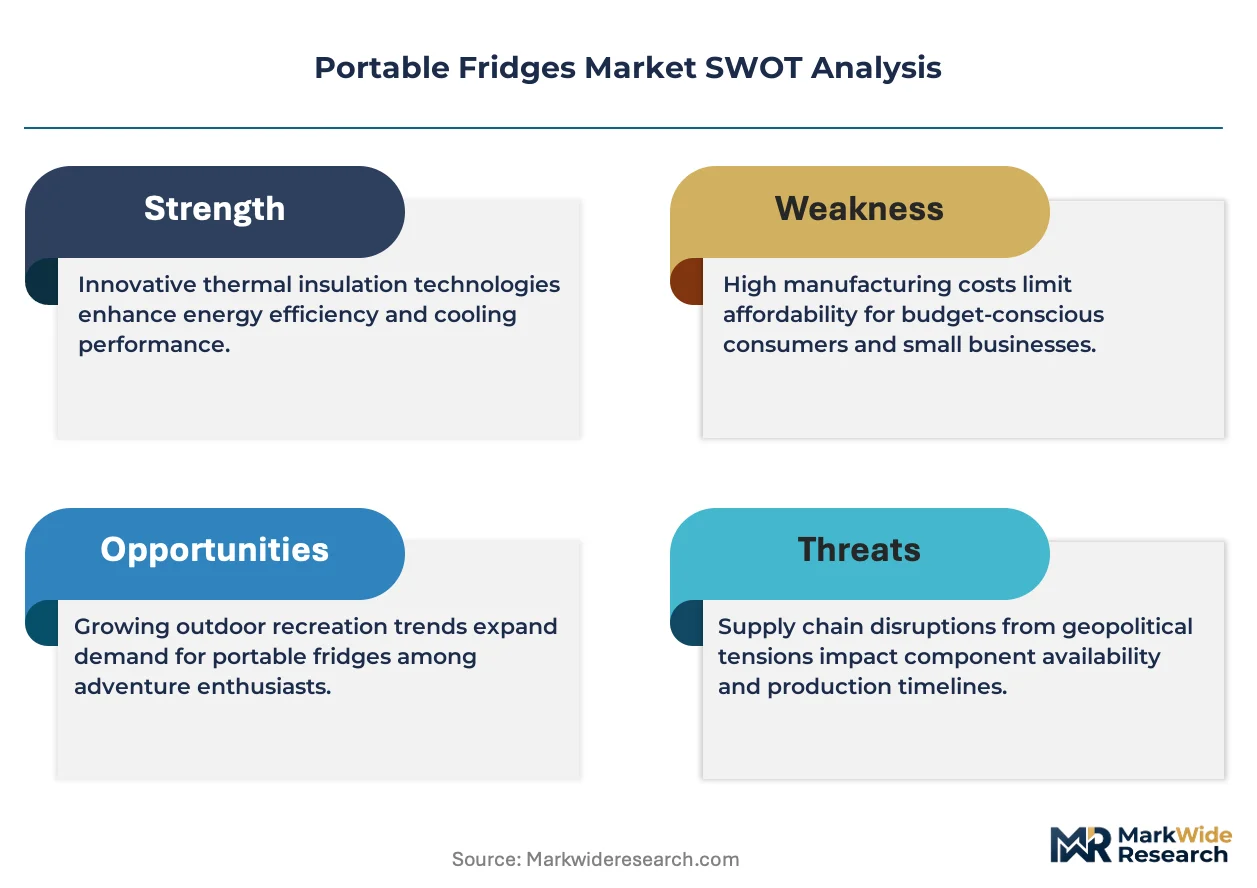
Direct-to-consumer online channels is tilting the competitive balance away from traditional retail networks. Dometic Group AB leverages its established marine and RV heritage to dominate premium outdoor segments. Haier Group Corporation anchors volume production through massive Chinese manufacturing bases. Alpicool competes aggressively on price in the entry-level compressor category through streamlined e-commerce fulfillment.
Portable fridges are self-contained cooling units designed for mobile deployment, typically employing vapor-compression, absorption, or thermoelectric refrigeration cycles with power draws ranging from 12V DC to 240V AC inputs. These units preserve perishables in off-grid environments where grid electricity remains unavailable, serving commercial fleets, emergency responders, and recreational users alike. Compressor fridges capture the dominant share of value as efficiency thresholds rise and lithium battery pairing becomes standard. Thermoelectric variants occupy the budget tier where cooling speed and ambient temperature tolerance matter less than acquisition cost. The 31L-50L capacity bracket leads unit shipments among road travelers seeking balanced cargo space against cooling volume.
The US Department of Energy enforces minimum efficiency standards through its appliance certification program, while the EPA's SNAP program governs refrigerant selections affecting compressor design trajectories. China's GB standards and MIIT circular economy directives shape domestic manufacturing requirements and export compliance simultaneously. Stakeholders must track refrigerant phase-down schedules and battery chemistry regulations as these twin forces redefine product architecture and supply chain sourcing decisions.
Market Dynamics
Compressor efficiency mandates from the US Department of Energy are forcing simultaneous redesign of refrigeration cycles and power electronics across the portable cooling sector. Lithium battery pairing requirements are compressing development timelines as manufacturers race to integrate bidirectional charging and solar compatibility.
Growth Catalysts
- EPA SNAP refrigerant phase-down:The program accelerates adoption of low-GWP alternatives, compelling compressor redesigns that improve thermal efficiency and extend operational range in extreme ambient temperatures.
- Outdoor recreation participation:Camping and overlanding segments drive demand for ruggedized 12V/24V DC units with vibration tolerance and off-grid autonomy measured in days rather than hours.
- Lithium iron phosphate chemistry:Cell cost declines and energy density improvements enable true portable operation without generator dependency, opening remote commercial applications from medical transport to field research.
Market Restraints
- Copper and rare-earth magnet volatility:Compressor motor laminations depend on neodymium supply concentrated in Chinese processing facilities, exposing margins to export quota fluctuations.
- Thermoelectric performance ceiling:Peltier devices face hard physics limits on delta-T and COP, locking them out of high-ambient or rapid-cooling applications regardless of price positioning.
- China MIIT circular economy compliance:Extended producer responsibility rules impose recovery and recycling costs that compress margins on entry-tier export volumes.
Strategic Opportunities
- India PLI scheme for advanced chemistry cells:Domestic battery manufacturing incentives create localized supply chains for South Asian and Middle Eastern export markets currently served from Chinese ports.
- Telematics integration:Fleet operators seek GPS-tracked, temperature-logged units for pharmaceutical and food-service compliance, creating recurring SaaS revenue streams atop hardware sales.
- EU F-Gas Regulation tightening:The 2024-2030 phase-down schedule rewards early movers with R290 (propane) or R600a (isobutane) compressor platforms that lock in specification advantages for European tenders.
Industry Challenges
- Thermodynamic simulation talent scarcity:Refrigeration cycle optimization requires specialized CFD and two-phase flow expertise that commands premium compensation and extends recruitment cycles.
- Dual-certification timelines:Simultaneous UL (North America) and CE (Europe) testing for new refrigerant platforms stretches product launch windows by 8-14 months.
- Legacy 12V electrical integration:Automotive and marine electrical systems vary by manufacturer and model year, forcing extensive harness and protection circuit customization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Portable Fridges Market |
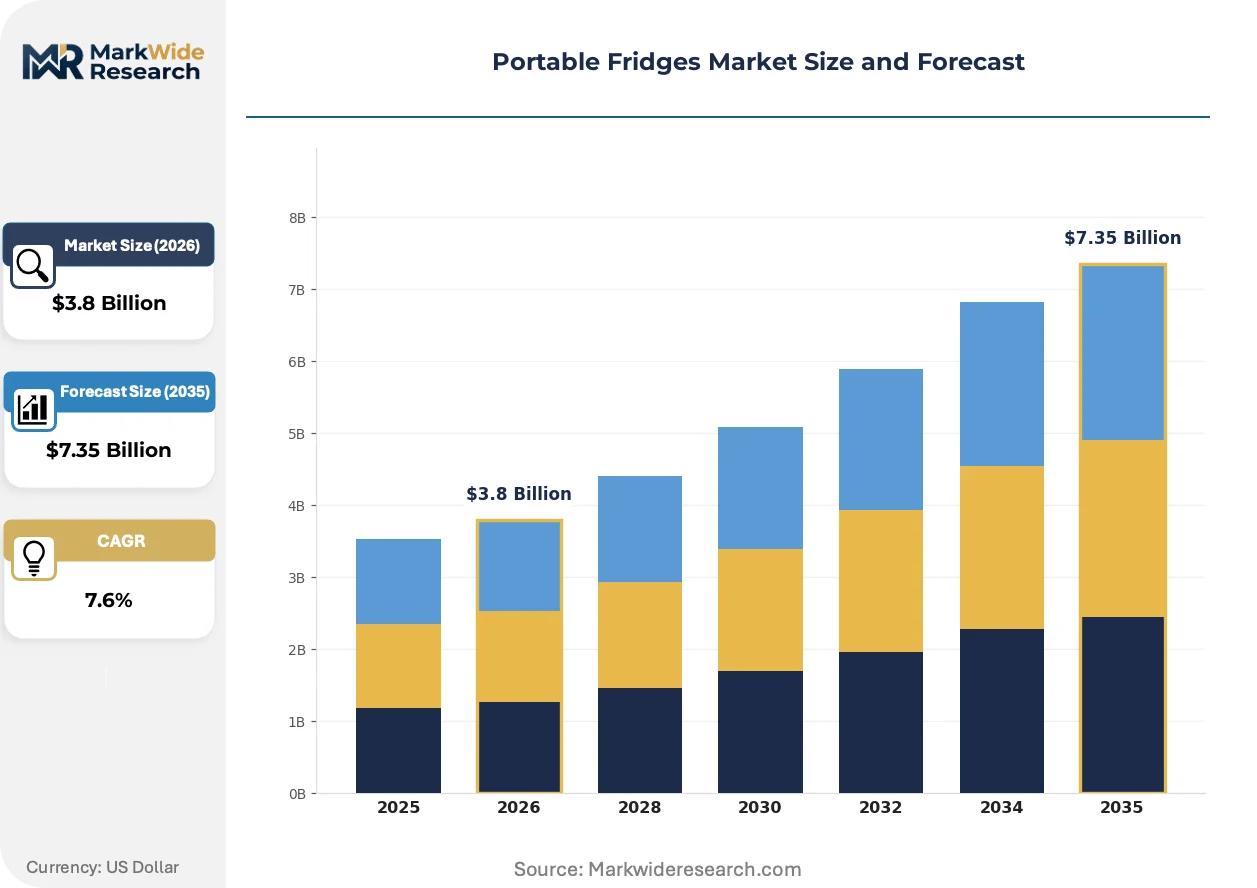
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $7.35 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Absorption Fridges, Compressor Fridges, Thermoelectric Fridges, Mini Fridges Power Source: Battery-Powered, Solar-Powered, Mains Electric, LPG End User: Camping Enthusiasts, Road Travelers, Outdoor Events, Emergency Services Capacity: 15L-30L, 31L-50L, 51L-70L, Above 70L |
| Companies Covered | Dometic Group AB, ARB USA, Danby Products Limited, Haier Group Corporation, Whynter LLC, Alpicool, Whirlpool Corporation, Panasonic Corporation, LG Electronics Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Portable Fridges Market Evolving Landscape
Digital twin and simulation technologies are compressing prototype cycles while predictive maintenance capabilities reshape ownership economics. Three convergent forces are redefining product architecture and go-to-market approaches.
Variable-speed inverter compressors with brushless DC motors are virtualizing the traditional on/off refrigeration cycle. Overlanding and expedition vehicle builders specify these units for their 40-60% energy savings against fixed-speed alternatives. The technology is virtualizing the distinction between automotive and stationary cooling applications, as identical hardware platforms serve both markets through firmware configuration.
The EU F-Gas Regulation's stepped HFC reduction targets are redirecting R&D investment toward hydrocarbon and CO2 trans-critical cycles. Compressor manufacturers must retool sealing and safety systems to handle flammable refrigerants at higher pressures. European commercial fleet operators are responding fastest, embedding propane-compatible units in pharmaceutical transport specifications ahead of 2027 mandates.
Direct-to-consumer fulfillment via manufacturer-owned storefronts and specialized outdoor retail platforms is fragmenting traditional distribution. Specialty e-commerce channels capture enthusiast segments willing to pay premium prices for technical validation and community endorsement. This pattern concentrates in Australia and the western United States, where dispersed populations and high outdoor recreation participation reward digital-first purchasing over mass retail presence.
Portable Fridges Market Segmentation
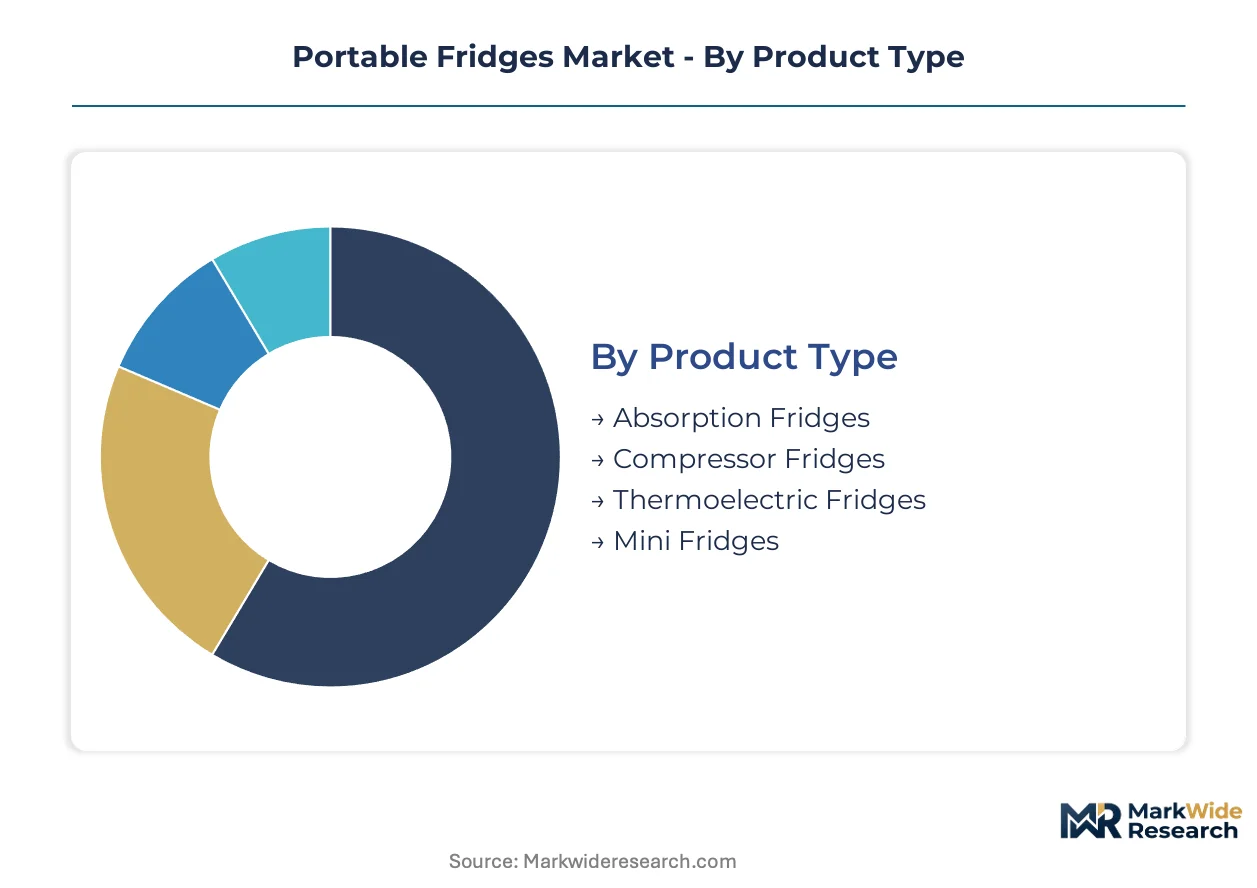
Portable fridge purchasing decisions split sharply between recreational autonomy needs and commercial duty-cycle requirements. Segment boundaries increasingly blur as compressor platforms adapt across power sources and capacity tiers through modular electronics.
Product Type:
Compressor fridges turn inventory fastest in outdoor retail channels, while absorption units linger longest in marine and RV OEM pipelines. Thermoelectric variants cycle rapidly through mass-market e-commerce with minimal technical pre-sale support.
- Compressor Fridges:Vapor-compression cycles with brushless DC motors deliver 40-60% energy savings against fixed-speed alternatives. Demand concentrates among overlanding vehicle builders in Australia and the western United States seeking multi-day off-grid autonomy. Lithium battery pairing has become standard specification.
- Thermoelectric Fridges:Peltier devices operate without moving parts but face hard physics limits on coefficient of performance and delta-T capability. Budget-conscious road travelers in entry-level segments accept slower cooling speeds in exchange for acquisition cost advantages.
- Absorption Fridges:Ammonia-based cycles operate silently on LPG or electric inputs, suiting marine and RV installations where noise restrictions apply.
- Mini Fridges:Compact thermoelectric or compressor units target dormitory, office, and hospitality applications with limited cargo requirements.
Compressor fridges dominate installed base. Thermoelectric variants are where expansion concentrates for price-sensitive first-time buyers.
Power Source:
Cost tier structure separates premium lithium-integrated systems from economy mains-dependent units, with solar-hybrid configurations commanding mid-tier positioning.
- Battery-Powered:Lithium iron phosphate cell integration enables true portable operation without generator dependency. Camping enthusiasts and emergency responders in remote geographies drive specification requirements for multi-day runtime.
- Solar-Powered:Photovoltaic panel pairing with MPPT charge controllers extends autonomy indefinitely in high-irradiance conditions. Field research stations and off-grid medical transport in sub-Saharan Africa and South Asia represent concentrated demand pockets.
- Mains Electric:120V/240V AC operation limits mobility to grid-connected environments but minimizes unit cost and complexity.
- LPG:Propane absorption systems serve RV and marine installations where electrical load management is constrained.
Battery-powered units dominate installed base. Solar-powered configurations are where expansion concentrates for sustainability-motivated segments.
End User:
Application intensity varies dramatically: emergency services demand 24/7 reliability with temperature logging, while outdoor events prioritize rapid deployment over precision control.
- Camping Enthusiasts:Backpacking and overlanding participants require ruggedized 12V/24V DC units with vibration tolerance and weatherproofing. This segment is climbing the fastest as outdoor recreation participation expands across North America and Australia.
- Road Travelers:Long-haul truckers and van-life converts balance cooling volume against cargo space constraints. The 31L-50L capacity bracket leads unit shipments among this cohort.
- Outdoor Events:Catering vendors and festival operators need rapid-deployment cooling with minimal setup complexity.
- Emergency Services:Medical transport and disaster response teams require GPS-tracked, temperature-logged units for pharmaceutical and blood product compliance.
Road travelers dominate installed base. Camping enthusiasts are where expansion concentrates.
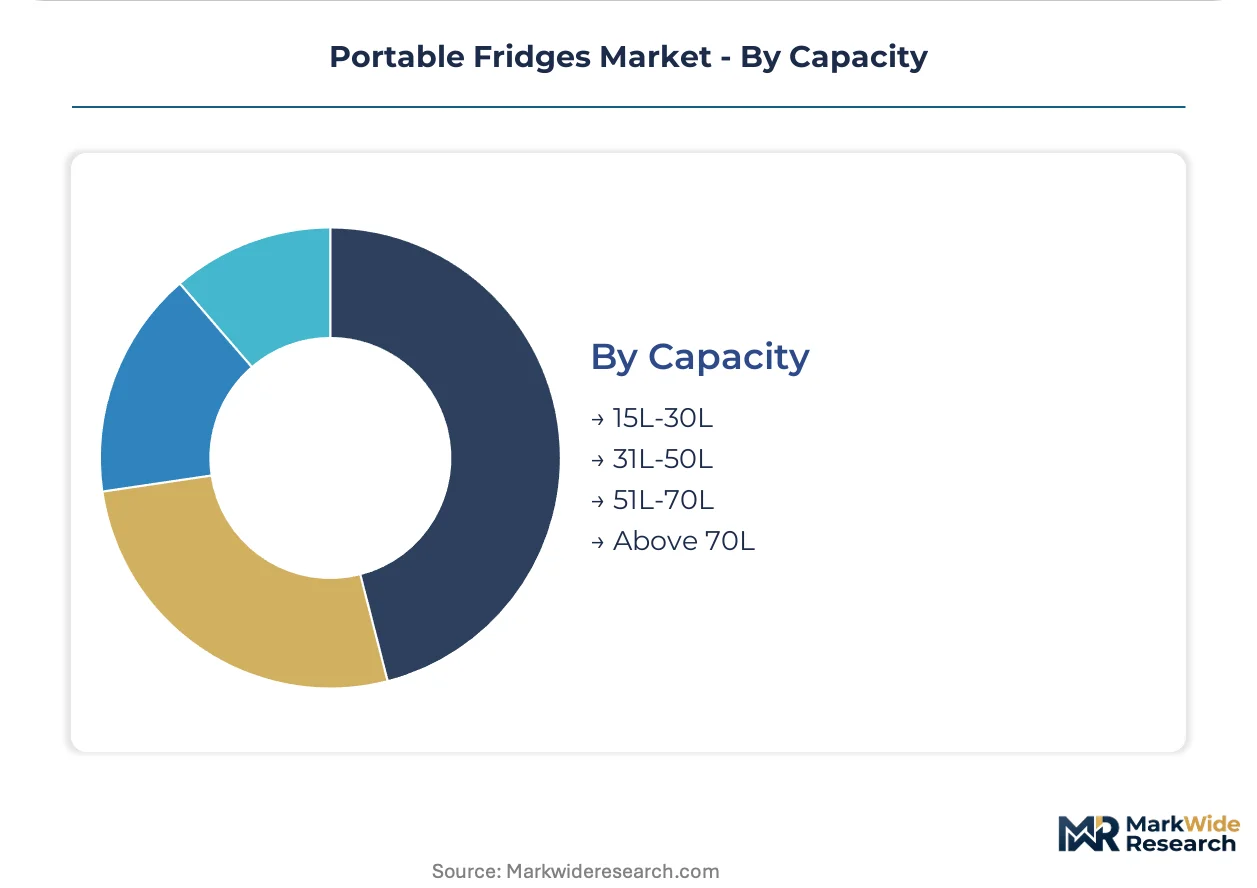
Capacity:
Volume tier alignment maps directly to vehicle integration constraints and trip duration requirements, with mid-capacity units capturing the broadest addressable demand.
- 31L-50L:Balanced cooling volume against cargo space requirements suits extended road trips and weekend camping excursions. This bracket leads unit shipments among recreational users seeking versatility without excessive weight penalties.
- 15L-30L:Compact footprints fit passenger vehicle footwells and motorcycle panniers for solo travelers and day-trip applications. Urban apartment dwellers seeking secondary refrigeration drive secondary demand.
- 51L-70L:Family-scale cooling supports week-long expeditions and commercial catering operations with moderate payload requirements.
- Above 70L:Expedition-grade and commercial fleet specifications accommodate multi-week autonomy and high-volume perishable transport.
31L-50L units dominate installed base. Above 70L configurations are where expansion concentrates for commercial fleet operators.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Shanghai anchors Asia-Pacific logistics for compressor components and finished refrigeration units, while the Trans-Australian Railway underpins distribution networks spanning the continent's remote interior markets.
United States
Overlanding vehicle builders in the western states drive specification demand for lithium-integrated 12V DC units. The EPA's SNAP refrigerant phase-down program compels compressor redesigns toward low-GWP alternatives. Manufacturing clusters concentrate in Michigan and Ohio where automotive supplier networks support brushless DC motor production.
China
Domestic manufacturing scale and export volume expansion concentrate demand in coastal provinces. The MIIT's circular economy directives impose extended producer responsibility rules on recovery and recycling costs. The Yangtze River Delta hosts compressor motor lamination facilities serving global OEM supply chains.
Germany
Commercial fleet operators prioritize pharmaceutical transport compliance with GPS-tracked temperature logging. The EU F-Gas Regulation's 2024-2030 phase-down schedule accelerates R290 and R600a hydrocarbon compressor adoption. Industrial R&D clusters in Bavaria specialize in trans-critical CO2 cycle development for mobile cooling.
Australia
Dispersed populations and high outdoor recreation participation reward digital-first purchasing channels for ruggedized expedition units. The Australian Energy Regulator oversees grid interconnection standards affecting solar-hybrid system specifications. Queensland and Western Australia host field research stations driving solar-powered medical transport demand.
India
Emergency responders and remote medical transport operators seek multi-day battery autonomy without generator dependency. The PLI scheme for advanced chemistry cells incentivizes domestic lithium iron phosphate manufacturing. Gujarat and Maharashtra are developing localized supply chains for South Asian and Middle Eastern export markets.
Portable Fridges Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream supplying compressors, power electronics, and thermal management subsystems. The vendor base stratifies across three tiers: multinational appliance conglomerates with captive distribution networks, outdoor recreation specialists leveraging marine and RV heritage, and price-focused entrants optimizing e-commerce fulfillment velocity. Strategic moves concentrate on M&A for refrigerant platform access and capacity expansion in lithium battery pairing capabilities.
Within the heritage outdoor tier, Dometic Group AB and ARB USA exemplify positioning built on marine and expedition vehicle integration expertise. Haier Group Corporation anchors the volume manufacturing archetype through Chinese production base scale. Alpicool occupies the entry-level compressor segment where streamlined direct-to-consumer fulfillment displaces traditional retail intermediaries.
| Leading Market Players |
|---|
| Dometic Group AB |
| ARB USA |
| Danby Products Limited |
| Haier Group Corporation |
| Whynter LLC |
| Alpicool |
| Whirlpool Corporation |
| Panasonic Corporation |
| LG Electronics Inc. |
| Others |
Value Network & Pricing Analysis
Copper and rare-earth magnet volatility compresses margin structures across entry-tier and premium segments alike, forcing manufacturers to choose between absorbing cost spikes or pushing price increases through concentrated retail channels. This input-cost uncertainty widens spreads between lithium-integrated premium units and mains-dependent economy alternatives while reshaping sourcing footprints toward tariff-advantaged assembly locations.
Pricing Analysis
Volume-discount tiering structures separate expedition-grade compressor platforms with brushless DC motors from thermoelectric entry units through certification grade and after-sales bundling differentiation. Pricing stratifies across premium, standard, and economy tiers where UL/CE dual-certification investments add margin capture for overlanding specialists. Cost compression in the thermoelectric category is intensifying because Peltier device commoditization attracts price-focused e-commerce entrants. Road travelers exhibit highest price sensitivity among recreational segments, while emergency services prioritize temperature-logging compliance over acquisition cost.
Supply Chain Analysis
Contract-manufacturing concentration in the Yangtze River Delta and Pearl River Delta anchors global compressor motor lamination capacity, with secondary clusters in South Korea and Japan supplying precision power electronics. Neodymium magnet processing draws from Chinese facilities, copper windings rest on Chilean and Peruvian concentrate flows, and lithium iron phosphate cells hinge on domestic Chinese cathode production. Single-source vulnerability in rare-earth magnet supply exposes margins to export quota fluctuations. Distribution runs through manufacturer-owned digital storefronts and specialized outdoor retail platforms that fragment traditional wholesale networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among fleet operators and direct-to-consumer platforms, compressing incumbent margin structures as procurement scales shift toward volume-contracting specialists and digital-native aggregators.
For Market Incumbents: Entrench position through captive lithium battery pairing capabilities and R&D investment in hydrocarbon refrigerant platforms ahead of EU F-Gas mandates. Compressor motor lamination capacity expansion in tariff-advantaged geographies defends against supply disruption. Certification investment in UL/CE dual-labeling locks in specification advantages for pharmaceutical transport tenders. For New Entrants and Emerging Players: Solar-hybrid configurations in sub-Saharan African field research stations offer white-space penetration with minimal incumbent presence. India's PLI-scheme battery manufacturing incentives create localized assembly opportunities for South Asian and Middle Eastern export markets. Direct-to-consumer fulfillment through specialized outdoor retail platforms bypasses wholesale margin extraction. For Investors and Strategic Acquirers: The EPA SNAP refrigerant phase-down reshapes the acquisition landscape toward compressor redesign specialists with low-GWP platform expertise. Long-term viability centers on R290/R600a hydrocarbon capability and lithium integration scale. Platform integrators with marine and RV heritage command premium multiples. The signal to watch is EU tender specifications embedding 2027 hydrocarbon mandates as inflection indicator.| Strategic Initiative | Industry Significance |
|---|---|
| Refrigerant Platform Transition | R290 and R600a compressor adoption locks in European pharmaceutical transport compliance ahead of F-Gas deadlines. |
| Lithium Battery Integration | LFP cell pairing enables multi-day off-grid autonomy for camping and emergency responder segments. |
| Direct-to-Consumer Channel Buildout | Manufacturer-owned storefronts capture enthusiast margins and technical validation data from dispersed populations. |
| Telematics and SaaS Layer Development | GPS-tracked temperature logging creates recurring revenue atop hardware sales for fleet compliance. |
| Geographic Manufacturing Diversification | India PLI-scheme assembly reduces tariff exposure and serves Middle Eastern export markets. |
Research Methodology
Desk research of customs trade records, appliance efficiency certification databases, and refrigerant phase-down regulatory filings preceded structured interviews with compressor OEM procurement directors, outdoor retail category managers, fleet operations executives, and lithium battery system integrators. Primary fieldwork validated shipment volumes and pricing trajectories through bottom-up channel checks and top-down production capacity assessments. Triangulation across these sources anchored segmentation splits and growth rate derivations.
Assumptions held fixed include EPA SNAP refrigerant schedules, EU F-Gas Regulation phase-down timelines, and MIIT circular economy compliance costs across the projection horizon. The analytical framework modeled product type, power source, end-user application, capacity tier, and regional regulatory cluster as primary segmentation dimensions. CAGRs were derived from fitted growth curves against historical shipment data and forward-looking capacity expansion announcements. Compressor efficiency thresholds and lithium cell cost decline curves served as key forecast inputs.
The forecast holds incumbent behavior within observed patterns; aggressive capacity addition by Chinese manufacturing conglomerates or accelerated refrigerant platform transitions by European specialists would shift outcomes. Quarterly review of neodymium export quota announcements, EU tender specification releases, and EPA certification timeline updates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Appliances
Dishwasher Market
Appliances
APAC White Goods Market
Appliances
Domestic Food Preparation Appliances Market
Appliances
Colombia Appliances and Electronics Market
Appliances
Electric Kettle Market
Appliances
Built-In Large Cooking Appliance Market
Appliances
Triple Barrel Waver Market
Appliances
Household Beauty Appliances Market
Appliances
United Kingdom Tumble Dryers Market
Appliances
Electric Dryers Market
Appliances
Commercial Microwave Ovens Market
Appliances
Europe Induction Hobs Market
Appliances
Portable Mini Fridge Market
Appliances
Electric Hand Dryer Market
Appliances
Global Home Ice Maker Market
Appliances
Portable Dishwasher Market