
 Rooftop Tent Market | 2026-2036
Rooftop Tent Market Size, Share, and Industry Trends Forecast 2026-2036
Rooftop Tent Market Insights
Chinese aluminum extrusion capacity is restructuring supply economics for hard-shell rooftop tent manufacturers worldwide. iKamper leverages direct-to-consumer digital channels to sustain margin capture across North American and European markets. Thule/Tepui anchors its position through rack-system compatibility that locks in ecosystem-driven repeat purchases. ARB competes in Australasia by dominating expedition-grade distribution through dedicated 4WD retail networks.
A rooftop tent is a vehicle-mounted shelter system engineered from aluminum, fiberglass, or reinforced fabric composites, typically rated for dynamic wind loads and static roof-bar capacities between 100 and 300 pounds. Its primary commercial purpose is to provide elevated sleeping quarters that detach from ground conditions, expanding vehicle utility for remote camping and extended overland travel. Hard-shell variants command premium positioning due to aerodynamic efficiency and rapid deployment mechanics, while soft-shell configurations occupy volume tiers through lighter weight and lower price points. The overlanding application segment leads growth trajectory as dedicated adventure travel infrastructure expands across backcountry corridors.
FCC certification governs integrated electronics such as LED lighting and ventilation systems in US-bound rooftop tent shipments, while ECE R14-02 anchorage standards regulate rack-mounted safety across European type approvals. ISO 11154 roof load testing protocols determine market access eligibility for cross-border OEM accessory programs. Stakeholders must monitor evolving vehicle electrification platforms, as battery placement and roof structural redesigns in electric SUVs reshape compatibility requirements and load-rating assumptions.
Market Dynamics
Vehicle electrification is forcing fundamental redesigns of rooftop load-bearing structures, as battery placement in electric SUVs alters center-of-gravity calculations and roof-rack mounting geometries that tent systems depend upon.
Growth Catalysts
- ISO 11154 roof load testing:Standardized certification protocols enable cross-border OEM accessory programs, unlocking factory-integrated distribution channels previously closed to aftermarket suppliers.
- Overlanding infrastructure expansion:Dedicated backcountry corridor development across Australia and the western United States creates pull-through demand for expedition-grade shelter systems.
- Aluminum extrusion supply restructuring:Chinese capacity expansion compresses input costs for hard-shell manufacturers, lowering barriers to premium product tier entry.
Market Restraints
- Dynamic wind load certification costs:FCC testing for integrated electronics and ECE R14-02 anchorage validation impose fixed compliance burdens that disproportionately constrain small-scale manufacturers.
- Roof-bar capacity fragmentation:Vehicle-specific static load ratings between 100 and 300 pounds force SKU proliferation and inventory complexity across OEM compatibility matrices.
- Ground tent substitution:Lightweight backpacking shelters and towable camper trailers capture price-sensitive segments unwilling to accept rooftop aerodynamic penalties.
Strategic Opportunities
- European CSRD alignment:Sustainability reporting mandates create preference for repairable, recyclable hard-shell designs with documented material provenance.
- Direct-to-consumer channel maturation:Digital-native brands bypass traditional outdoor retail markups, capturing margin and customer relationship data simultaneously.
- EV platform native integration:Collaboration with electric SUV manufacturers on roof-structure co-design enables locked-in accessory ecosystem positioning.
Industry Challenges
- Vehicle compatibility database maintenance:Continuous model-year updates across global OEM portfolios require dedicated technical resources and real-time validation workflows.
- Cross-border certification timeline compression:Simultaneous pursuit of FCC, ECE, and ISO approvals extends product launch windows and strains regulatory affairs capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Rooftop Tent Market |
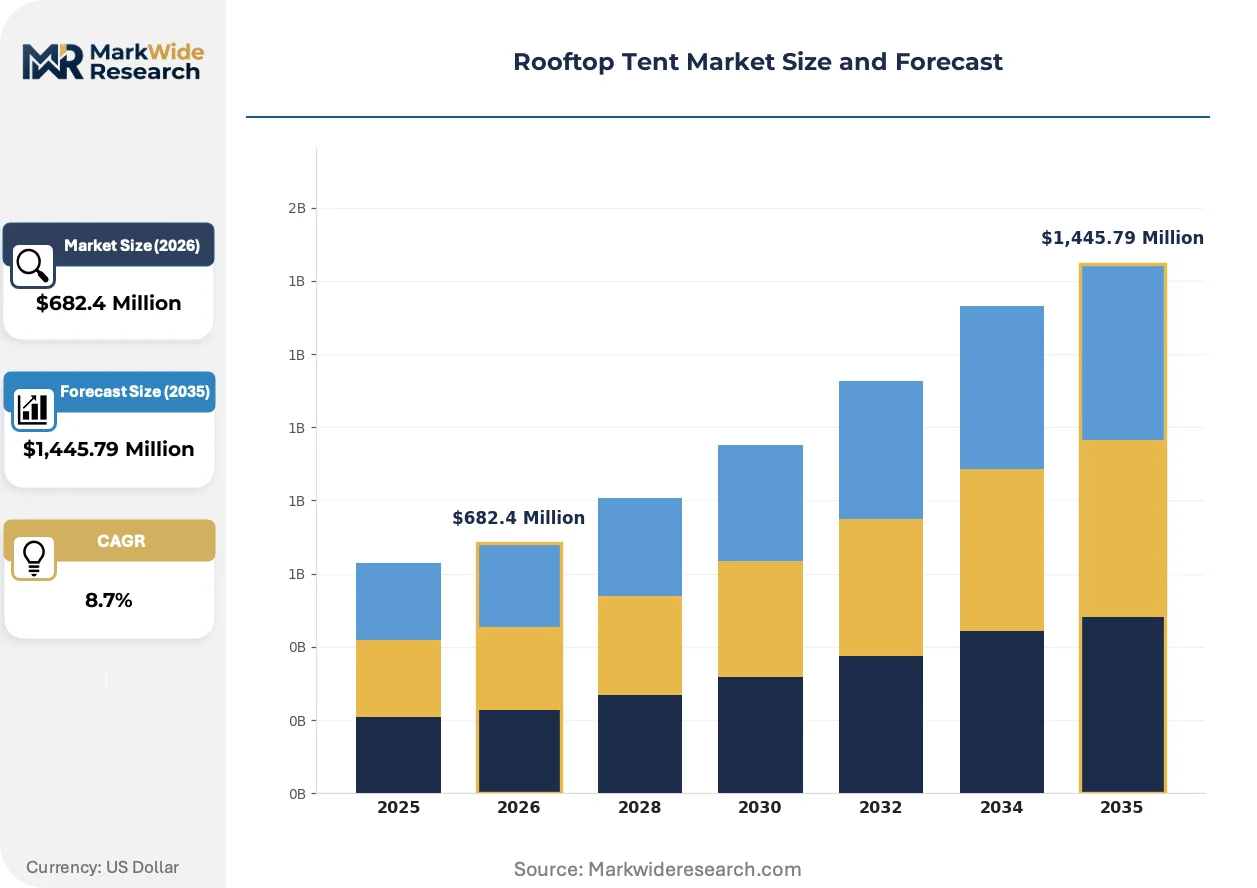
| Market Size in 2026 | $682.4 Million |
| Market Size in 2035 | $1,445.79 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hard-shell, Soft-shell, Semi-rigid, Expandable Material: Aluminum, Polyester, Canvas, Fiberglass Application: Camping, Overlanding, Adventure Travel, Off-roading Attachment Type: Clamp-on, Rack-mounted, Trailer-mounted, Integrated |
| Companies Covered | James Baroud, Thule/Tepui, iKamper, Overland Vehicle Systems, Smittybilt, Roofnest, ARB, Darche, Alu-Cab, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Rooftop Tent Market Trends and Innovations
Deployment mechanism automation and integrated electronics standardization are compressing setup times and expanding climate-control capabilities, while regulatory pressure on vehicle efficiency forces aerodynamic optimization trade-offs.
Gas-strut-assisted hard-shell opening is automating what previously required manual lifting and locking, reducing deployment time from minutes to seconds. Overlanding enthusiasts and solo travelers are adopting these systems fastest, prioritizing rapid camp establishment in remote settings. This automation is compressing the functional differentiation between rooftop and ground-based shelter options.
EU F-Gas Regulation phase-down is restricting hydrofluorocarbon-based insulation foams used in thermal-efficient hard-shell designs, forcing material substitution toward vacuum panels or aerogel composites. Manufacturers serving European markets face reformulation timelines that overlap with product refresh cycles. Hard-shell variants with climate-control aspirations are absorbing the highest compliance burden and accelerating supplier qualification processes.
Subscription-based accessory bundling is displacing single-transaction retail models, with buyers expecting rack systems, awnings, and annex rooms as configurable packages rather than separate purchases. Specialty outdoor retailers and dedicated overlanding outfitters are losing share to platform-integrated configurators that simulate complete vehicle setups. Australia and the western United States exhibit the fastest behavioral transition, where established touring cultures normalize higher initial outlays for ecosystem completeness.
Rooftop Tent Market Segmentation
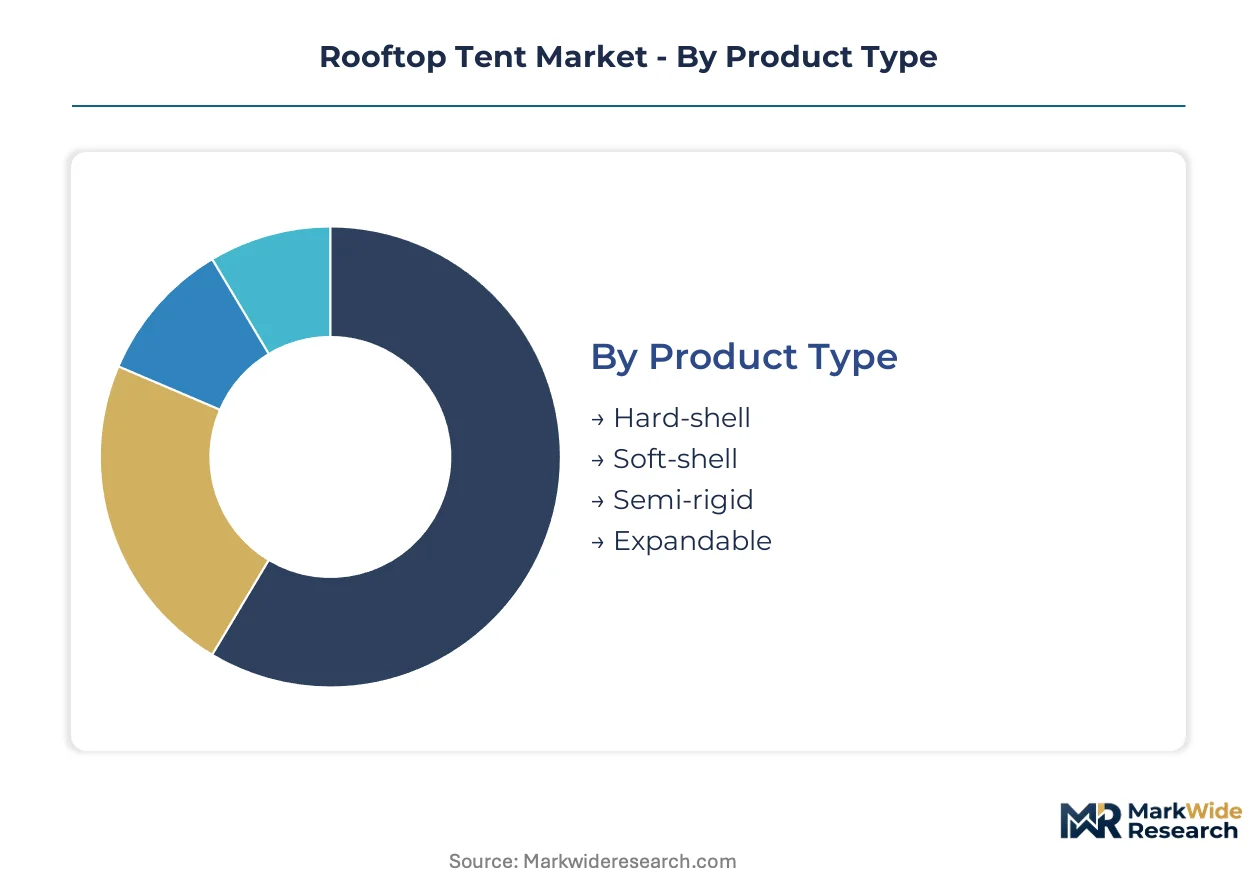
Product architecture in rooftop tents determines manufacturing capital requirements, supply chain complexity, and aftermarket service infrastructure. Segment boundaries reflect divergent technical competencies among suppliers and distinct buyer willingness-to-pay across use cases.
Product Type:
Capital intensity varies sharply across deployment mechanisms, with automated hard-shell systems requiring precision molding equipment and gas-strut inventory that soft-shell competitors avoid entirely.
- Hard-shell:Gas-strut-assisted clamshell or pop-top designs in aluminum or fiberglass composites achieve sub-60-second deployment. Australian overlanding corridors and western US backcountry routes concentrate demand, driven by solo travelers prioritizing rapid camp establishment and weather sealing.
- Soft-shell:Fabric canopy systems with collapsible aluminum or composite frames fold into compact storage profiles. Entry-level pricing and reduced vehicle weight penalties attract price-sensitive campers in European markets where fuel efficiency regulations tighten.
- Semi-rigid:Hybrid constructions combine rigid base panels with fabric upper sections, balancing aerodynamics with partial automation. Weekend recreational users in Germany and France favor this compromise tier.
- Expandable:Modular annex attachments and slide-out sleeping platforms extend footprint beyond vehicle roofline. Extended-stay overlanders in Australia's remote touring networks drive adoption for base-camp functionality.
Hard-shell absorbs the bulk of installed capacity; expandable configurations are expanding most quickly.
Material:
Input cost volatility and regional supply availability shape procurement strategies, with aluminum extrusion capacity concentration in China restructuring competitive economics for premium manufacturers.
- Aluminum:Extruded and sheet-grade alloys form hard-shell bases, ladder frames, and rack interfaces. Australian manufacturers source heavily from Chinese capacity expansions that compress input costs.
- Polyester:Ripstop and coated synthetic fabrics dominate soft-shell canopies for UV resistance and packability. Volume production concentrates in Vietnam and Bangladesh textile corridors serving European and North American brands.
- Canvas:Heavy-duty cotton or cotton-polyester blends offer breathability and durability for extended overland expeditions. South African and Australian expedition-grade suppliers maintain premium positioning through material provenance.
- Fiberglass:Reinforced polymer shells deliver aerodynamic profiles and thermal insulation in hard-top variants. EU F-Gas Regulation compliance costs are forcing reformulation timelines for insulation-integrated designs.
Aluminum commands the largest share of material throughput; fiberglass is climbing the fastest on electrification-driven aerodynamic requirements.
Application:
End-use differentiation determines distribution channel selection, with overlanding specialists requiring technical consultation that mass retail camping channels cannot provide.
- Camping:Recreational weekend use with emphasis on setup simplicity and family accommodation. State park systems in California, Colorado, and Queensland drive seasonal demand concentration.
- Overlanding:Multi-day vehicle-dependent travel through remote corridors without fixed infrastructure. Australia's Canning Stock Route and Utah's White Rim Trail represent corridor-specific demand nodes.
- Adventure Travel:Guided and self-guided tourism incorporating vehicle-based lodging. East African safari circuits and Patagonian route networks expand addressable market for rental-fleet configurations.
- Off-roading:Technical terrain traversal with shelter as secondary to vehicle capability. Moab, Utah and Australia's Simpson Desert attract enthusiasts prioritizing rack-system integration over sleeping comfort.
Camping retains the broadest installed base; overlanding is gaining share fastest on dedicated corridor development.
Attachment Type:
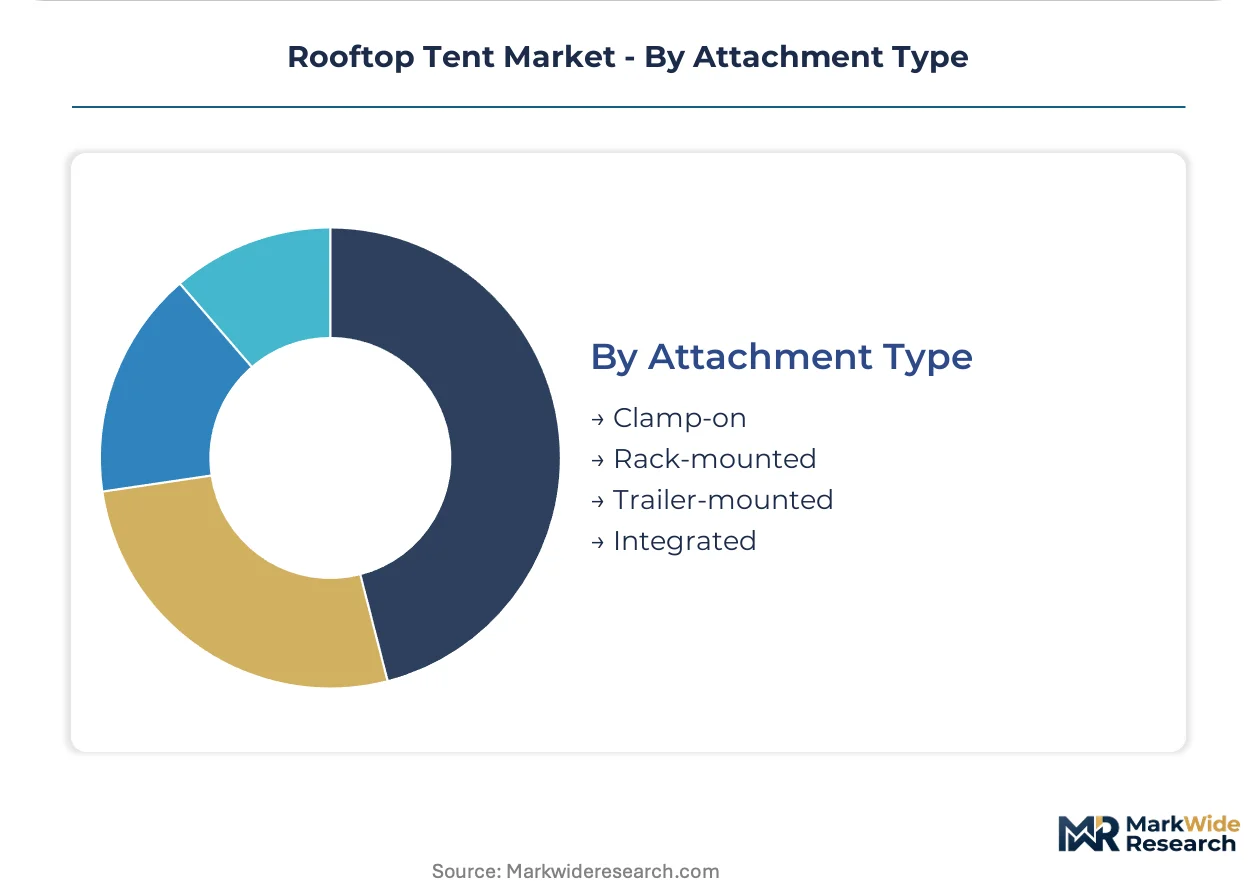
Mounting geometry compatibility creates vehicle-specific SKU requirements, with rack-mounted systems dominating due to ISO 11154 certification enabling cross-border OEM programs.
- Clamp-on:Direct gutter or door-frame attachment without roof rack, common in legacy 4WD platforms. Australian and South African markets retain demand for older Toyota Land Cruiser and Defender configurations.
- Rack-mounted:Cross-bar or platform rack systems with standardized load ratings. Thule, Yakima, and Rhino-Rack compatibility locks dominate North American and European aftermarket distribution.
- Trailer-mounted:Dedicated overland or utility trailer integration for base-camp deployment. US western states and Australian caravan parks drive adoption for extended-stay mobility.
- Integrated:Factory-installed or dealer-fit OEM accessory programs. Volkswagen, Ford, and Toyota approved-accessory pipelines in Germany, US, and Japan represent emerging channel expansion.
Rack-mounted systems absorb dominant capacity share; integrated configurations are expanding most quickly through OEM co-development programs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chinese aluminum extrusion clusters in Guangdong and Shandong provinces supply raw material for hard-shell manufacturers worldwide, creating supply chain dependencies that shape regional market development.
United States
Western backcountry corridor expansion across Utah, Colorado, and California drives overlanding equipment demand. FCC certification governs integrated electronics in US-bound shipments. Denver and Salt Lake City host the densest concentration of specialty retailers and installation service providers.
Australia
Remote-area touring culture sustains premium hard-shell adoption rates unmatched elsewhere. TGA and ISO 11154 compliance requirements structure product certification for domestic and export sales. Brisbane and Perth anchor expedition-grade distribution networks serving the Canning Stock Route and Simpson Desert corridors.
Germany
Weekend recreational camping and EV platform integration priorities reshape buyer preferences. ECE R14-02 anchorage standards and EU F-Gas Regulation constrain product design options. Stuttgart and Munich concentrate OEM co-development programs with Volkswagen and automotive supplier networks.
China
Domestic overlanding culture emergence and manufacturing scale advantages position suppliers for export growth. MIIT vehicle accessory regulations and GB standards govern domestic market entry. Guangzhou and Qingdao industrial zones integrate aluminum extrusion, precision molding, and final assembly capabilities.
South Africa
Expedition-grade canvas and hybrid designs serve regional safari tourism and export markets. National Regulator for Compulsory Specifications enforces load-rating and safety standards. Cape Town and Johannesburg host design studios and testing facilities serving sub-Saharan African overland routes.
Rooftop Tent Market Competitive Landscape
Global majors compete with regional champions across distribution channel access and vehicle compatibility database depth. The vendor base organizes into three tiers: integrated automotive suppliers with OEM pipelines, direct-to-consumer digital natives with margin capture advantages, and regional expedition specialists with terrain-specific expertise. Consolidation pressure concentrates among mid-scale manufacturers lacking certification bandwidth for simultaneous FCC, ECE, and ISO approvals. Strategic moves center on OEM co-development partnerships and direct-to-consumer channel buildouts that bypass traditional outdoor retail markups.
Within the integrated automotive tier, Thule/Tepui anchors ecosystem positioning through rack-system compatibility that locks in repeat purchases. Among Asia-Pacific digital natives, iKamper exemplifies direct-to-consumer margin capture across North American and European markets. Australian expedition specialists find representation in ARB, which dominates 4WD retail network distribution across Australasia. These three archetypes—ecosystem integrator, digital-native challenger, and regional terrain expert—occupy distinct competitive positions without direct overlap.
| Leading Market Players |
|---|
| James Baroud |
| Thule/Tepui |
| iKamper |
| Overland Vehicle Systems |
| Smittybilt |
| Roofnest |
| ARB |
| Darche |
| Alu-Cab |
| Others |
Pricing and Supply Chain Analysis
Aluminum LME spot pricing volatility cascades through Chinese extrusion clusters into hard-shell rooftop tent manufacturing, compressing input costs for premium tiers while amplifying margin pressure on soft-shell competitors lacking material hedging capabilities.
Pricing Analysis
Warranty and installation service bundling separates premium hard-shell offerings from unbundled soft-shell transactions, with Australian overlanding specialists commanding sustained premiums through expedition-grade support networks. Three-tier pricing structure across premium, standard, and economy levels reflects ISO 11154 certification status, aerodynamic performance ratings, and integrated electronics sophistication. Price erosion runs through soft-shell tiers as Vietnamese textile sourcing and direct-to-consumer channel compression eliminate traditional retail markups. Ground tent substitution threats concentrate price sensitivity among recreational weekend campers in European fuel-efficiency markets, while overlanding enthusiasts in Australian remote corridors exhibit minimal elasticity.
Supply Chain Analysis
Regional distribution centers in Brisbane, Denver, and Stuttgart anchor hub-and-spoke fulfillment patterns that compress delivery timelines for rack-system-integrated orders. Manufacturing gravity centers on Guangdong and Shandong provinces for aluminum extrusion, Vietnam and Bangladesh for polyester textile weaving, and South Africa for expedition-grade canvas finishing. Raw material dependencies encompass 6061-T6 aluminum alloy, hydrophobic coating chemicals, and gas-strut pneumatic components. Single-source vulnerability concentrates in Chinese aluminum capacity, where environmental compliance shutdowns disrupt global hard-shell production schedules. Distribution runs through dedicated 4WD retail networks in Australasia, specialty outdoor retailers in North America, and direct-to-consumer platforms in European markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a cost-of-compliance arena where ISO 11154 roof load certification creates a structural barrier-to-entry moat, privileging incumbents with dedicated regulatory affairs bandwidth and simultaneous FCC, ECE, and ISO pursuit capabilities.
For Market Incumbents: Acquire vehicle compatibility database assets to deepen technical validation moats against emerging digital-native challengers. Prioritize OEM co-development partnerships with electric SUV manufacturers as roof-structure redesigns in battery-electric platforms render legacy compatibility matrices obsolete. Expand backward integration into aluminum extrusion through offtake agreements with Shandong and Guangdong capacity expansions. For New Entrants and Emerging Players: Begin with semi-rigid hybrid configurations in German and French weekend recreational segments, where ECE R14-02 compliance requirements remain manageable without full hard-shell capital intensity. Target trailer-mounted deployments in US western states as the most penetrable attachment category, bypassing vehicle-specific SKU proliferation. Deploy platform-integrated configurators that simulate complete vehicle setups to capture subscription-based accessory bundling demand. For Investors and Strategic Acquirers: Distressed-cycle entries favor digital-native brands with direct-to-consumer infrastructure in North American markets, where customer relationship data assets compound valuation resilience. Long-term viability hinges on EV platform native integration capabilities as battery placement reshapes roof-rack mounting geometries. Monitor electric SUV roof-structure redesign announcements as the critical inflection signal for accessory ecosystem lock-in opportunities.| Strategic Initiative | Industry Significance |
|---|---|
| OEM Co-Development Partnership | Volkswagen and Ford accessory pipelines enable factory-integrated distribution channel access. |
| Direct-to-Consumer Channel Buildout | iKamper's digital-native model captures margin and customer data simultaneously across continents. |
| Backward Integration into Extrusion | Captive aluminum supply from Chinese clusters insulates against LME volatility and environmental shutdowns. |
| Certification Bandwidth Expansion | Simultaneous FCC, ECE, and ISO pursuit accelerates product launch windows for cross-border OEM programs. |
| EV Platform Native Integration | Tesla and Rivian roof-structure co-design locks in accessory ecosystem positioning for electrified overlanding. |
Research Methodology
Document review covered SEC filings of outdoor equipment manufacturers, ISO 11154 certification registries, and customs trade data for aluminum extrusion flows, complemented by interviews with product development directors at hard-shell manufacturers, regulatory affairs managers at rack-system suppliers, procurement leads at Australian 4WD retail networks, and category buyers at North American specialty outdoor retailers. Secondary validation drew from ECE R14-02 type approval databases, FCC equipment authorization records, and vehicle production databases tracking electric SUV roof-structure specifications. Bottom-up segment sizing triangulated against top-down macroeconomic indicators for adventure tourism expenditure.
Market value and volume trajectories emerged from integrated modeling across product architecture, material composition, application intensity, and attachment geometry dimensions throughout the forecast period. CAGRs derived from regression analysis against vehicle electrification penetration curves, overlanding infrastructure investment pipelines, and aluminum input cost forecasting. Industry-specific inputs encompassed dynamic wind load certification timelines, EU F-Gas Regulation phase-down schedules, and EV platform roof-rack redesign roadmaps.
Underlying measurement precision varies by segment; hard-shell and rack-mounted configurations carry tighter precision than soft-shell and clamp-on categories due to concentrated supplier reporting. Forecasts reflect documented assumptions around electrification adoption rates, regulatory enforcement consistency, and raw material cost trajectories. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Outdoor Gear
Diving Regulator Market
Outdoor Gear
Wheeled Insulated Cooler Market
Outdoor Gear
Picnic Coolers Market
Outdoor Gear
Campsite Cooking Gears Market
Outdoor Gear
Artificial Grass Turf Market
Outdoor Gear
Sleeping Bag Market
Outdoor Gear
Rechargeable Camping Gear Market
Outdoor Gear
North America and Europe Leaf Blower Market
Outdoor Gear
Spain Camping Equipment Market
Outdoor Gear
Trail Running Bags Market
Outdoor Gear
China Camping Equipment Market
Outdoor Gear
Camping Equipment and Furniture Market
Outdoor Gear
Shoulder Strap Insulated Cooler Market
Outdoor Gear
Outdoor Camping Toilet Market
Outdoor Gear
UK Camping Equipment Market
Outdoor Gear
Australia Camping Equipment Market