
 United Kingdom Compact Dishwasher Market | 2026-2036
United Kingdom Compact Dishwasher Market Size, Share, and Industry Trends Forecast 2026-2036
United Kingdom Compact Dishwasher Market Insights
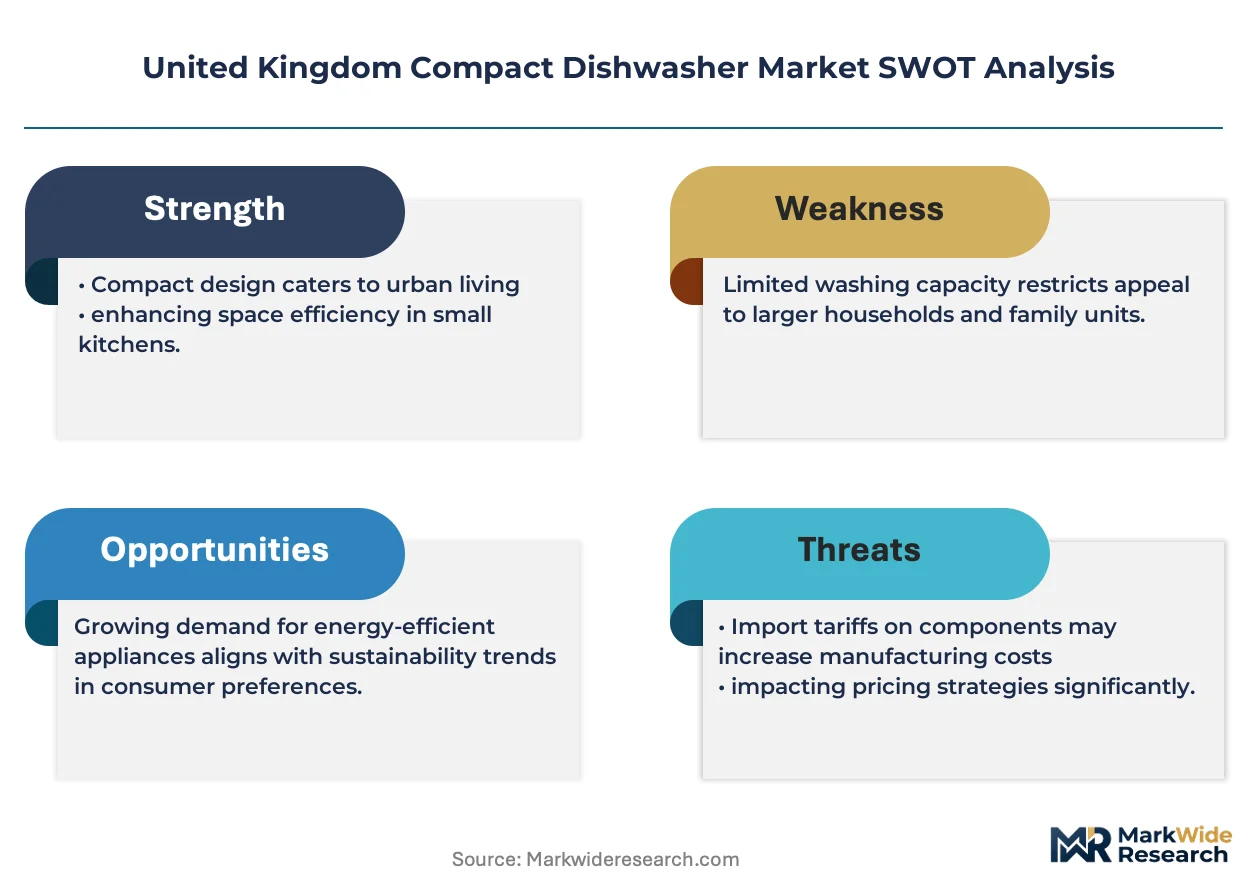
Asset-light leasing models is fragmenting the competitive landscape for compact dishwashers in the United Kingdom, lowering entry barriers for new entrants and reshaping capital deployment across the value chain. Robert Bosch leverages its established service infrastructure to anchor premium positioning in built-in segments. Beko competes aggressively on manufacturing scale, sustaining cost leadership across freestanding units. SMEG specializes in design-led countertop variants, occupying a defensible niche among style-conscious urban buyers.
A compact dishwasher is a reduced-capacity dishwashing appliance typically measuring 45 centimetres in width or less, engineered for installation in space-constrained kitchens through freestanding, built-in, countertop, or portable configurations. These units employ spray-arm wash systems with water consumption rates generally below 10 litres per cycle, serving residential and small commercial environments where full-size appliance installation proves impractical. Built-in and countertop product types lead volume in the United Kingdom due to persistent space restrictions in Victorian-era housing stock and new-build micro-apartments. Energy Efficient and Smart Features technology segments capture expanding margin pools as electricity pricing pressures and connected-home integration reshape buyer priorities. Standard Efficiency variants face structural decline as minimum energy performance standards tighten across the distribution channel landscape.
The UK's Environment Agency water-efficiency regulations and BEIS energy-labelling frameworks compel manufacturers to redesign spray systems and heating elements, directly influencing R&D allocation and product-line refresh cycles. BSI standards for electrical safety and electromagnetic compatibility create compliance thresholds that filter out non-specialist importers, consolidating shelf access for established brands. Stakeholders must monitor how Ofwat pricing reviews and building regulation amendments for new residential developments reshape the addressable base for compact versus full-size alternatives.
Market Dynamics
Rental housing expansion across Greater London is fragmenting traditional appliance ownership models, forcing manufacturers to recalibrate distribution channels and service architectures around asset-light consumption patterns.
Growth Catalysts
- BEIS Energy Labelling Frameworks:Tightening minimum efficiency standards are accelerating replacement cycles for older units across Victorian-era housing stock, pulling forward demand for compliant compact models.
- Countertop Configurations:Space-constrained micro-apartments in Manchester and Birmingham are driving specification shifts toward portable, plug-and-play dishwashing solutions that bypass installation requirements.
- Ofwat Pricing Reviews:Rising water tariffs are amplifying buyer sensitivity to per-cycle consumption metrics, privileging spray-arm systems engineered below 10-litre thresholds.
Market Restraints
- Stainless Steel Input Volatility:Sheet metal price fluctuations compress margin stability for freestanding unit producers, particularly those competing at volume-tier price points.
- BSI Electromagnetic Compatibility Certification:Compliance timelines and testing costs create friction for non-specialist importers, filtering shelf access and consolidating incumbent advantages.
- Manual Dishwashing Substitution:Single-occupancy households in cost-sensitive segments retain hand-washing habits, capping penetration ceilings in specific demographic cohorts.
Strategic Opportunities
- Lease-to-Own Channel Innovation:Rental housing operators in Edinburgh and Bristol are piloting bundled appliance subscriptions, creating recurring revenue streams distinct from point-of-sale transactions.
- Smart Home Convergence:Integration of Wi-Fi-enabled diagnostics with connected-home ecosystems is hybridizing product value propositions for tech-forward urban buyers.
- Scottish Building Regulation Amendments:New residential development standards in Glasgow are mandating water-efficient fixture specifications, expanding the addressable base for compact alternatives.
Industry Challenges
- Installation Skill Scarcity:Qualified technicians for built-in unit retrofitting remain concentrated in southern England, creating service delivery gaps in northern markets.
- Legacy Housing Electrical Infrastructure:Victorian-era wiring in London boroughs imposes power-draw limitations, complicating heating element upgrades and smart-feature integration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United Kingdom Compact Dishwasher Market |
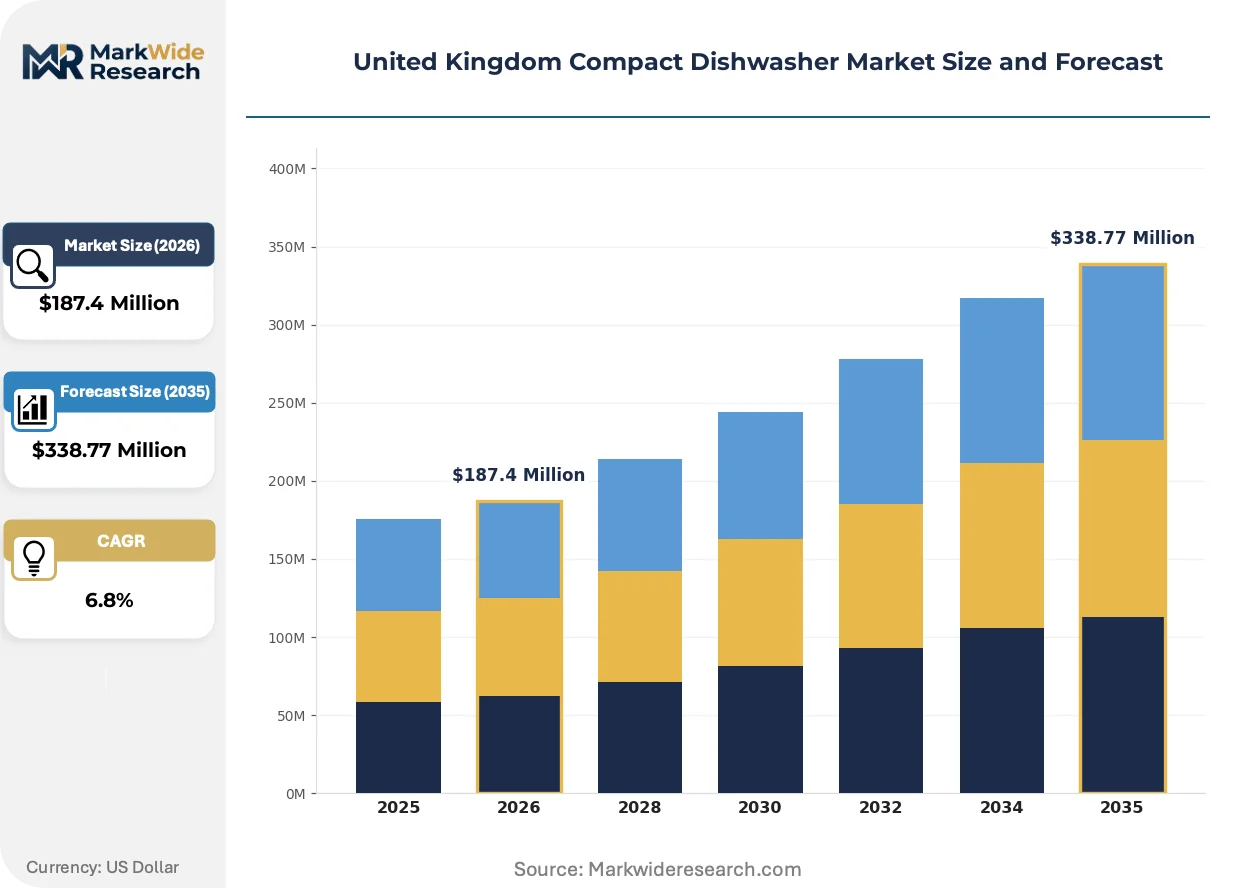
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Freestanding, Built-in, Countertop, Portable End User: Household, Small Office, Cafés, Restaurants Distribution Channel: Online Retail, Specialty Stores, Supermarkets, Wholesalers Technology: Energy Efficient, Low Water Consumption, Smart Features, Standard Efficiency |
| Companies Covered | LG Electronics, Robert Bosch, Midea Group, Haier Electronics Group, Gorenje Group, Siemens, Electrolux, Beko, SMEG, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United Kingdom Compact Dishwasher Market Trends and Innovations
Connected-home integration and water-efficiency mandates are converging to redefine product specification priorities, compressing development cycles and reshaping competitive differentiation beyond traditional capacity metrics.
Heat-pump drying technology is hybridizing conventional condenser architectures, enabling sub-A+++ energy ratings that satisfy BEIS labelling thresholds. Buy-to-let landlords in Greater London are specifying these units at accelerating rates. The technology is compressing total cost-of-ownership calculations and displacing standard-efficiency variants from premium channel positioning.
UK Environment Agency water-efficiency standards are tightening spray-system specifications, compelling manufacturers to redesign pump configurations and nozzle geometries. Industrial consequence includes extended R&D timelines and accelerated product-line refresh cycles. Built-in segments face the steepest compliance burden, with distributors prioritizing certified inventory ahead of regulatory enforcement windows.
Subscription-based procurement is displacing outright purchase in urban rental corridors, unbundling after-sales service from hardware acquisition. Build-to-rent operators in Manchester and Leeds are negotiating fleet-level agreements that include maintenance and upgrade provisions. This pattern concentrates demand volume among property management platforms rather than fragmented individual consumers.
United Kingdom Compact Dishwasher Market Segmentation
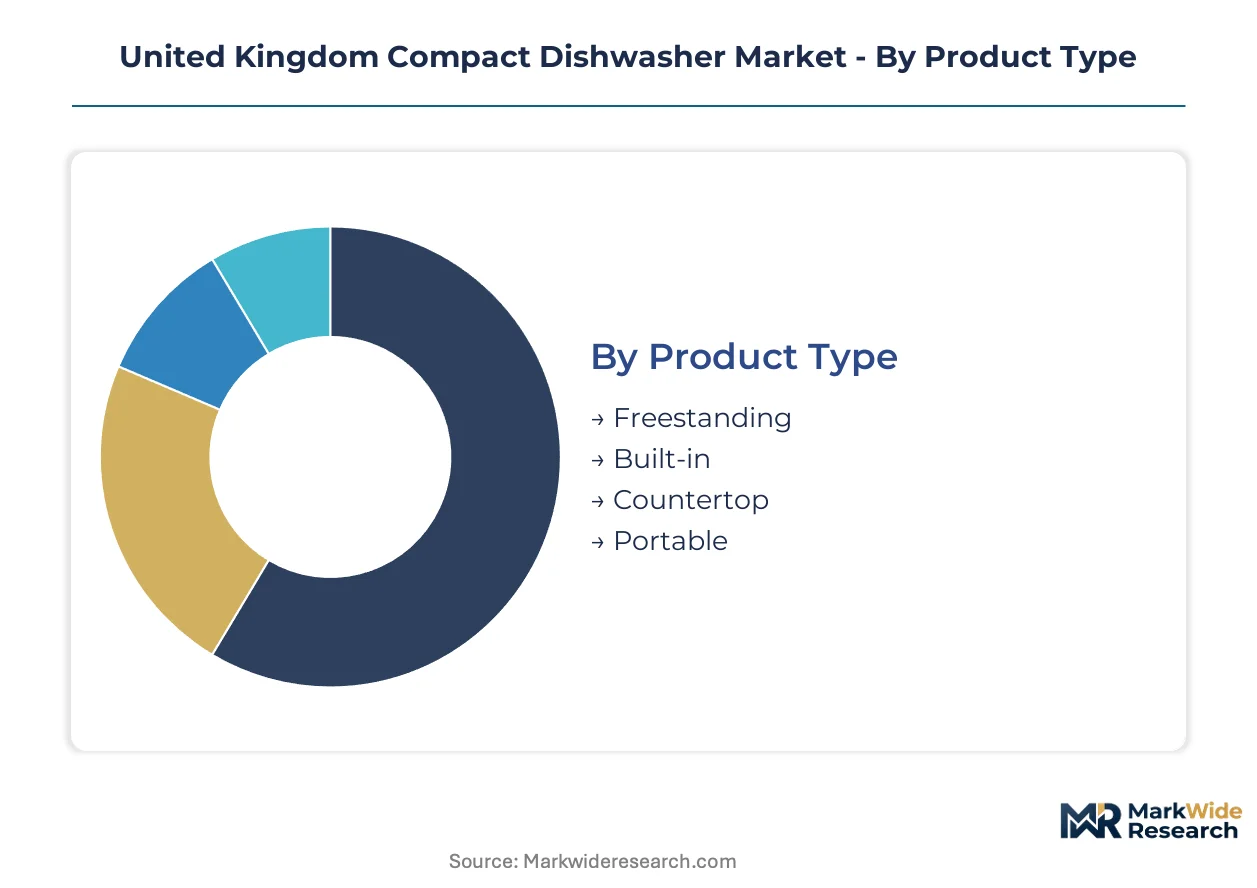
Segmentation in the United Kingdom compact dishwasher market reveals how space constraints, rental housing patterns, and regulatory pressures fragment demand across distinct product configurations and buyer profiles. Understanding these divides enables targeted channel strategies and R&D prioritization.
Product Type:
Configuration choices map directly to housing stock age and installation feasibility across British urban centers.
- Built-in:These units integrate beneath worktops within fixed cabinetry, requiring professional installation and permanent kitchen modifications. Demand clusters in Greater London's new-build micro-apartments where developers pre-specify space-efficient appliance niches to meet building regulation efficiency mandates.
- Countertop:Freestanding surface-mounted units measuring 45 centimetres or less in width plug into standard power outlets without plumbing alterations. Manchester and Birmingham rental corridors favor these for tenant turnover flexibility and deposit-friendly portability.
- Freestanding:Slimline floor-standing units with finished panels suit Victorian-era kitchens lacking integrated appliance bays.
- Portable:Wheeled variants with temporary hose connections serve seasonal holiday lets and temporary accommodation providers.
Built-in holds installed capacity. Countertop is rotating up the share rankings.
End User:
Application scope stretches from private residential to food-service micro-operations with divergent duty cycles and procurement behaviors.
- Household:Single-occupancy and dual-income urban renters dominate this segment, prioritizing water-efficiency ratings to offset Ofwat tariff pressures. Buy-to-let landlords in Edinburgh and Bristol increasingly specify compact units as tenant amenities to reduce void periods.
- Small Office:Professional services firms with 10-50 employees deploy countertop units in pantry facilities, valuing low decibel ratings and cycle completion alerts.
- Cafés:Independent coffee shops with limited back-of-house footprints favor rapid-cycle portable units for cup and saucer throughput during peak service windows.
- Restaurants:Small independent eateries deploy compact units as secondary warewashing for glassware and cutlery, reserving commercial hood-type machines for primary loads.
Household commands volume leadership. Small Office is climbing the fastest as hybrid work patterns normalize office pantry upgrades.
Distribution Channel:
Route-to-market structures reflect buyer sophistication, installation complexity, and after-sales service requirements.
- Online Retail:E-commerce platforms capture price-transparent shoppers comparing energy-label grades and water-consumption metrics. Countertop and portable configurations dominate this channel due to minimal installation support needs.
- Specialty Stores:Kitchen design showrooms and independent appliance retailers provide specification consultation and installation coordination. Built-in segments rely on this channel for qualified technician referrals.
- Supermarkets:Mass-market grocers with home goods extensions stock entry-level freestanding units for impulse and replacement purchases.
- Wholesalers:Trade distributors serve property developers, build-to-rent operators, and hospitality procurement teams with fleet pricing and staged delivery logistics.
Specialty Stores anchor premium built-in throughput. Online Retail is gaining share fastest as subscription financing platforms digitize lease-to-own workflows.
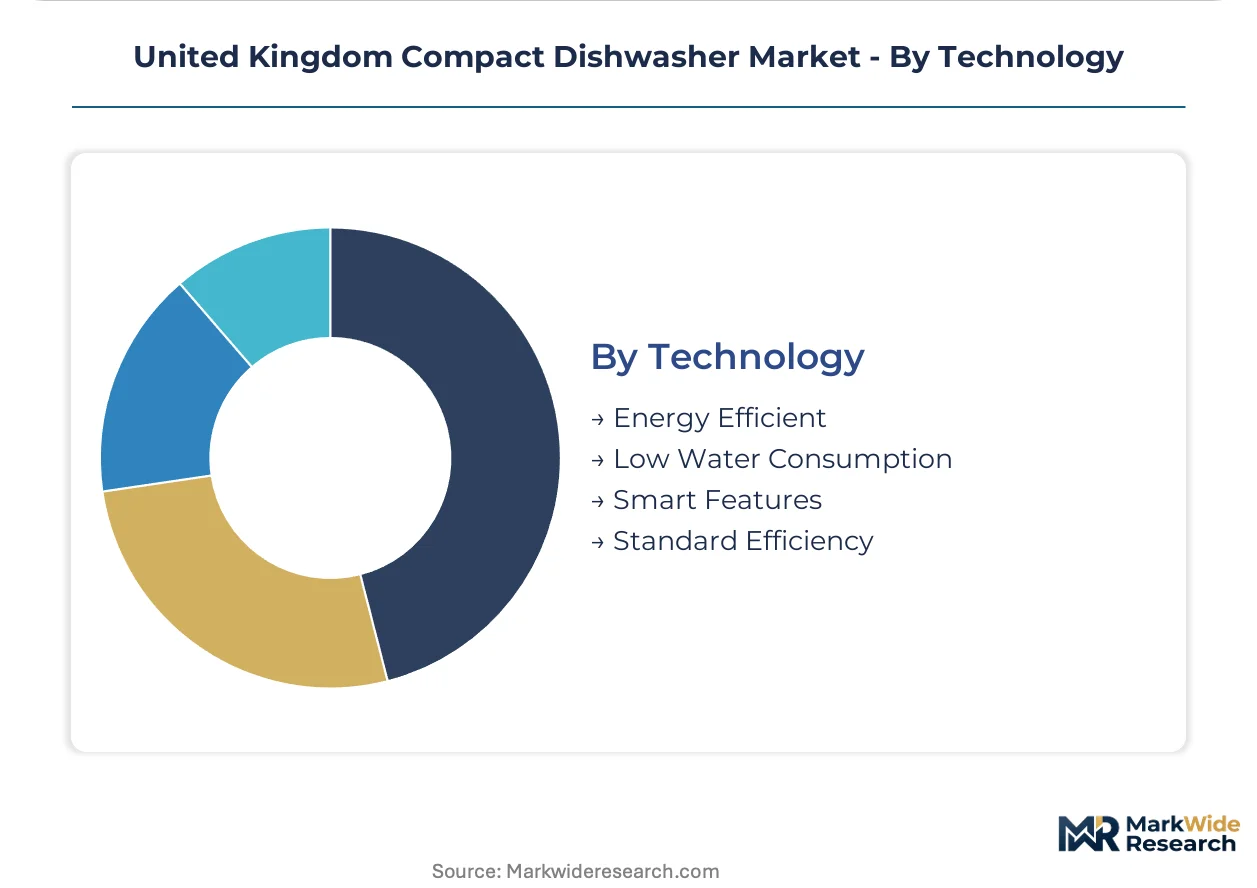
Technology:
Performance tiers separate compliance-driven replacement demand from efficiency-seeking upgrade cycles.
- Energy Efficient:A+++ rated units with heat-pump drying architectures command premium positioning as BEIS labelling thresholds tighten. Buy-to-let landlords specify these to future-proof rental stock against regulatory enforcement windows.
- Smart Features:Wi-Fi-enabled diagnostics, cycle customization via mobile applications, and connected-home ecosystem integration attract tech-forward urban buyers in London's high-density residential towers.
- Low Water Consumption:Spray-arm systems engineered below 8-litre per cycle thresholds satisfy Environment Agency water-efficiency specifications.
- Standard Efficiency:Legacy-rated units face structural decline as minimum energy performance standards filter non-compliant inventory from distribution channels.
Energy Efficient holds installed base leadership. Smart Features is expanding most quickly as electricity pricing volatility drives total cost-of-ownership calculations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Greater London commands premium pricing power through developer-led specification channels, while northern England operates on thinner margins driven by rental-landlord procurement volumes. This asymmetry shapes inventory allocation and service architecture deployment across British distribution networks.
Greater London
New-build micro-apartments in Tower Hamlets and Southwark drive built-in compact dishwasher specification through developer pre-installation mandates. BEIS energy-labelling thresholds filter non-compliant inventory from premium channels. Build-to-rent operators in Canary Wharf negotiate fleet-level agreements with maintenance bundling.
Midlands
Countertop configurations dominate Birmingham's private rental sector where tenant turnover favors plug-and-play portability. Ofwat water tariff pressures amplify buyer sensitivity to sub-10-litre cycle consumption. Leicester's manufacturing heritage supports component supply clustering for spray-system assembly.
North England
Victorian-era housing stock in Manchester and Leeds constrains installation feasibility to freestanding slimline units. Scottish Building Regulation amendments for water-efficient fixtures create spillover specification pressure across northern procurement patterns. Sheffield's steelworking legacy feeds sheet metal input channels for appliance casing production.
Scotland
Edinburgh's buy-to-let market pilots lease-to-own bundled subscriptions with upgrade provisions. The Environment Agency's tightening water-efficiency standards compress R&D timelines for spray-arm redesign. Glasgow's new residential developments mandate compact fixture specifications, expanding addressable demand for certified inventory.
Wales
Cardiff's student housing sector favors portable wheeled variants for seasonal letting cycles. BSI electromagnetic compatibility certification creates compliance friction filtering non-specialist imports. Swansea's coastal tourism economy drives holiday-let procurement for temporary accommodation providers.
United Kingdom Compact Dishwasher Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream supplying pump assemblies and heating elements to finished-goods assemblers. The vendor base organizes around three strategic archetypes: diversified appliance conglomerates with full-category coverage, regional manufacturing specialists leveraging scale economics, and design-forward niche players occupying premium positioning. Consolidation pressures concentrate shelf access among established brands with compliant inventory. Competitive moves center on service infrastructure expansion and heat-pump technology licensing.
Among diversified appliance conglomerates, Robert Bosch and LG Electronics exemplify platform-scale positioning with established service networks. Beko represents the manufacturing-scale archetype competing on cost leadership across volume-tier segments. SMEG occupies the design-specialist tier with style-led countertop variants targeting urban aesthetic preferences. These three anchors illustrate how competitive positioning fragments across pricing, performance, and specification vectors rather than consolidating around single-dominant players.
| Leading Market Players |
|---|
| LG Electronics |
| Robert Bosch |
| Midea Group |
| Haier Electronics Group |
| Gorenje Group |
| Siemens |
| Electrolux |
| Beko |
| SMEG |
| Others |
Pricing and Supply Chain Analysis
Stainless steel input volatility from Turkish and Chinese mills compresses margin stability for freestanding unit producers while simultaneously widening pricing spreads between premium heat-pump architectures and standard-efficiency alternatives. This commodity exposure determines both the three-tier pricing structure across premium, standard, and economy levels and the geographic sourcing strategies that appliance assemblers deploy across their component networks.
Pricing Analysis
Buy-to-let landlords anchor pricing power in Greater London's built-in segment through fleet-level procurement negotiations that bundle installation and maintenance services. Price differentiation separates A+++ certified heat-pump units from standard-efficiency inventory based on BEIS labelling thresholds and after-sales service bundling. Pricing pressure stems from BSI electromagnetic compatibility certification costs filtering non-compliant imports from distribution channels. Single-occupancy renters in Manchester's private rental sector exhibit highest price sensitivity, while Canary Wharf build-to-rent operators demonstrate lowest sensitivity due to total cost-of-ownership calculations.
Supply Chain Analysis
Tariff exposure between China and the United Kingdom dominates supply chain risk calculus for pump assembly and heating element sourcing. Component manufacturing concentrates in China, Turkey, and Poland for spray-system assemblies, stainless steel casings, and electronic control modules. Raw material dependencies include nickel-alloy sheet metal, copper wiring, and semiconductor chips for smart-feature integration. Single-source vulnerability persists for heat-pump compressor technology licensed from German engineering specialists. Distribution runs through trade wholesalers serving property developers, specialty kitchen retailers coordinating installation, and direct e-commerce platforms for portable configurations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The United Kingdom compact dishwasher market sits at a regulatory inflection where BEIS energy-labelling thresholds and Environment Agency water-efficiency mandates are compressing replacement cycles and fragmenting competitive positioning around compliance capabilities.
For Market Incumbents: Insulate premium positioning by deepening captive supply of heat-pump drying components and expanding qualified technician networks across northern England where installation skill scarcity creates service delivery gaps. Accelerate R&D allocation toward sub-8-litre spray-system architectures ahead of Environment Agency enforcement windows. Defend shelf access through BSI certification investment that filters non-specialist importers from distribution channels.
For New Entrants and Emerging Players: Establish a beachhead in Scotland's lease-to-own subscription segment where Edinburgh buy-to-let operators pilot bundled appliance procurement with upgrade provisions. Target countertop configurations for Birmingham's high-turnover rental corridors where plug-and-play portability bypasses installation barriers. Pursue direct partnerships with build-to-rent platforms rather than fragmented individual consumer acquisition.
For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors component specialists with heat-pump technology licensing and established BSI compliance track records. Long-term viability hinges on regulatory adaptation speed rather than manufacturing scale alone. Acquisition target archetypes include spray-system engineering specialists and connected-home integration platforms. Monitor Scottish Building Regulation amendment timelines as the signal indicating acceleration in certified inventory demand across northern procurement patterns.
| Strategic Initiative | Industry Significance |
|---|---|
| Heat-Pump Technology Licensing | Secures A+++ BEIS certification pathways that displace standard-efficiency inventory from premium channels. |
| Lease-to-Own Channel Partnership | Captures recurring revenue streams from Manchester and Edinburgh build-to-rent operators. |
| Qualified Technician Network Expansion | Closes service delivery gaps in northern England where installation scarcity constrains built-in penetration. |
| Spray-System R&D Redesign | Satisfies Environment Agency sub-8-litre thresholds ahead of regulatory enforcement windows. |
| Connected-Home Platform Integration | Hybridizes product value propositions for tech-forward urban buyers in London high-density towers. |
Research Methodology
Operator-level perspectives from appliance procurement managers at build-to-rent operators, kitchen design showroom directors, qualified installation technicians, and trade wholesale account managers anchored the qualitative base. These primary inputs combined with secondary validation from BEIS energy-labelling databases, Environment Agency water-efficiency compliance registers, Ofwat tariff review documentation, and BSI certification records. Bottom-up demand modeling across product configurations and end-user segments triangulated against top-down market sizing from customs trade data and distribution channel inventory flows.
Scenario-bracketing around BEIS regulatory enforcement timing, Ofwat pricing review outcomes, and Scottish Building Regulation amendment adoption shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product configuration, end-user application, distribution channel structure, and technology performance tier. CAGRs derived from replacement cycle acceleration patterns in Victorian-era housing stock and new-build micro-apartment completion rates. Heat-pump technology penetration curves and subscription financing adoption rates served as industry-specific forecast inputs.
Stress conditions across stainless steel price volatility bands, BSI certification timeline delays, and rental housing market absorption rates were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding regulatory enforcement sequencing and technology cost curves. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Appliances
Induction Cooktops Market
Appliances
Europe Garment Steamers Market
Appliances
Digital Showers Market
Appliances
Global Vended Laundry Equipment Market
Appliances
Middle East and Africa Commercial Dishwashers Market
Appliances
Dishwasher Market
Appliances
Portable Dishwasher Market
Appliances
Bhutan and Nepal White Goods Market
Appliances
Fully Integrated Dishwasher Market
Appliances
Window Air Conditioners Market
Appliances
Turkey Washing Machine Market
Appliances
Built-In Large Cooking Appliance Market
Appliances
UK Residential Vacuum Cleaner Market
Appliances
United States Microwave Oven Market
Appliances
India Washing Machine Market
Appliances
United Kingdom Tumble Dryers Market