
 Microwave Market | 2026-2036
Microwave Market Size, Share, and Industry Trends Forecast 2026-2036
Microwave Market Outlook
Asset-light leasing models for commercial kitchen equipment are reshaping competitive dynamics in the microwave industry by lowering capital barriers for independent restaurants and catering operators. Samsung Electronics leverages its semiconductor supply chain to sustain in-house magnetron production and cost advantages. Midea Group anchors its position through manufacturing scale across multiple price tiers in Asia. Panasonic Corporation differentiates via technology leadership in inverter-based power control systems.
A microwave is a high-frequency electromagnetic appliance operating at 2.45 GHz that generates dielectric heating by causing polar molecules in food to rotate, with cavity sizes typically ranging from 0.5 to 2.2 cubic feet and power outputs from 600 to 1,200 watts for residential units; its primary purpose is rapid thermal processing for defrosting, reheating, and cooking applications in both household and commercial foodservice environments. Countertop units dominate residential volume due to low replacement cost and installation flexibility, while built-in configurations command higher margins through kitchen integration and premium positioning. Convection technology leads growth in the commercial segment as operators seek dual-function equipment that reduces appliance count and floor space requirements.
The US Department of Energy sets minimum efficiency standards under ENERGY STAR certification programs, while the EU's Ecodesign Directive and F-Gas Regulation govern energy consumption limits and refrigerant use in combination microwave-convection units. China's SAMR enforces GB standards for electromagnetic compatibility and electrical safety in domestic appliances. Stakeholders must monitor how efficiency mandates in North America and Europe affect magnetron design costs and whether regional compliance divergence creates product line fragmentation.
Market Dynamics
The US Department of Energy's tightening appliance efficiency standards are forcing magnetron redesigns and compressing margins across the microwave supply chain as manufacturers absorb compliance costs while defending price positions.
Growth Catalysts
- Quick-service restaurant expansion:Commercial kitchen operators deploy microwave systems to reduce ticket times and energy consumption per meal served.
- China's urban housing density:Compact built-in and over-the-range configurations dominate new apartment installations in tier-one cities.
- ENERGY STAR certification thresholds:US federal standards create pull-through demand for inverter-based power control systems that exceed baseline efficiency requirements.
Market Restraints
- Magnetron supply concentration:Critical vacuum tube components rely on a narrow supplier base concentrated in East Asian manufacturing clusters.
- Copper and rare earth volatility:Input costs for magnetron windings and magnetic materials fluctuate with commodity markets.
- EU F-Gas Regulation friction:Combination microwave-convection units face refrigerant compliance burdens that increase engineering overhead.
Strategic Opportunities
- India's underserved commercial segment:Independent restaurants and catering operators represent an underpenetrated equipment leasing market.
- Smart kitchen convergence:IoT connectivity and automated cooking algorithms create premium positioning for connected microwave platforms.
- Asset-light leasing channels:Subscription-based equipment procurement lowers capital barriers for foodservice startups.
Industry Challenges
- Electromagnetic compatibility certification:China's SAMR enforces GB standards that extend product validation timelines for new entrants.
- Legacy kitchen integration:Retrofit installations require custom cavity modifications that strain contractor capacity and inflate project costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Microwave Market |
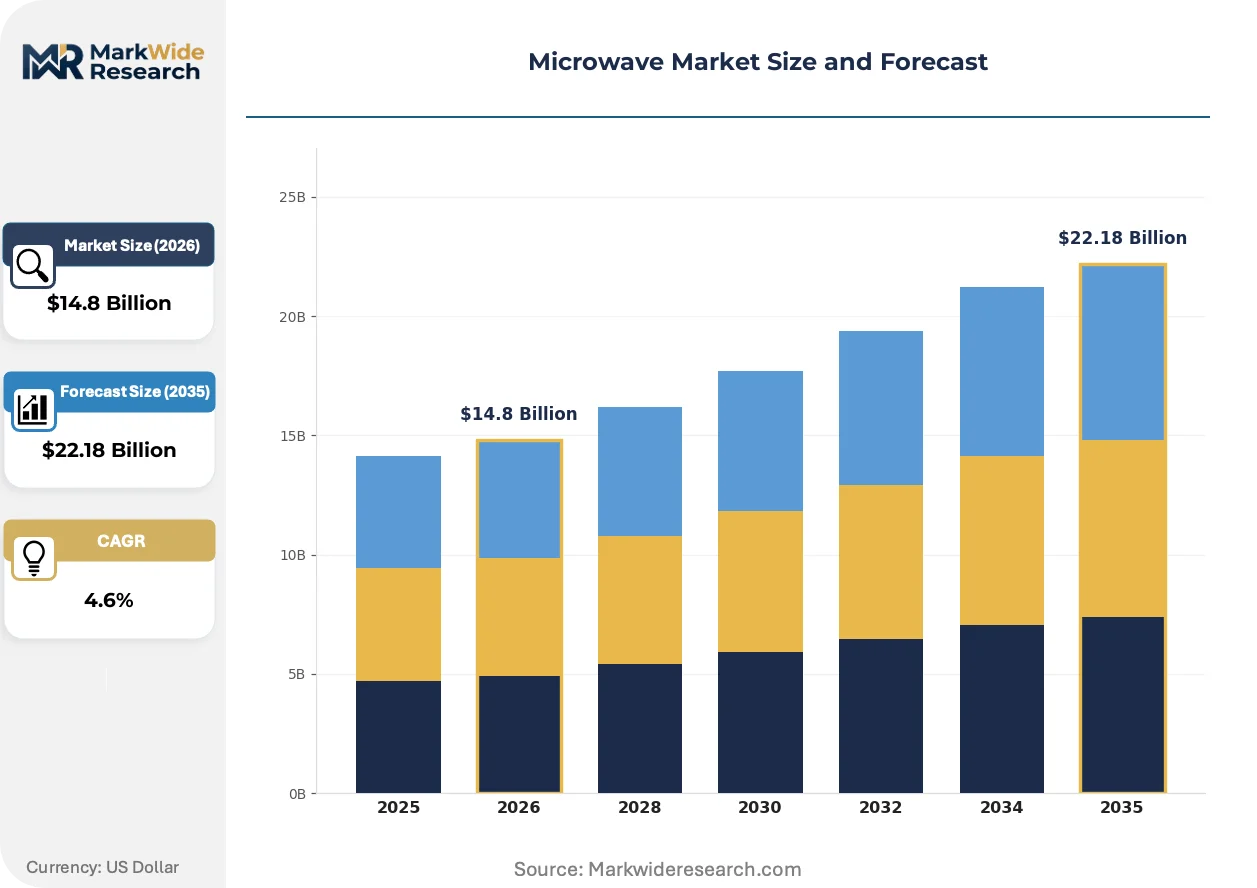
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $22.18 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Countertop, Built-in, Over-the-Range, Commercial Technology: Convection, Grill, Solo, Steam End User: Residential, Restaurants, Cafeterias, Catering Services Distribution Channel: Online Retail, Specialty Stores, Wholesalers, Direct Sales |
| Companies Covered | Samsung Electronics, LG Electronics, Electrolux AB, Panasonic Corporation, Whirlpool Corporation, Bosch, Midea Group, GE Appliances, Sharp Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Microwave Market Strategic Shifts
Inverter-based power control is collapsing the traditional trade-off between cooking precision and energy efficiency. Three interconnected developments are reshaping how microwave technology propagates through residential and commercial channels.
Solid-state RF power amplifiers are collapsing the dominance of vacuum tube magnetrons in premium residential and commercial segments. Quick-service restaurant chains pilot these systems for precise temperature control and reduced maintenance cycles. The technology is collapsing replacement part revenue streams while enabling predictive service models.
The EU Ecodesign Directive's 2024 amendments tighten standby power limits and mandate recycled content disclosures for cooking appliances. Manufacturers must redesign control boards and source certified plastics to maintain CE marking eligibility. Commercial combination units face the steepest compliance burden due to dual-function classification.
Foodservice procurement teams now bundle microwave acquisition with preventive maintenance contracts and energy monitoring subscriptions. Equipment lessors displace traditional distributor relationships in mid-scale restaurant chains. This pattern concentrates in North American markets where capital efficiency metrics dominate operator decision frameworks.
Microwave Market Segmentation
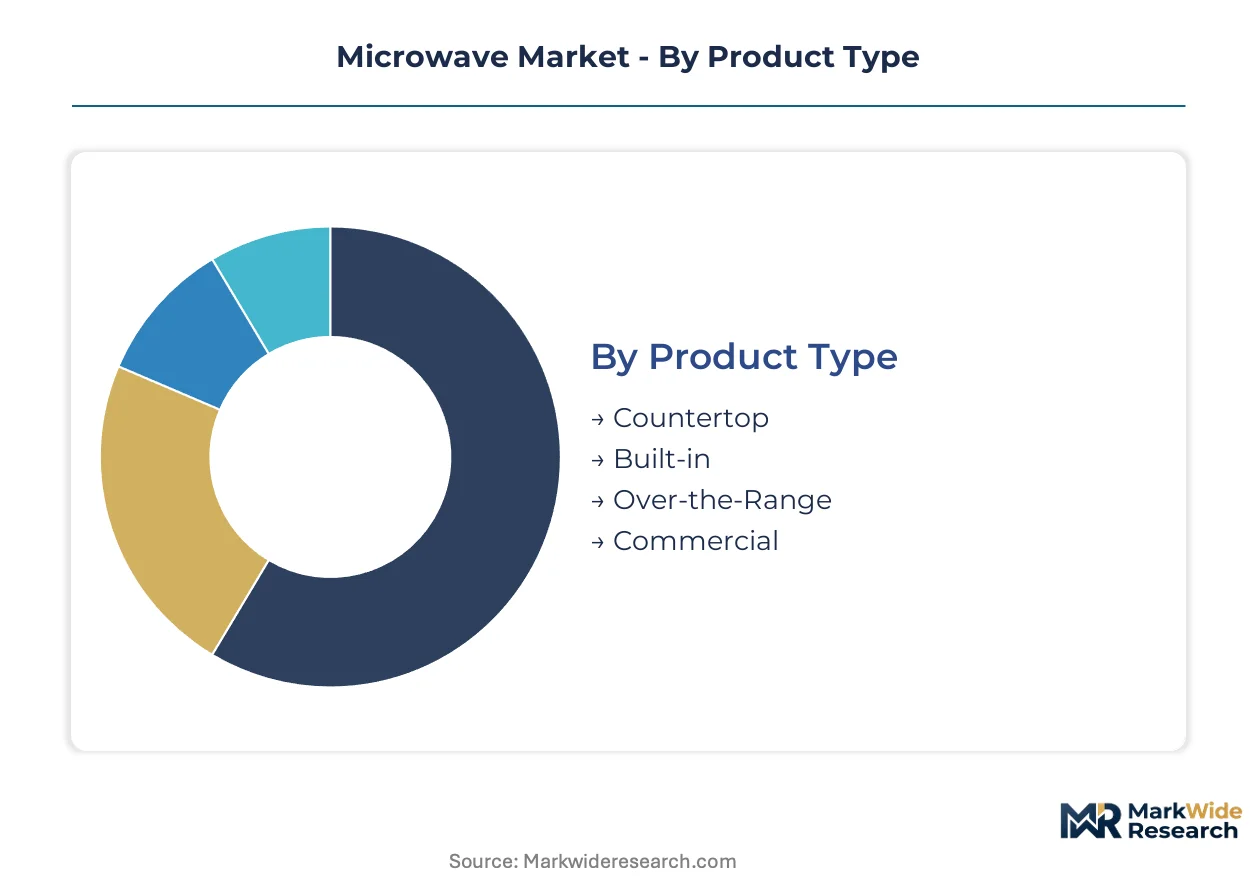
Microwave segmentation reveals how cooking technology fragments across installation constraints, power systems, and procurement channels. Each dimension carries distinct margin profiles and regulatory exposure that reshape competitive positioning.
Product Type:
Installation flexibility spans from portable countertop units to permanent commercial infrastructure, with each configuration commanding different kitchen real estate trade-offs and replacement cycles.
- Countertop:Freestanding units with zero installation requirements dominate residential volume through low replacement cost and immediate deployment. Demand concentrates in China's tier-two and tier-three cities where rental housing turnover accelerates replacement cycles and portability outweighs aesthetic integration.
- Built-in:Cabinet-integrated systems with custom trim kits command premium positioning through seamless kitchen aesthetics. China's urban apartment density in Shanghai and Shenzhen favors these configurations where square-meter constraints eliminate standalone appliance footprints.
- Over-the-Range:Combined ventilation-cooking systems optimize vertical space in compact kitchens. These units carry higher margin profiles through dual-function positioning.
- Commercial:Heavy-duty stainless steel platforms with 1,800+ watt outputs serve high-throughput foodservice operations. Quick-service restaurant chains in the United States deploy these systems to compress ticket times.
The dominant share belongs to Countertop configurations, while Commercial systems are gaining share fastest through foodservice automation trends.
Technology:
Power delivery mechanisms differentiate thermal performance, with each technology tier carrying distinct energy efficiency profiles and electromagnetic compatibility certification burdens.
- Convection:Forced-air circulation combined with microwave energy enables browning and crisping functions impossible with standard dielectric heating. European markets under Ecodesign Directive pressure favor these dual-mode systems for their reduced appliance count and energy optimization.
- Grill:Quartz or sheath heater elements add surface searing capability to microwave cores. These mid-tier systems capture price-sensitive consumers seeking expanded functionality without convection complexity.
- Solo:Pure microwave dielectric heating without supplementary thermal elements. Solo technology retains cost leadership in emerging markets and institutional procurement.
- Steam:Integrated water reservoirs and vapor injection systems preserve moisture in vegetables and proteins. Health-conscious residential segments in Japan and South Korea drive adoption.
Convection platforms hold the technology lead by revenue, with Steam configurations expanding most quickly through wellness positioning.
End User:
Procurement behavior bifurcates between price-sensitive household replacement and total-cost-of-optimization commercial operators.
- Residential:Individual households purchasing through retail channels with 7-10 year replacement cycles. China's urban middle class concentrates demand in built-in and over-the-range premium tiers.
- Restaurants:Independent and chain operators prioritizing throughput per square meter and energy cost per meal. United States quick-service chains deploy asset-light leasing models to minimize capital deployment.
- Cafeterias:Institutional foodservice in educational and corporate settings with standardized equipment procurement. Volume concentration favors durable commercial platforms with extended warranty terms.
- Catering Services:Mobile and event-based operators requiring portable, high-output systems with rapid recovery times. India's underserved independent catering segment presents expansion opportunity.
Residential volume dominates absolute units, while Restaurants drive value concentration through commercial-grade specifications.
Distribution Channel:
Channel structure determines margin capture and post-sale service attachment, with digital platforms disrupting traditional appliance retail.
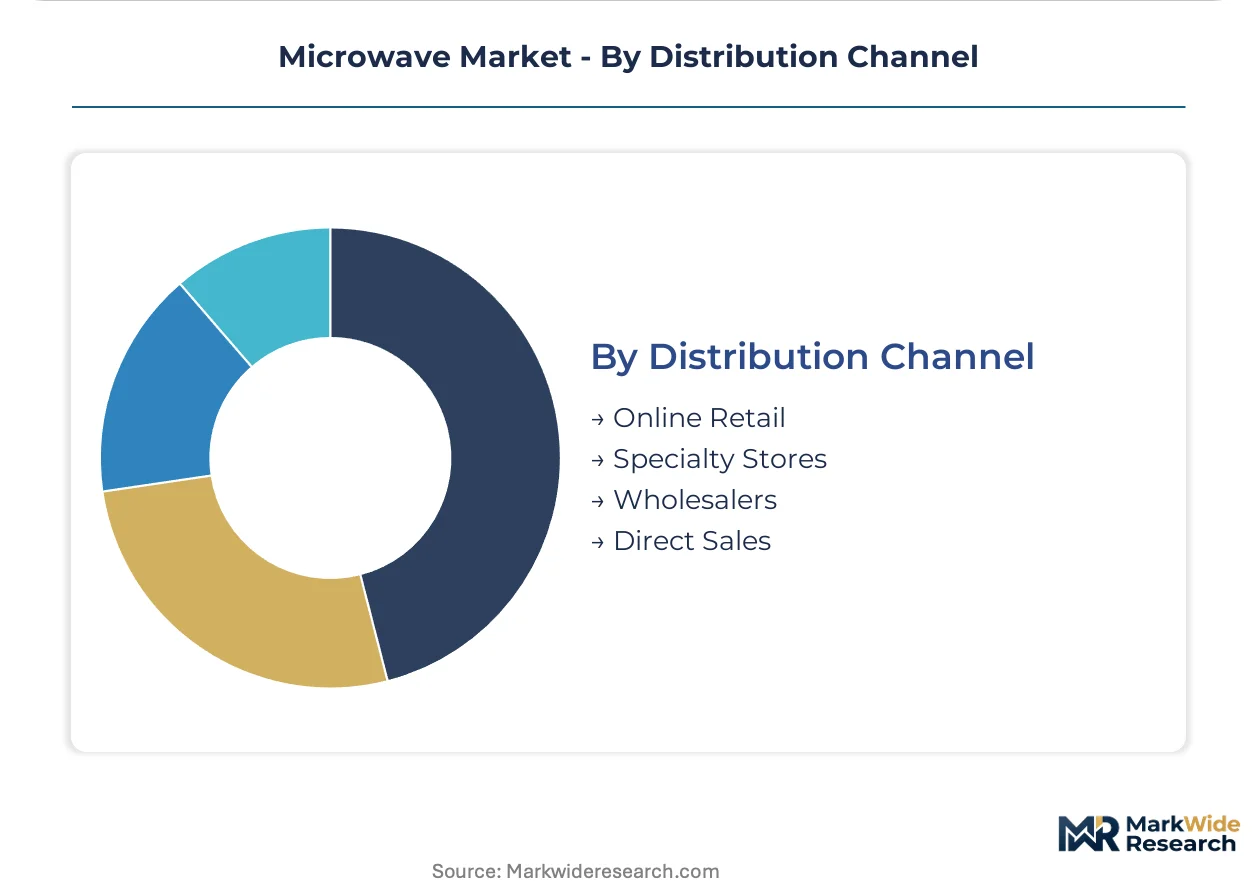
- Online Retail:E-commerce platforms with direct-to-consumer logistics and comparison-shopping interfaces. China's Alibaba and JD.com ecosystems concentrate microwave volume through price transparency and delivery infrastructure.
- Specialty Stores:Kitchen design showrooms with consultation services and installation coordination. Built-in and premium configurations depend on this channel for specification support.
- Wholesalers:Bulk procurement intermediaries serving contractor and institutional accounts. Commercial segment reliance on this channel creates price pressure through competitive bidding.
- Direct Sales:Manufacturer-owned channels with bundled service contracts and IoT platform integration. Smart kitchen convergence favors this high-touch approach.
Online Retail commands the volume lead, with Direct Sales climbing fastest through subscription-based equipment procurement models.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China commands pricing leverage through manufacturing scale dominance, while European markets extract premium positioning through regulatory differentiation. This asymmetry shapes how manufacturers configure product lines across geographies.
China
Urban apartment density in Shanghai and Shenzhen accelerates demand for compact built-in and over-the-range configurations. SAMR enforces GB standards for electromagnetic compatibility and electrical safety that extend validation timelines. Manufacturing clusters in Guangdong Province concentrate magnetron production and final assembly operations.
United States
Quick-service restaurant chains deploy commercial-grade systems to compress ticket times and optimize energy cost per meal served. The Department of Energy tightens ENERGY STAR certification thresholds that pull demand toward inverter-based power control systems. Equipment lessors in Texas and California displace traditional distributor relationships through subscription-based procurement models.
Germany
Commercial foodservice operators favor combination microwave-convection units to reduce appliance count and floor space requirements. The EU Ecodesign Directive mandates standby power limits and recycled content disclosures that increase engineering overhead. Industrial clusters in Bavaria specialize in precision control systems for premium residential and commercial tiers.
Japan
Health-conscious residential segments in Tokyo and Osaka drive adoption of steam-injection configurations that preserve moisture in proteins and vegetables. METI oversees appliance efficiency standards that exceed baseline international requirements. Manufacturing concentration in the Chubu region around Nagoya anchors supply chains for advanced power control components.
India
Independent restaurants and catering operators in Mumbai and Delhi represent an underpenetrated equipment leasing market with compressed capital deployment cycles. BIS certification requirements for electrical safety create compliance barriers for new entrants. Commercial kitchen procurement in Maharashtra increasingly bundles microwave acquisition with preventive maintenance contracts.
Microwave Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream with narrower but defensible positions. The market structure consolidates around diversified appliance conglomerates with captive magnetron supply or semiconductor integration. Three archetypes dominate: diversified electronics conglomerates with vertical semiconductor capabilities, pure-play appliance manufacturers scaling across price tiers, and specialist component suppliers serving multiple OEMs. Competitive moves concentrate on backward integration into magnetron production and geographic expansion through asset-light leasing channels.
Among diversified electronics conglomerates, Samsung Electronics and Panasonic Corporation exemplify platform integrators leveraging semiconductor supply chains to sustain in-house component production. LG Electronics occupies a position bridging consumer electronics integration with appliance-specific engineering. These anchors represent how control over upstream magnetron or inverter technology translates into cost position defense across residential and commercial segments.
| Leading Market Players |
|---|
| Samsung Electronics |
| LG Electronics |
| Electrolux AB |
| Panasonic Corporation |
| Whirlpool Corporation |
| Bosch |
| Midea Group |
| GE Appliances |
| Sharp Corporation |
| Others |
Value Chain & Pricing Dynamics
The Shanghai-Los Angeles maritime corridor's freight cost volatility compresses margins for magnetron-dependent manufacturers while amplifying price differentiation between captive-supply conglomerates and component-dependent assemblers. This logistics chokepoint concentrates cost pressure on mid-tier producers who lack upstream vacuum tube production, forcing pricing stratification across premium inverter systems, standard magnetron platforms, and economy solo units.
Pricing Analysis
Industrial OEM buyers anchor a contract-based pricing structure that locks in magnetron supply commitments against commodity copper volatility. Price differentiation hinges on ENERGY STAR certification tier and volume scale, with certified inverter systems commanding premium positioning over baseline units. Cost compression in the economy tier intensifies because Chinese manufacturers absorb SAMR compliance overhead while defending export price positions. Quick-service restaurant chains exhibit lowest price sensitivity through total-cost-of-ownership frameworks, whereas India's independent catering operators demonstrate highest sensitivity to upfront capital deployment.
Supply Chain Analysis
Export control restrictions on semiconductor manufacturing equipment constrain South Korean and Japanese suppliers from expanding solid-state RF amplifier capacity in China. Magnetron production concentrates in China, South Korea, and Japan, with rare earth magnetic materials and copper windings as critical inputs. Single-source vulnerability around vacuum tube expertise threatens supply continuity as legacy engineers retire. Distribution runs through manufacturer-direct channels for commercial leasing contracts and Alibaba-JD.com ecosystems for residential volume.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The microwave market functions as a regulatory-moat industry where ENERGY STAR and Ecodesign Directive entrenchment creates switching costs for foodservice operators who standardize on certified platforms. This compliance layering defends incumbent positions against low-cost challengers lacking validation infrastructure.
For Market Incumbents: Build certification moats by accelerating inverter technology R&D ahead of Department of Energy threshold tightening. Secure captive magnetron supply through backward integration into Guangdong manufacturing clusters. Consolidate channel control via preventive maintenance subscription bundling that raises switching costs for quick-service restaurant chains evaluating replacement vendors.
For New Entrants and Emerging Players: Establish a beachhead in India's underpenetrated commercial leasing segment where capital-constrained independent restaurants prioritize subscription procurement over ownership. Target steam-injection configurations for Japan's health-conscious residential tier where wellness positioning commands premium tolerance. Deploy direct sales teams with IoT platform integration to bypass entrenched distributor relationships in North American mid-scale chains.
For Investors and Strategic Acquirers: Component-specialist suppliers with solid-state RF amplifier patents represent the most defensible acquisition archetype as magnetron replacement cycles collapse. Long-term viability centers on semiconductor integration capabilities that transcend vacuum tube dependence. Watch for solid-state pilot deployments at major quick-service chains as inflection signal for technology substitution velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Magnetron Production | Samsung Electronics and Panasonic Corporation defend cost positions through captive vacuum tube supply chains. |
| Asset-Light Leasing Channel Expansion | Equipment lessors in Texas and California displace traditional distributors through subscription-based procurement models. |
| Inverter Technology R&D Acceleration | Panasonic Corporation differentiates via power control systems that exceed ENERGY STAR baseline requirements. |
| Smart Kitchen Platform Integration | Direct sales channels bundle IoT connectivity with automated cooking algorithms for premium residential positioning. |
| India Commercial Segment Market Development | Independent restaurants and catering operators in Mumbai represent underpenetrated equipment leasing opportunity. |
Study Parameters
A standing panel of commercial kitchen procurement directors, foodservice equipment distributors, magnetron manufacturing engineers, and restaurant chain operations executives provided ongoing calibration against secondary validation from customs trade records, Department of Energy appliance standards filings, and SAMR GB certification databases. Primary interviews with stakeholders across China, the United States, Germany, and India combined with bottom-up shipment data and top-down macroeconomic triangulation to anchor volume estimates.
Scenario bracketing around efficiency regulation timing and solid-state RF substitution velocity structured the analytical framework across the projection horizon. Segmentation dimensions modeled include installation configuration, power delivery technology, end-user procurement behavior, and distribution channel structure. CAGRs derived from fitted growth curves against historical replacement cycles and urban housing formation patterns in tier-one Chinese cities, with magnetron cost curves and copper commodity trajectories as industry-specific forecast inputs.
Sensitivities concentrate around Department of Energy standard implementation pace and solid-state RF amplifier cost reduction trajectories. Forecasts reflect documented assumptions about replacement cycle stability and commercial kitchen automation adoption. Material shifts in ENERGY STAR threshold stringency or export control expansion would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Appliances
Electric Ranges Market
Appliances
France Household Side by Side Refrigerator Market
Appliances
Europe Garment Steamers Market
Appliances
Window Air Conditioners Market
Appliances
China Washing Machine Market
Appliances
Automatic Dishwasher Market
Appliances
Mexico Washing Machine Market
Appliances
Asia-Pacific Tumble Dryers Market
Appliances
Conveyor Dishwasher Market
Appliances
Colombia Appliances and Electronics Market
Appliances
AI Washing Machine Market
Appliances
Personal Care Appliances Market
Appliances
Asia-Pacific Washing Machine Market
Appliances
Saudi Arabia Electric Water Heater Market
Appliances
Refrigerator Repair Service Market
Appliances
APAC White Goods Market