
 Household Side by Side Refrigerator Market | 2026-2036
Household Side by Side Refrigerator Market Size, Share, and Industry Trends Forecast 2026-2036
Household Side by Side Refrigerator Market Insights
The EU F-Gas Regulation is pivoting appliance manufacturers toward lower-global-warming-potential refrigerant chemistries. Samsung Electronics leverages its semiconductor-derived inverter compressor expertise to sustain premium positioning in frost-free platforms. Haier Group Corporation anchors volume leadership through captive manufacturing scale across multiple continents. LG Electronics differentiates via connected-home integration and AI-driven energy optimization in its smart refrigerator lineup.
A household side by side refrigerator comprises two vertically split compartments with independent temperature zones, typically employing vapor-compression cycles with R-600a or R-134a refrigerants and polyurethane foam insulation to maintain 0-4°C refrigeration and -18°C freezing. The primary purpose is extended food preservation for residential kitchens with high throughput and visibility. Energy Efficient and Smart product types command expanding margin pools as utility rebates and connected-home ecosystems reshape buyer calculus. Inverter technology leads technology segmentation for its load-matching efficiency, while Direct Cool retains economy-tier dominance in price-sensitive markets.
The US EPA SNAP program and California Air Resources Board enforce refrigerant transition timelines that reshape product roadmaps for North American suppliers. BIS energy-labeling mandates in India and China's GB standards for appliance efficiency create parallel compliance architectures that filter market access. Stakeholders must monitor refrigerant chemistry patent cliffs and regional energy-label escalation schedules to align R&D allocation with compliance windows.
Market Dynamics
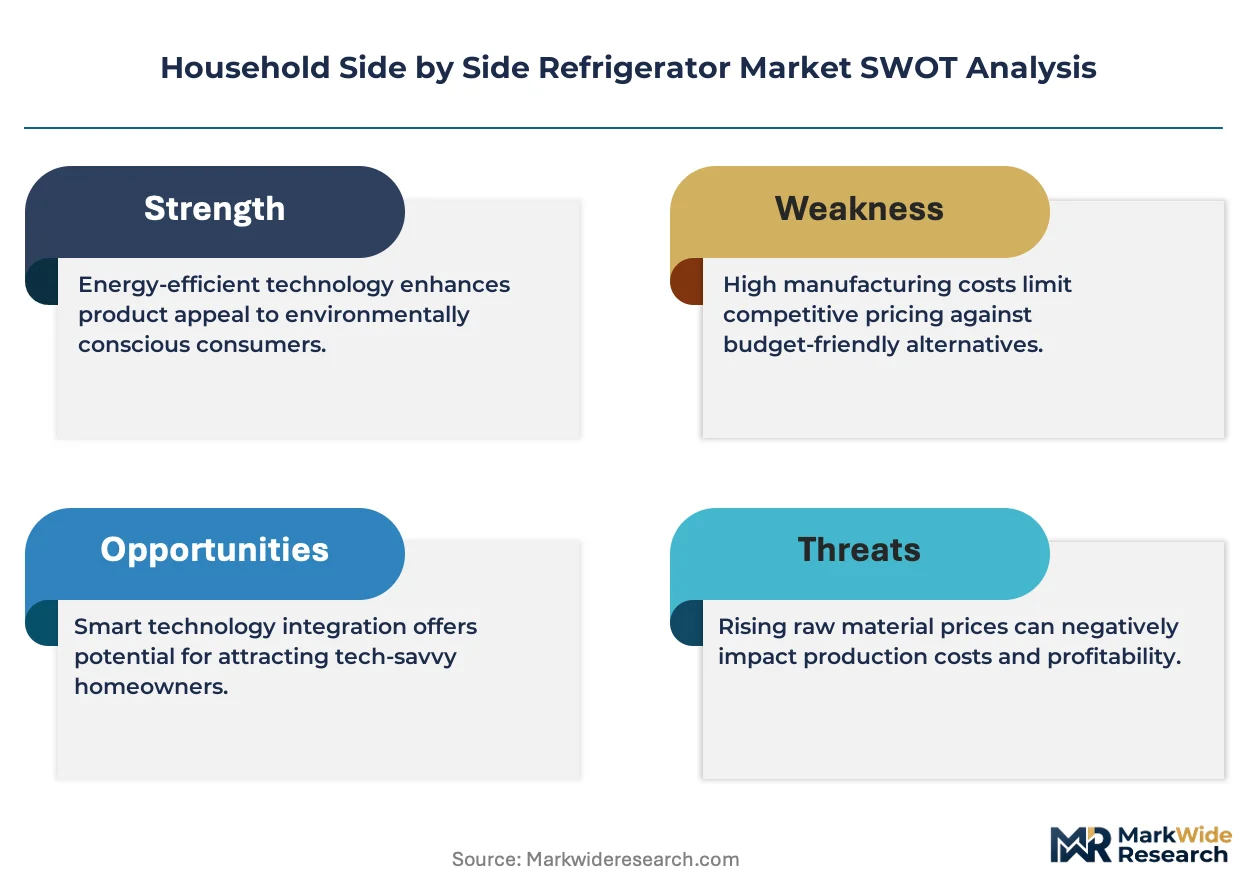
The EU F-Gas Regulation is forcing refrigerant chemistry transitions across manufacturing footprints, compressing product development timelines while opening premium positioning for compliant platforms. This regulatory pressure intersects with inverter compressor maturation and urban residential density shifts to restructure competitive advantage.
Growth Catalysts
- Inverter compressor adoption:Variable-speed drives reduce energy consumption by matching cooling load to compressor output. China's GB standards for appliance efficiency accelerate this transition in high-volume manufacturing zones.
- Urban residential complex expansion:High-rise kitchen configurations favor side-by-side formats with vertical access and visibility. Brazil's middle-class household formation concentrates demand in São Paulo and Rio de Janeiro corridors.
- Utility rebate programs:Energy-efficient model subsidies reduce effective purchase prices for qualified units. India's BIS energy-labeling mandates create tiered incentive structures that pull buyers toward higher-efficiency ratings.
Market Restraints
- Refrigerant input cost volatility:R-600a and lower-GWP alternative chemistries face supply concentration in Chinese petrochemical corridors. Price swings compress margin stability for manufacturers locked into long procurement contracts.
- Polyurethane foam insulation technical limitation:Thermal performance requirements conflict with thickness constraints in standard cabinet dimensions. This forces expensive vacuum-insulated panel adoption in premium tiers.
- Substitution threat from bottom-freezer formats:French-door configurations capture similar capacity requirements with improved freezer ergonomics. This alternative gains share in North American suburban installations.
Strategic Opportunities
- Connected-home ecosystem integration:AI-driven energy optimization and predictive maintenance create recurring service revenue streams. Smart appliance platforms differentiate beyond hardware specifications.
- Rural electrification corridors in India:Grid expansion into tier-2 and tier-3 cities unlocks first-time refrigerator ownership. Side-by-side formats penetrate as aspirational upgrades from single-door units.
- Refrigerant transition patent windows:Lower-GWP formulation chemistry creates temporary exclusivity for early movers. Regulatory compliance deadlines compress competitive response timelines.
Industry Challenges
- Refrigerant handling certification complexity:Technician training for flammable R-600a and emerging A2L blends lags deployment schedules. Service network readiness constrains rollout velocity.
- Cross-border compliance timeline synchronization:Divergent phase-down schedules between EPA SNAP, EU F-Gas, and China's MEE create SKU fragmentation. Product platform economics suffer from regional customization requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Household Side by Side Refrigerator Market |
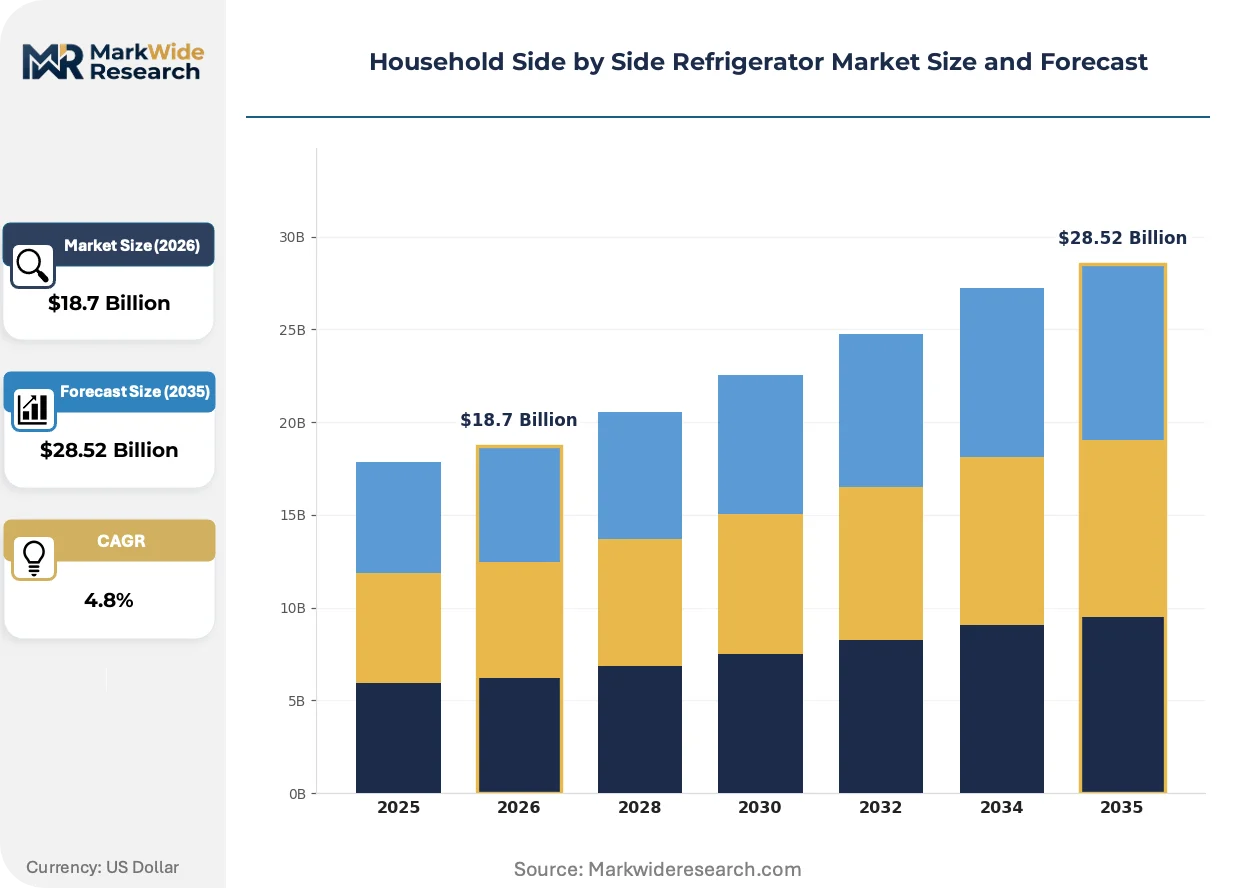
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $28.52 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard, Energy Efficient, Smart, Convertible Technology: Frost-Free, Direct Cool, Inverter, Compressor End User: Kitchen, Restaurants, Cafeterias, Grocery Stores Price Tier: Economy, Mid-Range, Premium, Luxury |
| Companies Covered | Whirlpool Corporation, Haier Group Corporation, Samsung Electronics, LG Electronics, Electrolux, Bosch Group, General Electric, Midea Group, Panasonic Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Household Side by Side Refrigerator Market Trends and Innovations
Refrigerant chemistry transitions and compressor electrification are converging to redefine product architecture. These shifts compress legacy platform lifecycles while opening new competitive dimensions.
Variable-capacity inverter compressors are expanding into mainstream product tiers after proving load-matching efficiency in premium frost-free platforms. Urban residential buyers in China and India specify these units to qualify for utility rebate thresholds. The technology is expanding into economy-tier portfolios as semiconductor cost curves enable cost-neutral integration.
The EU F-Gas Regulation mandates progressive HFC phase-downs that force refrigerant platform redesigns across European manufacturing footprints. Appliance engineers pivot toward R-600a and hydrocarbon blends with lower global warming potential. North American suppliers face parallel pressure from EPA SNAP program timelines, compressing their product roadmap synchronization with European compliance windows.
Buyer preference is rotating toward visible food storage and accessibility features that favor vertical compartment splits. High-throughput households in Brazil and India prioritize door-in-door configurations that reduce cold air loss during frequent access. This behavioral shift pulls procurement toward side-by-side formats even where bottom-freezer alternatives offer comparable capacity economics.
Household Side by Side Refrigerator Market Segmentation
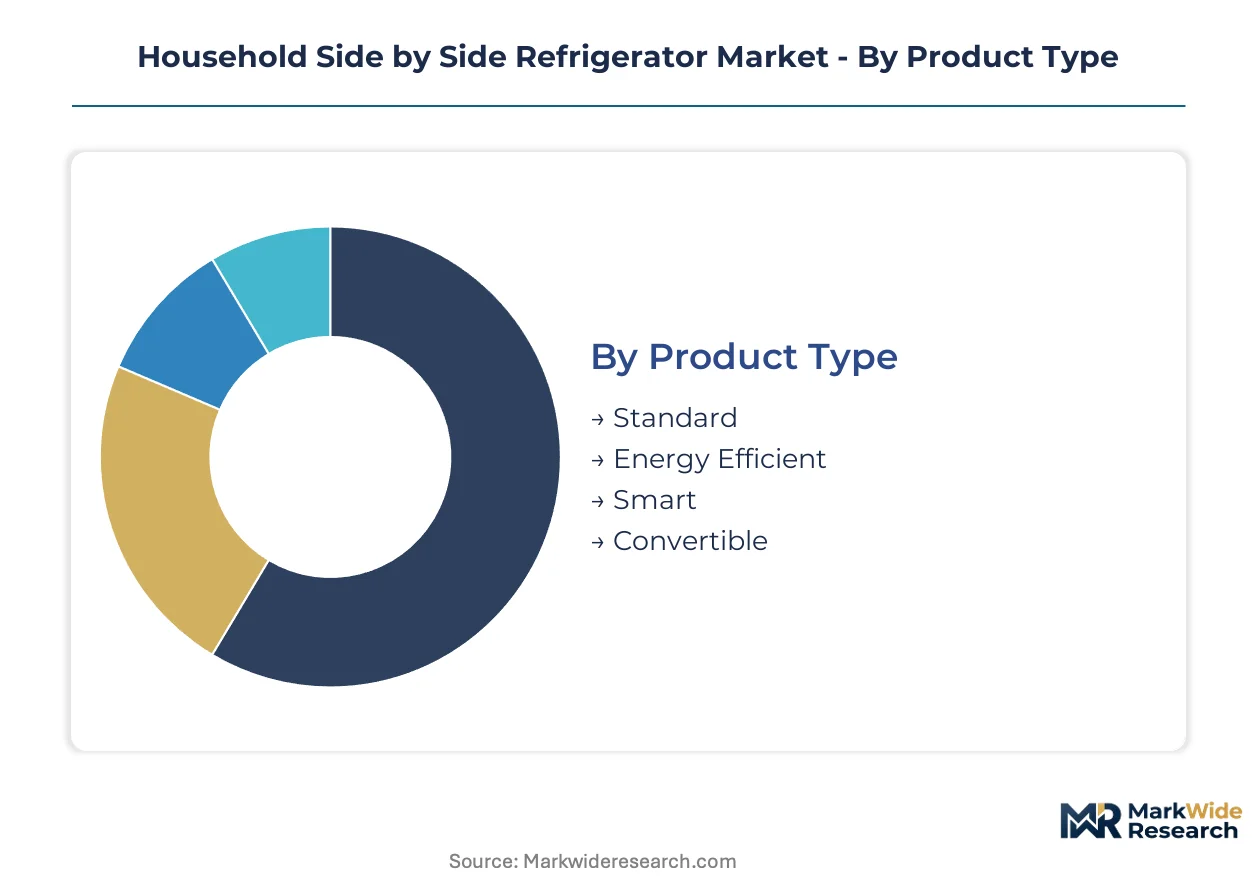
Segmentation in household side by side refrigerators reveals how technology positioning, price architecture, and end-use specifications create distinct margin pools. Procurement patterns diverge sharply across these axes as energy regulations and connected-home ecosystems reshape buyer priorities.
Product Type:
Product type segmentation tracks the efficiency and connectivity spectrum that manufacturers use to tier their portfolios across regulatory environments and utility rebate programs.
- Standard:Conventional vapor-compression units with fixed-speed compressors and basic polyurethane insulation serve price-sensitive replacement cycles in emerging markets. Demand concentrates in Brazil's São Paulo corridor where middle-class household formation prioritizes capacity over efficiency certification.
- Energy Efficient:Inverter-driven compressors with optimized insulation packages qualify for India's BIS energy-labeling rebates and China's GB standards tiered incentives. These units capture expanding margin pools as utility programs reduce effective purchase prices in high-volume manufacturing zones.
- Smart:Connected-home platforms with AI-driven energy optimization and predictive maintenance create recurring service revenue streams. Adoption clusters in urban residential complexes across China where ecosystem integration differentiates beyond hardware specifications.
- Convertible:Flexible compartment configurations switch between refrigeration and freezing modes based on seasonal demand patterns. These units address space-constrained kitchens in India's tier-2 cities where single-appliance versatility substitutes for multiple units.
Standard leads on scale; Smart leads on momentum.
Technology:
Technology segmentation reflects the compressor and refrigerant architecture choices that determine compliance trajectories across divergent regulatory timelines.
- Frost-Free:Forced-air circulation with automatic defrost cycles eliminates manual ice removal and maintains consistent temperature profiles. Samsung Electronics leverages semiconductor-derived inverter expertise to sustain premium positioning in this segment across multiple continents.
- Inverter:Variable-speed drives match compressor output to cooling load, reducing energy consumption by precise thermal demand tracking. China's GB standards accelerate this transition in high-volume manufacturing zones where efficiency mandates reshape procurement specifications.
- Direct Cool:Natural convection cooling with manual defrost retains economy-tier dominance in price-sensitive markets through simpler mechanical architecture. Haier Group anchors volume leadership through captive manufacturing scale deploying this technology.
- Compressor:Core refrigeration engine specifications span reciprocating, rotary, and linear drive architectures with varying noise and efficiency profiles. LG Electronics differentiates via connected-home integration and AI-driven optimization in premium compressor platforms.
Inverter climbs the fastest; Direct Cool retains the largest installed base.
End User:
End user segmentation captures the divergence between residential kitchen specifications and commercial food service requirements that strain the same cabinet architectures.
- Kitchen:Residential installations in urban high-rises and suburban homes prioritize vertical access, visibility, and door-in-door configurations. Brazil's middle-class households drive specification toward side-by-side formats even where bottom-freezer alternatives offer comparable capacity.
- Restaurants:Commercial food service demands higher compressor duty cycles and stainless steel finishes that withstand intensive cleaning protocols. These units command premium pricing through durability certifications and extended warranty terms.
- Cafeterias:Institutional feeding operations require high-throughput visibility and rapid access patterns that favor vertical compartment splits. Procurement concentrates in India's expanding educational and corporate campus infrastructure.
- Grocery Stores:Small-format retail and convenience store applications use residential-scale units for beverage and frozen food display. This segment experiences substitution pressure from purpose-built commercial merchandisers.
Kitchen dominates volume contribution; Cafeterias show steepest expansion trajectory.
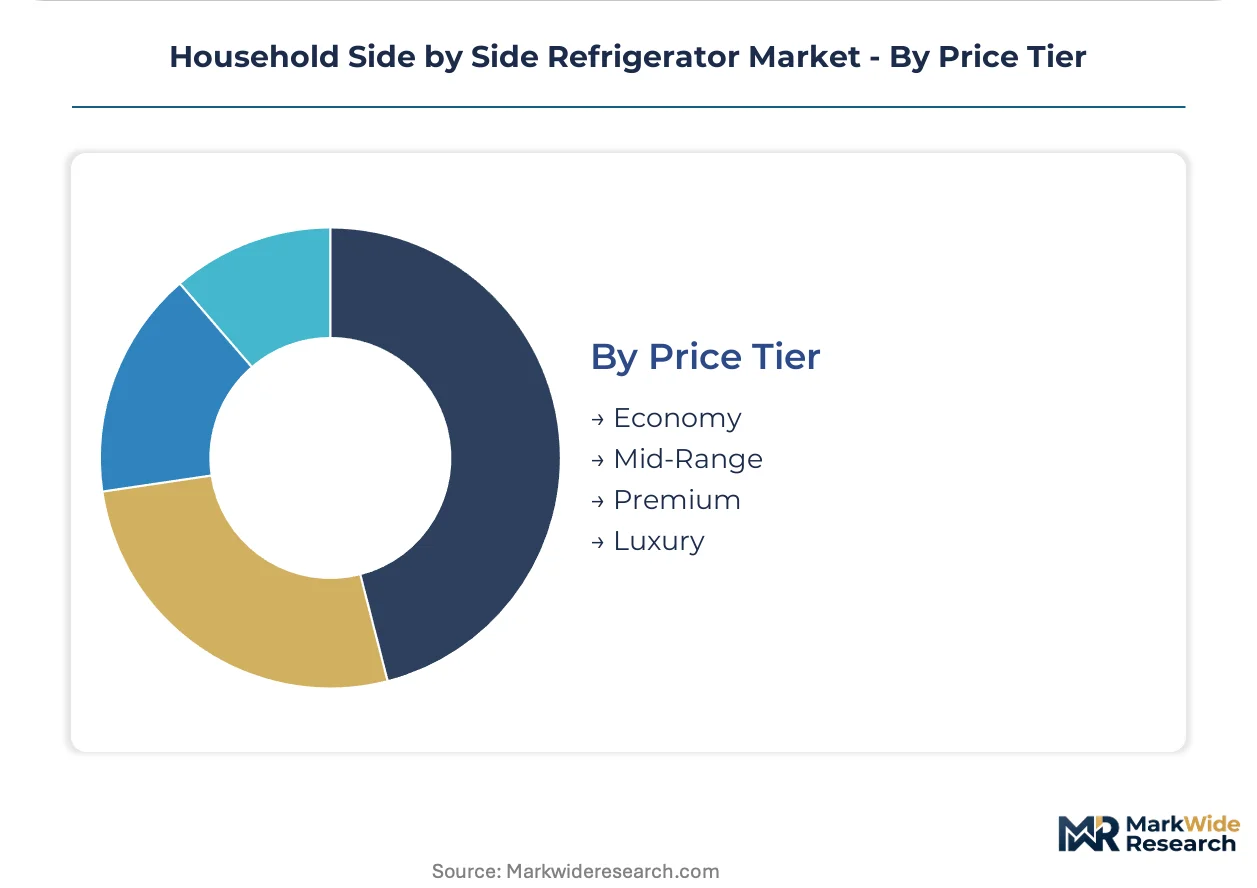
Price Tier:
Price tier segmentation maps how certification grades, material specifications, and feature bundles stratify access across household income distributions.
- Economy:Fixed-speed compressors with basic insulation and manual defrost serve first-time ownership and replacement cycles in rural electrification corridors. India's tier-3 cities unlock demand as grid expansion enables appliance acquisition.
- Mid-Range:Frost-free platforms with partial inverter integration and enhanced finishing materials capture the efficiency-conscious middle market. Utility rebate eligibility pulls procurement toward this tier in regulated markets.
- Premium:Full inverter drives, connected-home integration, and advanced refrigerant chemistries address EU F-Gas Regulation compliance and California Air Resources Board timelines. These units carry the cost of lower-GWP platform development.
- Luxury:Custom panel integration, wine preservation zones, and bespoke interior configurations serve ultra-high-net-worth residential installations. Vacuum-insulated panel adoption resolves thermal performance constraints in constrained cabinet dimensions.
Economy leads on unit volume; Premium gains share fastest as regulatory compliance costs filter down.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Engineering talent pools in compressor electrification and refrigerant chemistry anchor manufacturing competitiveness across major production zones. Workforce density in precision electronics and polymer science determines which geographies capture platform transitions.
China
Urban residential complex construction in Shanghai and Shenzhen drives specification toward inverter-driven frost-free platforms. GB standards for appliance efficiency mandate tiered energy labeling that pulls procurement toward higher-efficiency ratings. Manufacturing concentrates in the Yangtze River Delta where compressor electrification expertise enables cost-neutral integration of variable-speed drives into mid-range portfolios.
United States
Suburban kitchen renovation cycles sustain replacement demand for side-by-side configurations with door-in-door access. EPA SNAP program timelines enforce refrigerant transitions that compress product development roadmaps for domestic suppliers. Production and distribution cluster in the Midwest industrial corridor where logistics infrastructure supports continental-scale fulfillment.
India
Rural electrification into tier-2 and tier-3 cities unlocks first-time refrigerator ownership with aspirational upgrades from single-door units. BIS energy-labeling mandates create tiered incentive structures that pull buyers toward higher-efficiency ratings. Demand concentrates in Maharashtra and Gujarat where middle-class household formation outpaces national averages.
Brazil
São Paulo and Rio de Janeiro corridors concentrate middle-class household formation that prioritizes vertical compartment visibility and accessibility. ANVISA and national energy efficiency programs shape import and certification requirements for foreign suppliers. Local assembly operations in the Southeast industrial zone address import substitution pressures while serving Mercosur distribution.
Germany
EU F-Gas Regulation mandates progressive HFC phase-downs that force refrigerant platform redesigns across European manufacturing footprints. REACH compliance and CE marking requirements filter market access for non-EU suppliers. Engineering expertise in Baden-Württemberg anchors development of lower-GWP hydrocarbon blend systems for premium-tier export.
Household Side by Side Refrigerator Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across divergent technology roadmaps. The vendor base organizes around captive manufacturing scale, semiconductor-derived component expertise, and connected-home platform integration. Three archetypes dominate: integrated appliance conglomerates with continental production footprints, electronics specialists leveraging chip design for compressor control, and diversified industrials with modular platform economics. Competitive moves center on refrigerant transition patent positioning and utility rebate program alignment.
Within the integrated conglomerate tier, Haier Group Corporation and Whirlpool Corporation exemplify scale-driven archetypes with multi-continental manufacturing footprints. Samsung Electronics and LG Electronics occupy positions at the electronics-component interface, leveraging semiconductor expertise for inverter compressor differentiation. Bosch Group represents the diversified industrial archetype with modular platform economics spanning appliance and automotive applications.
| Leading Market Players |
|---|
| Whirlpool Corporation |
| Haier Group Corporation |
| Samsung Electronics |
| LG Electronics |
| Electrolux |
| Bosch Group |
| General Electric |
| Midea Group |
| Panasonic Corporation |
| Others |
Pricing and Supply Chain Analysis
Compressor electrification specialists concentrated in China's Yangtze River Delta and South Korea's Gyeonggi Province create labor-cost differentials that widen spreads between premium inverter-driven units and economy-tier fixed-speed alternatives. GB standards and BIS energy-labeling mandates reshape procurement specifications, pulling buyers toward higher-efficiency ratings that justify price premiums through utility rebate eligibility.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates procurement architectures, with certification grade under EU F-Gas Regulation and India's BIS energy-labeling tier serving as primary differentiation drivers. Price compression runs through economy tiers as Chinese petrochemical corridors concentrate refrigerant supply and compress margin stability for manufacturers locked into long procurement contracts. Rural electrification corridors in India's tier-2 and tier-3 cities exhibit highest price sensitivity, while luxury-tier buyers in Germany and the United States prioritize connected-home integration and custom panel configurations with minimal elasticity.
Supply Chain Analysis
Direct-to-retail channels anchored by big-box appliance chains and e-commerce platforms handle volume distribution across urban residential complexes, while project-direct sales serve commercial food service installations. Manufacturing concentrates in China, South Korea, and Mexico, with compressor electrification components drawing from Taiwanese semiconductor foundries and German precision engineering clusters. Polyurethane foam insulation and lower-GWP refrigerant chemistries rest on petrochemical feedstocks vulnerable to commodity price volatility. Single-source vulnerability in R-600a supply from Chinese chemical corridors presents structural risk to margin stability across all tiers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Inverter compressor maturation and refrigerant transition patent windows create margin expansion opportunities as semiconductor cost curves enable cost-neutral integration of variable-speed drives into mid-range portfolios. Premium-tier shift toward connected-home ecosystems and AI-driven energy optimization sustains pricing power against commodity pressure in economy segments.
For Market Incumbents: Acquire refrigerant chemistry patent portfolios and inverter control algorithm assets to secure compliance runway ahead of EPA SNAP and EU F-Gas deadlines. Consolidate service network capacity for flammable R-600a and emerging A2L blend handling certification to constrain rollout velocity for challengers. Vertical integration into compressor electrification components mitigates semiconductor supply concentration risk from Taiwanese foundries. For New Entrants and Emerging Players: Begin with convertible compartment configurations targeting India's tier-2 cities where space-constrained kitchens demand single-appliance versatility substituting for multiple units. Rural electrification corridors in Maharashtra and Gujarat present white-space penetration opportunity as grid expansion unlocks first-time refrigerator ownership with aspirational side-by-side upgrades. Direct-to-consumer digital channels bypass incumbent retail gatekeeper relationships in Brazil's São Paulo corridor. For Investors and Strategic Acquirers: Electronics specialists with semiconductor-derived compressor control expertise are the most active acquirer in this space, seeking appliance manufacturing scale to complete vertical integration. Long-term viability hinges on refrigerant transition patent positioning and utility rebate program alignment across divergent regulatory timelines. Monitor EPA SNAP program timeline synchronization with EU F-Gas phase-down schedules as inflection indicator for SKU fragmentation risk and platform economics stress.| Strategic Initiative | Industry Significance |
|---|---|
| Refrigerant Platform Redesign | EU F-Gas Regulation mandates lower-GWP hydrocarbon blends that force manufacturing footprint retooling. |
| Inverter Compressor Integration | Semiconductor cost curves enable cost-neutral variable-speed drive adoption in mid-range portfolios. |
| Connected-Home Ecosystem Development | AI-driven energy optimization creates recurring service revenue beyond hardware specifications in China's urban complexes. |
| Service Network Certification Buildout | Technician training for flammable R-600a handling lags deployment schedules and constrains rollout velocity. |
| Utility Rebate Program Alignment | India's BIS energy-labeling and China's GB standards create tiered incentive structures that reshape procurement. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with appliance manufacturing executives, compressor electrification engineers, retail category buyers, regulatory affairs specialists, and aftermarket service network managers with secondary validation. Trade customs data, SEC appliance segment disclosures, BIS and GB standards documentation, and utility rebate program filings anchored supply-side and demand-side triangulation. Bottom-up unit shipment modeling and top-down value reconciliation cross-checked segment outputs.
Historical reference periods spanning pre-regulatory baseline through active transition phases anchored the projection horizon across technology adoption curves and compliance deadline clustering. Segmentation dimensions modeled include product type efficiency tier, compressor technology architecture, end-use kitchen versus commercial specification, and regional regulatory framework cluster. CAGRs derived from fitted technology diffusion curves incorporating inverter adoption rates and refrigerant transition velocity. Forecast inputs included utility rebate program expansion schedules and rural electrification grid connection trajectories.
Several conditions sit outside the modeled scope, including abrupt refrigerant chemistry patent litigation, trade policy discontinuities affecting compressor component flows, and pandemic-scale demand shocks disrupting replacement cycles. Forecasts reflect assumptions about regulatory timeline adherence and semiconductor cost curve continuity. Periodic stress-testing of base assumptions is recommended against EPA SNAP program revisions and EU F-Gas phase-down acceleration scenarios.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Appliances
Washing Appliances Market
Appliances
United States Microwave Oven Market
Appliances
Wall Oven Market
Appliances
United States Electronics and Appliance Stores Market
Appliances
Sanitary Towel Machine Market
Appliances
Electric Dryers Market
Appliances
United States Electric Kettle Market
Appliances
North America Tumble Dryers Market
Appliances
Small Electric Kettles Market
Appliances
Mexico Washing Machine Market
Appliances
UAE Microwave Ovens Market
Appliances
Cordless Vacuum Cleaner Market
Appliances
Dishwasher Market
Appliances
United Kingdom Handheld Vacuum Cleaners Market
Appliances
Qatar Dishwashers Market
Appliances
Smart Washing Machine Market