
 Smart Connected Washing Machine Market | 2026-2036
Smart Connected Washing Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Connected Washing Machine Market Analysis
Multi-unit residential property management is consolidating procurement of connected laundry fleets as build-to-rent developments expand across North America and Western Europe. Samsung Electronics leverages its SmartThings platform to anchor ecosystem lock-in across apartment installations. LG Electronics competes through AI-driven fabric care algorithms that differentiate its ThinQ-enabled units in premium channels. Whirlpool Corporation sustains commercial-grade reliability ratings that dominate hospitality and coin-laundry verticals.
A smart connected washing machine integrates sensors, microprocessors, and wireless communication modules to enable remote operation, predictive maintenance, and energy optimization through cloud-based analytics. These appliances typically incorporate load-weight detection, vibration reduction motors, and automatic detergent dosing to minimize water and chemical consumption per cycle. Front-load configurations command margin pools in European and North American markets where energy efficiency certifications influence purchasing decisions. Wi-Fi-enabled units represent the dominant technology segment, though IoT-connected platforms with open APIs are gaining traction among property technology integrators seeking centralized building management interfaces.
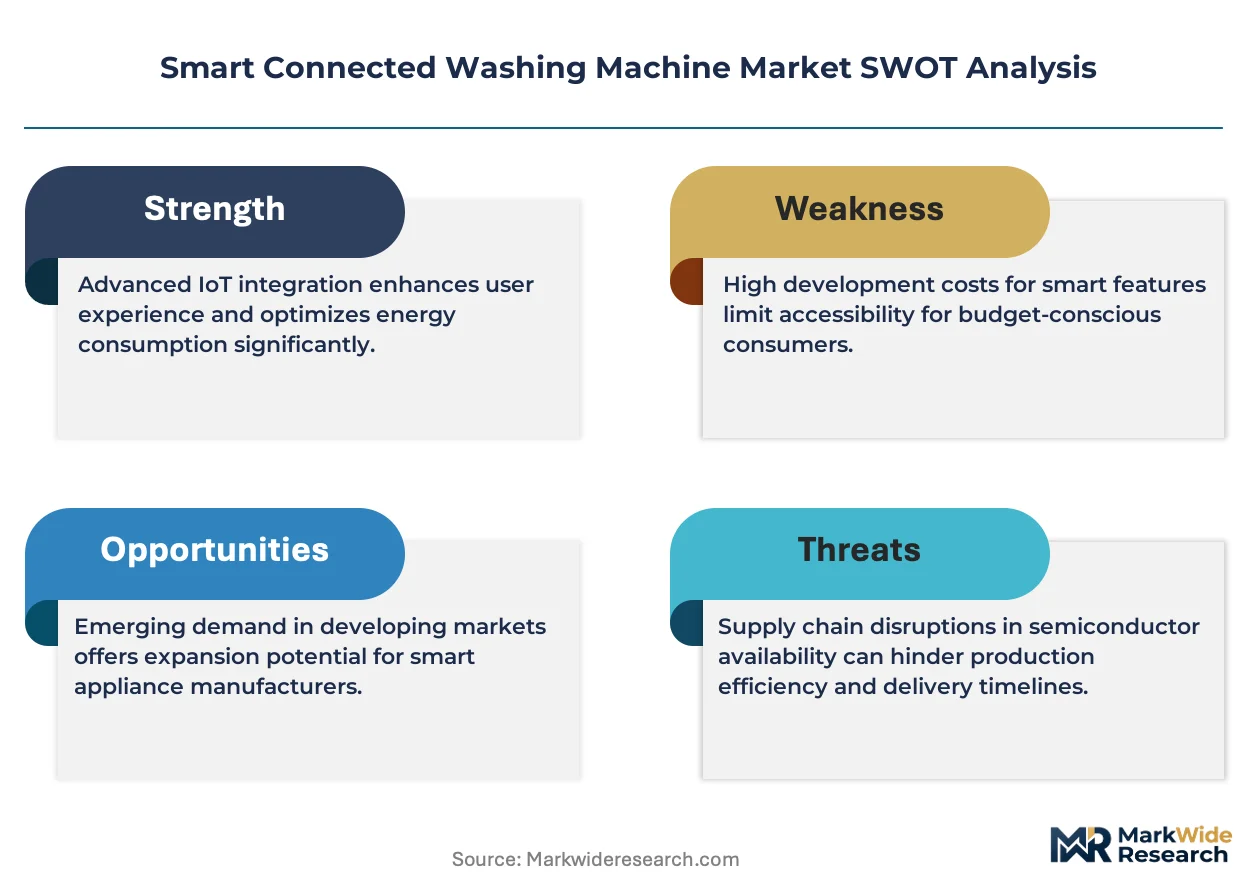
The EU Ecodesign Directive and Energy Labeling Framework mandate minimum efficiency thresholds for networked appliances sold in member states, while the U.S. EPA ENERGY STAR program sets voluntary benchmarks that de facto shape retailer assortment decisions. China's GB standards for household appliance energy consumption, administered by SAMR, create compliance costs that favor scaled manufacturers with in-house testing laboratories. Stakeholders must monitor fragmentation between proprietary cloud protocols and emerging Matter interoperability standards, as the resolution of this tension will determine whether platform owners or appliance makers capture recurring service revenue.
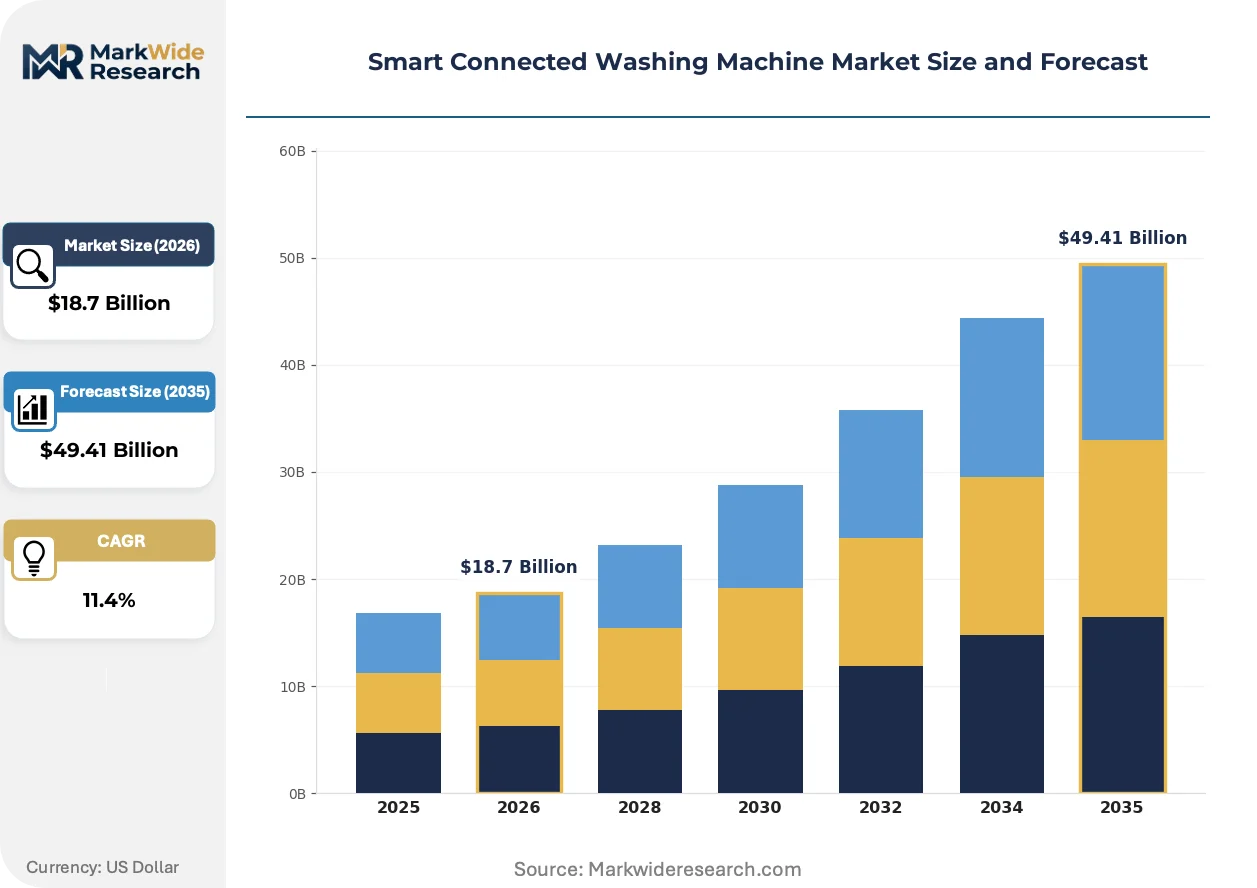
Market Dynamics
Consolidation of purchasing power across multi-unit residential portfolios is compressing sales cycles and forcing manufacturers to reconfigure service architectures around fleet management rather than individual unit retail.
Growth Catalysts
- EU Ecodesign Directive:Tightening minimum efficiency thresholds for networked appliances in member states is accelerating replacement cycles among efficiency-conscious households and institutional buyers.
- Build-to-rent developments:North American and Western European property technology platforms are standardizing connected laundry infrastructure as amenity differentiators in competitive rental markets.
- AI-driven fabric care algorithms:Machine learning models that optimize water temperature and mechanical action per load are commanding price premiums in premium residential channels.
Market Restraints
- Semiconductor supply concentration:Microprocessor and Wi-Fi module fabrication concentrated in East Asian foundries creates vulnerability to geopolitical trade friction and capacity constraints.
- Copper and rare earth volatility:Motor windings and permanent magnet materials face input cost swings that compress margin predictability for mid-tier manufacturers.
- Proprietary cloud protocol fragmentation:Incompatible manufacturer-specific platforms prevent seamless multi-brand fleet management for property managers seeking vendor flexibility.
Strategic Opportunities
- Matter interoperability standard:Emerging open-source protocol adoption creates white space for third-party property management software integrators to capture service revenue streams.
- Coin-laundry vertical modernization:Cashless payment integration and remote cycle monitoring are unlocking upgrade demand in aging North American self-service laundry infrastructure.
- India BIS energy labeling expansion:Mandatory efficiency disclosure requirements for household appliances are creating first-mover advantages for connected models with verifiable consumption data.
Industry Challenges
- Cybersecurity certification timelines:IEC 62443 compliance for industrial IoT security is extending product development cycles and requiring dedicated firmware engineering teams.
- Legacy building electrical infrastructure:Older multi-unit residential properties lack dedicated circuits and load capacity for high-efficiency front-load installations, forcing expensive retrofit coordination.
- Cross-functional talent scarcity:Appliance engineering teams lack embedded systems and cloud architecture expertise, slowing platform development relative to pure-play IoT competitors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Connected Washing Machine Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $49.41 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Front-Load, Top-Load, Washer-Dryer Combo, Stackable Technology: Wi-Fi Enabled, NFC, IoT-Connected, Cloud-Based End User: Residential, Commercial, Hospitality, Industrial Features: Smart Control, Energy Efficiency, Self-Cleaning, Automatic Detergent Dispenser |
| Companies Covered | Samsung Electronics, LG Electronics, Haier Group Corporation, Whirlpool Corporation, BSH Hausgeräte GmbH, Panasonic Corporation, AB Electrolux, Siemens AG, GE Appliances, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Connected Washing Machine Market Emerging Trajectories
Sensor fusion and edge computing capabilities are migrating from premium tiers toward mass-market price points, compressing the technology diffusion cycle and redefining baseline consumer expectations for appliance intelligence.
Load-weight detection combined with automatic detergent dosing is overtaking manual configuration as the default expectation in European and North American retail channels. Property management firms deploying fleet-scale installations are specifying these capabilities as standard procurement requirements. The shift is overtaking traditional feature differentiation strategies based on mechanical reliability alone, forcing manufacturers to compete on algorithmic performance and data integration depth.
China's GB standards for household appliance energy consumption, administered by SAMR, are tightening testing protocols for networked standby power and active-mode efficiency. Domestic manufacturers with in-house certification laboratories are accelerating product refresh cycles to maintain compliance headroom. Export-oriented producers face compliance cost escalation that favors scaled players with dedicated regulatory affairs teams.
Subscription-based detergent replenishment and predictive maintenance bundles are displacing transactional hardware sales in direct-to-consumer channels. Appliance manufacturers are building recurring revenue models through integrated consumable logistics and remote diagnostic services. China and South Korea represent the most advanced markets for this transition, with integrated smart home ecosystems enabling seamless service bundling.
Smart Connected Washing Machine Market Segmentation
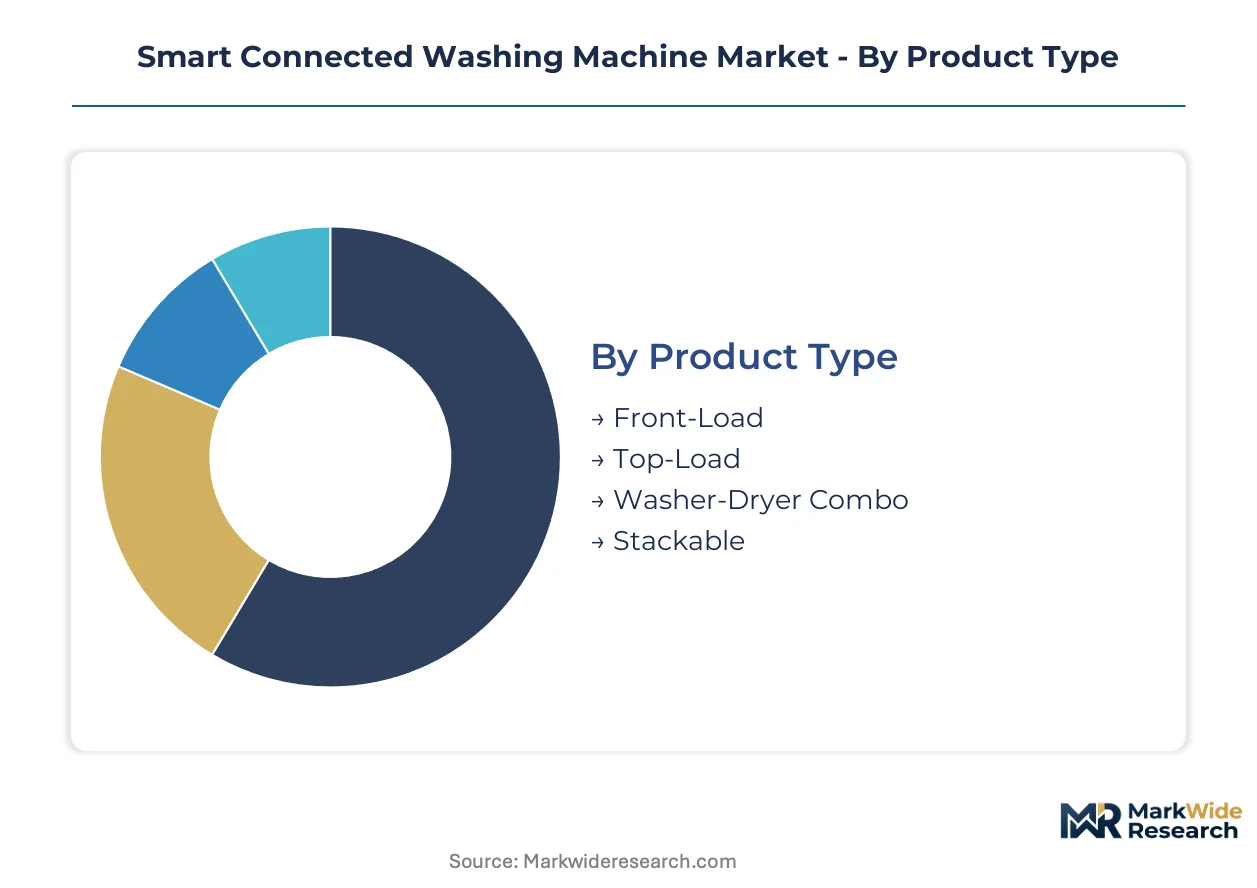
Segmentation in the Smart Connected Washing Machine Market reveals how purchasing power consolidates around specific configurations and connectivity architectures. Fleet operators and institutional buyers drive standardization that compresses variant proliferation while elevating service integration requirements.
Product Type:
Supply concentration among front-load specialists in Germany and South Korea shapes component availability and pricing dynamics for this category.
- Front-Load:Horizontal drum orientation enables superior water efficiency and gentler mechanical action on fabrics. Demand concentrates in European markets where the EU Ecodesign Directive mandates minimum efficiency thresholds, with property management firms specifying these units for build-to-rent developments.
- Top-Load:Vertical axis configuration with agitator or impeller mechanisms offers faster cycle completion and ergonomic loading height. North American residential channels favor these units where legacy electrical infrastructure in older multi-unit properties limits front-load adoption.
- Washer-Dryer Combo:Integrated washing and drying functions within a single cabinet address space constraints in urban apartments.
- Stackable:Vertical pairing of separate washer and dryer units maximizes floor space efficiency in compact utility rooms.
Today's leader: Front-Load. Tomorrow's challenger: Stackable configurations in dense urban housing.
Technology:
Cost tier differentiation separates basic connectivity from premium ecosystem integration, with mid-tier manufacturers struggling to bridge the capability gap.
- Wi-Fi Enabled:Wireless local network connectivity enables smartphone-based remote start, cycle monitoring, and maintenance alerts. Mass-market retail channels in the United States and China standardize this capability as baseline consumer expectation.
- IoT-Connected:Full internet protocol stack with cloud analytics, predictive maintenance algorithms, and API access for third-party integration. Property technology platforms in Germany and the Netherlands specify these units for centralized building management systems.
- NFC:Near-field communication for tap-to-pair authentication and localized data exchange without full network dependency.
- Cloud-Based:Processing and storage offloaded to remote servers enabling continuous software updates and subscription service bundling.
Volume concentrates in Wi-Fi Enabled. Margin accrues to IoT-Connected platforms with recurring revenue attachment.
End User:
Application-specific durability requirements and usage intensity create divergent procurement specifications across customer types.
- Residential:Individual household ownership with moderate duty cycles and premium placed on noise reduction and aesthetic integration. China's tier-one cities anchor volume through smart home ecosystem bundling by Haier and Midea.
- Commercial:Multi-unit residential fleet deployments with centralized management, cashless payment systems, and remote diagnostics. North American build-to-rent developers specify these capabilities as amenity differentiators in competitive rental markets.
- Hospitality:Hotel and resort on-premise laundry operations demanding commercial-grade reliability ratings and rapid cycle turnaround.
- Industrial:High-throughput processing facilities for healthcare, food service, and uniform rental operations with specialized sanitization protocols.
Fleet-scale Commercial procurement is climbing the fastest. Residential remains the volume foundation.
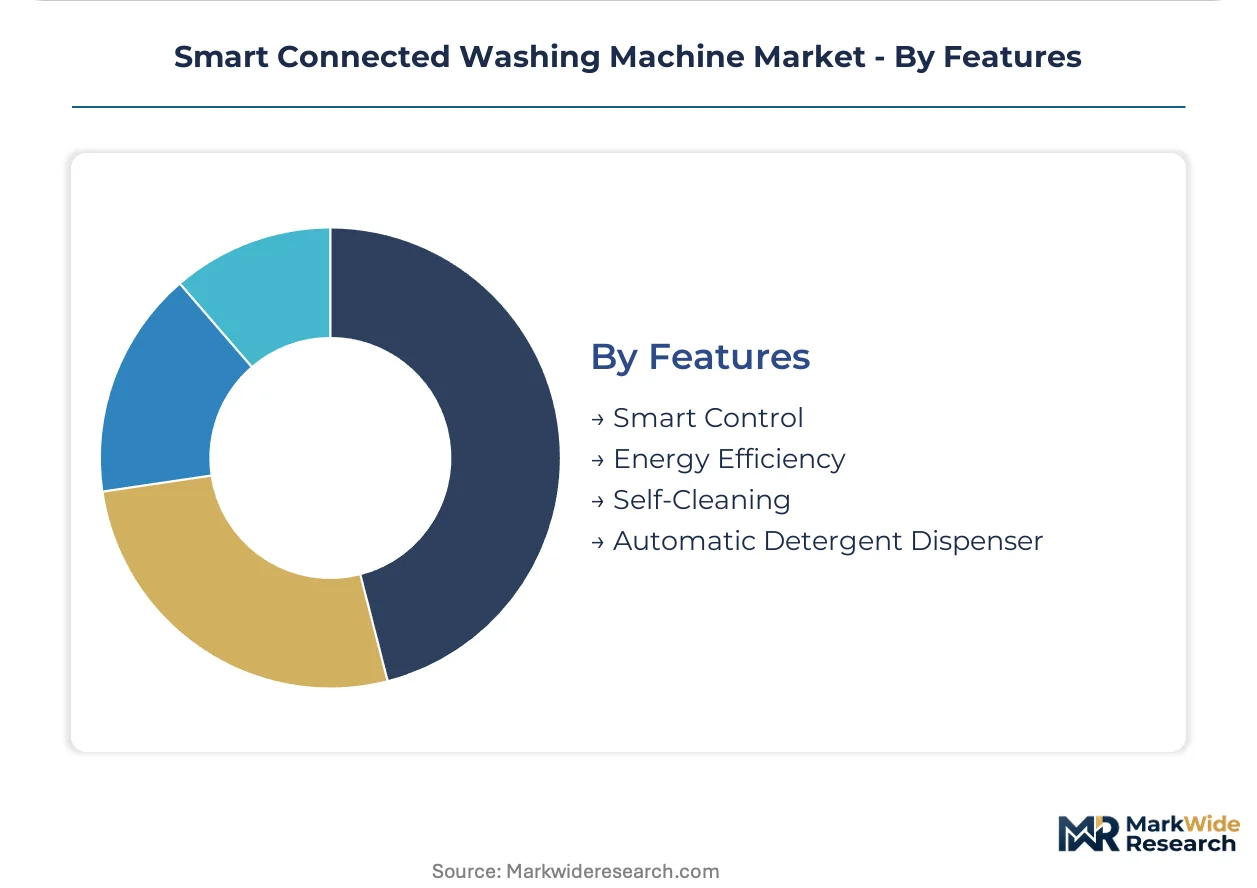
Features:
Customer type determines which capabilities command price premiums versus baseline inclusion.
- Energy Efficiency:Optimized motor control, heat pump drying, and load-adaptive water heating minimize consumption per cycle. The U.S. EPA ENERGY STAR program shapes retailer assortment decisions through voluntary benchmarks.
- Smart Control:Voice assistant integration, geofencing triggers, and automated scheduling based on utility rate signals. South Korean manufacturers lead algorithm development for these capabilities.
- Self-Cleaning:Automated drum sanitization cycles and drain pump flushing reduce maintenance requirements and odor accumulation.
- Automatic Detergent Dispenser:Load-weight sensors trigger precise dosing of liquid or pod detergents, minimizing chemical waste and optimizing cleaning performance.
Energy Efficiency dominates regulatory compliance. Smart Control drives ecosystem lock-in and recurring service attachment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is reshaping manufacturing footprints as producers migrate toward jurisdictions with streamlined compliance pathways and integrated testing infrastructure. The EU Ecodesign Directive's efficiency mandates accelerate replacement cycles in Western Europe while China's GB standards create compliance cost barriers that favor scaled domestic manufacturers.
United States
Build-to-rent developers in Texas and Florida are standardizing connected laundry infrastructure as amenity differentiators in competitive rental markets. The EPA ENERGY STAR program shapes retailer assortment decisions through voluntary benchmarks that de facto become procurement requirements. Atlanta anchors property technology platform development for centralized building management integration.
Germany
Front-load configuration demand concentrates among efficiency-conscious households and institutional buyers responding to EU Ecodesign Directive thresholds. The country's national appliance regulator enforces stringent networked standby power testing protocols. The Rhine-Ruhr industrial corridor hosts specialized motor and control system suppliers serving premium-tier manufacturers.
China
Tier-one cities including Shanghai and Beijing anchor volume through smart home ecosystem bundling by domestic platform owners. SAMR-administered GB standards for household appliance energy consumption tighten testing protocols for networked standby power. The Yangtze River Delta manufacturing cluster concentrates Wi-Fi module and sensor component production.
South Korea
AI-driven fabric care algorithm development commands price premiums in premium residential channels domestically and for export. The Ministry of Trade, Industry and Energy (METI) coordinates smart appliance standardization with regional interoperability initiatives. Seoul Capital Area manufacturers lead edge computing migration toward mass-market price points.
India
Mandatory BIS energy labeling expansion for household appliances creates first-mover advantages for connected models with verifiable consumption data. The Bureau of Indian Standards tightens disclosure requirements that favor digitized efficiency tracking. Maharashtra's Pune-Aurangabad industrial belt attracts component assembly investments from export-oriented producers.
Smart Connected Washing Machine Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with ecosystem owners capturing recurring service revenue while fabrication specialists compete on component cost and assembly scale. The vendor base organizes around three tiers: integrated platform owners with proprietary cloud infrastructure, component-scale specialists supplying private-label retailers, and regional assemblers serving price-sensitive emerging markets. Two competitive moves dominate: strategic partnerships between appliance makers and property technology platforms for fleet deployment contracts, and backward integration into sensor and motor production to secure supply continuity.
Among Asian-headquartered platform owners, Samsung Electronics and LG Electronics occupy positions as ecosystem anchors, with the former leveraging its SmartThings platform and the latter competing through AI-driven fabric care differentiation. Haier Group Corporation represents the vertically integrated archetype with in-house certification laboratories and smart home ecosystem bundling capabilities. These three exemplify how scale and regulatory compliance infrastructure determine competitive position in efficiency-regulated markets.
| Leading Market Players |
|---|
| Samsung Electronics |
| LG Electronics |
| Haier Group Corporation |
| Whirlpool Corporation |
| BSH Hausgeräte GmbH |
| Panasonic Corporation |
| AB Electrolux |
| Siemens AG |
| GE Appliances |
| Others |
Supply Flow & Price Mechanics
Certification-grade divergence between ENERGY STAR-qualified IoT platforms and basic Wi-Fi-enabled units manifests in both channel markups and component sourcing strategies. Premium-tier manufacturers absorb SAMR laboratory costs and Matter interoperability investments into hardware pricing, while mid-tier competitors face margin compression from concentrated semiconductor procurement in the Yangtze River Delta.
Pricing Analysis
Distributor margins on front-load fleet contracts compress where property technology platforms consolidate procurement across multi-unit portfolios. Three-tier pricing structure across premium, standard, and economy levels reflects differentiation by AI algorithm sophistication and API accessibility rather than mechanical reliability alone. Price erosion runs through basic Wi-Fi-enabled units as Chinese module suppliers achieve scale. Commercial fleet buyers exhibit lowest price sensitivity due to amenity-driven procurement specifications, while individual residential purchasers in North American retail channels drive transactional discounting.
Supply Chain Analysis
Freight cost volatility on trans-Pacific routes from Shanghai and Busan to Long Beach and Rotterdam elevates landed costs for European and North American assemblers sourcing motor controllers and load sensors. Component fabrication concentrates in China, South Korea, and Germany, with permanent magnet materials drawing from concentrated rare earth processing. Single-source vulnerability in Wi-Fi module supply creates exposure to foundry capacity allocation decisions. Distribution runs through property technology integrators for fleet-scale commercial deployments and big-box retail channels for residential replacement cycles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Smart Connected Washing Machine Market compounds steadily as regulatory efficiency mandates across the EU, China, and India force replacement cycles regardless of macroeconomic conditions.
For Market Incumbents: Cement ecosystem lock-in through backward integration into sensor production and exclusive fleet management contracts with build-to-rent developers. Threat from pure-play IoT platform competitors with superior cloud architecture expertise demands accelerated firmware engineering hiring. Prioritize IEC 62443 cybersecurity certification to extend development cycle headroom against mid-tier challengers.
For New Entrants and Emerging Players: Begin with coin-laundry vertical modernization in North American markets where aging cash infrastructure creates white space for cashless payment integration. Target India's BIS energy labeling expansion as the most penetrable geography where verifiable consumption data commands first-mover premiums. Pursue white-label partnerships with regional property management software vendors rather than direct appliance brand building.
For Investors and Strategic Acquirers: Consolidation pressure builds where mid-tier manufacturers lack in-house SAMR certification laboratories and face compliance cost escalation from tightening GB standards. Long-term viability favors vertically integrated platform owners with recurring service revenue attachment over component-scale specialists. Monitor Matter interoperability adoption rates as the inflection signal determining whether appliance makers or third-party integrators capture service margins.
| Strategic Initiative | Industry Significance |
|---|---|
| Matter Interoperability Certification | Determines service revenue capture between appliance OEMs and property technology platforms. |
| AI-Driven Fabric Care Algorithm Development | Commands price premiums in South Korean and German premium residential channels. |
| Fleet Management Platform Integration | Locks in multi-year contracts with North American build-to-rent developers. |
| Backward Integration into Sensor Production | Secures supply continuity against East Asian foundry concentration risks. |
| Predictive Maintenance Service Bundling | Transforms transactional hardware sales into recurring revenue in China and South Korea. |
Methodological Framework
Coverage spans North America, Western Europe, and Asia-Pacific, with primary inputs from each region combined with secondary validation. Interviews with appliance engineering directors, property technology platform procurement leads, smart home ecosystem architects, and regulatory affairs specialists at scaled manufacturers informed demand-side and supply-side assessments. Secondary sources include EPA ENERGY STAR certification databases, SAMR GB standard filings, EU Ecodesign Directive implementation reports, and trade customs data on component flows. Bottom-up unit shipment modeling and top-down value triangulation cross-validated segment-level estimates.
Rate-of-change decomposition separates replacement cycle acceleration from first-penetration demand across the analysis window. Segmentation dimensions modeled include product configuration, connectivity architecture, end-user application, and regional regulatory cluster. CAGRs derive from installed base evolution, efficiency mandate compliance deadlines, and smart home ecosystem adoption curves. Forecast inputs incorporate semiconductor supply constraints, copper and rare earth price trajectories, and property technology platform deployment timelines.
Several conditions sit outside the modeled scope, including geopolitical trade friction escalation, catastrophic foundry disruption, and retroactive cybersecurity certification requirements. Forecasts reflect documented assumptions about Matter standard adoption velocity and fleet procurement consolidation rates. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Appliances
Fully Automatic Dishwasher Market
Appliances
Microwave Market
Appliances
Colombia Laundry Appliances Market
Appliances
UAE Dishwasher Market
Appliances
Small Appliances Market
Appliances
Portable Fridges Market
Appliances
US Washing Machine Parts Market
Appliances
Asia-Pacific Tumble Dryers Market
Appliances
Electrical Appliances Plastics Market
Appliances
Europe Microwave Oven Market
Appliances
Smart Refrigerator Market
Appliances
APAC White Goods Market
Appliances
Refrigerator Door Seal Market
Appliances
Induction Cooktops Market
Appliances
Body Dryer Market
Appliances
UAE Microwave Ovens Market