
 Kuwait Home Appliances Market | 2026-2036
Kuwait Home Appliances Market Size, Share, and Industry Trends Forecast 2026-2036
Kuwait Home Appliances Market Foresight
Kuwait's mandatory energy efficiency labeling is consolidating the cost-of-entry calculus for appliance importers, forcing smaller trading houses to absorb certification costs or exit. LG Electronics leverages its established service infrastructure across the emirate to sustain repeat purchases in premium cooling segments. Midea Group competes aggressively on price while navigating the Gulf Technical Regulation for low-energy appliances. Samsung Electronics anchors its position through integrated smart-home ecosystems that lock in multi-device households.
Kuwait home appliances comprise electrically powered machines designed for domestic tasks, typically operating at 240V/50Hz with desert-climate adaptations such as enhanced corrosion resistance and high-ambient-temperature compressor ratings; their primary purpose is to automate food preservation, garment cleaning, thermal comfort, and meal preparation in residential and commercial settings. Air conditioners dominate volume given Kuwait's extreme summer heat, though margin pools concentrate in premium refrigeration where inverter technology and smart connectivity differentiate offerings. The distribution channel structure shows online retail gaining traction among younger demographics, while specialty stores retain dominance in high-consideration purchases requiring installation and warranty assurance.
The Public Authority for Industry (PAI) administers Gulf Standardization Organization conformity marks, while the Ministry of Electricity and Water promotes demand-side management programs that steer consumer preference toward A+++ rated units. Kuwait's national building codes increasingly mandate energy-efficient appliance specifications in new construction, tightening the regulatory boundary for non-compliant imports. Stakeholders must monitor evolving Gulf Technical Regulations and local subsidy programs that could abruptly shift the competitive balance between imported and domestically assembled product lines.
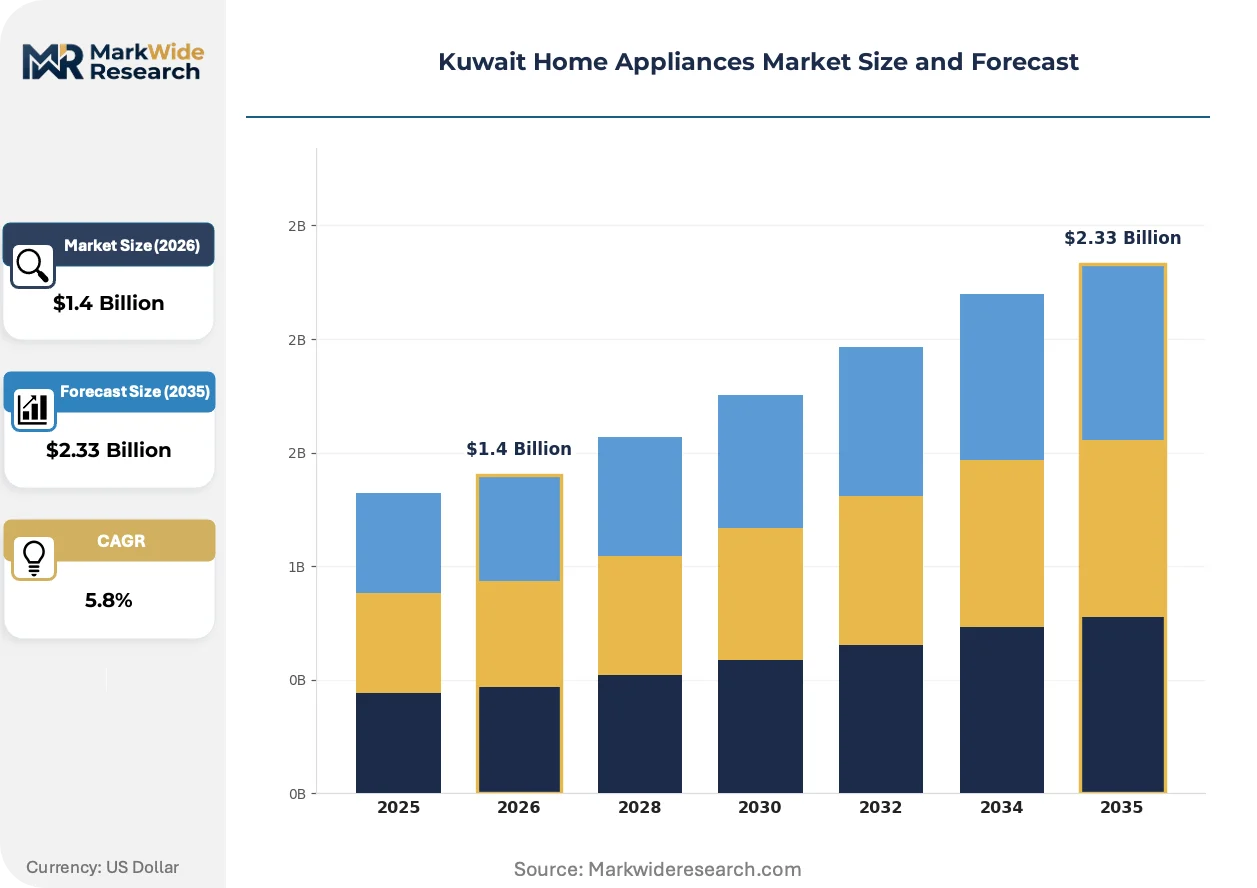
Market Dynamics
Kuwait's mandatory Gulf Technical Regulation for energy-efficient appliances is compressing import margins while accelerating consolidation among trading houses unable to absorb recurring conformity assessment costs.
Growth Catalysts
- Residential construction permits:New housing developments in Hawalli and Ahmadi governorates are embedding inverter-rated cooling systems as baseline specifications, pulling volume through project channels.
- PAI certification alignment:Streamlined Gulf Standardization Organization mark recognition reduces duplicate testing for manufacturers already compliant with Saudi and UAE regimes, shortening Kuwait entry timelines.
- Smart-home integration:Wi-Fi-enabled appliance ecosystems are locking multi-device households into platform-specific repurchase cycles, raising lifetime value per installed base.
Market Restraints
- Copper and aluminum input volatility:Compressor and heat exchanger fabrication costs swing with London Metal Exchange pricing, eroding forward-margin visibility for distributors holding inventory.
- Single-port concentration:Shuwaikh Port handles over 90% of appliance imports, creating customs clearance bottlenecks during peak summer pre-stocking windows.
- Technical labor scarcity:Certified refrigeration technicians and inverter control board diagnosticians remain under-supplied relative to installed-base growth, extending service wait times.
Strategic Opportunities
- Jahra Governorate penetration:Lower appliance density per household and rising expatriate worker housing construction create first-mover positioning for value-tier cooling and laundry equipment.
- Ministry demand-side management subsidies:Rebate programs for A+++ rated units steer retail preference toward premium efficiency tiers, compressing payback periods for inverter technology upgrades.
- Direct-to-installer digital platforms:Contractor-facing apps bypass traditional distributor markups, capturing margin pool reallocation in commercial hospitality fit-outs.
Industry Challenges
- GSO mark renewal timelines:Factory audit scheduling backlogs and documentation resubmission cycles delay seasonal product launches, compressing effective selling windows.
- Legacy 240V infrastructure compatibility:Voltage fluctuation tolerance requirements add design complexity for smart-connected control modules, raising failure rates in older residential districts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Kuwait Home Appliances Market |
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.33 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Refrigerators, Washing Machines, Ovens, Air Conditioners Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Wholesale Price Tier: Economy, Mid-Range, Premium, Luxury End User: Residential, Commercial, Institutions, Government |
| Companies Covered | Whirlpool Corporation, Midea Group, Panasonic, LG Electronics, Sharp Corporation, Samsung Electronics, Bosch, Haier Group Corporation, Electrolux, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Kuwait Home Appliances Market Shifts & Advancements
Connected appliance ecosystems and efficiency-grade compression are redrawing competitive boundaries in Kuwait's import-dependent market, with regulatory stringency now outpacing product-cycle innovation.
Inverter-driven variable-speed compressor technology is electrifying residential cooling efficiency benchmarks. Villa owners in Salmiya and Fahaheel are specifying dual-rotary inverter systems as standard, displacing fixed-speed units from new construction tenders. This electrifying shift is compressing margin pools for basic-tier imports while rewarding manufacturers with captive inverter motor production.
The Gulf Technical Regulation for low-energy appliances is tightening allowable energy consumption thresholds for imported air conditioners and refrigerators. Kuwait's Public Authority for Industry enforces mandatory testing at accredited regional laboratories, extending pre-shipment lead times by six to eight weeks. Premium inverter product lines absorb these compliance costs more readily than economy-tier competitors, reshaping import portfolio composition toward higher-efficiency SKUs.
Younger Kuwaiti households are unbundling after-sales service from initial purchase decisions, comparing warranty terms and technician response commitments across specialty retailers and direct-to-consumer platforms. Online channels capture growing consideration share for replacement purchases, though complex installations still route through contractor networks. This behavioral pivot is most pronounced among dual-income professional households in Kuwait City, where time scarcity outweighs price sensitivity in appliance selection.
Kuwait Home Appliances Market Segmentation
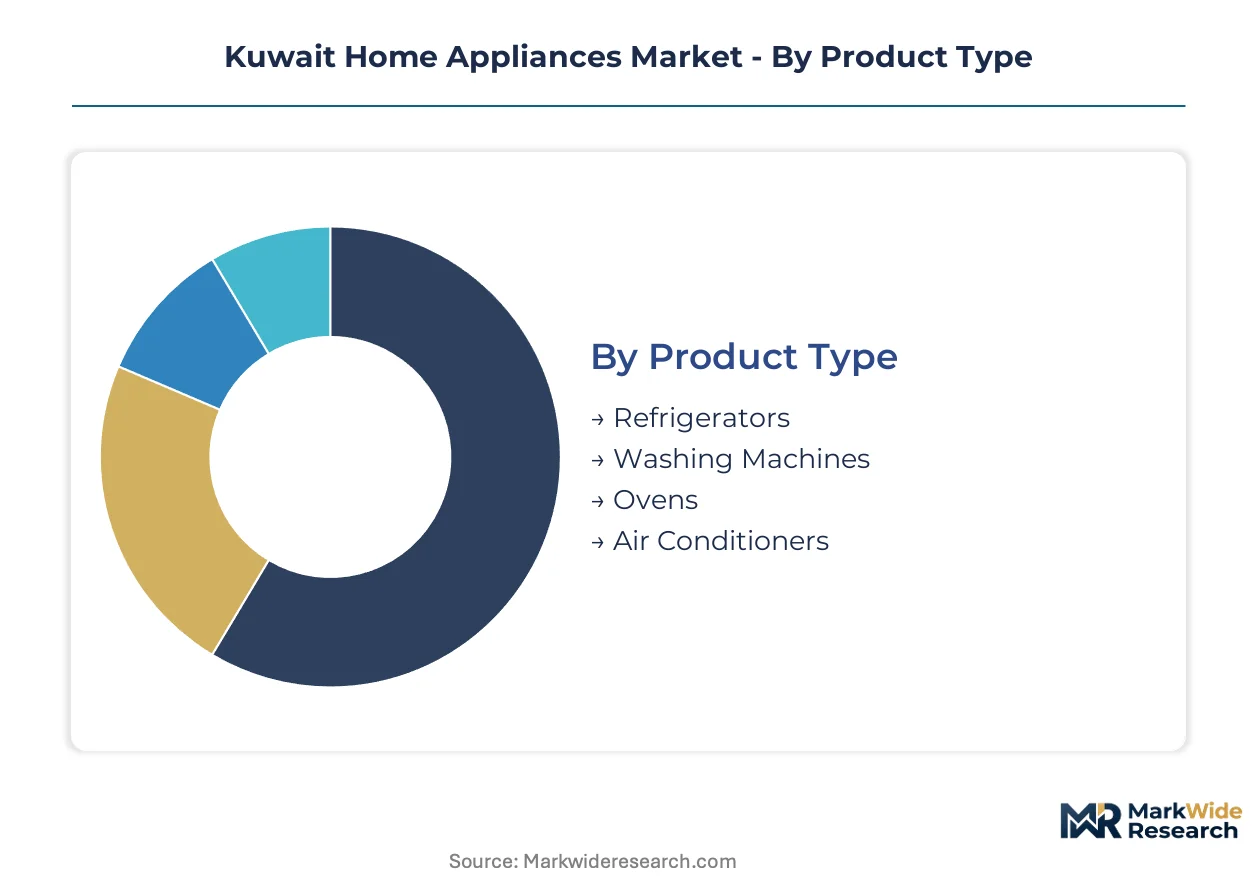
Kuwait's import-dependent appliance market fragments across four distinct dimensions. Each segmentation layer reveals different competitive dynamics, from PAI certification burdens on premium imports to contractor channel concentration in commercial end-uses.
Product Type:
Purchase frequency and technical complexity separate buyer decision-making across appliance categories.
- Air Conditioners:Split-system and window units rated for 55°C ambient operation dominate import volume. Demand concentrates in Jahra and Ahmadi governorates where new worker housing construction specifies inverter-rated cooling as baseline. Extreme summer heat compresses replacement cycles to 5-7 years.
- Refrigerators:French-door and side-by-side configurations with inverter compressors command margin concentration. Villa owners in Salmiya and Fahaheel prioritize A+++ rated units eligible for Ministry of Electricity and Water rebates. Smart connectivity features now appear in 40% of premium shipments.
- Washing Machines:Front-loading units with desert-dust filtration systems address Kuwait's fine particulate environment. Compact capacities suit apartment dwellers in Kuwait City.
- Ovens:Built-in electric and gas ranges follow kitchen renovation cycles in established residential districts.
Volume sits with air conditioners; growth tilts toward inverter-rated refrigeration.
Distribution Channel:
Channel selection tracks purchase complexity and installation requirements rather than pure price sensitivity.
- Specialty Stores:Dedicated appliance retailers in Shuwaikh and Salmiya retain dominance for high-consideration purchases requiring warranty negotiation and installation scheduling. These outlets capture 60% of cooling system volume through contractor referral networks.
- Online Retail:Direct-to-consumer platforms gain traction among dual-income professional households in Kuwait City seeking replacement purchases without store visits. Delivery logistics remain constrained for large-format items requiring crane access.
- Supermarkets:Hypermarket chains stock compact appliances and microwave ovens for impulse and replacement demand.
- Wholesale:Project channels supply bulk cooling equipment to hospitality developers and government housing authorities.
Specialty stores anchor current volume; online retail is expanding most quickly among replacement purchases.
Price Tier:
Regulatory compliance costs and energy efficiency standards stratify the market into distinct procurement bands.
- Premium:Inverter-driven appliances with Gulf Standardization Organization certification and Wi-Fi connectivity occupy the 2,000-4,000 KWD range. PAI testing requirements and factory audit costs embed disproportionately in this tier, squeezing out mid-tier competitors lacking captive manufacturing.
- Mid-Range:Fixed-speed cooling and basic frost-free refrigeration target value-conscious villa owners in expanding suburbs. This segment absorbs copper and aluminum input volatility most acutely.
- Economy:Basic appliances serve expatriate worker housing and rental property investors in Jahra Governorate.
- Luxury:Built-in kitchen systems and smart-home integrated cooling serve high-net-worth households in Dasman and Bneid Al Gar.
Premium tier captures installed-base value; economy tier is gaining share fastest in new worker housing construction.
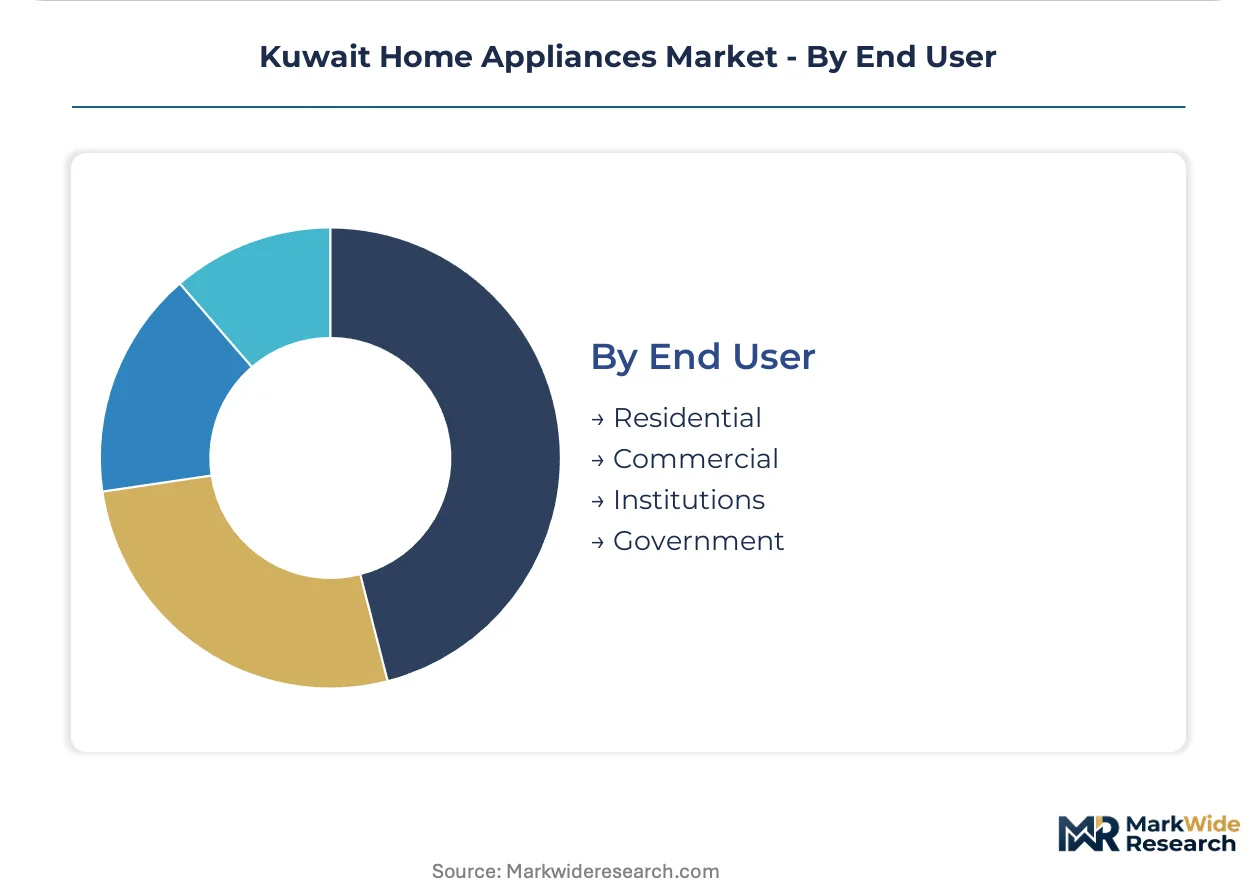
End User:
Procurement authority and replacement urgency create fundamentally different buying behaviors across user categories.
- Residential:Individual households drive 75% of volume through replacement cycles and new home fittings. Family size and villa versus apartment configuration determine capacity requirements across Kuwait's governorates.
- Commercial:Hospitality developers in Kuwait City and Salmiya specify commercial-grade cooling and kitchen equipment through contractor channels. Project timelines compress effective selling windows to Q1-Q2 pre-summer stocking.
- Institutions:Schools and hospitals procure through centralized tender processes with extended payment terms.
- Government:Public housing authorities mandate specific efficiency grades in new construction specifications.
Residential dominates absolute volume; commercial procurement shows the steepest expansion trajectory in hospitality fit-outs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Al-Zour South Zone tax incentives concentrate appliance assembly operations near Kuwait's primary industrial corridor, pulling component suppliers toward the Ahmadi Governorate logistics hub.
Kuwait City Governorate
High-rise residential towers and hospitality developments in Sharq and Dasman districts specify inverter-rated cooling systems as baseline. The Public Authority for Industry enforces Gulf Standardization Organization mark recognition on all imported units. Retail concentration in Salmiya and Hawalli sustains specialty store dominance for warranty-intensive purchases.
Hawalli Governorate
Villa construction in Salwa and Rumaithiya drives premium refrigeration demand with A+++ efficiency ratings. Ministry of Electricity and Water rebate programs compress payback periods for inverter technology upgrades. Contractor networks in Salmiya coordinate bulk procurement for commercial fit-outs.
Ahmadi Governorate
Worker housing projects in Fahaheel and Mangaf create volume demand for economy-tier cooling equipment. New industrial zone incentives attract regional logistics operators to Al-Zour. Port proximity through Shuwaikh reduces inland distribution costs for containerized appliance shipments.
Jahra Governorate
Expatriate residential compounds and rental property investment expand addressable market for value-tier laundry and cooling systems. Lower household appliance density per unit creates first-mover positioning opportunities. Distribution infrastructure remains underdeveloped relative to coastal governorates.
Farwaniya Governorate
Dense apartment configurations in Jleeb Al-Shuyoukh and Khaitan suit compact-capacity washing machines with desert-dust filtration. Online retail penetration runs highest among dual-income professional households here. Installation complexity sustains contractor channel relevance despite digital platform growth.
Kuwait Home Appliances Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across Kuwait's import-dependent appliance market, creating a tiered structure where captive manufacturing and service infrastructure determine sustainable positioning. Korean and Japanese electronics conglomerates leverage established Gulf distribution networks to defend premium cooling segments. Chinese manufacturers anchor volume tiers through aggressive pricing while navigating PAI certification requirements. Two dominant competitive moves define current positioning: M&A activity consolidating trading house capabilities, and strategic partnerships with local installation contractors securing project channel access.
Within the diversified electronics conglomerate tier, LG Electronics and Samsung Electronics occupy positions defined by integrated smart-home ecosystems and captive service infrastructure across the emirate. Midea Group represents the scale-driven Chinese manufacturing archetype competing on price-adjusted efficiency compliance. These three companies exemplify the strategic divergence between platform-integrated premium positioning and volume-focused certification navigation in a market where regulatory compliance costs disproportionately burden mid-tier competitors lacking captive regional laboratories or factory audit resources.
| Leading Market Players |
|---|
| Whirlpool Corporation |
| Midea Group |
| Panasonic |
| LG Electronics |
| Sharp Corporation |
| Samsung Electronics |
| Bosch |
| Haier Group Corporation |
| Electrolux |
| Others |
Supply & Pricing Matrix
Family-owned trading houses consolidated through private-equity rollups dominate import licensing and customs clearance, concentrating pricing power at Shuwaikh Port while compressing distributor margins through bundled certification services. This ownership pattern tightens supply-side discipline as rolled-up specialists extract efficiency gains from shared PAI documentation workflows and consolidated inland logistics.
Pricing Analysis
Premium pricing attaches to six-week lead time guarantees for pre-summer cooling inventory, while spot purchases of containerized shipments trade at discounts during off-peak windows. Three-tier pricing structure across premium inverter-rated, standard fixed-speed, and economy basic cooling separates buyers by certification grade and after-sales bundling. Cost compression in mid-range fixed-speed units is intensifying because copper and aluminum input volatility erodes forward-margin visibility. Expatriate worker housing developers in Jahra Governorate exhibit highest price sensitivity, while villa owners in Hawalli prioritize warranty terms over unit cost.
Supply Chain Analysis
Direct-to-contractor digital platforms handle commercial hospitality fit-out demand, bypassing traditional distributor markups in Kuwait City and Salmiya project channels. Manufacturing concentration rests on China, South Korea, and Thailand for compressor assemblies and inverter control modules. Copper winding stock, aluminum heat exchanger tubing, and semiconductor power components feed fabrication lines. Single-port vulnerability at Shuwaikh concentrates customs clearance risk during peak summer pre-stocking windows. Distribution runs through specialty retailer networks for warranty-intensive residential purchases, with online platforms capturing growing replacement volume.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Certified refrigeration technician scarcity props pricing for installation and maintenance services, creating supply-constrained value capture for service-capable incumbents. This bottleneck sustains premium attachment rates for warranty-bundled sales.
For Market Incumbents: Anchor market position through captive inverter motor production and PAI-recognized regional laboratory access, compressing compliance timelines for seasonal product launches. Defend against Chinese price-tier entrants by locking contractor referral networks in commercial hospitality channels. Prioritize backward integration into compressor assembly to offset London Metal Exchange input volatility. For New Entrants and Emerging Players: Launch via direct-to-installer digital platforms targeting Jahra Governorate worker housing construction, where appliance density per household remains lowest and first-mover positioning is available. Penetrate the value-tier cooling segment through aggressive A+++ efficiency compliance without smart-connectivity premium features. Employ project-channel bulk procurement to bypass established distributor markups in Fahaheel and Mangaf developments. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-cap trading houses with consolidated PAI certification capabilities and established Shuwaikh Port customs relationships in Ahmadi Governorate. Long-term viability hinges on service infrastructure density rather than pure import volume scale. Monitor Ministry of Electricity and Water subsidy program expansions as inflection signal for premium efficiency tier demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| GSO Certification Streamlining | PAI-recognized regional laboratories shorten Kuwait entry timelines for Saudi-compliant manufacturers. |
| Direct-to-Installer Platform Launch | Contractor-facing apps capture margin pool reallocation in commercial hospitality fit-outs. |
| Inverter Motor Backward Integration | Captive compressor production insulates margin pools from London Metal Exchange copper volatility. |
| Jahra Governorate Distribution Buildout | Underdeveloped logistics infrastructure creates first-mover positioning for value-tier cooling volume. |
| Smart-Home Ecosystem Integration | Wi-Fi-enabled appliance platforms lock multi-device households into repurchase cycles. |
Research Methodology
Document review covered customs import records, PAI certification registries, and Ministry of Electricity and Water subsidy program disclosures, complemented by interviews with appliance trading house procurement directors, specialty retailer category managers, commercial hospitality project contractors, and certified refrigeration technicians. Secondary validation drew from Gulf Standardization Organization technical regulations, Kuwait Public Authority for Industry factory audit schedules, and London Metal Exchange pricing archives. Bottom-up volume estimates from shipment data triangulated against top-down construction permit and household formation projections.
Cross-referencing historical import patterns against distributor panel input established baseline demand assumptions across the projection horizon. Segmentation modeling incorporated product type, price tier, distribution channel, and end-user category dimensions. CAGRs derived from trend extrapolation of construction permit pipelines and replacement cycle compression factors. Forecast inputs included voltage fluctuation tolerance requirements for smart-connected modules and evolving Gulf Technical Regulation efficiency thresholds.
Regulatory enforcement intensity shifts, copper and aluminum price spikes, and certified technician training pipeline expansion are the dominant revision risks to installed-base growth assumptions. Forecasts reflect documented base-case assumptions regarding PAI audit scheduling efficiency and subsidy program continuity. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Home Appliances
Latin America Washing Machine Market
Home Appliances
North America Small Home Appliances Market
Home Appliances
Smart Home Appliances Market
Home Appliances
Middle East and Africa Laundry Appliances Market
Home Appliances
Residential Dishwashers Market
Home Appliances
Germany Washing Machine Market
Home Appliances
Household Fridge Market
Home Appliances
India Refrigerator Market
Home Appliances
Sweden Laundry Appliances Market
Home Appliances
North America Home Appliances Market
Home Appliances
Europe White Goods Market
Home Appliances
Israel Home Appliances Market
Home Appliances
France Household Appliances Market
Home Appliances
United States Home Appliances Market
Home Appliances
Built-In Hobs Market
Home Appliances
Germany Major Home Appliance Market