
 Water Dispenser Market | 2026-2036
Water Dispenser Market Size, Share, and Industry Trends Forecast 2026-2036
Water Dispenser Market Intelligence
A shift in demand from residential to commercial and educational end-users is restructuring the market's customer base. Waterlogic Holdings Limited specializes in bottleless point-of-use systems for corporate clients, focusing on recurring service revenue. Primo Water Corporation leverages its extensive bottled water delivery network, serving both homes and small offices. Meanwhile, Coway Co., Ltd. differentiates through advanced filtration technologies and a subscription-based model popular in South Korea.
A water dispenser is an appliance designed to deliver temperature-controlled drinking water, either cooled or heated. Modern units often integrate multi-stage filtration systems, including reverse osmosis membranes or UV purification lamps for microbial inactivation. The market's product landscape shows bottleless, point-of-use systems gaining share over traditional bottled dispensers due to lower long-term costs. Within technology, models featuring advanced reverse osmosis and UV purification command higher price points and are gaining traction in health-conscious segments.
Product design and market access are shaped by a complex regulatory environment. In the United States, the FDA sets standards for food-contact materials, while in Europe, CE marking is mandatory for electrical safety. China's GB standards dictate product performance and material safety requirements. Future competitive advantage will hinge on developing energy-efficient models with smart connectivity features that meet these diverse international compliance standards.
Market Dynamics
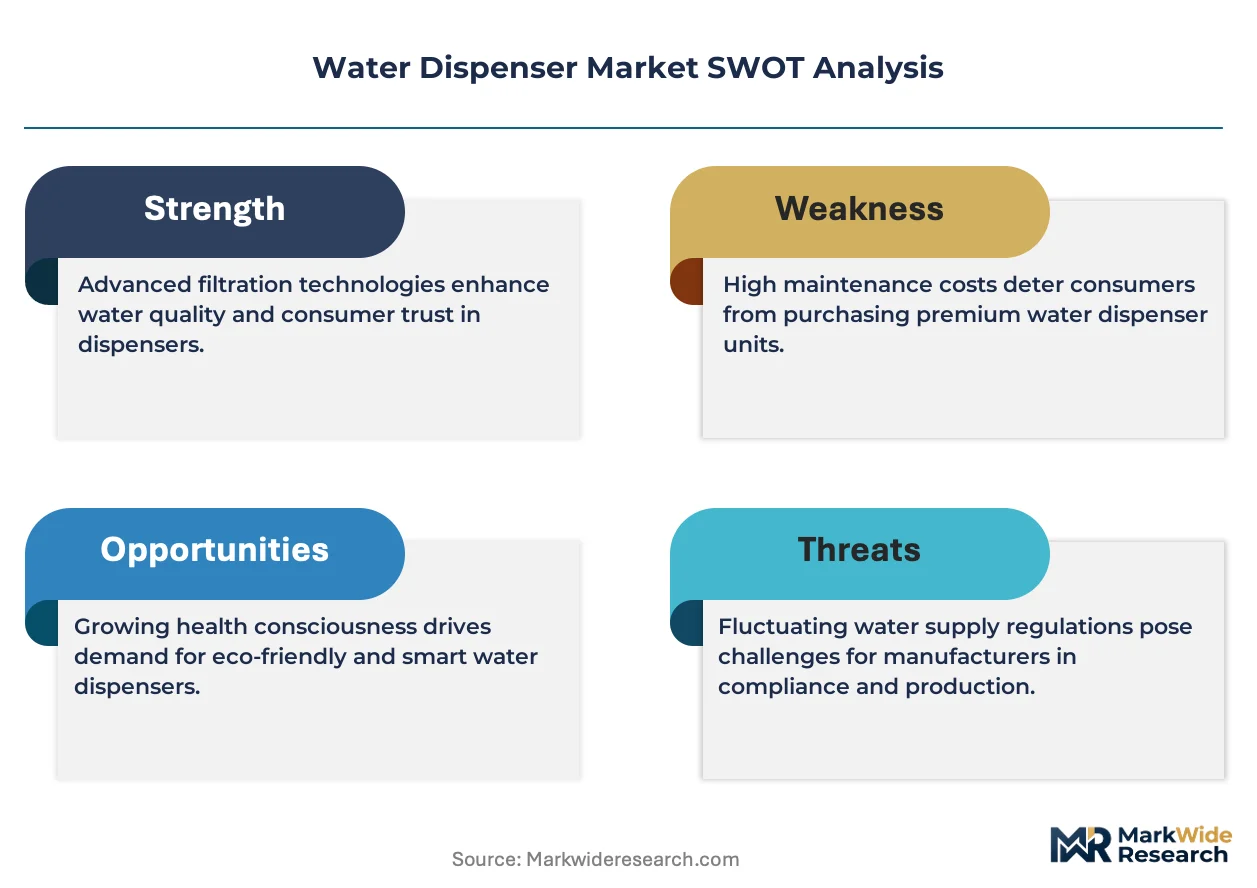
The market's structure is reconfiguring around the accelerated transition from bottled water coolers to point-of-use systems. This pivot is driven by commercial end-users seeking lower operational costs and by public health concerns over municipal water quality in major emerging economies.
Growth Catalysts
- Corporate Wellness Initiatives:A focus on employee hydration in corporate offices is expanding POU system installations, supported by internal health and safety programs.
- Urban Water Quality:In India and Brazil, poor municipal water supplies compel users to invest in dispensers with advanced filtration for safety.
- Smart Technology:IoT features for remote monitoring and automated alerts create value for facilities managers in commercial buildings.
Market Restraints
- High Upfront Investment:The capital outlay for advanced bottleless systems with reverse osmosis is a barrier for small businesses and residential users.
- Fragmented Regulatory Compliance:Manufacturers face costs navigating divergent rules like US FDA regulations, European CE marking, and China's GB standards.
- Infrastructural Dependencies:Point-of-use systems require plumbing, limiting installation in older buildings or sites without water lines.
Strategic Opportunities
- Educational and Healthcare Sectors:Schools and hospitals are underpenetrated segments where demand for safe hydration can be met with durable POU models.
- Subscription-Based Models:"Water-as-a-Service" for small enterprises offers recurring revenue and lowers adoption barriers from high upfront costs.
- Energy-Efficient Technologies:Dispensers exceeding energy standards, like those in the EU Green Deal, create advantage with sustainability-focused clients.
Industry Challenges
- Service Network Scalability:Building a skilled technician network for installation, filter replacement, and repair across dispersed clients is a significant operational challenge.
- Competition from Integrated Solutions:Refrigerators with built-in water filters and dispensers pose a substitution threat, particularly in residential and small office segments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Water Dispenser Market |
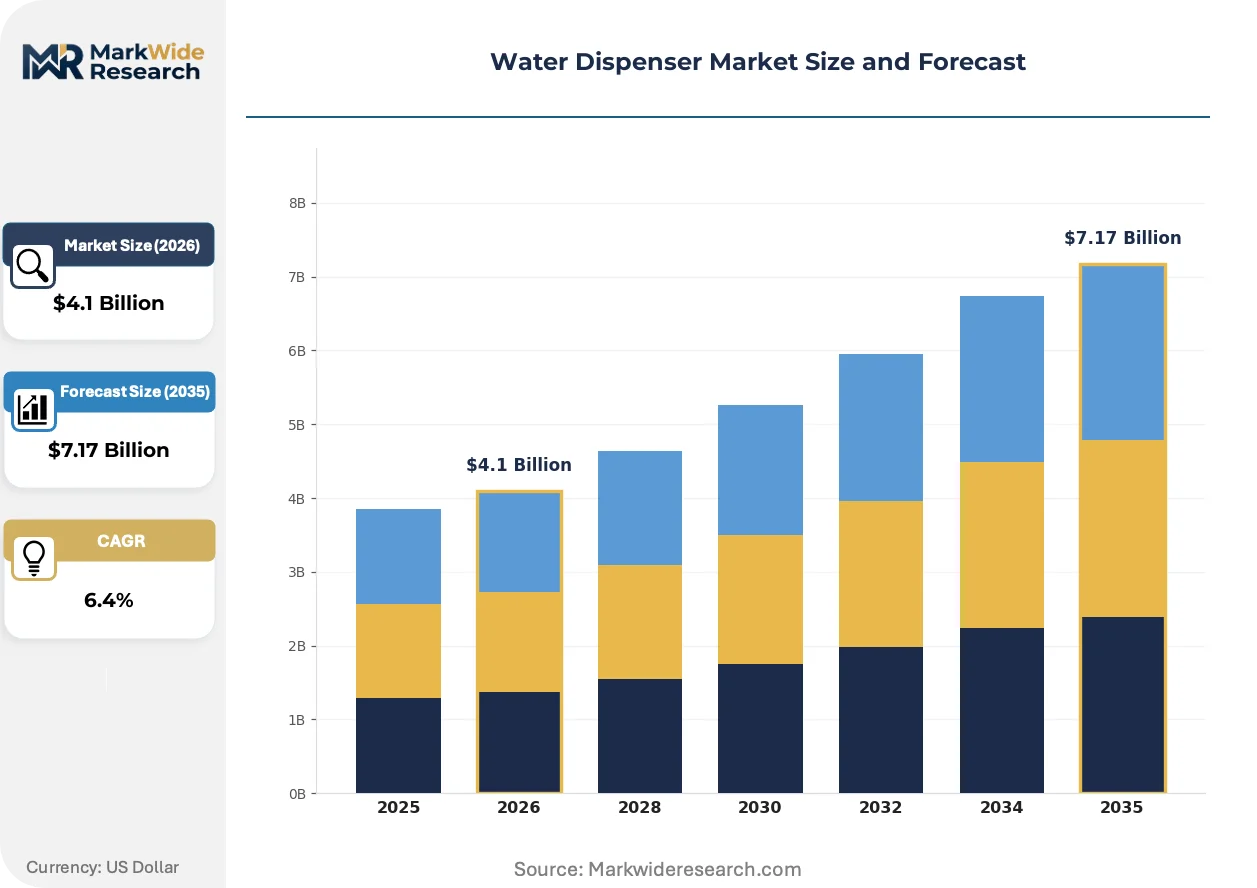
| Market Size in 2026 | $4.1 Billion |
| Market Size in 2035 | $7.17 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bottleless, Bottled, Countertop, Floor-standing End User: Residential, Commercial, Industrial, Educational Technology: Filtered, Reverse Osmosis, UV Purification, Thermal Features: Hot & Cold Function, Energy Saving, Smart Controls, Self-Cleaning |
| Companies Covered | Primo Water Corporation, Culligan International Company, Waterlogic Holdings Limited, Whirlpool Corporation, Honeywell International Inc., Midea Group Co., Ltd., A.O. Smith Corporation, Blue Star Limited, Coway Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Water Dispenser Market Strategic Shifts & Innovations
Product innovation is coalescing around the dual priorities of enhanced purification and environmental sustainability. This focus is driving the integration of advanced filtration with resource-efficient designs, fundamentally altering performance expectations for both commercial and residential users.
UV-C LED technology offers continuous, chemical-free microbial inactivation directly at the point of dispense. Healthcare facilities and corporate offices are primary adopters, seeking higher hygiene assurance. The integration of this mercury-free technology is rewriting the benchmarks for safety and maintenance in the point-of-use category.
The European Union's RoHS directive imposes stricter limits on hazardous substances in electronic components. This regulation compels manufacturers to redesign circuitry and find compliant alternatives for smart controls and purification modules. Consequently, suppliers targeting the EU are overhauling supply chains, often adopting these standards across their portfolios.
A notable shift is occurring where commercial customers favor all-inclusive rental agreements over direct capital purchases. This service-based model bypasses traditional equipment sales, bundling the unit with routine maintenance, filter replacement, and sanitization. This preference for predictable operational spending is most visible in corporate and healthcare settings across the United States and Europe.
Water Dispenser Market Segmentation
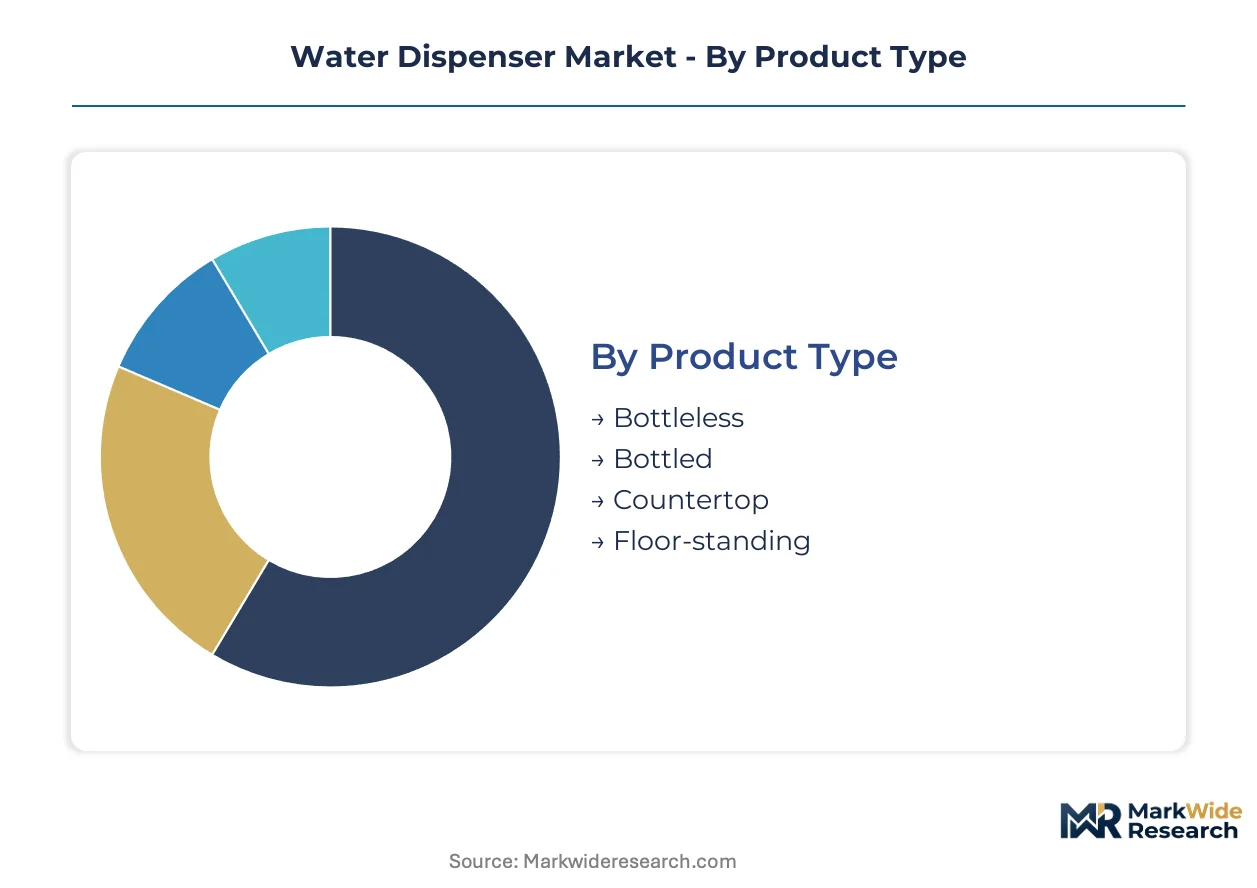
Market segmentation provides a granular understanding of the water dispenser landscape, revealing distinct customer preferences, technological adoption patterns, and operational requirements. This detailed breakdown allows manufacturers and service providers to tailor product offerings and market strategies effectively.
Product Type:
Supply concentration in specific product types reflects evolving consumer priorities for convenience, cost-efficiency, and sustainability.
- Bottleless:These systems connect directly to a water line, offering continuous supply without manual bottle replacement. Demand is concentrating in corporate offices seeking reduced logistics and improved sanitation.
- Floor-standing:Larger, standalone appliances provide higher capacity and often integrate advanced filtration systems, making them suitable for high-traffic commercial environments. Corporate wellness initiatives in Europe are increasingly driving installations of these robust units.
- Bottled:These dispensers utilize large pre-filled water bottles, requiring regular delivery and manual replacement for residential and small office users.
- Countertop:Compact units designed for placement on flat surfaces, often found in smaller offices or home kitchens.
Today's leader: Floor-standing. Tomorrow's challenger: Bottleless.
End User:
Different customer types exhibit distinct hydration needs, influencing the design and deployment of water dispensing solutions.
- Commercial:Businesses and corporate environments deploy dispensers for employee and client hydration, often prioritizing high capacity and advanced filtration. Corporate wellness initiatives in major urban centers like Mumbai and São Paulo are driving this segment's expansion.
- Educational:Schools, universities, and daycare centers require robust, safe hydration solutions for students and staff, emphasizing hygiene and durability. Underpenetrated segments in countries like Brazil show significant potential for POU system adoption.
- Residential:Individual households utilize dispensers for convenient access to filtered or temperature-controlled drinking water.
- Industrial:Manufacturing plants and warehouses provide hydration for workers in demanding environments, focusing on durability and high-volume output.
The fastest-growing demand is observed in Commercial settings, while Residential users represent a stable baseline.
Technology:
Performance differentiation among technologies drives varied adoption rates, with advanced purification methods gaining traction in health-conscious segments.
- Reverse Osmosis:This advanced membrane filtration system removes dissolved solids, contaminants, and chemicals from water, providing high-purity drinking water. Health-conscious segments in urban areas of India are adopting RO systems due to prevalent municipal water quality concerns.
- UV Purification:Ultraviolet light technology inactivates bacteria, viruses, and other microorganisms without chemicals, ensuring microbial safety at the point of dispense. Healthcare facilities and corporate offices in Europe are increasingly integrating UV-C LED technology for enhanced hygiene assurance.
- Filtered:Basic filtration systems remove sediment, chlorine, and some organic compounds, improving water taste and odor.
- Thermal:These systems primarily focus on heating or cooling water, often combined with basic filtration.
Advanced purification technologies, particularly UV Purification, are gaining market share against traditional Filtered options.
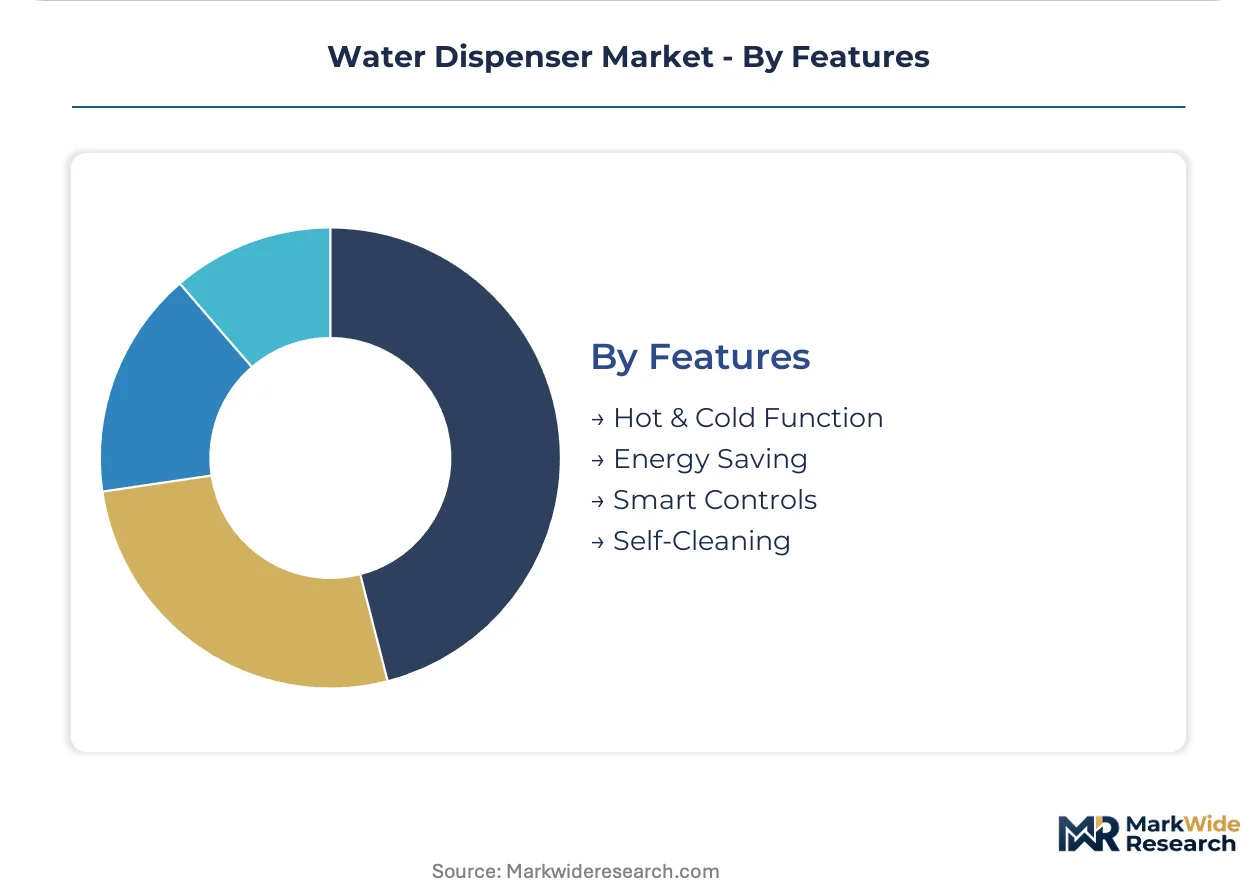
Features:
Innovation in dispenser features responds directly to end-user demands for convenience, efficiency, and enhanced hygiene.
- Smart Controls:Integrated IoT capabilities allow for remote monitoring, automated alerts, and usage tracking, optimizing maintenance and operational efficiency. Facilities managers in large commercial buildings are leveraging smart features for proactive system management.
- Self-Cleaning:Automated sanitization cycles and antimicrobial surfaces reduce manual maintenance requirements and enhance hygiene standards. Healthcare facilities and food service establishments prioritize self-cleaning features for operational safety.
- Hot & Cold Function:These basic features provide immediate access to both heated and chilled drinking water.
- Energy Saving:Features like eco-modes and efficient compressors reduce power consumption, aligning with sustainability goals.
The most significant innovation trajectory is seen in Smart Controls, while Hot & Cold Function remains a foundational expectation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage influences water dispenser manufacturing, with production shifting to regions offering lower compliance costs. This dynamic reshapes global supply chains and product availability. Companies seek to optimize operations by aligning with regional standards and market demands.
United States
Corporate wellness initiatives and healthcare facilities drive demand for advanced water dispensing systems. The FDA sets stringent standards for food-contact materials, influencing product design and manufacturing. Tech campuses in Silicon Valley prioritize employee amenities, accelerating POU system adoption.
Germany
Commercial settings and sustainability goals underpin the demand for energy-efficient water dispensers. CE marking is mandatory for electrical safety, while the EU Green Deal promotes energy-efficient models. Munich's corporate parks increasingly integrate models that align with regional environmental commitments.
India
Urban water quality concerns and health-conscious segments fuel the adoption of purification technologies. BIS standards for water purification systems assure product quality and safety for consumers. Mumbai's high-density urban areas show strong demand for RO systems to address municipal water issues.
Brazil
Poor municipal water supplies compel users to invest in dispensers with advanced filtration, especially in educational sectors. ANVISA regulations govern drinking water quality and appliance safety. São Paulo's commercial districts invest in advanced filtration to ensure safe hydration for employees.
China
Product performance, material safety, and smart control features shape consumer preferences. GB standards dictate product performance and material safety requirements for all imported and domestic units. Shenzhen's manufacturing hubs focus on integrating smart connectivity features into new dispenser designs.
Water Dispenser Market Key Industry Players
Strategic partnerships and geographic expansion dominate the current landscape, as companies seek to broaden market reach and integrate new technologies. The market exhibits a tiered structure, with global players, specialized point-of-use system providers, and regional players leveraging local distribution. Portfolio diversification and M&A for technology acquisition represent additional competitive moves.
Specialists in recurring service models include Primo Water Corporation, which leverages an extensive bottled water delivery network. Waterlogic Holdings Limited exemplifies companies focusing on bottleless point-of-use systems for corporate clients, emphasizing service revenue. Coway Co., Ltd. sits within the advanced technology segment, differentiating through superior filtration and subscription-based models popular in South Korea.
| Leading Market Players |
|---|
| Primo Water Corporation |
| Culligan International Company |
| Waterlogic Holdings Limited |
| Whirlpool Corporation |
| Honeywell International Inc. |
| Midea Group Co., Ltd. |
| A.O. Smith Corporation |
| Blue Star Limited |
| Coway Co., Ltd. |
| Others |
Cost & Logistics Intelligence
Polypropylene resin prices heavily influence the cost structure of water dispenser manufacturing, cascading into distinct pricing tiers for various product types. This commodity benchmark directly impacts the final unit price, especially for entry-level and mid-range models.
Pricing Analysis
Distributor margin structures significantly influence the final retail price of water dispensers. The market operates on a hybrid subscription and transactional model, with advanced filtration technologies and comprehensive after-sales service bundles driving premium pricing. Pricing softness emerges from competition with integrated refrigerator solutions, particularly in residential segments. Small businesses and residential users exhibit higher price sensitivity compared to corporate offices and healthcare facilities.
Supply Chain Analysis
Global logistics and freight costs significantly influence water dispenser pricing and regional market access. Manufacturing concentrates in East Asia, particularly China, South Korea, and Vietnam. The supply chain relies heavily on plastics, electronic components, and advanced filtration membranes. Commodity price volatility for these inputs poses a structural risk, while distribution runs through a hybrid of B2B direct sales and extensive distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The water dispenser market acts as a stable compounder, driven by sustained corporate wellness initiatives expanding point-of-use system installations. This consistent demand underpins predictable long-term growth for industry participants.
For Market Incumbents: Anticipate continued competitive pressure from refrigerator integrated solutions by acquiring advanced filtration technology specialists. Expand recurring service revenue models, particularly in the commercial sector, to build customer loyalty. Investing in multi-regional regulatory compliance, such as CE marking and GB standards, will protect market access and differentiate offerings. Strengthen channel control to counter emerging threats and maintain market share.
For New Entrants and Emerging Players: Capture underpenetrated segments like educational institutions and small enterprises with flexible "Water-as-a-Service" models. The educational sector in Brazil presents a significant white-space opportunity for durable POU systems. Focus on energy-efficient models that align with sustainability goals, providing a clear value proposition for new clients. Leveraging digital marketing to target facilities managers can accelerate adoption.
For Investors and Strategic Acquirers: Asymmetric upside sits with specialized point-of-use system providers offering advanced purification and recurring service models. The market demonstrates long-term viability over a 5-10 year window, supported by commercial and health-conscious demand. Target acquisition candidates include companies with strong intellectual property in UV-C LED or RO filtration. A key signal to watch is the accelerating market share gain of bottleless POU systems over traditional bottled dispensers.
| Strategic Initiative | Industry Significance |
|---|---|
| Expand POU Service Networks | Waterlogic Holdings Limited can ensure efficient installation and maintenance for corporate clients. |
| Integrate UV-C LED Technology | Coway Co., Ltd. can enhance microbial inactivation and hygiene assurance for healthcare facilities. |
| Develop Smart Connectivity Features | Midea Group Co., Ltd. can offer remote monitoring and automated alerts for facilities managers. |
| Target Educational Sector Partnerships | Primo Water Corporation can address demand for safe hydration in underpenetrated segments like Brazilian schools. |
| Offer Subscription-Based "Water-as-a-Service" | Culligan International Company can lower upfront costs and generate recurring revenue from small enterprises. |
Research Approach
Bottom-up commercial end-use modeling reconciled against top-down water dispenser supply-side tracking forms the analytical core of this study. Primary interviews with facilities managers, procurement leads, product development engineers, and regulatory compliance officers provided critical qualitative insights. Secondary validation drew from FDA standards, CE marking guidelines, China's GB standards, and industry association reports. This dual approach ensures a robust and comprehensive data foundation.
Historical trendline analysis informed market growth projections over the projection horizon. Segmentation dimensions modeled include product type, end user, technology, features, and geographic region. Compound annual growth rates were derived from a detailed assessment of market drivers. Forecast inputs considered urbanization rates and municipal water quality indices in key regions.
Regulatory shifts, raw material price volatility, and the emergence of new competitive integrated solutions are the dominant revision risks for these forecasts. All projections reflect assumptions about market conditions and technological advancements throughout the modeling period. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Appliances
Europe Tumble Dryers Market
Appliances
AI Washing Machine Market
Appliances
Germany Compact Dishwasher Market
Appliances
North America Microwave Oven Market
Appliances
Middle East Water Heater Market
Appliances
Household Vacuum Cleaners Market
Appliances
US Portable Washing Machines Market
Appliances
Large Cooking Appliance Market
Appliances
United States Washing Machine Market
Appliances
Electrical Appliances Plastics Market
Appliances
United Kingdom Tumble Dryers Market
Appliances
Saudi Arabia Microwave Ovens Market
Appliances
Glass Ceramic Cooktop Market
Appliances
United States Microwave Oven Market
Appliances
Portable Mini Fridge Market
Appliances
Conveyor Dishwasher Market