
 Domestic Food Preparation Appliances Market | 2026-2036
Domestic Food Preparation Appliances Market Size, Share, and Industry Trends Forecast 2026-2036
Domestic Food Preparation Appliances Market Outlook
A capital-intensity divergence between integrated manufacturers and assembly-reliant competitors is rotating competitive advantage toward firms with captive motor and blade production. Whirlpool Corporation leverages its North American manufacturing footprint to sustain margin control across full-size mixer lines. Samsung Electronics anchors its position through smart appliance ecosystems that integrate with connected kitchen platforms. BSH Home Appliances differentiates via German-engineered precision motors that command premium positioning in European markets.
Domestic food preparation appliances encompass electrically powered countertop and handheld devices designed to mechanically process, blend, mix, or chop food ingredients, typically operating at voltages between 120-240V with motor outputs ranging from 200W to 1500W depending on function intensity. These appliances serve the dual purpose of reducing manual preparation time while standardizing texture and consistency for home-cooked meals. The technology dimension reveals smart appliances capturing disproportionate attention as connectivity modules add bill-of-materials cost but unlock recurring software-service revenue pools. Multi-functional appliances demonstrate the fastest structural expansion as consumers prioritize space-efficient units combining blending, processing, and mixing capabilities in single housings. Traditional appliances retain volume dominance in emerging markets where price sensitivity limits connected-feature penetration.
The US Consumer Product Safety Commission enforces electrical safety standards for small kitchen appliances, while the EU Ecodesign Directive and REACH framework govern energy consumption thresholds and material composition limits respectively. China's SAMR administers compulsory certification under GB standards that dictate electromagnetic compatibility and food-contact material safety for domestic sales. Stakeholders must monitor evolving interoperability standards between smart appliances and third-party recipe platforms as these specifications will determine ecosystem lock-in value and aftermarket revenue potential.
Market Dynamics
Smart connectivity modules are compressing replacement cycles as consumers upgrade to Wi-Fi-enabled blenders and processors that integrate with recipe platforms, while the EU Ecodesign Directive forces motor efficiency redesigns that favor manufacturers with captive component production.
Growth Catalysts
- EU Ecodesign mandates:Energy-efficiency thresholds for small motors are accelerating premium product turnover as consumers replace aging units with compliant models.
- China's urban household formation:First-time homebuyers in tier-1 cities are driving replacement demand for full kitchen appliance suites including multi-functional food processors.
- Silicon carbide motor controllers:Power electronics miniaturization enables quieter, more efficient appliances that command price premiums in European markets.
Market Restraints
- Copper and rare-earth price volatility:Permanent magnet motor costs fluctuate with neodymium supply disruptions concentrated in Chinese processing facilities.
- Technical limitation of blade durability:High-torque applications in nut processing and ice crushing accelerate stainless steel fatigue, shortening product lifespans below consumer expectations.
- Substitution threat from manual tools:Premium hand-powered alternatives from Japanese and German craft brands capture sustainability-conscious buyers in Nordic markets.
Strategic Opportunities
- India's underpenetrated market:BIS certification alignment and localized production under the PLI scheme open access to middle-class households upgrading from manual preparation.
- Technology convergence of IoT sensors and recipe AI:Appliances that auto-adjust blending profiles based on ingredient recognition create recurring software revenue streams.
- SAMR food-contact material standards:Compliance with China's GB 4806 series enables premium positioning for brands with verified ceramic and glass component safety.
Industry Challenges
- Embedded firmware engineering talent scarcity:Connectivity feature development requires scarce expertise in real-time operating systems and cybersecurity protocols.
- Multi-certification timeline compression:Simultaneous UL, CE, and GB testing for global product launches extends time-to-market by 4-8 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Domestic Food Preparation Appliances Market |
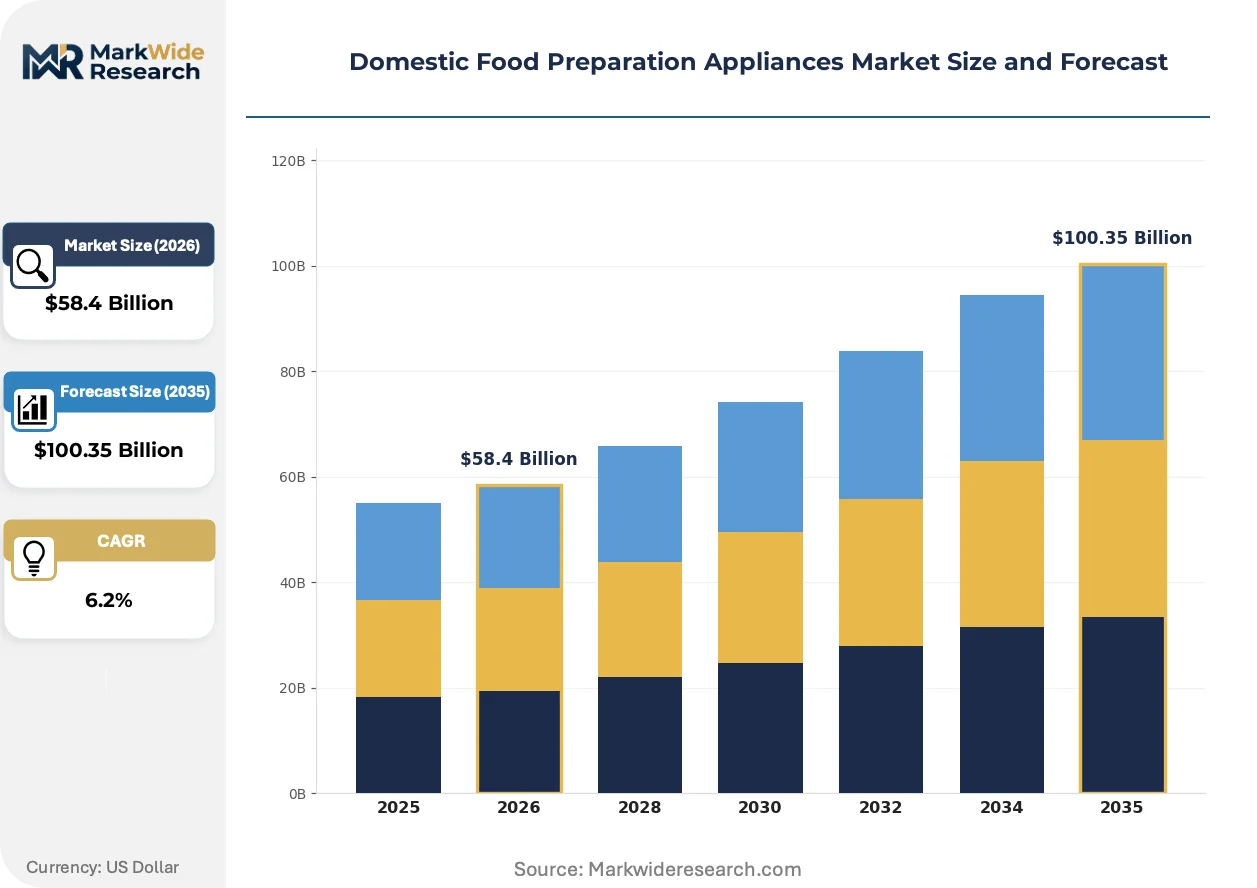
| Market Size in 2026 | $58.4 Billion |
| Market Size in 2035 | $100.35 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Blenders, Mixers, Food Processors, Choppers Technology: Smart Appliances, Standard Appliances, Multi-functional Appliances, Traditional Appliances Size: Compact, Full-size, Countertop, Handheld End User: Households, Professional Chefs, Catering Services, Health-conscious Consumers |
| Companies Covered | Whirlpool Corporation, Samsung Electronics, LG Electronics, Electrolux AB, BSH Home Appliances, Koninklijke Philips N.V., Panasonic Corporation, Breville Group Ltd., Haier Group Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Domestic Food Preparation Appliances Market Strategic Shifts
Three distinct vectors are compressing development cycles and reshaping competitive positioning: motor and blade technology miniaturization, regulatory pressure on energy consumption and material safety, and shifting purchase channels that disintermediate traditional retail.
Brushless DC motor technology is miniaturizing. These compact, electronically commutated motors replace brushed universal designs in handheld immersion blenders and compact food processors. Premium kitchen renovators in German and Japanese markets are adopting these quieter, longer-lasting units at twice the rate of standard replacements. The technology is miniaturizing appliance housings while maintaining torque output, enabling countertop footprints that suit urban apartments in Seoul and Singapore.
The EU Ecodesign Directive's 2024 standby power limits are forcing redesigns of phantom-load circuits in smart appliances. Manufacturers must either add physical power switches or redesign control boards to achieve sub-0.5W standby consumption. Full-size mixer and processor lines sold in France, Italy, and Spain face the steepest compliance costs, prompting BSH and comparable integrated producers to consolidate controller sourcing.
Direct-to-consumer subscription bundling is displacing big-box retail for initial appliance acquisition. Younger buyers in US coastal metros and London are purchasing blenders through meal-kit platforms that embed hardware in recurring food delivery contracts. This channel compression forces traditional manufacturers to build API integrations with HelloFresh, Gousto, and comparable services or surrender brand visibility at point of first use.
Domestic Food Preparation Appliances Market Segmentation
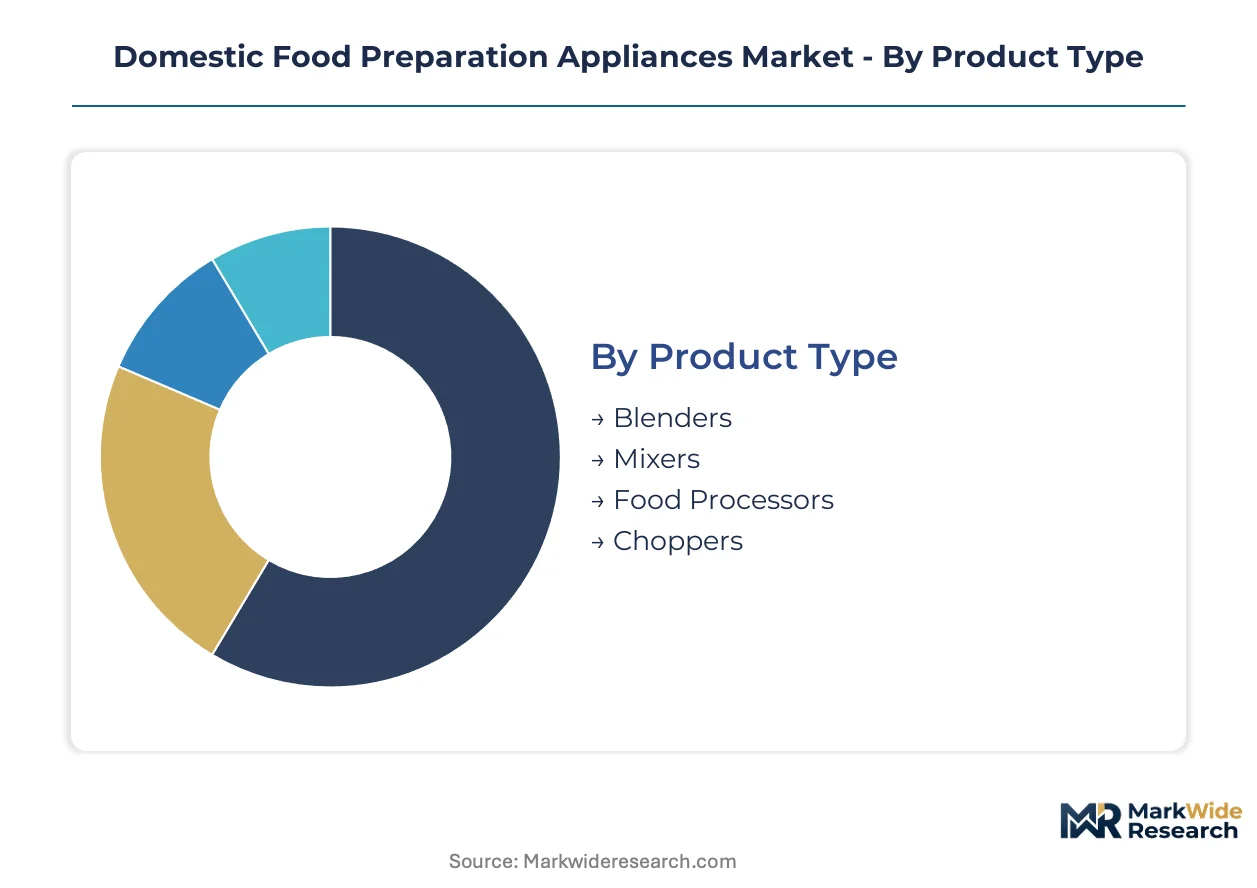
Segmentation in domestic food preparation appliances reveals how purchasing behavior splits across technical sophistication, spatial constraints, and user expertise. Manufacturers must align motor specifications and connectivity features against these divides to avoid mismatched inventory positions.
Product Type:
Blenders concentrate manufacturing in export-oriented Chinese facilities, while mixers and food processors retain stronger domestic production footprints in Germany and the United States.
- Blenders:High-speed blade assemblies with motor outputs between 500W and 1500W process smoothies, soups, and nut butters. Demand clusters in North American health-conscious households upgrading from basic models to variable-speed units with thermal protection circuits.
- Mixers:Planetary gear systems with bowl capacities from 3.5 to 7 liters standardize dough and batter consistency. European home bakers drive replacement demand for bowl-lift designs that handle dense rye and whole-grain formulations.
- Food Processors:Interchangeable disc and blade systems automate slicing, shredding, and emulsifying tasks. Compact 7-cup units suit Japanese and Korean urban kitchens with limited storage.
- Choppers:Miniature 200W to 350W units with pull-cord or electric activation target single-task ingredient prep. Manual alternatives from craft brands capture sustainability-focused buyers in Nordic markets.
Mixers command the established base. The steepest expansion runs through blenders.
Technology:
Cost tier stratification separates premium connected units from standard motor-driven designs, with mid-market multi-functional appliances bridging the gap.
- Smart Appliances:Wi-Fi modules and embedded sensors enable app-controlled blending profiles and usage tracking. Recipe platform integrations from Yummly and Tasty drive adoption in US coastal metros where subscription bundling with meal kits accelerates initial purchase.
- Standard Appliances:Electromechanical controls without connectivity satisfy price-sensitive replacement demand. These units dominate rural Indian and Southeast Asian markets where electricity reliability limits smart-feature utility.
- Multi-functional Appliances:Modular attachments convert base motors between blending, processing, and mixing functions. Space-constrained apartments in London and Singapore favor these units over single-purpose alternatives.
- Traditional Appliances:Brushed universal motors with mechanical switches serve emerging market entry points. Volume concentration in Brazil, Mexico, and Indonesia reflects distribution through informal retail channels.
Standard appliances capture the volume base. Multi-functional designs are expanding most quickly.
Size:
Volume distribution tracks urban household density, with compact and handheld units gaining share in high-rise residential markets.
- Compact:Footprints under 200 square centimeters accommodate studio apartments and secondary kitchen installations. German-engineered 400W units with die-cast housings command premium positioning in Swiss and Austrian markets.
- Full-size:Commercial-grade motor assemblies and reinforced gearboxes handle continuous operation. Professional catering operations in France and Italy specify these units for sauce and dough production.
- Countertop:Mid-capacity housings balance performance with storage practicality. These units represent the default specification for first-time homebuyers in China's tier-2 cities.
- Handheld:Immersion blenders and stick mixers with detachable shafts enable direct pot processing. Cordless lithium-ion variants from Japanese manufacturers gain traction in Korean and Taiwanese markets.
Countertop units anchor household penetration. Handheld formats are climbing the fastest.
End User:
Application intensity separates occasional home users from continuous-duty commercial operators, with health tracking creating a distinct behavioral segment.
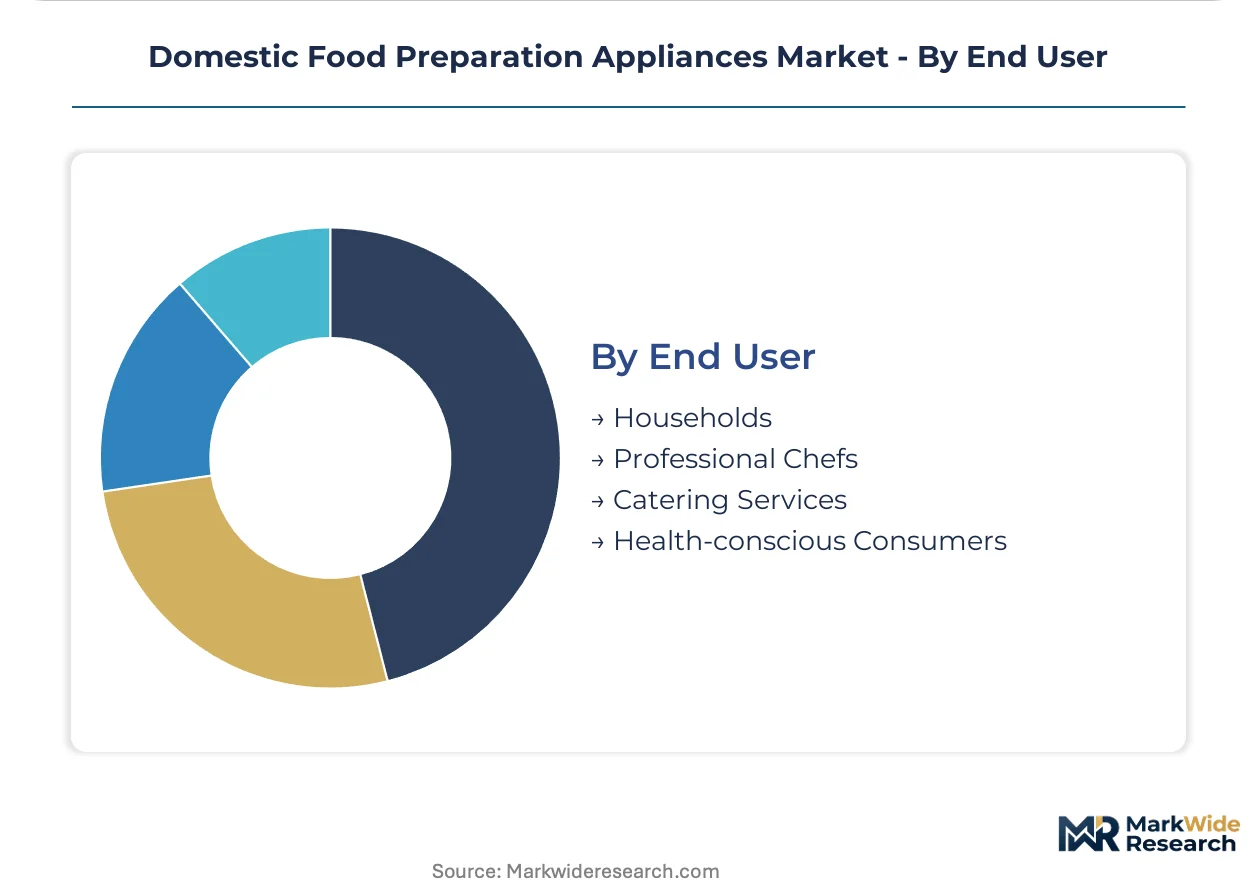
- Households:General-purpose appliances with 3-5 year replacement cycles dominate this segment. EU Ecodesign standby power mandates accelerate turnover as families replace pre-compliant units.
- Professional Chefs:NSF-certified construction and continuous-duty motors withstand restaurant kitchen environments. These users prioritize torque consistency over connectivity features.
- Catering Services:High-capacity batch processing equipment with reinforced safety interlocks serves mobile and institutional food operations. Rental and lease financing models predominate in this segment.
- Health-conscious Consumers:Nutrient extraction metrics and portion-control features drive appliance selection. This cohort over-indexes on smart appliances with integrated scale and timer functions.
Households retain the volume concentration. Health-conscious consumers are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across geographies. European buyers prioritize energy-efficient motors and compact footprints for urban kitchens. Chinese and Indian markets favor multi-functional units that maximize utility in space-constrained households. North American demand clusters around premium smart features and health-tracking integration.
China
Urban household formation in tier-1 cities drives replacement demand for full kitchen appliance suites. SAMR's compulsory GB certification for electromagnetic compatibility and food-contact material safety shapes product compliance costs. Shenzhen and Guangzhou manufacturing clusters concentrate brushless DC motor production for export-oriented blender lines.
United States
Health-conscious coastal metro buyers adopt Wi-Fi-enabled blenders bundled with meal-kit subscriptions. The Consumer Product Safety Commission enforces electrical safety standards that extend certification timelines for smart appliances. Chicago and Milwaukee industrial corridors retain planetary mixer assembly for premium home baking segments.
Germany
Home bakers in Bavaria and Baden-Württemberg specify bowl-lift mixer designs for dense whole-grain formulations. The EU Ecodesign Directive's standby power limits force control board redesigns for sub-0.5W phantom-load compliance. Stuttgart engineering clusters develop silicon carbide motor controllers for quieter, premium-positioned units.
India
Middle-class households upgrading from manual preparation drive demand for compact 400W processors. BIS certification alignment and PLI scheme incentives attract localized production investments. Maharashtra and Gujarat industrial zones host assembly operations targeting price-sensitive replacement cycles.
Japan
Urban apartment dwellers in Tokyo and Osaka favor handheld immersion blenders with detachable shafts and cordless lithium-ion power. METI efficiency standards accelerate turnover of pre-compliant brushed motor designs. Nagoya manufacturing bases supply compact die-cast housings for Swiss and Austrian premium markets.
Domestic Food Preparation Appliances Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier that relies on outsourced motor and blade assemblies. Captive production of permanent magnet motors and precision gearboxes separates margin-sustainable players from assembly-dependent competitors. Three archetypes dominate: diversified appliance conglomerates with smart ecosystem platforms, precision-engineering specialists with German or Japanese heritage, and scale-driven manufacturers leveraging Chinese supply chains. Competitive moves center on backward integration into motor production and API partnerships with recipe platforms to secure recurring revenue streams.
Among diversified appliance conglomerates, Whirlpool Corporation and Samsung Electronics exemplify contrasting ecosystem strategies. Whirlpool anchors North American manufacturing control through captive mixer assembly footprints. Samsung occupies a position defined by smart kitchen platform integration rather than component specialization. BSH Home Appliances represents the precision-engineering archetype, with German GmbH structure signaling heritage positioning in European markets. These three players illustrate how vertical integration depth, geographic manufacturing footprint, and connectivity feature depth create distinct competitive vectors without overlapping strategic emphasis.
| Leading Market Players |
|---|
| Whirlpool Corporation |
| Samsung Electronics |
| LG Electronics |
| Electrolux AB |
| BSH Home Appliances |
| Koninklijke Philips N.V. |
| Panasonic Corporation |
| Breville Group Ltd. |
| Haier Group Corporation |
| Others |
Value Chain & Pricing Dynamics
Long-term motor procurement contracts with Shenzhen and Guangzhou suppliers lock in neodymium magnet access and buffer manufacturers against rare-earth price volatility while anchoring component cost visibility across multi-year production cycles. This contract structure concentrates pricing power with integrated producers who command captive blade and motor production, forcing assembly-reliant competitors into spot-market exposure for copper windings and silicon carbide controllers.
Pricing Analysis
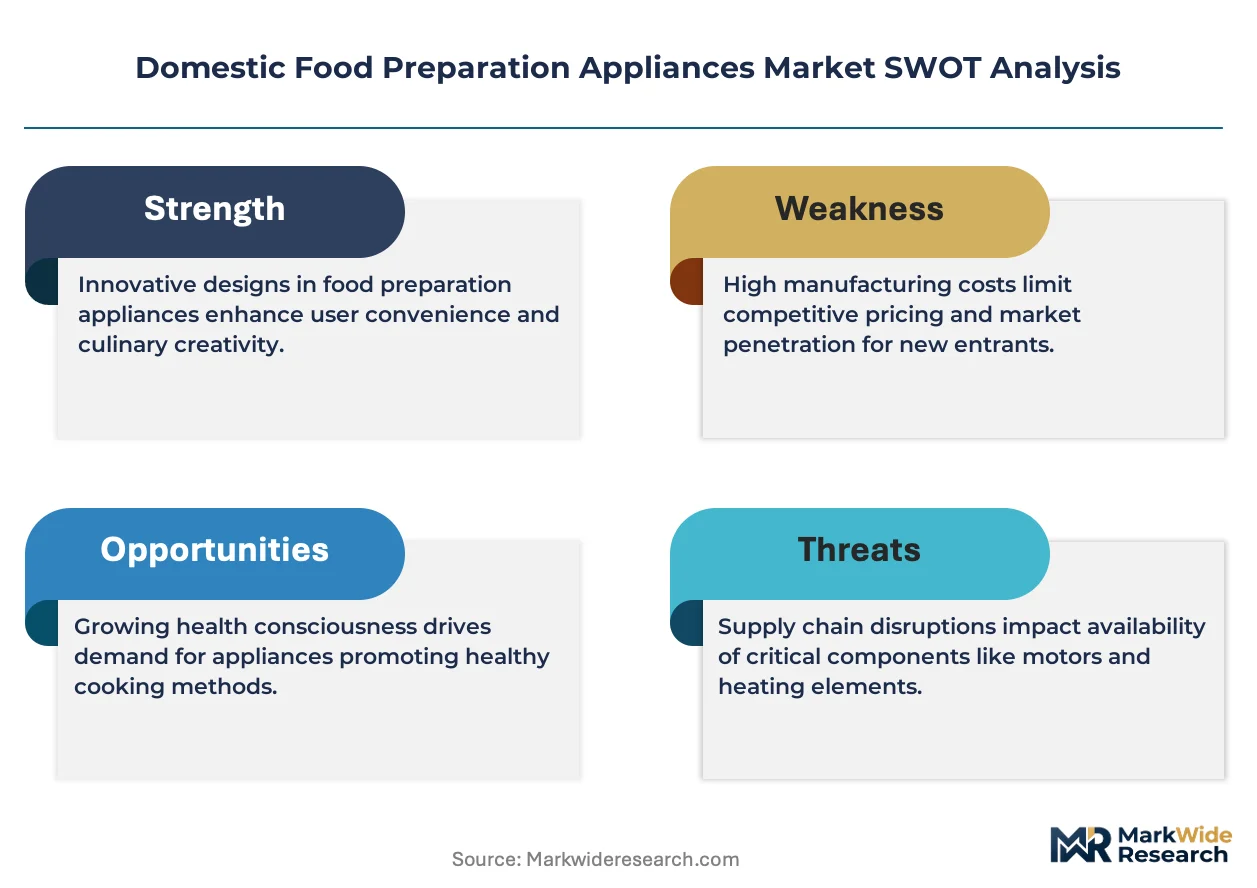
After-sales parts and extended service contracts drive lifetime value for premium blender and mixer lines, with three-tier pricing structure across premium, standard, and economy levels stratifying by motor efficiency certification and smart connectivity depth. Price differentiation hinges on EU Ecodesign standby-power compliance and captive component production, with cost compression in economy tiers intensifying due to Chinese export price competition. Health-conscious coastal metro buyers show lowest price sensitivity, while rural Indian replacement cycles exhibit highest elasticity.
Supply Chain Analysis
Inventory lead times for brushless DC motor controllers stretch longest when sourced from Stuttgart engineering clusters, compressing when drawn from Shenzhen manufacturing bases. Supply concentrates in China for high-speed blade assemblies and motor housings, in Germany for precision gearboxes, and in Japan for compact die-cast housings. Raw material dependencies rest on neodymium permanent magnets, copper windings, and food-grade stainless steel. Single-source vulnerability concentrates in Chinese rare-earth processing. Distribution runs through big-box retail in North America and direct-to-consumer subscription bundling in European coastal metros.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Embedded firmware engineering talent for real-time operating systems and cybersecurity protocols sits in acute shortage, constraining connectivity feature development timelines and compressing competitive advantage toward firms with established software engineering benches.
For Market Incumbents: Shield margin position by deepening backward integration into permanent magnet motor production and securing API partnerships with recipe platforms before subscription bundling displaces traditional retail channels. Prioritize certification investment for EU Ecodesign standby-power compliance to accelerate premium product turnover against aging inventory.
For New Entrants and Emerging Players: Anchor in India's underpenetrated middle-class households upgrading from manual preparation, where BIS certification alignment and PLI scheme incentives lower barrier to entry. Target compact multi-functional appliances for space-constrained tier-1 Chinese apartments, leveraging localized assembly to bypass import cost structures.
For Investors and Strategic Acquirers: Capital is best deployed toward vertically integrated specialists with captive motor and blade production, as these assets sustain margin control through commodity price cycles. Over a five-to-ten-year horizon, ecosystem lock-in value from recipe platform API integrations signals durable competitive positioning. Watch silicon carbide motor controller adoption rates in European premium markets as inflection indicator for technology leadership shifts.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Motor Production | Captive neodymium magnet supply buffers Whirlpool and BSH against Chinese processing disruptions. |
| Recipe Platform API Partnership | HelloFresh and Gousto integrations secure brand visibility at point of first use for smart appliance lines. |
| EU Ecodesign Compliance Investment | Sub-0.5W standby power certification unlocks premium positioning in French and Italian replacement cycles. |
| Localized Production under PLI Scheme | Maharashtra and Gujarat assembly operations target price-sensitive Indian middle-class demand. |
| Silicon Carbide Controller Adoption | Stuttgart-engineered power electronics enable quieter operation commanding Swiss and Austrian price premiums. |
Study Parameters
A standing panel of appliance category managers, motor procurement leads at tier-1 manufacturers, SAMR certification consultants, and recipe platform integration engineers provided ongoing calibration against market developments. Primary interviews with BSH supply chain directors and Shenzhen export facility operators combined with secondary validation from EU Ecodesign Directive implementation reports, UL certification databases, and Chinese customs trade records. Bottom-up unit shipment modeling triangulated against top-down consumer expenditure surveys across the analysis window.
Consistency checks against external benchmarks validated volume and value outputs, with segmentation modeling across product type, technology tier, size format, and end-user application throughout the projection horizon. CAGRs derived from installed base replacement dynamics and urban household formation rates, incorporating motor efficiency mandate compliance curves and smart connectivity adoption slopes as industry-specific forecast inputs.
Material uncertainties — rare-earth supply disruptions, EU standby-power enforcement intensity, and meal-kit platform bundling penetration — sit outside the modeled envelope. Forecasts reflect documented assumptions about regulatory timeline adherence and consumer willingness-to-pay for connected features. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Appliances
Industrial Gas Stove Market
Appliances
Asia Pacific Compact Dishwasher Market
Appliances
Mexico Laundry Appliances Market
Appliances
Saudi Arabia Water Heater Market
Appliances
Middle East Water Heater Market
Appliances
Japan Massage Equipment Market
Appliances
France Household Electric Grills Market
Appliances
United Kingdom Compact Dishwasher Market
Appliances
Sanitary Towel Machine Market
Appliances
Global Electric Water Heaters Market
Appliances
Fully Integrated Dishwasher Market
Appliances
United States Electronics and Appliance Stores Market
Appliances
Europe Microwave Oven Market
Appliances
North America Washing Machine Market
Appliances
Fully Automatic Dishwasher Market
Appliances
Asia-Pacific Tumble Dryers Market