
 Hairdryer Market | 2026-2036
Hairdryer Market Size, Share, and Industry Trends Forecast 2026-2036
Hairdryer Market Foresight
Ceramic heating elements are displacing traditional metal-coil constructions and is realigning cost structures across the supply chain. Dyson leverages advanced digital motor R&D to sustain premium positioning in North America and Western Europe. Panasonic anchors its competitive stance through integrated manufacturing of high-RPM brushless motors and proprietary nanoe ionization systems.
A hairdryer is an electromechanical device that accelerates evaporative drying of hair through forced convection, typically employing AC or brushless DC motors rated between 1000W and 2400W, with heating elements controlled by thermostats or thermistors to maintain outlet temperatures between 40°C and 140°C. Professional-grade units dominate margin pools due to durability requirements and salon replacement cycles, while travel and compact segments compete on portability and dual-voltage compatibility. Infrared and tourmaline technologies are gaining share as consumers prioritize moisture retention and cuticle-sealing performance over raw drying speed.
The EU Ecodesign Directive and REACH chemical compliance frameworks constrain material choices and motor efficiency thresholds for products sold in Europe. The U.S. Consumer Product Safety Commission and UL safety standards govern cord durability, overheat protection, and grounding requirements across the North American market. Stakeholders must monitor evolving wattage caps in major economies and assess whether motor-platform standardization or regional SKU fragmentation offers superior returns on compliance investment.
Market Dynamics
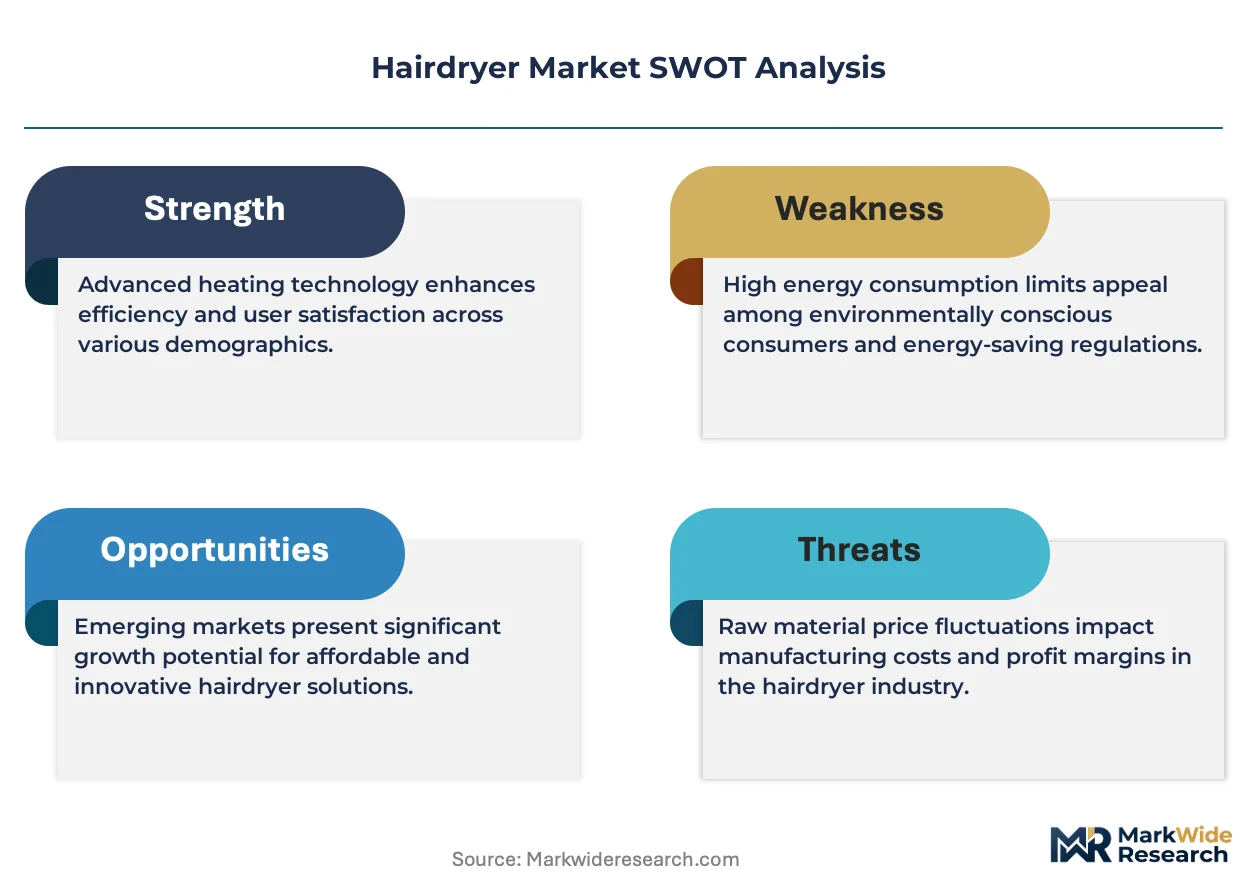
Professional salon operators now prioritize motor efficiency and heat-damage mitigation over wattage ratings, compressing replacement cycles and forcing manufacturers to redesign thermal management architectures around brushless DC platforms.
Growth Catalysts
- Ionic technology penetration:Tourmaline-infused heating elements reduce static electricity and cuticle damage, driving replacement demand among professional stylists in high-throughput salon environments.
- EU Ecodesign Directive:Mandatory energy-efficiency thresholds for small household appliances are accelerating R&D investment in lower-wattage, high-airflow motor designs for European market access.
- China production scaling:Domestic contract manufacturers in Guangdong and Zhejiang provinces are expanding automated assembly capacity to serve both local consumption and export markets.
Market Restraints
- Neodymium magnet cost volatility:Rare-earth price swings directly impact brushless motor production economics, squeezing margins on mid-tier product lines.
- REACH chemical compliance:Restricted substance lists for plastics and coatings add formulation complexity and extend qualification timelines for European-bound SKUs.
- Copper winding substitution limits:Aluminum alternatives degrade thermal performance in high-RPM applications, constraining cost-down pathways for premium motor platforms.
Strategic Opportunities
- India salon sector formalization:Organized retail chains and franchise beauty clinics are standardizing equipment procurement, creating bulk purchasing channels previously fragmented across independent operators.
- Travel segment dual-voltage integration:USB-C PD charging compatibility opens distribution through electronics retailers and airport retail, bypassing traditional beauty supply channels.
- Infrared heating convergence:Combination ceramic-infrared elements penetrate deeper into hair shafts with lower surface temperatures, enabling professional claims around moisture retention.
Industry Challenges
- Brushless motor controller firmware:Embedded software development for precise RPM modulation requires specialized electromechanical engineering talent scarce outside Japan and Germany.
- UL 859 certification timelines:Cord flex testing and overheat protection validation for North American entry routinely extends product launch schedules by eight to fourteen months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hairdryer Market |
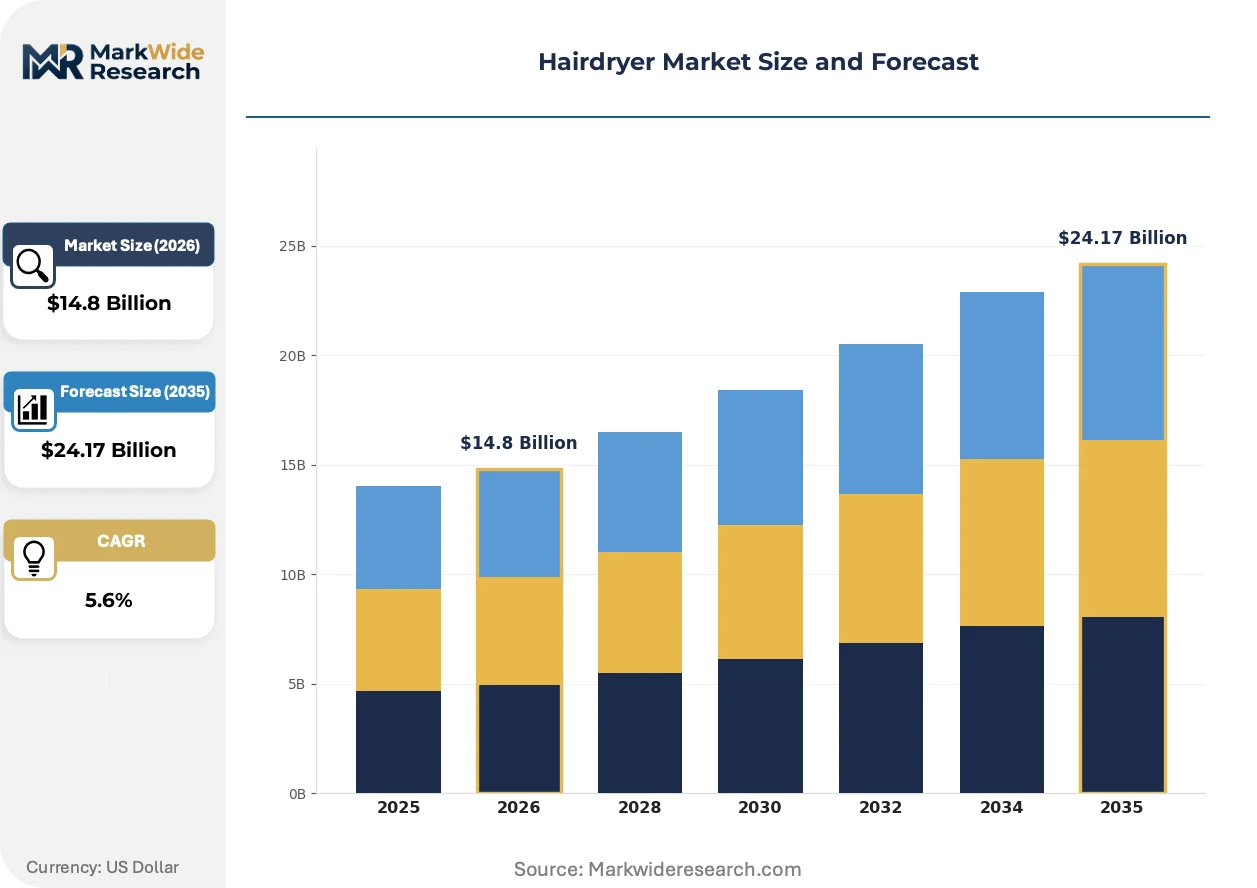
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $24.17 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Travel, Ionic, Hooded, Professional Technology: Infrared, Tourmaline, Ceramic, Conventional End User: Consumer, Salon, Hospitality, B2B Power Rating: 1000W, 1500W, 2000W, Above 2000W |
| Companies Covered | Dyson, Koninklijke Philips, Panasonic, Conair Corporation, Helen of Troy, Spectrum Brands, Groupe SEB, Revlon, TESCOM, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hairdryer Market Shifts & Advancements
Product development cycles are compressing as thermal engineering and materials science converge, with manufacturers racing to integrate sensor-controlled heat delivery before regulatory wattage caps harden in major economies.
Digital motor controllers with real-time temperature feedback are absorbing functionality previously handled by mechanical thermostats, enabling precise outlet temperature maintenance within two-degree tolerances. High-end salon equipment buyers are specifying these systems for color-treated hair protocols. The shift is absorbing margin from conventional bimetallic switch suppliers and consolidating electronic component sourcing toward specialized semiconductor vendors.
REACH authorization requirements for flame retardants in polymer housings are forcing reformulation of ABS and polycarbonate blends used in handle assemblies. The industrial consequence is extended material qualification periods and elevated testing costs for European market entry. Professional-grade manufacturers with existing laboratory infrastructure are absorbing these costs more readily than economy-tier competitors, widening the compliance gap between segments.
Salon procurement officers are consolidating vendor relationships and demanding multi-year service agreements with guaranteed replacement part availability. Independent beauty supply distributors are losing shelf space to direct manufacturer partnerships with national salon chains. This consolidation is most visible in Germany and South Korea, where franchise clinic networks now specify single-source equipment contracts spanning dryers, irons, and processing units.
Hairdryer Market Segmentation
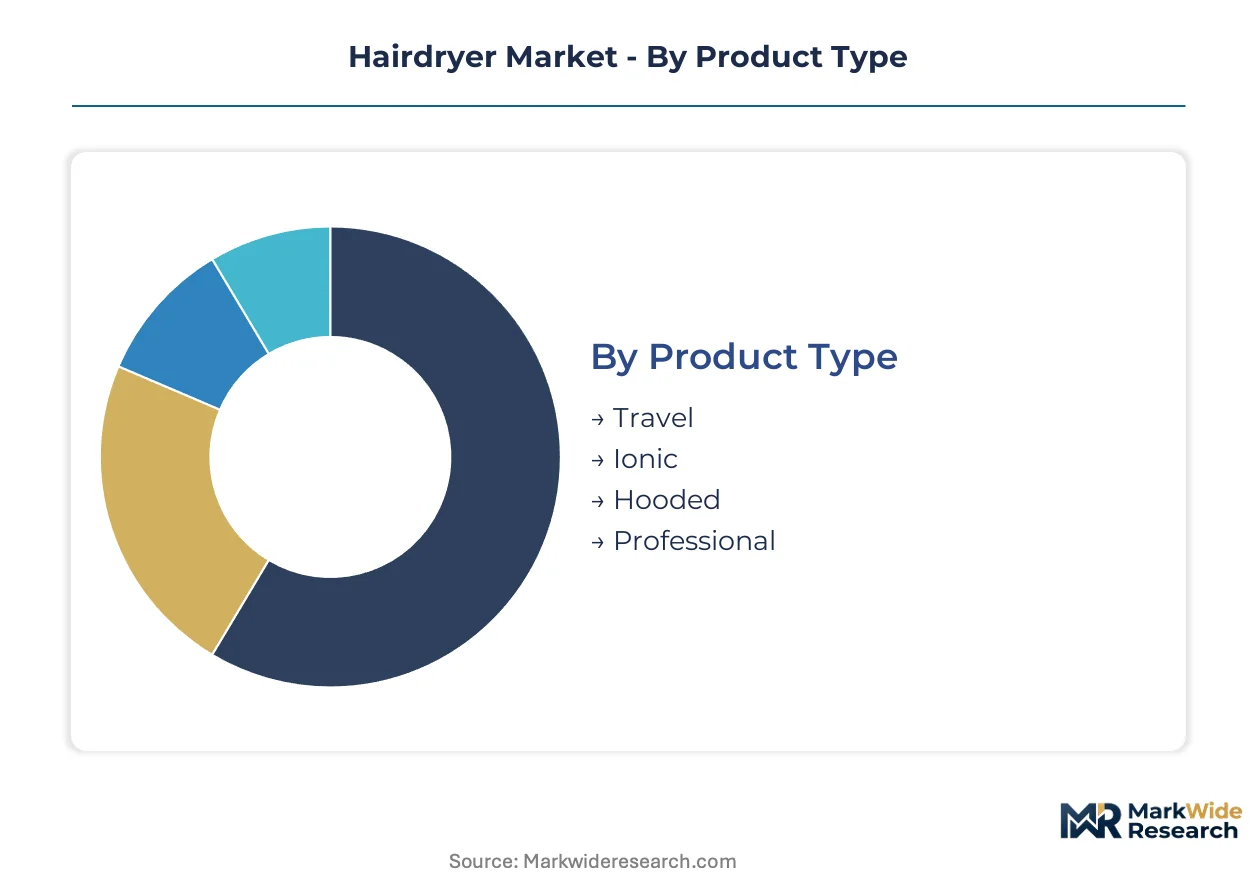
Hairdryer procurement patterns diverge sharply across use cases, with certification requirements, duty cycles, and thermal specifications creating distinct margin architectures. Manufacturers must align motor platforms and safety testing investments to the compliance burden each segment carries.
Product Type:
UL 859 certification applies universally across North American-bound units, while hooded salon systems trigger additional FCC electromagnetic emissions review due to higher-wattage motor controllers.
- Professional:Brushless DC motors rated 1800W–2400W dominate this tier, with thermistor-controlled heat delivery maintaining ±2°C outlet tolerance. Demand concentrates in German and South Korean salon chains standardizing on single-source equipment contracts with multi-year service agreements.
- Ionic:Tourmaline-infused heating elements generate negative ions to reduce static electricity and seal cuticles. Stylists in high-throughput Tokyo and New York salon environments drive replacement demand for reduced heat-damage protocols on color-treated hair.
- Travel:Compact form factors prioritize dual-voltage compatibility and foldable handles. USB-C PD charging integration opens airport retail and electronics distributor channels bypassing traditional beauty supply networks.
- Hooded:Stationary salon processors with bonnet attachments for chemical treatments and deep conditioning. Italian and French salon equipment importers specify these for franchise clinic networks.
Leading the category by volume: Professional. Expanding most quickly: Travel.
Technology:
Material science investments separate cost tiers, with ceramic and tourmaline platforms commanding 40–60% manufacturing cost premiums over conventional metal-coil constructions.
- Ceramic:Aluminum oxide or porcelain-coated heating elements distribute heat evenly and reduce hot spots. Guangdong contract manufacturers are scaling automated ceramic deposition lines to serve export markets facing EU Ecodesign Directive efficiency thresholds.
- Tourmaline:Crushed semiprecious mineral coatings emit infrared heat and negative ions simultaneously. Japanese motor specialists integrate proprietary nanoe ionization systems to differentiate premium positioning.
- Infrared:Penetrates hair shafts at lower surface temperatures, enabling moisture retention claims. Professional equipment buyers in Brazilian and Australian salon chains specify these for damaged-hair treatment protocols.
- Conventional:Nichrome wire heating coils with bimetallic thermostat control. Economy-tier manufacturers in Zhejiang province concentrate production here for price-sensitive Southeast Asian and African markets.
Dominating margin pools: Ceramic and Tourmaline. Steepest expansion trajectory: Infrared.
End User:
Procurement consolidation is compressing vendor counts, with national salon chains and hospitality groups displacing independent beauty supply distributors through direct manufacturer partnerships.
- Salon:Franchise clinic networks in Germany and South Korea now specify single-source contracts spanning dryers, irons, and processing units. These buyers prioritize guaranteed replacement part availability and firmware update commitments.
- Consumer:Mass-market retail through electronics and beauty supply channels. Indian organized retail chains are standardizing equipment procurement previously fragmented across independent operators.
- Hospitality:Hotel and cruise line amenity programs specify compact, dual-voltage units with theft-resistant mounting options. Dubai and Singapore hospitality procurement offices lead specification trends.
- B2B:Contract manufacturing and private-label supply to retailer-owned brands. Guangdong and Zhejiang production clusters serve both local consumption and export markets.
Highest absolute volume: Consumer. Fastest share gain: Salon.
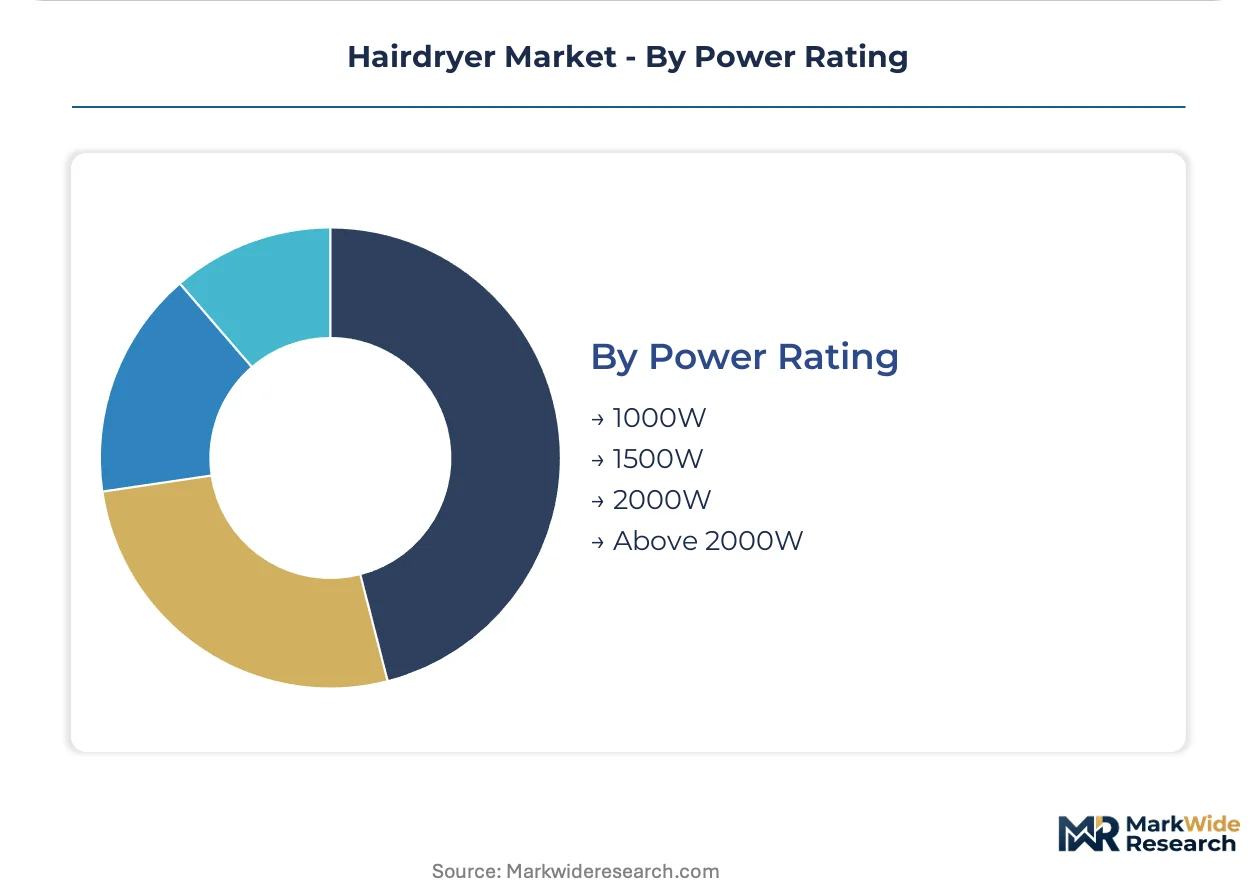
Power Rating:
Regulatory wattage caps are forcing thermal engineering innovation, with EU Ecodesign Directive thresholds and emerging limits in California and South Korea compressing viable operating ranges.
- Above 2000W:High-RPM brushless platforms with advanced aerodynamics maintain airflow performance despite regulatory pressure. Professional stylists in US and Canadian salons continue specifying these for rapid throughput.
- 2000W:The historical professional standard now facing compliance headwinds in European markets. Manufacturers are redesigning thermal management architectures to preserve drying speed at lower wattage.
- 1500W:The emerging sweet spot for EU market access, with motor efficiency investments compensating for reduced thermal output. Panasonic and Dyson R&D centers prioritize this segment.
- 1000W:Travel and compact segment standard, with dual-voltage designs dominating. USB-C PD compatibility is extending this category into electronics retail channels.
Largest installed base: 2000W. Gaining share fastest: 1500W.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China concentrates production capacity across Guangdong and Zhejiang provinces, while professional salon demand clusters in Germany, South Korea, and the United States. Regulatory divergence around energy efficiency and chemical safety is fragmenting product specifications across major economies.
China
Domestic consumption and export manufacturing dominate volume, with Guangdong contract manufacturers scaling automated assembly for both local retail and European-bound professional units. MIIT efficiency guidelines and GB standards for household appliances shape motor platform designs. Shenzhen and Dongguan production clusters specialize in brushless DC motor integration for premium OEM contracts.
Germany
Franchise salon chains standardize procurement through single-source equipment contracts spanning dryers, irons, and processing units. EU Ecodesign Directive wattage thresholds and REACH chemical compliance constrain polymer formulation and motor efficiency requirements. North Rhine-Westphalia distributors serve as the primary gateway for professional-grade imports into Central European markets.
United States
Professional stylists in high-throughput New York and Los Angeles salons specify high-RPM platforms for rapid client turnover. UL 859 safety certification and CPSC cord durability standards govern North American market entry. Midwest retail distribution centers handle mass-market volume through electronics and beauty supply channels.
South Korea
Organized clinic networks consolidate vendor relationships and demand multi-year service agreements with guaranteed replacement part availability. MFDS electrical safety standards and emerging energy efficiency guidelines shape product qualification. Seoul-based salon chains anchor premium equipment specification trends across Northeast Asia.
India
Organized retail chains and franchise beauty clinics standardize equipment procurement previously fragmented across independent operators. BIS certification requirements for electrical appliances and import duty structures influence sourcing decisions. Maharashtra and Karnataka distribution hubs serve emerging salon formalization in Mumbai and Bangalore metro areas.
Hairdryer Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with premium positioning concentrated among motor technology leaders and volume production anchored in Chinese OEM clusters. The structure tiers across three levels: integrated technology owners, regional brand licensees, and pure-play contract fabricators. Dominant competitive moves include direct manufacturer partnerships with national salon chains and firmware-controlled thermal management differentiation.
Among integrated technology owners, Dyson and Panasonic exemplify archetypes built on proprietary motor platforms and controlled air delivery systems. Koninklijke Philips occupies a position bridging professional specification and mass-market accessibility through licensed production arrangements. These three represent the strategic poles around which mid-tier competitors and contract manufacturers orient positioning.
| Leading Market Players |
|---|
| Dyson |
| Koninklijke Philips |
| Panasonic |
| Conair Corporation |
| Helen of Troy |
| Spectrum Brands |
| Groupe SEB |
| Revlon |
| TESCOM |
| Others |
Supply & Pricing Matrix
The EU Ecodesign Directive and REACH chemical compliance frameworks gate qualified supply for European market access while compressing premium-tier pricing power for manufacturers lacking in-house laboratory infrastructure. Professional-grade producers absorb extended material qualification periods more readily than economy-tier competitors, widening the compliance-driven margin gap between segments.
Pricing Analysis
Volume concentrates in economy-tier conventional coil units manufactured in Zhejiang province, while margin pools accrue to ceramic and tourmaline platforms commanding manufacturing cost premiums through proprietary nanoe ionization and brushless DC motor integration. Price differentiation hinges on UL 859 certification grade for North American entry and firmware-controlled thermal management precision for salon specification. Cost compression in mid-tier brushless motor lines intensifies because neodymium magnet price volatility squeezes production economics. Independent beauty supply distributors exhibit highest price sensitivity, whereas German and South Korean franchise clinic networks prioritize guaranteed replacement part availability over unit cost.
Supply Chain Analysis
Regional distribution centers in North Rhine-Westphalia and Midwest retail hubs handle professional-grade imports and mass-market volume respectively, with hub-and-spoke patterns consolidating toward direct manufacturer partnerships. Manufacturing concentrates in China, Japan, and Germany, with Guangdong contract manufacturers scaling automated ceramic deposition lines and Shenzhen clusters specializing in brushless DC motor integration. Raw material dependencies center on neodymium rare-earth magnets, copper windings, and ABS polycarbonate blends for flame-retardant housings. Single-source vulnerability in rare-earth supply from concentrated mining jurisdictions poses structural risk. Distribution runs through national salon chain procurement offices and electronics retailer channels for travel-segment USB-C PD compatible units.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The hairdryer market sits in a technology-transition phase as brushless DC platforms displace conventional AC motor architectures, with digital motor controllers absorbing functionality from mechanical thermostats.
For Market Incumbents: Anticipate regulatory wattage caps hardening in California and South Korea by accelerating R&D in 1500W high-efficiency thermal management architectures. Defend margin position through backward integration into brushless motor controller firmware development, addressing scarce electromechanical engineering talent outside Japan and Germany. Consolidate vendor relationships with national salon chains through multi-year service agreements spanning guaranteed replacement part availability. For New Entrants and Emerging Players: Capture white-space in India organized retail chains and franchise beauty clinics standardizing equipment procurement previously fragmented across independent operators. Target travel-segment USB-C PD charging compatibility to open airport retail and electronics distributor channels bypassing traditional beauty supply networks. Pursue private-label contract manufacturing arrangements with Guangdong production clusters serving export markets facing EU Ecodesign Directive thresholds. For Investors and Strategic Acquirers: Firmware-controlled thermal management precision achieving two-degree outlet tolerance is the leading indicator that premium salon specification trends are consolidating toward integrated technology owners. Long-term viability favors acquisition targets with captive brushless motor platforms and existing laboratory infrastructure for REACH compliance qualification. Monitor single-source equipment contract announcements from German and South Korean franchise clinic networks as inflection signals for vendor consolidation velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Brushless DC Motor Platform Standardization | Reduces firmware development costs across EU and North American SKU portfolios while meeting Ecodesign thresholds. |
| Direct Salon Chain Partnership | Bypasses independent beauty supply distributors losing shelf space to manufacturer-direct procurement consolidation. |
| Ceramic-Tourmaline Deposition Scale-Up | Guangdong automated lines serve export demand for ionic technology penetration in high-throughput Tokyo and New York salons. |
| USB-C PD Charging Integration | Opens electronics retail and airport distribution channels for travel-segment dual-voltage compact units. |
| REACH Compliance Laboratory Investment | Absorbs extended material qualification periods for flame-retardant polymer housing reformulation in European-bound professional units. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this hairdryer market analysis, supplemented by primary interviews with salon procurement officers, brushless motor R&D directors, contract manufacturing plant managers, and beauty supply distributors. Secondary sources included UL certification databases, EU Ecodesign Directive compliance registries, MIIT efficiency guideline publications, and import-export manifests from Guangdong and Zhejiang customs zones. Bottom-up unit shipment estimates triangulated against top-down value projections derived from manufacturer revenue disclosures and retail audit data.
Granularity-level modeling captured product type, technology platform, end-user segment, power rating tier, and regional regulatory cluster across the projection horizon. Segment-level CAGRs were derived from fitted growth curves applied to historical shipment trajectories, with motor efficiency investment cycles and salon replacement frequency patterns serving as industry-specific forecast inputs. Professional-grade unit economics incorporated thermistor-controlled heat delivery specification premiums and multi-year service agreement attach rates.
The model holds under stable rare-earth magnet pricing and steady EU Ecodesign Directive enforcement; deviation in neodymium supply disruptions or accelerated wattage cap adoption in additional jurisdictions would shift volume and value trajectories. Forecasts reflect assumptions around brushless motor cost-down curves and salon sector formalization velocity in emerging markets. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Appliances
US Washing Machine Parts Market
Appliances
Turkey Washing Machine Market
Appliances
Residential Space Heater Market
Appliances
United States Microwave Oven Market
Appliances
Global Home Ice Maker Market
Appliances
UK Residential Vacuum Cleaner Market
Appliances
Middle East Water Heater Market
Appliances
United States Electric Kettle Market
Appliances
Fully Automatic Dishwasher Market
Appliances
France Household Electric Grills Market
Appliances
North America Personal Care Appliances Market
Appliances
Oman Dishwashers Market
Appliances
Saudi Arabia Gas Hobs Market
Appliances
Bathroom Heaters Market
Appliances
Mobile Refrigerators Market
Appliances
Europe Induction Hobs Market