
 Japan Massage Equipment Market | 2026-2036
Japan Massage Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Japan Massage Equipment Market Insights
JIS C 1010 electrical safety certification is bifurcating the competitive landscape into qualified incumbents and cost-driven challengers. Panasonic leverages its domestic manufacturing footprint to sustain premium positioning across full-body massage chair lines. Family Inada anchors its reputation on proprietary roller mechanism R&D developed at its Osaka headquarters. Fujiiryoki competes through specialized shiatsu-mimicking technology that dominates the therapeutic segment.
Japan massage equipment encompasses electromechanical devices engineered to deliver percussive, rolling, or compressive tissue manipulation through motorized actuators typically operating at 50-60 Hz with heating elements reaching 40-50°C for therapeutic applications. These systems serve both consumer wellness and clinical rehabilitation purposes across residential and professional settings. Massage chairs command the dominant revenue share due to high unit values and integration of multi-modal vibration, heating, rolling, and air compression technologies. Home use applications lead volume consumption, while commercial use in spa treatment and fitness centers captures concentrated margin pools through durable-specification procurement contracts.
PMDA medical device classification rules and METI energy-efficiency standards jointly determine product compliance costs and market access timelines for manufacturers. JIS standards further govern electrical safety and electromagnetic compatibility, creating layered certification requirements that favor established players with dedicated regulatory affairs capabilities. Stakeholders must monitor evolving PMDA guidance on wellness-versus-medical claims as this boundary shapes permissible marketing and distribution channels.
Market Dynamics
METI energy-efficiency guidelines are forcing a redesign of heating elements and motor assemblies across Japanese massage equipment manufacturing, compressing margins for cost-optimized producers while rewarding incumbents with captive R&D infrastructure.
Growth Catalysts
- Tokyo Metropolitan senior care expansion:Prefecture-level wellness infrastructure subsidies are accelerating procurement cycles for therapeutic-grade massage chairs in assisted living facilities.
- PMDA medical device pathway clarification:The regulator's 2023 guidance on wellness-versus-medical claims boundary has opened institutional reimbursement channels for certified therapeutic equipment.
- Air compression module innovation:Osaka-based component suppliers are delivering quieter pneumatic systems that enable residential installation without structural modifications.
Market Restraints
- JIS C 1010 compliance cost escalation:Third-party electrical safety testing fees have risen substantially, disproportionately burdening sub-scale domestic assemblers.
- Copper and rare-earth magnet price volatility:Motor core materials face supply concentration from Chinese processing facilities, transmitting input cost shocks.
- Substitution from manual therapy services:Licensed acupuncture and shiatsu practitioners in Kansai urban centers compete directly for chronic pain management spending.
Strategic Opportunities
- Hokkaido and Tohoku underpenetration:Prefectures outside Kanto show substantially lower massage chair household penetration, presenting whitespace for distribution network extension.
- Hotel wellness amenity integration:Ryokan chains and business hotels are specifying compact massage units for guest room deployment, creating a new procurement vertical.
- AI-powered body scanning convergence:Integration of pressure sensors with machine learning algorithms enables personalized massage programming that differentiates premium tiers.
Industry Challenges
- Embedded systems firmware talent scarcity:Domestic engineering programs produce insufficient graduates with real-time control software expertise for actuator coordination.
- PMDA pre-market notification timelines:Medical device classification reviews average 14-18 months, freezing product launch schedules and inventory planning.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Japan Massage Equipment Market |
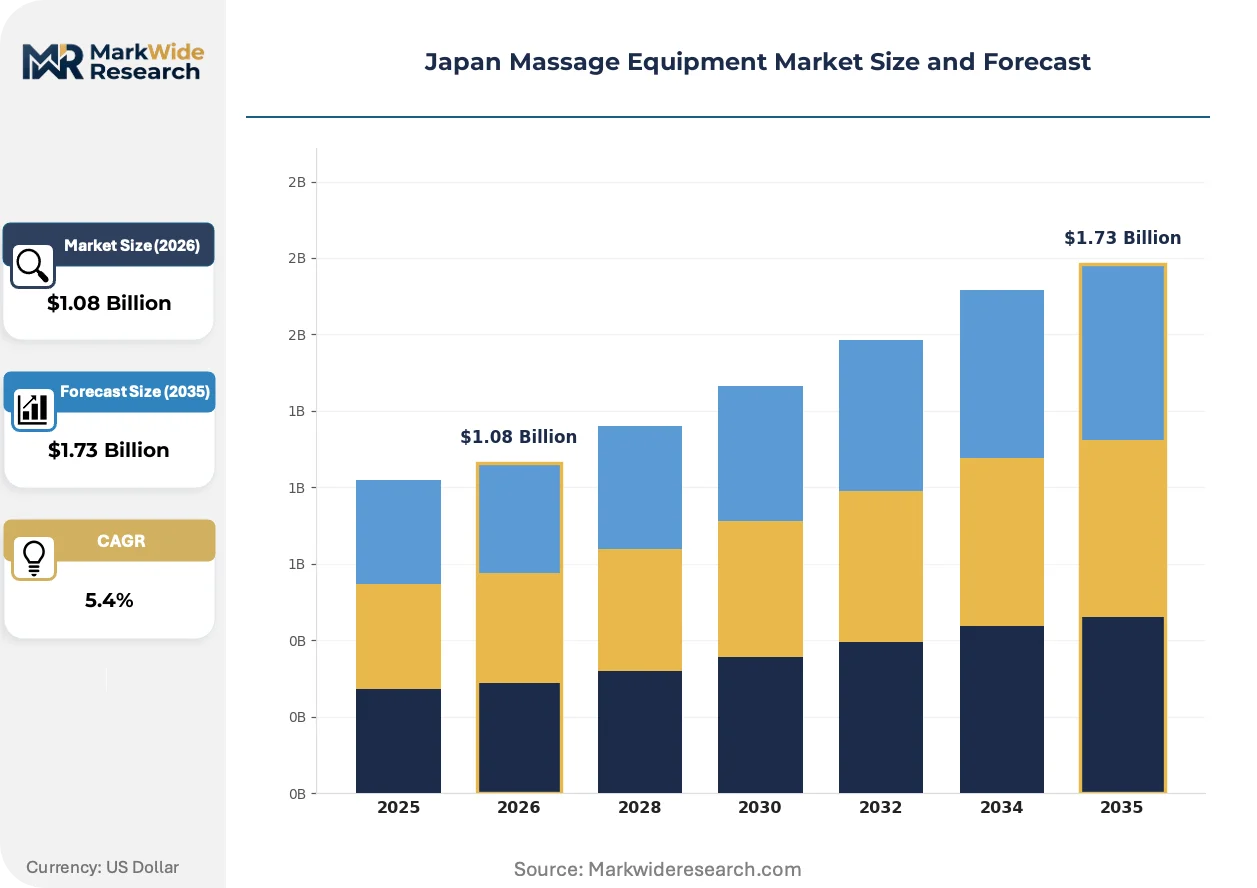
| Market Size in 2026 | $1.08 Billion |
| Market Size in 2035 | $1.73 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Massage Chairs, Handheld Massagers, Massage Cushions, Foot Massagers Application: Home Use, Commercial Use, Spa Treatment, Fitness Centers Technology: Vibration, Heating, Rolling, Air Compression End User: Individuals, Therapists, Gyms, Wellness Centers |
| Companies Covered | Panasonic, Family Inada, Osaki, Fujiiryoki, JPMedics, Omron Corporation, Samsung Electronics, LG Electronics, HUTECH, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Japan Massage Equipment Market Trends and Innovations
Actuator engineering and control systems are converging to deliver personalized tissue manipulation at lower physical footprints, compressing the traditional trade-off between therapeutic intensity and residential space constraints.
Brushless DC motor arrays with integrated force feedback are miniaturizing the mechanical chassis required for full-body coverage. Osaka-headquartered manufacturers are deploying these systems in compact ottoman-style chairs targeting Tokyo apartment dwellers. The technology is miniaturizing installation barriers that previously restricted market penetration to single-family residences.
METI's 2024 appliance efficiency standards are mandating standby power draw below 0.5W for all motorized wellness equipment. Manufacturers must redesign power management circuits and heating element insulation, extending development cycles by 8-12 months. The therapeutic segment faces the steepest compliance burden due to thermal output requirements for muscle relaxation claims.
Corporate wellness programs are unbundling after-sales service from equipment procurement, with facility managers negotiating separate maintenance contracts rather than bundled multi-year agreements. This shift compresses upfront capital requirements but exposes manufacturers to price competition on replacement parts. The pattern is most pronounced in Kanto region technology sector employers with centralized procurement functions.
Japan Massage Equipment Market Segmentation
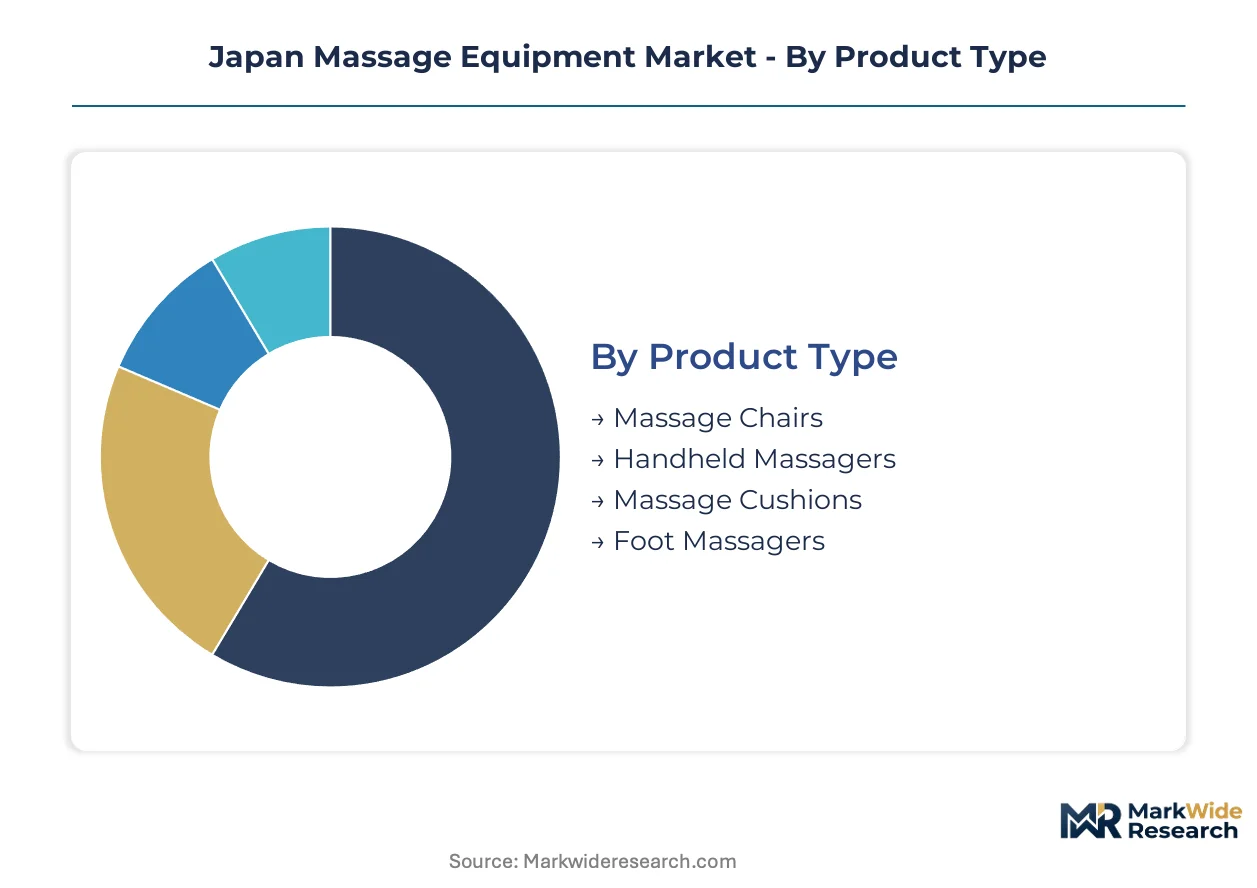
Segmentation in the Japan massage equipment market reveals how METI efficiency mandates and PMDA classification rules create divergent compliance burdens across product tiers. Manufacturers optimize their portfolios by matching technical specifications to the regulatory intensity of each segment.
Product Type:
PMDA medical device classification splits this category into therapeutic-grade equipment requiring pre-market notification and general wellness products governed by simpler METI appliance standards.
- Massage Chairs:Full-body electromechanical systems integrate brushless DC motors, heating elements, and air compression modules in chassis designs requiring JIS C 1010 electrical safety certification. Tokyo metropolitan senior care facilities and Kanto region luxury residential towers concentrate procurement for therapeutic-grade units with force-feedback roller mechanisms.
- Handheld Massagers:Portable percussive devices operate through battery-powered linear actuators or vibration motors at 50-60 Hz frequencies, typically exempt from medical device classification but subject to METI standby power regulations. Osaka-based component suppliers dominate motor sourcing for this segment.
- Massage Cushions:Seat-back attachments deliver shiatsu-mimicking roller movement through compact electromechanical arrays targeting vehicle and office chair installation.
- Foot Massagers:Lower-extremity systems combine air compression chambers with thermal elements in pedestal or ottoman configurations.
Massage chairs handle the majority of throughput; handheld massagers are expanding most quickly on share.
Application:
Cost tier differentiation separates institutional procurement with multi-year service contracts from direct-to-consumer retail channels.
- Home Use:Residential installations demand compact footprints compatible with Tokyo apartment spatial constraints, driving demand for ottoman-style chairs with miniaturized brushless motor arrays. Prefecture-level wellness subsidies in Tokyo accelerate therapeutic-grade penetration among aging households.
- Commercial Use:Corporate wellness programs and hospitality deployments specify durable-specification equipment with unbundled maintenance contracts rather than bundled multi-year agreements, compressing upfront capital requirements.
- Spa Treatment:Licensed shiatsu and acupuncture facilities in Kansai urban centers source professional-grade equipment for chronic pain management services.
- Fitness Centers:Gym chains integrate recovery stations with massage chairs and targeted compression systems for post-workout muscle relaxation protocols.
Home use commands the volume base; commercial use captures the steepest expansion trajectory in procurement value.
Technology:
Volume concentration favors established electromechanical platforms while emerging control systems attract R&D investment.
- Vibration:Oscillating motor arrays deliver percussive tissue manipulation through eccentric rotating mass mechanisms, dominating handheld and cushion form factors with simpler manufacturing requirements and lower JIS compliance costs.
- Heating:Resistive element systems reaching 40-50°C therapeutic temperatures face the steepest METI 2024 efficiency redesign burden due to thermal output requirements for muscle relaxation claims.
- Rolling:Proprietary roller mechanism R&D developed at Osaka headquarters anchors premium positioning through programmable track systems mimicking shiatsu finger pressure patterns.
- Air Compression:Pneumatic bladder arrays with quieter compressor systems from Osaka-based suppliers enable residential installation without structural modifications.
Vibration handles the highest unit volumes; air compression is climbing the fastest on technology investment.
End User:
Customer type determines whether procurement flows through retail, institutional contracting, or reimbursement channels.
- Individuals:Direct consumer purchases concentrate in Kanto region urban centers with elevated disposable income, with purchasing decisions influenced by PMDA wellness-versus-medical claims boundary clarity.
- Therapists:Licensed practitioners in Kansai and Kanto urban centers source certified therapeutic equipment eligible for institutional reimbursement under clarified PMDA guidance.
- Gyms:Fitness facility procurement functions negotiate centralized equipment specifications with separate maintenance contract structures.
- Wellness Centers:Ryokan chains and business hotels specify compact massage units for guest room deployment, creating a new hospitality vertical.
Individuals represent the largest addressable base; wellness centers are gaining share fastest on amenity integration trends.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Prefecture-level wellness infrastructure subsidies are redirecting procurement flows toward therapeutic-grade equipment across Japan's major economic zones. METI energy-efficiency mandates and PMDA classification rules create divergent compliance costs that favor established manufacturing clusters.
Kanto/Tokyo
Tokyo metropolitan senior care facilities account for concentrated demand for full-body massage chairs with force-feedback roller mechanisms. The Tokyo Metropolitan Government operates wellness infrastructure subsidy programs that accelerate procurement cycles in assisted living facilities. Chiyoda and Shinjuku wards host corporate headquarters of Panasonic and Omron Corporation, anchoring R&D coordination between manufacturers and institutional buyers.
Kansai/Osaka
Licensed shiatsu and acupuncture practitioners in Osaka urban centers compete directly for chronic pain management spending against electromechanical alternatives. Osaka Prefecture maintains industrial promotion programs supporting component suppliers delivering quieter pneumatic systems. Family Inada anchors proprietary roller mechanism development at its Osaka headquarters, concentrating therapeutic-grade engineering talent.
Chubu/Nagoya
Manufacturing supply chains for brushless DC motor arrays cluster around Nagoya's precision machinery ecosystem. Aichi Prefecture's SME support programs fund component miniaturization research for compact ottoman-style chair designs. Toyota City suppliers are repurposing automotive actuator expertise for wellness equipment motor assemblies.
Kyushu
Fukuoka's growing technology sector is generating corporate wellness program demand for compact massage units. The Kyushu Economic Federation advocates for prefecture-level adoption of Tokyo's senior care equipment subsidy models. Kitakyushu manufacturing zones are attracting Osaka-based suppliers seeking lower facility costs for air compression module assembly.
Hokkaido
Sapporo's aging demographic profile exceeds national averages, creating latent demand for residential therapeutic equipment. Hokkaido Prefecture's rural healthcare infrastructure programs remain underpenetrated by massage equipment distributors. Otaru and Hakodate secondary cities present whitespace for distribution network extension from Kanto logistics hubs.
Japan Massage Equipment Market Competitive Landscape
Player mix skews toward integrated electronics conglomerates with captive appliance divisions alongside specialized wellness equipment fabricators. Domestic incumbents leverage JIS C 1010 certification infrastructure and METI regulatory relationships to sustain premium positioning. Three strategic archetypes dominate: diversified electronics majors with wellness verticals, dedicated massage equipment specialists with proprietary mechanism IP, and Korean consumer appliance exporters competing on feature density. Competitive moves concentrate on AI-powered body scanning integration and unbundling of maintenance contracts from equipment sales.
Among diversified Japanese electronics conglomerates, Panasonic and Omron Corporation exemplify the integrated model combining domestic manufacturing footprint with dedicated regulatory affairs capabilities. Family Inada and Fujiiryoki occupy specialist positions anchored on proprietary roller mechanism R&D developed at Osaka headquarters. Korean exporters Samsung Electronics and LG Electronics represent the feature-competition archetype, leveraging display and semiconductor integration expertise from adjacent consumer electronics categories.
| Leading Market Players |
|---|
| Panasonic |
| Family Inada |
| Osaki |
| Fujiiryoki |
| JPMedics |
| Omron Corporation |
| Samsung Electronics |
| LG Electronics |
| HUTECH |
| Others |
Pricing and Supply Chain Analysis
Fourteen-to-eighteen-month PMDA pre-market notification timelines compress inventory turns for therapeutic-grade manufacturers while concentrating pricing power among JIS C 1010-certified incumbents with captive regulatory affairs infrastructure. This lead-time band forces working capital intensity that cost-optimized challengers cannot sustain, bifurcating the competitive landscape into premium-certified and economy-uncertified tiers.
Pricing Analysis
Certification level creates the primary spread between therapeutic-grade and general wellness equipment. Three-tier pricing structure across premium, standard, and economy levels reflects JIS C 1010 compliance costs, METI energy-efficiency redesign investments, and after-sales service bundling. Pricing pressure stems from copper and rare-earth magnet input volatility transmitted through Chinese processing concentration. Corporate wellness programs exhibit highest price sensitivity through unbundled maintenance contract negotiations, while senior care facilities with Tokyo Metropolitan subsidies show lowest sensitivity.
Supply Chain Analysis
China and South Korea anchor motor core and rare-earth magnet processing for Japanese massage equipment manufacturers. Brushless DC motor arrays, heating element assemblies, and pneumatic compressor modules feed from Osaka-based component suppliers and Nagoya precision machinery clusters. Single-source vulnerability concentrates in Chinese rare-earth processing facilities. Distribution runs through Kanto-region electronics retailers, institutional procurement channels for senior care facilities, and direct-to-consumer e-commerce platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Japan's massage equipment market sits at a platform-economics inflection where AI-powered body scanning and personalized massage programming create interoperability standards that will determine ecosystem control. The convergence of pressure sensors with machine learning algorithms is shifting competitive advantage from hardware mechanisms to software-defined personalization layers.
For Market Incumbents: Consolidate regulatory affairs capabilities and captive R&D infrastructure as defensive moats against Korean feature-competition entrants. Deepen backward integration into brushless DC motor production through Nagoya precision machinery partnerships to offset Chinese rare-earth price volatility. Prioritize JIS C 1010 certification maintenance as the priority barrier against cost-optimized challengers. For New Entrants and Emerging Players: Differentiate on compact ottoman-style form factors targeting Tokyo apartment spatial constraints where established players retain legacy chassis designs. Target Hokkaido and Tohoku distribution whitespace where prefecture-level wellness subsidies remain underpenetrated. Pursue ryokan chain and business hotel wellness amenity integration as the most penetrable procurement vertical with unbundled service contract structures. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified electronics conglomerates seeking to divest non-core wellness verticals amid portfolio rationalization pressures. Five-to-ten-year viability hinges on AI-powered personalization software capabilities rather than electromechanical hardware heritage. Watch PMDA guidance evolution on wellness-versus-medical claims boundary as the signal for reimbursement channel expansion and therapeutic-grade margin inflection.| Strategic Initiative | Industry Significance |
|---|---|
| AI Body Scanning Integration | Machine learning algorithms from Osaka R&D clusters enable personalized massage programming that differentiates premium tiers. |
| Backward Integration into Motors | Nagoya precision machinery partnerships reduce exposure to Chinese rare-earth processing concentration and input volatility. |
| JIS C 1010 Certification Investment | Electrical safety compliance creates regulatory moats that cost-optimized challengers cannot cross without dedicated affairs capabilities. |
| Hokkaido Distribution Expansion | Prefecture-level wellness subsidy adoption in Sapporo and secondary cities opens whitespace from Kanto logistics hub extension. |
| Hotel Wellness Amenity Partnerships | Ryokan chains and business hotels specify compact massage units for guest room deployment, creating new hospitality procurement vertical. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with senior care facility procurement managers, licensed shiatsu practitioners in Kansai urban centers, Osaka-based component supplier engineering leads, and METI regulatory affairs specialists. Secondary validation drew from PMDA medical device filings, METI appliance efficiency standard disclosures, JIS certification registries, and prefecture-level wellness infrastructure subsidy documentation. Bottom-up unit economics and top-down macroeconomic triangulation anchored market sizing.
Across the analysis window, the forecasting framework modeled volume and value trajectories through product type segmentation by PMDA classification status, application tier by procurement channel structure, technology platform by METI compliance burden, and end-user category by reimbursement eligibility. CAGRs were derived from regression analysis of historical prefecture-level procurement data and forward projection of senior care facility expansion plans. Industry-specific inputs included Tokyo Metropolitan Government wellness subsidy allocation patterns and Osaka-headquartered manufacturer R&D disclosure trends.
Forecasts assume regulatory continuity in METI energy-efficiency standards and PMDA medical device classification regimes; material policy shifts in standby power mandates or wellness-versus-medical claims boundaries would require re-modeling. Input cost volatility in copper and rare-earth magnet markets, alongside firmware engineering talent scarcity, constitute primary revision triggers. Recalibration cycles align with material shifts in prefecture-level subsidy adoption and PMDA guidance evolution.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Appliances
Gas Ranges Market
Appliances
Digital Showers Market
Appliances
United Kingdom Handheld Vacuum Cleaners Market
Appliances
Laundry Kiosk Market
Appliances
Toaster Ovens Market
Appliances
Europe Household Electric Grills Market
Appliances
Portable Dishwasher Market
Appliances
India Washing Machine Market
Appliances
United States Washing Machine Market
Appliances
Electric Fan Market
Appliances
United States Electronics and Appliance Stores Market
Appliances
Clothing Iron Market
Appliances
Middle East and Africa Commercial Dishwashers Market
Appliances
United Kingdom Tumble Dryers Market
Appliances
Electric Yogurt Maker Market
Appliances
North America Washing Machine Market