
 Middle East Water Heater Market | 2026-2036
Middle East Water Heater Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East Water Heater Market Analysis
Saudi manufacturing clusters is restructuring regional supply chains for water heater components. Rheem Manufacturing Company leverages its established distribution network across Gulf markets. Bradford White Corporation anchors its position through specialized commercial-grade tank fabrication. A.O. Smith competes aggressively on electric instant systems for residential towers.
Middle East water heaters are thermodynamic appliances engineered to elevate potable water temperature through electric resistance, combustion, or ambient heat transfer, typically achieving set points between 49°C and 60°C for sanitary and process applications. Storage water heaters dominate installed base volumes across aging building stock while heat pump variants capture premium retrofit specifications in the UAE's Leadership in Energy and Environmental Design-certified developments. Solar technology segments command elevated margins in Jordan and Morocco where irradiance profiles support year-round thermal collection. The hospitality application category absorbs high-capacity gas-fired systems as hotel operators prioritize continuous draw reliability over capital minimization.
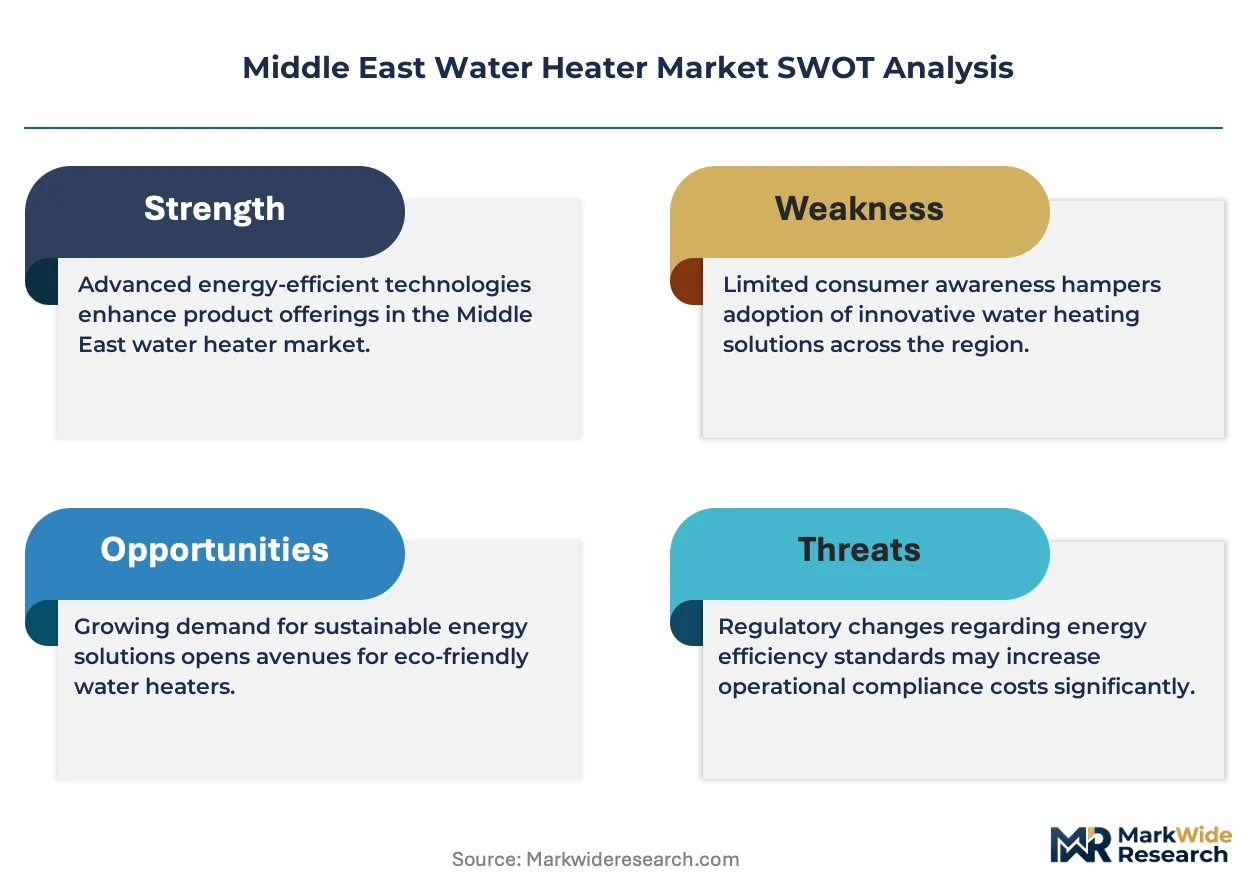
Saudi Arabia's SFDA enforces efficiency disclosure protocols that filter substandard imports from Asian manufacturing zones. The UAE's Emirates Authority for Standardization and Metrology mandates G-Mark conformity for electrical heating appliances entering Gulf customs territories. Stakeholders must monitor evolving green building mandates that increasingly precondition project financing on renewable-ready water heating specifications.
Market Dynamics
Hospitality developers across the Gulf Cooperation Council region are restructuring procurement specifications around solar-integrated thermal systems, compressing traditional equipment replacement cycles and elevating efficiency thresholds for commercial-grade installations.
Growth Catalysts
- SFDA Efficiency Mandates:Saudi Arabia's building codes now require disclosure protocols for commercial water heating equipment, filtering substandard imports and elevating baseline performance standards across the kingdom's construction pipeline.
- Hotel Construction Concentration:Dubai and Abu Dhabi emirates maintain active hospitality development pipelines that absorb high-capacity gas-fired and solar-thermal systems for continuous-draw reliability requirements.
- Heat Pump Technology Maturation:UAE's Leadership in Energy and Environmental Design-certified developments are specifying heat pump variants for premium retrofit installations, displacing conventional electric resistance units in upscale residential towers.
Market Restraints
- Copper and Steel Input Volatility:Tank fabrication depends on commodity metal pricing that fluctuates with global mining output, compressing margin buffers for regional manufacturers serving price-sensitive residential segments.
- Asian Manufacturing Concentration:Component sourcing clusters in East Asian production zones create customs clearance bottlenecks and extended lead times for Gulf distributors managing just-in-time project deliveries.
- Solar Thermal Seasonality:Heat collection performance degrades during winter months in northern Middle East territories, limiting year-round displacement of conventional backup systems and extending payback calculations for building owners.
Strategic Opportunities
- Jordanian Solar Irradiance Premium:Elevated year-round thermal collection potential in Jordan supports margin-rich solar water heater deployments for residential and agricultural process heating applications.
- Green Building Financing Linkage:Evolving project finance mandates in the UAE increasingly precondition lending on renewable-ready water heating specifications, creating regulatory tailwinds for solar-integrated system vendors.
- Smart Control Convergence:Integration of IoT-enabled temperature management with traditional tank architectures enables predictive maintenance offerings and recurring revenue streams for equipment suppliers.
Industry Challenges
- Certification Timeline Compression:Emirates Authority for Standardization and Metrology G-Mark conformity assessments for electrical heating appliances require extended laboratory testing cycles that delay product launches.
- Legacy Building Stock Integration:Aging residential towers across Saudi Arabia's established districts present spatial constraints for heat pump outdoor unit placement and solar collector mounting infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East Water Heater Market |
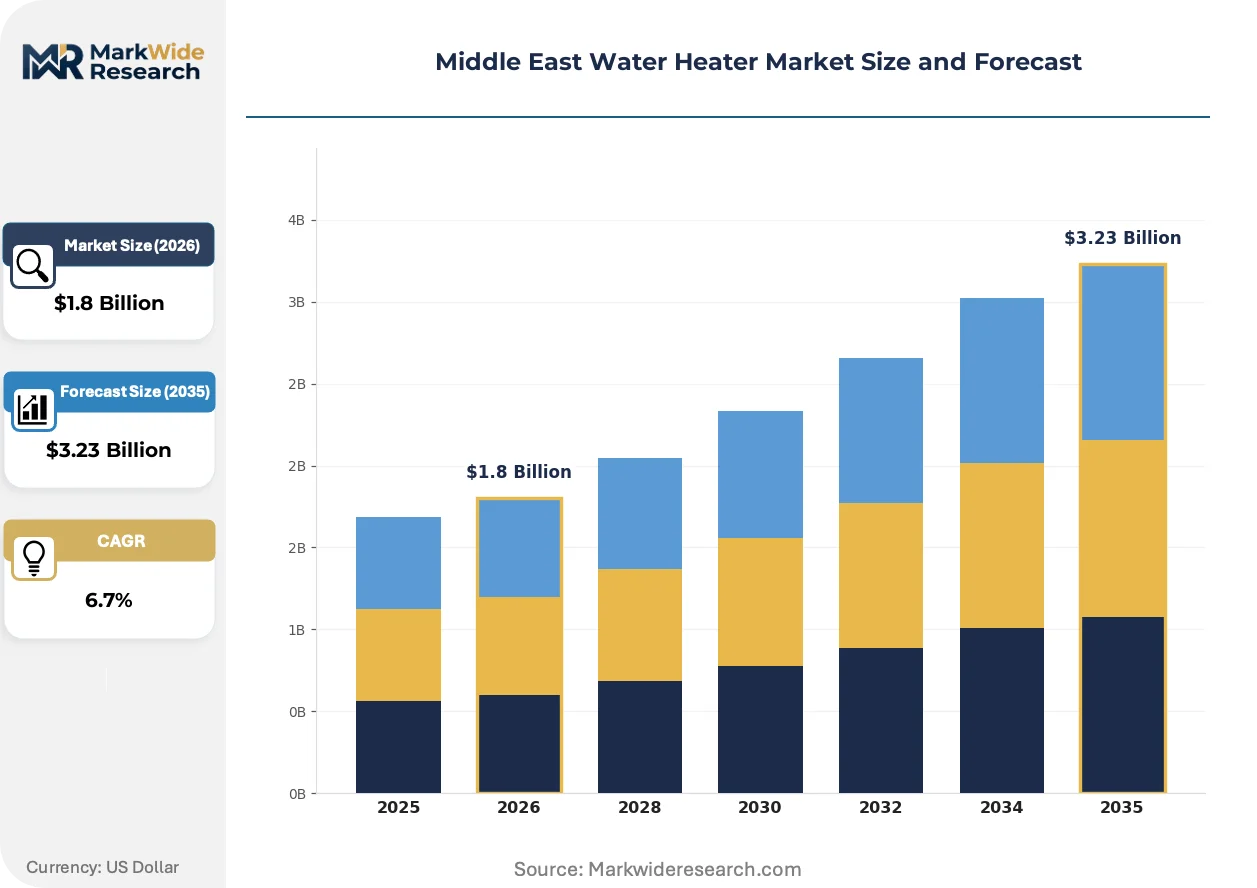
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Storage Water Heaters, Instant Water Heaters, Heat Pump Water Heaters, Solar Water Heaters Application: Residential, Commercial, Industrial, Hospitality Technology: Electric, Gas, Hybrid, Solar End User: Households, Hotels, Offices, Factories |
| Companies Covered | Rheem Manufacturing Company, Bradford White Corporation, A.O. Smith, Whirlpool, Macro International Co., Ariston Holding N.V., Rinnai Corporation, Midea Group, Bosch Thermotechnology Corp., Others |
| Regions Covered | Middle East: Saudi Arabia, UAE, Qatar, Israel, Kuwait, Oman, Bahrain, Iran, Iraq, Rest of Middle East |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East Water Heater Market Emerging Trajectories
Digital control architectures and ambient energy capture systems are restructuring equipment specifications across Middle East construction verticals, compressing the performance gap between conventional combustion and renewable thermal technologies.
Heat pump water heaters utilizing vapor-compression refrigeration cycles are automating temperature modulation through variable-speed compressors and adaptive defrost algorithms. UAE hospitality operators are specifying these systems for LEED-certified properties at accelerating rates. The technology is automating load-balancing between thermal storage and real-time demand, reducing auxiliary heating activation hours by half in pilot installations.
SFDA efficiency disclosure protocols now mandate standardized testing and labeling for commercial water heating equipment entering Saudi customs territories. The regulation compresses market access for uncertified Asian manufacturing sources while elevating procurement transparency for engineering consultants. Large-scale hospital and university projects in Riyadh and Jeddah are now preconditioning vendor selection on verified performance coefficients.
Engineering-procurement-construction firms are consolidating specification authority for major hospitality and healthcare developments across the Gulf Cooperation Council region. Traditional distributor networks face compression as developers direct-source equipment packages through framework agreements with manufacturers. This concentration is most visible in Dubai's hotel construction pipeline, where procurement teams now mandate ten-year service commitments and localized spare parts inventory as contract conditions.
Middle East Water Heater Market Segmentation
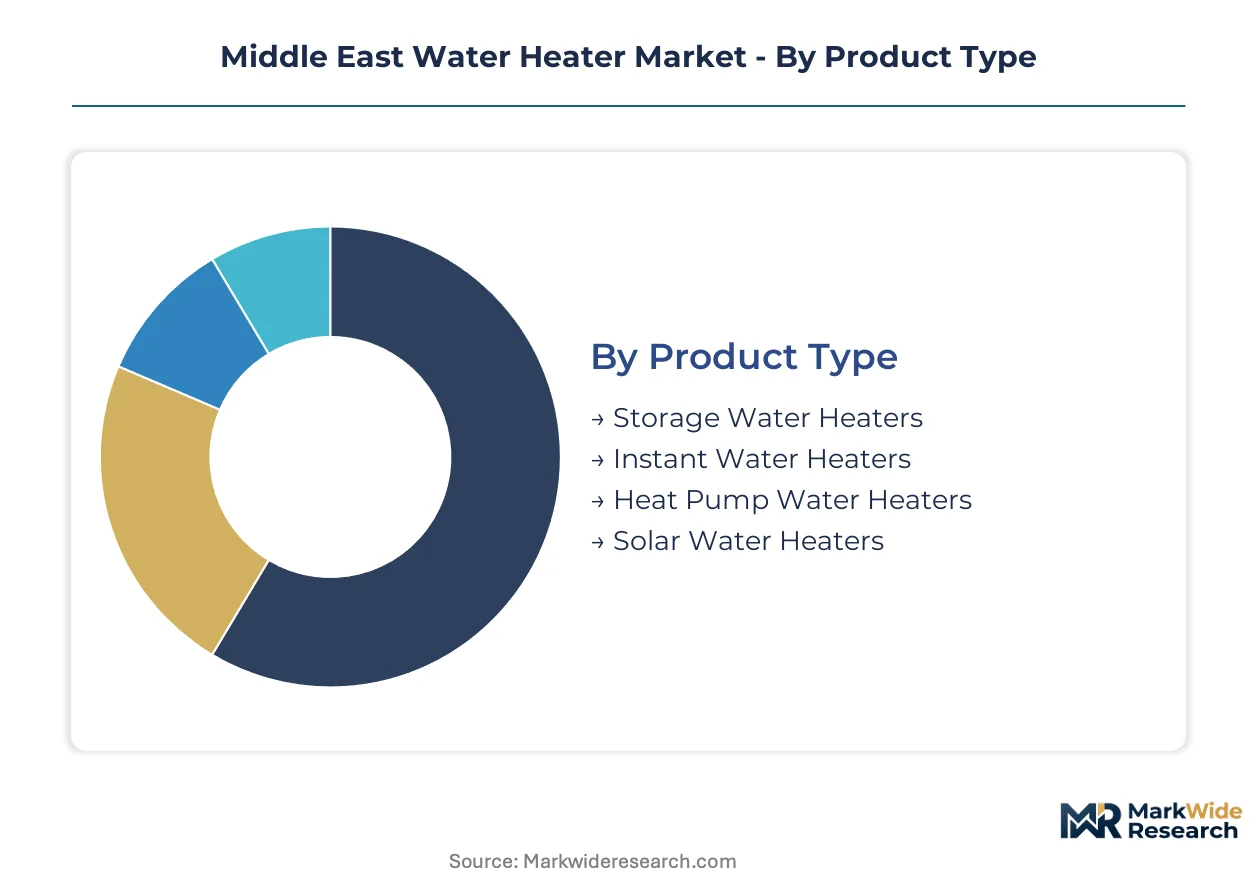
Water heater procurement across the Middle East fragments across thermal technologies, building typologies, and fuel sources. Each segmentation dimension carries distinct margin profiles and regulatory exposure that reshape vendor positioning.
Product Type:
Supply concentration clusters around tank fabrication capacity in Saudi Arabia and the UAE, with component sourcing dependencies determining regional availability patterns.
- Storage Water Heaters:Insulated cylindrical tanks maintain thermal reservoirs between 40 and 150 liters capacity. Aging building stock across Saudi Arabia's established districts sustains replacement demand for these conventional units despite spatial inefficiency.
- Instant Water Heaters:Compact electric resistance or gas-fired modules heat water on demand without storage losses. UAE residential towers specify these systems for space-constrained installations where tank footprint is prohibitive.
- Heat Pump Water Heaters:Vapor-compression cycles extract ambient thermal energy for water heating applications.
- Solar Water Heaters:Flat-plate or evacuated-tube collectors harness irradiance for thermal collection.
Storage water heaters absorb the bulk of installed capacity; heat pump variants are expanding most quickly.
Application:
Cost tier differentiation separates premium hospitality specifications from price-sensitive residential procurement, with engineering-procurement-construction firms consolidating authority for major developments.
- Residential:Individual household installations span electric instant units to solar-thermal systems. Dubai and Abu Dhabi emirates drive volume through active tower construction pipelines.
- Commercial:Office buildings and retail facilities require mid-capacity systems balancing capital constraints against operational reliability.
- Industrial:Process heating applications demand heavy-duty configurations with continuous draw capabilities.
- Hospitality:Hotels prioritize uninterrupted hot water availability over capital minimization. Gulf Cooperation Council hospitality developers specify high-capacity gas-fired and solar-thermal hybrid systems for guest facility reliability requirements.
Residential applications anchor volume shipments; hospitality specifications command premium pricing tiers.
Technology:
Volume concentration favors mature electric and gas combustion systems, though regulatory pressure is restructuring procurement toward renewable-thermal alternatives.
- Electric:Resistance heating elements deliver precise temperature control without combustion emissions. A.O. Smith competes aggressively on instant electric systems for UAE residential towers.
- Gas:Natural gas or LPG combustion provides rapid recovery rates for high-demand environments. Gulf hospitality operators specify gas-fired systems for continuous-draw reliability.
- Hybrid:Dual-source configurations combine conventional heating with renewable thermal inputs.
- Solar:Thermal collectors leverage Jordan's elevated irradiance profiles for year-round operation.
Electric technology dominates unit shipments; solar thermal installations are gaining share fastest.
End User:
Customer type determines specification complexity, with institutional buyers demanding extended service commitments and localized spare parts inventory.
- Households:Individual consumers prioritize upfront cost and installation convenience over lifecycle efficiency. Saudi SFDA efficiency labeling now filters substandard imports from residential procurement channels.
- Hotels:Hospitality operators mandate ten-year service agreements and regional parts stocking. Dubai's hotel construction pipeline directs procurement through manufacturer framework agreements that compress traditional distributor roles.
- Offices:Commercial facilities balance occupant comfort against operational expenditure targets.
- Factories:Industrial process heating requires ruggedized configurations for demanding duty cycles.
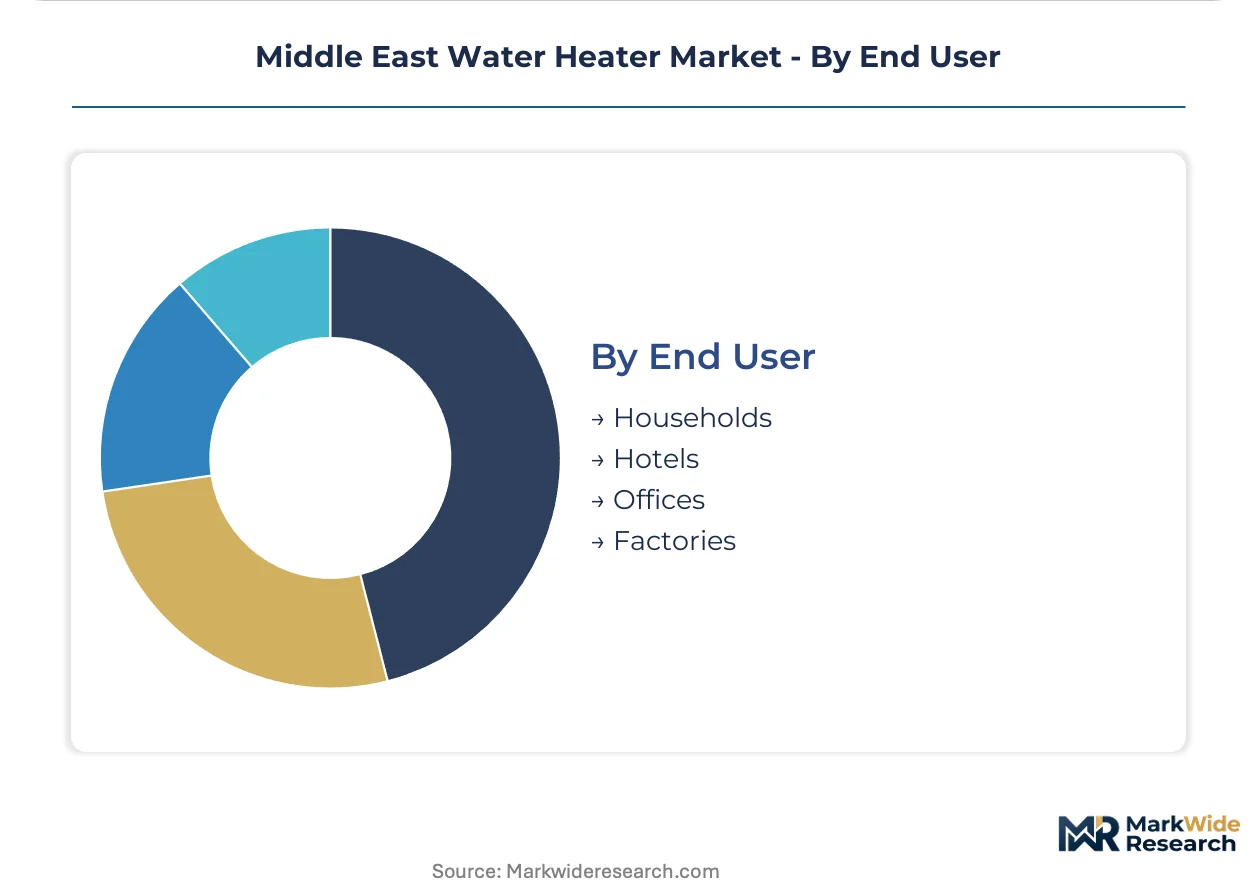
Households represent the largest addressable base; hotel procurement is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Copper and steel fabrication clusters in the Eastern Province of Saudi Arabia anchor regional supply chains for water heater tank manufacturing and component assembly across Gulf markets.
Saudi Arabia
Riyadh's hospital and university construction pipelines absorb high-capacity commercial water heating systems for continuous-draw reliability. The SFDA enforces efficiency disclosure protocols that filter substandard imports from Asian manufacturing zones. Western Region districts present spatial constraints for heat pump outdoor unit placement in aging residential towers.
United Arab Emirates
Dubai and Abu Dhabi emirates drive hospitality procurement through active hotel construction pipelines specifying solar-thermal hybrid configurations. The Emirates Authority for Standardization and Metrology mandates G-Mark conformity assessments that delay product launches for uncertified electrical heating appliances. Al Ain and Northern Emirates sub-regions concentrate residential tower development demanding compact instant water heater installations.
Jordan
Elevated solar irradiance profiles support year-round thermal collection for margin-rich residential and agricultural process heating deployments. The national energy regulator promotes renewable thermal specifications through building code amendments. Amman and Aqaba urban corridors concentrate solar water heater distribution networks serving premium retrofit specifications.
Morocco
Coastal and inland irradiance zones sustain solar thermal collector performance across seasonal variations. The national standards body aligns efficiency labeling with European conformity frameworks. Casablanca and Rabat industrial zones host assembly operations for flat-plate and evacuated-tube collector systems.
Middle East Water Heater Market Vendor Landscape
Global majors compete with regional champions across distribution networks and certification compliance capabilities. The vendor base organizes into three tiers: integrated multinational manufacturers with Gulf distribution infrastructure, specialized commercial-grade fabricators serving hospitality procurement channels, and price-focused electric instant system suppliers targeting residential tower specifications. Dominant competitive moves include framework agreements with engineering-procurement-construction firms that compress traditional distributor roles, and backward integration into tank fabrication capacity to secure margin buffers against commodity metal volatility.
Among North American-based manufacturers, Rheem Manufacturing Company and Bradford White Corporation occupy positions within the integrated multinational tier, anchoring Gulf market presence through established distribution infrastructure. A.O. Smith represents the electric instant system specialization vector, competing aggressively for residential tower specifications in space-constrained UAE developments. These three entities exemplify contrasting strategic archetypes: network-leveraged incumbents, commercial-grade specialists, and technology-focused challengers.
| Leading Market Players |
|---|
| Rheem Manufacturing Company |
| Bradford White Corporation |
| A.O. Smith |
| Whirlpool |
| Macro International Co. |
| Ariston Holding N.V. |
| Rinnai Corporation |
| Midea Group |
| Bosch Thermotechnology Corp. |
| Others |
Supply Flow & Price Mechanics
LEED certification requirements in UAE hospitality developments gate qualified supplier access and premium-tier pricing power for solar-integrated and heat pump water heating systems. This environmental mandate compresses vendor pools to certified manufacturers while elevating procurement budgets for compliant equipment packages.
Pricing Analysis
Warranty bundling separates Gulf market tiers, with ten-year service commitments and localized spare parts inventory commanding 15-25% premiums over unbundled transactional sales. Three-tier pricing structure across premium certified, standard compliant, and economy import levels reflects G-Mark conformity status and SFDA efficiency disclosure compliance. Pricing pressure stems from Asian manufacturing concentration and customs clearance bottlenecks compressing margin buffers for regional distributors. Residential tower developers in Saudi Arabia's Western Region exhibit highest price sensitivity, while Dubai hospitality operators prioritize reliability over capital minimization.
Supply Chain Analysis
Dual-sourcing mandates from engineering-procurement-construction firms now require Gulf distributors to qualify backup manufacturers for critical components. Tank fabrication draws from copper and steel processing clusters in Saudi Arabia's Eastern Province, component assembly in China's Guangdong and Zhejiang provinces, and control system manufacturing in South Korea. Single-source vulnerability concentrates in East Asian electronics and compressor supply. Distribution runs through manufacturer-direct framework agreements with EPC firms that compress traditional distributor roles in major hospitality developments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around certification-compliant manufacturers as SFDA efficiency mandates and G-Mark conformity requirements filter substandard imports and elevate capital barriers for new entrants.
For Market Incumbents: Lock in framework agreements with engineering-procurement-construction firms serving Dubai and Abu Dhabi hospitality pipelines before procurement authority consolidates further. Secure captive tank fabrication capacity in Saudi Arabia's Eastern Province to buffer margin compression from copper and steel input volatility. Prioritize G-Mark pre-certification for heat pump variants to capture LEED-certified retrofit specifications. For New Entrants and Emerging Players: Direct-to-contractor digital platforms bypass compressed distributor networks and reach specification engineers at Saudi hospital and university projects. Target Jordan's solar irradiance premium segment where year-round thermal collection supports margin-rich residential deployments. Lead with IoT-enabled predictive maintenance bundles that create recurring revenue differentiation against transactional competitors. For Investors and Strategic Acquirers: SFDA efficiency mandate expansion to residential equipment categories is the leading indicator that certification-compliant manufacturing assets will command scarcity premiums. Five-to-ten year viability favors vertically integrated tank fabricators with Gulf distribution infrastructure over pure trading operations. Watch for Emirates Authority for Standardization and Metrology timeline compression announcements as inflection signals for laboratory testing bottleneck severity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Tank Fabrication | Saudi Arabia's Eastern Province steel clusters anchor captive supply against commodity volatility. |
| G-Mark Pre-Certification Investment | Emirates Authority for Standardization and Metrology compliance accelerates product launch timelines. |
| Framework Agreement with EPC Firms | Dubai hospitality developers now mandate ten-year service commitments as contract conditions. |
| IoT Control System Development | Smart temperature management enables predictive maintenance recurring revenue streams. |
| Jordan Distribution Network Buildout | Elevated solar irradiance supports margin-rich residential and agricultural process heating. |
Methodological Framework
Document review covered SFDA regulatory filings, Emirates Authority for Standardization and Metrology conformity assessment records, and Gulf hospitality construction pipeline databases, complemented by interviews with procurement directors at engineering-procurement-construction firms, maintenance directors at Saudi hospital systems, and distribution channel managers across UAE emirates. Secondary validation drew from customs import data, Saudi Building Code amendments, and LEED project registries. Bottom-up equipment shipment estimates triangulated against top-down construction spending allocations.
Segmented outputs across product type, application, technology, and end-user dimensions calibrated growth trajectories over the projection horizon. Modeled variables included SFDA efficiency disclosure adoption curves, G-Mark certification timeline distributions, and solar irradiance-adjusted capacity factors for thermal collector performance. CAGRs derived from regression analysis of historical equipment replacement cycles against construction pipeline forecasts and regulatory mandate implementation schedules.
The model holds under stable regulatory enforcement intensity and construction spending continuity; deviation in SFDA mandate expansion timing or copper price volatility spikes would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Appliances
Bhutan and Nepal White Goods Market
Appliances
Mobile Refrigerators Market
Appliances
Personal Care Appliances Market
Appliances
United Kingdom Handheld Vacuum Cleaners Market
Appliances
Mexico Laundry Appliances Market
Appliances
Electric Fan Market
Appliances
Digital Showers Market
Appliances
China Induction Hobs Market
Appliances
Kuwait Dishwasher Market
Appliances
Microwave Market
Appliances
Mini Washing Machine Market
Appliances
GCC Dishwashers Market
Appliances
Asia Pacific Compact Dishwasher Market
Appliances
Smart Massage Appliances Market
Appliances
Dishwasher Market
Appliances
Smart Dishwasher Market