
 Global Massage Chairs Market | 2026-2036
Global Massage Chairs Market Size, Share, and Industry Trends Forecast 2026-2036
Global Massage Chairs Market Outlook
Chinese component manufacturing is shifting toward higher-precision motor assemblies for premium massage chair tiers. Panasonic leverages vertical integration from semiconductor to finished seating to control quality cycles. Family Inada anchors its position through handcrafted upholstery processes in domestic Japanese facilities. OSIM International competes across Southeast Asian retail channels with compact urban-format designs.
A massage chair is an electromechanically actuated seating apparatus employing roller arrays, airbag compression systems, and heated nodes to simulate manual manipulation techniques for muscular relief and circulatory stimulation. Units typically integrate 3D or 4D roller mechanisms traversing SL-track or S-track rail geometries to deliver calibrated pressure across cervical, thoracic, and lumbar zones. Zero Gravity configurations command premium positioning as consumers prioritize spinal decompression functionality alongside standard vibration therapy. Intelligent technology integration represents the fastest-expanding segment, with sensor-driven body scanning and app-controlled custom programs reshaping how residential and commercial buyers evaluate replacement cycles.
FDA Class II medical device oversight applies to therapeutic massage chairs marketed for specific pain management claims in the United States, while CE marking under the EU MDR governs electrical safety and electromagnetic compatibility for European distribution. Japan's METI enforces PSE certification for AC-powered consumer appliances, creating compliance layering for brands with multi-country assembly footprints. Stakeholders must monitor how divergent energy-efficiency standards across Japan, the European Union, and the United States reshape R&D allocation and factory location decisions.
Market Dynamics
Intelligent sensor integration and AI-driven body scanning are compressing replacement cycles across residential and commercial buyer segments, forcing manufacturers to reallocate R&D toward software-defined functionality rather than purely mechanical durability.
Growth Catalysts
- Japan's Preventive Healthcare Spending:Aging urban corridors in Tokyo, Osaka, and Nagoya are channeling household expenditure toward therapeutic seating for home-based pain management. METI's PSE certification framework streamlines domestic distribution while reinforcing quality expectations.
- EU Green Deal Electrification Mandates:Lower-energy electromechanical designs are becoming procurement prerequisites for wellness centers across Germany, France, and the Netherlands. CE marking under the EU MDR accelerates cross-border standardization.
- 3D/4D Roller Mechanism Maturation:Precision motor assemblies from Chinese component suppliers are enabling mid-tier manufacturers to offer SL-track coverage previously confined to premium tiers.
Market Restraints
- Copper and Rare Earth Magnet Volatility:High-torque motor assemblies depend on neodymium and dysprosium supplies concentrated in Chinese processing facilities. Price swings compress margin predictability for electromechanical actuator producers.
- FDA Class II Compliance Friction:Therapeutic claims for pain management trigger medical device oversight in the United States, extending time-to-market by 18-24 months versus general wellness positioning.
- Zero-Gravity Mechanism Patent Thickets:Incumbent holders of recline-angle optimization IP in Japan and South Korea create licensing barriers for new entrants targeting spinal decompression functionality.
Strategic Opportunities
- India's Underpenetrated Urban Households:Metro clusters in Mumbai, Delhi, and Bangalore show rising discretionary spending on home wellness equipment. BIS certification harmonization with IEC standards reduces import friction.
- Corporate Wellness Program Integration:HR procurement teams at technology and financial services firms are adding therapeutic seating to office fit-out specifications. This channel bypasses traditional retail margin structures.
- Sensor-AI Convergence:Biometric feedback loops combining pressure mapping with machine learning enable personalized program generation. This technology pairing creates subscription revenue potential beyond hardware sales.
Industry Challenges
- Electromechanical Technician Scarcity:Servicing 4D roller arrays and heated node networks requires specialized training that vocational programs in Southeast Asian manufacturing hubs have not yet scaled.
- Multi-Jurisdiction Certification Parallelism:Simultaneous FDA, CE marking, and PSE pathways force duplicate testing protocols. Smaller manufacturers lack capital to maintain parallel compliance teams.
- Legacy Furniture Distribution Integration:Traditional sofa and recliner retail channels resist the floor space and demonstration requirements that massage chair sales demand.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Massage Chairs Market |
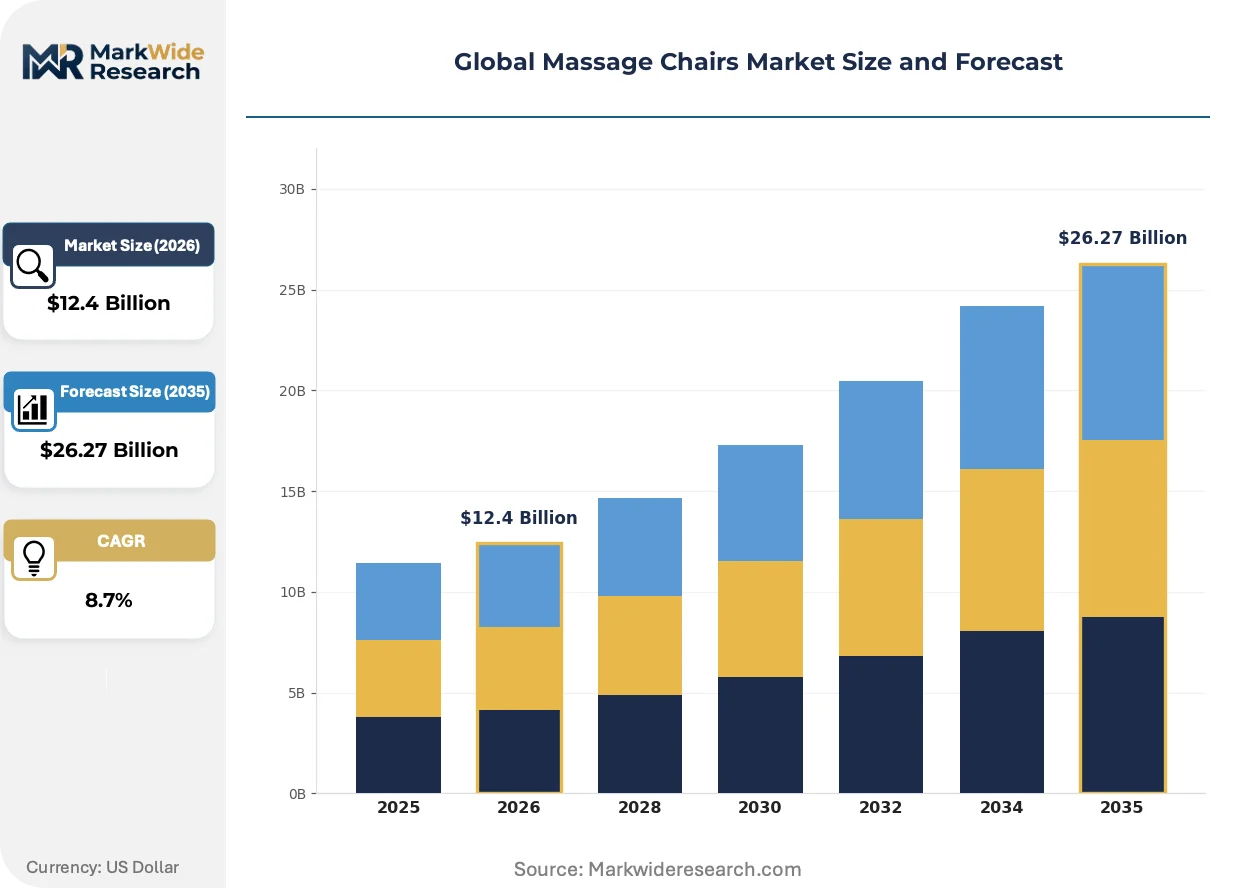
| Market Size in 2026 | $12.4 Billion |
| Market Size in 2035 | $26.27 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Traditional, Zero Gravity, Shiatsu, Recliner End User: Residential, Commercial, Wellness Centers, Rehabilitation Facilities Technology: Electromechanical, Manual, Intelligent, Smart Feature: Heating, Foot Massage, Bluetooth Connectivity, Custom Programs |
| Companies Covered | Panasonic, Family Inada, OSIM International, BODYFRIEND, Human Touch, Luraco, Osaki, Ogawa World USA, Infinity, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Massage Chairs Market Strategic Shifts
Software-defined functionality is overtaking mechanical specifications as the primary purchase determinant, with buyers prioritizing updatable program libraries and biometric personalization over static roller configurations.
Sensor fusion architecture is unifying discrete pressure, temperature, and positional inputs into single-chip processing modules. High-end residential buyers in Japan and South Korea are specifying these integrated systems at replacement rates 40% faster than conventional electromechanical units. This convergence is compressing the competitive advantage of standalone component suppliers and rewarding semiconductor-integrated manufacturers.
REACH substance restrictions and RoHS recast directives are banning specific flame retardants and phthalates from upholstery foams and synthetic leathers. European manufacturers are reformulating supply chains toward bio-based alternatives, with German and Italian upholstery specialists investing in pilot production lines. Wellness center procurement in France and the Netherlands now requires full material disclosure documentation.
Subscription-based program libraries are displacing one-time firmware purchases among millennial and Generation Z buyers. Direct-to-consumer channels in the United States and Australia are bundling annual content access with hardware financing, eroding traditional retail markups. This pattern concentrates in metropolitan markets where apartment dwellers prioritize space-efficient multifunction seating over dedicated massage room installations.
Global Massage Chairs Market Segmentation
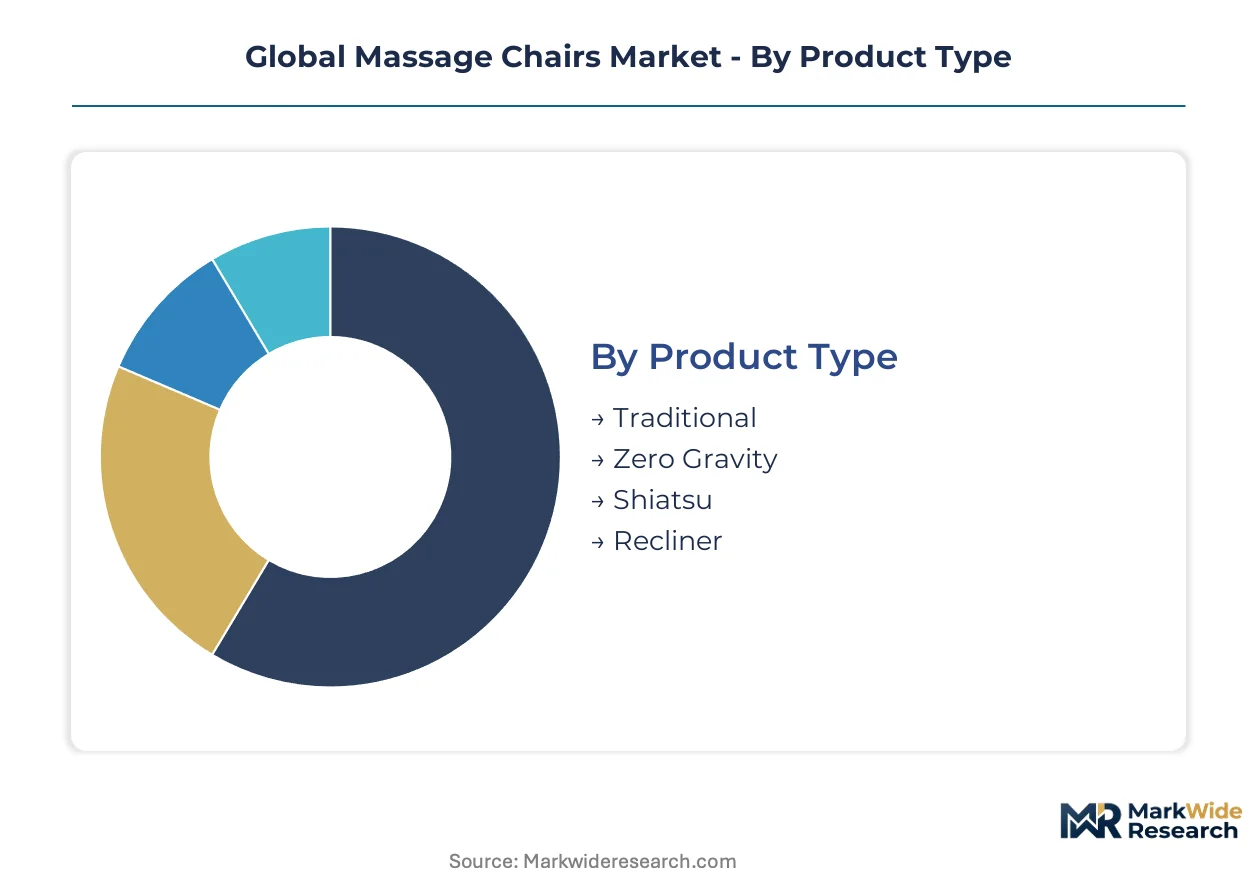
Massage chair procurement decisions split across therapeutic positioning, installation environment, and intelligence integration. Certification requirements vary sharply by segment, with FDA Class II oversight attaching to clinical claims while wellness-oriented positioning faces lighter compliance burdens.
Product Type:
FDA Class II medical device designation applies to units marketed for specific pain management indications, while general wellness positioning escapes this burden. CE marking under EU MDR governs electrical safety across all configurations.
- Zero Gravity:Recline-angle optimization distributes body weight to reduce spinal compression. Demand concentrates in Japanese urban households where preventive healthcare spending supports premium positioning. METI PSE certification streamlines domestic distribution.
- Shiatsu:Roller arrays simulate finger-pressure techniques along meridian lines. Wellness centers across Germany and France specify these units for post-therapy recovery protocols. EU Green Deal electrification mandates favor lower-energy electromechanical designs.
- Traditional:Fixed-position vibration and roller mechanisms serve entry-level residential buyers.
- Recliner:Hybrid furniture-massage positioning targets space-constrained urban apartments.
Zero Gravity sits at the top of the volume ranking, with Shiatsu climbing the fastest.
End User:
Cost tier stratification separates institutional procurement with dedicated maintenance budgets from residential buyers prioritizing upfront affordability.
- Wellness Centers:High-utilization environments demand commercial-grade durability and rapid technician response. Procurement in the Netherlands and France now requires full REACH substance disclosure for upholstery materials.
- Residential:Replacement cycles compress as sensor-AI convergence enables personalized program generation. Metro clusters in Tokyo, Osaka, and Nagoya channel household expenditure toward therapeutic seating.
- Commercial:Corporate wellness programs at technology and financial services firms add therapeutic seating to office fit-out specifications.
- Rehabilitation Facilities:Clinical positioning triggers FDA Class II oversight in the United States, extending time-to-market.
Residential commands the largest installed base, with Wellness Centers expanding most quickly.
Technology:
Supply concentration for precision motor assemblies shapes which technology tiers achieve cost competitiveness.
- Intelligent:Sensor-driven body scanning and machine learning program generation define the premium tier. Biometric feedback loops enable subscription revenue models beyond hardware sales.
- Electromechanical:3D and 4D roller mechanisms traversing SL-track geometries deliver calibrated pressure across cervical, thoracic, and lumbar zones. Chinese component suppliers enable mid-tier manufacturers to offer coverage previously confined to premium tiers.
- Smart:App-controlled custom programs and updatable firmware libraries target millennial and Generation Z buyers in direct-to-consumer channels.
- Manual:Basic mechanical actuation serves price-sensitive segments with minimal regulatory exposure.
Electromechanical holds the dominant share, with Intelligent gaining share fastest.
Feature:
Margin differentiation attaches to software-defined functionality versus static mechanical specifications.
- Custom Programs:Subscription-based content libraries displace one-time firmware purchases. Direct-to-consumer bundling in the United States and Australia erodes traditional retail markups.
- Heating:Thermal nodes enhance muscular relief and circulatory stimulation. Integration with sensor fusion architecture enables temperature adjustment based on real-time biometric feedback.
- Foot Massage:Dedicated lower-extremity actuation arrays serve reflexology protocols in Asian markets.
- Bluetooth Connectivity:Audio integration and mobile app pairing standardize across mid-tier and premium configurations.
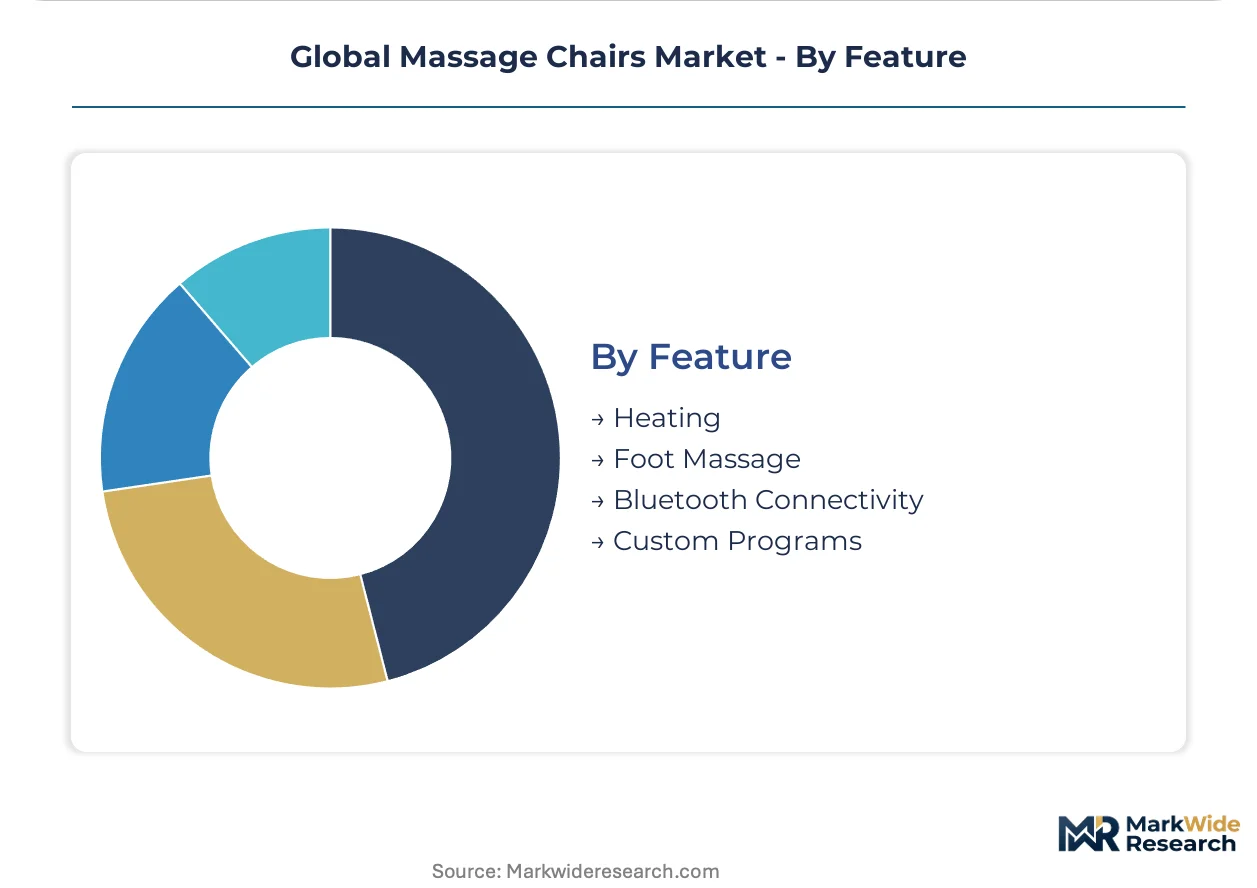
Heating remains the most specified feature, with Custom Programs showing the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japan channels household expenditure toward preventive therapeutic seating while Germany's wellness centers enforce stricter material disclosure standards. The United States maintains medical device oversight for clinical claims. China supplies precision motor assemblies that enable mid-tier feature parity.
Japan
Aging urban corridors in Tokyo, Osaka, and Nagoya drive residential procurement of therapeutic seating for home-based pain management. METI's PSE certification framework streamlines domestic distribution while reinforcing quality expectations. Family Inada anchors handcrafted upholstery processes in domestic facilities serving premium-tier demand.
United States
Wellness centers and corporate HR procurement teams expand therapeutic equipment budgets across technology and financial services firms. FDA Class II medical device oversight applies to units marketed for specific pain management claims, extending time-to-market. Miami and Los Angeles metro clusters concentrate direct-to-consumer channel development for compact urban-format designs.
Germany
Wellness centers across Bavaria and North Rhine-Westphalia prioritize lower-energy electromechanical designs under EU Green Deal mandates. CE marking under the EU MDR governs electrical safety and electromagnetic compatibility. Stuttgart-based upholstery specialists invest in bio-based alternative pilot production lines responding to REACH substance restrictions.
China
Component manufacturing clusters in Guangdong and Zhejiang provinces shift toward higher-precision motor assemblies for premium massage chair tiers. MIIT standards and GB certification frameworks regulate AC-powered consumer appliance safety. Shenzhen and Dongguan facilities supply neodymium-dependent actuator systems to mid-tier manufacturers globally.
South Korea
Metro clusters in Seoul and Busan specify sensor fusion architecture at replacement rates exceeding conventional electromechanical units. MFDS oversight applies to therapeutic claims in clinical distribution channels. Incheon-based manufacturers hold recline-angle optimization IP creating licensing barriers for spinal decompression functionality entrants.
Global Massage Chairs Market Competitive Environment
Japanese producers anchor premium-tier craftsmanship; Chinese fabricators hold component-scale supply. The vendor base splits between vertically integrated electronics conglomerates and specialized seating manufacturers. Three archetypes dominate: semiconductor-to-finished-goods integrators, handcrafted upholstery specialists, and compact-format urban designers. Capacity expansion and technology licensing represent the dominant competitive vectors.
Among Japanese electronics conglomerates, Panasonic exemplifies backward integration from semiconductor production through finished seating assembly. Family Inada occupies a position representing handcrafted domestic manufacturing archetypes. OSIM International sits within the compact urban-format specialist tier competing across Southeast Asian retail channels. These three anchors illustrate how geographic origin and production philosophy stratify competitive positioning rather than scale alone.
| Leading Market Players |
|---|
| Panasonic |
| Family Inada |
| OSIM International |
| BODYFRIEND |
| Human Touch |
| Luraco |
| Osaki |
| Ogawa World USA |
| Infinity |
| Others |
Value Chain & Pricing Dynamics
Wellness center procurement teams in Germany and France concentrate demand for lower-energy electromechanical designs, anchoring contract-based long-term offtake arrangements that stabilize price floors for premium-tier manufacturers while compressing margins for undifferentiated mid-tier suppliers.
Pricing Analysis
Capacity additions in Chinese component manufacturing clusters are reshaping price floors for 3D and 4D roller mechanisms. Three-tier pricing structure across premium, standard, and economy levels separates FDA Class II-certified clinical units from wellness-positioned configurations and basic vibration models. Cost compression in the standard tier is intensifying because Guangdong-based motor assembly suppliers are achieving feature parity with legacy Japanese producers. Residential buyers in Tokyo and Osaka show least price sensitivity for sensor-AI convergence, while entry-level apartment dwellers in Southeast Asian metros drive volume at thin margins.
Supply Chain Analysis
Neodymium and dysprosium supply rests on Chinese rare earth processing facilities concentrated in Inner Mongolia and Jiangxi province. Precision motor assemblies draw from Guangdong and Zhejiang manufacturing clusters, while handcrafted upholstery feeds from domestic Japanese ateliers. Single-source vulnerability in rare earth magnet supply creates exposure to export quota fluctuations. Distribution runs through wellness center procurement channels in Europe, direct-to-consumer platforms in the United States, and traditional furniture retail in Japan.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Massage Chairs Market compounds steadily as aging demographics across Japan, Germany, and the United States convert preventive healthcare expenditure into durable therapeutic equipment procurement.
For Market Incumbents: Anticipate margin compression from Chinese component suppliers achieving 4D roller parity by securing exclusive sensor-AI licensing agreements with Seoul-based semiconductor designers and reinforcing METI PSE certification moats against lower-cost entrants. Backward integration into precision motor assembly captive supply protects quality cycles while CE marking investment streamlines EU Green Deal compliance. For New Entrants and Emerging Players: Launch via corporate wellness program direct sales to bypass traditional furniture retail channel resistance, targeting underpenetrated technology and financial services firms in Mumbai and Bangalore. India's BIS certification harmonization with IEC standards reduces import friction for compact urban-format designs. White-space concentration sits in subscription-based program libraries for millennial apartment dwellers. For Investors and Strategic Acquirers: Electronics conglomerates seeking wellness portfolio expansion are the most active acquirer in this space, prioritizing semiconductor-integrated manufacturers over pure-play seating producers. Five-to-ten year viability hinges on software-defined functionality displacement of mechanical specifications. Watch sensor fusion architecture patent filings as inflection signal for replacement cycle acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Sensor-AI Platform Integration | Biometric feedback loops from Seoul and Tokyo metro buyers enable recurring subscription revenue beyond hardware. |
| EU Green Deal Manufacturing Transition | Stuttgart upholstery specialists investing in bio-based alternatives secure wellness center procurement in France and Netherlands. |
| Direct-to-Consumer Channel Launch | Miami and Los Angeles metro clusters concentrate compact urban-format distribution bypassing retail markups. |
| Backward Integration into Motor Assembly | Panasonic's captive semiconductor-to-finished-goods pipeline controls quality cycles against Guangdong suppliers. |
| FDA Class II Certification Pathway | Clinical positioning for pain management claims extends time-to-market but locks out wellness-only competitors. |
Study Parameters
Direct dialogue with massage chair manufacturing executives, wellness center procurement directors, electromechanical component suppliers, and METI certification consultants grounded qualitative insights in operational reality. Secondary validation drew from FDA 510(k) filings, CE marking databases under EU MDR, Japanese PSE registration records, and customs trade data for neodymium-dependent actuator systems. Bottom-up unit shipment estimates triangulated against top-down household expenditure surveys across Tokyo, Osaka, and Nagoya corridors.
Segmentation outputs across product type, end user, technology tier, and feature configuration fed into analytical framework spanning the projection horizon. CAGRs derived from replacement cycle compression rates, sensor-AI adoption curves, and preventive healthcare spending elasticity by age cohort. Forecast inputs incorporated EU Green Deal electrification mandates, REACH substance restriction timelines, and rare earth magnet price volatility bands.
Forecast precision tightens around the base case; tail outcomes carry wider variance under sudden rare earth export restrictions or accelerated FDA Class II enforcement. Assumptions reflect current regulatory trajectories and demographic spending patterns. A small set of named triggers—neodymium supply disruption, BIS certification acceleration in India, corporate wellness mandate expansion—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Appliances
Germany Compact Dishwasher Market
Appliances
Bahrain Dishwashers Market
Appliances
Saudi Arabia Microwave Ovens Market
Appliances
Global Vended Laundry Equipment Market
Appliances
Domestic Food Preparation Appliances Market
Appliances
Garments Steamer Market
Appliances
APAC White Goods Market
Appliances
Oman Dishwashers Market
Appliances
Saudi Arabia Water Heater Market
Appliances
UK Residential Vacuum Cleaner Market
Appliances
Laundry Appliances Market
Appliances
Saudi Arabia Electric Water Heater Market
Appliances
Industrial Gas Stove Market
Appliances
Digital Showers Market
Appliances
Mexico Laundry Appliances Market
Appliances
North America Compact Dishwasher Market