
 Saudi Arabia Water Heater Market | 2026-2036
Saudi Arabia Water Heater Market Size, Share, and Industry Trends Forecast 2026-2036
Saudi Arabia Water Heater Market Analysis
SASO's updated energy-efficiency mandates is decoupling market access from legacy product portfolios, forcing manufacturers to redesign thermal insulation and control systems. Saudi Ceramics leverages its domestic manufacturing footprint to sustain price competitiveness against imports. Rheem Manufacturing Company anchors its position through specialized high-capacity commercial units for hospitality chains. A. O. Smith Corp. differentiates via advanced corrosion-resistant tank linings suited to the Kingdom's harsh water chemistry.
A water heater is a thermodynamic appliance that raises water temperature through electric resistance elements, gas combustion, solar thermal collectors, or heat pump refrigeration cycles, typically achieving set points between 49°C and 60°C for sanitary and process applications. The device serves residential hygiene, commercial food service, and industrial wash-down operations across Saudi Arabia's climate-stressed built environment. Electric water heaters occupy the largest installed base due to grid accessibility in urban corridors, though solar water heaters are gaining fastest as SASO rebates and Vision 2030 sustainability targets redirect specification decisions. The 30-100 liter capacity band dominates residential replacement cycles, while above-300 liter systems command premium margins in industrial and hospitality deployments where continuous draw requirements justify higher capital outlays.
SFDA product safety registrations, SASO energy-performance labeling, and the Saudi Building Code thermal efficiency provisions collectively determine which manufacturers qualify for government and institutional procurement channels. Compliance with these frameworks now requires third-party testing at accredited laboratories within the Kingdom, extending lead times for new market entrants. Stakeholders must monitor forthcoming revisions to the Saudi Energy Efficiency Center's minimum performance standards, as these will likely eliminate sub-80% efficiency factor products from eligibility and compress margins for brands lacking R&D adaptation capacity.
Market Dynamics
SFDA energy-efficiency labeling mandates and SASO thermal performance standards are forcing manufacturers to redesign thermal insulation and control systems, decoupling market access from legacy product portfolios across Saudi Arabia's climate-stressed built environment.
Growth Catalysts
- Vision 2030 Housing Initiatives:Bulk procurement contracts for residential villa developments in Riyadh's expanding suburbs are accelerating unit installations and creating sustained demand pipelines for water heater suppliers.
- SASO Rebate Programs:Financial incentives for solar thermal collector systems are redirecting specification decisions away from conventional electric resistance models toward renewable alternatives.
- Central Region Construction:Jeddah's hospitality sector expansion and commercial food service growth are driving continuous-draw requirements for above-300 liter capacity systems.
Market Restraints
- Third-Party Testing Requirements:SFDA product safety registrations now mandate accredited laboratory validation within the Kingdom, extending lead times for new market entrants and compressing margin flexibility.
- Corrosion-Resistant Material Costs:The Kingdom's harsh water chemistry necessitates specialized tank linings and alloys, elevating input costs relative to standard galvanized steel configurations.
- Grid Infrastructure Constraints:Rural corridors outside urban electrified zones limit electric water heater penetration, capping addressable market expansion in peripheral regions.
Strategic Opportunities
- Heat Pump Refrigeration Convergence:Integration of heat pump cycles with solar thermal collectors offers efficiency factor improvements that exceed standalone system performance, creating premium positioning for technology-agnostic suppliers.
- Western Region Underpenetration:Taif and Tabuk provinces exhibit lower installed-base density relative to Riyadh and Jeddah, presenting first-mover advantages for distribution network expansion.
- Saudi Energy Efficiency Center Revisions:Forthcoming minimum performance standards eliminating sub-80% efficiency factor products will clear marginal competitors and consolidate market share among R&D-capable manufacturers.
Industry Challenges
- Certification Timeline Compression:SASO thermal performance standard updates require rapid product recertification, straining quality assurance bandwidth and accelerating obsolescence of existing inventory.
- Retrofit Integration Complexity:Legacy tank installations in established Riyadh residential compounds resist replacement with smart control systems, limiting premium feature penetration in the replacement cycle segment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Saudi Arabia Water Heater Market |
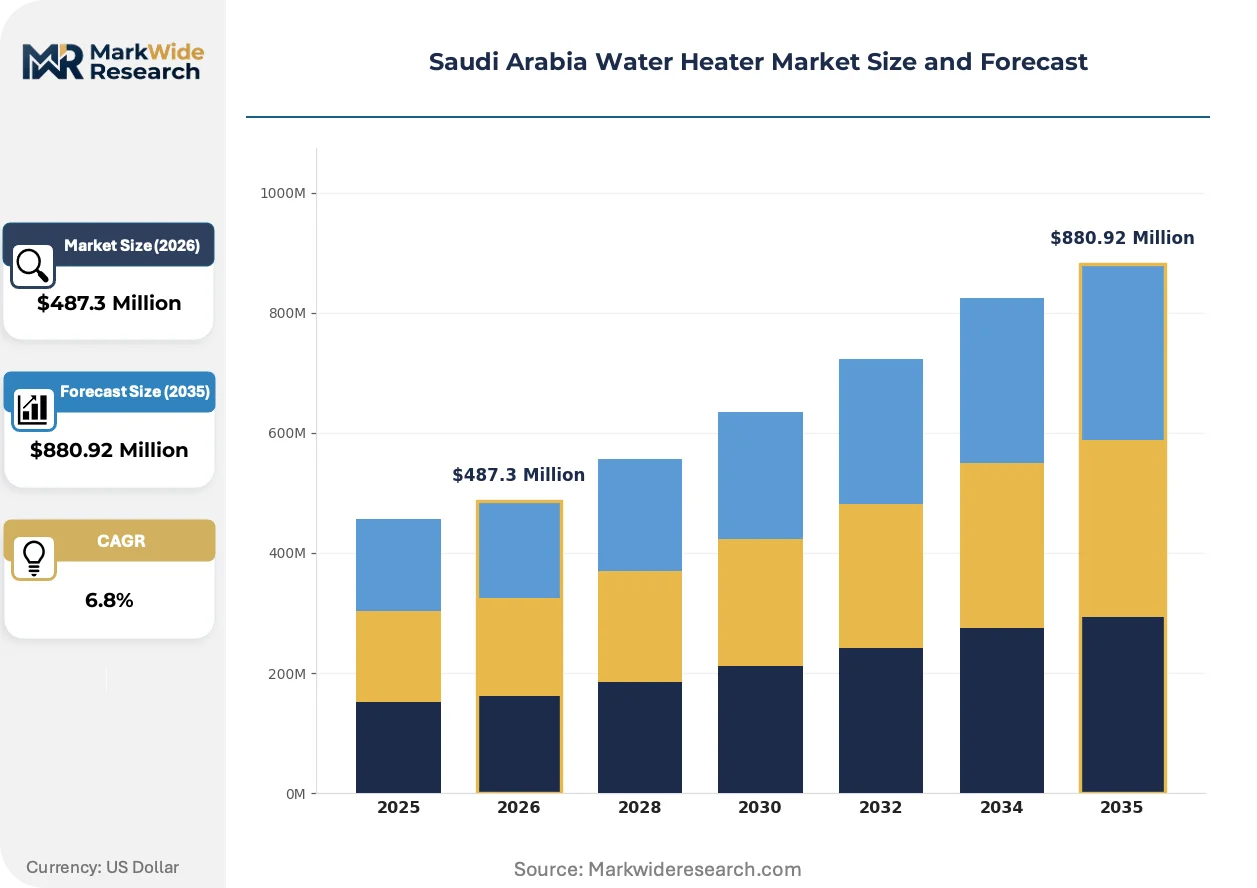
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $880.92 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electric Water Heaters, Gas Water Heaters, Solar Water Heaters, Heat Pump Water Heaters End User: Residential, Commercial, Industrial, Hospitality Capacity: Under 30 Liters, 30-100 Liters, 100-300 Liters, Above 300 Liters Installation Type: Indoor, Outdoor, Wall-mounted, Floor-standing |
| Companies Covered | Saudi Ceramics, Orbital Horizon, Rheem Manufacturing Company, Whirlpool Corporation, Al Huraiz, Ariston Thermo Group, Bosch Thermotechnology, Haier, A. O. Smith Corp., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Saudi Arabia Water Heater Market Emerging Trajectories
Intelligent control systems and corrosion-resistant materials are redefining product differentiation in Saudi Arabia's water heater market, while regulatory pressure accelerates efficiency threshold escalation.
Smart thermostat integration with building management systems is automating temperature modulation based on occupancy patterns and time-of-use electricity pricing. Hospitality chains in Jeddah's coastal corridor are adopting these networked controls fastest, prioritizing operational cost reduction over upfront capital outlays. This automation is compressing margins for manufacturers lacking IoT development capabilities while creating service revenue streams for control-system specialists.
SASO's updated energy-performance labeling framework now requires real-world thermal loss testing rather than laboratory-only certification. Industrial laundries and food processing facilities face the steepest compliance burden, as their high-duty-cycle operations fall under enhanced scrutiny. Above-300 liter commercial systems are responding with vacuum insulation panel integration to maintain eligibility for government and institutional procurement channels.
Specification decisions in Riyadh's master-planned communities are rotating toward bundled appliance procurement through developer-direct channels. Bulk purchasing agreements for entire villa inventories are displacing traditional retail showroom selection, compressing distributor influence and elevating price transparency. This concentration is most visible in Diriyah Gate and Red Sea Project developments, where EPC contractors negotiate system-wide thermal equipment packages.
Saudi Arabia Water Heater Market Segmentation
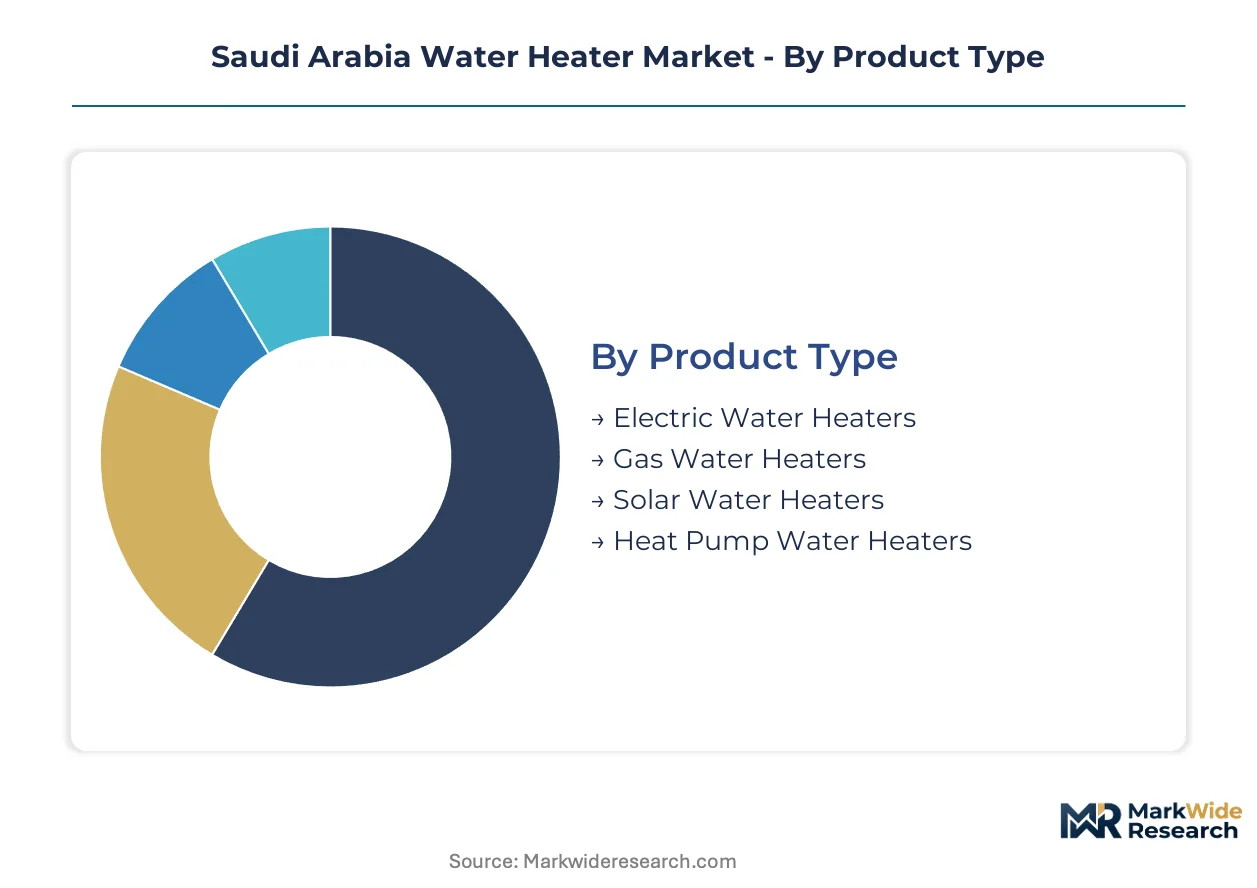
Water heater procurement in Saudi Arabia fragments across four distinct specification axes. Each segmentation dimension carries unique regulatory weight and margin implications for suppliers navigating SASO certification requirements and Vision 2030 construction pipelines.
Product Type:
Technology differentiation determines compliance burden and rebate eligibility under SFDA energy-efficiency frameworks.
- Electric Water Heaters:Resistance-element systems dominate Riyadh and Jeddah urban corridors where grid infrastructure is densest. Residential villa developments in Diriyah Gate specify these units for standardized bulk procurement, though operating costs face pressure from time-of-use electricity pricing reforms.
- Solar Water Heaters:Evacuated-tube and flat-plate collector systems capture SASO rebate incentives tied to Vision 2030 sustainability targets. Western Region hospitality projects along the Red Sea coast are adopting these fastest, prioritizing operational cost reduction over higher capital outlays.
- Gas Water Heaters:Combustion-based instantaneous and storage systems serve areas with piped natural gas distribution, primarily older Riyadh districts and industrial zones.
- Heat Pump Water Heaters:Refrigeration-cycle systems extract ambient thermal energy, achieving efficiency factors that exceed standalone electric or solar configurations in high-duty-cycle commercial applications.
Electric systems lead on installed-base scale; solar configurations lead on policy-driven momentum.
End User:
Demand concentration varies sharply across customer types, with procurement channels and specification authority residing at different organizational levels.
- Residential:Villa construction across Riyadh's expanding suburbs generates continuous replacement and new-installation demand. Master-planned communities negotiate developer-direct bulk contracts, displacing traditional retail showroom selection.
- Commercial:Food service, retail, and office facilities require 100-300 liter capacity systems with networked controls for operational cost management.
- Hospitality:Jeddah's coastal hotel chains and Red Sea Project resorts specify above-300 liter continuous-draw systems with corrosion-resistant tank linings suited to the Kingdom's harsh water chemistry.
- Industrial:Laundries and processing facilities face enhanced SASO scrutiny for high-duty-cycle thermal loss performance, driving vacuum insulation panel integration.
Residential commands volume concentration; hospitality delivers premium margin capture.
Capacity:
Volume segmentation directly correlates with application intensity and capital expenditure thresholds across the Kingdom's built environment.
- 30-100 Liters:Standard residential villa specifications dominate replacement cycles in established Riyadh compounds. These units face retrofit integration complexity when smart control upgrades are attempted in legacy installations.
- Above 300 Liters:Industrial laundries, food processing facilities, and hospitality chains require continuous-draw performance that justifies elevated capital outlays and specialized corrosion-resistant materials.
- Under 30 Liters:Compact point-of-use systems serve auxiliary applications in commercial kitchens and remote facility outbuildings.
- 100-300 Liters:Mid-range commercial and large residential villas occupy this band, balancing capacity requirements with space constraints in dense urban construction.
The 30-100 liter band anchors replacement revenue; above-300 liter systems anchor margin expansion.
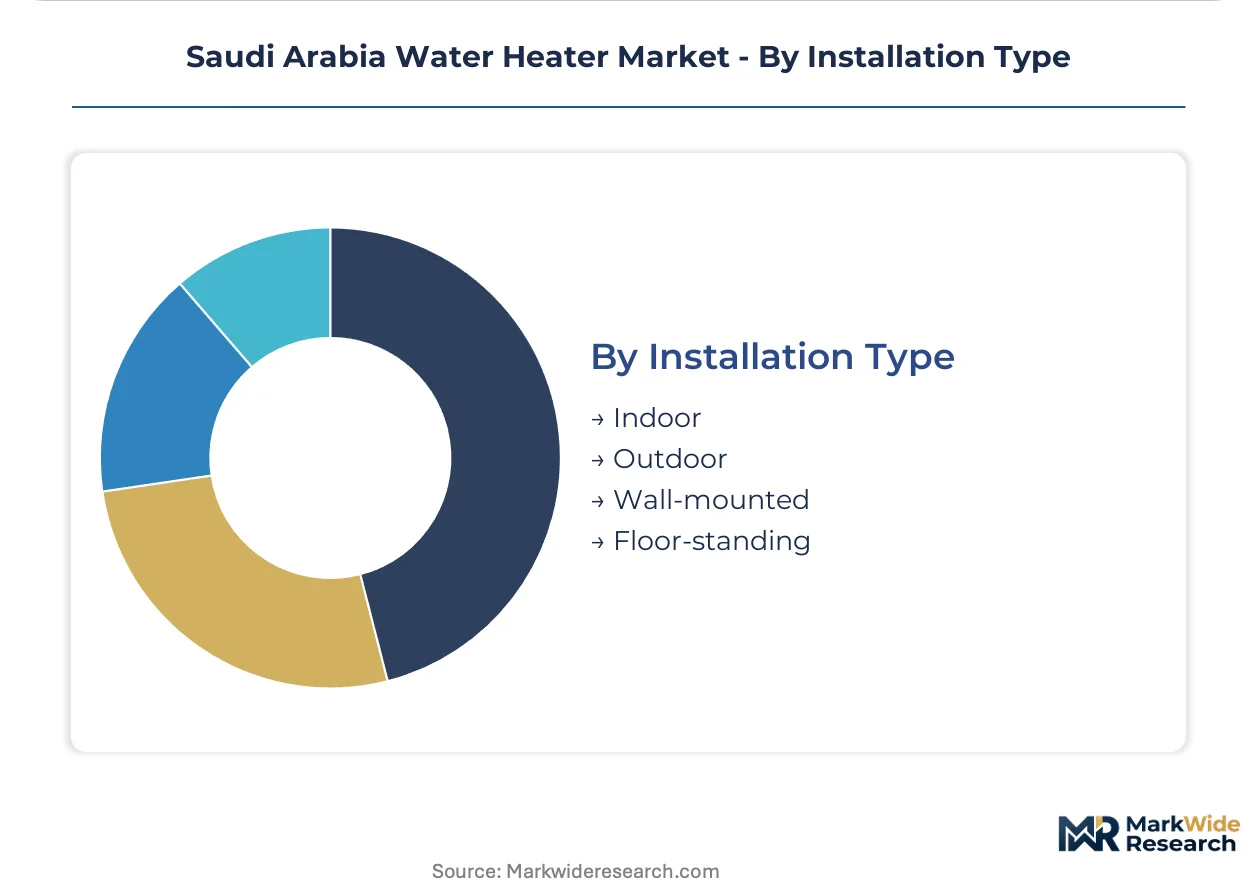
Installation Type:
Mounting configuration and environmental exposure determine material specifications and distribution channel requirements.
- Indoor:Climate-controlled installations in Riyadh residential compounds and commercial facilities prioritize compact footprints and aesthetic integration with building systems.
- Outdoor:Exposed installations in peripheral regions and industrial zones require enhanced weatherproofing and thermal insulation to maintain efficiency factors under ambient temperature swings.
- Wall-mounted:Space-optimized configurations dominate urban villa construction where floor area carries premium valuation in master-planned communities.
- Floor-standing:Large-capacity commercial and industrial systems utilize this configuration for stability and service access in mechanical rooms and utility structures.
Indoor installations dominate unit volume; outdoor specifications are gaining share in decentralized industrial development.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Skilled construction labor pools in Riyadh and Jeddah anchor installation capacity for water heater deployment across Saudi Arabia's built environment. Regional demand fragments across four distinct economic zones, each shaped by distinct regulatory frameworks and infrastructure maturity.
Riyadh
Master-planned villa communities in Diriyah Gate and expanding northern suburbs generate bulk procurement contracts for 30-100 liter residential systems. SFDA product safety registrations mandate accredited laboratory testing within the Kingdom, extending fulfillment timelines for suppliers serving this corridor. Developer-direct purchasing agreements for entire housing inventories are displacing traditional retail showroom channels across the metropolitan area.
Eastern Province
Industrial laundries and food processing facilities in Dammam and Al Khobar drive continuous-draw demand for above-300 liter capacity systems. SASO thermal performance standards impose enhanced scrutiny on high-duty-cycle commercial operations, accelerating vacuum insulation panel adoption. The Jubail Industrial City cluster concentrates procurement authority among petrochemical and manufacturing facility operators with centralized maintenance budgets.
Western Region
Jeddah's hospitality sector expansion and Red Sea Project resort developments specify corrosion-resistant tank linings suited to coastal water chemistry. SASO rebate programs for solar thermal collectors redirect specification decisions away from conventional electric resistance models. Taif and Tabuk provinces exhibit lower installed-base density, presenting distribution network expansion opportunities for first-mover suppliers.
NEOM Northwest
The linear city development and Oxagon industrial zone prioritize heat pump refrigeration cycles integrated with renewable energy infrastructure. Saudi Energy Efficiency Center minimum performance standards eliminate sub-80% efficiency factor products from eligibility for government-backed projects. Trojena and Sindalah island hospitality clusters negotiate system-wide thermal equipment packages through EPC contractor channels.
Saudi Arabia Water Heater Market Vendor Landscape
The competitive structure tilts toward domestic manufacturing specialists with established SFDA certification pathways. Market access concentrates among players with accredited laboratory relationships and rapid product recertification capabilities. Three archetypes dominate: local fabricators leveraging proximity advantages, multinational appliance conglomerates with diversified thermal portfolios, and corrosion-resistant material specialists addressing the Kingdom's harsh water chemistry. Consolidation pressure intensifies through developer-direct bulk purchasing agreements and bundled EPC procurement packages.
Within the domestic specialist tier, Saudi Ceramics exemplifies manufacturing footprint advantages against import-dependent competitors. Among multinational thermal equipment providers, Rheem Manufacturing Company and A. O. Smith Corp. occupy positions shaped by commercial-scale system capabilities and tank lining specialization respectively. Bosch Thermotechnology represents European engineering standards within the premium specification segment. These anchors illustrate how regulatory compliance velocity and material science differentiation determine procurement eligibility in centralized buying channels.
| Leading Market Players |
|---|
| Saudi Ceramics |
| Orbital Horizon |
| Rheem Manufacturing Company |
| Whirlpool Corporation |
| Al Huraiz |
| Ariston Thermo Group |
| Bosch Thermotechnology |
| Haier |
| A. O. Smith Corp. |
| Others |
Supply Flow & Price Mechanics
Skilled thermal insulation technicians in Riyadh's manufacturing corridor anchor production cost structures, compressing labor-cost differentials between domestic fabricators and import-dependent competitors while widening pricing-tier spreads across certification-grade segments.
Pricing Analysis
Bundled EPC procurement packages for master-planned communities separate transaction structures from unbundled retail showroom sales. Three-tier pricing structure across premium, standard, and economy levels stratifies by SASO energy-efficiency certification grade and corrosion-resistant material specifications. Price differentiation hinges on developer-direct volume scale versus individual replacement-cycle purchases. Hospitality chains in Jeddah demonstrate lowest price sensitivity due to operational cost priorities, while peripheral region residential buyers exhibit highest elasticity.
Supply Chain Analysis
Workforce availability for specialized welding and vacuum insulation panel fabrication concentrates in Saudi Arabia's Central Region and select manufacturing zones across China and South Korea. Raw material dependencies span copper heating elements, magnesium anode rods, and epoxy-based corrosion-resistant coatings. Single-source vulnerability for accredited laboratory testing within the Kingdom creates fulfillment bottlenecks for new market entrants. Distribution runs through developer-direct channels for bulk procurement and specialized HVAC contractors for replacement-cycle installations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a late-cycle quality story as specification decisions rotate toward premium heat pump and solar-thermal systems with efficiency factors exceeding standalone electric configurations.
For Market Incumbents: Hedge against certification-timeline compression by accelerating in-house production of corrosion-resistant tank linings and securing captive supply relationships with Kingdom-accredited testing laboratories. SFDA product safety registration backlogs threaten inventory obsolescence for brands lacking rapid recertification bandwidth. SASO thermal performance standard updates are forcing margin pressure on sub-80% efficiency factor product lines. For New Entrants and Emerging Players: Heat pump refrigeration convergence with solar thermal collectors offers a technology-first wedge into NEOM Northwest government-backed projects where Saudi Energy Efficiency Center standards eliminate legacy product eligibility. Taif and Tabuk distribution network gaps present the most penetrable geographic white space. Developer-direct bulk procurement channels in Riyadh's northern suburbs offer the clearest go-to-market angle for volume scale. For Investors and Strategic Acquirers: EPC contractors with bundled appliance procurement capabilities are the most active acquirer in this space, consolidating thermal equipment specification authority across Vision 2030 housing initiatives. Long-term viability favors manufacturers with backward integration into corrosion-resistant materials and rapid R&D adaptation capacity. Monitor forthcoming Saudi Energy Efficiency Center minimum performance standard revisions for inflection signals on marginal competitor elimination.| Strategic Initiative | Industry Significance |
|---|---|
| Accredited Laboratory Partnership | SFDA certification velocity determines procurement eligibility in government-backed developments. |
| Corrosion-Resistant Material Integration | Kingdom water chemistry necessitates specialized tank linings for hospitality and industrial segments. |
| Heat Pump-Solar Hybrid Development | NEOM efficiency standards prioritize refrigeration-cycle systems with renewable energy integration. |
| Developer-Direct Channel Expansion | Master-planned community bulk contracts displace traditional retail showroom influence. |
| Vacuum Insulation Panel Adoption | SASO thermal loss testing mandates drive above-300 liter commercial system upgrades. |
Methodological Framework
Direct dialogue with EPC procurement managers, HVAC contractor operations heads, Saudi Ceramics manufacturing executives, and SFDA regulatory affairs specialists combined with secondary validation from SASO technical bulletins, Saudi Building Code provisions, customs import records, and Vision 2030 project development databases. Bottom-up installation volume estimates triangulated against top-down construction pipeline valuations.
Bottom-up modeling segmented by product type, end user, capacity band, and installation configuration across the projection horizon. CAGRs derived from regression analysis of historical installation patterns against construction permit trajectories and regulatory phase-in schedules. Forecast inputs incorporated SFDA certification timeline data and SASO rebate program uptake rates.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to Saudi Energy Efficiency Center standard revisions and grid infrastructure expansion in peripheral regions. Practitioners should monitor developer-direct procurement contract awards and accredited laboratory capacity expansion for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Appliances
Under Counter Dishwasher Market
Appliances
Middle East Portable Washing Machines Market
Appliances
Global Electric Water Heaters Market
Appliances
Europe Tumble Dryers Market
Appliances
North America Compact Dishwasher Market
Appliances
Electric Iron Market
Appliances
North America Personal Care Appliances Market
Appliances
UAE Gas Hobs Market
Appliances
Middle East and Africa Commercial Dishwashers Market
Appliances
Hair Removal Appliances Market
Appliances
Asia Pacific Water Heater Market
Appliances
Smart Connected Washing Machine Market
Appliances
North America Tumble Dryers Market
Appliances
Electric Dryers Market
Appliances
Japan Laundry Appliances Market
Appliances
Sanitary Towel Machine Market