
 North America Tankless Water Heater Market | 2026-2036
North America Tankless Water Heater Market Size, Share, and Industry Trends Forecast 2026-2036
North America Tankless Water Heater Market Insights
The EPA ENERGY STAR Most Efficient program is restructuring buyer specifications across North America, compelling specifiers to prioritize units with uniform energy factors above 0.90. A.O. Smith leverages its vertically integrated manufacturing footprint across Tennessee and South Carolina to control component costs. Rinnai Corporation dominates the gas-fired segment through extensive distribution partnerships with regional plumbing wholesalers. Navien Inc. differentiates via condensing heat exchanger technology that extracts latent heat from exhaust gases.
North America tankless water heaters are instantaneous heating appliances that activate flow sensors to ignite burners or energize heating elements when hot water demand begins, typically achieving 0.82 to 0.98 uniform energy factor ratings depending on condensing architecture. These units serve residential, commercial, and industrial end users seeking to eliminate standby thermal losses inherent in conventional storage tanks. Gas-fired product types anchor current revenue pools due to higher flow rates and lower operating costs in regions with accessible natural gas infrastructure. Electric variants are gaining specification share in multifamily hospitality projects where venting constraints prohibit combustion equipment. Wall-mounted installation types concentrate margin pools by reducing mechanical room footprints and enabling retrofit applications in dense urban housing stock.
The DOE maintains federal minimum efficiency standards under 10 CFR Part 430, while NRCan enforces parallel regulations through Canada's Energy Efficiency Regulations that align with NAECA amendments. CSA Group and UL standards govern venting safety and electrical certification, creating compliance thresholds that filter out smaller import competitors. Stakeholders must monitor state-level electrification mandates in California, New York, and Washington that are beginning to restrict new natural gas connections in residential construction.
Market Dynamics
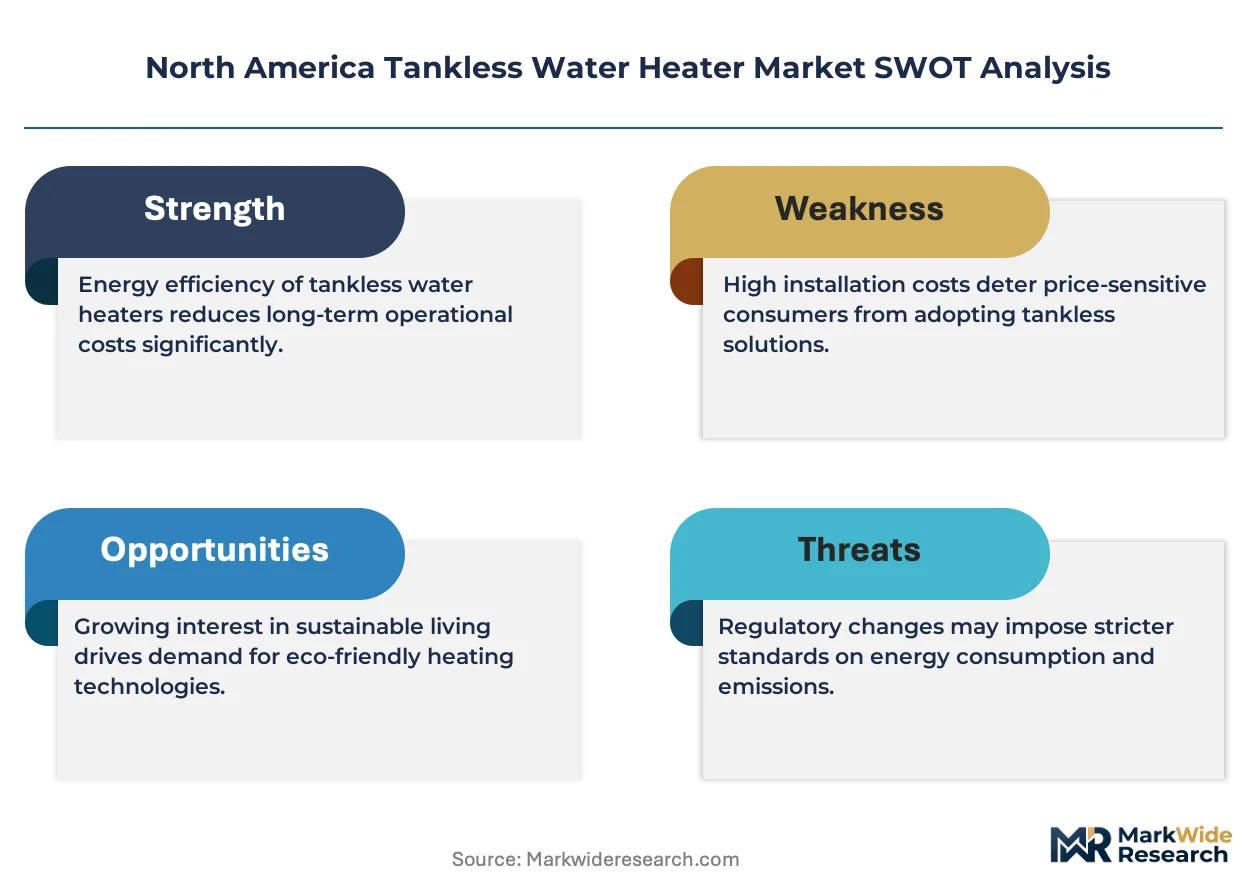
DOE appliance efficiency standards under 10 CFR Part 430 are compressing the competitive field by mandating uniform energy factors above 0.90, forcing manufacturers to abandon non-condensing architectures and absorb higher stainless steel heat exchanger costs.
Growth Catalysts
- EPA ENERGY STAR Most Efficient program:This specification tier is restructuring builder procurement across Texas and California, compelling residential developers to specify condensing tankless units to meet stricter energy codes.
- Warmer inlet water temperatures:Southern United States geographies deliver superior unit performance and shortened payback periods, concentrating demand in Sun Belt metropolitan construction markets.
- Natural gas infrastructure accessibility:Existing pipeline networks in suburban developments enable gas-fired specifications with higher flow rates, anchoring revenue pools in new residential construction corridors.
Market Restraints
- Copper and stainless steel input volatility:Heat exchanger material costs fluctuate with commodity markets, compressing margins on condensing architectures that require corrosion-resistant alloys.
- Certification timeline friction:CSA Group and UL venting safety standards create multi-month approval cycles that filter out smaller import competitors lacking capital for testing protocols.
- Electric resistance substitution:Heat pump water heaters are capturing specification share in moderate-climate zones where ambient air temperatures support coefficient of performance advantages.
Strategic Opportunities
- Multifamily hospitality electrification:Venting constraints in dense urban housing stock across New York and Washington are opening specification pathways for electric variants in high-rise retrofit applications.
- State-level electrification mandates:California's restrictions on new natural gas connections are creating captive demand for electric tankless and heat pump alternatives in residential construction.
- Smart home convergence:Integration with Wi-Fi-enabled energy management systems and utility demand-response programs is enabling premium pricing for connected tankless units.
Industry Challenges
- Condensing technology skill gap:Installation of secondary heat exchangers and condensate drainage systems requires specialized plumbing expertise that remains scarce in rural service territories.
- Legacy electrical panel upgrades:Electric tankless units demanding 100+ amp service create retrofit friction in older housing stock with 100-amp main breaker limitations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Tankless Water Heater Market |
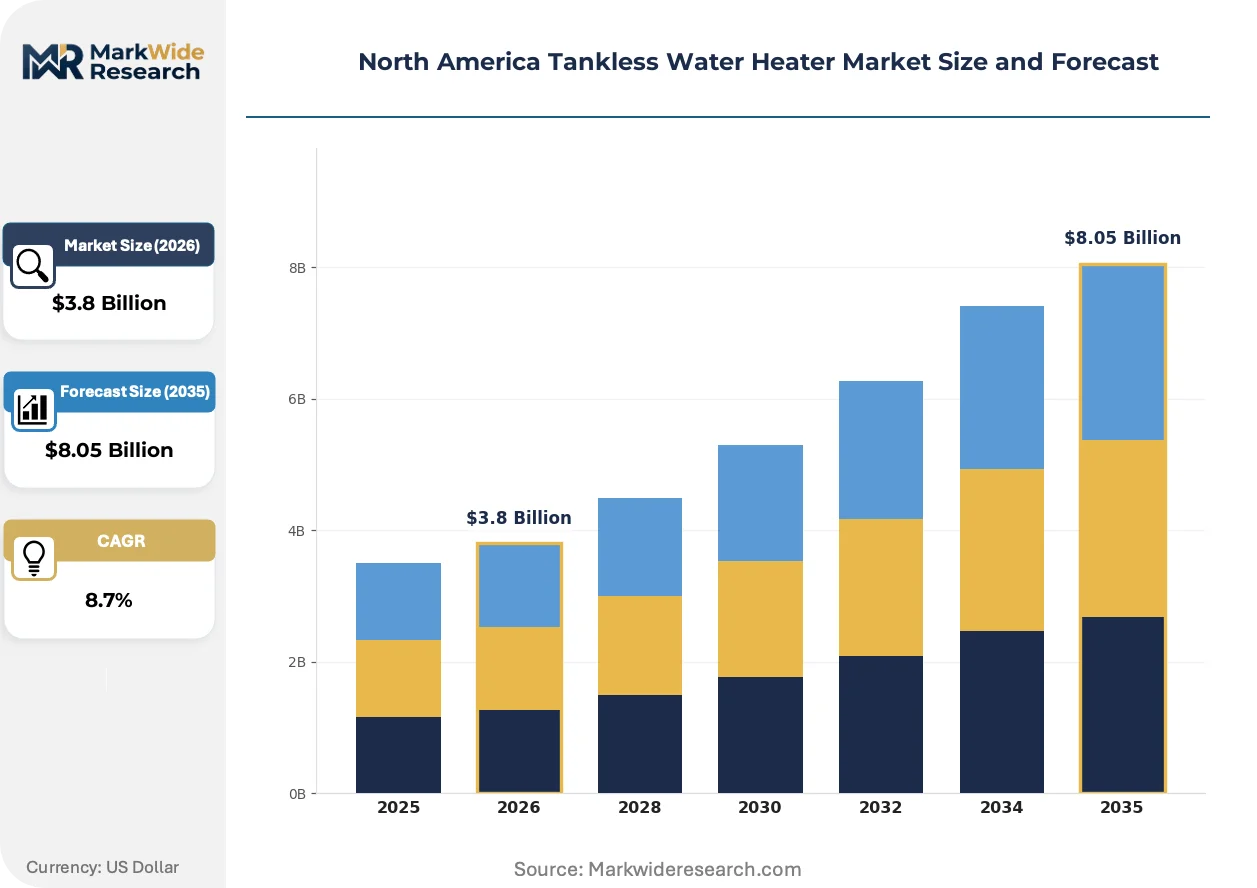
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gas, Electric, Solar, Hybrid End User: Residential, Commercial, Industrial, Hospitality Installation Type: Wall-Mounted, Floor-Mounted, Point-of-Use, Centralized Energy Source: Natural Gas, Propane, Electricity, Renewable Energy |
| Companies Covered | A.O. Smith, Noritz America, Navien Inc., Stiebel Eltron Inc., Robert Bosch LLC, Rinnai Corporation, Bradford White Corporation, General Electric, Rheem Manufacturing Company, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Tankless Water Heater Market Trends and Innovations
Flow-activated ignition systems and modulating burner controls are compressing the performance gap between entry-level and premium tankless architectures. Manufacturers are embedding diagnostic capabilities that reduce service call frequency and compress warranty cost reserves.
Condensing heat exchanger technology is automating latent heat recovery from exhaust gases, enabling uniform energy factor ratings approaching 0.98. Residential builders in California and Texas are specifying these units to satisfy Title 24 energy codes and local green building programs. The technology is automating compliance with progressively stricter federal minimums while extending product replacement cycles.
NRCan is enforcing Canada's Energy Efficiency Regulations in parallel with NAECA amendments, creating harmonized North American compliance thresholds. Manufacturers serving cross-border distribution channels must certify to both DOE and NRCan protocols, consolidating testing investment toward unified heat exchanger architectures. The Canadian market is responding with specification shifts toward condensing gas-fired units that satisfy both regulatory regimes.
Plumbing wholesalers are unbundling after-sales service from equipment procurement, shifting risk to third-party service aggregators. Regional distributors across the southern United States are piloting subscription maintenance models that cover descaling and burner inspection. This pattern is most visible in Texas metropolitan markets where hard water accelerates scale accumulation and drives recurring revenue attachment.
North America Tankless Water Heater Market Segmentation
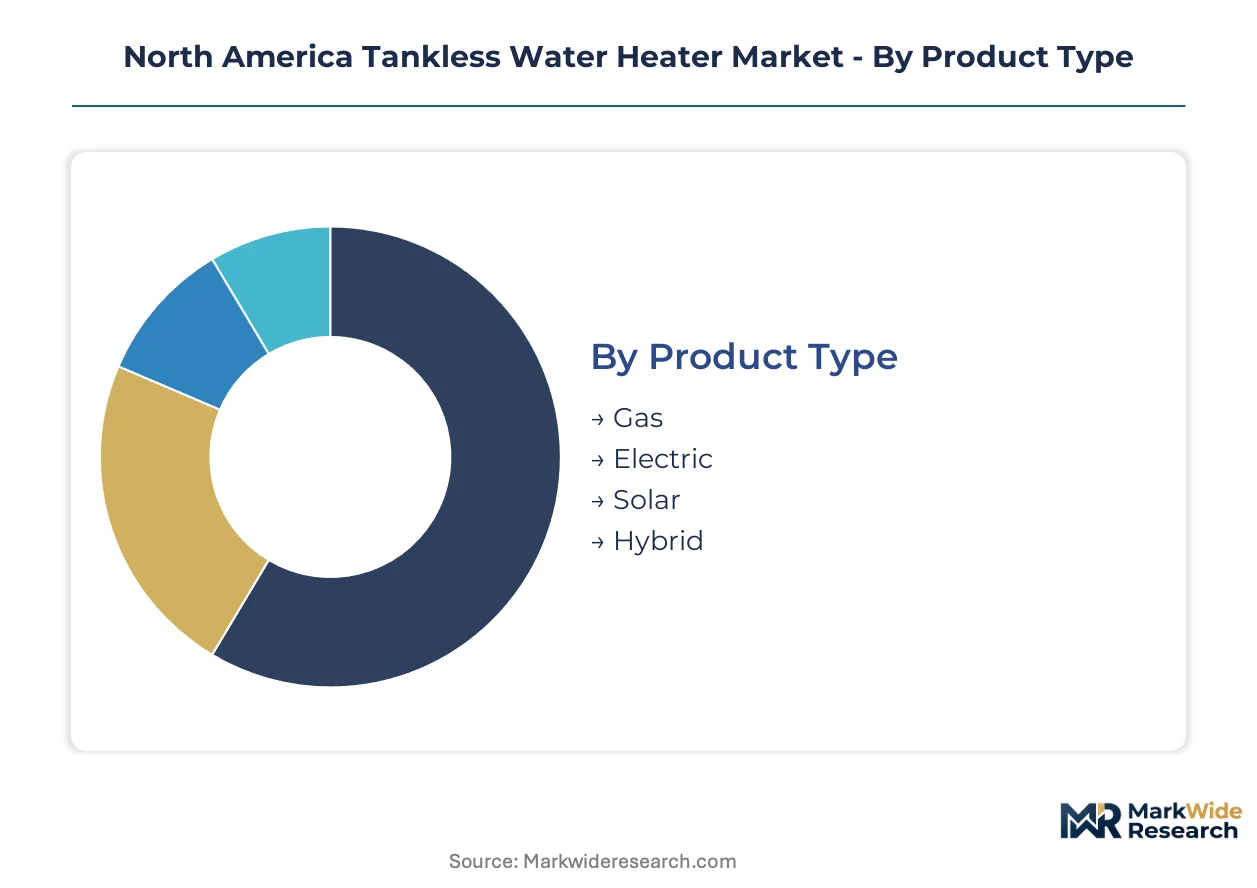
Segmentation in the North America tankless water heater market reveals how technology specifications, installation constraints, and energy infrastructure shape procurement decisions across residential construction corridors and commercial retrofit projects.
Product Type:
Combustion technology and heating element architecture define performance ceilings and regulatory compliance pathways across the region.
- Gas:Higher flow rates and lower operating costs dominate suburban developments with accessible natural gas infrastructure. Texas and California residential builders specify condensing gas units to satisfy Title 24 energy codes and DOE uniform energy factor mandates above 0.90.
- Electric:Resistance heating elements eliminate venting requirements, enabling installation in multifamily hospitality projects across New York and Washington where combustion equipment faces space constraints. California electrification mandates are accelerating specification shifts toward high-amperage electric variants.
- Solar:Thermal collector integration supplements heating capacity in southwestern United States markets with high solar irradiance.
- Hybrid:Heat pump-tankless combinations extract ambient thermal energy to reduce electrical load in moderate-climate zones.
Mature deployment sits with Gas. Newer deployment is concentrated in Electric.
End User:
Scale of hot water demand and duty cycle intensity separate margin profiles across customer categories.
- Residential:Single-family and multifamily installations prioritize compact footprints and standby loss elimination. Southern United States metropolitan construction markets concentrate volume due to warmer inlet water temperatures shortening payback calculations.
- Commercial:Restaurants, laundromats, and small retail require continuous flow capacity driving specification toward high-BTU gas-fired architectures. Installation concentrates in Sun Belt suburban corridors with available natural gas lateral connections.
- Industrial:Process hot water applications demand heavy-duty heat exchanger materials and redundant unit configurations.
- Hospitality:Hotels and extended-stay properties balance peak demand coverage with space constraints in dense urban cores, expanding specification share for electric variants in high-rise retrofits.
Volume leadership belongs to Residential. Steepest expansion trajectory is occurring in Hospitality.
Installation Type:
Physical mounting configuration and distribution architecture determine labor cost structures and retrofit feasibility.
- Wall-Mounted:Vertical installation reduces mechanical room footprints and enables replacement of conventional storage tanks in existing utility closets. Dense urban housing stock across northeastern United States and Canadian metropolitan markets drives specification for this configuration.
- Floor-Mounted:Ground-level placement accommodates heavier condensing units with secondary heat exchangers and integrated condensate management in suburban new construction.
- Point-of-Use:Proximity installation under sinks or near fixtures eliminates distribution losses in large-footprint commercial buildings.
- Centralized:Whole-building systems with recirculation loops serve multifamily properties and small commercial campuses.
Retrofit applications favor Wall-Mounted. New construction is standardizing on Floor-Mounted for condensing gas architectures.
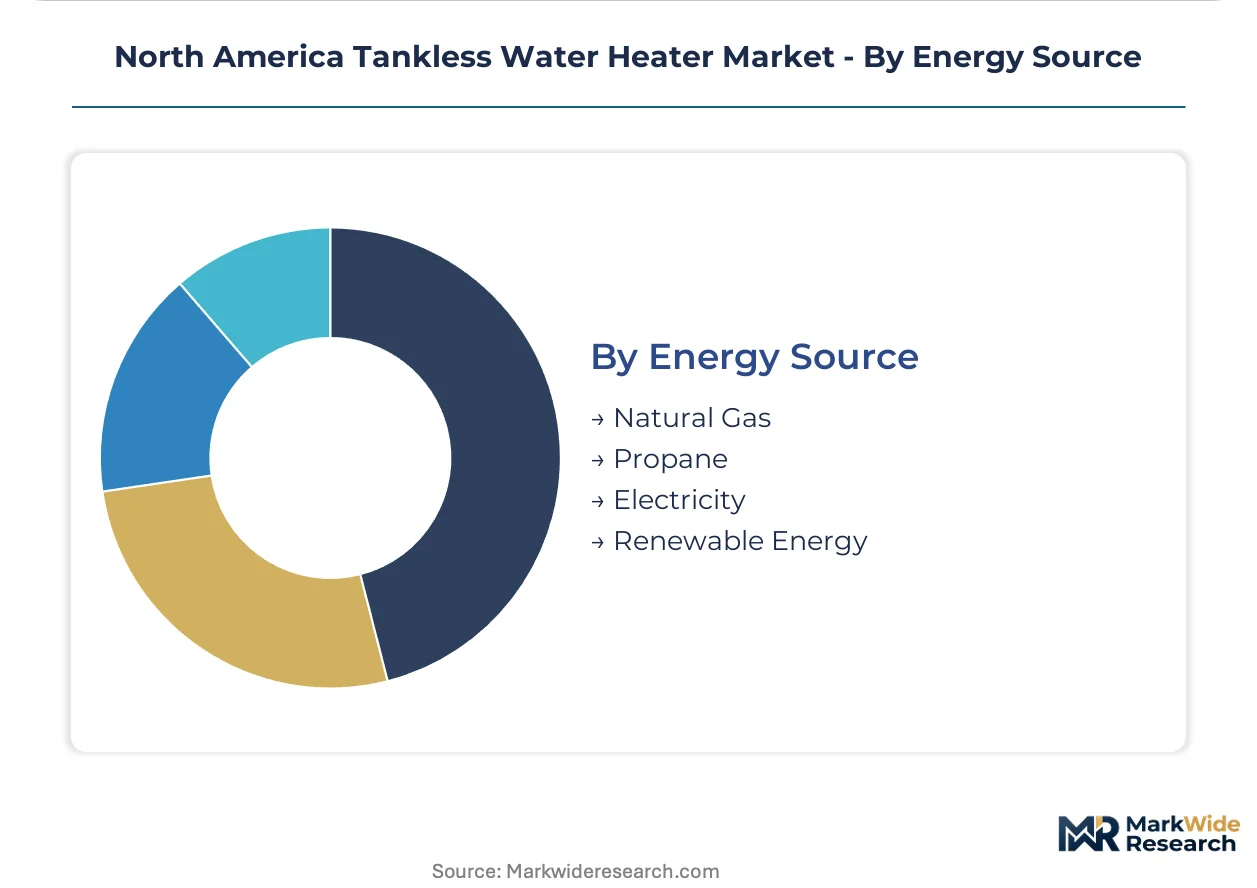
Energy Source:
Fuel availability and carbon intensity regulations are restructuring specification patterns across state and provincial jurisdictions.
- Natural Gas:Pipeline infrastructure anchors current revenue pools in suburban development corridors across Texas, Arizona, and Florida where utilities maintain extensive distribution networks.
- Propane:Tank-fed combustion serves rural and exurban properties beyond natural gas mains, concentrating in mountainous western United States regions and Canadian prairie provinces.
- Electricity:Grid-connected resistance and heat pump variants gain share in jurisdictions restricting new fossil fuel connections. California's building code amendments and New York City Local Law 97 are accelerating this shift.
- Renewable Energy:Solar thermal and photovoltaic-to-resistance configurations serve off-grid installations and net-zero building programs.
Established infrastructure supports Natural Gas. Policy-driven transition is elevating Electricity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Dallas-Fort Worth metroplex anchors North American tankless water heater demand through rapid single-family construction and accessible natural gas infrastructure. Southern metropolitan corridors concentrate procurement volume where warmer inlet water temperatures compress payback periods. State-level electrification mandates are restructuring specification patterns across the continent.
United States
Texas and California residential builders specify condensing gas units to satisfy Title 24 energy codes and DOE uniform energy factor mandates above 0.90. The EPA ENERGY STAR Most Efficient program is restructuring procurement across Sun Belt metropolitan construction markets. Southern states including Florida and Arizona concentrate volume due to superior unit performance in warm-climate conditions.
Canada
Ontario and Quebec multifamily developers are shifting specification toward electric variants as NRCan enforces Energy Efficiency Regulations aligned with NAECA amendments. The harmonized North American compliance threshold is consolidating testing investment toward unified heat exchanger architectures. Vancouver and Toronto metropolitan markets drive high-rise retrofit applications where venting constraints favor wall-mounted electric configurations.
Mexico
Nuevo León and the Bajío Region industrial corridors are expanding commercial hospitality installations as manufacturing investment accelerates workforce housing construction. The country's national energy efficiency regulator is developing appliance standards that reference DOE 10 CFR Part 430 frameworks. Mexico City metropolitan area demand concentrates in premium residential developments seeking standby loss elimination.
Southwest United States
Arizona and New Mexico desert climates deliver optimal condensing unit performance with minimal winterization requirements. California's building code amendments restricting new natural gas connections are creating spillover specification shifts into neighboring jurisdictions. Phoenix and Las Vegas construction markets standardize on floor-mounted condensing architectures for suburban new development.
Northeast United States
New York and Massachusetts state-level electrification mandates are accelerating electric tankless specification in dense urban housing stock. Local Law 97 and parallel Boston building performance standards prohibit new fossil fuel connections in residential construction. New York City high-rise retrofits favor point-of-use and wall-mounted electric configurations to circumvent venting constraints.
North America Tankless Water Heater Market Competitive Landscape
The competitive structure tilts toward vertically integrated manufacturers with captive heat exchanger production and established distribution partnerships with regional plumbing wholesalers. Three strategic archetypes dominate: diversified water heating conglomerates with multi-brand portfolios, specialized tankless engineering firms with condensing technology focus, and diversified industrial conglomerates leveraging appliance brand equity. Capacity expansion in stainless steel heat exchanger fabrication and strategic partnerships with smart home platform providers represent the dominant competitive moves.
Among North American market participants, A.O. Smith Corporation and Rinnai Corporation exemplify the vertically integrated archetype through manufacturing footprint control and wholesale distribution anchoring. Navien Inc. occupies a specialist position within the condensing technology tier. Stiebel Eltron Inc. represents the European-origin engineering-focused entrant with electric resistance specialization. These three named entities collectively illustrate the competitive segmentation between gas-fired infrastructure leverage and electric variant innovation pathways.
| Leading Market Players |
|---|
| A.O. Smith |
| Noritz America |
| Navien Inc. |
| Stiebel Eltron Inc. |
| Robert Bosch LLC |
| Rinnai Corporation |
| Bradford White Corporation |
| General Electric |
| Rheem Manufacturing Company |
| Others |
Pricing and Supply Chain Analysis
Captive production of stainless steel heat exchangers anchors supply positioning and pricing power for vertically integrated manufacturers across Tennessee and South Carolina, insulating them from commodity volatility that compresses margins for assembly-only competitors sourcing from third-party fabricators.
Pricing Analysis
Uniform energy factor ratings anchor value-based pricing tiers, with condensing architectures commanding premiums over non-condensing units due to DOE compliance thresholds above 0.90. Price differentiation separates UL-certified condensing models from economy-tier imports lacking CSA Group venting approval. Cost compression in the entry tier is intensifying because Asian manufacturers absorb certification timeline friction to gain specification share. Residential builders in Texas demonstrate lowest price sensitivity due to total-cost-of-ownership calculations, while multifamily developers in New York prioritize upfront capital minimization.
Supply Chain Analysis
Single-source vulnerability sits with Taiwanese semiconductor components governing modulating burner controls and Wi-Fi connectivity modules. Heat exchanger fabrication draws from domestic stainless steel mills in Pennsylvania and Ohio, supplemented by South Korean cold-rolled coil imports. Tariff exposure on Chinese electrical components creates margin instability for manufacturers lacking alternative sourcing pathways. Distribution runs through regional plumbing wholesalers with exclusive territory agreements, concentrating channel control among established incumbents.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
DOE efficiency mandates above 0.90 uniform energy factor are consolidating competitive positions, forcing smaller import competitors to absorb unsustainable testing investment or exit the market entirely.
For Market Incumbents: Hedge against electrification risk by diversifying into high-amperage electric variants for California and New York construction markets while maintaining condensing gas dominance in Texas and Florida. Secure backward integration into stainless steel heat exchanger fabrication to defend margin position against copper and nickel volatility. Prioritize CSA Group and UL certification maintenance as regulatory barriers that filter out emerging competitors. For New Entrants and Emerging Players: Capture specification share in multifamily hospitality retrofits across dense urban corridors where venting constraints prohibit gas-fired installation. Focus initial penetration on electric point-of-use configurations for New York City high-rise applications with 100-amp panel limitations. Pursue utility demand-response partnership programs as a go-to-market angle that enables premium positioning against commodity resistance units. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by diversified water heating conglomerates seeking condensing technology portfolios and established wholesale distribution relationships. Long-term viability favors manufacturers with captive heat exchanger production and smart home platform integration capabilities. Watch California's electrification mandate enforcement velocity as the critical inflection signal for gas-fired asset valuation.| Strategic Initiative | Industry Significance |
|---|---|
| Condensing Heat Exchanger Capacity Expansion | Domestic stainless steel fabrication in Tennessee satisfies DOE uniform energy factor mandates above 0.90. |
| Smart Home Platform Integration | Wi-Fi-enabled demand-response compatibility with utility programs enables premium pricing in Texas and California. |
| Electric Variant Certification Investment | UL and CSA Group approval for high-amperage units unlocks New York and Washington electrification mandates. |
| Wholesale Distribution Partnership | Exclusive territory agreements with regional plumbing suppliers anchor channel control against direct-to-consumer entrants. |
| Aftermarket Service Subscription Model | Descaling and burner inspection programs in hard-water Texas markets generate recurring revenue attachment. |
Research Methodology
Document review covered DOE 10 CFR Part 430 regulatory filings, EPA ENERGY STAR certification databases, and NRCan Energy Efficiency Regulations, complemented by interviews with manufacturing executives at vertically integrated producers, regional plumbing wholesaler procurement directors, and multifamily developer specification managers. Secondary validation drew from customs trade data on stainless steel coil imports, UL and CSA Group certification registries, and state-level building code amendment records. Bottom-up unit shipment estimates triangulated against top-down construction permit analysis.
Market sizing outputs segmented by combustion technology, installation configuration, end-use category, and regional energy infrastructure availability across the projection horizon. CAGRs derived from regression analysis correlating housing starts, energy code adoption timelines, and equipment replacement cycles. Forecast inputs incorporated inlet water temperature performance curves, natural gas lateral connection rates, and electrification mandate implementation schedules.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to state-level electrification policy reversals, copper and nickel commodity swings, and heat pump water heater substitution rates in moderate-climate zones. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Household Items
Infrared Sauna Heaters Market
Household Items
North America Liquid Hand Soap Market
Household Items
Integrated Smart Toilet Market
Household Items
Leaf Blower Market
Household Items
Smart Connected Water Purifier Market
Household Items
Domestic Sauna Heaters Market
Household Items
Global Refrigerator Water Filters Market
Household Items
Mosquito Trap Market
Household Items
Electric Air Freshener Market
Household Items
Asean Cookware Market
Household Items
Portable Humidifiers Market
Household Items
Global Electronic Bidet Seats Market
Household Items
Saudi Arabia Cookware Market
Household Items
Plastic Carafe Market
Household Items
Range Hood Cleaning Service Market
Household Items
Qatar Gas Hobs Market