
 United States Commercial Laundry Appliances Market | 2026-2036
United States Commercial Laundry Appliances Market Size, Share, and Industry Trends Forecast 2026-2036
United States Commercial Laundry Appliances Market Insights
The gap between premium and commodity tiers is broadening as multi-housing developers specify connected machines with remote monitoring while budget laundromats prioritize upfront cost over lifecycle efficiency. Alliance Laundry Systems leverages its vended laundry expertise to sustain dominance in coin-operated channels. Whirlpool competes through service network density that anchors its position in institutional accounts. Electrolux differentiates via energy recovery systems that reduce utility costs for hospital clients.
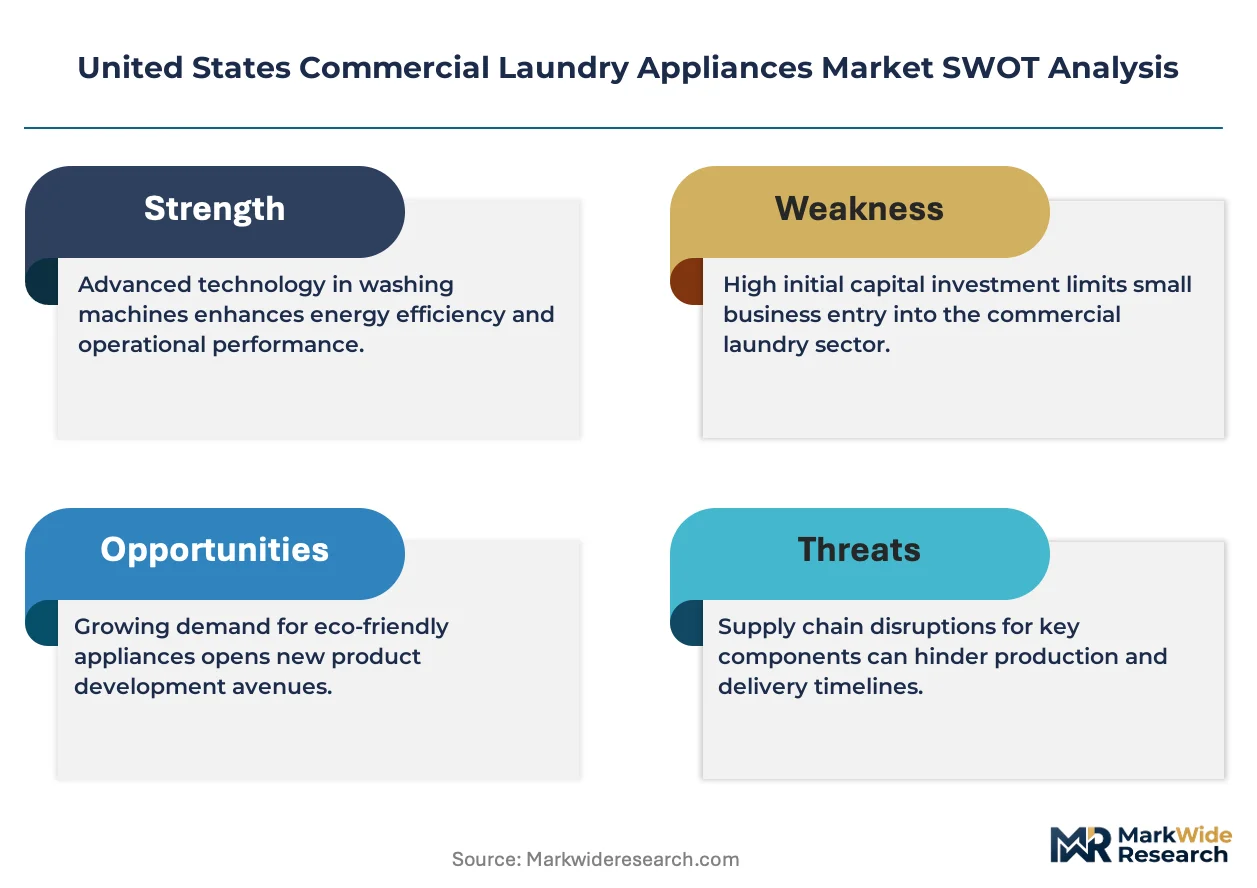
Commercial laundry appliances encompass industrial-grade washing, drying, and finishing equipment engineered for continuous operation cycles exceeding residential units by tenfold, typically constructed with stainless steel drums, reinforced suspension systems, and programmable controls managing water temperatures up to 180°F for sanitization protocols. These machines serve on-premise linen processing for hospitality, healthcare, and food service operations where throughput reliability directly affects business continuity. Washing machines and dryers occupy the core revenue pool given replacement frequency and parts aftermarket, while smart appliances represent the fastest-expanding technology segment as operators deploy IoT-enabled load tracking and predictive maintenance. Energy-efficient models command margin premiums in states with aggressive utility rebate programs, though compact designs remain niche outside urban multi-housing developments.
DOE appliance efficiency standards and EPA WaterSense specifications constrain allowable water and energy consumption, pushing manufacturers toward heat pump dryers and ozone wash systems. OSHA workplace safety rules govern commercial laundry ergonomics and chemical handling, influencing machine loading heights and detergent dispensing integration. State-level building codes in California and New York add layered compliance requirements that filter accessible product portfolios. Stakeholders must weigh total cost of ownership against capital outlay as utility tariffs and environmental enforcement tighten operational economics.
Market Dynamics
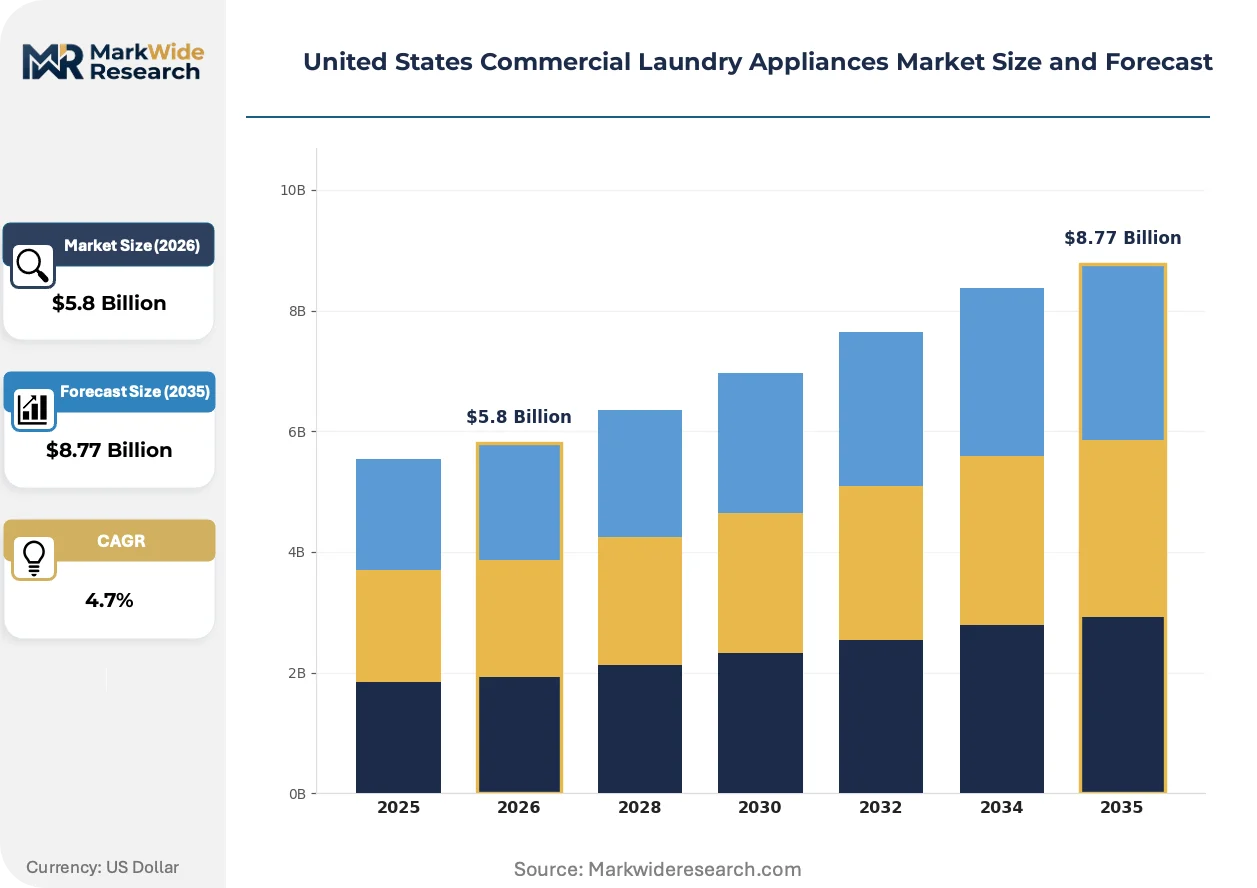
Utility rebate programs and state water mandates are compressing replacement cycles for aging equipment while simultaneously elevating the specification threshold for new procurement, forcing operators to reconcile upfront capital constraints with lifecycle cost accounting.
Growth Catalysts
- EPA WaterSense specifications:Federal efficiency benchmarks are accelerating retirements of pre-2018 machines in municipal facilities and hospital systems across the Southwest.
- Hospitality linen autonomy:Hotel operators in Texas and Florida are installing on-premise capacity to bypass third-party service dependencies and control turnaround reliability.
- Heat pump dryer adoption:Natural gas price volatility is redirecting multi-housing developers toward electric heat pump systems eligible for IRA-aligned utility incentives.
Market Restraints
- Stainless steel input costs:Drum and chassis fabrication depends on commodity steel pricing that has exhibited 20-40% volatility, squeezing manufacturer margins on fixed-price institutional contracts.
- Regional supply concentration:Component sourcing for programmable control modules clusters in East Asian manufacturing zones, exposing lead time risk to US assemblers.
- Technical limitation of ozone systems:Ozone wash technology requires water chemistry monitoring infrastructure that exceeds the technical capacity of many independent laundromat operators.
Strategic Opportunities
- Healthcare facility expansion in California:Hospital construction in the Central Valley and Inland Empire is generating demand for infection-control-grade equipment with 180°F sanitization protocols.
- IoT-enabled predictive maintenance:Convergence of cellular telemetry and machine learning is opening subscription-based service revenue streams for equipment financiers.
- State-level rebate stacking:California's SGIP and Texas PUCT programs allow combined incentives that narrow the payback gap between standard and heat pump dryer installations.
Industry Challenges
- EPA compliance documentation:WaterSense and ENERGY STAR certification timelines extend 8-14 months, delaying product launches and freezing R&D roadmaps.
- Integration complexity with legacy payment systems:Retrofitting IoT connectivity into installed coin-op infrastructure requires proprietary middleware that fragments vendor support obligations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Commercial Laundry Appliances Market |
| Market Size in 2026 | $5.8 Billion |
| Market Size in 2035 | $8.77 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Washing Machines, Dryers, Ironers, Folding Machines End User: Hotels, Hospitals, Laundromats, Restaurants Technology: Stackable Units, Smart Appliances, Energy-Efficient Models, Compact Designs Capacity: Small Scale, Medium Scale, Large Scale, Extra Large |
| Companies Covered | Alliance Laundry Systems LLC, Whirlpool Corporation, Electrolux AB, Dexter Laundry Inc., Continental Girbau Inc., LG Electronics, Bosch, Miele, Speed Queen, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Commercial Laundry Appliances Market Trends and Innovations
Equipment intelligence and thermal efficiency are converging to redefine competitive differentiation, with software-enabled service models displacing pure hardware transactions and regulatory pressure accelerating technology substitution.
Heat pump dryer technology is consolidating market share in segments where natural gas infrastructure is absent or carbon reporting requirements apply. Hospital systems in California and New York are specifying these systems to satisfy institutional sustainability commitments and qualify for municipal green building incentives. The technology is consolidating what had been a fragmented electric-versus-gas procurement landscape into a single efficiency-graded product hierarchy.
OSHA workplace safety rules governing commercial laundry ergonomics are mandating revised loading heights and chemical dispensing integration for new installations. Manufacturers must redesign chassis architectures to accommodate front-load accessibility standards while maintaining throughput specifications. The rule most acutely affects replacement demand in aging urban multi-housing stock where existing equipment predates current accessibility thresholds.
Equipment-as-a-service contracting is displacing traditional capital purchase arrangements among mid-scale hospitality operators. Third-party financiers now bundle machines, maintenance, and chemical supply into per-pound linen processing agreements that transfer operational risk from hotel owners to service providers. This restructuring concentrates most visibly in Florida's vacation rental management sector, where asset-light operating models dominate capital allocation decisions.
United States Commercial Laundry Appliances Market Segmentation
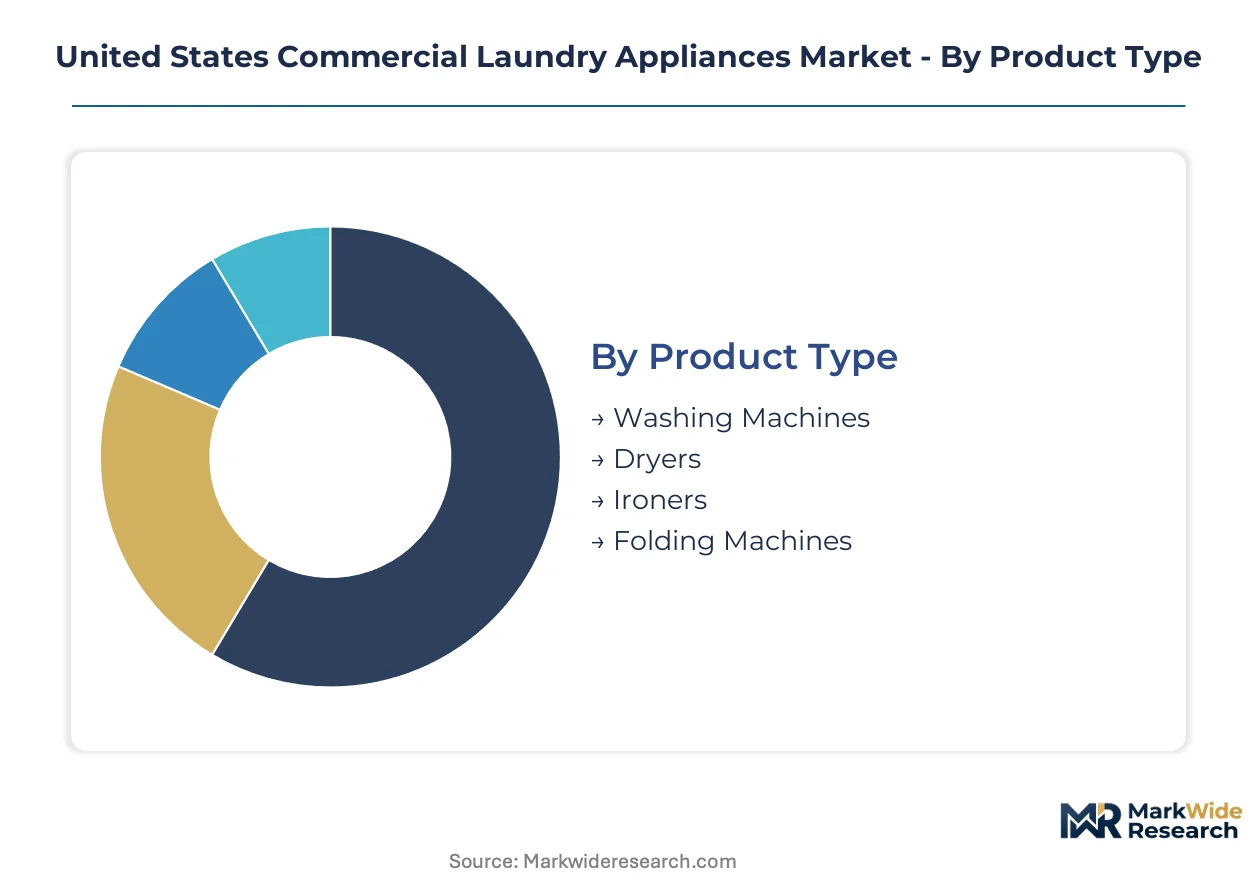
Equipment specification in the US commercial laundry market diverges sharply by operational scale and capital deployment strategy. Procurement committees weigh replacement cycles, utility rebate eligibility, and throughput requirements against total cost of ownership benchmarks.
Product Type:
Capital intensity peaks with ironers and folding machines requiring dedicated floor space and specialized installation, while washing machines and dryers dominate replacement frequency.
- Washing Machines:Stainless steel drums rated for 180°F sanitization cycles anchor hospital and hospitality procurement. Texas and Florida hotel construction is concentrating demand for programmable units with ozone compatibility.
- Dryers:Heat pump configurations are displacing natural gas systems in California multi-housing developments pursuing IRA-aligned utility incentives. Electric heat pump models command premium positioning where gas infrastructure is absent.
- Ironers:Roll-fed finishing equipment requires substantial upfront investment and dedicated line power, limiting adoption to institutional laundries with volume throughput above 500 pounds hourly.
- Folding Machines:Automated linen folding reduces labor hours in high-volume operations but demands precise feed mechanisms that complicate maintenance scheduling.
Washing machines absorb the bulk of installed capacity; heat pump dryers are expanding most quickly.
End User:
Customer archetypes segment by linen autonomy requirements and third-party service dependency tolerance.
- Hotels:On-premise capacity expansion in Texas and Florida bypasses third-party turnaround risk. Full-service properties specify connected machines with remote monitoring for linen inventory management.
- Hospitals:Infection-control protocols mandate 180°F wash cycles and EPA WaterSense-certified equipment. California Central Valley construction is generating demand for sanitization-grade installations.
- Laundromats:Coin-operated and card-activated vended laundry prioritizes upfront cost over lifecycle efficiency. Independent operators face technical barriers to ozone system adoption.
- Restaurants:Compact footprint requirements dominate procurement for food service linen processing, with throughput needs below institutional thresholds.
Hospitals maintain the strictest specification thresholds; hotels are gaining share fastest among end-user categories.
Technology:
Connectivity and thermal efficiency are restructuring competitive differentiation and procurement evaluation criteria.
- Smart Appliances:IoT-enabled load tracking and predictive maintenance capabilities are opening subscription revenue streams for equipment financiers. Cellular telemetry integration requires proprietary middleware that fragments vendor support.
- Energy-Efficient Models:ENERGY STAR certification and state rebate programs elevate specification thresholds in municipal and hospital procurement. California SGIP and Texas PUCT stacking incentives narrow payback gaps.
- Stackable Units:Vertical configuration maximizes floor space utilization in urban multi-housing developments with constrained mechanical room footprints.
- Compact Designs:Reduced-capacity equipment serves niche urban installations but remains limited outside dense metropolitan construction zones.
Energy-efficient models dominate new procurement specifications; smart appliances are climbing the fastest among technology segments.
Capacity:
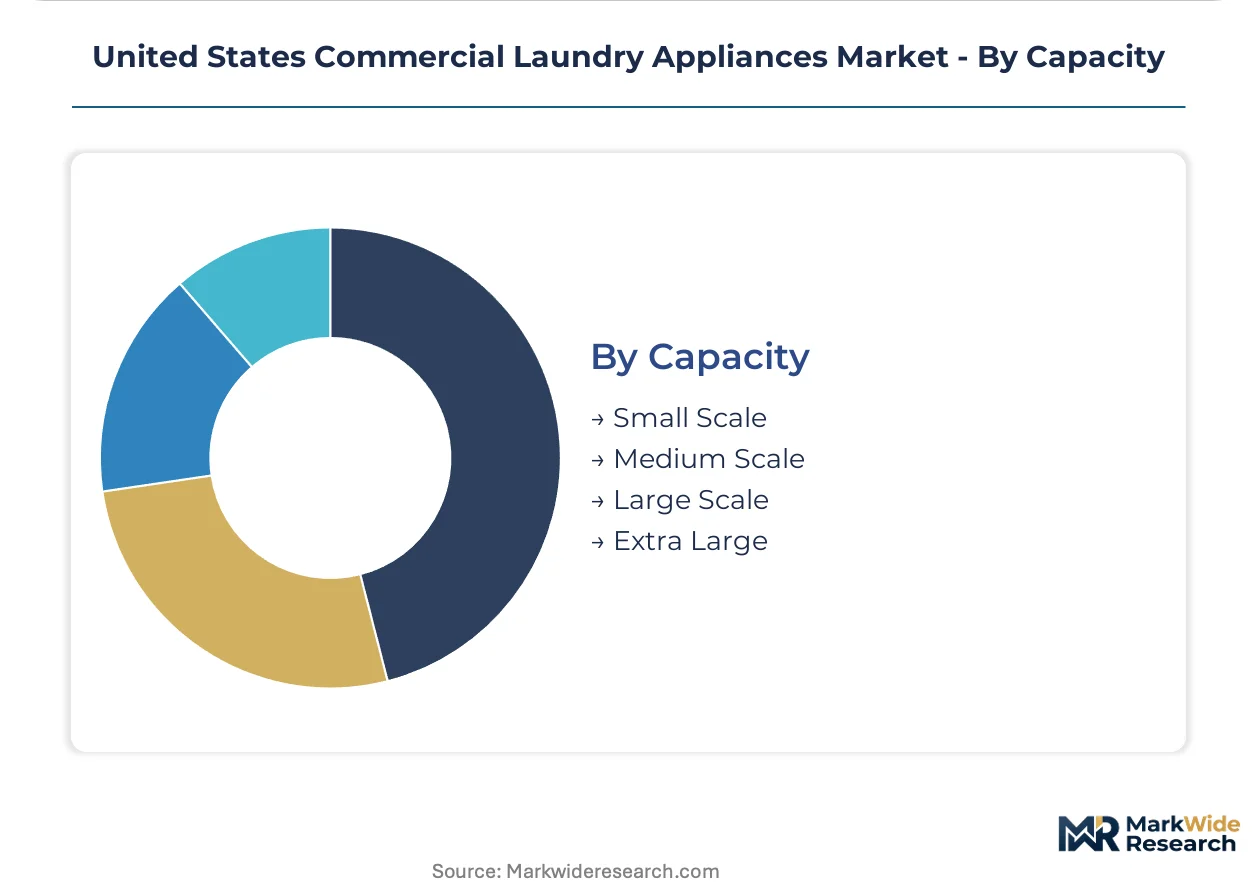
Scale segmentation aligns with batch processing economics and facility throughput requirements.
- Large Scale:Industrial-grade equipment processing 75-125 pound loads anchors hospital and hotel central laundries with continuous operation cycles. Reinforced suspension systems withstand tenfold residential duty cycles.
- Extra Large:Tunnel washer systems serve regional linen processing facilities with throughput exceeding 1,000 pounds hourly, requiring substantial capital deployment and dedicated utility infrastructure.
- Medium Scale:Mid-range capacity equipment balances throughput and footprint for independent laundromats and restaurant operations with moderate volume requirements.
- Small Scale:Compact units serve boutique hospitality and limited-service food operations with batch processing below 35 pounds.
Large scale equipment anchors institutional procurement; extra large systems are gaining share fastest in regional processing facilities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Texas hotel construction corridors and Florida vacation rental zones concentrate the bulk of new equipment demand, with California healthcare expansion adding institutional volume. State-level rebate programs and water mandates create divergent procurement economics across jurisdictions.
California
Central Valley and Inland Empire hospital construction is driving demand for infection-control-grade equipment with 180°F sanitization protocols. The California Public Utilities Commission SGIP program stacks incentives with federal IRA credits for heat pump dryer installations. Los Angeles and San Francisco multi-housing developers specify connected machines with remote monitoring to satisfy municipal green building codes.
Texas
Hospitality operators in Dallas-Fort Worth and Houston are expanding on-premise laundry capacity to bypass third-party linen service dependencies. The Texas PUCT utility rebate program narrows payback periods for energy-efficient equipment procurement. Austin and San Antonio hotel construction corridors concentrate demand for programmable washing systems with ozone compatibility.
Florida
Vacation rental management companies across Orlando and Miami-Dade are adopting equipment-as-a-service contracting to maintain asset-light operating models. State water efficiency mandates accelerate replacement of pre-2018 machines in municipal facilities. Tampa and Jacksonville healthcare facility expansion adds demand for EPA WaterSense-certified installations.
New York
Urban multi-housing stock in New York City faces OSHA-mandated equipment replacement for accessibility compliance, driving retrofit demand. State building codes layer additional requirements on commercial laundry installations beyond federal baselines. Buffalo and Rochester institutional laundries are upgrading to heat pump systems to satisfy carbon reporting commitments.
Illinois
Chicago metropolitan healthcare systems are specifying energy recovery systems to reduce utility costs amid volatile natural gas pricing. State procurement guidelines prioritize ENERGY STAR certification for municipal facility equipment. Midwest distribution hubs support parts aftermarket logistics for regional service networks.
United States Commercial Laundry Appliances Market Competitive Landscape
Premium-margin players sit above commodity-margin players across technology sophistication and service integration depth. The market exhibits moderate concentration with three to five dominant participants controlling institutional channels while fragmented regional assemblers serve independent laundromats. Strategic archetypes include full-line manufacturers with captive financing arms, component specialists with deep vended laundry expertise, and diversified appliance conglomerates leveraging residential service networks. Competitive moves center on vertical integration into software-enabled service models and geographic densification of field technician coverage.
Within the institutional-tier segment, Alliance Laundry Systems LLC and Whirlpool Corporation exemplify divergent channel strategies, with the former anchoring coin-operated expertise and the latter deploying dense service networks for hospital accounts. Electrolux AB occupies a position emphasizing energy recovery systems for utility-conscious healthcare clients. These three manufacturers represent distinct archetypes: vended laundry specialization, institutional service density, and thermal efficiency engineering.
| Leading Market Players |
|---|
| Alliance Laundry Systems LLC |
| Whirlpool Corporation |
| Electrolux AB |
| Dexter Laundry Inc. |
| Continental Girbau Inc. |
| LG Electronics |
| Bosch |
| Miele |
| Speed Queen |
| Others |
Pricing and Supply Chain Analysis
Heat pump dryer manufacturing transitions are simultaneously compressing production economics and redistributing supply leverage toward control module fabricators. This dual shift elevates procurement risk for US assemblers while reshaping how equipment financiers structure per-pound linen processing contracts.
Pricing Analysis
Per-pound linen processing agreements anchor value-based pricing as equipment financiers bundle machines, maintenance, and chemical supply into outcome-based contracts. Three-tier pricing structure across premium, standard, and economy levels separates ENERGY STAR-certified heat pump systems from conventional electric units and aging natural gas configurations. Cost compression in the commodity tier intensifies because independent laundromat operators prioritize upfront capital outlay over lifecycle efficiency calculations. Budget laundromats exhibit highest price sensitivity; hospital procurement committees demonstrate lowest sensitivity due to infection-control protocol mandates.
Supply Chain Analysis
Direct-to-institutional channels handle hyperscale healthcare and hospitality buyer demand while distributor networks serve fragmented laundromat operators. Component sourcing for programmable control modules clusters in Taiwan, South Korea, and mainland China manufacturing zones. Drum and chassis fabrication draws from stainless steel commodity markets subject to volatility. Single-source vulnerability in semiconductor-based control systems exposes US assemblers to lead time risk. Distribution runs through manufacturer-direct field service organizations for institutional accounts and regional equipment distributors for independent operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is a vertical-integration race. Players are pursuing captive financing arms to capture recurring service revenue and lock in equipment placement longevity.
For Market Incumbents: Deploy proprietary IoT middleware stacks to fragment competitor retrofit opportunities in installed coin-op infrastructure. Deepen field technician coverage density in Texas and Florida construction corridors to preempt service contract poaching. Heat pump technology substitution and emerging equipment-as-a-service financiers threaten legacy capital-sale margins.
For New Entrants and Emerging Players: Launch via subscription-based predictive maintenance platforms targeting mid-scale hospitality operators in Florida's vacation rental management sector. Exploit technical capacity gaps among independent laundromat operators for ozone wash system adoption. White-space concentrates in California Central Valley hospital construction zones requiring 180°F sanitization-grade installations.
For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisition by diversified appliance conglomerates seeking vended laundry channel expertise. Long-term viability hinges on software-enabled service revenue attachment rates exceeding hardware depreciation cycles. Acquisition targets with cellular telemetry integration capabilities and established hospital GPO contracts warrant premium positioning. Monitor EPA WaterSense certification timeline compression as inflection indicator for regulatory compliance cost escalation.
| Strategic Initiative | Industry Significance |
|---|---|
| Heat Pump Dryer Platform Expansion | Captures IRA-aligned utility incentives in California and Texas multi-housing developments. |
| IoT Middleware Development | Creates proprietary retrofit barriers against competitor equipment in installed base. |
| Equipment-as-a-Service Contracting | Transfers operational risk from Florida vacation rental operators to financiers. |
| Field Service Network Densification | Accelerates response times for hospital accounts with infection-control uptime requirements. |
| Ozone Wash System Integration | Addresses California and New York water efficiency mandates with chemistry monitoring infrastructure. |
Research Methodology
Independent corroboration across hospital procurement committees, hospitality operations directors, and laundromat owner-operators underwrites the qualitative findings. Primary fieldwork encompassed maintenance directors at institutional laundries, OEM procurement teams, and aftermarket service heads. Secondary validation drew from EPA WaterSense certification databases, DOE appliance efficiency standard filings, and state-level utility rebate program disclosures. Bottom-up equipment shipment analysis and top-down end-use demand modeling were reconciled through iterative triangulation.
Rate-of-change decomposition across the analysis window segments volume and value outputs by product type, end-user category, technology tier, and regional construction activity. CAGRs were derived from replacement cycle compression rates, rebate program eligibility thresholds, and hospital construction pipeline tracking. Forecast inputs incorporated natural gas price volatility assumptions and OSHA accessibility compliance retrofit schedules.
The model assumes a particular technology adoption path; alternative pathways for heat pump dryer penetration would alter the outlook. Forecasts reflect assumptions regarding EPA certification timeline stability and stainless steel commodity price normalization. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Appliances
Toaster Ovens Market
Appliances
Portable Mini Fridge Market
Appliances
UAE Microwave Ovens Market
Appliances
UAE Dishwasher Market
Appliances
Household Vacuum Cleaners Market
Appliances
Colombia Laundry Appliances Market
Appliances
Electric Iron Market
Appliances
Smart Washing Machine Market
Appliances
Digital Showers Market
Appliances
Body Dryer Market
Appliances
US Electric Rice Cooker Market
Appliances
United States Electric Kettle Market
Appliances
China Washing Machine Market
Appliances
Asia Pacific Household Side by Side Refrigerator Market
Appliances
Europe Garment Steamers Market
Appliances
Mini Refrigerator Market