
 Asia-Pacific Tumble Dryers Market | 2026-2036
Asia-Pacific Tumble Dryers Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Tumble Dryers Market Insights
Washer dryer combos is pivoting from niche to mainstream configuration across Asia-Pacific urban households. LG Electronics leverages its inverter heat pump technology to sustain premium positioning in Japanese and Australian markets. Haier anchors volume through localized production networks serving China's domestic channel. Midea competes aggressively on cost-engineered condenser units targeting Southeast Asian first-time buyers.
Asia-Pacific tumble dryers are electromechanical appliances that remove moisture from textiles through heated airflow, with heat pump variants achieving coefficient of performance ratings above three by recirculating thermal energy through refrigerant cycles. Their primary commercial purpose spans residential garment care, hospitality linen processing, and industrial textile finishing operations. Heat pump dryers command expanding share as energy efficiency regulations tighten, while washer dryer combos capture space-constrained apartment demand in Tokyo, Seoul, and Shanghai. Commercial end users in hotel and hospital sectors represent a concentrated margin pool due to durability requirements and service contract attach rates.
China's SAMR enforces GB standards on appliance energy consumption and safety certification, directly conditioning market access for imported and domestic units alike. Australia's energy rating label program and MEPS thresholds compel manufacturers to optimize heat pump architectures or face retail delisting. India's BIS mandatory registration scheme for electronic goods is extending compliance burdens to tumble dryer imports. Stakeholders must monitor divergence between national efficiency test protocols and the pace of smart connectivity mandates across the region.
Market Dynamics
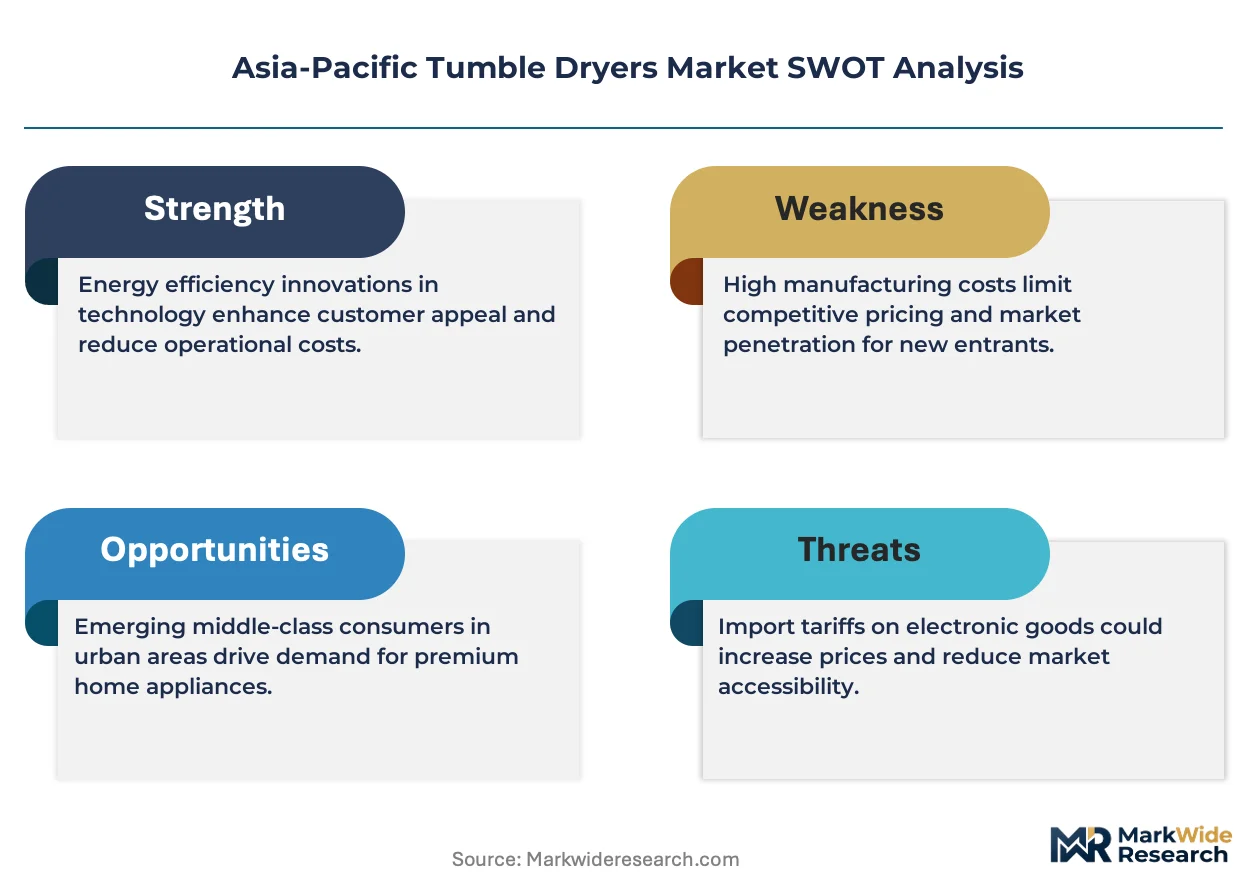
Heat pump technology is compressing energy consumption benchmarks across Asia-Pacific residential laundry, forcing condenser and vented architectures into terminal decline as GB standards and Australia's MEPS thresholds harden efficiency floors.
Growth Catalysts
- Urban apartment densification:Tokyo, Seoul, and Shanghai household formations below 50 square meters are eliminating outdoor drying space and mandating compact heat pump or washer-dryer configurations.
- Australia's MEPS tightening:Minimum Energy Performance Standards are delisting sub-2-star condenser units from retail channels, accelerating heat pump replacement cycles.
- Hospital linen throughput requirements:India's tertiary care expansion is creating concentrated demand for commercial-grade heat pump dryers with 15+ kilogram capacities and service contract attach rates.
Market Restraints
- Refrigerant input volatility:R290 and R32 pricing swings are compressing heat pump dryer margin structures for manufacturers without captive chemical supply.
- Component supply concentration:Inverter compressor and heat exchanger production clusters in China's Yangtze River Delta are creating single-point vulnerability for assembly networks across Southeast Asia.
- Vented dryer substitution persistence:Low-cost vented units retain 40%+ share in Indonesia and Philippines rental housing where installation flexibility outweighs operating cost sensitivity.
Strategic Opportunities
- Vietnam and Indonesia underpenetration:First-time appliance ownership curves in Ho Chi Minh City and Jakarta corridor households present volume expansion for condenser-to-heat pump upgrade pathways.
- Smart grid load balancing:Demand-response-enabled dryers communicating with Australia's AEMO and Japan's TEPCO grids unlock tariff arbitrage revenue streams for connected hardware.
- Commercial hospitality retrofit:Thailand and Malaysia resort renovation cycles are displacing gas-fired tumble systems with heat pump units to meet corporate ESG procurement mandates.
Industry Challenges
- Heat pump technician scarcity:Refrigerant handling certification and sealed system repair skills are bottlenecking service network expansion in India's tier-two cities.
- Multi-protocol smart home integration:Fragmentation between Matter, Tuya, and proprietary IoT ecosystems is forcing duplicate firmware development for China versus Australia-Japan product variants.
- BIS compliance timeline compression:India's mandatory registration scheme for electronic goods is extending import clearance cycles and testing queue backlogs for new heat pump SKUs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Tumble Dryers Market |
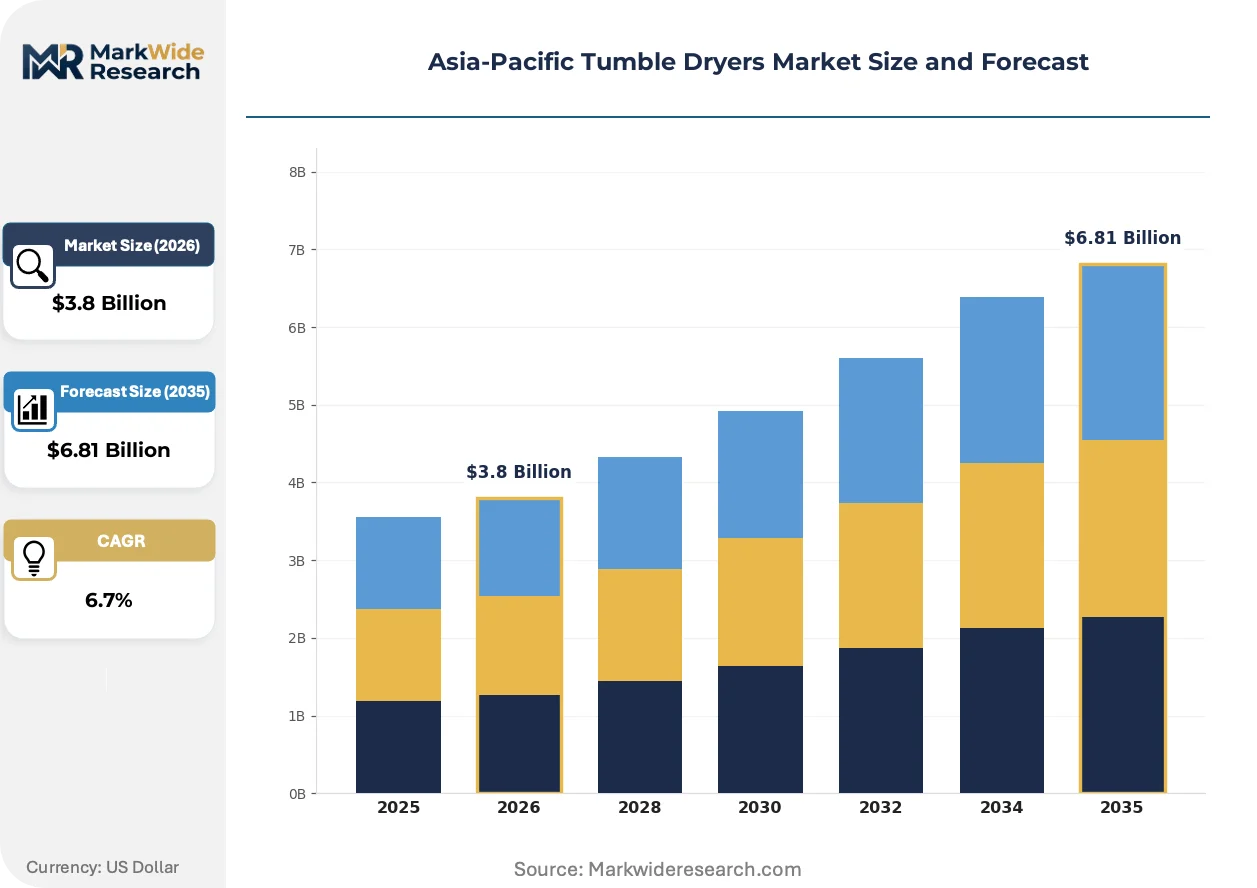
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vented Dryers, Condenser Dryers, Heat Pump Dryers, Washer Dryer Combos End User: Residential, Commercial, Industrial, Institutional Feature: Smart Technology, Energy Efficiency, Dryer Capacity, Noise Level Distribution Channel: Online Retail, Appliance Stores, Hypermarkets, Specialty Stores |
| Companies Covered | Bosch, Electrolux, Haier, LG Electronics, Panasonic, Midea, Siemens, Little Swan, Smad, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Tumble Dryers Market Trends and Innovations
Product architecture is bifurcating between premium heat pump systems with connected diagnostics and cost-optimized condenser units for price-sensitive Southeast Asian entry markets.
Inverter-driven variable-speed compressor technology is decentralizing thermal management precision in residential dryers. Japanese and South Korean apartment dwellers are specifying units with humidity sensors and refrigerant cycle modulation that cuts per-cycle energy draw by half versus fixed-speed alternatives. This capability is decentralizing the traditional trade-off between drying time and operating cost that constrained heat pump adoption in prior product generations.
China's SAMR is enforcing GB 12021.4 energy consumption limits and safety certification protocols that delist non-compliant imports from e-commerce channels. Manufacturers must redesign control systems and insulation packages to meet revised test procedures. Australian retailers are responding by consolidating shelf space toward heat pump architectures that satisfy both GB alignment and local MEPS thresholds.
After-sales service unbundling is fragmenting buyer-supplier relationships in Australia's commercial laundry segment. Hospitality and aged care operators are separating equipment procurement from maintenance contracts, awarding multi-year service agreements to specialized refrigerant technicians rather than OEM networks. This pattern is most visible in Queensland and Western Australia where independent service providers are capturing margin pools previously retained by manufacturer captive service arms.
Asia-Pacific Tumble Dryers Market Segmentation
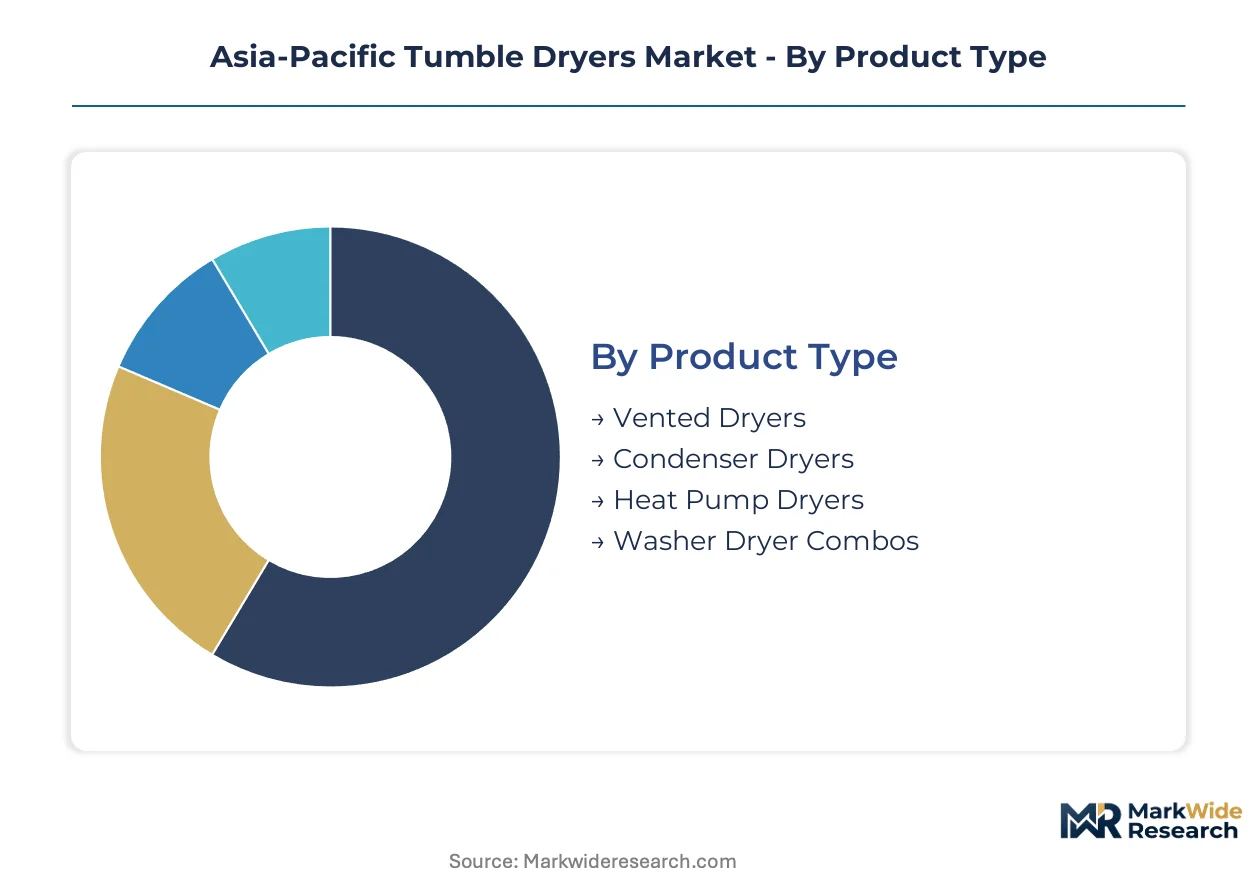
Technology architecture and installation constraints dictate purchasing patterns across Asia-Pacific's heterogeneous housing stock. Segmentation reveals how efficiency mandates and urban density reshape product mix from Tokyo apartments to Australian suburban homes.
Product Type:
Refrigerant cycle efficiency separates premium positioning from commodity volume in residential laundry.
- Heat Pump Dryers:Closed-loop refrigerant systems recirculate thermal energy through R290 or R32 cycles, achieving coefficient of performance ratings above three. Australia's MEPS tightening and Japan's METI efficiency guidelines are compressing adoption timelines in Sydney and Osaka metropolitan corridors.
- Washer Dryer Combos:Integrated drum systems combine washing and drying functions in sub-60-centimeter footprints. Seoul and Shanghai apartment formations below 50 square meters are eliminating standalone dryer space, forcing specification of ventless heat pump combo units.
- Condenser Dryers:Passive moisture extraction suits Southeast Asian first-time buyers in Jakarta and Ho Chi Minh City.
- Vented Dryers:Basic airflow systems retain cost-sensitive rental housing penetration in Philippines and Indonesia.
Mature deployment sits with vented and condenser architectures. Newer deployment is concentrated in heat pump and combo configurations.
End User:
Volume scale and service contract attach rates fragment margin structures across customer categories.
- Residential:Individual household procurement dominates unit volume, with purchasing decisions driven by energy label ratings and smart home protocol compatibility. China's tier-one cities and India's metropolitan corridors concentrate replacement demand.
- Commercial:Hotel and hospital operators specify 15+ kilogram capacities with multi-year maintenance agreements. India's tertiary care expansion and Thailand's resort renovation cycles are displacing gas-fired systems with heat pump units.
- Industrial:Textile finishing operations require continuous-duty drum systems with automated moisture sensing.
- Institutional:Prison, military, and university laundry facilities prioritize durability over efficiency optimization.
Residential captures the steepest expansion trajectory. Commercial represents the concentrated margin pool.
Feature:
Specification differentiation increasingly centers on connectivity and operating cost rather than mechanical performance alone.
- Energy Efficiency:GB standards and Australia's star rating schemes are delisting sub-compliant units from retail channels. Manufacturers redesign insulation packages and control systems to satisfy revised test protocols.
- Smart Technology:Demand-response-enabled units communicating with Australia's AEMO and Japan's TEPCO grids unlock tariff arbitrage revenue streams.
- Dryer Capacity:Drum volume specifications range from 7-kilogram apartment units to 25-kilogram commercial systems.
- Noise Level:Decibel ratings below 60 dB command premium positioning in Japanese and South Korean dense housing.
Energy efficiency dominates procurement criteria. Smart connectivity is climbing fastest in Australia and Japan.
Distribution Channel:
Channel economics reflect installation complexity and after-sales service requirements.
- Appliance Stores:Specialist retailers anchor heat pump and combo sales through demonstration and installation bundling. Australia's retail consolidation is compressing shelf space toward MEPS-compliant architectures.
- Online Retail:E-commerce platforms capture price-sensitive condenser and vented volume in Southeast Asia. China's SAMR enforces GB certification visibility on product listings.
- Hypermarkets:Mass merchandisers move entry-level units with limited service attach rates.
- Specialty Stores:Commercial laundry specialists serve hospitality and healthcare procurement with multi-unit contract negotiation.
Appliance stores retain premium positioning. Online retail is expanding most quickly in underpenetrated Southeast Asian markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's Yangtze River Delta concentrates manufacturing output while consumption concentrates in tier-one cities. Japan and South Korea import high-efficiency heat pump architectures. Australia's MEPS regime accelerates replacement cycles. India's BIS compliance timeline compresses import clearance for new heat pump SKUs.
China
Shanghai and Beijing apartment formations below 50 square meters are eliminating outdoor drying space and mandating compact heat pump or washer-dryer configurations. SAMR enforces GB 12021.4 energy consumption limits and safety certification protocols that delist non-compliant imports from e-commerce channels. The Yangtze River Delta cluster anchors inverter compressor and heat exchanger production networks serving assembly operations across Southeast Asia.
Japan
Tokyo and Osaka metropolitan corridors drive specification of units with humidity sensors and refrigerant cycle modulation that cuts per-cycle energy draw by half versus fixed-speed alternatives. METI efficiency guidelines compress adoption timelines for heat pump architectures. Kanto and Kansai regions concentrate dense housing stock where decibel ratings below 60 dB command premium positioning.
South Korea
Seoul Capital Area household formations are forcing adoption of ventless heat pump combo units in sub-60-centimeter footprints. The country's national appliance efficiency regulator mandates performance thresholds that accelerate condenser displacement. Busan-Ulsan corridor commercial laundries specify 15+ kilogram capacities with multi-year maintenance agreements.
Australia
Sydney and Melbourne suburban homes drive replacement demand as MEPS tightening delists sub-2-star condenser units from retail channels. The energy rating label program compels manufacturers to optimize heat pump architectures or face retail delisting. Queensland and Western Australia hospitality operators are separating equipment procurement from maintenance contracts, awarding service agreements to specialized refrigerant technicians.
India
Maharashtra and Delhi-NCR metropolitan corridors concentrate replacement demand from tier-one city households. BIS mandatory registration scheme for electronic goods extends compliance burdens to tumble dryer imports and compresses clearance cycles for new heat pump SKUs. India's tertiary care expansion in Karnataka and Telangana creates concentrated demand for commercial-grade heat pump dryers with service contract attach rates.
Asia-Pacific Tumble Dryers Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across technology tiers and price points. The vendor base separates into three strategic archetypes: diversified home appliance conglomerates with captive compressor supply, mid-scale fabricators competing on cost-engineered condenser units, and premium specialists leveraging inverter heat pump technology. Competitive moves concentrate on geographic licensing partnerships and backward integration into refrigerant handling capabilities.
Among diversified home appliance conglomerates, LG Electronics and Haier occupy positions spanning premium heat pump systems through volume-anchored domestic channels. Midea exemplifies the cost-engineered tier targeting Southeast Asian first-time buyers. Bosch and Electrolux sit within the European-origin specialist tier competing on energy efficiency certification and connected diagnostics. Little Swan and Smad represent China-based fabricators serving localized production networks.
| Leading Market Players |
|---|
| Bosch |
| Electrolux |
| Haier |
| LG Electronics |
| Panasonic |
| Midea |
| Siemens |
| Little Swan |
| Smad |
| Others |
Pricing and Supply Chain Analysis
R290 and R32 refrigerant price indices cascade through Asia-Pacific tumble dryer supply chains, compressing heat pump margins for assemblers without captive chemical supply while forcing three-tier pricing stratification across premium inverter systems, standard condenser units, and economy vented alternatives.
Pricing Analysis
Margin tightening in heat pump tiers reflects refrigerant input volatility and Australia's MEPS-driven retail delisting of sub-2-star condenser units. Pricing stratifies across premium inverter heat pump systems with connected diagnostics, standard fixed-speed heat pump configurations, and cost-engineered condenser units for Southeast Asian first-time buyers. Cost compression accelerates in condenser architectures as Chinese fabricators compete on volume. Commercial hospitality buyers in Thailand and Malaysia exhibit lowest price sensitivity due to ESG procurement mandates, while Indonesia and Philippines rental housing segments drive economy vented demand.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale demand from LG Electronics and Haier, while specialized distributors serve Australia's commercial laundry retrofit market. Manufacturing concentrates in China's Yangtze River Delta, South Korea's Gyeonggi-do corridor, and Thailand's Eastern Economic Zone. Component sourcing draws from Japan for inverter compressors, Germany for precision sensors, and domestic China for heat exchangers. Single-source vulnerability clusters in Yangtze River Delta inverter compressor production. Distribution runs through appliance stores for premium heat pump demonstration, e-commerce platforms for Southeast Asian condenser volume, and commercial specialists for hospitality procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Asia-Pacific tumble dryer manufacturing is consolidating around refrigerant-handling capabilities and inverter compressor supply, with Australia's MEPS tightening and India's BIS compliance compression forcing cost-engineered assemblers toward acquisition or exit.
For Market Incumbents: Hedge refrigerant price exposure through backward integration into R290 and R32 supply or long-term offtake agreements with Chinese chemical producers. Secure inverter compressor allocation from Yangtze River Delta clusters before capacity constraints harden. Defend Australian retail shelf space by accelerating heat pump SKUs through MEPS certification ahead of condenser delisting deadlines. For New Entrants and Emerging Players: Capture white-space in Vietnam and Indonesia first-time appliance ownership curves by importing cost-optimized condenser units with localized packaging and voltage adaptation. Target India's tier-two commercial laundry segment where heat pump technician scarcity has slowed incumbent service network expansion. Lead with refrigerant-handling certification partnerships to differentiate against OEM captive service arms. For Investors and Strategic Acquirers: The window for entry favors mid-scale fabricators with captive inverter compressor supply and established BIS or SAMR compliance pathways. Long-term viability hinges on exposure to Australia's MEPS-aligned product mix and India's tertiary care commercial demand. Watch refrigerant price volatility indices as inflection indicator for margin compression timing across heat pump-dependent assemblers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Refrigerant Supply | R290 and R32 price hedging secures heat pump margin stability against chemical input volatility. |
| Inverter Compressor Capacity Expansion | Yangtze River Delta manufacturing scale-up addresses single-point vulnerability for Southeast Asian assembly networks. |
| MEPS Pre-Certification Investment | Australia's energy rating label program compels early compliance to avoid retail delisting. |
| Commercial Service Network Buildout | India's tertiary care expansion creates attach-rate revenue pools for hospital linen processing contracts. |
| Smart Grid Connectivity Development | Demand-response firmware unlocks tariff arbitrage with Australia's AEMO and Japan's TEPCO grids. |
Research Methodology
Trade publications, customs export records, and SAMR certification databases formed the secondary backbone, cross-referenced with primary interviews across appliance store buyers, commercial laundry procurement managers, refrigerant handling technicians, and OEM supply chain directors. Bottom-up and top-down triangulation validated shipment volumes and pricing tiers across the analysis window.
Bottom-up modeling aggregated unit economics by technology architecture, installation type, and end-user segment, while top-down approaches cross-checked against national appliance stock estimates and replacement cycle assumptions. Segmentation dimensions included product type, end user category, feature specification, and distribution channel. CAGRs derived from regression analysis against efficiency regulation timelines and urban household formation data.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to refrigerant price volatility, BIS clearance timeline extensions, and divergence in smart home protocol standards. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Appliances
Personal Care Appliances Market
Appliances
Window Air Conditioners Market
Appliances
Saudi Arabia Dishwasher Market
Appliances
Refrigerator Repair Service Market
Appliances
United States Commercial Laundry Appliances Market
Appliances
Washing Appliances Market
Appliances
Israel Laundry Appliances Market
Appliances
Dishwasher Market
Appliances
Mini Washing Machine Market
Appliances
Refrigerated Cabinet Market
Appliances
Mexico Washing Machine Market
Appliances
Automatic Dishwasher Market
Appliances
Mobile Refrigerators Market
Appliances
France Household Electric Grills Market
Appliances
Smart Microwave Oven Market
Appliances
Smart Massage Appliances Market