
 Asia Pacific IoT Security Market | 2026-2036
Asia Pacific IoT Security Market Size, Share, and Industry Trends Forecast 2026-2036
Asia Pacific IoT Security Market Intelligence
A shortage of embedded systems security engineers is reorganizing vendor priorities across the Asia Pacific IoT Security Market, forcing platform providers to build training pipelines and partner with regional universities. Cisco Systems Inc. anchors its position through extensive certification programs that feed talent directly into enterprise deployment teams. Trend Micro competes by sustaining deep research operations in Tokyo and Taipei that specialize in firmware vulnerability discovery. Palo Alto Networks Inc. differentiates through channel control, leveraging exclusive distributor relationships across Southeast Asian markets to limit competitive access.
Asia Pacific IoT Security encompasses cryptographic protocols, hardware trust modules, and behavioral analytics designed to protect interconnected devices transmitting data across heterogeneous networks; implementations typically require AES-256 encryption, secure boot architectures, and continuous anomaly detection operating at sub-100 millisecond latency thresholds. The primary commercial purpose is preventing unauthorized access, data exfiltration, and operational disruption in environments where legacy industrial equipment interfaces with cloud-connected sensors. Endpoint Security solutions currently dominate procurement budgets as organizations retrofit aging manufacturing assets with agent-based monitoring. Cloud Security deployments are expanding fastest among utilities and financial services firms migrating operational technology workloads to distributed infrastructure. Identity & Access Management retains concentrated margin pools due to complex integration requirements with existing enterprise directory services and multi-factor authentication hardware.
Japan's METI issues binding IoT security guidelines for critical infrastructure operators, while Australia's TGA enforces data integrity standards for connected medical devices; India's BIS is developing mandatory certification protocols for consumer electronics with network connectivity, effectively raising market entry barriers for uncertified hardware imports. Australia's ACSC framework and Singapore's CSA Cybersecurity Labelling Scheme add overlapping compliance layers that shape product development roadmaps. Stakeholders must monitor which regulatory body achieves de facto harmonization across ASEAN member states, as divergent national standards would fragment procurement specifications and inflate certification costs for cross-border solution deployments.
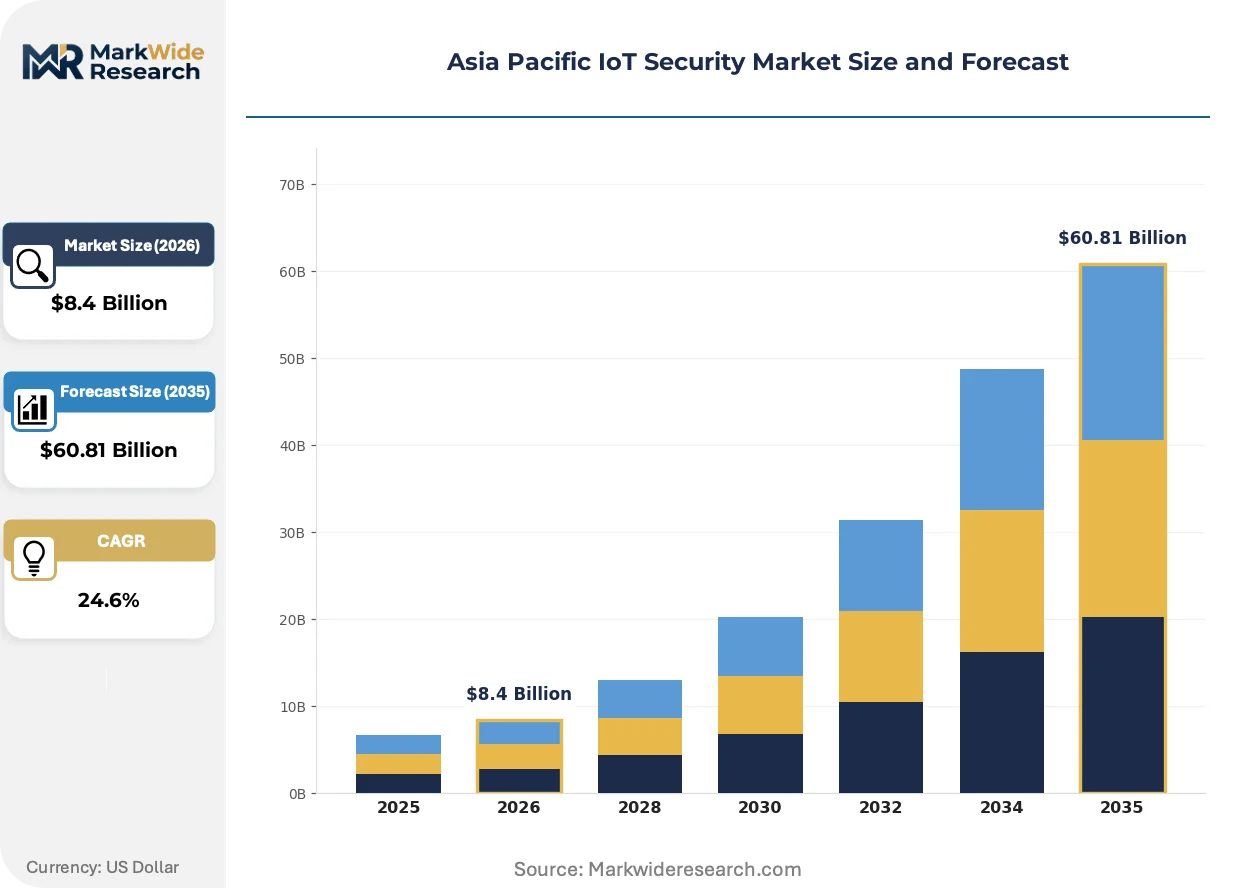
Market Dynamics
Japan's METI IoT security guidelines are forcing automotive and electronics suppliers to retrofit embedded hardware trust modules across production lines, compressing deployment timelines and reshaping vendor qualification criteria throughout the Asia Pacific supply base.
Growth Catalysts
- Industrial automation mandates:Smart manufacturing facilities across South Korea's Gyeonggi-do corridor are accelerating procurement of endpoint protection and network segmentation tools to secure legacy equipment interfaces.
- Australia's TGA data governance rules:Connected medical device manufacturers must implement AES-256 encryption and secure boot architectures, creating certified demand pools for cryptographic protocol vendors.
- India's BIS cybersecurity framework:Mandatory certification protocols for consumer electronics with network connectivity are raising compliance obligations that favor established platform providers with testing infrastructure.
Market Restraints
- Silicon supply concentration:Hardware trust module fabrication depends on concentrated foundry capacity in Taiwan, exposing procurement schedules to single-source risk.
- Specialized talent scarcity:Embedded systems security engineers command premium compensation in Tokyo and Singapore, inflating implementation costs for mid-tier enterprises.
- Regulatory fragmentation:Divergent national standards across ASEAN member states fragment procurement specifications and inflate certification costs for cross-border solution deployments.
Strategic Opportunities
- Vietnam's industrial zones:Underpenetrated manufacturing corridors offer first-mover positioning for vendors establishing localized support infrastructure ahead of compliance deadline waves.
- Utilities sector migration:Cloud security deployments are expanding fastest among financial services firms and power distributors migrating operational technology workloads to distributed infrastructure.
- Singapore's CSA Cybersecurity Labelling Scheme:Regulatory tailwinds create preference premiums for certified devices, rewarding early certification investments with procurement shortlist advantages.
Industry Challenges
- Firmware vulnerability discovery timelines:Continuous anomaly detection operating at sub-100 millisecond latency requires specialized testing pipelines that stretch internal R&D capacity.
- Multi-factor authentication hardware integration:Complex directory service integration for identity and access management solutions extends sales-to-implementation cycles and strains professional services teams.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia Pacific IoT Security Market |
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $60.81 Billion |
| CAGR (2026 – 2036) | 24.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Solution Type: Network Security, Endpoint Security, Data Security, Identity & Access Management, Cloud Security, Behavioral Analysis Deployment Mode: On-Premises, Cloud-Based, Hybrid, Managed Security Service, Edge Deployment Use Case: Smart Manufacturing, Connected Vehicles, Smart Homes, Healthcare Monitoring, Energy Management, Agricultural Automation End User Industry: Telecommunications, Consumer Electronics, Utilities, Government Agencies, Transportation, Financial Services |
| Companies Covered | Symantec Corporation, IBM Corporation, FireEye Inc., Intel Corporation, Infineon Technologies, Trend Micro, Cisco Systems Inc., Fortinet Inc., Palo Alto Networks Inc., Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia Pacific IoT Security Market Strategic Shifts & Innovations
Behavioral analytics engines are displacing signature-based detection across Asia Pacific industrial deployments, while regulatory layering between national frameworks forces vendors toward modular certification architectures.
Post-quantum cryptographic protocols are fragmenting the hardware security module landscape. Automotive suppliers in Japan's Aichi Prefecture are piloting lattice-based encryption for firmware signing ahead of METI compliance deadlines. This migration is fragmenting vendor consolidation patterns as specialized cryptographic hardware providers capture design wins from generalist platform vendors.
Australia's ACSC Essential Eight framework is tightening baseline controls for critical infrastructure operators. The industrial consequence mandates multi-factor authentication and privileged access management for all remote operational technology connections. Water utilities in New South Wales are responding fastest, embedding these requirements into tender specifications ahead of federal enforcement timelines.
Enterprise buyers are unbundling after-sales service contracts from initial platform procurement. Japanese automotive tier-1 suppliers now separate three-year maintenance agreements from license purchases, compressing upfront vendor revenue recognition. This pattern is most visible in Osaka's electronics manufacturing cluster, where procurement teams negotiate service tiers through competitive rebidding rather than bundled extensions.
Asia Pacific IoT Security Market Segmentation
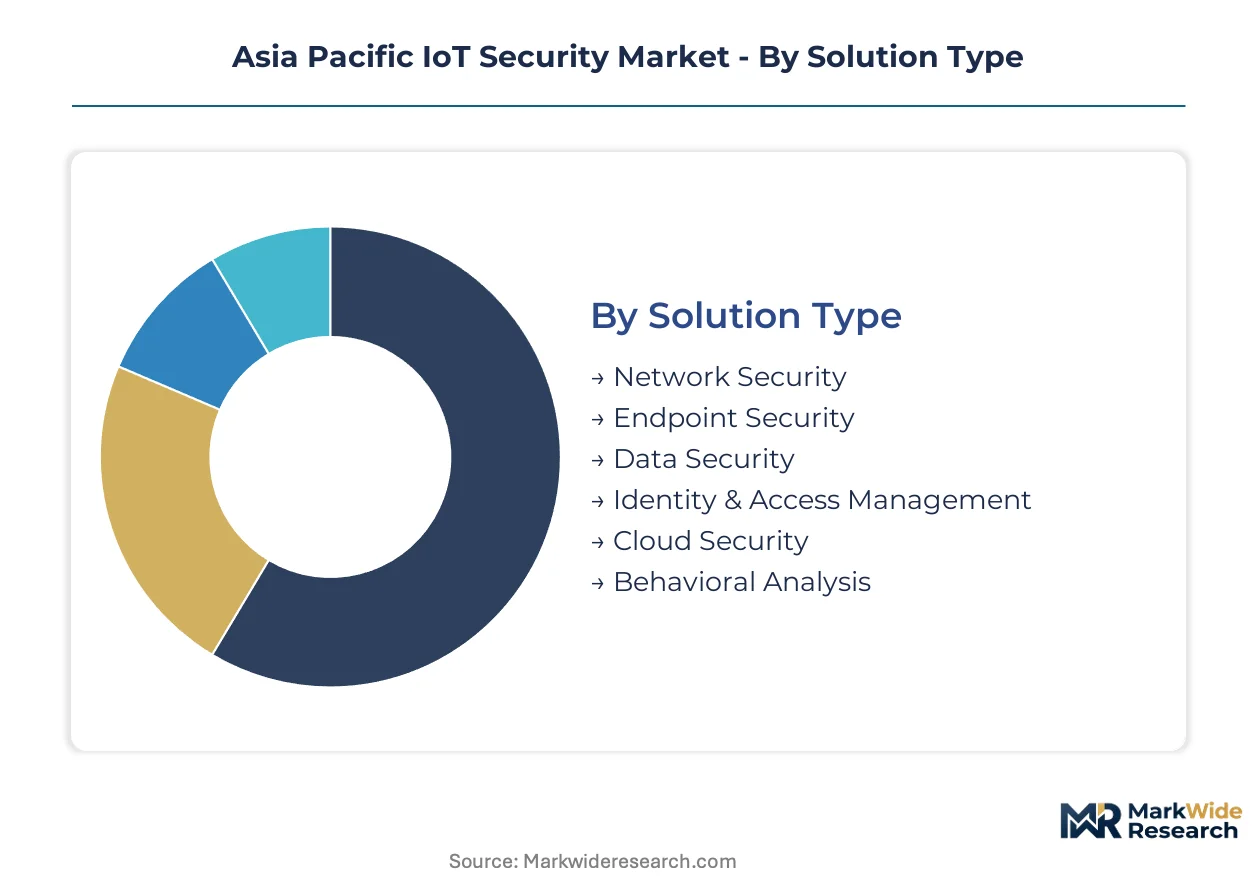
Regulatory layering across Asia Pacific jurisdictions fragments procurement specifications, forcing vendors to architect modular solutions that satisfy multiple compliance regimes simultaneously. Segmentation reveals where compliance costs concentrate and which solution architectures capture premium positioning.
Solution Type:
Japan's METI guidelines and Australia's TGA rules create divergent technical requirements that reshape solution architecture priorities across vendor portfolios.
- Endpoint Security:Agent-based monitoring systems retrofit aging manufacturing assets with continuous anomaly detection operating at sub-100 millisecond latency. Procurement concentrates in South Korea's Gyeonggi-do corridor where smart manufacturing mandates accelerate deployment timelines.
- Cloud Security:Distributed infrastructure protection for operational technology workloads migrating to cloud environments. Utilities and financial services firms in Australia and Singapore drive fastest expansion as they rebalance on-premise legacy systems.
- Network Security:Segmentation tools securing heterogeneous device interfaces across industrial networks.
- Data Security:AES-256 encryption implementations for data integrity in connected medical devices.
- Identity & Access Management:Complex integration with enterprise directory services and multi-factor authentication hardware.
- Behavioral Analysis:Engines displacing signature-based detection across industrial deployments.
Endpoint Security handles the majority of throughput; Cloud Security is expanding most quickly on share.
Deployment Mode:
Cost tier differentiation separates enterprise self-managed implementations from mid-market service-dependent alternatives.
- Cloud-Based:Subscription models reduce capital expenditure for utilities migrating operational technology workloads. Australian water utilities in New South Wales embed ACSC Essential Eight requirements into cloud procurement specifications ahead of federal enforcement.
- Managed Security Service:Outsourced monitoring and response capabilities address embedded systems security engineer scarcity in Tokyo and Singapore. Mid-tier enterprises accept premium pricing to bypass internal talent constraints.
- On-Premises:Air-gapped architectures for critical infrastructure operators with sovereignty requirements.
- Hybrid:Split workloads balancing latency-sensitive edge processing with centralized analytics.
- Edge Deployment:Sub-100 millisecond latency enforcement for autonomous manufacturing lines.
Cloud-Based deployments capture the steepest expansion trajectory; Managed Security Service commands premium pricing tiers.
Use Case:
Application maturity varies sharply across industrial verticals, with compliance deadlines forcing retrofit investments ahead of greenfield deployments.
- Smart Manufacturing:Network segmentation and endpoint protection securing legacy equipment interfaces with cloud-connected sensors. Japan's automotive and electronics suppliers in Aichi Prefecture retrofit embedded hardware trust modules under METI guideline pressure.
- Connected Vehicles:Post-quantum cryptographic protocols for firmware signing in automotive supply chains. Lattice-based encryption pilots precede binding compliance deadlines.
- Smart Homes:India's BIS mandatory certification protocols for consumer electronics with network connectivity.
- Healthcare Monitoring:Australia's TGA data integrity standards for connected medical devices.
- Energy Management:Grid-edge security for distributed power generation assets.
- Agricultural Automation:Low-bandwidth optimization for remote sensor networks.
Smart Manufacturing absorbs the largest implementation spend; Connected Vehicles is gaining share fastest as automotive compliance deadlines approach.
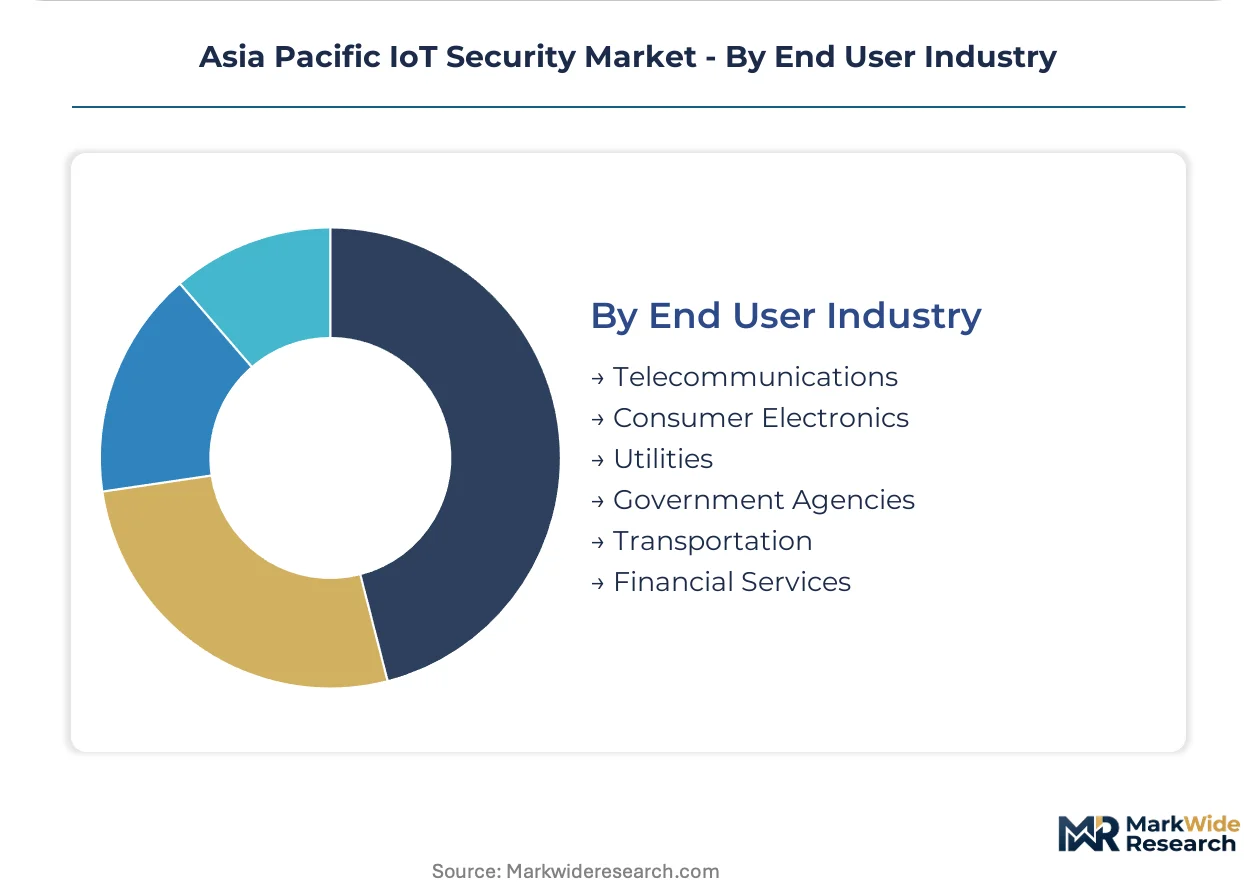
End User Industry:
Customer type determines integration complexity, with regulated industries demanding certified architectures that extend sales cycles.
- Utilities:Critical infrastructure operators implementing multi-factor authentication and privileged access management for all remote operational technology connections. Australia's ACSC framework tightens baseline controls fastest among Asia Pacific jurisdictions.
- Financial Services:Cloud security deployments expanding operational technology workload migration to distributed infrastructure with stringent audit requirements.
- Telecommunications:Core network protection for 5G-connected IoT device proliferation.
- Consumer Electronics:India's BIS certification raising market entry barriers for uncertified hardware imports.
- Government Agencies:Sovereign cloud mandates and data localization requirements.
- Transportation:Connected vehicle infrastructure and logistics tracking security.
Utilities dominates current procurement volume; Financial Services is climbing fastest on implementation pace.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
METI's IoT security guidelines anchor Japan's dominant position in the Asia Pacific IoT Security Market, with procurement concentration across industrial corridors reshaping vendor qualification criteria throughout the regional supply base.
Japan
Automotive and electronics suppliers in Aichi Prefecture retrofit embedded hardware trust modules under METI guideline pressure, compressing deployment timelines. The METI IoT security guidelines mandate cryptographic protocol upgrades for critical infrastructure operators. Osaka's electronics manufacturing cluster unbundles after-sales service contracts from initial platform procurement, compressing upfront vendor revenue recognition.
South Korea
Smart manufacturing facilities across Gyeonggi-do corridor accelerate procurement of endpoint protection and network segmentation tools. The country's national cybersecurity regulator enforces baseline controls for industrial control systems. Daegu-Gyeongbuk manufacturing zones concentrate demand for agent-based monitoring systems retrofitting aging production assets.
Australia
Water utilities in New South Wales embed ACSC Essential Eight requirements into cloud procurement specifications ahead of federal enforcement. The TGA enforces data integrity standards for connected medical devices, creating certified demand pools for cryptographic protocol vendors. Sydney and Melbourne financial services firms drive fastest cloud security expansion as they rebalance on-premise legacy systems.
India
Consumer electronics manufacturers face mandatory BIS certification protocols for network-connected devices, raising market entry barriers for uncertified hardware imports. The BIS cybersecurity framework tightens compliance obligations that favor established platform providers with testing infrastructure. Maharashtra and Gujarat industrial corridors concentrate procurement for mid-tier enterprises accepting premium managed security service pricing.
Singapore
The CSA Cybersecurity Labelling Scheme creates preference premiums for certified devices, rewarding early certification investments with procurement shortlist advantages. Financial services and power distributors drive operational technology workload migration to distributed infrastructure. The city-state's data center concentration attracts cloud security deployments from regional headquarters operations.
Asia Pacific IoT Security Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes across the Asia Pacific IoT Security Market, with platform consolidation around established providers creating tiered competitive dynamics. Network equipment specialists and endpoint security pure-plays occupy distinct strategic positions, while semiconductor-integrated security vendors capture hardware trust module design wins. Dominant competitive moves include exclusive distributor relationship-building across Southeast Asian markets and localized training pipeline development feeding enterprise deployment teams.
Within the network infrastructure tier, Cisco Systems Inc. and Palo Alto Networks Inc. occupy positions shaped by channel control strategies and certification program investments. Trend Micro exemplifies the research-driven archetype through sustained vulnerability discovery operations. These three anchors represent how geographic concentration of engineering talent and distributor exclusivity arrangements partition competitive access across national markets.
| Leading Market Players |
|---|
| Symantec Corporation |
| IBM Corporation |
| FireEye Inc. |
| Intel Corporation |
| Infineon Technologies |
| Trend Micro |
| Cisco Systems Inc. |
| Fortinet Inc. |
| Palo Alto Networks Inc. |
| Others |
Cost & Logistics Intelligence
Sixty-to-ninety day lead times for hardware trust module procurement concentrate pricing power with Taiwan-based foundries, compressing margin flexibility for downstream platform vendors while amplifying cost pass-through to Australian utilities and Japanese automotive suppliers under METI compliance deadlines.
Pricing Analysis
Singapore commands 15-25% premiums over Indian and Vietnamese markets for equivalent endpoint security deployments, reflecting certification density and localized support infrastructure. Three-tier pricing structure across premium, standard, and economy levels segments by compliance grade and after-sales bundling. Cost compression in mid-tier managed security services is intensifying because embedded systems security engineer scarcity inflates implementation labor costs. Small and mid-tier enterprises in India's Maharashtra corridor exhibit highest price sensitivity, while Japanese critical infrastructure operators under METI guidelines show lowest sensitivity due to non-negotiable compliance deadlines.
Supply Chain Analysis
Container availability constraints on the Shanghai-Singapore trade lane elevate inbound logistics costs for cryptographic hardware imports, forcing Australian vendors to buffer inventory ahead of TGA enforcement waves. Hardware trust module fabrication draws from concentrated foundry capacity in Taiwan, South Korea, and Japan. Silicon wafer, secure element chips, and post-quantum cryptographic IP constitute critical input dependencies. Single-source vulnerability in Taiwan-based fabrication exposes procurement schedules to geopolitical disruption. Distribution runs through exclusive distributor relationships across Southeast Asian markets, with channel partners controlling technical certification and localized deployment support.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents must defend against substitution from open-source firmware security stacks and hyperscaler-integrated IoT platforms that bundle security as loss-leader infrastructure, eroding standalone vendor pricing power across Asia Pacific procurement teams.
For Market Incumbents: Fortify embedded hardware trust module supply through captive allocation agreements with Taiwan foundries, securing priority wafer access ahead of METI and TGA compliance deadline waves. Deepen firmware vulnerability research operations in Tokyo and Taipei to maintain technical differentiation against open-source alternatives. Channel exclusivity renewals in Thailand and Indonesia limit competitive access to mid-tier enterprise segments where price sensitivity concentrates.
For New Entrants and Emerging Players: Post-implementation training and certification services represent an under-served layer where incumbents under-invest, creating white-space for specialized education providers to capture recurring revenue streams. Vietnam's industrial zones in Binh Duong and Bac Ninh offer most penetrable geography ahead of compliance deadline waves. Partner with regional universities to build embedded systems security talent pipelines, feeding directly into enterprise deployment teams under resource constraints.
For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-compression play because binding frameworks across Japan, Australia, and India transform security spending from discretionary to non-negotiable procurement line items. Acquisition targets should exhibit modular certification architectures that satisfy multiple Asia Pacific compliance regimes simultaneously. Watch for de facto harmonization signals from ASEAN regulatory coordination bodies as inflection indicator for cross-border solution scalability.
| Strategic Initiative | Industry Significance |
|---|---|
| Post-Quantum Cryptographic Protocol Migration | Lattice-based encryption pilots in Japan's Aichi Prefecture precede METI binding compliance deadlines. |
| Modular Certification Architecture Development | Multi-framework compliance reduces redundant testing costs across Australia's TGA and India's BIS regimes. |
| Localized Training Pipeline Construction | University partnerships in Tokyo and Singapore address embedded systems security engineer scarcity directly. |
| Exclusive Distributor Network Expansion | Southeast Asian channel control limits competitive access to price-sensitive mid-tier enterprise segments. |
| Managed Security Service Tier Launch | Outsourced monitoring capabilities capture premium pricing from talent-constrained Indian and Australian utilities. |
Research Approach
Cross-validation between primary interviews with IoT platform engineering directors and secondary validation through regulatory filing databases anchors the qualitative findings. Stakeholder roles interviewed include embedded systems security engineers, critical infrastructure procurement officers, channel distribution partners, and compliance certification specialists. Secondary sources span METI guideline documentation, TGA medical device security advisories, BIS certification protocols, and ASEAN regulatory coordination white papers. Bottom-up deployment sizing triangulates against top-down market aggregation across solution type and deployment mode segments.
Sensitivity analysis around compliance deadline timing and foundry capacity utilization shapes the analytical framework across the projection horizon. Segmentation dimensions modeled include solution architecture, deployment mode, industrial vertical, and regulatory jurisdiction cluster. CAGRs derive from installed base growth rates, replacement cycle compression, and compliance-driven retrofit demand. Post-quantum cryptographic migration timelines and hardware trust module penetration curves constitute industry-specific forecast inputs.
Underlying assumptions cover stable regulatory enforcement trajectories in Japan, Australia, and India, with deviation risk concentrated in ASEAN harmonization failure and Taiwan supply disruption scenarios. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cybersecurity
Data Protection Market
Cybersecurity
Global Cyber Threat Intelligence Market
Cybersecurity
Application Programming Interface Security Market
Cybersecurity
Cloud-Based Database Security Market
Cybersecurity
Cloud Endpoint Protection Market
Cybersecurity
Post-Quantum Cryptography Market
Cybersecurity
United Arab Emirates Cybersecurity Market
Cybersecurity
UK Cybersecurity Market
Cybersecurity
Colombia Cybersecurity Market
Cybersecurity
Global Cloud Encryption Market
Cybersecurity
Global Database Security Market
Cybersecurity
Next-Generation Firewall Market
Cybersecurity
Global Content Disarm and Reconstruction Market
Cybersecurity
Global Cyber Data Security Market
Cybersecurity
Wireless Network Security Market
Cybersecurity
Content Delivery Network (CDN) Security Market