
 Colombia Cybersecurity Market | 2026-2036
Colombia Cybersecurity Market Size, Share, and Industry Trends Forecast 2026-2036
Colombia Cybersecurity Market Outlook
Managed security service channels are reshaping how Colombian enterprises procure threat protection, with local integrators and international vendors competing for recurring revenue relationships. Fortinet Inc. anchors its position through hardware-software integration across firewall and SD-WAN portfolios. Cisco Systems Inc. leverages extensive partner networks to sustain enterprise and government access. Palo Alto Networks Inc. specializes in cloud-native security platforms that differentiate its offering from legacy appliance competitors.
Cybersecurity encompasses technologies, processes, and controls designed to protect systems, networks, and data from digital attacks, with encryption standards such as AES-256 and TLS 1.3 forming core defensive layers. Its primary purpose spans confidentiality preservation, integrity assurance, and availability maintenance for critical information assets. Firewall and intrusion detection system solutions command established spending among Colombian financial institutions and government agencies, while cloud-based deployment models represent the fastest-expanding segment as organizations migrate workloads from on-premises data centers. Managed services capture expanding margin pools by converting capital expenditure into operational expenditure structures.
Colombia's Superintendencia de Industria y Comercio enforces personal data protection compliance under Law 1581 of 2012 and Decree 1377 of 2013, creating audit-driven demand for encryption and access control solutions. The Financial Superintendence of Colombia imposes cybersecurity protocols on banks and insurers, mandating incident reporting and resilience testing. Stakeholders must monitor regulatory enforcement intensity and cloud sovereignty requirements as determinants of vendor selection and deployment architecture.
Market Dynamics
Financial institutions in Bogotá and Medellín are redirecting capital from on-premises infrastructure toward cloud-native security architectures, compressing procurement cycles and elevating managed service providers over traditional hardware vendors.
Growth Catalysts
- Law 1581 Compliance Mandate:Colombia's Superintendencia de Industria y Comercio enforces personal data protection audits, forcing banks and insurers to upgrade encryption and access control systems.
- Cloud Migration Acceleration:Mid-market enterprises across Cali and Barranquilla are migrating workloads from legacy data centers, creating immediate demand for scalable threat detection platforms.
- Financial Superintendence Protocols:Mandatory incident reporting and resilience testing requirements imposed on Colombian banks are expanding recurring security service contracts.
Market Restraints
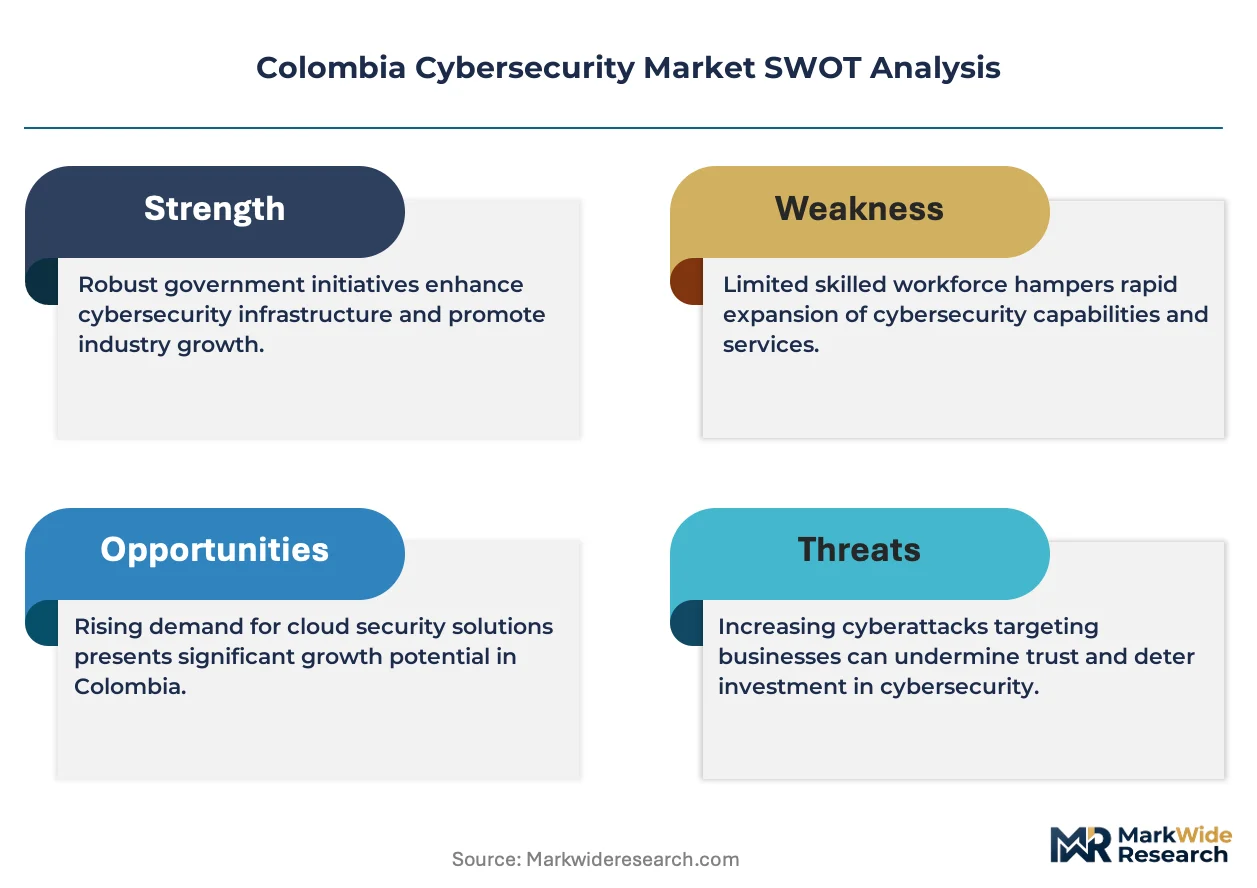
- Specialized Talent Scarcity:Bogotá's cybersecurity labor pool lacks sufficient certified cloud security architects, inflating implementation timelines for complex deployments.
- Import Dependency:Hardware security modules and advanced firewall appliances concentrate sourcing from US and Asian suppliers, exposing buyers to currency fluctuation and shipping delays.
- Legacy Integration Friction:Decades-old core banking systems in Colombian financial institutions resist seamless API connectivity with modern zero-trust architectures.
Strategic Opportunities
- Pacific Coast SME Expansion:Underpenetrated mid-sized manufacturers in Buenaventura and surrounding port zones present greenfield demand for affordable managed detection and response services.
- AI-Augmented Threat Intelligence:Convergence of machine learning analytics with security operations center workflows is opening premium service tiers for Colombian enterprise buyers.
- Decree 1377 Enforcement Intensification:Tighter breach notification requirements are compelling healthcare providers and telecommunications operators to purchase automated compliance monitoring tools.
Industry Challenges
- Certification Bottlenecks:ISO 27001 and SOC 2 audit queues in Colombia stretch six to nine months, delaying vendor qualification for government procurement frameworks.
- Multi-Cloud Complexity:Enterprises adopting hybrid AWS-Azure-Google environments struggle to maintain consistent policy enforcement across fragmented control planes.
- Retention Warfare:Experienced security engineers in Medellín command salary premiums that strain mid-tier integrator margins and project profitability.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Colombia Cybersecurity Market |
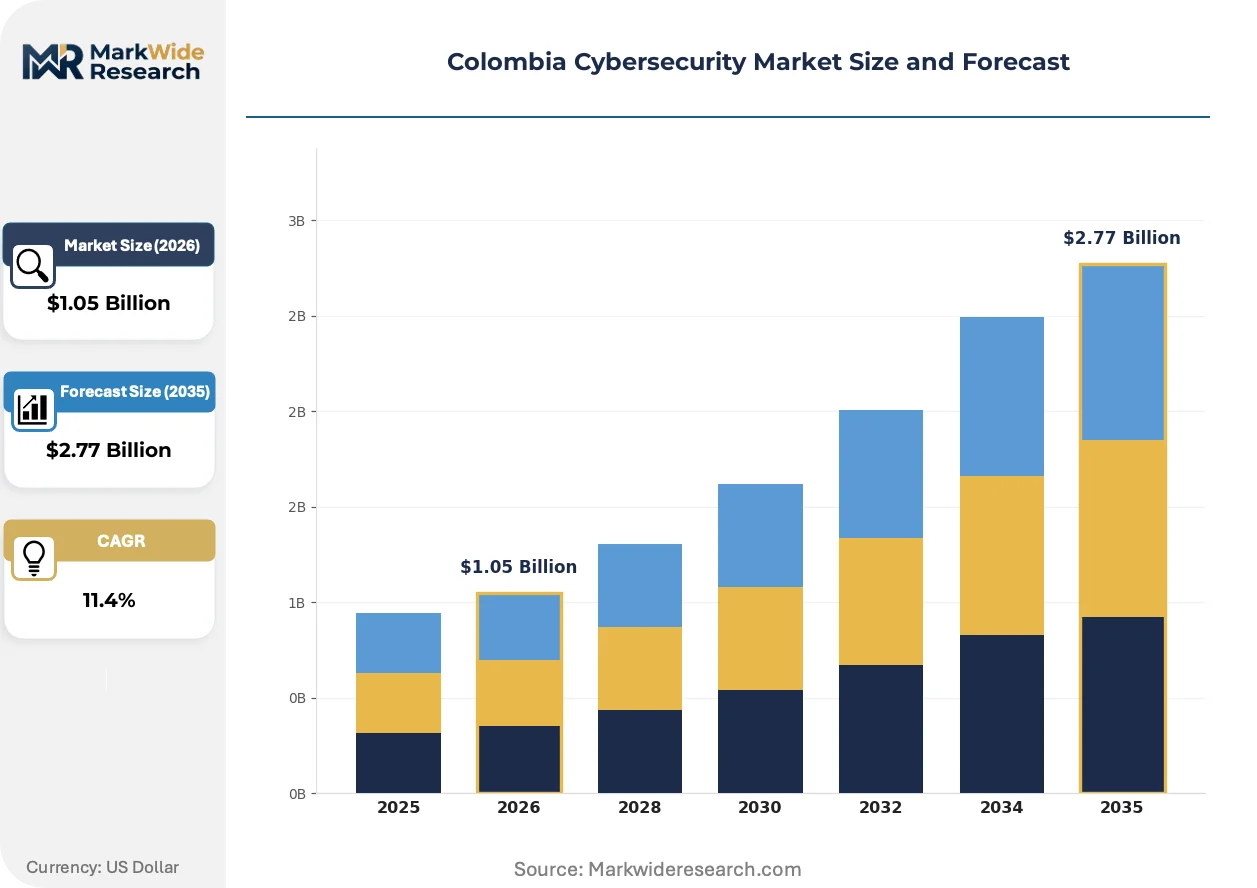
| Market Size in 2026 | $1.05 Billion |
| Market Size in 2035 | $2.77 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Solution Type: Firewall, Antivirus, Intrusion Detection System, Encryption End User Type: Government, Financial Institutions, Healthcare Providers, Retail Deployment Model: On-Premises, Cloud-Based, Hybrid, Managed Services Service Type: Consulting, Implementation, Training, Support |
| Companies Covered | Fortinet Inc., Grupo Oruss, Cisco Systems Inc., GMV, O4IT Colombia SAS, Palo Alto Networks Inc., CrowdStrike Holdings Inc., Entelgy Innotec Security Colombia S.A.S., International Business Machines Corporation (IBM), Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Colombia Cybersecurity Market Strategic Shifts
Colombian enterprise security stacks are fragmenting across cloud, edge, and on-premises domains, forcing vendors to engineer unified control planes that abstract complexity rather than add operational burden.
Extended detection and response platforms are hybridizing endpoint, network, and identity telemetry into single-pane workflows. Large Colombian banks and insurers are piloting these consolidated architectures to reduce mean-time-to-response. This convergence is compressing standalone point-solution vendors into acquisition targets or channel partners.
Colombia's Superintendencia de Industria y Comercio is intensifying Decree 1377 enforcement against delayed breach notifications, triggering procurement of automated incident response orchestration tools. Healthcare providers and e-commerce platforms face the steepest compliance penalties. Vendors are embedding native audit logging and evidence preservation to accelerate buyer certification.
Security purchasing in Colombian mid-market enterprises is consolidating under chief information security officers with direct board reporting lines, displacing IT managers as primary decision-makers. This elevation compresses sales cycles for strategic platforms while marginalizing commodity firewall resellers. Manufacturing and logistics verticals in the Aburrá Valley exhibit the most pronounced CISO empowerment patterns.
Colombia Cybersecurity Market Segmentation
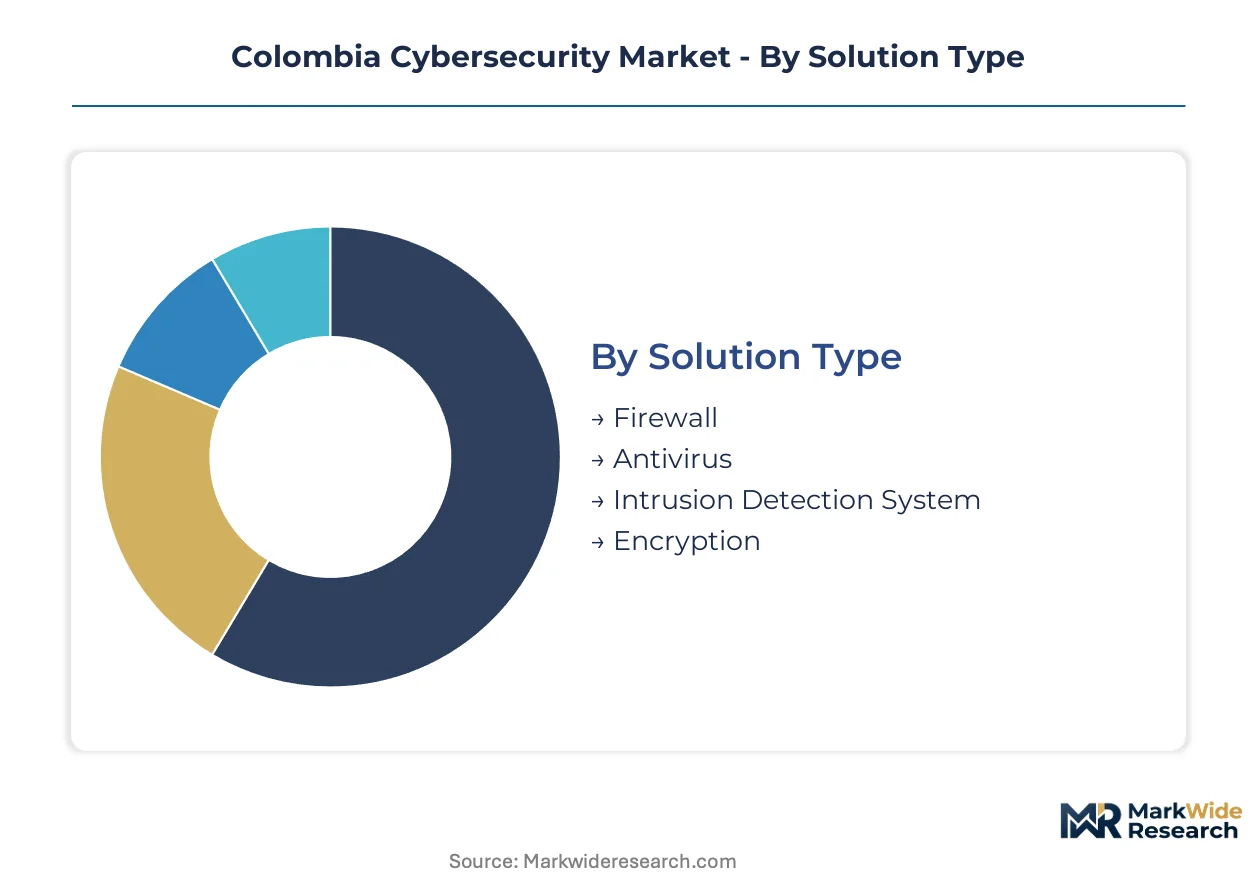
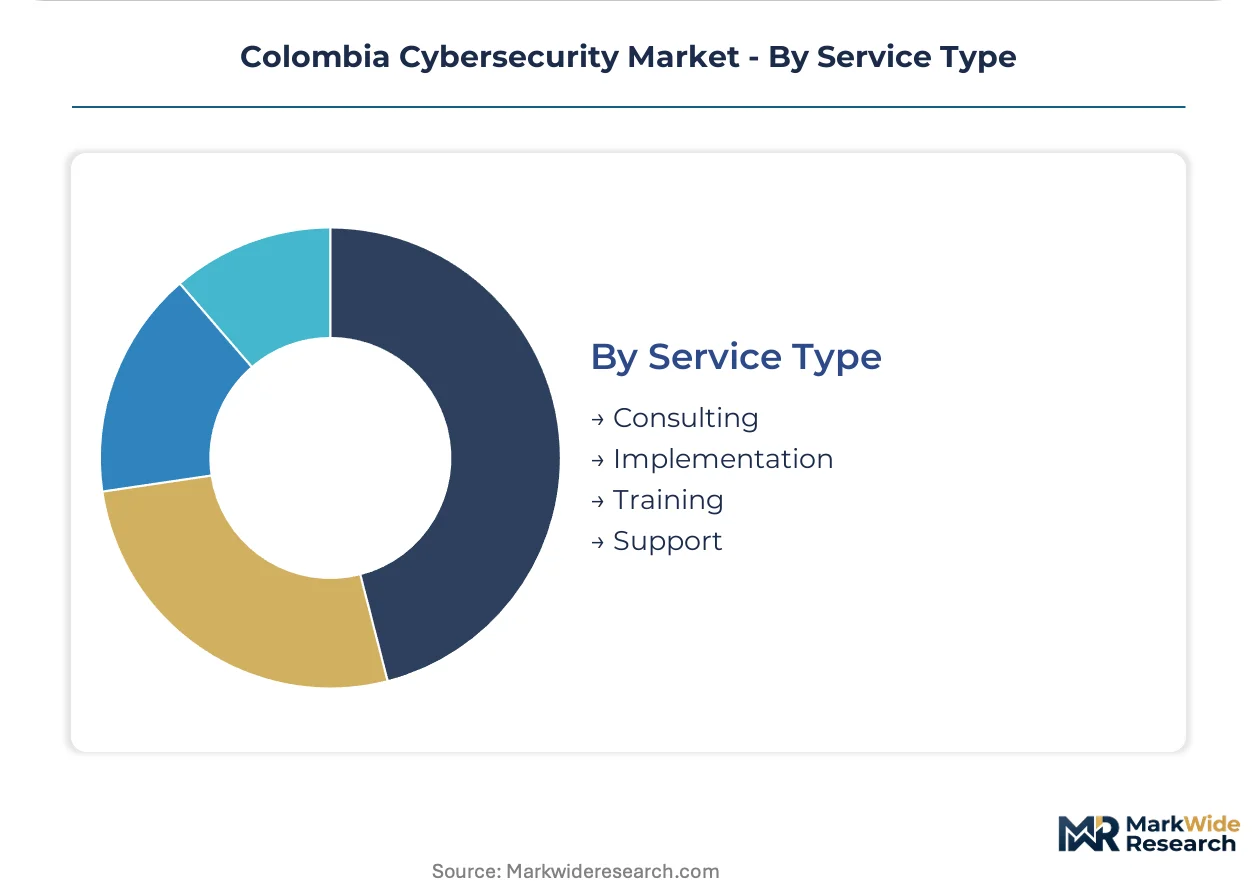
Colombian enterprises structure cybersecurity procurement around four distinct axes that shape vendor positioning and margin capture. Solution type determines technical architecture, end user type dictates compliance intensity, deployment model governs capital structure, and service type influences relationship durability.
Solution Type:
Mature perimeter defenses coexist with emerging cloud-native protections as Colombian organizations navigate hybrid infrastructure transitions.
- Firewall:Network traffic filtering appliances and software dominate capital expenditure budgets at Bogotá financial institutions. Legacy hardware refresh cycles compress as banks migrate toward next-generation firewall platforms with integrated SD-WAN capabilities.
- Encryption:AES-256 and TLS 1.3 implementations expand under Law 1581 audit pressure, with healthcare providers in Cali and Medellín driving demand for data-at-rest and data-in-transit protection. Cloud key management services are displacing on-premises hardware security modules.
- Antivirus:Endpoint protection platforms with behavioral detection capabilities address ransomware threats targeting Colombian SMEs.
- Intrusion Detection System:Network-based and host-based monitoring tools support Superintendencia de Industria y Comercio compliance requirements for critical infrastructure operators.
Firewall handles the majority of throughput; Encryption is the fastest mover on share.
End User Type:
Regulatory intensity varies sharply across sectors, with financial and government verticals commanding premium pricing for certified solutions.
- Financial Institutions:Banks and insurers in Bogotá and Medellín face mandatory incident reporting under Financial Superintendence protocols. Zero-trust architecture deployments and resilience testing contracts concentrate revenue for managed security providers.
- Government:National and departmental agencies procure through centralized frameworks with ISO 27001 certification requirements. Digital transformation initiatives at the national level expand cloud security spending.
- Healthcare Providers:Clinics and hospital networks respond to Decree 1377 breach notification mandates with automated compliance monitoring investments.
- Retail:E-commerce platforms and payment processors in Barranquilla prioritize PCI-DSS alignment and customer data protection.
Financial Institutions command the largest contract values; Healthcare Providers are expanding most quickly as enforcement intensifies.
Deployment Model:
Cost structure preferences divide Colombian buyers between capital-intensive legacy approaches and operational expenditure flexibility.
- Cloud-Based:Scalable threat detection platforms from AWS, Azure, and Google Cloud attract mid-market enterprises in Cali and Barranquilla eliminating data center overhead. Native security controls and third-party cloud workload protection platforms compete for attachment revenue.
- Managed Services:Security operations center outsourcing converts fixed security staffing costs to variable contracts, appealing to resource-constrained manufacturers in the Aburrá Valley. Recurring revenue relationships displace one-time appliance sales.
- On-Premises:Air-gapped environments persist in defense and critical infrastructure sectors with sovereignty requirements.
- Hybrid:Split workloads across cloud and data center demand unified policy enforcement tools.
Managed Services capture expanding margin pools; Cloud-Based deployment shows the steepest expansion trajectory.
Service Type:
Customer maturity determines whether Colombian buyers prioritize advisory relationships or operational execution.
- Consulting:Risk assessments and compliance gap analyses support CISO elevation trends in manufacturing and logistics verticals. Strategic advisory contracts precede technology procurement decisions.
- Implementation:Integration services bridge legacy core banking systems with modern zero-trust architectures, extending project timelines and service revenue.
- Training:Certification programs address specialized talent scarcity in Bogotá's cybersecurity labor market.
- Support:Tiered maintenance contracts sustain vendor relationships post-deployment.
Implementation generates the longest engagement cycles; Consulting is gaining share fastest as strategic buying centralizes under CISO leadership.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates sharply in Bogotá's financial district, where banks absorb 40% premium markups on certified security stacks, while Pacific Coast SMEs in Buenaventura face vendor reluctance and elongated procurement cycles.
Bogotá Capital District
Financial institutions and government agencies drive concentrated demand for zero-trust architectures and compliance-certified encryption. The Superintendencia de Industria y Comercio enforces Law 1581 audits that mandate AES-256 implementations. CISOs at major banks in the Salitre and Usaquén business corridors are consolidating vendor relationships under direct board reporting structures.
Antioquia Department
Medellín's Aburrá Valley manufacturing and logistics clusters are elevating cybersecurity procurement authority from IT managers to dedicated security executives. The Financial Superintendence of Colombia's incident reporting protocols apply to regional bank headquarters. Mid-market enterprises in Envigado and Sabaneta are converting capital expenditure to managed security service contracts.
Valle del Cauca Department
Cali-based healthcare providers and pharmaceutical distributors are responding to intensified Decree 1377 breach notification enforcement with automated compliance monitoring investments. The Superintendencia de Industria y Comercio has issued steeper penalties against delayed disclosures. Cloud migration among mid-market enterprises in the Yumbo industrial zone is accelerating demand for scalable threat detection platforms.
Atlántico Department
Barranquilla's port logistics operators and e-commerce platforms prioritize PCI-DSS alignment for payment processing infrastructure. Retail cybersecurity spending concentrates in the metropolitan trade corridor. Local integrators are competing with international vendors for recurring revenue relationships in an underpenetrated mid-market segment.
Valle del Cauca Pacific Coast
Buenaventura's port-dependent manufacturers and maritime logistics operators present greenfield demand for affordable managed detection and response services. Regulatory enforcement intensity remains lower than in interior cities, depressing pricing power. Vendors are developing tiered service offerings to penetrate this price-sensitive, underpenetrated zone.
Colombia Cybersecurity Market Competitive Environment
Integrated platform vendors and specialized service providers split the market between recurring subscription revenue and project-based implementation fees. The vendor structure concentrates around three strategic archetypes: multinational hardware-software integrators with firewall-SD-WAN portfolios, cloud-native platform specialists, and local managed security service providers with regulatory compliance expertise. Dominant competitive moves include strategic partnerships with systems integrators and geographic expansion through channel partner networks.
Within the multinational platform tier, Fortinet Inc. and Cisco Systems Inc. occupy positions anchored by hardware-software integration capabilities and extensive partner ecosystems respectively. Palo Alto Networks Inc. exemplifies the cloud-native specialist archetype. Among Colombia-based service providers, Grupo Oruss and O4IT Colombia SAS represent the local integrator segment competing for mid-market recurring contracts. These named entities serve as anchor points for understanding competitive positioning without asserting specific strategic actions or financial performance.
| Leading Market Players |
|---|
| Fortinet Inc. |
| Grupo Oruss |
| Cisco Systems Inc. |
| GMV |
| O4IT Colombia SAS |
| Palo Alto Networks Inc. |
| CrowdStrike Holdings Inc. |
| Entelgy Innotec Security Colombia S.A.S. |
| International Business Machines Corporation (IBM) |
| Others |
Value Chain & Pricing Dynamics
The Buenaventura-Pacific freight corridor's elevated logistics costs amplify supply concentration effects for Colombian cybersecurity vendors, compressing margins on hardware-dependent solutions while enabling premium pricing for cloud-native alternatives that bypass physical distribution chokepoints. Bogotá financial institutions absorb certification-driven markups that Pacific Coast SMEs reject, fragmenting pricing power across geography.
Pricing Analysis
The customization-premium spread separates configured-to-order zero-trust deployments from standard firewall appliances, with subscription-based SaaS tiers dominating recurring revenue structures. Price differentiation hinges on ISO 27001 certification grade and vertical integration depth, as vendors with captive professional services command higher attach rates. Pricing pressure stems from mid-market buyers converting capital expenditure to operational expenditure models. Government agencies exhibit lowest price sensitivity due to procurement framework rigidity, while Buenaventura manufacturers demand economy-tier managed detection and response offerings.
Supply Chain Analysis
Contract-manufacturing concentration rests with Taiwanese and Chinese EMS providers for firewall appliances, while US-based cloud infrastructure operators anchor software delivery. Hardware security modules draw from South Korean and German component suppliers, with TLS 1.3 certificate authorities concentrated in US and European trust anchors. Single-source vulnerability pervades advanced threat intelligence feeds, as Colombian integrators depend on foreign-sourced IP reputation databases. Distribution runs through Bogotá-based systems integrators with Medellín and Cali satellite offices, bypassing direct vendor relationships outside capital district financial corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The acute shortage of certified cloud security architects in Bogotá and Medellín constrains implementation velocity, creating asymmetric returns for stakeholders who secure this capability layer before competitors.
For Market Incumbents: Build switching-cost moats through embedded professional services that integrate legacy core banking systems with modern zero-trust architectures, converting one-time appliance sales into decade-long managed service relationships. Deepen API connectivity investments to resist displacement by cloud-native platform specialists. Prioritize certification queue positioning for ISO 27001 and SOC 2 audits to maintain government procurement eligibility. For New Entrants and Emerging Players: Pursue underpenetrated mid-sized manufacturers in Buenaventura and Pacific Coast port zones with tiered managed detection and response offerings priced below Bogotá financial district benchmarks. Target healthcare providers in Cali responding to intensified Decree 1377 enforcement with automated compliance monitoring tools. Lead with channel partnerships through local integrators rather than direct enterprise sales to bypass incumbent relationship barriers. For Investors and Strategic Acquirers: Local managed security service providers with established Superintendencia de Industria y Comercio compliance expertise and recurring revenue concentration present the most defensible acquisition archetype. Long-term viability across the analysis window hinges on cloud migration acceleration sustaining operational expenditure conversion trends. Monitor certification bottleneck resolution timelines at Colombian ISO 27001 audit bodies as inflection indicator for vendor qualification velocity and market access expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Zero-Trust Architecture Deployment | Financial Superintendence protocols mandate incident reporting that legacy perimeter defenses cannot satisfy. |
| Managed Security Service Expansion | Mid-market enterprises in Aburrá Valley convert fixed staffing costs to variable operational expenditure structures. |
| Cloud-Native Platform Migration | AWS, Azure, and Google Cloud native controls displace on-premises hardware security modules in Cali. |
| Compliance Automation Investment | Decree 1377 enforcement intensification drives automated breach notification tools for healthcare providers. |
| Channel Partner Network Deepening | Local integrators in Barranquilla compete for recurring revenue relationships in underpenetrated retail segments. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with CISOs at Bogotá financial institutions, Medellín manufacturing security directors, Cali healthcare compliance officers, and channel partners across Barranquilla. Secondary validation drew from Superintendencia de Industria y Comercio enforcement records, Financial Superintendence of Colombia regulatory circulars, hyperscaler capex disclosures, and customs data on hardware security module imports. Bottom-up segment sizing triangulated against top-down macroeconomic anchors.
Calibration across the analysis window employed scenario-weighted projections with elasticity adjustments for cloud migration velocity and regulatory enforcement intensity. Segmentation dimensions modeled include solution type, deployment model, end-user vertical, and service tier complexity. CAGRs derived from historical trajectory analysis modified by technology substitution curves and compliance-driven replacement cycles. Inputs incorporated talent scarcity indices and certification queue lengths as Colombia-specific demand constraints.
The forecast holds incumbent behavior within observed patterns; aggressive moves by cloud-native platform specialists or accelerated Decree 1377 penalty escalation would shift outcomes materially. Cross-checking against Financial Superintendence incident reporting frequency trends is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cybersecurity
Europe Data Exfiltration Market
Cybersecurity
V2X Cybersecurity Market
Cybersecurity
Malaysia Cybersecurity Market
Cybersecurity
Italy Cybersecurity Market
Cybersecurity
Data Center Logical Security Market
Cybersecurity
Cloud Security Gateway Market
Cybersecurity
Quantum Cryptography Market
Cybersecurity
Saudi Arabia Cybersecurity Market
Cybersecurity
Bangladesh Cybersecurity Market
Cybersecurity
Network Sandboxing Market
Cybersecurity
North America Extended Detection and Response Market
Cybersecurity
Network Edge Security Solutions Market
Cybersecurity
5G Security Market
Cybersecurity
Cloud Application Security Market
Cybersecurity
Middle East & Africa AI Cybersecurity Market
Cybersecurity
SOC As a Service Market