
 Global Database Security Market | 2026-2036
Global Database Security Market Size, Share, and Industry Trends Forecast 2026-2036
Global Database Security Market Foresight
Healthcare is decoupling from traditional financial services as the fastest-growing adopter of database security platforms. Oracle sustains deep entrenchment in enterprise data architectures through its integrated cloud and on-premises security stack. IBM leverages decades of mainframe security heritage to dominate high-assurance government and banking deployments. Fortinet competes aggressively at the network-database boundary with converged firewall and database activity monitoring appliances.
Database security encompasses the technologies, policies, and controls that protect database management systems from unauthorized access, data exfiltration, and integrity compromise through encryption, access control, and continuous activity monitoring. Deployment architecture spans on-premises hardware, public cloud instances, hybrid configurations, and virtual private cloud enclosures, with encryption and database activity monitoring solutions commanding premium positioning due to their role in breach containment and forensic traceability. Cloud deployment is expanding fastest as organizations retire legacy data centers, while access control retains mature margin pools in regulated BFSI and government verticals where certification cycles extend sales timelines.
FDA HIPAA rules, EU GDPR enforcement by national data protection authorities, and SEC cybersecurity disclosure mandates are collectively elevating database security from IT expenditure to board-level compliance necessity. The EU AI Act adds algorithmic training data governance requirements that ripple into database audit and lineage controls. Stakeholders must monitor divergence between US federal zero-trust architecture mandates and European data sovereignty localization rules when architecting cross-border database protection strategies.
Market Dynamics
Zero-trust architecture mandates from US federal agencies are forcing enterprise database security vendors to rebuild access control frameworks around continuous verification rather than perimeter defense.
Growth Catalysts
- Ransomware targeting healthcare records:Hospital systems and regional clinics are accelerating procurement of encryption and activity monitoring solutions as patient data extortion incidents multiply.
- EU AI Act training data governance:Multinational enterprises must implement algorithmic lineage tracking and audit controls that ripple into database architecture requirements.
- Cloud migration exhaustion:Organizations retiring on-premises data centers are purchasing hybrid-compatible security stacks to maintain consistent policy enforcement across environments.
Market Restraints
- Certified security talent scarcity:Implementation of database activity monitoring and encryption at scale requires specialized administrators that command premium compensation in tight labor markets.
- Legacy mainframe integration friction:Financial institutions with IBM z/OS environments face extended deployment timelines when layering modern security controls atop decades-old data architectures.
- Cross-border data localization conflicts:Divergence between US federal cloud-first mandates and EU data sovereignty requirements forces redundant infrastructure spending for multinational enterprises.
Strategic Opportunities
- India's digitizing healthcare networks:Hospital chains and diagnostic laboratory networks are building first-generation security infrastructure as CDSCO and RBI data protection rules tighten.
- Converged firewall-database monitoring appliances:Vendors bundling network edge protection with database activity surveillance are capturing mid-market buyers seeking simplified vendor management.
- SEC cybersecurity disclosure mandates:Public companies must document database breach preparedness, creating pull-through demand for forensic-ready audit and encryption solutions.
Industry Challenges
- Multi-generational database coexistence:Enterprises operate Oracle, PostgreSQL, MongoDB, and cloud-native warehouses simultaneously, fragmenting security policy enforcement and incident response workflows.
- Encryption performance overhead:Real-time analytics workloads resist transparent data encryption due to latency penalties, forcing security architects into compromise configurations that auditors question.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Database Security Market |
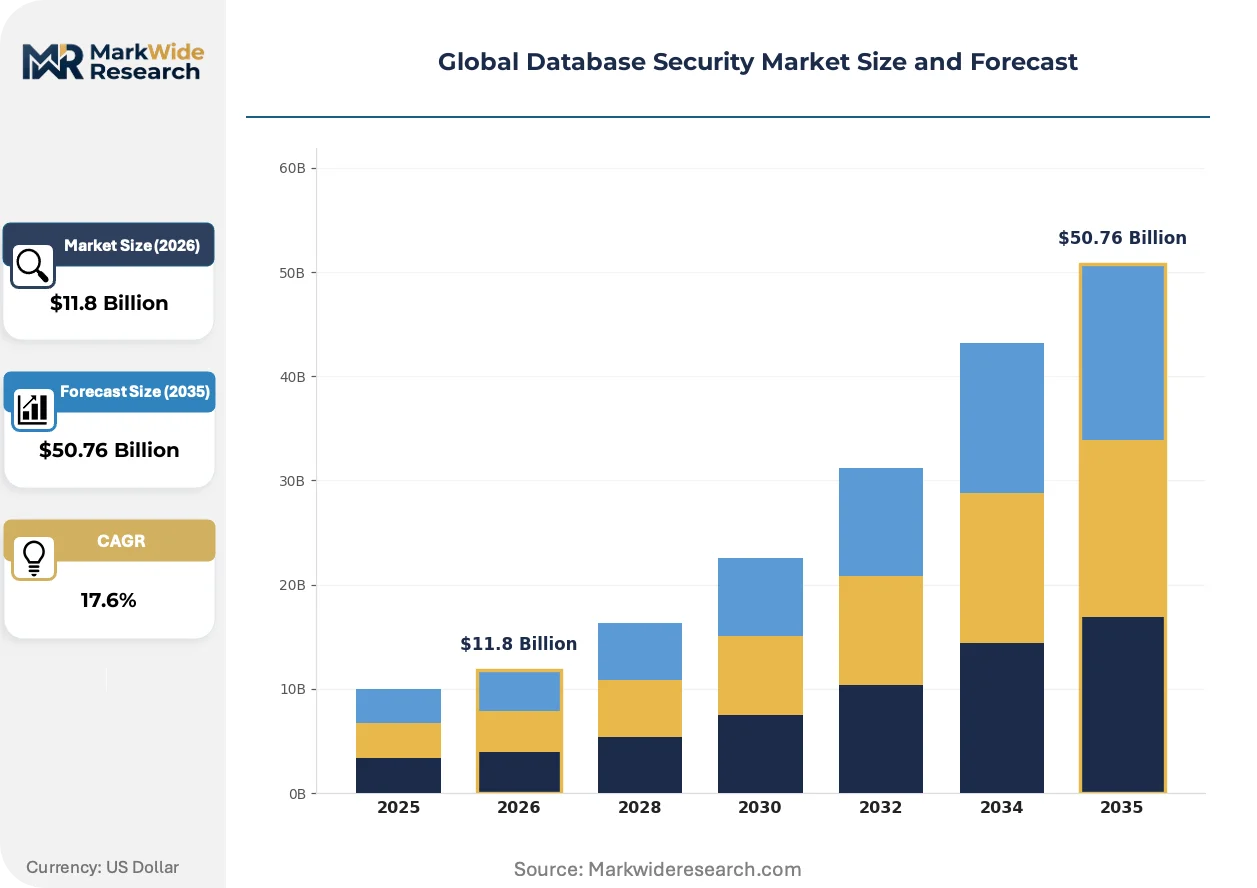
| Market Size in 2026 | $11.8 Billion |
| Market Size in 2035 | $50.76 Billion |
| CAGR (2026 – 2036) | 17.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premises, Cloud, Hybrid, Virtual Private Cloud Solution: Data Masking, Database Activity Monitoring, Encryption, Access Control, Backup & Recovery Application: Fraud Detection, Regulatory Compliance, Insider Threat Protection, Data Loss Prevention, Identity Management End User: BFSI, Telecom, Government Agencies, Education, Media & Entertainment |
| Companies Covered | IBM, Oracle, Thales, Cisco Systems, Fortinet, McAfee, Imperva, Microsoft, Hewlett Packard Enterprise, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Database Security Market Shifts & Advancements
Database security architecture is pivoting from static perimeter models toward continuous behavioral analytics that flag anomalous access patterns before exfiltration occurs.
Extended detection and response platforms are consolidating database activity monitoring with endpoint and network telemetry into unified security operations dashboards. Financial services and healthcare providers with ISO 27001 mandates are adopting these converged stacks fastest, compressing procurement cycles for standalone database security point products. The integration is consolidating vendor relationships and raising switching costs for enterprises that previously assembled best-of-breed toolchains.
The EU AI Act's algorithmic accountability requirements are mandating training data provenance documentation that database audit systems must now support. Organizations deploying machine learning pipelines must implement lineage tracking that connects model outputs to specific database records and transformation histories. Pharmaceutical and financial services firms with cross-border operations are most affected, reconfiguring data warehouse architectures to satisfy both GDPR retention limits and AI Act audit trails.
Security procurement committees are displacing sole IT department ownership as HIPAA business associate agreements and SEC disclosure rules elevate database breach liability to board-level concern. Hospitals and publicly traded manufacturers now involve legal compliance officers and risk committees in vendor selection, extending sales cycles but increasing contract values for solutions with documented regulatory mappings. This pattern is most visible in US healthcare and critical infrastructure sectors where federal agencies designate specific security frameworks.
Global Database Security Market Segmentation
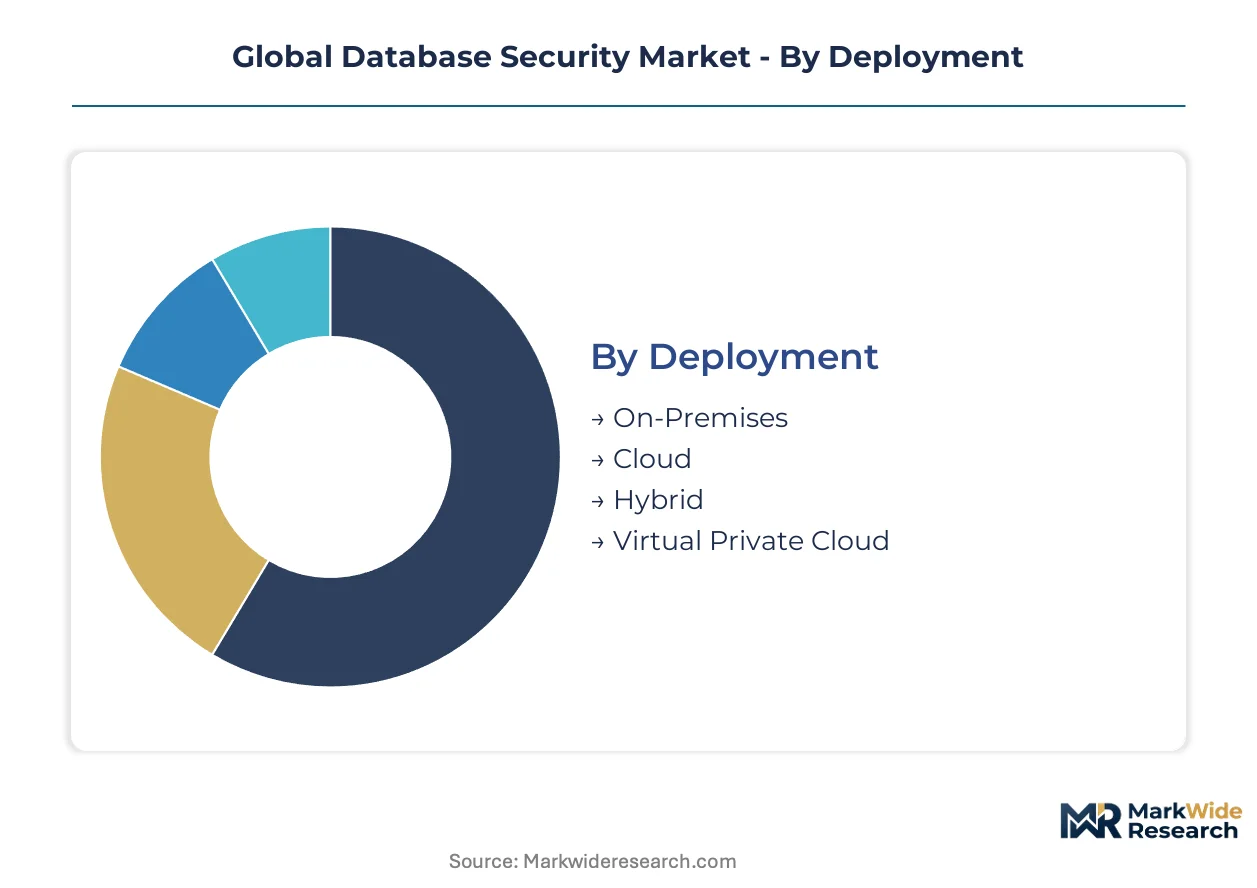
Database security procurement splits sharply between volume-driven cloud deployments and premium-priced on-premises installations. Understanding these segment boundaries reveals where vendors capture margin versus where they chase scale.
Deployment:
Cloud configurations dominate transaction volume while on-premises retains pricing power in regulated environments.
- On-Premises:Hardware-anchored installations within enterprise data centers deliver maximum control over encryption key management and audit logging. Demand concentrates in German automotive manufacturers and Swiss pharmaceutical headquarters where GDPR and FDA validation requirements mandate physical infrastructure oversight.
- Cloud:Public cloud instances offer elastic scaling for seasonal analytics workloads and rapid disaster recovery provisioning. US healthcare systems undergoing federal cloud migration mandates represent the steepest expansion trajectory, though data residency concerns slow adoption for cross-border patient records.
- Hybrid:Split architectures maintain sensitive workloads on-premises while bursting analytics to public cloud.
- Virtual Private Cloud:Isolated cloud enclosures provide dedicated network segments for single-tenant security policies.
Today's leader: On-Premises. Tomorrow's challenger: Cloud.
Solution:
Functional specialization separates commodity backup tools from high-margin real-time monitoring platforms.
- Encryption:Transparent data encryption and column-level field protection render breached databases unusable to attackers. Financial services firms in Singapore and London deploy these solutions most aggressively as MAS and FCA operational resilience rules harden.
- Database Activity Monitoring:Continuous query analysis and behavioral profiling detect anomalous access patterns before exfiltration completes. US hospital systems facing HIPAA business associate agreement audits are expanding procurement fastest.
- Data Masking:Production data obfuscation for non-production environments reduces insider exposure.
- Access Control:Role-based and attribute-based permission frameworks govern authentication workflows.
- Backup & Recovery:Point-in-time restoration capabilities satisfy ransomware recovery objectives.
Encryption commands premium positioning. Database Activity Monitoring is gaining share fastest.
Application:
Use-case prioritization reflects vertical-specific threat models and regulatory exposure.
- Regulatory Compliance:Automated audit trails and retention policies map controls to GDPR, HIPAA, and SEC disclosure frameworks. EU-headquartered multinationals facing overlapping AI Act and GDPR enforcement are consolidating procurement around unified compliance platforms.
- Insider Threat Protection:Privileged user monitoring and data exfiltration detection address malicious or negligent employee actions. US defense contractors with CMMC certification requirements anchor demand in this segment.
- Fraud Detection:Real-time transaction pattern analysis identifies synthetic identity and account takeover attempts.
- Data Loss Prevention:Content inspection and egress filtering block unauthorized data movement.
- Identity Management:Lifecycle provisioning and deprovisioning automate access governance.
Regulatory Compliance absorbs the largest budget share. Insider Threat Protection is climbing the fastest.
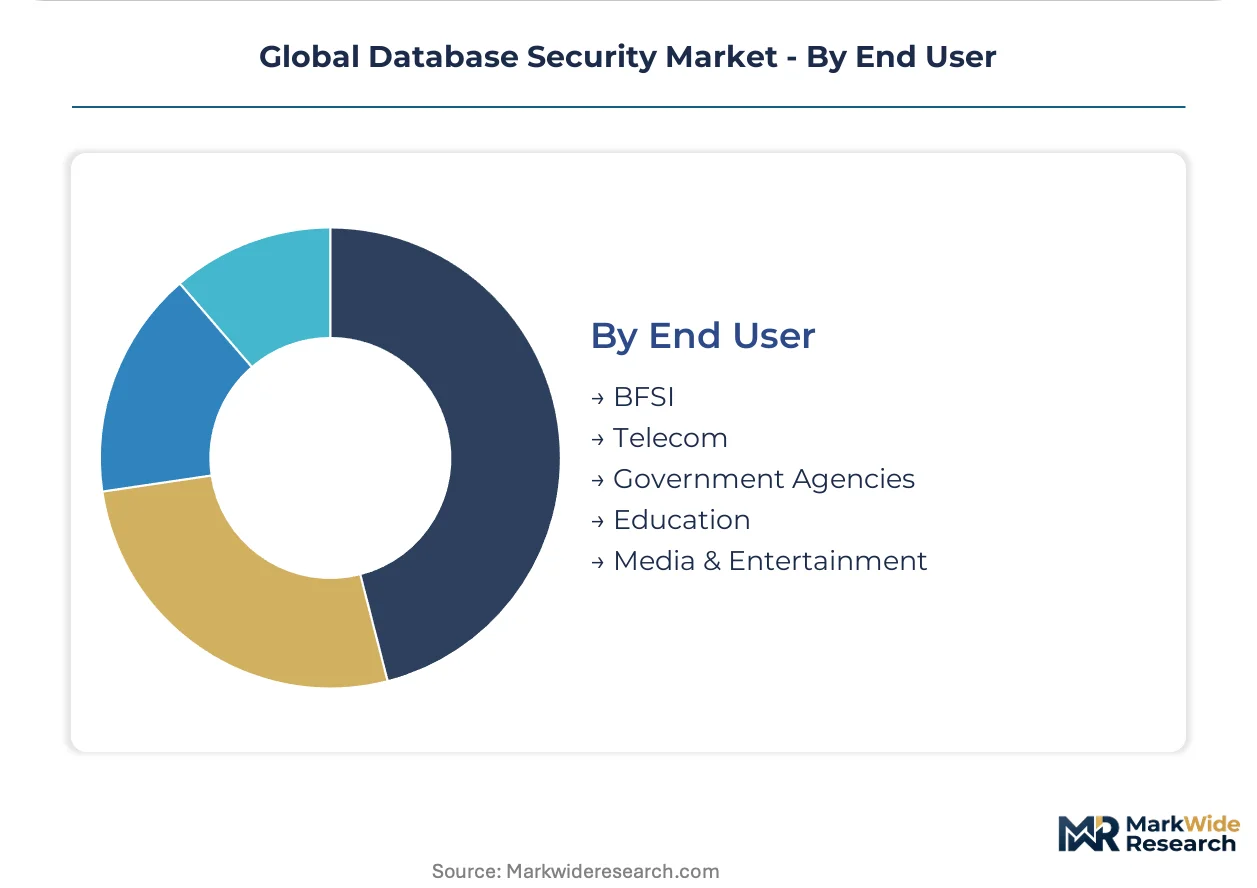
End User:
Vertical buying patterns diverge between compliance-driven procurement and threat-response urgency.
- BFSI:Banks and insurers operate multi-generational database estates spanning mainframe, relational, and cloud-native warehouses. Japanese megabanks and German regional Landesbanks maintain the most complex integration requirements, extending sales cycles but inflating contract values.
- Government Agencies:Federal, state, and municipal entities face zero-trust architecture mandates and critical infrastructure designations. US civilian agencies and UK NHS trusts are accelerating cloud security procurement under executive order timelines.
- Telecom:Subscriber databases and billing systems require high-availability protection against ransomware.
- Education:Research institutions and university medical centers balance open collaboration with student privacy rules.
- Media & Entertainment:Content rights management and subscriber analytics drive database security investment.
BFSI retains the deepest pockets. Government Agencies are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Silicon Valley's cybersecurity corridor drives global database security innovation through concentrated venture funding and federal procurement proximity. The United States anchors investment volume. Germany and Japan sustain premium on-premises demand. India and Brazil emerge as high-growth expansion markets.
United States
Federal cloud migration mandates and zero-trust architecture requirements from civilian agencies accelerate procurement of hybrid-compatible security stacks. SEC cybersecurity disclosure rules elevate database breach preparedness to board-level priority. Hospital systems in Texas and California expand encryption deployments fastest under HIPAA business associate agreement pressure.
Germany
Automotive manufacturers and pharmaceutical headquarters in Stuttgart and Basel-adjacent Baden-Württemberg mandate physical infrastructure oversight for GDPR and FDA validation compliance. Landesbanks maintain complex multi-generational database estates extending sales cycles. The country's data protection authorities enforce algorithmic accountability requirements rippling into audit system procurement.
Japan
Megabanks in Tokyo operate mainframe-anchored architectures requiring specialized integration expertise for modern security layering. METI operational resilience guidelines harden requirements for financial services database protection. Osaka-based manufacturers balance cloud migration with on-premises control for intellectual property databases.
India
Hospital chains and diagnostic laboratory networks in Maharashtra and Karnataka build first-generation security infrastructure as CDSCO and RBI data protection rules tighten. Bangalore's technology corridor attracts cloud-native security vendor expansion. Domestic IT services firms integrate database monitoring into managed security offerings for export markets.
Brazil
Financial institutions in São Paulo accelerate compliance-driven procurement under central bank operational resilience mandates. Healthcare networks in Rio de Janeiro and Minas Gerais address ransomware exposure through encryption investments. The country's national data protection authority enforcement creates pull-through demand for audit-ready database architectures.
Global Database Security Market Competitive Landscape
Strategic partnerships dominate the current landscape as vendors bundle network edge protection with database activity surveillance to capture mid-market consolidation demand. The market structures around three tiers: integrated cloud-native platforms, mainframe-anchored heritage systems, and converged firewall-database appliance specialists. Portfolio diversification and geographic expansion constitute the dominant competitive vectors as vendors address India's digitizing healthcare networks and Brazil's compliance-driven financial sector.
Within the integrated platform tier, Oracle and Microsoft exemplify cloud-native breadth, while IBM occupies a position representing mainframe-anchored heritage deployments. Fortinet sits within the converged appliance specialist archetype, capturing buyers seeking simplified vendor management at the network-database boundary. These three anchors span the strategic spectrum from elastic cloud scaling to high-assurance government certification cycles.
| Leading Market Players |
|---|
| IBM |
| Oracle |
| Thales |
| Cisco Systems |
| Fortinet |
| McAfee |
| Imperva |
| Microsoft |
| Hewlett Packard Enterprise |
| Others |
Supply & Pricing Matrix
Federal cloud migration mandates from US civilian agencies are compressing procurement timelines for hybrid-compatible security stacks, forcing vendors to absorb certification costs upfront while competing on subscription pricing models that trade immediate margin for multi-year contract lock-in.
Pricing Analysis
Input-cost pass-through from specialized security engineering talent and FedRAMP certification overhead shapes tiered pricing structures across the market. Pricing stratifies across premium, standard, and economy tiers, with premium tiers commanding separation through Common Criteria certification and dedicated key management infrastructure. Cost compression in the standard tier is intensifying because mid-market buyers consolidate vendor relationships around converged firewall-database appliances. Healthcare systems with HIPAA business associate agreement exposure demonstrate highest price sensitivity, while defense contractors with CMMC mandates exhibit lowest sensitivity due to budgetary insulation from critical infrastructure designations.
Supply Chain Analysis
Freight and logistics costs for hardware security modules and on-premises appliance shipments from manufacturing centers in Taiwan, Israel, and the United States feed into landed pricing for regulated deployments. Component sourcing draws from semiconductor fabrication in Taiwan, specialized encryption chip design in Israel, and systems integration in the United States. Single-source vulnerability concentrates in hardware security module substrate supply. Distribution runs through value-added resellers with vertical specialization in government and healthcare certification pathways.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds regulatory demand through overlapping enforcement timelines, with the EU AI Act's algorithmic accountability requirements now layering atop GDPR retention mandates to force architectural reconfiguration.
For Market Incumbents: Deploy certification acceleration as the primary lever. IBM and Oracle should deepen mainframe-cloud bridge investments to capture extended deployment timelines at German Landesbanks and Japanese megabanks. Fortinet must harden converged appliance positioning against pure-play database activity monitoring specialists threatening mid-market consolidation gains. Cloud-native platforms face margin pressure from hyperscaler bundling.
For New Entrants and Emerging Players: Regional hospital chains in India's Maharashtra and Karnataka represent the most penetrable buyer archetype, with first-generation security infrastructure needs unmet by legacy vendor channel density. CDSCO data localization rules create procurement urgency without entrenched incumbent relationships. A cloud-native, API-first deployment model with RBI compliance pre-certification offers the clearest go-to-market angle.
For Investors and Strategic Acquirers: Asymmetric upside sits with converged security platform specialists possessing both network edge and database telemetry capabilities. Long-term viability hinges on cross-selling coefficient expansion across the projection horizon. Acquisition targets should demonstrate FedRAMP or Common Criteria certification momentum. The signal to watch is hyperscaler partnership announcement velocity as distribution channel validation.
| Strategic Initiative | Industry Significance |
|---|---|
| FedRAMP Certification Acceleration | US civilian agencies mandate this designation for cloud procurement, creating vendor exclusion thresholds. |
| EU AI Act Lineage Integration | Pharmaceutical firms in Basel-adjacent Baden-Württemberg require audit trail connectivity to training data repositories. |
| Converged Appliance Development | Mid-market buyers in Texas hospital systems seek simplified vendor management at the network-database boundary. |
| India Healthcare Channel Buildout | Diagnostic laboratory networks in Bangalore lack incumbent security vendor density for first-generation deployments. |
| Mainframe-Cloud Bridge Investment | Japanese megabanks in Tokyo require specialized integration expertise for z/OS security layering. |
Research Methodology
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region combined with secondary validation. Interviews with CISOs at US hospital systems, compliance officers at German automotive manufacturers, and procurement leads at Japanese megabanks anchored demand-side assessment. Secondary sources include SEC cybersecurity disclosure filings, EDPB enforcement action databases, and METI operational resilience guidelines. Bottom-up segment sizing triangulated against top-down IT security spending benchmarks.
Rate-of-change decomposition across deployment models, solution types, and vertical end-uses structured the analytical framework over the projection horizon. Segmentation dimensions modeled include on-premises versus cloud-native deployment, encryption versus activity monitoring functional specialization, and healthcare versus BFSI versus government vertical buying patterns. CAGRs derived from regression against historical IT security procurement cycles and regulatory enforcement intensity indices. Forecast inputs incorporated HIPAA audit frequency trends and EU AI Act implementation timelines.
Underlying measurement precision varies by segment; cloud deployment projections carry tighter precision than legacy mainframe integration estimates due to disclosed hyperscaler capex trajectories. Forecasts reflect assumptions about regulatory enforcement continuity and certification backlog clearance rates. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cybersecurity
Managed SIEM Service Market
Cybersecurity
North America Data Exfiltration Market
Cybersecurity
United States Cybersecurity Market
Cybersecurity
Data Protection Market
Cybersecurity
Threat Intelligence Market
Cybersecurity
Cloud Siem Market
Cybersecurity
China Cybersecurity Market
Cybersecurity
Cyber Warfare Market
Cybersecurity
Germany Ransomware Protection Market
Cybersecurity
SD-WAN Security Market
Cybersecurity
Thailand IT and Security Market
Cybersecurity
Global Cyber Data Security Market
Cybersecurity
Digital Security Market
Cybersecurity
Middle East Cybersecurity Market
Cybersecurity
Quantum Cryptography Market
Cybersecurity
Spain Cybersecurity Market