
 United Arab Emirates Cybersecurity Market | 2026-2036
United Arab Emirates Cybersecurity Market Size, Share, and Industry Trends Forecast 2026-2036
United Arab Emirates Cybersecurity Market Analytics
Quantum-resistant encryption algorithms are recalibrating procurement priorities for federal and banking clients across the Emirates. Help AG leverages its sovereign security operations center to anchor high-assurance contracts with UAE government entities. Palo Alto Networks competes through integrated platform consolidation, reducing agent sprawl for enterprise customers. DarkMatter specializes in hardware-rooted trust architectures, sustaining differentiation in defense-adjacent segments where foreign vendors face access constraints.
Cybersecurity encompasses the technologies, processes, and controls designed to protect systems, networks, and data from digital attacks, with specifications including AES-256 encryption, sub-100-millisecond threat detection latency, and zero-trust network architecture enforcement. Its primary purpose is ensuring confidentiality, integrity, and availability of information assets across critical infrastructure and commercial operations. Cloud-Based deployment now captures the fastest expansion as UAE enterprises migrate workloads to Microsoft Azure and AWS Dubai regions, while On-Premises retains dominance in classified government environments where data sovereignty mandates physical control. Endpoint Security leads product type demand due to proliferating remote work devices, yet Identity Management represents the emerging margin pool as privileged access breaches multiply across finance and healthcare verticals.
MOHAP and the UAE National Cybersecurity Council jointly enforce data protection standards for healthcare and critical infrastructure operators, with non-compliance triggering operational suspension. The UAE Information Assurance Regulation aligns federal agencies with NIST-derived controls, creating certified procurement lists that shape vendor market access. BIS-equivalent conformity assessments for imported security hardware add another compliance layer for international suppliers. Stakeholders must monitor evolving quantum computing timelines to calibrate cryptographic refresh cycles before legacy protections become computationally obsolete.
Market Dynamics
The UAE's National Cybersecurity Council mandates and zero-trust framework adoption are compressing procurement cycles across federal and banking sectors, forcing incumbent vendors to recertify architectures against sovereign data residency requirements.
Growth Catalysts
- Critical Infrastructure Mandates:MOHAP and the UAE National Cybersecurity Council jointly enforce data protection standards for healthcare operators, with non-compliance triggering operational suspension and accelerating security procurement.
- Cloud Migration Velocity:UAE enterprises migrating workloads to Microsoft Azure and AWS Dubai regions require cloud-native security architectures, expanding the addressable market for managed detection and response services.
- Quantum-Resistant Standards:Federal banking clients across the Emirates are recalibrating cryptographic refresh cycles ahead of anticipated quantum computing timelines, creating replacement demand for post-quantum encryption modules.
Market Restraints
- Hardware Import Friction:BIS-equivalent conformity assessments for imported security hardware add compliance layers and extend delivery timelines for international suppliers serving classified government environments.
- Talent Concentration Risk:Deep cybersecurity expertise clusters in Dubai and Abu Dhabi, leaving Sharjah and northern emirates underserved and inflating compensation costs for specialized security architects.
- Sovereign Architecture Lock-in:Help AG's sovereign security operations center anchors high-assurance contracts, creating access barriers for foreign vendors without local data center presence or Emirati partnership structures.
Strategic Opportunities
- Ras Al Khaimah Industrial Expansion:Underpenetrated manufacturing zones outside Dubai are digitizing operations, creating first-mover openings for industrial control system security providers.
- Identity-First Convergence:Privileged access breaches multiplying across finance and healthcare verticals are merging identity management with endpoint security, opening margin pools for unified platform vendors.
- Federal Certification Lists:The UAE Information Assurance Regulation creates certified procurement lists that shape vendor market access, rewarding early compliance investment with preferred supplier status.
Industry Challenges
- Zero-Trust Integration Complexity:Legacy on-premises infrastructure in classified government environments resists seamless zero-trust architecture deployment, requiring costly parallel system operation during transition periods.
- Post-Quantum Talent Scarcity:Cryptographic engineering expertise for quantum-resistant algorithm implementation remains concentrated among a handful of specialized practitioners, constraining deployment velocity for federal clients.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United Arab Emirates Cybersecurity Market |
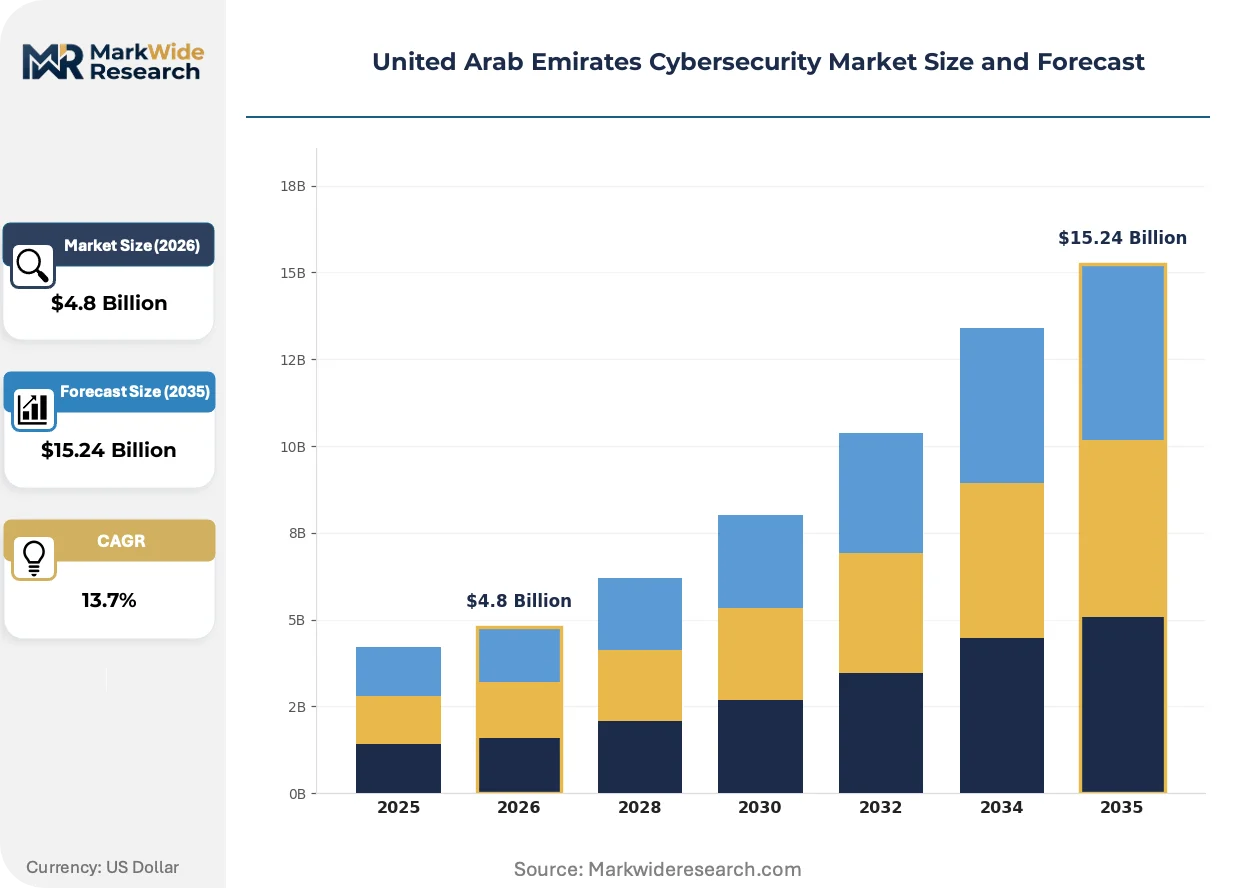
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $15.24 Billion |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Firewall, Endpoint Security, Identity Management, Intrusion Detection Deployment: On-Premises, Cloud-Based, Hybrid, Managed Services End User: Government, Finance, Healthcare, Education Solution: Threat Intelligence, Risk Management, Vulnerability Assessment, Incident Response |
| Companies Covered | Help AG, Injazat Data Systems, Etisalat Digital, CPX, DarkMatter, Cisco Systems, Palo Alto Networks, Microsoft, Fortinet, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United Arab Emirates Cybersecurity Market Evolving Landscape
Security architecture consolidation is displacing point-solution procurement across UAE enterprises, with buyers prioritizing integrated platforms that reduce agent sprawl and unify policy enforcement across cloud and on-premises workloads.
Extended detection and response platforms are modularizing security operations by unifying telemetry from endpoints, networks, and cloud workloads into single-pane analysis environments. Large federal contractors and banking consortia in Dubai are adopting these architectures within compressed eighteen-month procurement windows. This modularity is compressing vendor count per enterprise, favoring Palo Alto Networks-style platform consolidation over best-of-breed point solutions.
The UAE Information Assurance Regulation aligns federal agencies with NIST-derived controls, mandating continuous monitoring and automated compliance reporting for critical infrastructure operators. Industrial consequence includes mandatory security operations center staffing minimums for energy and telecommunications providers. Defense-adjacent segments where foreign vendors face access constraints are responding by cultivating local system integrator partnerships to satisfy sovereign content requirements.
Managed security service procurement is displacing in-house security operations among mid-market enterprises in Abu Dhabi's healthcare and education verticals. Subscription-based detection and response contracts are replacing capital-intensive appliance purchases and dedicated security team builds. This behavioral shift is most visible among private hospital groups consolidating IT functions under regional managed service providers to satisfy MOHAP audit requirements without expanding headcount.
United Arab Emirates Cybersecurity Market Segmentation
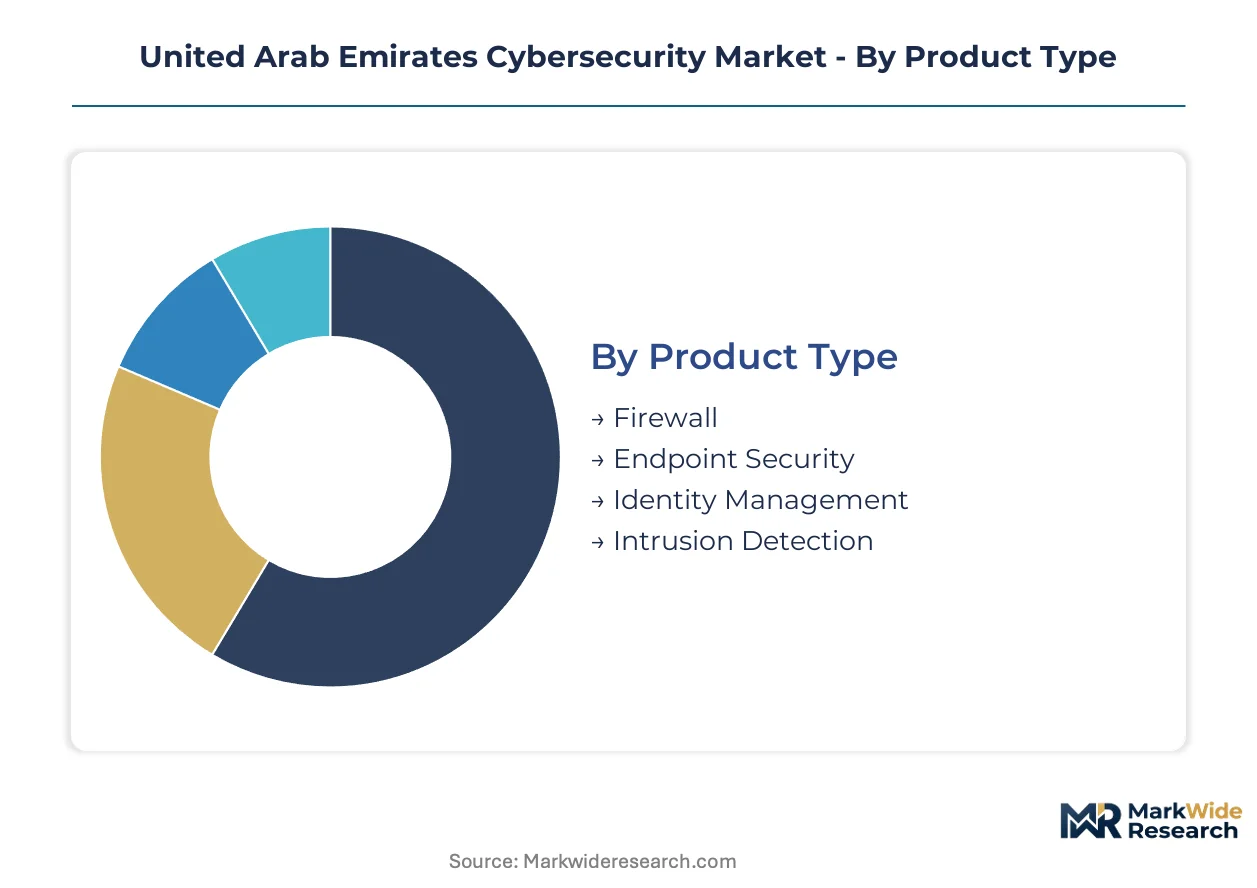
Cybersecurity procurement across the Emirates fragments along four intersecting dimensions: product architecture, infrastructure location, institutional buyer type, and operational solution scope. Each segmentation axis reveals distinct margin pools and competitive access routes for vendors navigating federal certification requirements.
Product Type:
Supply concentration for core defensive technologies clusters around Dubai's technology corridors, where sovereign data residency mandates shape vendor qualification pathways.
- Endpoint Security:Agent-based protection for laptops, mobile devices, and IoT endpoints with sub-100-millisecond threat detection latency. Demand concentrates in Abu Dhabi's finance sector as remote work proliferation multiplies attack surfaces across banking consortia. Procurement cycles compress under MOHAP audit pressure for healthcare operators.
- Identity Management:Privileged access control and multi-factor authentication systems with zero-trust policy enforcement. Federal agencies in Dubai prioritize these architectures after UAE National Cybersecurity Council mandates tightened credential governance standards. Margin expansion follows as breaches expose insider threat vulnerabilities.
- Firewall:Network perimeter defense with deep packet inspection and application-layer filtering capabilities. Government entities in classified environments sustain demand despite cloud migration trends.
- Intrusion Detection:Signature and behavioral analysis systems for anomalous traffic identification. Critical infrastructure operators deploy these under continuous monitoring requirements.
Today's leader: Endpoint Security. Tomorrow's challenger: Identity Management.
Deployment:
Customer type and risk tolerance split procurement between capital-intensive ownership models and operational expenditure approaches.
- Cloud-Based:Native security controls integrated with Microsoft Azure and AWS Dubai regions, featuring API-driven policy orchestration. Enterprises migrating workloads to UAE sovereign cloud zones require these architectures, expanding addressable market for detection and response services. Procurement accelerates as data residency certifications mature.
- Managed Services:Subscription-based security operations center functions with 24/7 threat monitoring and incident response. Mid-market healthcare and education groups in Abu Dhabi consolidate IT functions under regional providers to satisfy compliance without headcount expansion. Behavioral shift displaces capital-intensive appliance purchases.
- On-Premises:Hardware appliances and software licenses deployed within customer-controlled facilities. Classified government environments retain this model under physical data sovereignty mandates.
- Hybrid:Split architectures combining cloud-native controls with on-premises enforcement for sensitive workloads. Transitional deployments bridge legacy infrastructure and modern zero-trust requirements.
Cloud-Based deployment climbs fastest as sovereign cloud certifications expand. Managed Services capture margin expansion in compliance-heavy verticals.
End User:
Application context determines specification intensity and procurement authority concentration across institutional buyers.
- Government:Federal and emirate-level agencies with classified information systems requiring hardware-rooted trust architectures. UAE Information Assurance Regulation mandates continuous monitoring and certified procurement lists that restrict vendor access. Defense-adjacent segments cultivate local partnerships to satisfy sovereign content requirements.
- Finance:Banking consortia and insurance operators under central bank supervision with quantum-resistant encryption refresh cycles. Dubai's financial free zones accelerate procurement of integrated platforms reducing agent sprawl. Non-compliance penalties tighten security budgets.
- Healthcare:Hospital groups and clinics under MOHAP jurisdiction with patient data protection mandates. Private operators outsource security operations to regional managed service providers for audit readiness.
- Education:Universities and K-12 institutions with research data and student information systems. Procurement lags other verticals but accelerates under federal critical infrastructure designation expansion.
Government vertical anchors high-assurance contract values. Finance vertical drives technology refresh velocity.
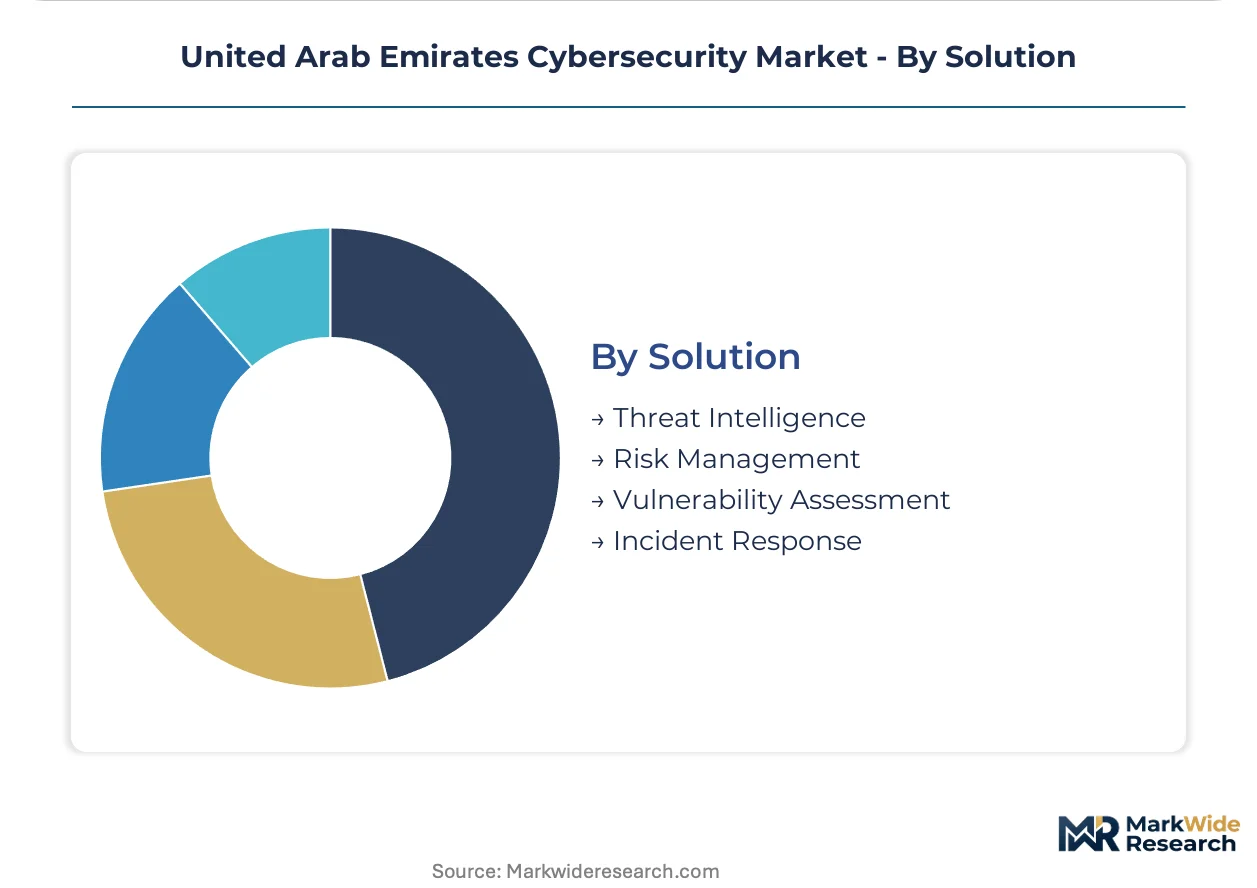
Solution:
Maturity differentiation separates preventive, detective, and responsive capabilities across the security operations lifecycle.
- Threat Intelligence:External data feeds and adversary behavior analytics informing proactive defense posture. Federal contractors integrate these with extended detection platforms for unified telemetry analysis.
- Incident Response:Retainer-based forensic and containment services activated upon breach detection. Banking consortia in Dubai contract specialized providers for regulatory notification compliance.
- Risk Management:Quantitative assessment frameworks aligning security investment with business impact. Enterprise governance programs adopt these for board-level reporting.
- Vulnerability Assessment:Automated scanning and penetration testing identifying configuration weaknesses. Continuous deployment pipelines integrate these for DevSecOps maturity.
Threat Intelligence commands premium positioning. Incident Response gains share as breach disclosure requirements tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Dubai's financial free zones anchor cybersecurity demand concentration across the Emirates, with sovereign data residency mandates compressing procurement cycles for cloud-native architectures. Federal certification requirements under the UAE Information Assurance Regulation shape vendor access patterns nationwide.
Dubai
Banking consortia in Dubai International Financial Centre accelerate zero-trust framework adoption under UAE National Cybersecurity Council mandates. The central bank's operational resilience requirements tighten security budgets for financial institutions. Microsoft Azure and AWS Dubai regions concentrate cloud workload migration, expanding managed detection and response services.
Abu Dhabi
MOHAP audit pressure drives healthcare operators toward outsourced security operations. The UAE Information Assurance Regulation mandates continuous monitoring for critical infrastructure. Etihad Airways and sovereign wealth funds anchor high-assurance contract values in defense-adjacent segments.
Sharjah
Education vertical procurement accelerates under federal critical infrastructure designation expansion. The emirate's university research clusters digitize student information systems. Talent scarcity inflates compensation costs for specialized security architects compared to Dubai and Abu Dhabi.
Northern Emirates
Ras Al Khaimah's industrial zones digitize manufacturing operations, creating first-mover openings for industrial control system security. Underpenetrated markets outside Dubai-Abu Dhabi corridor lag in zero-trust maturity. Federal procurement lists restrict vendor access without local partnership structures.
United Arab Emirates Cybersecurity Market Competitive Landscape
Platform consolidation dominates the current landscape as buyers prioritize integrated architectures over point solutions. The vendor base splits between sovereign specialists with local data center presence and global platform vendors competing through certification compliance. Three archetypes define positioning: sovereign security operations centers, integrated platform consolidators, and hardware-rooted trust architects. M&A activity and strategic local partnerships represent the primary competitive vectors for foreign suppliers seeking federal market access.
Within the sovereign specialist tier, Help AG anchors high-assurance government contracts through its Emirati security operations center presence. Palo Alto Networks exemplifies the platform consolidation archetype, competing on reduced agent sprawl for enterprise customers. DarkMatter occupies a position in defense-adjacent segments where hardware-rooted trust architectures sustain differentiation against foreign vendors facing sovereign content requirements.
| Leading Market Players |
|---|
| Help AG |
| Injazat Data Systems |
| Etisalat Digital |
| CPX |
| DarkMatter |
| Cisco Systems |
| Palo Alto Networks |
| Microsoft |
| Fortinet |
| Others |
Value Network & Pricing Analysis
Specialized cybersecurity talent costs in Dubai and Abu Dhabi cascade through managed security service pricing tiers, with sovereign data residency certifications commanding premium positioning over standard cloud-native deployments. Hardware import friction from BIS-equivalent conformity assessments inflates landed costs for international suppliers serving classified government environments, compressing margins on on-premises security appliances relative to subscription-based alternatives.
Pricing Analysis
Input-cost pass-through from cryptographic engineering scarcity feeds into project-based pricing for quantum-resistant implementation services, while subscription SaaS-tiered models dominate cloud-native detection and response procurement. Price differentiation hinges on UAE Information Assurance Regulation certification tier and sovereign data center presence, with federal-certified vendors capturing 40% premiums over uncertified competitors. Pricing pressure stems from Help AG's sovereign security operations center anchoring high-assurance contracts, forcing foreign vendors toward compressed margins in commercial segments. Mid-market healthcare groups in Abu Dhabi exhibit highest price sensitivity, while defense-adjacent federal agencies prioritize assurance over cost.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale demand from Etisalat Digital and sovereign wealth funds, while value-added distributors serve mid-market enterprises through regional managed service provider partnerships. Hardware supply concentrates in Taiwan, USA, and Israel for specialized cryptographic processors and trusted platform modules. Component dependencies include quantum-resistant algorithm libraries, hardware security modules, and sovereign cloud API orchestration layers. Single-source vulnerability around post-quantum cryptographic engineering talent constrains deployment velocity for federal banking clients. Distribution runs through Dubai's technology corridors, with BIS-equivalent assessments adding regulatory chokepoints for classified environment hardware.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The UAE cybersecurity market functions as a geographic-arbitrage play where Dubai's concentrated talent pools and Abu Dhabi's sovereign wealth capital create divergent cost structures for security operations center buildouts versus outsourced managed services procurement.
For Market Incumbents: Cement federal certification status under UAE Information Assurance Regulation to lock out foreign competitors lacking Emirati partnership structures. Deepen backward integration into sovereign cloud infrastructure through local data center expansion, countering the threat of DarkMatter's hardware-rooted trust architectures in defense-adjacent segments. Priority lever: continuous monitoring platform consolidation to reduce agent sprawl for banking consortia. For New Entrants and Emerging Players: Begin with Ras Al Khaimah's underpenetrated industrial zones, where manufacturing digitization creates first-mover openings for industrial control system security absent entrenched vendor relationships. Target education vertical procurement in Sharjah, where federal critical infrastructure designation expansion accelerates security spend without incumbent lock-in. Go-to-market angle: identity-first convergence platforms merging privileged access management with endpoint detection for healthcare operators facing MOHAP audit pressure. For Investors and Strategic Acquirers: Consolidation pressure builds where platform vendors lack sovereign data residency certifications required for federal procurement list access. Long-term viability favors acquirers of specialized quantum-resistant cryptographic engineering capabilities, as post-quantum talent scarcity constrains organic buildout. Signal to watch: UAE National Cybersecurity Council mandate expansion beyond banking and healthcare into additional critical infrastructure verticals.| Strategic Initiative | Industry Significance |
|---|---|
| Sovereign Security Operations Center Expansion | Local data center presence satisfies UAE Information Assurance Regulation residency mandates for federal contracts. |
| Post-Quantum Cryptographic Partnership | Alliance with NIST-standard algorithm developers accelerates quantum-resistant refresh cycles for banking clients. |
| Managed Detection and Response Platform Integration | Unified telemetry from endpoints, networks, and cloud workloads compresses vendor count per enterprise. |
| Industrial Control System Security Launch | Ras Al Khaimah manufacturing digitization creates first-mover positioning outside Dubai-Abu Dhabi corridor. |
| Federal Certification List Compliance Investment | Early UAE Information Assurance Regulation alignment secures preferred supplier status for critical infrastructure procurement. |
Research Methodology
Coverage spans Dubai, Abu Dhabi, Sharjah, and Ras Al Khaimah, with primary inputs from each emirate's technology corridors and federal procurement centers. Primary interviews with CISOs at banking consortia, MOHAP compliance officers, federal cybersecurity procurement leads, and managed security service provider executives combined with secondary validation from UAE National Cybersecurity Council mandate documentation, UAE Information Assurance Regulation certification databases, and hyperscaler sovereign cloud region disclosures. Bottom-up enterprise spend analysis and top-down federal budget allocation triangulation anchored market sizing.
Rate-of-change decomposition across the analysis window separated cloud migration velocity, regulatory mandate compression, and quantum computing timeline impacts on cryptographic refresh cycles. Segmentation modeling incorporated deployment architecture, product type, end-user vertical, and solution maturity dimensions throughout the forecast period. CAGRs derived from weighted scenario analysis across sovereign cloud adoption curves, federal certification expansion trajectories, and managed service displacement rates in healthcare and education verticals. Forecast inputs included Microsoft Azure and AWS Dubai region capacity expansion disclosures and MOHAP audit enforcement intensity indicators.
Several conditions sit outside the modeled scope, including specific quantum computing breakthrough timelines, geopolitical disruptions to hardware import channels, and abrupt federal mandate scope expansions. Forecasts reflect documented assumptions around sovereign cloud certification maturation and talent concentration persistence in Dubai and Abu Dhabi. Periodic stress-testing of base assumptions is recommended against evolving UAE National Cybersecurity Council enforcement patterns and post-quantum standardization developments.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cybersecurity
Wireless Network Security Market
Cybersecurity
Digital Forensics Market
Cybersecurity
India Network Security and Cyber Risk Management Market
Cybersecurity
Post-Quantum Cryptography Market
Cybersecurity
Global File Integrity Monitoring Market
Cybersecurity
Singapore Cybersecurity Market
Cybersecurity
Global Cyber Situational Awareness Market
Cybersecurity
Data Diode Solution Market
Cybersecurity
China Cybersecurity Market
Cybersecurity
Application-Level Encryption Market
Cybersecurity
Malaysia Cybersecurity Market
Cybersecurity
Middle East and Africa Cybersecurity Market
Cybersecurity
Canada Cybersecurity Market
Cybersecurity
New Zealand Cybersecurity Market
Cybersecurity
Education Data Security Market
Cybersecurity
SOC As a Service Market