
 Global Cloud Encryption Market | 2026-2036
Global Cloud Encryption Market Size, Share, and Industry Trends Forecast 2026-2036
Global Cloud Encryption Market Analysis
Mid-market enterprises is bifurcating from large-cap incumbents as the primary growth vector in cloud encryption procurement. Amazon Web Services leverages its integrated key management infrastructure to anchor enterprise-grade deployments across regulated industries. Microsoft Corporation competes through native encryption layers embedded within productivity and cloud suites. Thales specializes in hardware security module integration, differentiating its offerings for government and defense buyers who demand physical root-of-trust architectures.
Cloud encryption encompasses cryptographic protocols, key lifecycle management systems, and access control frameworks that protect data at rest, in transit, and during processing across distributed infrastructure. The technology employs AES-256 symmetric algorithms, RSA-4096 asymmetric standards, and hardware security modules with FIPS 140-2 Level 3 certification to enforce confidentiality and integrity guarantees for multi-tenant environments. Hybrid cloud deployments now command the largest addressable base as enterprises retain sensitive workloads on-premises while bursting to public infrastructure. Encryption as a Service is expanding fastest among service types, driven by developer preference for API-first key provisioning that eliminates operational overhead. BFSI end users sustain premium pricing tolerance due to PCI-DSS audit requirements and cross-border transaction compliance burdens.
The EU AI Act, HIPAA, and GDPR collectively mandate encryption as a baseline control for personal data processing, with breach notification penalties scaling to four percent of global revenue under European enforcement. NIST post-quantum cryptography standards and the FDA's updated guidance on medical device software security are accelerating refresh cycles for legacy encryption implementations. Stakeholders must evaluate quantum-resistant algorithm migration timelines against existing certificate infrastructure depreciation schedules to avoid stranded cryptographic assets.
Market Dynamics
Post-quantum cryptography migration is compressing enterprise refresh cycles as NIST standards force algorithm replacement before certificate infrastructure depreciation completes. This technological discontinuity is restructuring vendor competitive positioning and procurement timelines.
Growth Catalysts
- EU AI Act enforcement:GDPR breach penalties scaling to four percent of global revenue are mandating encryption as baseline infrastructure for personal data processing across European deployments.
- Healthcare data migration:Patient record digitization and telemedicine expansion are accelerating procurement of FIPS 140-2 Level 3 certified hardware security modules.
- Hybrid cloud architecture adoption:Enterprises retaining sensitive workloads on-premises while bursting to public infrastructure are driving demand for unified key lifecycle management across distributed environments.
Market Restraints
- Hardware security module supply concentration:Manufacturing of FIPS-certified HSMs clusters among limited specialized foundries, creating procurement bottlenecks for government and defense buyers.
- Certificate infrastructure depreciation friction:Legacy PKI systems with multi-year certificate lifecycles delay post-quantum algorithm migration, stranding cryptographic investments.
- Cross-border data sovereignty complexity:Conflicting national encryption key escrow requirements between Germany, France, and United States jurisdictions fragment unified deployment architectures.
Strategic Opportunities
- India BFSI modernization:RBI data localization mandates and digital payment infrastructure expansion create concentrated demand for API-first encryption services.
- Medical device software security:FDA updated guidance on connected health devices is opening specialized procurement channels for encryption integrated at firmware level.
- Quantum-resistant algorithm convergence:CRYSTALS-Kyber and CRYSTALS-Dilithium standardization is enabling hybrid classical-quantum cryptographic stacks for long-term data protection.
Industry Challenges
- Cryptographic engineering talent scarcity:Shortage of specialists qualified in both lattice-based mathematics and production systems integration is extending deployment timelines.
- Multi-cloud key federation complexity:Enterprises operating across AWS, Azure, and Google Cloud environments face operational overhead in maintaining consistent key governance policies.
- Post-quantum certificate authority readiness gaps:Root CA infrastructure migration timelines lag NIST standard finalization, creating interoperability risks during transition periods.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Cloud Encryption Market |
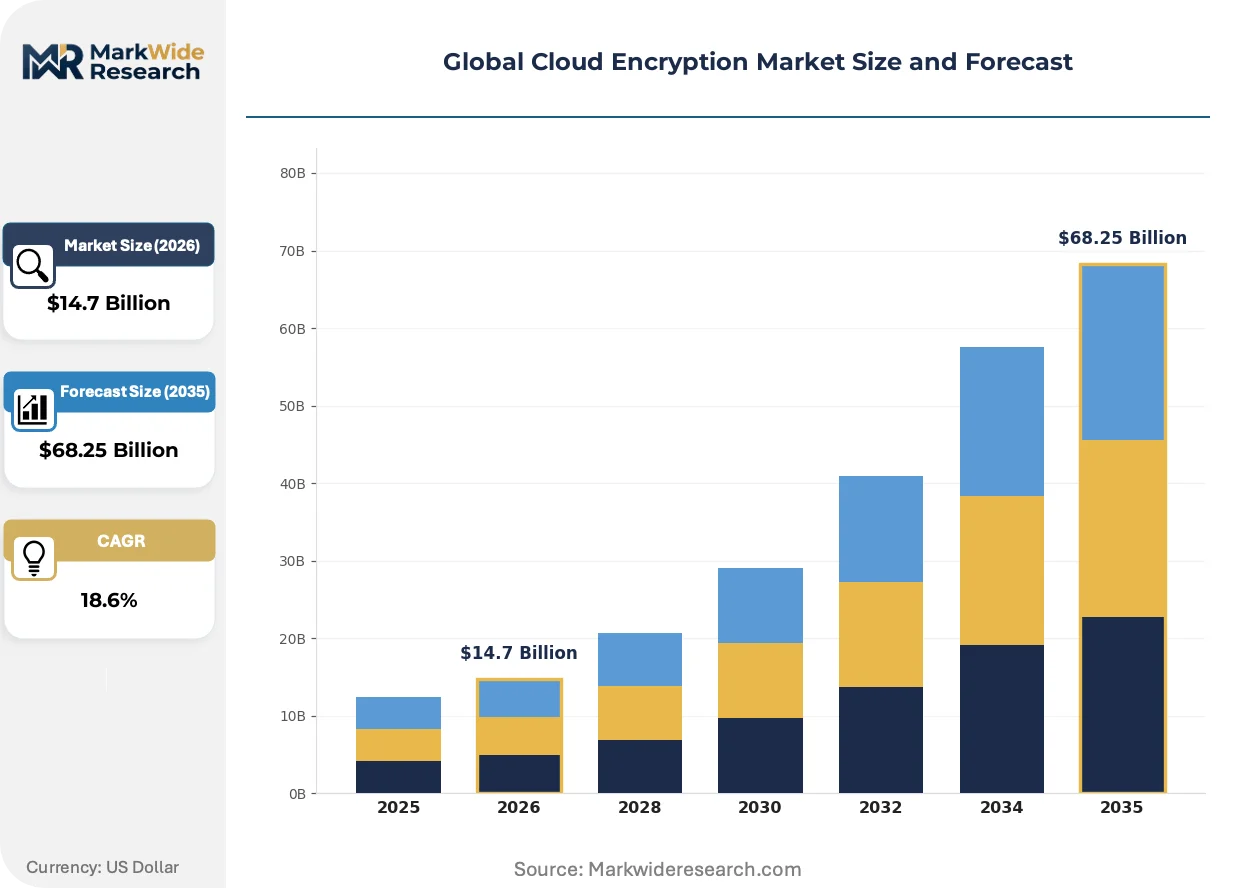
| Market Size in 2026 | $14.7 Billion |
| Market Size in 2035 | $68.25 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Public Cloud, Private Cloud, Hybrid Cloud, Community Cloud Service Type: Encryption as a Service, Data Masking Services, Key Management Services, Tokenization Services End User: Healthcare, BFSI, Government, Retail Technology: Symmetric Encryption, Asymmetric Encryption, Hashing, Tokenization |
| Companies Covered | Amazon Web Services, Microsoft Corporation, IBM Corporation, Google Cloud, Thales, Symantec Corporation, Oracle, Netskope, Sophos, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Cloud Encryption Market Emerging Trajectories
Encryption architectures are fragmenting from monolithic perimeter models toward granular data-centric protection. This decomposition is redistributing competitive advantage toward API-native specialists and away from legacy hardware-centric vendors.
Homomorphic encryption is decomposing traditional boundaries between computation and confidentiality. Pharmaceutical researchers at Merck and Roche are piloting privacy-preserving machine learning on encrypted genomic datasets. The technology is compressing regulatory approval timelines by enabling multi-party analytics without raw data exposure.
CSRD sustainability disclosure requirements in Europe are mandating encryption for supply chain emissions data transmission. Industrial cloud adopters in Germany must now document cryptographic controls in audited sustainability reports. Automotive suppliers with EU manufacturing footprints are prioritizing AES-256-GCM implementations to satisfy both cybersecurity and environmental compliance audits.
Developer-led procurement is displacing centralized IT security gatekeeping for encryption services. Engineering teams at fintech startups in Singapore and São Paulo are directly integrating Stripe-style API key management without enterprise security review cycles. This pattern is most visible in Y Combinator-backed companies where speed-to-deployment overrides traditional vendor evaluation protocols.
Global Cloud Encryption Market Segmentation
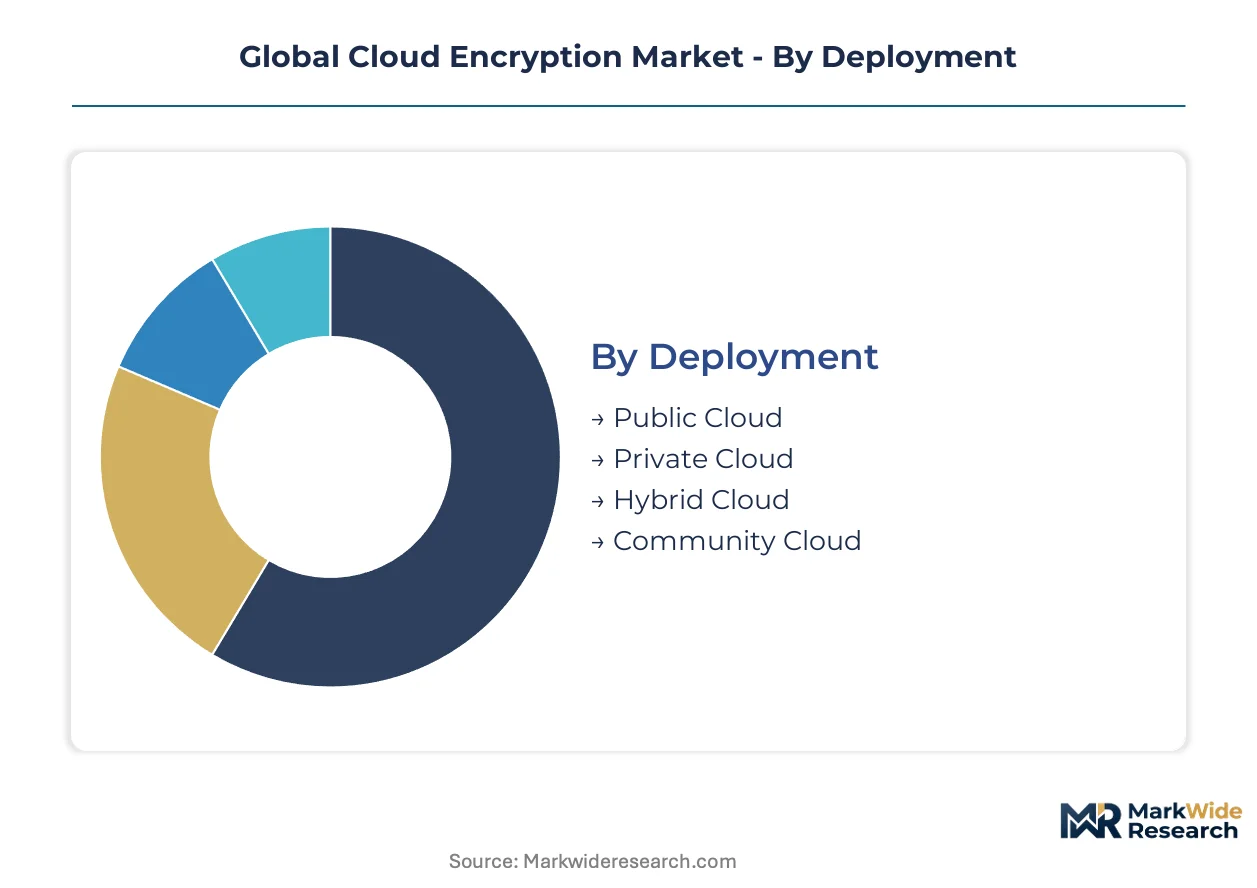
Cloud encryption procurement patterns diverge sharply across deployment architectures and service models. Regulatory jurisdiction and data residency requirements determine which segments dominate enterprise spending versus developer-led adoption.
Deployment:
Geographic spread varies by deployment model: public cloud serves export-oriented multinationals, while private and hybrid deployments concentrate in domestically regulated sectors.
- Public Cloud:Shared infrastructure encryption relies on provider-managed key hierarchies with tenant isolation through hardware security modules. Demand concentrates among SaaS-native enterprises in Singapore and Ireland seeking rapid scaling without capital expenditure on dedicated cryptographic hardware.
- Hybrid Cloud:Unified key lifecycle management spans on-premises hardware security modules and public cloud key management services through federated architectures. German automotive suppliers and US healthcare systems drive procurement as they retain patient records and engineering data on-premises while bursting analytics workloads to public infrastructure.
- Private Cloud:Single-tenant encryption stacks with dedicated FIPS 140-2 Level 3 certified hardware serve defense contractors and central banks requiring physical root-of-trust control.
- Community Cloud:Shared infrastructure among regulated industry peers—such as US credit unions or EU pharmaceutical consortiums—enables collective bargaining on encryption service procurement while maintaining sector-specific compliance.
Hybrid cloud commands the established base. The steepest expansion runs through public cloud deployments among mid-market enterprises.
Service Type:
Cost tier separation distinguishes fully managed API services from labor-intensive professional implementations.
- Encryption as a Service:RESTful APIs abstract key provisioning, rotation, and revocation for development teams without cryptographic expertise. Fintech startups in São Paulo and Singapore integrate Stripe-style key management directly into CI/CD pipelines, bypassing traditional enterprise security review cycles.
- Key Management Services:Centralized key lifecycle governance across multi-cloud environments addresses the operational overhead of maintaining consistent policies across AWS, Azure, and Google Cloud deployments. Large European banks prioritize these services for PCI-DSS audit readiness.
- Data Masking Services:Format-preserving encryption enables non-production data use without exposing sensitive records, serving software testing and analytics teams.
- Tokenization Services:Value substitution replaces sensitive data elements with non-sensitive equivalents, reducing compliance scope for retail payment processors.
Key management services anchor enterprise procurement. Encryption as a service gains share fastest among developer-led organizations.
End User:
Application criticality determines encryption investment intensity across sectors.
- Healthcare:HIPAA enforcement and FDA medical device guidance mandate FIPS 140-2 Level 3 hardware security modules for patient data at rest and in transit. US hospital systems and telemedicine platforms accelerate procurement as patient record digitization expands attack surfaces.
- BFSI:PCI-DSS audit requirements and cross-border transaction compliance sustain premium pricing tolerance for quantum-resistant algorithm implementations. RBI data localization mandates in India concentrate demand for API-first encryption among payment infrastructure modernizers.
- Government:Classified workload protection requires physical root-of-trust architectures with domestic manufacturing provenance.
- Retail:E-commerce platform encryption focuses on tokenization for payment card data and TLS 1.3 for customer session protection.
BFSI sustains the highest per-account spending. Healthcare demonstrates the steepest expansion trajectory as regulatory enforcement tightens.
Technology:
Maturity curves separate established standards from emerging post-quantum alternatives.
- Symmetric Encryption:AES-256-GCM dominates data-at-rest protection with hardware acceleration on modern processors. German automotive suppliers prioritize this implementation to satisfy both CSRD sustainability disclosure requirements and cybersecurity audits for supply chain emissions data transmission.
- Asymmetric Encryption:RSA-4096 secures key exchange and digital signatures, though NIST post-quantum standards are forcing migration to CRYSTALS-Kyber and CRYSTALS-Dilithium lattice-based alternatives before certificate infrastructure depreciation completes.
- Hashing:SHA-3 and BLAKE3 provide integrity verification for software supply chains and blockchain applications.
- Tokenization:Format-preserving substitution reduces compliance scope without mathematical reversibility, serving retail and healthcare de-identification use cases.
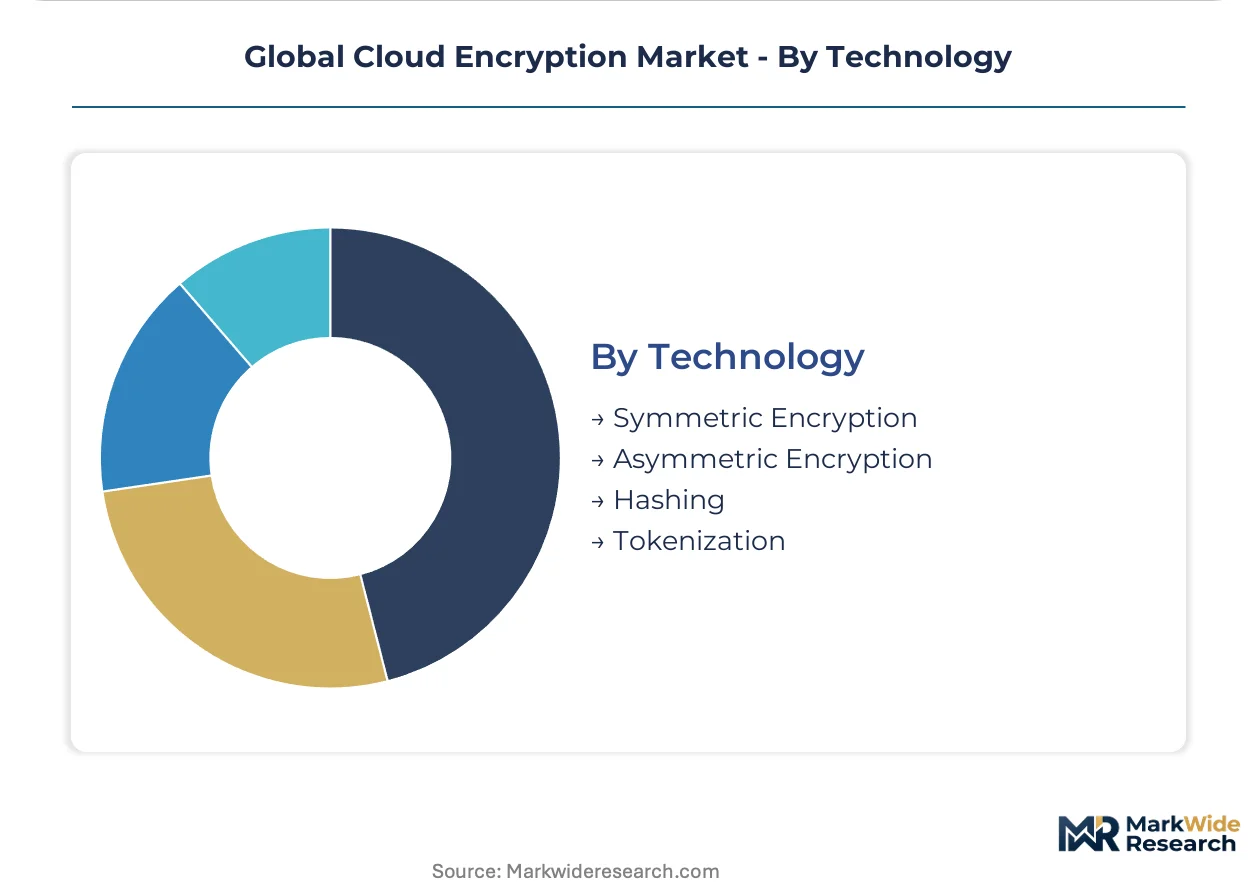
Symmetric encryption underpins the installed base. Asymmetric encryption faces the steepest refresh cycle pressure from post-quantum migration mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German encryption vendors export hardware security modules to healthcare systems across the United States and defense contractors in the United Kingdom, establishing a transatlantic trade corridor in cryptographic infrastructure.
United States
Federal cloud migration and HIPAA enforcement drive procurement of FIPS 140-2 Level 3 certified modules. FDA medical device guidance mandates firmware-level encryption for connected health devices. Hospital systems in Boston and telemedicine platforms in Silicon Valley accelerate deployment timelines.
Germany
Industrial cloud adoption and federal cybersecurity mandates concentrate demand for unified key lifecycle management. CSRD sustainability disclosure requirements mandate encryption for supply chain emissions data transmission. Automotive suppliers in Bavaria prioritize AES-256-GCM implementations for compliance audits.
India
RBI data localization mandates and digital payment infrastructure expansion create concentrated demand for API-first encryption services. BFSI modernization programs enforce cryptographic controls on cross-border transaction processing. Fintech clusters in Mumbai and Bangalore integrate developer-led key management directly into CI/CD pipelines.
United Kingdom
Post-Brexit data sovereignty requirements and NHS digitization programs sustain procurement of hybrid cloud encryption architectures. National Cyber Security Centre guidance mandates quantum-resistant algorithm readiness for critical infrastructure. Financial services firms in the City of London prioritize multi-cloud key federation solutions.
Singapore
SaaS-native enterprises and regional headquarters of multinational corporations drive demand for provider-managed key hierarchies. Monetary Authority of Singapore digital banking licenses mandate encryption for customer data across distributed infrastructure. Technology companies in the One-North district seek rapid scaling without capital expenditure on dedicated cryptographic hardware.
Global Cloud Encryption Market Vendor Landscape
Player mix skews toward hyperscale cloud providers with integrated key management infrastructure. The vendor base concentrates among three tiers: hyperscale platforms with native encryption layers, specialized hardware security module manufacturers, and API-native encryption services. Strategic archetypes include integrated cloud platforms, physical root-of-trust specialists, and developer-first API providers. Dominant competitive moves encompass strategic partnerships for multi-cloud key federation and portfolio diversification into post-quantum cryptographic stacks.
Within the integrated cloud platform tier, Amazon Web Services and Microsoft Corporation anchor enterprise-grade deployments through native encryption layers embedded within productivity and cloud suites. Thales occupies a position among physical root-of-trust specialists, exemplifying hardware security module integration for government and defense buyers who demand FIPS 140-2 Level 3 certified architectures. These three entities represent the primary competitive anchors structuring procurement patterns across regulated industries and developer-led organizations respectively.
| Leading Market Players |
|---|
| Amazon Web Services |
| Microsoft Corporation |
| IBM Corporation |
| Google Cloud |
| Thales |
| Symantec Corporation |
| Oracle |
| Netskope |
| Sophos |
| Others |
Supply Flow & Price Mechanics
Ninety-day lead times for FIPS 140-2 Level 3 certified hardware security modules concentrate pricing power among specialized foundries in Germany and the United States, compressing margins for system integrators while elevating premiums for domestic manufacturing provenance.
Pricing Analysis
Post-quantum algorithm migration widens the pricing gap between legacy RSA-4096 implementations and CRYSTALS-Kyber certified stacks. Three-tier pricing structure across FIPS Level 3 certified, Level 2 compliant, and non-certified implementations separates government buyers from mid-market enterprises and developer-led adopters. Cost compression in standard-tier key management services is intensifying because hyperscale cloud providers bundle encryption into infrastructure pricing. Healthcare systems demonstrate the least price sensitivity due to HIPAA audit requirements, while SaaS-native startups in Singapore and São Paulo exhibit the highest.
Supply Chain Analysis
Inventory cycles for tamper-resistant cryptographic processors currently extend to sixteen weeks, reflecting foundry concentration in Germany, Taiwan, and the United States. Manufacturing draws from specialized silicon substrates, precision assembly equipment, and domestic cleanroom facilities. Single-source vulnerability persists where defense procurement mandates domestic manufacturing provenance. Distribution runs through authorized security equipment resellers and direct hyperscale cloud marketplaces.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Cloud Encryption Market is recovering from post-quantum standardization disruption as NIST-mandated algorithm refresh cycles drive replacement demand across certificate infrastructure.
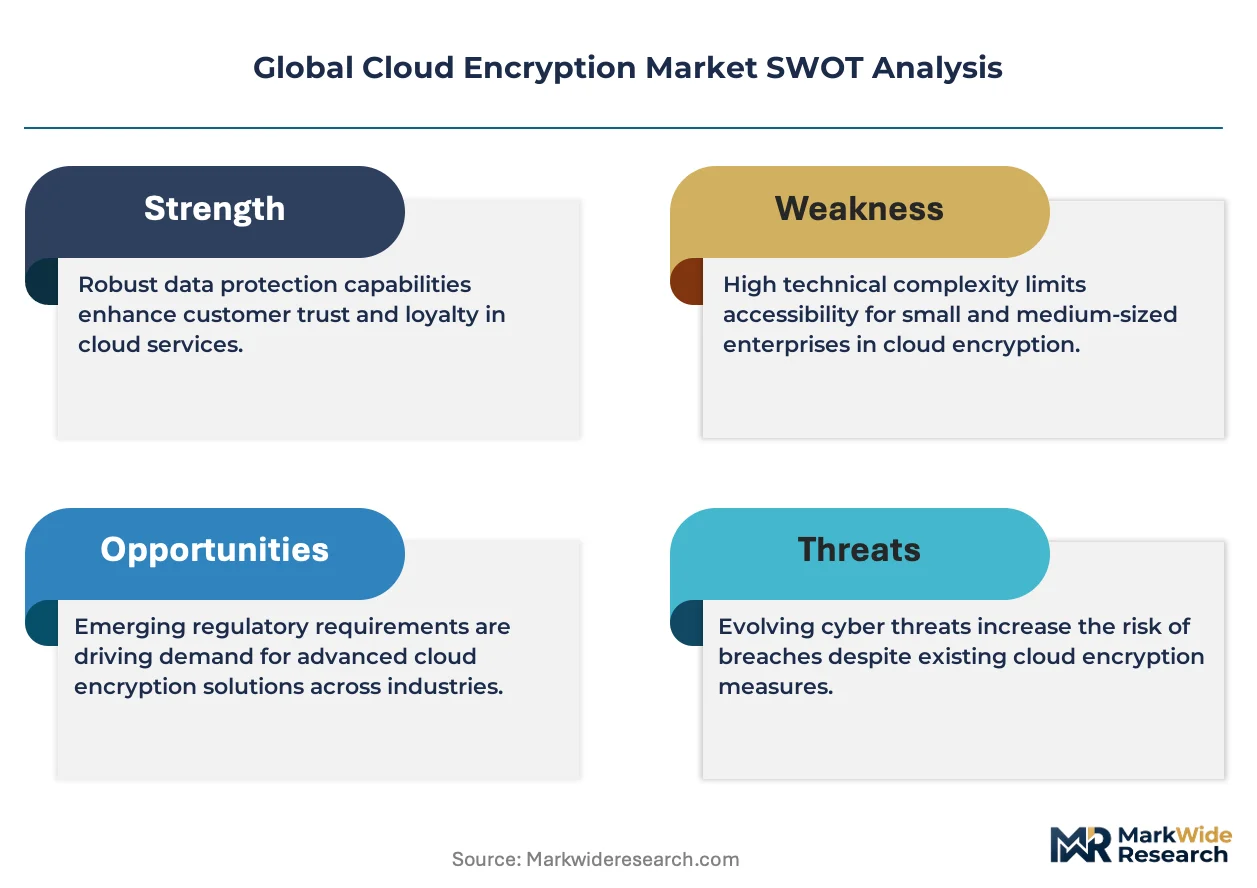
For Market Incumbents: Shield enterprise accounts from API-native entrants by embedding quantum-resistant key management into existing productivity suite contracts. Deepen backward integration into FIPS-certified hardware security module manufacturing to reduce foundry dependency and capture margin from defense procurement requirements. For New Entrants and Emerging Players: Mid-market hybrid cloud deployments represent the most penetrable segment where centralized IT security gatekeeping has weakened and developer-led procurement prevails. Target API-first encryption services for fintech clusters in Mumbai and Bangalore where RBI data localization mandates create urgent procurement windows. Lead with Stripe-style CI/CD integration to bypass traditional vendor evaluation cycles. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-compression play because encryption is hardening from optional security control to baseline infrastructure mandate across GDPR, HIPAA, EU AI Act, and FDA medical device guidance. Acquire physical root-of-trust specialists with existing FIPS 140-2 Level 3 certification infrastructure. Watch NIST post-quantum certificate authority readiness timelines as the inflection signal for interoperability risk premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Post-Quantum Algorithm Integration | CRYSTALS-Kyber and CRYSTALS-Dilithium standardization enables hybrid classical-quantum cryptographic stacks for long-term data protection. |
| Hardware Security Module Capacity Expansion | FIPS 140-2 Level 3 certified manufacturing investments reduce procurement bottlenecks for government and defense buyers. |
| API-First Encryption Service Launch | RESTful key provisioning eliminates operational overhead for developer-led organizations in fintech and healthcare. |
| Multi-Cloud Key Federation Partnership | Unified governance across AWS, Azure, and Google Cloud environments addresses operational complexity for European banks. |
| Medical Device Firmware Security Integration | FDA guidance on connected health devices opens specialized procurement channels for encryption at hardware level. |
Methodological Framework
A standing panel of chief information security officers, cloud infrastructure architects, hardware security module procurement leads, and regulatory compliance directors provided ongoing calibration across the study period. Primary interviews combined with secondary validation against NIST publication archives, FDA guidance documents, EU AI Act regulatory texts, and hyperscaler service documentation. Bottom-up deployment modeling triangulated against top-down regulatory mandate analysis.
Consistency checks validated volume and value outputs against external benchmarks including cloud infrastructure capex disclosures, healthcare IT spending surveys, and BFSI technology budget allocations. Segmentation dimensions modeled deployment architecture, service type, end-user vertical, and regulatory jurisdiction cluster. CAGRs derived from algorithm refresh cycle timelines and certificate infrastructure depreciation schedules. Post-quantum migration urgency and data sovereignty enforcement intensity served as industry-specific forecast inputs.
Forecasts assume regulatory continuity in EU AI Act implementation, HIPAA enforcement, and RBI data localization mandates; material policy shifts would require re-modeling. Specific risks include NIST post-quantum standard delays, hardware security module supply disruptions, and cross-border encryption key escrow requirement fragmentation. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cybersecurity
Europe Digital Forensics Market
Cybersecurity
Europe Zero Trust Security Market
Cybersecurity
Hong Kong Cybersecurity Market
Cybersecurity
Global Healthcare IoT Security Market
Cybersecurity
Retail Cybersecurity Market
Cybersecurity
United States Virtualization Security Market
Cybersecurity
Spear Phishing Solution Market
Cybersecurity
New Zealand Cybersecurity Market
Cybersecurity
Saudi Arabia Cybersecurity Market
Cybersecurity
E-Mail Security Market
Cybersecurity
South Korea Ransomware Protection Market
Cybersecurity
Europe IoT Security Market
Cybersecurity
Cloud Application Security Market
Cybersecurity
Global Database Encryption Market
Cybersecurity
Germany Cybersecurity Market
Cybersecurity
Finland Cybersecurity Market