
 Next-Generation Firewall Market | 2026-2036
Next-Generation Firewall Market Size, Share, and Industry Trends Forecast 2026-2036
Next-Generation Firewall Market Intelligence
Buyer concentration among large enterprises is restructuring procurement patterns across the NGFW landscape. Palo Alto Networks leverages its integrated platform strategy to capture multi-year contracts from Fortune 500 accounts. Fortinet anchors its position through proprietary ASIC development that reduces latency at scale. Check Point Software Technologies competes by emphasizing unified threat prevention across on-premises and cloud edges.
A next-generation firewall integrates deep packet inspection, application-aware filtering, and intrusion prevention at throughput rates exceeding 100 Gbps to enforce granular security policies across enterprise networks. Cloud-based deployment is capturing the fastest expansion as organizations migrate security stacks to distributed architectures, while on-premises installations retain dominance in regulated sectors with strict data residency requirements. Managed services within the service type dimension are accumulating margin pools as staffing shortages drive outsourcing of policy tuning and threat response.
The FCC enforces baseline cybersecurity expectations for critical communications infrastructure in the United States, while GDPR and the EU AI Act impose cross-border data governance obligations that shape product architecture decisions. NIS2 mandates expanded incident disclosure timelines across European member states, compelling vendors to embed automated telemetry and compliance reporting. Stakeholders must evaluate whether their vendor portfolios align with emerging certification requirements before procurement cycles lock in multi-year commitments.
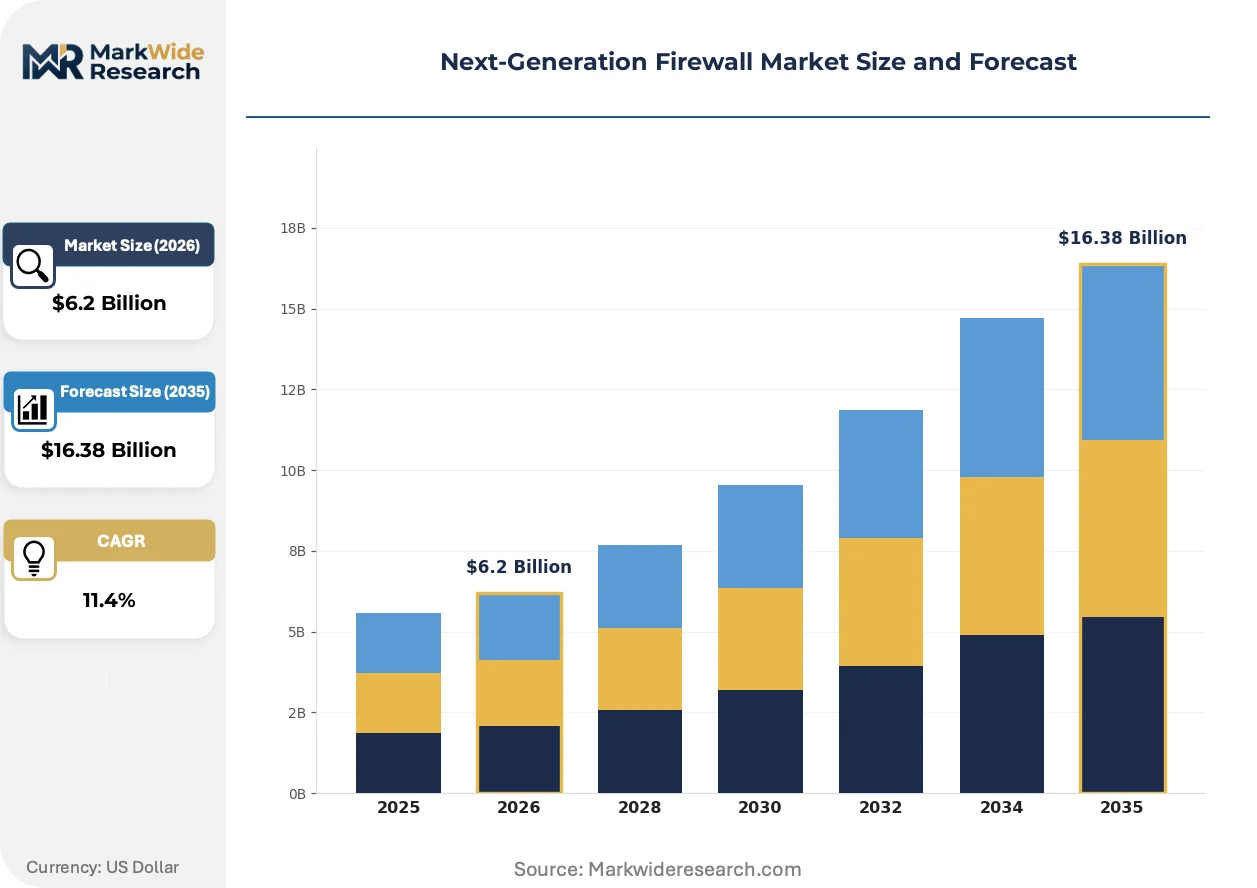
Market Dynamics
Hybrid cloud migration is fragmenting network perimeters, forcing enterprises to redistribute security enforcement across distributed architectures rather than consolidating at single chokepoints.
Growth Catalysts
- NIS2 Directive:Mandatory incident reporting timelines across EU member states are compelling enterprises to upgrade from legacy stateful inspection to automated NGFW telemetry. Financial services firms in Germany and France face the tightest compliance windows.
- Zero Trust Architecture:Federal mandates in the United States are accelerating replacement of perimeter-centric designs with identity-aware microsegmentation. Defense contractors and civilian agencies now specify NGFW integration with identity providers.
- Managed Security Services:Talent shortages in security operations centers are pushing mid-market enterprises toward cloud-managed NGFW deployments. Service providers absorb policy tuning and threat response functions previously retained in-house.
Market Restraints
- Semiconductor Supply Concentration:Proprietary ASIC fabrication for high-throughput NGFW appliances depends on concentrated foundry capacity in Taiwan. Vendor delivery timelines stretch when advanced node allocation tightens.
- Data Residency Requirements:GDPR and sector-specific banking regulations in Switzerland and Germany block cloud NGFW adoption for certain workloads. On-premises hardware retains mandatory share in these jurisdictions.
- Skills Gap in Network Security:Deep packet inspection policy engineering requires specialized expertise that remains scarce outside major technology hubs. Enterprise buyers face premium labor costs or extended implementation timelines.
Strategic Opportunities
- India Digital Infrastructure Expansion:Data center construction under the country's digital sovereignty initiatives is creating fresh demand for localized NGFW deployments. Domestic cloud providers seek compliant security stacks.
- 5G Network Slicing Security:Telecommunications operators require granular policy enforcement at the slice boundary. NGFW vendors can embed security functions within mobile core infrastructure previously served by generic packet filters.
- EU Cybersecurity Certification:The European Cybersecurity Act's forthcoming CC-Ready scheme will create preferred vendor status for certified products. Early certification investments differentiate suppliers in public sector procurement.
Industry Challenges
- Multi-Vendor Console Sprawl:Enterprises operating hybrid environments struggle to correlate policies across on-premises NGFW, cloud-native firewalls, and CASB platforms. Security teams waste cycles on manual rule reconciliation.
- Encrypted Traffic Inspection:TLS 1.3 and certificate pinning complicate deep packet inspection without breaking application functionality. Vendors must balance visibility against privacy compliance and performance degradation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Next-Generation Firewall Market |
| Market Size in 2026 | $6.2 Billion |
| Market Size in 2035 | $16.38 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premises, Cloud-Based, Hybrid, Virtual End User: Enterprises, Government, Healthcare, Education Technology: Application Control, Threat Intelligence, VPN, IDS/IPS Service Type: Managed Services, Professional Services, Consulting, Support |
| Companies Covered | Palo Alto Networks, Fortinet, Cisco, Check Point Software Technologies, Juniper Networks, SonicWall, Sophos, Zscaler, WatchGuard, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Next-Generation Firewall Market Strategic Shifts & Innovations
Artificial intelligence is embedding directly into packet processing pipelines, shifting threat detection from signature-based matching to behavioral inference executed at line rate.
Machine learning inference engines are expanding into NGFW hardware platforms, enabling real-time classification of encrypted traffic patterns without full decryption. Large financial institutions in London and Singapore deploy these capabilities to detect data exfiltration through legitimate cloud storage APIs. The technology is expanding into mid-market SKUs as ASIC designs integrate neural network accelerators.
The EU AI Act imposes risk classification and documentation requirements on automated decision systems embedded in security products. NGFW vendors must now maintain algorithmic transparency logs and human oversight mechanisms for AI-driven blocking decisions. European enterprise procurement teams are inserting AI Act compliance clauses into security appliance RFPs ahead of enforcement deadlines.
Enterprise buying committees are consolidating security vendor relationships to reduce integration overhead and streamline incident response. CISOs increasingly demand NGFW platforms that natively federate with SIEM, SOAR, and identity systems rather than operating as isolated appliances. This preference concentrates procurement authority with integrated platform vendors in the United States and United Kingdom.
Next-Generation Firewall Market Segmentation
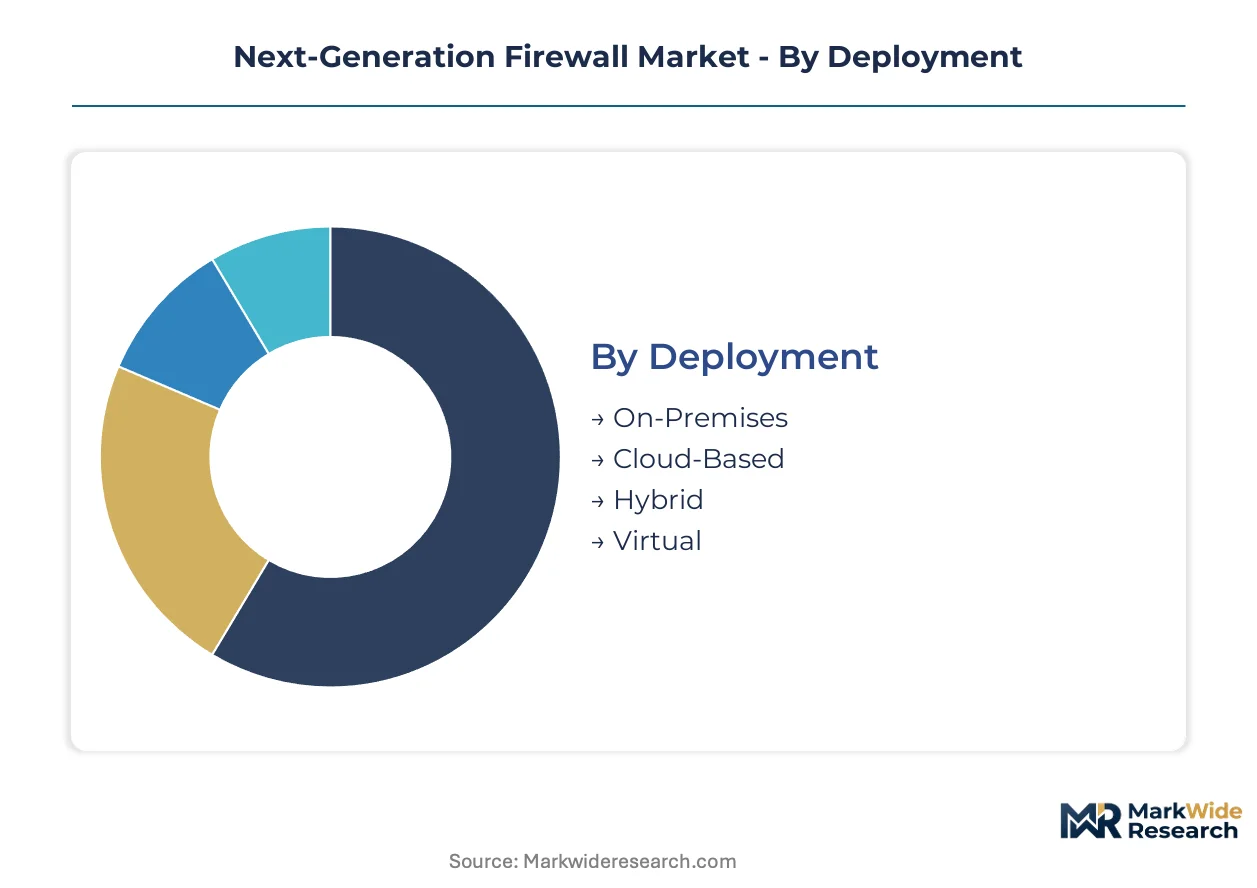
NGFW procurement patterns diverge sharply across deployment models and operational contexts. Buyer priorities shift from throughput optimization in financial data centers to compliance automation in European public sector tenders. Understanding these segment boundaries clarifies where vendors must differentiate platform architecture versus service wrap.
Deployment:
Cost tier separates buyers seeking capital efficiency from those prioritizing operational control over security telemetry.
- Cloud-Based:Distributed enforcement points scale elastically across multi-cloud footprints. Financial services firms in Germany and France favor this model to satisfy NIS2 incident reporting mandates without building captive security operations centers.
- On-Premises:Dedicated appliances process traffic through proprietary ASICs at line rates exceeding 100 Gbps. Swiss banking regulators and German federal data residency requirements preserve demand for hardware deployments in Frankfurt and Zurich clusters.
- Hybrid:Policy orchestration layers unify cloud-native and appliance-based enforcement. Manufacturing conglomerates with legacy operational technology networks adopt this architecture to avoid forklift upgrades.
- Virtual:Software instances deploy on standard compute infrastructure within private clouds. Telecommunications operators embedding security into 5G network slices favor virtual form factors for rapid instantiation.
Volume sits with On-Premises; growth tilts toward Cloud-Based.
End User:
Regulatory exposure and breach consequence severity reshape purchasing criteria across buyer categories.
- Enterprises:Fortune 500 accounts consolidate multi-year contracts with integrated platform vendors. Retail and logistics enterprises prioritize threat intelligence feeds that correlate with payment card industry forensic data.
- Government:Federal mandates in the United States specify Zero Trust Architecture compliance. Defense contractors integrate NGFW with identity providers under civilian agency procurement rules.
- Healthcare:HIPAA-covered entities demand deep packet inspection that preserves patient data encryption while detecting anomalous east-west traffic. Hospital systems in the United Kingdom face NHS Digital cybersecurity standards.
- Education:University networks manage porous perimeters with limited security staffing. Research institutions handling export-controlled technology face additional Commerce Department compliance layers.
Revenue concentrates in Enterprises; expansion accelerates fastest in Government.
Technology:
Functional sophistication determines whether NGFW displaces standalone point products or complements existing stacks.
- Application Control:Granular policy enforcement identifies and blocks traffic by application signature rather than port protocol. London-based financial institutions deploy this capability to detect data exfiltration through legitimate cloud storage APIs.
- Threat Intelligence:Real-time feed integration automates indicator-of-compromise blocking at network boundaries. Managed security service providers monetize curated intelligence streams as differentiated offerings.
- VPN:Encrypted tunnel termination supports remote workforce access and site-to-site connectivity. Post-pandemic hybrid work patterns sustain replacement cycles for legacy concentrator appliances.
- IDS/IPS:Signature and anomaly detection engines operate inline or in monitoring mode. Critical infrastructure operators in energy and water sectors favor this technology for OT network segmentation.
Deployment scale favors Application Control; capability investment flows toward Threat Intelligence.
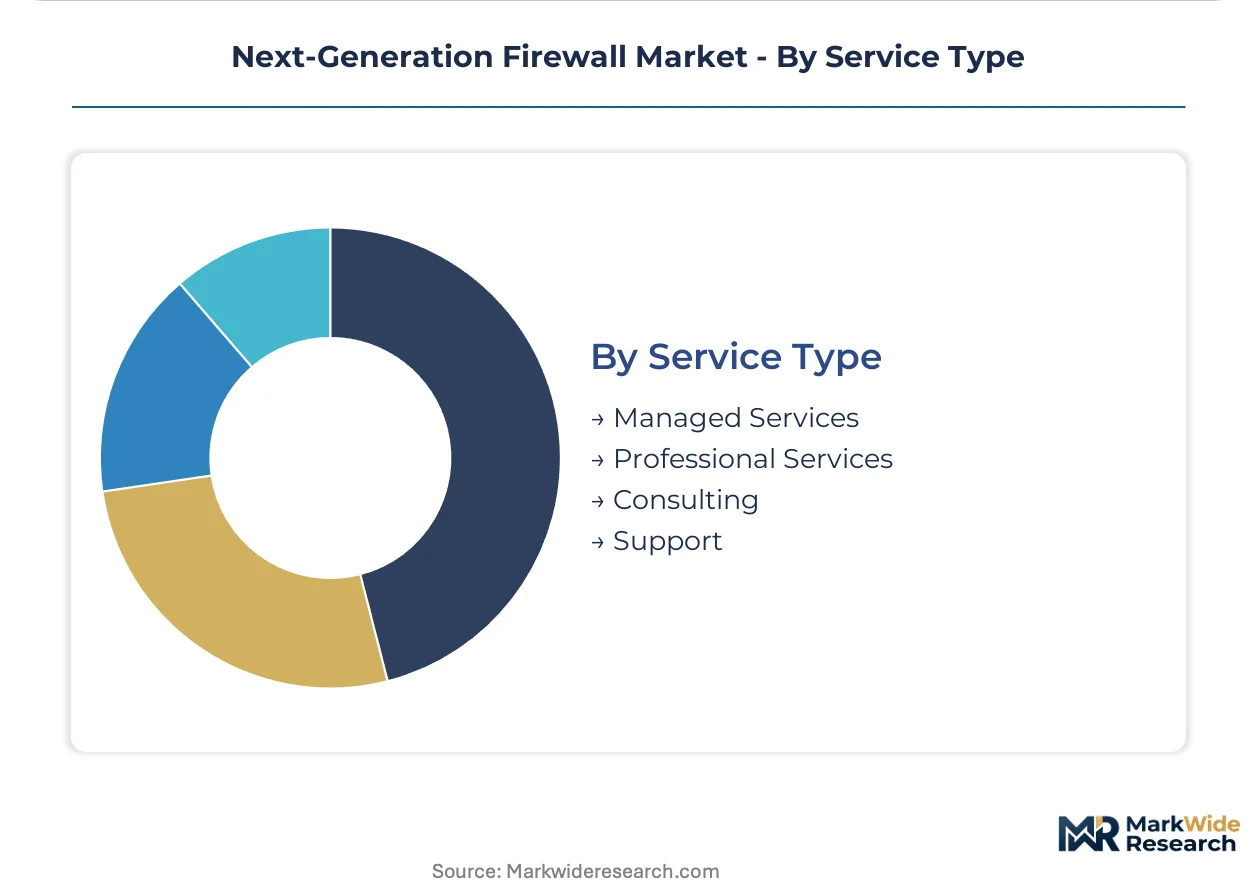
Service Type:
Internal capability gaps drive outsourcing depth across the policy lifecycle from design through incident response.
- Managed Services:Providers absorb policy tuning, threat hunting, and compliance reporting functions. Mid-market enterprises in the United Kingdom facing security operations center staffing shortages contract these services to meet cyber insurance requirements.
- Professional Services:Implementation teams architect distributed enforcement across hybrid environments. Complex migrations from legacy stateful inspection firewalls consume substantial consulting hours.
- Consulting:Advisory engagements assess zero trust readiness and segmentation strategy. CISOs in France and Germany engage these services ahead of NIS2 compliance deadlines.
- Support:Technical assistance and software maintenance subscriptions preserve appliance functionality. Hardware refresh cycles in regulated industries depend on vendor support continuity commitments.
Margin pools accumulate in Managed Services; contract volume concentrates in Support.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Taiwanese semiconductor foundries supply the specialized ASICs that power high-throughput NGFW appliances. Fabrication capacity constraints in Hsinchu and Tainan directly influence vendor delivery timelines worldwide.
United States
Defense contractors and civilian agencies drive procurement under federal Zero Trust Architecture mandates. The FCC enforces baseline cybersecurity expectations for critical communications infrastructure. Northern Virginia data center clusters host cloud-native NGFW deployments for intelligence community and financial services workloads.
Germany
Automotive manufacturers and chemical conglomerates modernize perimeter defenses to satisfy NIS2 incident reporting windows. The EU AI Act imposes risk classification requirements on automated blocking decisions embedded in security products. Frankfurt banking regulators preserve mandatory on-premises hardware shares for transaction processing systems.
United Kingdom
Mid-market enterprises contract managed security services to address security operations center staffing shortages. NHS Digital cybersecurity standards govern hospital system procurement in England and Scotland. London financial institutions deploy machine learning inference engines to detect data exfiltration through legitimate cloud storage APIs.
India
Domestic cloud providers seek compliant security stacks under digital sovereignty initiatives. The country's national data protection framework shapes product architecture decisions for localized deployments. Mumbai and Bengaluru data center construction creates fresh demand for NGFW appliances with indigenous certification requirements.
Japan
Financial institutions and telecommunications operators prioritize low-latency enforcement for high-frequency trading and 5G network slicing. METI industrial security guidelines influence enterprise procurement specifications. Tokyo and Osaka enterprise clusters favor integrated platform vendors that federate natively with SIEM and identity systems.
Next-Generation Firewall Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue cloud-native delivery models and managed service wraps. The vendor base stratifies across integrated platform specialists, proprietary hardware fabricators, and cloud-security pure-plays. Three archetypes dominate: ASIC-anchored appliance vendors, software-defined perimeter builders, and security-as-a-service operators. Consolidation pressure favors multi-year contract capture through portfolio breadth; differentiation concentrates on telemetry automation and cross-platform policy federation.
Among integrated platform vendors, Palo Alto Networks exemplifies the multi-product consolidation archetype that CISOs increasingly favor. Fortinet occupies a position anchored in proprietary silicon development that reduces latency at scale. Check Point Software Technologies sits within the unified threat prevention tier spanning on-premises and cloud edge deployments. These three represent divergent strategic bets on hardware specialization versus software abstraction versus hybrid orchestration.
| Leading Market Players |
|---|
| Palo Alto Networks |
| Fortinet |
| Cisco |
| Check Point Software Technologies |
| Juniper Networks |
| SonicWall |
| Sophos |
| Zscaler |
| WatchGuard |
| Others |
Cost & Logistics Intelligence
Fortune 500 procurement committees demanding multi-year integrated platform contracts are compressing vendor margins and forcing ASIC-dependent appliance makers to absorb foundry cost volatility rather than pass through price increases.
Pricing Analysis
Warranty and advanced replacement service bundles separate premium NGFW tiers from unbundled hardware-only transactions common in mid-market virtual deployments. Three-tier pricing structure across premium, standard, and economy levels reflects throughput certification, threat intelligence feed quality, and managed services attachment rates. Pricing pressure stems from cloud-native pure-plays undercutting appliance vendors on subscription economics. Government and defense contractors exhibit lowest price sensitivity due to mandated Zero Trust compliance windows, while education sector buyers face acute budget constraints.
Supply Chain Analysis
Reverse logistics flows for NGFW appliances concentrate refurbishment and remanufacturing operations in Taiwan and South Korea, where foundry partners reclaim ASICs from end-of-life units. Proprietary chip fabrication draws from concentrated Taiwanese foundry capacity, with advanced node allocation determining vendor delivery timelines. Memory modules and power supply components source from Chinese and Vietnamese contract manufacturers. Single-source vulnerability around TSMC's 7nm and 5nm nodes exposes hardware vendors to allocation shocks. Distribution runs through value-added resellers and direct enterprise sales teams, with managed security service providers emerging as fastest-growing channel.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
ASIC fabrication capacity constraints in Taiwanese foundries are propping pricing power for vendors with secured wafer allocations, while cloud-native competitors exploit software abstraction to bypass hardware bottlenecks entirely.
For Market Incumbents: Acquire cloud-native firewall specialists to fill portfolio gaps in containerized security and serverless workload protection. Palo Alto Networks and Fortinet must defend against Zscaler and other zero-trust pure-plays by embedding identity-aware microsegmentation into hardware platforms. Backward integration into threat intelligence curation and SOAR platform development preserves margin pools as appliance differentiation erodes. For New Entrants and Emerging Players: Enter via managed security service wraps targeting UK mid-market enterprises facing security operations center staffing shortages. White-space concentrates in cloud-native deployments for Indian domestic cloud providers under digital sovereignty mandates, and in 5G network slicing security for telecommunications operators. Channel partnerships with regional managed service providers offer fastest path to recurring revenue without captive ASIC development. For Investors and Strategic Acquirers: The window for entry favors cloud-security pure-plays with demonstrated identity federation capabilities and API-native architectures. Long-term viability hinges on platform consolidation rather than point-product positioning. Acquisition targets should exhibit embedded AI inference engines and EU AI Act compliance documentation. Monitor NIS2 enforcement timelines and CC-Ready certification progress as inflection indicators for European public sector procurement concentration.| Strategic Initiative | Industry Significance |
|---|---|
| ASIC Architecture Refresh | Proprietary silicon development at TSMC reduces latency for financial services data centers in London and Singapore. |
| Cloud-Native Platform Launch | Containerized enforcement points capture elastic demand from German automotive manufacturers migrating to hybrid infrastructure. |
| Managed Security Service Expansion | Policy tuning outsourcing addresses NHS Digital compliance requirements for UK hospital systems. |
| EU Cybersecurity Certification Investment | Early CC-Ready scheme alignment secures preferred vendor status in French and German public sector tenders. |
| Threat Intelligence Feed Integration | Real-time indicator blocking satisfies NIS2 automated telemetry mandates for Frankfurt banking regulators. |
Research Approach
Document review covered vendor technical specifications, EU regulatory filings for NIS2 and AI Act implementation guidance, and hyperscaler security partnership announcements, complemented by interviews with CISOs at Fortune 500 financial services firms, federal procurement officers in the United States, managed security service provider executives in London and Frankfurt, and network engineering directors at telecommunications operators. Secondary validation drew from SEC 10-K cybersecurity risk disclosures, FCC infrastructure security orders, and customs data on ASIC import flows. Bottom-up deployment model forecasts triangulated against top-down IT security spending surveys.
Segment-level value outputs across the projection horizon reflect modeled splits by deployment architecture, end-user vertical, and service type attachment rates. The analytical framework incorporated throughput tier migration curves, cloud adoption elasticity parameters, and compliance-driven replacement cycles specific to EU member state implementation schedules. CAGRs derived from logistic diffusion models of zero trust architecture penetration and hardware refresh cadences in regulated industries.
Forecast precision tightens around the base case; tail outcomes carry wider variance under semiconductor allocation shocks or accelerated EU AI Act enforcement timelines. Practitioners should monitor TSMC advanced node capacity announcements, NIS2 national implementation decrees, and hyperscaler security stack consolidation moves for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cybersecurity
Israel Cybersecurity Market
Cybersecurity
Cloud Security Gateway Market
Cybersecurity
SSL VPN Market
Cybersecurity
Cloud Workload Protection Market
Cybersecurity
Cloud Security in Banking Market
Cybersecurity
Saudi Arabia Cybersecurity Market
Cybersecurity
Global Sensitive Data Discovery Market
Cybersecurity
Cloud-Based Email Security Market
Cybersecurity
Ddos Protection and Mitigation Security Market
Cybersecurity
Cloud Access Security Broker Market
Cybersecurity
Europe Software Defined Perimeter Market
Cybersecurity
Asia Pacific Cybersecurity Market
Cybersecurity
Cloud Application Security Market
Cybersecurity
Europe Data Protection-As-A-Service Market
Cybersecurity
Corporate Web Security Market
Cybersecurity
Firewall-As-A-Service (Fwaas) Market