
 Thailand Data Center Cooling Market | 2026-2036
Thailand Data Center Cooling Market Size, Share, and Industry Trends Forecast 2026-2036
Thailand Data Center Cooling Market Insights
TISI certification for energy efficiency in building systems is bifurcating the supplier landscape into qualified and non-qualified tiers. Schneider Electric SE leverages its integrated power and cooling architecture to anchor large enterprise deployments in Bangkok. Vertiv Group Corp competes through thermal management specialization for high-density racks. Stulz GmbH differentiates via precision air conditioning engineered for tropical humidity loads.
Thailand data center cooling encompasses mechanical and thermal systems engineered to maintain IT equipment within operational temperature bands, typically 18°C to 27°C per ASHRAE guidelines, through heat rejection, air distribution, or liquid-mediated exchange. Liquid cooling is gaining structural momentum as GPU-intensive workloads exceed 30 kW per rack, while air cooling retains dominance in legacy enterprise facilities. Among end users, colocation facilities represent the fastest-growing demand pool as international operators seek ASEAN hub capacity. Modular installation types are expanding share by reducing deployment timelines for cloud service providers with phased buildouts.
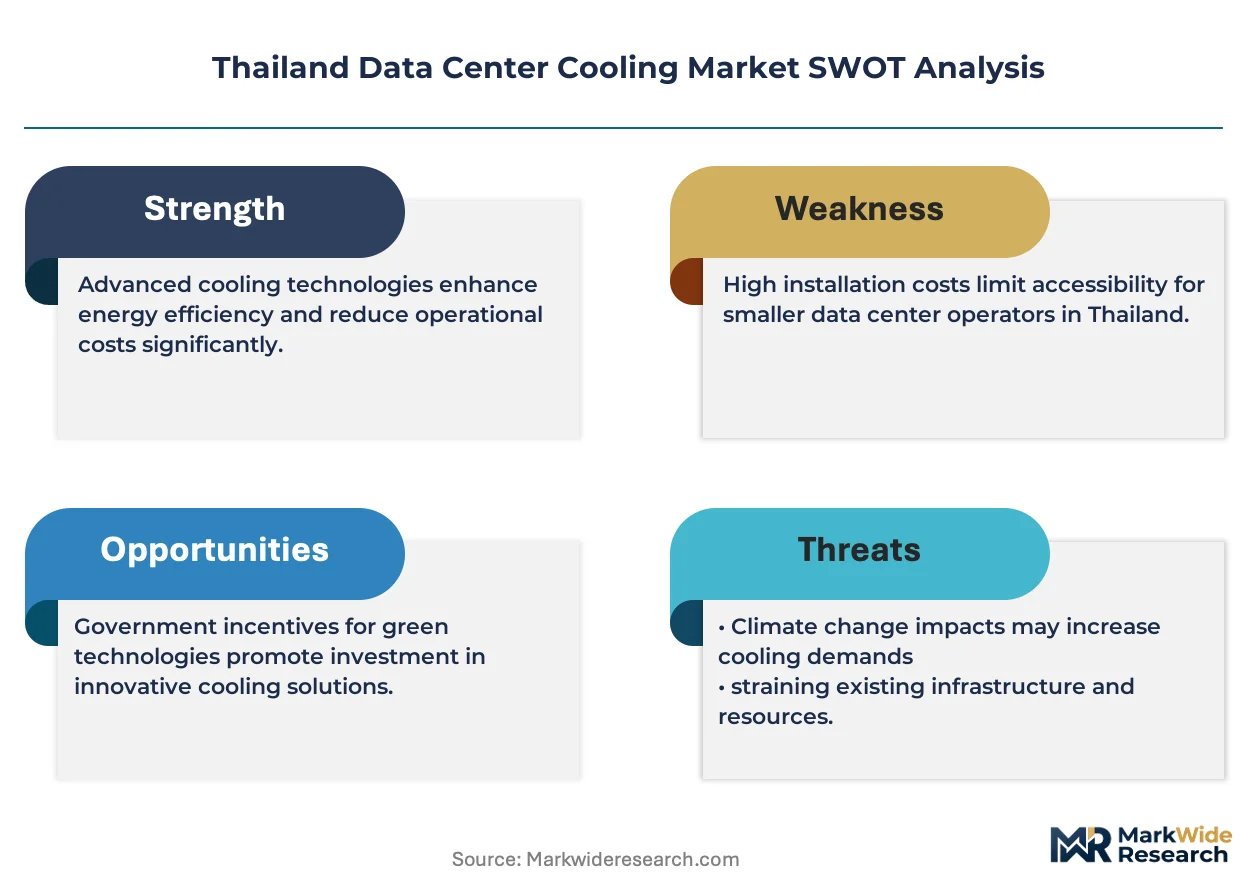
Thailand's Board of Investment coordinates with the Department of Alternative Energy Development and Efficiency to enforce building energy codes that mandate cooling system performance benchmarks for new data center investments. TISI standards and ASHRAE compliance frameworks shape equipment procurement specifications and disqualify uncertified suppliers from government and enterprise tenders. Stakeholders must monitor power density trajectories and regulatory tightening on refrigerant chemistries to align product roadmaps with operational requirements.
Market Dynamics
GPU rack densities exceeding 30 kW are forcing a wholesale architectural pivot from air-cooled to liquid-ready infrastructure across Greater Bangkok campuses. This thermal threshold is compressing design cycles and redrawing supplier qualification criteria.
Growth Catalysts
- BOI Incentive Programs:Thailand's Board of Investment grants eight-year tax holidays for digital infrastructure investments, redirecting regional capital toward liquid-cooled facilities in the Eastern Economic Corridor.
- Hyperscale Buildouts:Cloud service providers are commissioning multi-megawatt campuses with phased modular deployments, creating sustained demand for scalable thermal architectures.
- TISI Certification Mandates:Energy efficiency benchmarks for building systems now disqualify uncertified cooling equipment from government and enterprise tenders, advantaging qualified suppliers.
Market Restraints
- Copper and Aluminum Input Volatility:Heat exchanger fabrication depends on base metal prices that have swung unpredictably, compressing margins for precision air conditioning manufacturers.
- Refrigerant Chemistry Constraints:Thailand's alignment with Kigali Amendment phase-down schedules is limiting availability of high-GWP working fluids for legacy chiller retrofits.
- Specialized Workforce Scarcity:Liquid cooling system commissioning requires certified technicians in short supply across ASEAN, extending deployment timelines.
Strategic Opportunities
- Chonburi and Rayong Provinces:Eastern seaboard zones offer land and power cost advantages for large-campus development underserved by current cooling infrastructure.
- Immersion Cooling Convergence:Dielectric fluid systems paired with warm-water heat rejection are opening new thermal design envelopes for GPU clusters.
- Modular Channel Innovation:Factory-integrated cooling modules shipped in ISO containers are collapsing field installation from months to weeks for cloud providers.
Industry Challenges
- TISI Compliance Timelines:Certification testing for tropical humidity-rated equipment extends product launch cycles by six to nine months.
- Legacy Air System Integration:Hybrid facilities must orchestrate liquid loops with existing CRAH infrastructure without triggering downtime during cutover.
- Refrigerant Handling Certification:Technician licensing requirements under the Department of Alternative Energy Development and Efficiency are tightening faster than training pipeline output.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Thailand Data Center Cooling Market |
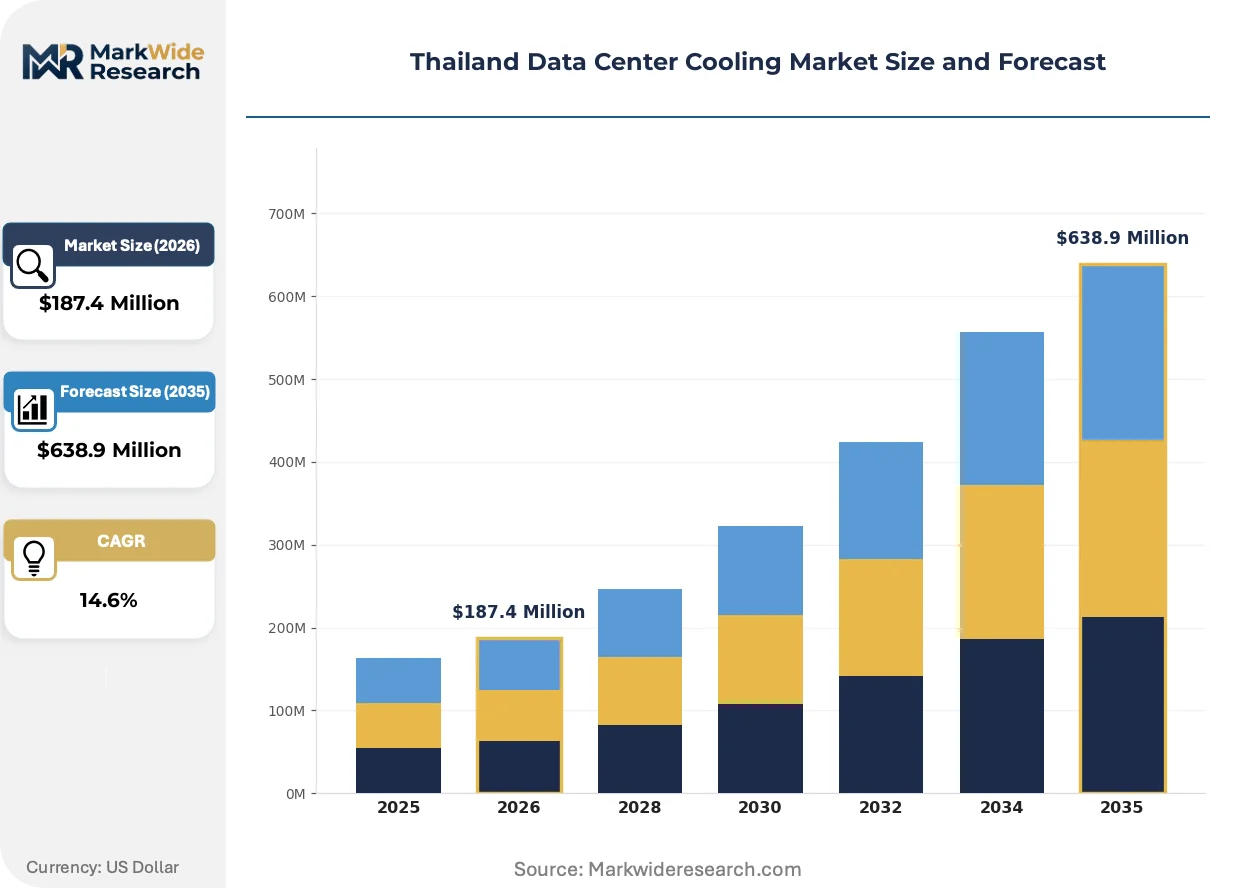
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $638.9 Million |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Cooling Type: Air Cooling, Liquid Cooling, Chilled Beam, Evaporative Cooling End User: Cloud Service Providers, Enterprises, Colocation Facilities, Government Technology: Free Cooling, Refrigerant-based Systems, Pumped Refrigerant, Indirect Cooling Installation Type: New Installations, Upgrades, Retrofits, Modular Systems |
| Companies Covered | Schneider Electric SE, Vertiv Group Corp, Stulz GmbH, Johnson Controls International PLC, Mitsubishi Electric, Daikin, Danfoss A/S, Carrier, Rittal, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Thailand Data Center Cooling Market Trends and Innovations
Mechanical infrastructure is fragmenting into discrete thermal units that align with compute deployment granularity. This decomposition is reshaping procurement patterns and supplier relationships across Thai data center construction.
Direct-to-chip liquid cooling is decomposing the traditional CRAC/CRAH monopoly over thermal management. Hyperscale operators are specifying cold plate manifolds for AI training clusters above 50 kW per rack. This shift is compressing the addressable market for precision air conditioning while expanding demand for heat rejection skids and coolant distribution units.
Thailand's Department of Alternative Energy Development and Efficiency is tightening building energy codes that mandate cooling system performance benchmarks for new investments. These regulations are disqualifying air-cooled designs above certain power density thresholds from receiving BOI incentives. Colocation operators are responding by pre-provisioning liquid infrastructure even in initial build phases.
Buying patterns are consolidating around integrated power and thermal packages rather than discrete equipment procurement. Enterprise data center managers are shifting from component sourcing to architecture contracting, bundling UPS, busway, and cooling into single-vendor performance guarantees. This bundling is most visible in Bangkok financial services deployments where uptime commitments dominate vendor selection criteria.
Thailand Data Center Cooling Market Segmentation
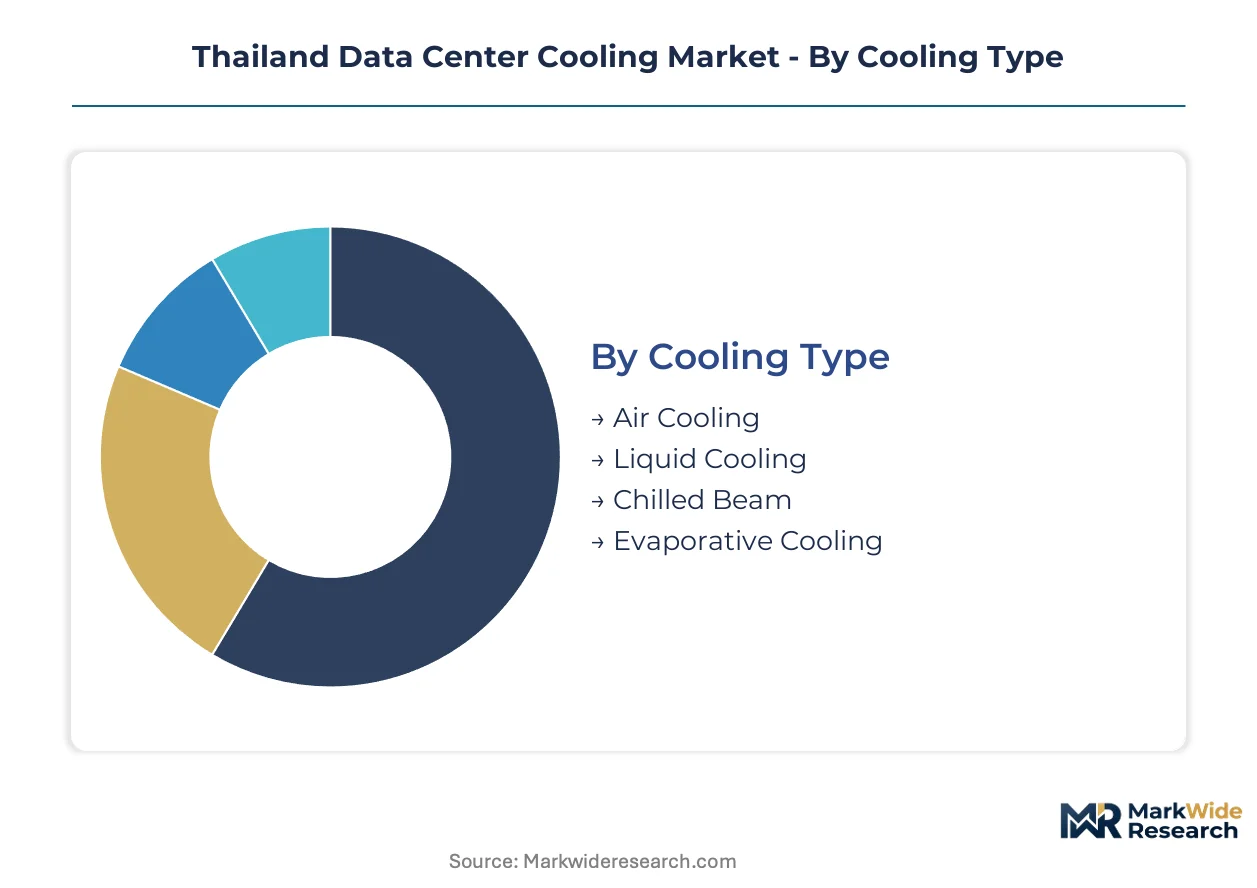
Thailand's data center cooling market fragments across thermal architectures, customer profiles, and deployment modes that respond differently to BOI incentive structures and TISI certification mandates. Each dimension carries distinct procurement patterns and supplier qualification requirements.
Cooling Type:
TISI certification benchmarks bifurcate cooling equipment into qualified and non-qualified tiers, with tropical humidity ratings determining eligibility for government and enterprise tenders.
- Air Cooling:Conventional precision air conditioning and CRAH units dominate legacy enterprise facilities across Bangkok. Demand concentrates in financial services data centers where uptime commitments override efficiency gains, though TISI efficiency mandates are compressing the addressable market for uncertified equipment.
- Liquid Cooling:Direct-to-chip cold plates and coolant distribution units handle GPU rack densities exceeding 30 kW in hyperscale campuses. Eastern Economic Corridor cloud builds are pre-provisioning liquid infrastructure even in initial phases to secure BOI tax holidays.
- Chilled Beam:Passive radiant cooling systems suit low-density enterprise halls with stable thermal loads. Deployment concentrates in government facilities where ASHRAE compliance outweighs power density optimization.
- Evaporative Cooling:Adiabatic systems leverage Thailand's ambient humidity patterns for heat rejection in free-cooling configurations. Regional operators in Rayong Province deploy these for cost-sensitive edge deployments.
Established volume favors Air Cooling; emerging adoption favors Liquid Cooling.
End User:
Procurement authority concentrates with operators whose capital cycles align with BOI incentive windows and modular deployment timelines.
- Cloud Service Providers:Hyperscale operators commission multi-megawatt campuses with phased thermal architectures across Greater Bangkok. Their specification power is compressing supplier margins while accelerating liquid cooling adoption curves.
- Colocation Facilities:International operators seeking ASEAN hub capacity represent the steepest expansion trajectory in the market. Eastern seaboard land costs and power availability are redirecting regional capital toward their multi-tenant builds.
- Enterprises:Bangkok-based financial services and telecom operators maintain captive facilities with conservative refresh cycles. Their procurement favors integrated power and cooling packages with single-vendor uptime guarantees.
- Government:Public sector tenders enforce TISI certification and ASHRAE compliance as disqualifying filters. Department of Alternative Energy Development and Efficiency building codes mandate performance benchmarks that exclude legacy air-cooled designs above density thresholds.
Volume leadership sits with Cloud Service Providers; procurement flexibility sits with Colocation Facilities.
Technology:
Margin structures vary sharply by thermal efficiency tier and refrigerant chemistry constraints under Kigali Amendment phase-down schedules.
- Free Cooling:Air-side and water-side economizers exploit Thailand's ambient temperature bands to reduce mechanical refrigeration hours. Chonburi Province facilities achieve extended economizer hours through elevated supply temperature setpoints.
- Refrigerant-based Systems:Compression chillers and direct expansion units face working fluid availability constraints as high-GWP refrigerants phase down. Retrofit demand is accelerating for lower-GWP alternatives in legacy Bangkok enterprise halls.
- Pumped Refrigerant:Two-phase cooling loops bridge air and liquid architectures for intermediate density racks. Cloud providers deploy these as transition technologies during hybrid facility cutovers.
- Indirect Cooling:Heat wheel and plate exchanger configurations isolate IT air streams from ambient humidity. Tropical-rated equipment extends product launch cycles by six to nine months due to TISI testing protocols.
Operational maturity favors Refrigerant-based Systems; efficiency premiums favor Free Cooling.
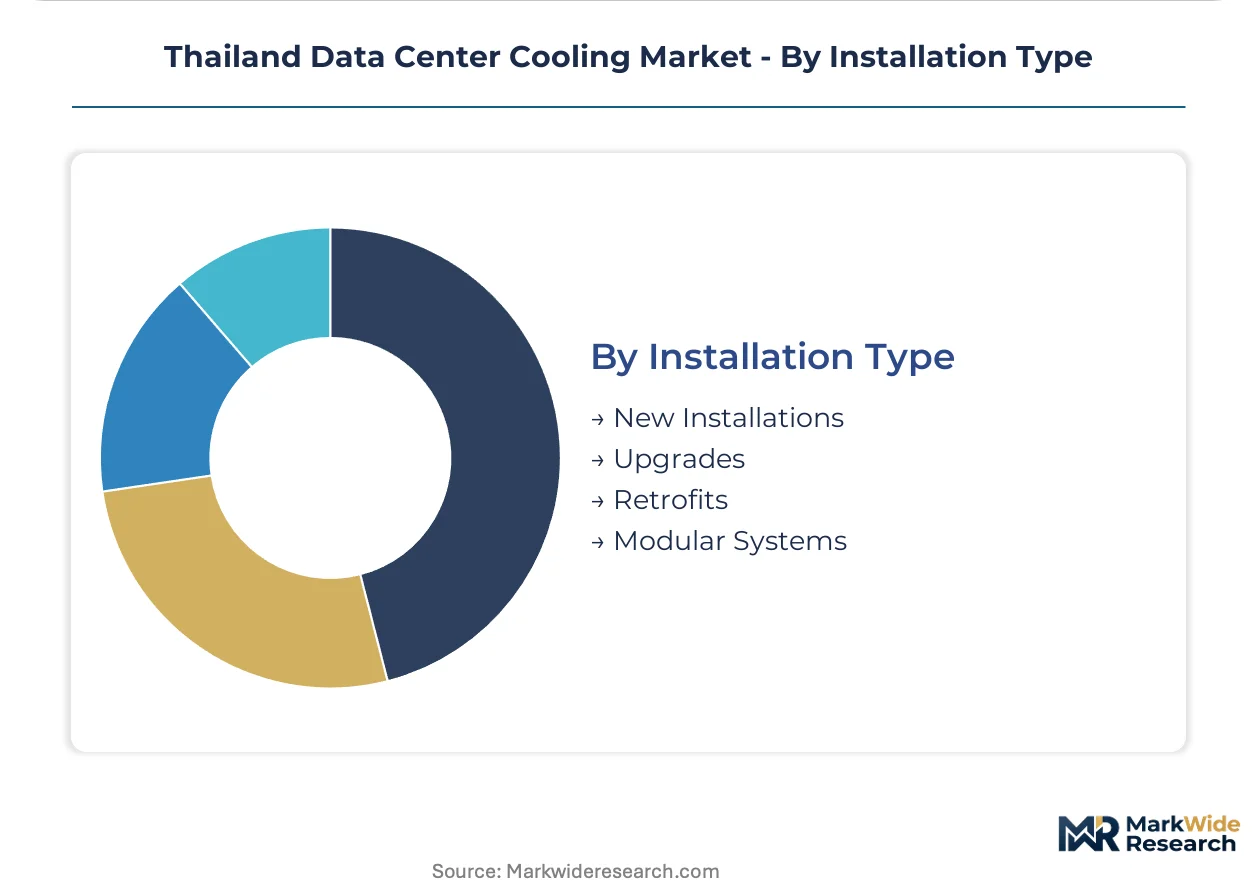
Installation Type:
Deployment velocity determines competitive positioning as cloud providers collapse field installation timelines from months to weeks.
- New Installations:Greenfield campuses in the Eastern Economic Corridor specify liquid-ready infrastructure from commissioning. BOI incentive eligibility requires cooling system performance benchmarks that favor advanced thermal architectures.
- Modular Systems:Factory-integrated cooling modules shipped in ISO containers align with phased hyperscale buildouts. Cloud service providers specify these for deployment velocity across Rayong and Chonburi provinces.
- Upgrades:Mid-life capacity expansions in existing Bangkok facilities face downtime constraints during thermal system cutovers. Hybrid liquid-air orchestration requires specialized commissioning technicians in short supply across ASEAN.
- Retrofits:Legacy chiller replacements confront refrigerant chemistry constraints and copper price volatility. Precision air conditioning manufacturers face margin compression on heat exchanger fabrication costs.
Capital deployment favors New Installations; supply chain agility favors Modular Systems.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Eastern Economic Corridor's high-voltage transmission backbone and deep-water port access at Laem Chabang underwrite Thailand's emergence as ASEAN's preferred data center destination. Landed power costs and submarine cable landing stations concentrate investment gravity along this seaboard corridor.
Bangkok Metropolitan Region
Enterprise captive facilities and financial services data centers dominate thermal demand in the capital. The Department of Alternative Energy Development and Efficiency enforces building energy codes that mandate cooling performance benchmarks for new investments. Lat Phrao and Ratchada districts host legacy air-cooled halls now facing TISI certification pressure during refresh cycles.
Chonburi Province
Hyperscale cloud campuses specify liquid-ready infrastructure from initial commissioning to secure BOI tax holidays. Free cooling economizers exploit elevated supply temperature setpoints to extend mechanical refrigeration-free operating hours. Amata City and Pinthong industrial estates attract modular cooling deployments for phased buildouts.
Rayong Province
Colocation operators seeking ASEAN hub capacity redirect capital toward Eastern seaboard land banks with favorable power tariffs. Evaporative adiabatic systems suit cost-sensitive edge deployments leveraging ambient humidity patterns. Map Ta Phut and Pluak Daeng zones concentrate international multi-tenant builds with pre-provisioned liquid loops.
Pathum Thani and Nonthaburi
Telecom and enterprise facilities in these northern extensions face hybrid liquid-air orchestration challenges during thermal system cutovers. The Board of Investment coordinates with provincial authorities on digital infrastructure zoning. Rangsit and Pak Kret industrial corridors see mid-life capacity expansions constrained by specialized technician scarcity.
Thailand Data Center Cooling Market Competitive Landscape
Listed leaders compete with private specialists across integrated system architectures and component-level thermal management. The supplier landscape bifurcates into qualified tiers based on TISI certification for tropical humidity-rated equipment. Three archetypes dominate: integrated power-cooling platform vendors, precision air conditioning specialists, and liquid cooling component suppliers. Competitive moves center on factory-integrated modular systems and certification-driven qualification barriers.
Within the integrated platform tier, Schneider Electric SE exemplifies architecture contracting approaches that bundle UPS, busway, and cooling into single-vendor performance guarantees. Vertiv Group Corp occupies a specialist position in thermal management for high-density rack configurations. Stulz GmbH represents precision air conditioning engineering focused on tropical humidity loads. These three anchors illustrate how supplier positioning fragments across mechanical infrastructure decomposition trends and procurement consolidation toward integrated packages.
| Leading Market Players |
|---|
| Schneider Electric SE |
| Vertiv Group Corp |
| Stulz GmbH |
| Johnson Controls International PLC |
| Mitsubishi Electric |
| Daikin |
| Danfoss A/S |
| Carrier |
| Rittal |
| Others |
Pricing and Supply Chain Analysis
Six-to-nine-month TISI certification lead times for tropical humidity-rated equipment concentrate pricing power among qualified suppliers while compressing margins for uncertified competitors awaiting test completion. This inventory cycle advantage allows certified manufacturers to command premium positioning in government and enterprise tenders, while buyers facing phased hyperscale buildouts absorb higher unit costs to secure BOI-compliant delivery schedules.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates procurement, with TISI certification status and liquid-cooling readiness as the primary differentiation drivers. Premium tiers capture hyperscale cloud providers pre-provisioning liquid infrastructure for BOI tax holidays, while economy tiers serve cost-sensitive edge operators in Rayong Province deploying evaporative adiabatic systems. Pricing pressure stems from copper and aluminum input volatility compressing heat exchanger fabrication margins, with colocation facilities exhibiting highest price sensitivity due to multi-tenant cost allocation constraints.
Supply Chain Analysis
Strait of Malacca transit underwrites component flows for precision air conditioning and liquid cooling systems serving Greater Bangkok campuses. Manufacturing concentration in China, South Korea, and Japan supplies heat rejection skids, coolant distribution units, and dielectric fluids to Thai integrators. Base metal dependencies—copper tubing, aluminum fins, stainless steel manifolds—expose margin structures to commodity volatility. Single-source vulnerability around specialized refrigerant chemistries under Kigali Amendment phase-down schedules compounds risk. Distribution runs through factory-integrated modular channels shipped in ISO containers to collapse field installation timelines.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory-moat arena where TISI certification entrenchment and BOI incentive alignment create durable switching costs for qualified suppliers. Network effects concentrate among integrated power-cooling platform vendors capable of anchoring large-campus performance guarantees.
For Market Incumbents: Fortify certification pipelines by accelerating tropical humidity test cycles at TISI-accredited labs, compressing six-to-nine-month launch delays that cede share to pre-qualified rivals. Deepen backward integration into copper and aluminum heat exchanger fabrication to offset commodity volatility eroding precision air conditioning margins. Anchor defensive positioning against emerging liquid-cooling component specialists by bundling UPS, busway, and thermal architectures into single-vendor uptime commitments for Bangkok financial services deployments.
For New Entrants and Emerging Players: Liquid cooling commissioning services represent the most penetrable white-space layer, as certified technician scarcity across ASEAN extends deployment timelines for hyperscale operators. Target Rayong Province colocation builds seeking ASEAN hub capacity, where pre-provisioned liquid loops outpace incumbent air-cooling refresh cycles. Pursue go-to-market alignment with Eastern Economic Corridor industrial estate developers offering turnkey thermal infrastructure packages to cloud providers with phased buildout requirements.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with under-monetized data center cooling divisions lacking TISI certification investment. Long-term viability hinges on liquid-cooling transition exposure rather than legacy air-cooling maintenance revenue. Monitor GPU rack density trajectories exceeding 50 kW per rack as the inflection signal forcing wholesale architectural pivots from mechanical refrigeration to direct-to-chip cold plate deployments.
| Strategic Initiative | Industry Significance |
|---|---|
| TISI Certification Acceleration | Reduces product launch cycles by 3-4 months, capturing BOI incentive windows before competitors complete testing protocols. |
| Backward Integration into Heat Exchangers | Captive copper and aluminum fabrication insulates margin structures from base metal price swings compressing precision air conditioning profitability. |
| Modular ISO Container Deployment | Factory-integrated cooling modules collapse field installation from months to weeks for cloud providers with phased Eastern Economic Corridor buildouts. |
| Liquid Cooling Technician Training Pipeline | Certified commissioning capacity alleviates ASEAN-wide scarcity extending hyperscale deployment timelines and deferring revenue recognition. |
| Integrated Power-Thermal Architecture Bundling | Single-vendor performance guarantees align with Bangkok financial services procurement consolidation toward uptime-centric vendor selection. |
Research Methodology
Cross-validation between primary interviews with data center infrastructure directors, thermal engineering leads at hyperscale operators, BOI investment promotion officers, and TISI certification specialists anchors the qualitative findings. Secondary validation draws from Board of Investment incentive disclosure records, Department of Alternative Energy Development and Efficiency building code filings, ASHRAE technical guidelines, and hyperscaler capital expenditure disclosures. Bottom-up equipment procurement patterns triangulate against top-down construction pipeline assessments across Greater Bangkok and Eastern Economic Corridor zones.
Sensitivity analysis around GPU rack density trajectories and refrigerant chemistry phase-down schedules shapes the analytical framework across the projection horizon. Segmentation dimensions modeled include cooling type architecture, end-user procurement authority, installation deployment mode, and regional regulatory cluster alignment with BOI incentive eligibility. CAGRs derive from equipment shipment volumes correlated with construction completion timelines and power density upgrade cycles. Industry-specific forecast inputs encompass tropical humidity equipment derating factors and liquid cooling adoption curves tied to AI training cluster deployments.
Forecasts assume regulatory continuity in Thailand's Board of Investment incentive regimes and Kigali Amendment alignment schedules; material policy shifts on digital infrastructure zoning or refrigerant availability would require re-modeling. Scenario boundaries exclude macroeconomic disruptions to ASEAN capital flows and construction labor availability. Practitioners should keep alternative scenarios live as GPU rack density trajectories and TISI certification queue lengths evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center Cooling
Canada Data Center Cooling Market
Data Center Cooling
United Arab Emirates Data Center Cooling Market
Data Center Cooling
Denmark Data Center Cooling Market
Data Center Cooling
Latin America Data Center Cooling Market
Data Center Cooling
Taiwan Data Center Cooling Market
Data Center Cooling
Ireland Data Center Cooling Market
Data Center Cooling
Saudi Arabia Data Center Cooling Market
Data Center Cooling
Brazil Data Center Cooling Market
Data Center Cooling
South Korea Data Center Cooling Market
Data Center Cooling
CPU Water Cooling Radiator Market
Data Center Cooling
Hong Kong Data Center Cooling Market
Data Center Cooling
Philippines Data Center Cooling Market
Data Center Cooling
AI Datacenter Liquid Cooling Market
Data Center Cooling
India Data Center Cooling Market
Data Center Cooling
Vietnam Data Center Cooling Market
Data Center Cooling
Indonesia Data Center Cooling Market