
 Facial Tracking Solution Market | 2026-2036
Facial Tracking Solution Market Size, Share, and Industry Trends Forecast 2026-2036
Facial Tracking Solution Market Foresight
Chinese sensor module producers is broadening output for infrared and 3D camera arrays, expanding the upstream supply base for facial tracking systems. Paravision leverages deep learning architectures optimized for edge deployment in security infrastructure. FaceFirst anchors its position through channel control across North American retail and aviation verticals. NEC NeoFace dominates public-sector biometric deployments in Japan and select Southeast Asian markets.
Facial tracking solutions encompass software algorithms, dedicated hardware, and sensor-integrated SDKs that detect, analyze, and follow human facial features in real time, typically processing 30-120 frames per second with sub-millimeter landmark precision for identity verification, emotion detection, or gaze estimation. The hardware segment sustains premium margins where specialized infrared and time-of-flight sensors require custom calibration and thermal management. Software and SDK offerings compete on inference speed and cross-platform compatibility, with machine learning-based approaches displacing rule-based 2D methods in accuracy-critical security and automotive applications. Entertainment and gaming represent emerging demand pockets where low-latency 3D facial capture enables immersive avatar control.
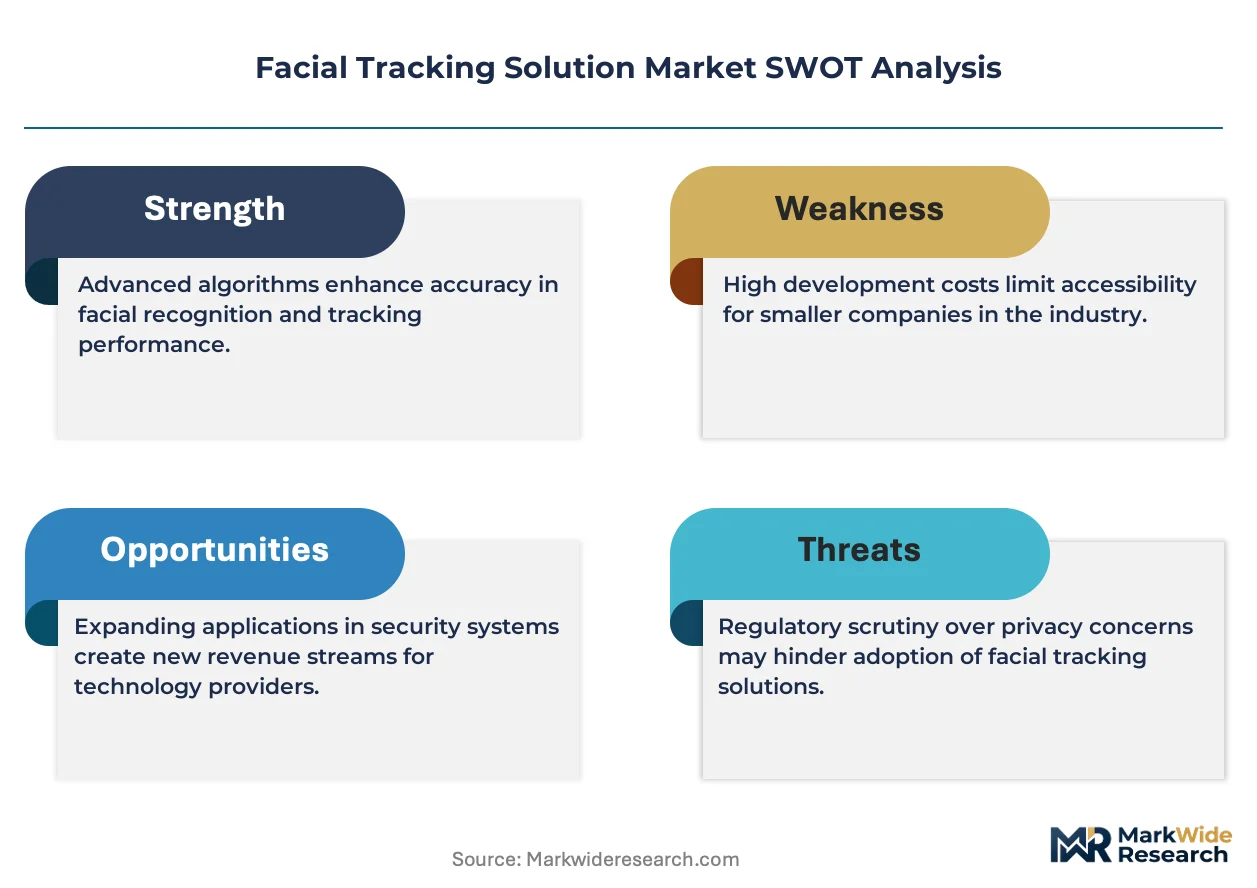
The EU AI Act classifies remote biometric identification as high-risk, mandating conformity assessments and human oversight that reshape product development cycles for vendors seeking European market access. The FDA regulates certain clinical deployments of facial analysis in healthcare diagnostics, while China's SAMR and MIIT enforce GB standards for biometric data collection and algorithm transparency. Stakeholders must monitor diverging regulatory timelines across jurisdictions to align R&D roadmaps with compliance requirements before scaling cross-border deployments.
Market Dynamics
The EU AI Act's high-risk classification of remote biometric identification is compressing product development timelines and forcing architectural redesigns across European-bound systems. Automotive OEMs in Germany and tier-one suppliers now embed conformity-by-design protocols upstream of hardware finalization.
Growth Catalysts
- Driver Monitoring Mandates:Automotive OEMs integrate facial tracking into cabin safety systems to meet evolving vehicle safety standards. Tier-one suppliers around Stuttgart scale production of infrared sensor arrays for production-line deployment.
- EU AI Act Conformity Requirements:The regulation's human-oversight provisions create sustained demand for audit-ready software architectures. Vendors redesign inference pipelines to accommodate real-time intervention capabilities.
- Time-of-Flight Sensor Maturation:Chinese module producers expand wafer-level packaging capacity for 3D camera arrays. This upstream expansion reduces component lead times for system integrators.
Market Restraints
- Specialized Sensor Cost Structure:Custom thermal management and calibration protocols for infrared arrays sustain premium hardware pricing. Cost compression remains limited by wafer-level precision requirements.
- Supply Concentration in East Asian Module Production:Infrared and 3D camera array manufacturing clusters in Shenzhen and Shanghai. Geographic concentration creates vulnerability to export control adjustments.
- Rule-Based Algorithm Obsolescence:Legacy 2D landmark detection methods face displacement by deep learning architectures. Technical debt in installed security infrastructure slows upgrade cycles.
Strategic Opportunities
- Healthcare Diagnostic Applications:FDA-regulated clinical deployments of facial analysis for neurological and dermatological screening remain underpenetrated. Algorithm developers pursue 510(k) clearance pathways for specific indications.
- Immersive Entertainment Integration:Low-latency 3D facial capture enables real-time avatar control in gaming and virtual production studios. Content creators in Los Angeles and Tokyo pilot direct-to-render pipelines.
- Aviation Passenger Processing:Biometric boarding systems at Dubai International and Singapore Changi demonstrate throughput advantages. Airlines evaluate facial tracking for lounge access and baggage claim integration.
Industry Challenges
- Cross-Platform SDK Fragmentation:Inference optimization across ARM, x86, and custom NPU architectures demands specialized engineering talent. Talent scarcity in embedded machine learning engineering constrains development velocity.
- Multi-Jurisdiction Certification Parallelism:Vendors must simultaneously satisfy EU AI Act conformity assessments, FDA quality system requirements, and China's GB algorithm transparency standards. Documentation overhead extends time-to-revenue.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Facial Tracking Solution Market |
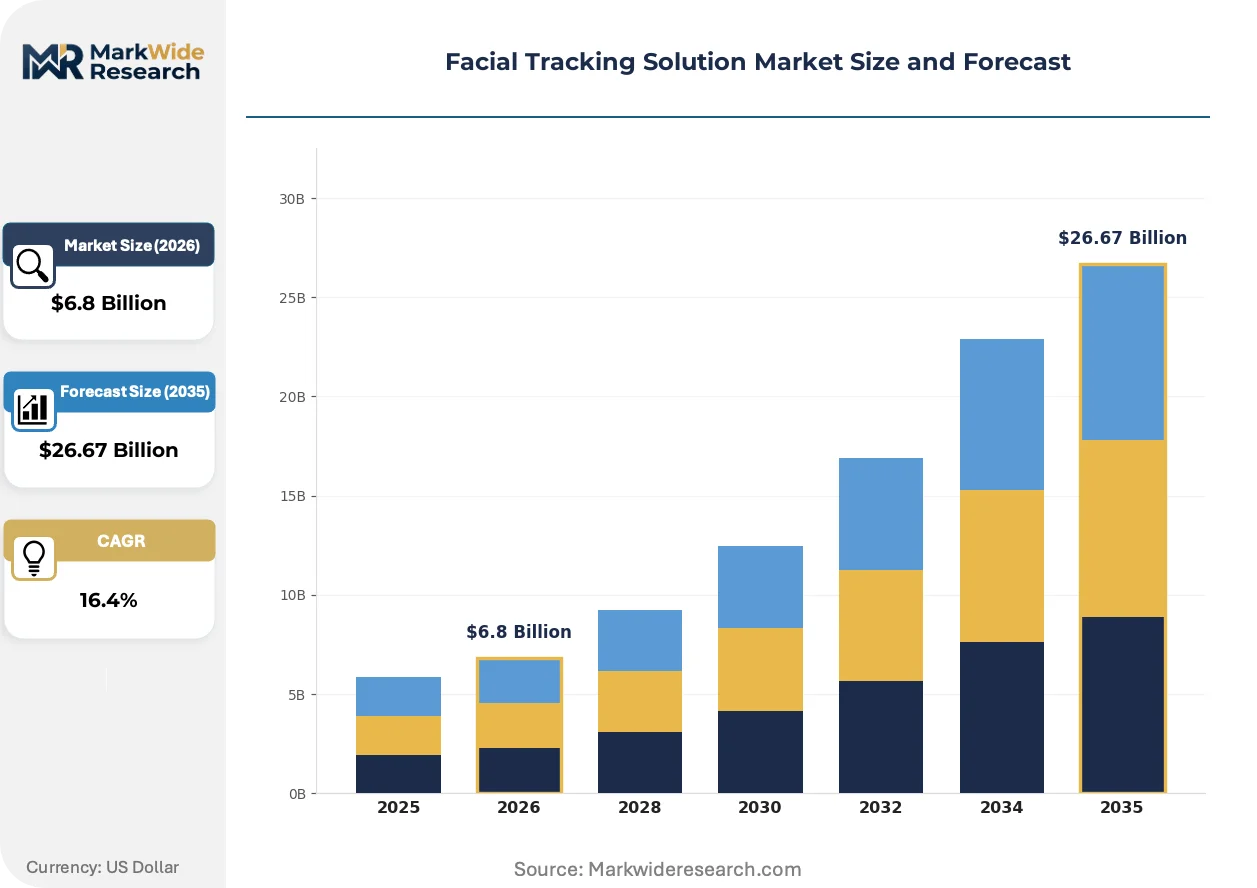
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $26.67 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Software, Hardware, SDK, Sensor End User: Retail, Healthcare, Automotive, Entertainment Technology: 2D, 3D, Infrared, Machine Learning Application: Security, Marketing, User Interaction, Gaming |
| Companies Covered | Paravision, FaceFirst, Clearview AI, Amazon Rekognition, TrueFace, NEC NeoFace, Oosto Vision AI, Visage Technologies, Cognitec FaceVACS, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Facial Tracking Solution Market Shifts & Advancements
Edge-optimized neural architectures are displacing cloud-dependent inference models, while regulatory fragmentation across jurisdictions forces modular compliance engineering. These shifts compress the viable product lifecycle and reward architectural flexibility.
Time-of-flight depth sensing is consolidating around standardized wafer-level packaging formats that reduce module footprint and thermal dissipation requirements. Automotive OEMs in Germany adopt these compact arrays for cabin monitoring systems at scale. The technology is consolidating supplier tiers as module producers absorb lens-assembly functions previously performed by discrete vendors.
The EU AI Act's high-risk system classification mandates third-party conformity assessment before market placement. Product development cycles now incorporate audit-ready documentation from initial architecture phases. European security infrastructure deployments face the steepest compliance burden, with vendors pre-certifying edge inference hardware through notified bodies in Munich and Rotterdam.
Buyers in North American retail and aviation verticals now demand inference-speed guarantees and cross-platform compatibility as baseline procurement criteria. Traditional SDK licensing models face pressure from outcome-based performance contracts tied to false-accept and false-reject rates. This specification intensity is most visible in aviation biometric boarding deployments, where throughput per lane directly determines contract value.
Facial Tracking Solution Market Segmentation
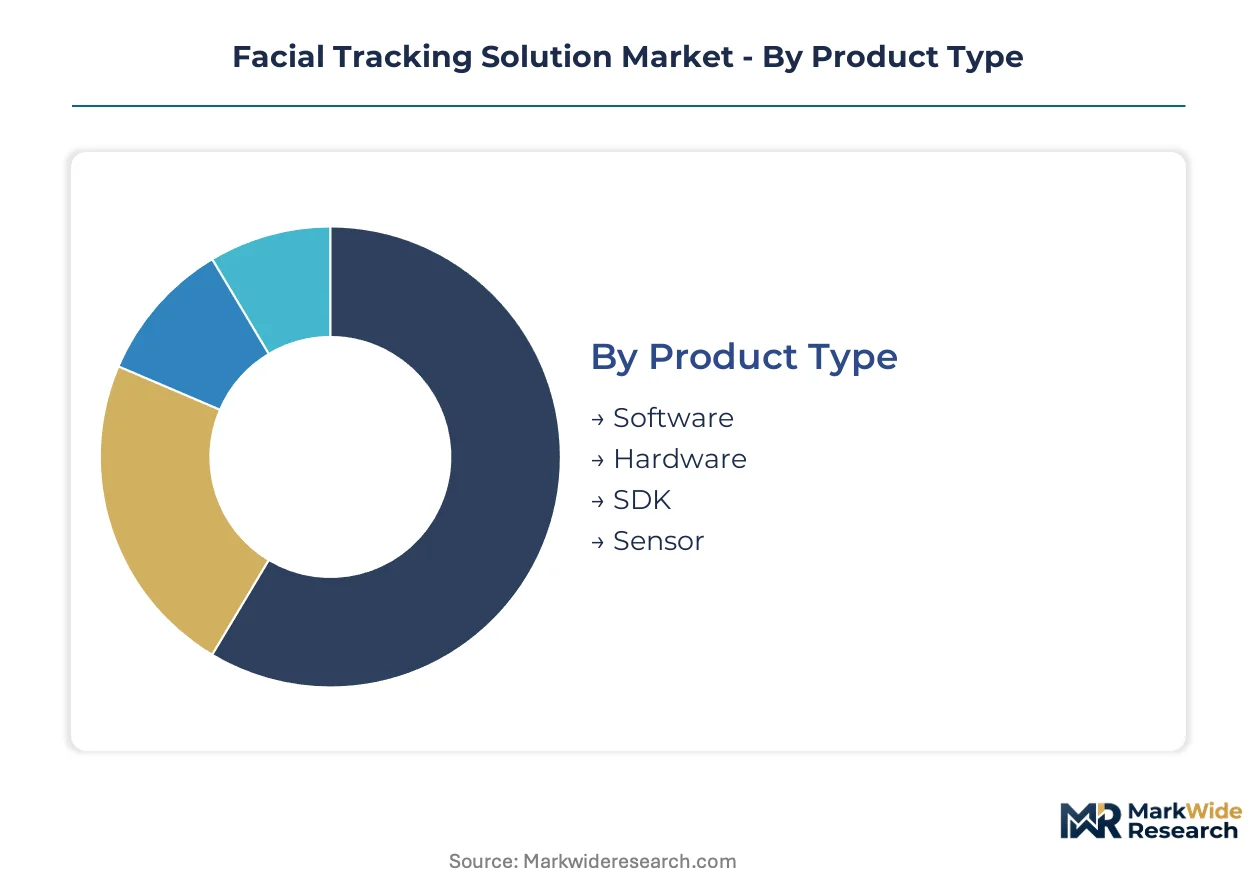
Facial tracking solutions fragment across four distinct taxonomies that determine procurement logic, margin structure, and compliance burden. Product type dictates hardware-software revenue mix and thermal engineering requirements. End user concentration in automotive and security verticals shapes R&D allocation and certification timelines.
Product Type:
Supply concentration in Shenzhen and Shanghai wafer-level packaging facilities directly shapes cost structures and lead-time reliability across hardware-dependent segments.
- Hardware:Infrared and time-of-flight sensor arrays with custom thermal management and calibration protocols command premium positioning. Stuttgart automotive OEMs and tier-one suppliers absorb the bulk of production-line volumes for driver monitoring systems. Specialized wafer-level precision requirements limit cost compression despite Chinese module capacity expansion.
- Software:Deep learning inference engines optimized for edge deployment displace rule-based 2D methods in accuracy-critical applications. EU AI Act conformity assessments and FDA quality system requirements extend documentation overhead for vendors targeting regulated verticals. Real-time intervention capabilities for human-oversight mandates reshape architecture design.
- SDK:Cross-platform compatibility across ARM, x86, and custom NPU architectures demands scarce embedded machine learning engineering talent. Inference speed guarantees have become baseline procurement criteria in North American retail and aviation verticals.
- Sensor:Discrete infrared module producers in China consolidate lens-assembly functions previously performed by separate vendors, compressing supplier tiers.
Hardware absorbs the bulk of installed capacity; software is expanding most quickly as machine learning architectures displace legacy methods.
End User:
Application maturity varies sharply across verticals, with regulatory intensity and safety-critical requirements determining technology selection and certification pathways.
- Automotive:Driver monitoring mandates in Germany and surrounding production clusters integrate facial tracking into cabin safety systems at scale. EU vehicle safety standards evolution sustains demand for infrared sensor arrays with sub-millimeter landmark precision.
- Security:Remote biometric identification deployments face the steepest EU AI Act compliance burden, with third-party conformity assessment through Munich and Rotterdam notified bodies mandatory before market placement. Audit-ready documentation requirements compress product development cycles.
- Healthcare:FDA-regulated clinical deployments for neurological and dermatological screening remain underpenetrated. Algorithm developers pursue 510(k) clearance pathways for specific diagnostic indications.
- Retail:Biometric boarding systems at Dubai International and Singapore Changi demonstrate throughput advantages, with airlines evaluating lounge access and baggage claim integration.
Automotive commands the deepest production integration; healthcare is climbing the fastest as diagnostic applications pursue regulatory clearance.
Technology:
Performance tier differentiation separates legacy architectures from next-generation inference methods, with accuracy thresholds determining viable deployment contexts.
- Machine Learning:Neural architectures optimized for edge deployment displace cloud-dependent inference models, reducing latency for real-time avatar control in gaming and virtual production. Los Angeles and Tokyo content creators pilot direct-to-render pipelines with low-latency 3D facial capture.
- 3D:Time-of-flight depth sensing consolidates around standardized wafer-level packaging formats that reduce module footprint and thermal dissipation. German automotive OEMs adopt compact arrays for cabin monitoring systems.
- Infrared:Specialized arrays with custom calibration sustain premium hardware margins where thermal management precision is non-negotiable.
- 2D:Rule-based landmark detection methods face technical debt burdens in installed security infrastructure, slowing upgrade cycles despite obsolescence pressure.
Machine learning captures the steepest expansion trajectory; 2D retains residual installed base in cost-sensitive legacy deployments.
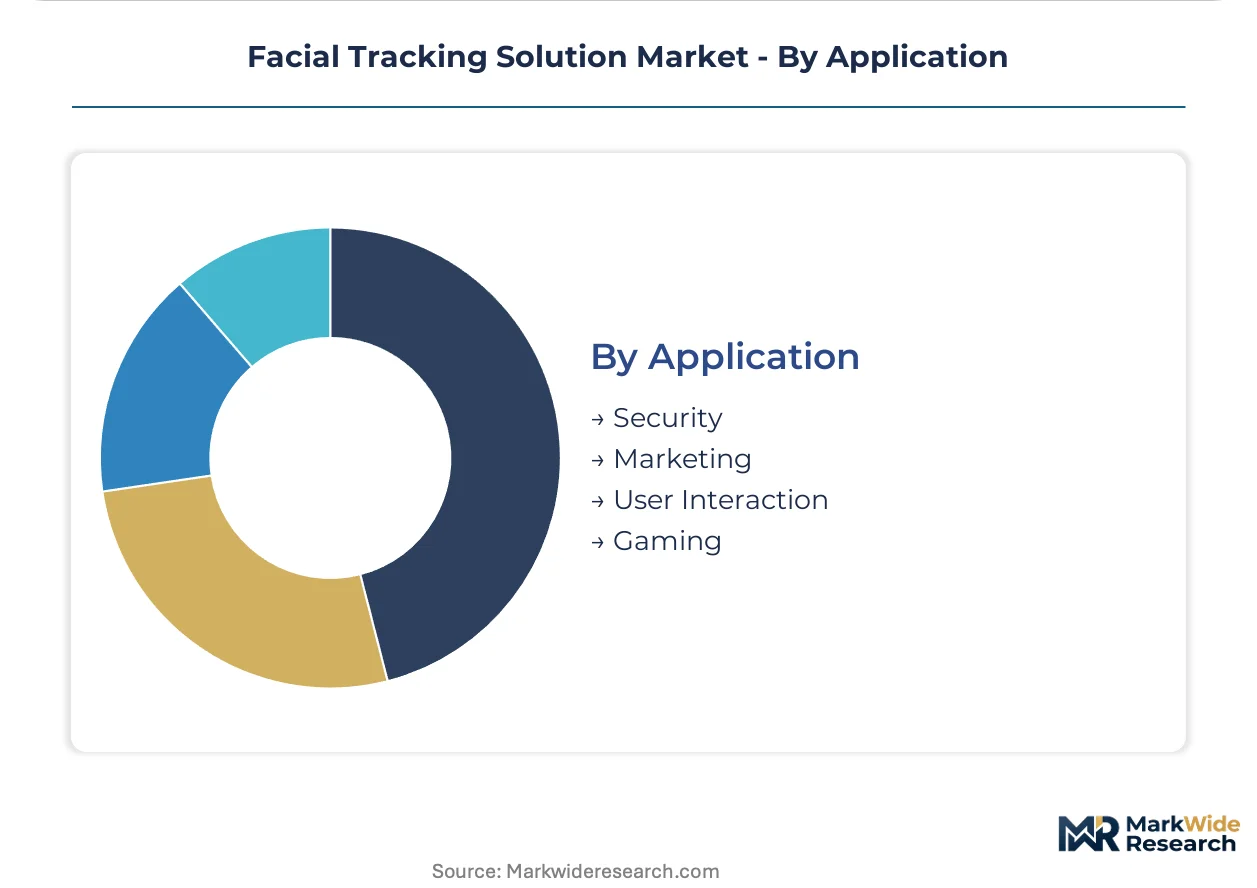
Application:
Procurement specification intensity varies by throughput sensitivity and false-accept rate tolerance, with aviation and security verticals demanding outcome-based performance contracting.
- Security:Remote biometric identification systems carry EU AI Act high-risk classification, mandating human oversight and real-time intervention capabilities. European infrastructure deployments face pre-certification requirements for edge inference hardware.
- Gaming:Immersive entertainment integration leverages low-latency 3D facial capture for real-time avatar control. Virtual production studios in Los Angeles and Tokyo drive demand for direct-to-render pipeline compatibility.
- User Interaction:Gaze estimation and emotion detection applications span automotive cabin monitoring and retail analytics, with cross-platform SDK compatibility as baseline requirement.
- Marketing:Audience attention measurement and demographic analysis applications compete on inference speed and privacy-compliant data handling.
Security holds the deepest regulatory embedding; gaming is gaining share fastest as immersive content production scales.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Wafer-level packaging capacity in Shenzhen and Shanghai anchors the upstream supply base for infrared and 3D camera arrays feeding facial tracking system integrators worldwide.
Germany
Automotive OEMs and tier-one suppliers cluster around Stuttgart and Munich for driver monitoring system deployment. The EU AI Act mandates third-party conformity assessment through Munich and Rotterdam notified bodies before market placement. Production-line integration of infrared sensor arrays scales across Baden-Württemberg manufacturing corridors.
United States
FDA-regulated clinical deployments for neurological and dermatological screening drive healthcare algorithm development. The FAA evaluates biometric boarding systems for aviation passenger processing throughput. Los Angeles content creators pilot direct-to-render pipelines with low-latency 3D facial capture for virtual production studios.
China
MIIT and SAMR enforce GB standards for biometric data collection and algorithm transparency across module production. Shenzhen wafer-level packaging facilities expand output for infrared and time-of-flight sensors. Shanghai lens-assembly consolidation absorbs functions previously performed by discrete vendors.
Japan
METI standards guide public-sector biometric infrastructure procurement for railway and airport deployments. NEC NeoFace anchors domestic market positioning through government contract concentration. Tokyo studios drive immersive entertainment integration with real-time avatar control specifications.
United Arab Emirates
Dubai International Airport demonstrates biometric boarding throughput advantages for lounge access integration. MOHAP frameworks govern healthcare facial analysis deployment in clinical settings. Aviation vertical demand concentrates in Dubai and Abu Dhabi hub infrastructure expansion.
Facial Tracking Solution Market Competitive Landscape
Global majors compete with regional champions across regulatory certification pathways and vertical-specific deployment expertise. The vendor base organizes into three tiers: automotive-integrated hardware suppliers, security-focused software specialists, and cross-platform SDK providers. Strategic differentiation centers on conformity-by-design protocols for EU AI Act compliance and edge-optimized inference architectures. Dominant competitive moves include geographic expansion through notified body pre-certification and technology licensing for automotive cabin monitoring integration.
Within the security infrastructure tier, Paravision and Clearview AI exemplify deep learning architecture optimization for high-accuracy biometric identification. NEC NeoFace occupies a position representing public-sector deployment concentration in East Asian markets. FaceFirst anchors North American retail and aviation vertical positioning through channel control specialization. These three company profiles illustrate the segmentation between regulatory-intensive European-bound systems, government-centric Asian deployments, and commercial-vertical Western markets.
| Leading Market Players |
|---|
| Paravision |
| FaceFirst |
| Clearview AI |
| Amazon Rekognition |
| TrueFace |
| NEC NeoFace |
| Oosto Vision AI |
| Visage Technologies |
| Cognitec FaceVACS |
| Others |
Supply & Pricing Matrix
Wafer-level packaging consolidation in Shenzhen and Shanghai anchors both component availability and hardware margin structures for facial tracking system integrators. This upstream integration pattern compresses supplier tiers while sustaining premium positioning for specialized infrared arrays requiring custom thermal calibration.
Pricing Analysis
Extended warranty and calibration service bundling separates premium hardware tiers from unbundled SDK licensing in procurement negotiations. Three-tier pricing structure across premium, standard, and economy levels reflects EU AI Act certification grade and volume scale. Cost compression in standard-tier sensor modules is intensifying because Chinese wafer-level capacity expansion feeds downstream competition. Tier-one automotive suppliers in Stuttgart exhibit lowest price sensitivity; retail analytics buyers in North America demonstrate highest elasticity.
Supply Chain Analysis
Single-source vulnerability sits with Shenzhen wafer-level packaging facilities for time-of-flight sensor arrays. Infrared module production draws from China, South Korea, and Japan; specialized lens assemblies feed from German precision optics clusters. German automotive OEMs and tier-one suppliers absorb the bulk of production-line volumes for driver monitoring systems. Distribution runs through direct OEM supply agreements for hardware, with SDK platforms delivered via cloud marketplaces and channel partners.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The facial tracking solution market is becoming a vertical-integration race as vendors pursue captive control over infrared sensor calibration protocols to defend margin structures against commoditization pressure.
For Market Incumbents: Deploy conformity-by-design engineering protocols to compress EU AI Act certification timelines before hardware finalization. Secure pre-certification through Munich and Rotterdam notified bodies to lock out late entrants. Deepen backward integration into wafer-level packaging partnerships in Shenzhen to secure component allocation priority against emerging entrant demand surges. For New Entrants and Emerging Players: EU AI Act high-risk classification in Europe opens a window for audit-ready software architectures targeting mid-tier security integrators underserved by incumbent documentation overhead. Pursue 510(k) clearance pathways for FDA-regulated healthcare diagnostic applications as the most penetrable vertical. Lead with outcome-based performance contracting tied to false-accept rates rather than traditional SDK licensing. For Investors and Strategic Acquirers: Exit pathways concentrate in automotive cabin monitoring integration specialists with established Tier 1 supplier relationships. Long-term viability favors vendors with modular compliance engineering capable of satisfying divergent EU AI Act, FDA, and China GB standards simultaneously. Watch for inflection when aviation biometric boarding deployments at Dubai International and Singapore Changi shift from pilot to fleet-wide rollout.| Strategic Initiative | Industry Significance |
|---|---|
| Notified Body Pre-Certification | EU AI Act conformity assessment through Munich bodies accelerates European market access timelines. |
| Wafer-Level Packaging Partnership | Upstream control over Shenzhen sensor module capacity secures allocation priority for automotive OEMs. |
| Healthcare Regulatory Clearance | FDA 510(k) submission for neurological screening opens underpenetrated diagnostic application vertical. |
| Aviation Biometric Integration | Dubai International throughput demonstrations validate lounge access and baggage claim expansion. |
| Edge Inference Optimization | ARM and custom NPU architecture compatibility addresses talent scarcity in embedded ML engineering. |
Research Methodology
Document review covered regulatory filings with EU notified bodies, FDA 510(k) submission databases, and Chinese GB standard documentation, complemented by interviews with automotive platform engineers, biometric software architects, Tier 1 supplier procurement leads, and healthcare diagnostic algorithm developers. Secondary validation drew from customs trade data, SEC filings of publicly traded sensor module producers, and aviation infrastructure procurement records. Bottom-up segment sizing triangulated against top-down market aggregation.
Segment-level projections across hardware, software, SDK, and sensor categories were generated through the analysis window using automotive production forecasts, security infrastructure deployment pipelines, and healthcare regulatory clearance timelines. Technology adoption curves for machine learning versus rule-based architectures were modeled against EU AI Act implementation phases. CAGRs were derived from regression analysis of historical pricing trajectories and capacity expansion announcements.
The model assumes a particular technology adoption path; alternative pathways for edge-optimized neural architectures displacing cloud-dependent inference would alter the outlook. Forecasts reflect assumptions about regulatory timeline adherence, automotive safety standard evolution, and wafer-level packaging capacity expansion. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors
Lidar Market
Sensors
Bluetooth Photo Capture Device Market
Sensors
Alcohol Sensor Market
Sensors
In-Counter Barcode Scanners Market
Sensors
Vibration Monitoring Market
Sensors
Wireless RFID Readers Market
Sensors
Indoor Air Quality Monitor Market
Sensors
Indoor Positioning and Navigation Market
Sensors
North America Eye Tracking Solutions Market
Sensors
Active Noise and Vibration Control (ANVC) Systems Market
Sensors
Conveyor Monitoring Market
Sensors
Asia Pacific RFID Market
Sensors
Mobile Mapping Systems Market
Sensors
Handheld GPS Units Market
Sensors
Barcode Scanner Market
Sensors
Europe RFID Market