
 Smart Shade Device Market | 2026-2036
Smart Shade Device Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Shade Device Market Outlook
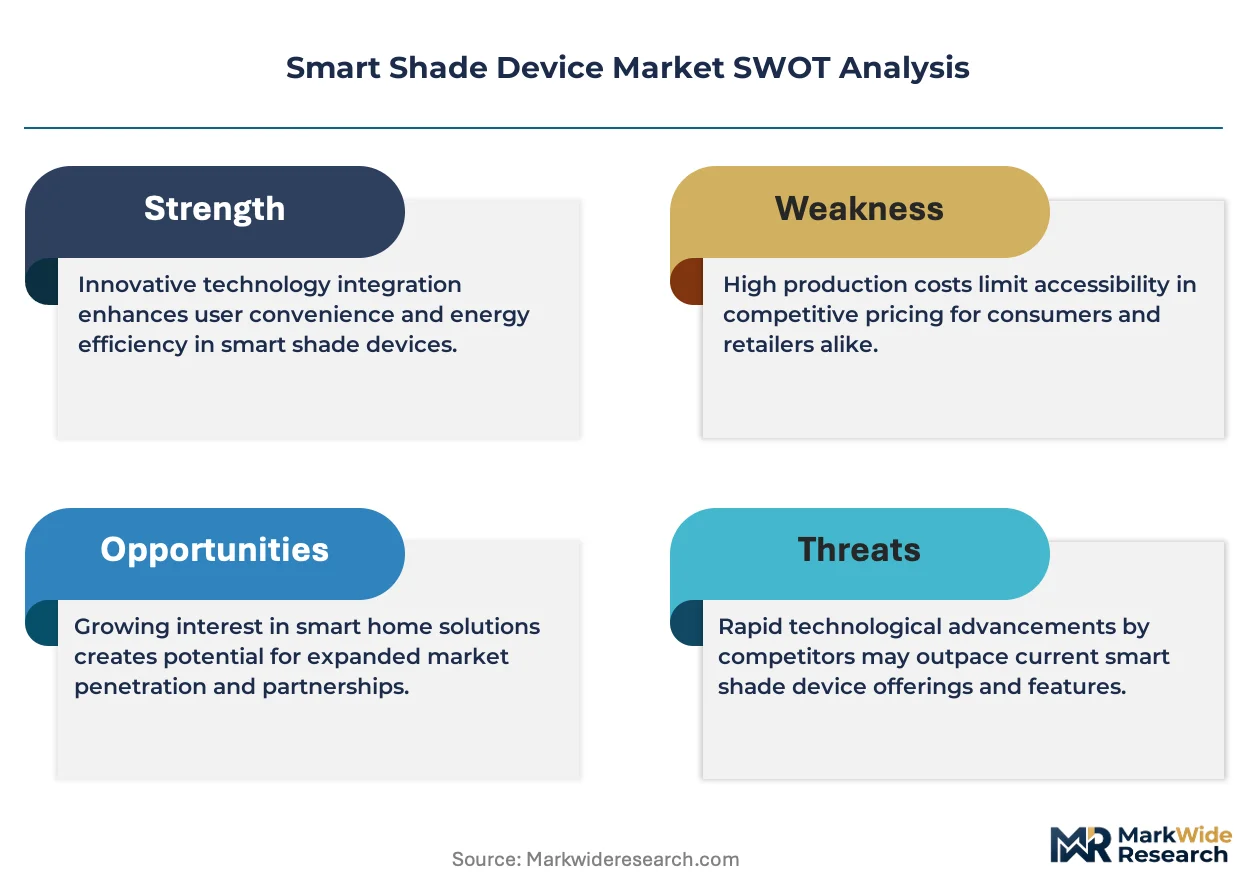
Product bundling of shade controllers with whole-home automation platforms is pivoting buyer choice away from standalone hardware purchases. Hunter Douglas leverages its captive distribution network to sustain premium positioning in North American custom residential channels. Lutron Electronics anchors its competitiveness through deep integration with lighting-control ecosystems. Somfy dominates European commercial retrofit projects through its specialized motorization technology.
Smart shade devices are motorized window coverings equipped with embedded sensors, low-voltage motors, and wireless communication modules that automatically adjust louver position or fabric deployment in response to solar intensity, temperature, or occupancy signals. The primary purpose is to reduce HVAC load and artificial lighting demand while maintaining visual comfort and glare control. Motorized shades lead the product-type dimension due to established installation infrastructure and proven energy savings in commercial buildings. Wi-Fi-enabled units are capturing the fastest growth in residential retrofits where homeowners prioritize smartphone-native control without additional hub hardware. Zigbee-based systems occupy the margin-rich hospitality segment where centralized building-management integration justifies higher equipment costs.
The US Department of Energy and EPA jointly influence demand through appliance-efficiency benchmarking and ENERGY STAR certification requirements that reward automated solar-control strategies. In Europe, the EU Green Deal and F-Gas Regulation tighten building-envelope performance standards, while CE marking and the Ecodesign Directive mandate interoperable control interfaces. Stakeholders must monitor whether emerging material-recycling rules under REACH and RoHS will restrict motor-housing polymers and electronic component supply chains.
Market Dynamics
Integration with whole-home automation platforms is compressing standalone shade controller margins while elevating bundled system value, forcing hardware manufacturers to cede point-of-sale control to platform orchestrators.
Growth Catalysts
- EU Green Deal building-envelope mandates:Passivhaus-certified projects in Germany now require automated solar-control systems, creating specification pull-through for motorized shading in new construction and deep retrofits.
- Low-voltage motorization advances:Whisper-quiet DC motor technology eliminates the acoustic barriers that previously blocked adoption in hospitality and healthcare settings.
- Dubai luxury residential procurement:Developers in the UAE are specifying automated shading as standard in premium tower inventory, normalizing the technology across Gulf Cooperation Council high-end construction.
Market Restraints
- Copper and rare-earth magnet cost volatility:Motor assemblies depend on neodymium and copper windings, with price swings directly compressing gross margins for European motor suppliers.
- Hub dependency for Zigbee systems:Proprietary bridge requirements create switching costs that slow replacement cycles in the installed base of commercial buildings.
- Manual shade substitution in cost-sensitive segments:Cordless spring-roller mechanisms retain specification share in multifamily rental construction where tenant-paid energy savings lack capital recovery pathways.
Strategic Opportunities
- Saudi Vision 2030 giga-project construction:NEOM and Red Sea Project developments are mandating smart building infrastructure from groundbreaking, creating specification windows absent retrofit friction.
- Wi-Fi Direct residential retrofit penetration:Hub-free connectivity eliminates installation complexity for homeowners replacing manual shades without electrical contractor involvement.
- Daylight harvesting convergence with LED controls:Integrated lumen-and-louver management systems are capturing specification in net-zero commercial targets where single-vendor accountability reduces commissioning risk.
Industry Challenges
- Building automation protocol fragmentation:BACnet, KNX, and proprietary cloud APIs require multi-stack engineering that strains mid-tier controller firmware teams.
- CE marking timeline compression under Ecodesign:Interoperability testing for wireless modules is extending product launch cycles by four to six months for non-captive manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Shade Device Market |
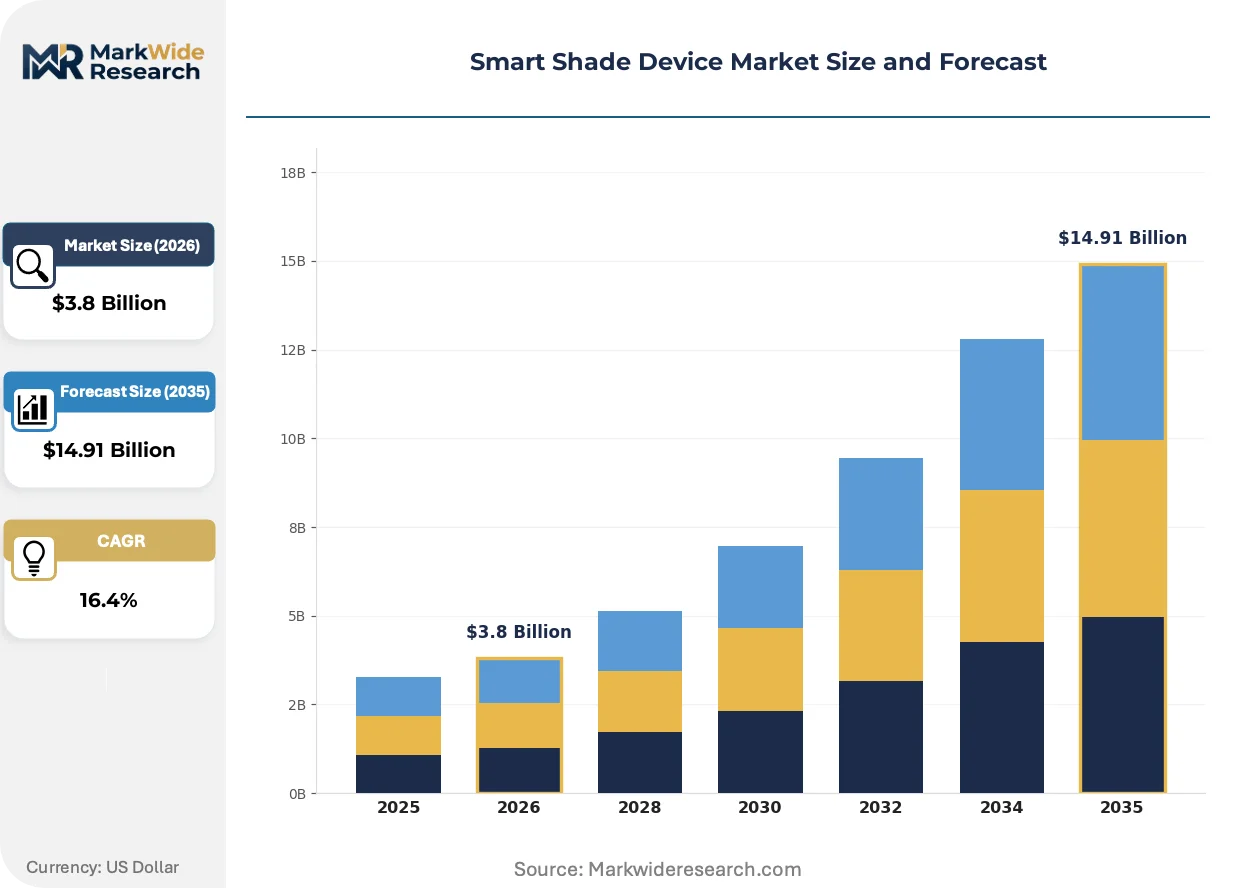
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $14.91 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Motorized Shades, Smart Blinds, Automated Curtains, Shade Controllers Technology: Wi-Fi, Bluetooth, Zigbee, RF End User: Residential, Commercial, Hospitality, Industrial Installation Type: Wall-mounted, Ceiling-mounted, Window-mounted, Portable |
| Companies Covered | Hunter Douglas, Lutron Electronics, Somfy, Crestron Electronics, Pella Corporation, Loxone Electronics, Skyco Shading Systems, Mecho Systems, Q Motion Shades, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Shade Device Market Strategic Shifts
Photovoltaic-integrated shading fabrics and sensor-embedded textiles are collapsing the distinction between passive envelope elements and active energy systems, redefining procurement criteria for facade contractors.
Photovoltaic-integrated shading fabrics embed thin-film solar cells directly into roller blind textiles, generating on-site electricity while blocking thermal gain. Commercial developers in California and the Netherlands are specifying these systems for net-zero targets where rooftop area is constrained. This dual-function material is absorbing specification share from conventional blackout fabrics by converting facade surface area from cost center to generation asset.
The F-Gas Regulation is accelerating refrigerant-phaseout timelines that indirectly tighten building-envelope performance requirements, as HVAC load reduction becomes the primary pathway to compliance. Automated solar control now features in energy modeling as a prerequisite for permit approval in German commercial construction. Project developers are responding by front-loading shading system specification into schematic design rather than treating it as interior finish.
Direct-to-consumer configuration tools are displacing dealer-mediated sales for residential retrofit projects, with web-based measurement apps and video installation guidance collapsing the traditional three-visit purchase process. Hunter Douglas and Lutron have both launched smartphone-native room-scanning features that bypass in-home consultation. This channel compression is most visible in US suburban markets where homeowners prioritize weekend project completion over white-glove service.
Smart Shade Device Market Segmentation
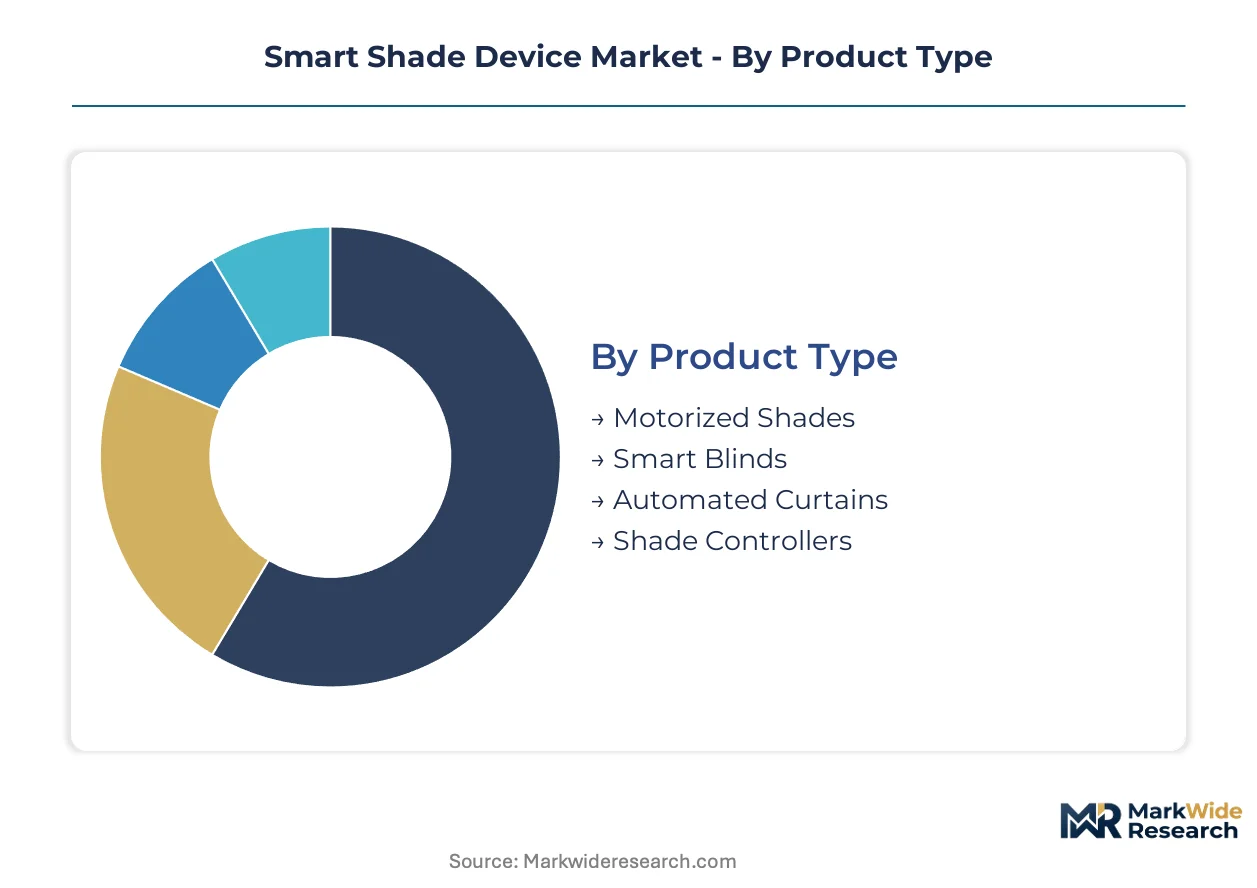
Smart shade device segmentation reveals divergent engineering priorities across residential comfort optimization and commercial energy compliance. Product architecture, connectivity protocols, and mounting configurations each create distinct value pools with incompatible supply chains and specification channels.
Product Type:
The customization-to-standardization spectrum stretches from bespoke fabric selection in luxury residential to pre-engineered motor assemblies for commercial retrofit.
- Motorized Shades:Roller and cellular fabric systems with integrated tubular motors and limit-switch positioning. Demand concentrates in German Passivhaus-certified commercial construction where automated solar control satisfies envelope performance mandates.
- Smart Blinds:Tilting louver systems with position-feedback servos and tilt-angle memory. Hospitality developers in Dubai and Riyadh are specifying these for guest room automation, driven by luxury positioning requirements and operational energy targets.
- Automated Curtains:Track-mounted drapery systems with synchronized multi-motor drive. Residential retrofits in suburban US markets favor these for whole-home theater integration.
- Shade Controllers:Standalone hub and interface modules enabling legacy motor retrofit. European commercial building managers deploy these to extend KNX infrastructure without full hardware replacement.
Most installed capacity flows through Motorized Shades. Expansion is steepest in Smart Blinds.
Technology:
Protocol selection tracks customer technical sophistication and infrastructure investment willingness.
- Wi-Fi:Direct-to-router connectivity eliminating bridge hardware. US residential retrofits prioritize smartphone-native control without electrical contractor involvement, making this the volume leader in single-family replacement cycles.
- Zigbee:Mesh-networked low-power specification with hub dependency. European hospitality and healthcare sectors absorb these systems for centralized building management integration and multi-device reliability.
- Bluetooth:Point-to-point pairing for localized control without network infrastructure. Apartment renters and temporary installations favor these for portability and minimal setup.
- RF:Proprietary radio-frequency protocols with dedicated remotes. Legacy commercial installations and budget residential new construction continue specifying these for cost containment.
Wi-Fi carries the highest shipment volumes. Zigbee commands the steepest expansion trajectory in premium commercial segments.
End User:
Customer type determines whether procurement emphasizes capital efficiency or operational energy recovery.
- Residential:Single-family and multifamily owner-occupied units. US suburban markets are absorbing Wi-Fi-enabled retrofit systems through direct-to-consumer channels.
- Commercial:Office, retail, and institutional buildings. German developers specify automated shading as prerequisite for permit approval under tightened envelope standards.
- Hospitality:Hotels, resorts, and serviced apartments. UAE luxury tower construction mandates integrated shading as standard amenity.
- Industrial:Manufacturing facilities and warehouses. Daylight harvesting for high-bay LED reduction drives specification in net-zero industrial targets.
Commercial applications dominate installed base. Residential retrofits are climbing the fastest.
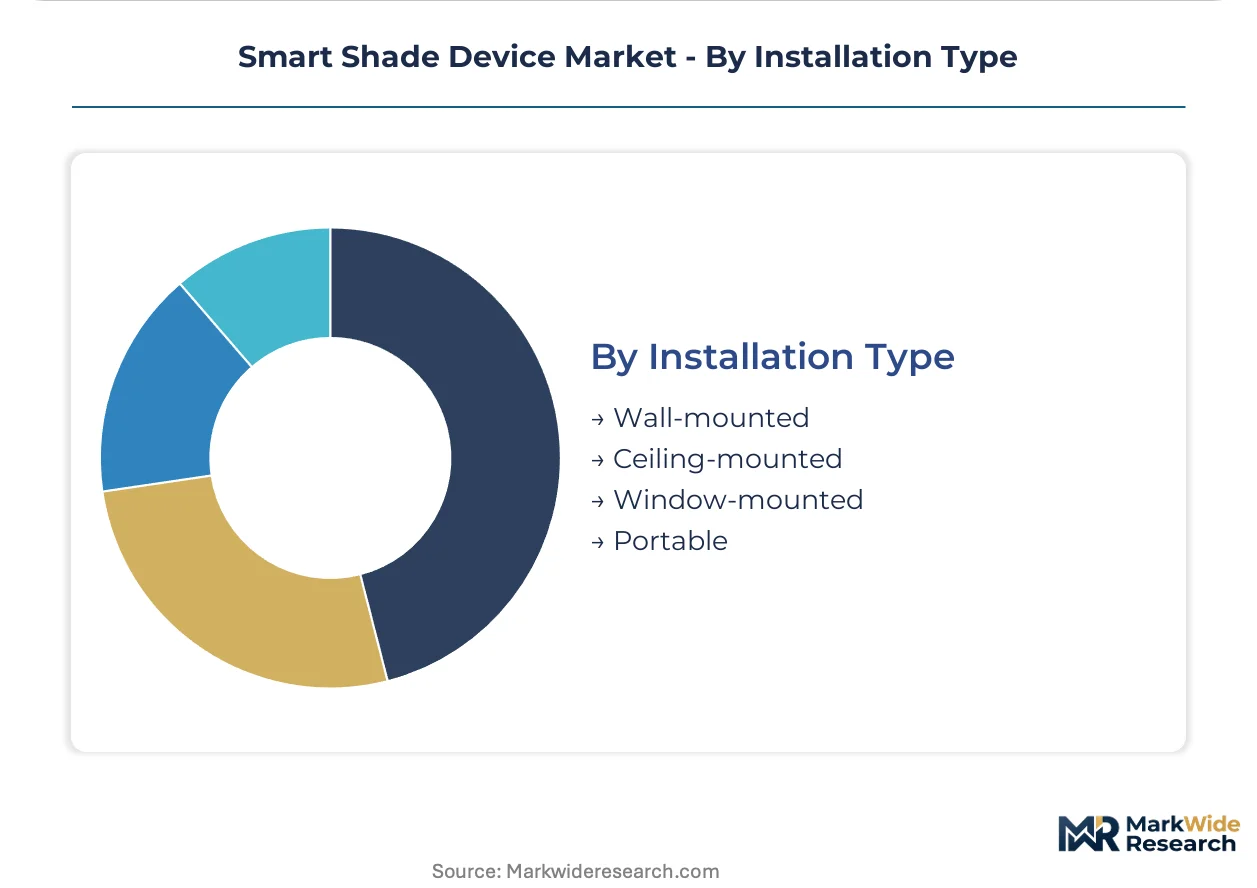
Installation Type:
Mounting configuration constrains motor torque requirements and electrical routing complexity.
- Wall-mounted:Bracket-fixed systems with concealed power runs. European commercial retrofits favor these for masonry facade compatibility.
- Ceiling-mounted:Recessed or surface-mounted housing above window openings. Hospitality specifiers in Gulf markets demand these for clean architectural lines.
- Window-mounted:Frame-integrated units with battery or solar power. US residential direct-to-consumer sales concentrate here for DIY installation.
- Portable:Freestanding or suction-mounted temporary solutions. Rental markets and seasonal applications absorb limited volumes.
Ceiling-mounted systems carry premium positioning. Window-mounted variants are expanding most quickly through retail channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The automated shading industry traces its commercial roots to European motorization engineering in the 1980s, with German industrial clusters later pioneering integration between solar-control hardware and building-management systems. Today, specification patterns diverge sharply across regulatory environments and construction cycles.
Germany
Passivhaus-certified construction in Berlin and Frankfurt mandates automated solar control for envelope compliance, with the EU Green Deal tightening F-Gas Regulation timelines that indirectly elevate shading specification priority. The Ecodesign Directive's interoperability requirements extend product launch cycles for wireless module certification. Bavaria's industrial corridor hosts concentrated motorization R&D activity serving Central European retrofit demand.
United States
Suburban residential retrofits absorb Wi-Fi-enabled shade systems through direct-to-consumer channels, with homeowners prioritizing smartphone-native control without electrical contractor involvement. The EPA's ENERGY STAR certification rewards automated solar-control strategies in appliance-efficiency benchmarking. California's Title 24 building standards explicitly credit automated shading for daylight harvesting compliance in commercial construction.
United Arab Emirates
Luxury residential towers in Dubai specify automated shading as standard amenity, with developers normalizing the technology across Gulf Cooperation Council high-end construction. MOHAP's building efficiency guidelines increasingly reference solar-control automation for cooling load reduction. NEOM and Red Sea Project giga-developments mandate smart building infrastructure from groundbreaking, eliminating retrofit friction.
China
Net-zero commercial targets in the Yangtze River Delta absorb integrated lumen-and-louver management systems, with daylight harvesting convergence reducing commissioning risk through single-vendor accountability. MIIT's GB standards for smart building interoperability create certification requirements for wireless control modules. Shenzhen's hardware ecosystem supplies motorization components for regional OEM assembly.
Saudi Arabia
Vision 2030 giga-project construction mandates smart building infrastructure specification windows absent retrofit friction, with Riyadh and Jeddah luxury developments front-loading shading systems into schematic design. SFDA's building product registration requirements apply to imported motorization assemblies. The Eastern Province's industrial cities host fabrication facilities serving domestic mega-project demand.
Smart Shade Device Market Competitive Environment
Premium-margin players sit above commodity-margin players across the protocol-integration dimension, with whole-home automation platform bundling compressing standalone controller economics. The vendor base stratifies between captive distribution networks, specialized motorization technology holders, and lighting-control ecosystem anchors. Three archetypes dominate: platform-orchestrated system integrators, component-specialist motor suppliers, and envelope-fabrication incumbents with automation extensions. Consolidation pressure operates through strategic partnerships with building-automation vendors and backward integration into sensor-embedded textile development.
Within the ecosystem-anchored tier, Hunter Douglas and Lutron Electronics represent distribution-intensive positioning, while Somfy exemplifies motorization-specialist concentration. Hunter Douglas leverages captive North American residential channels. Lutron Electronics anchors competitiveness through lighting-control integration depth. Somfy dominates European commercial retrofit specification. These three occupy positions reflecting divergent bets on platform openness versus proprietary stack control.
| Leading Market Players |
|---|
| Hunter Douglas |
| Lutron Electronics |
| Somfy |
| Crestron Electronics |
| Pella Corporation |
| Loxone Electronics |
| Skyco Shading Systems |
| Mecho Systems |
| Q Motion Shades |
| Others |
Value Chain & Pricing Dynamics
The EU Green Deal's building-envelope mandates gate qualified supply for premium-tier motorized shading systems, compressing margins for non-compliant manufacturers while rewarding certified suppliers with pricing power in German Passivhaus construction. Copper and rare-earth magnet cost volatility feeds directly into motor assembly economics, forcing European suppliers to absorb input swings or risk specification loss to Asian competitors with captive magnet sourcing.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates the competitive landscape, with CE marking and KNX interoperability certification separating premium motorization from commodity RF-based alternatives. Price differentiation rests on motor acoustic performance and wireless protocol integration depth, with whisper-quiet DC systems commanding substantial premiums in hospitality specification. Pricing pressure stems from Wi-Fi Direct module commoditization in US residential retrofits, where hub-free connectivity erodes Zigbee's historical margin advantage. Commercial building managers exhibit lowest price sensitivity due to energy compliance payback requirements, while multifamily developers in cost-sensitive segments substitute manual cordless mechanisms.
Supply Chain Analysis
Saudi Arabia's local-content rules under Vision 2030 are reshaping sourcing for giga-project motorization assemblies, pressuring European suppliers to establish domestic fabrication partnerships or forfeit NEOM specification windows. Manufacturing concentrates in Germany, China, and the United Arab Emirates, with Bavaria's industrial corridor hosting R&D-intensive motor design and Shenzhen supplying cost-optimized Wi-Fi control modules. Neodymium permanent magnets and copper windings draw from concentrated rare-earth processing in China, creating single-source vulnerability for European motor suppliers. Distribution runs through captive dealer networks for luxury residential channels and direct-to-consumer platforms for suburban US retrofits.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The smart shade device market operates as a regulatory compounder, with the EU F-Gas Regulation's refrigerant phaseout timelines indirectly mandating automated solar control as the primary pathway to HVAC load reduction compliance.
For Market Incumbents: Anchor competitiveness through backward integration into sensor-embedded textile development, capturing specification share from photovoltaic-integrated shading fabrics that convert facade surface area from cost center to generation asset. Defend against platform-orchestrator margin compression by deepening KNX and BACnet stack certification investment, creating switching costs that slow replacement cycles in European commercial installed bases.
For New Entrants and Emerging Players: Enter via Wi-Fi Direct residential retrofit penetration in US suburban markets, where hub-free connectivity eliminates electrical contractor involvement and collapses the traditional three-visit purchase process. Target window-mounted battery-powered systems for apartment renters seeking portability without infrastructure investment, leveraging smartphone-native room-scanning tools to bypass dealer-mediated sales channels.
For Investors and Strategic Acquirers: Valuations sit cheapest among component-specialist motor suppliers lacking lighting-control ecosystem integration, as whole-home automation platform bundling compresses standalone controller economics. Long-term viability favors vendors with dual capability in envelope-fabric fabrication and embedded sensor development. Monitor CE marking timeline compression under Ecodesign as inflection signal for wireless module certification bottlenecks that extend product launch cycles.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration Partnership | Deep Lutron or Crestron ecosystem integration secures specification in whole-home automation bundling. |
| Photovoltaic Fabric Development | Thin-film solar cell embedding transforms shading textiles into on-site generation assets for net-zero targets. |
| KNX Protocol Certification Investment | Interoperability testing completion unlocks German Passivhaus commercial construction specification windows. |
| Direct-to-Consumer Channel Launch | Smartphone-native configuration tools collapse dealer-mediated sales cycles in US suburban retrofits. |
| Saudi Domestic Fabrication Joint Venture | Local-content compliance secures NEOM and Red Sea Project giga-development specification from groundbreaking. |
Study Parameters
Coverage spans Germany, the United States, the United Arab Emirates, China, and Saudi Arabia, with primary inputs from each market's building automation integrators, motorization component suppliers, luxury residential developers, and commercial facility managers. Secondary validation draws from EU Ecodesign Directive filings, EPA ENERGY STAR certification databases, SEC disclosures from publicly traded building products firms, and customs records for tubular motor and wireless module trade flows. Bottom-up shipment estimates triangulate against top-down construction spending allocation models.
Rate-of-change decomposition separates volume growth from value expansion across the projection horizon, with CAGRs derived from segmented adoption curves for Wi-Fi, Zigbee, Bluetooth, and RF protocol technologies. The analytical framework models product type, connectivity technology, end-user segment, and installation configuration dimensions, incorporating daylight harvesting convergence with LED controls as a discrete industry-specific demand driver. Motor torque requirements and battery chemistry cost curves feed into window-mounted versus ceiling-mounted penetration assumptions.
The model holds under stable copper and rare-earth magnet pricing; deviation in neodymium supply disruption or EU wireless module certification timeline extension would shift commercial retrofit adoption trajectories. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Smart City Technology
Smart Space Market
Smart City Technology
Outdoor LED Smart Lighting Solution Market
Smart City Technology
Smart Mailbox Market
Smart City Technology
Smart Package Lockers Market
Smart City Technology
Smart City Kiosk Deployment Market
Smart City Technology
Singapore ICT Market
Smart City Technology
Smart City Framework Market
Smart City Technology
Smart Communities Market
Smart City Technology
Global Smart Ticketing Market
Smart City Technology
Global Smart City ICT Infrastructure Market
Smart City Technology
Smart Street Lights Market
Smart City Technology
Smart Ticketing Solutions Market
Smart City Technology
Global Smart City Market
Smart City Technology
Smart Parcel Locker Market
Smart City Technology
Smart City Platform Market
Smart City Technology
Smart City Kiosk Market