
 Emission Monitoring Software Market | 2026-2036
Emission Monitoring Software Market Size, Share, and Industry Trends Forecast 2026-2036
Emission Monitoring Software Market Foresight
Buyer concentration among energy and manufacturing conglomerates is recalibrating procurement priorities toward integrated compliance platforms. Emerson Electric Co. leverages its automation heritage to anchor large-scale utility deployments. Cority competes through specialized environmental health and safety software integration. Siemens sustains European market presence with industrial IoT-enabled monitoring architectures.
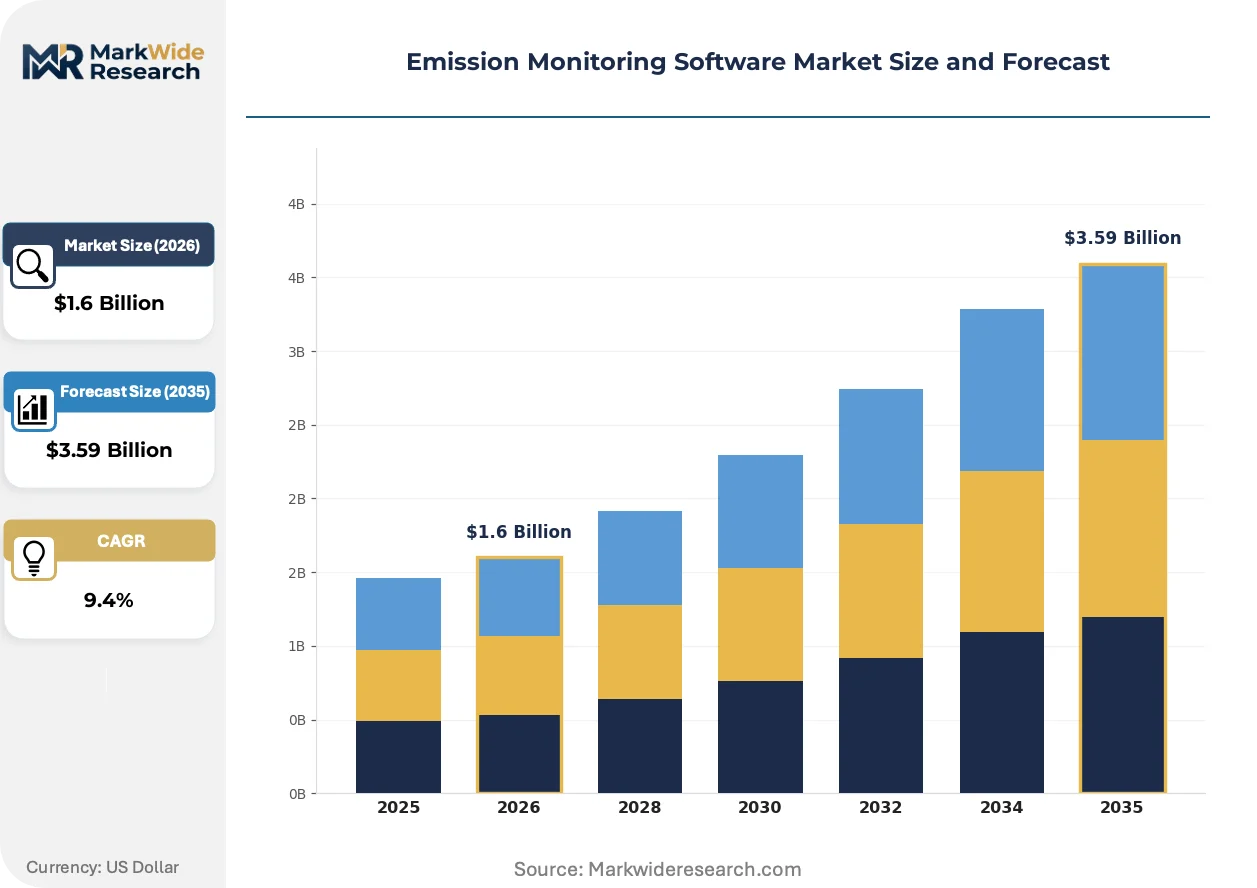
Emission monitoring software encompasses platforms that collect, process, and analyze pollutant data from stationary and mobile sources using protocols such as CEMS (Continuous Emission Monitoring Systems) with data acquisition and handling systems capable of 1-minute averaging periods. These systems serve primary industrial purposes including regulatory reporting, operational optimization, and carbon accounting verification. Cloud-based deployment now leads adoption as energy majors seek scalable infrastructure without capital-intensive on-premises maintenance. Real-time monitoring applications capture the fastest growth trajectory driven by tightening enforcement timelines. Data analytics technology holds concentrated margin pools where predictive emission forecasting commands premium pricing.
EPA enforcement under the Clean Air Act shapes US product standards through mandatory certification requirements for stack monitoring equipment. EMA coordination with EU Green Deal implementation drives demand for verified emission data across European industrial installations. China's MEE enforces GB standards that compel domestic facilities toward automated reporting systems. Stakeholders must evaluate how divergent certification timelines across EPA, EMA, and MEE jurisdictions will fragment platform development roadmaps and reshape partnership strategies.
Market Dynamics
Binding decarbonization mandates under the EU Emissions Trading System are forcing industrial clusters toward continuous emissions monitoring systems with sub-minute data granularity, compressing procurement cycles for integrated compliance platforms.
Growth Catalysts
- EU Green Deal enforcement:Industrial installations across Germany face binding emission reduction targets that require real-time monitoring infrastructure with automated reporting capabilities to EMA-coordinated verification bodies.
- Power generation utilities:Coal-to-gas transition projects in the United States are retrofitting stack monitoring systems to meet EPA Clean Air Act certification requirements for 1-minute averaging protocols.
- Cloud-based deployment architectures:Energy majors are abandoning capital-intensive on-premises maintenance in favor of scalable SaaS platforms that centralize multi-facility emission data management.
Market Restraints
- Sensor hardware cost volatility:Semiconductor supply constraints for data acquisition systems inflate upfront capital requirements for CEMS installations at mid-sized manufacturing facilities.
- Technical interoperability gaps:Legacy stack monitoring equipment from the 1990s lacks digital output protocols compatible with modern analytics platforms, forcing expensive hardware replacement cycles.
- Regulatory fragmentation:Divergent certification timelines across EPA, EMA, and China's MEE jurisdictions force platform developers to maintain multiple compliance codebases, inflating R&D overhead.
Strategic Opportunities
- Predictive emission forecasting:Data analytics modules that anticipate exceedance events before they occur command premium pricing from refineries seeking to avoid EPA enforcement penalties.
- India's industrial corridor expansion:Steel and cement clusters along the Delhi-Mumbai Industrial Corridor face tightening CEA emission norms that will require automated monitoring infrastructure at greenfield sites.
- Carbon accounting verification:Convergence of emission monitoring software with blockchain-based audit trails creates new revenue streams for platforms serving voluntary carbon market participants.
Industry Challenges
- Specialized technician scarcity:CEMS calibration and QA/QC procedures require certified personnel with expertise in both analytical chemistry and industrial control systems, creating hiring bottlenecks.
- Multi-jurisdiction compliance complexity:Facilities operating across US, EU, and Chinese markets must maintain parallel data handling protocols to satisfy divergent EPA, EMA, and MEE evidentiary standards.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Emission Monitoring Software Market |
| Market Size in 2026 | $1.6 Billion |
| Market Size in 2035 | $3.59 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premises, Cloud-Based, Hybrid, SaaS End User: Manufacturing, Energy, Transportation, Environmental Agencies Application: Regulatory Compliance, Real-Time Monitoring, Reporting, Data Analysis Technology: IoT Sensors, Data Analytics, AI Integration, Machine Learning |
| Companies Covered | Emerson Electric Co., Cority, Persefoni, Thermo Fisher Scientific Inc., Emex, ABB, Siemens, Greenly, AMETEK, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Emission Monitoring Software Market Shifts & Advancements
Real-time monitoring applications are capturing investment priority as enforcement timelines compress from quarterly to daily reporting windows, while predictive analytics capabilities differentiate premium platform tiers.
Edge computing architectures with on-premise data preprocessing are consolidating market share among refineries and chemical complexes that cannot tolerate latency in exceedance detection. Marathon Petroleum and BASF-operated facilities have piloted sub-second anomaly detection systems that trigger automated control responses before regulatory thresholds breach. This capability is consolidating competitive positioning for vendors with industrial automation heritage against pure-play software entrants.
EPA enforcement protocols under the Clean Air Act are mandating electronic reporting through the Compliance and Emissions Data Reporting Interface, eliminating paper-based submission pathways for major sources. This industrial consequence forces smaller emitters to adopt certified data acquisition systems previously considered cost-prohibitive. Power generation utilities with coal-fired assets face the most acute compliance pressure, accelerating procurement of integrated monitoring and reporting platforms.
Buyer concentration among energy conglomerates is compressing vendor negotiation cycles and unbundling after-sales service contracts from software licenses. Procurement teams at integrated oil majors now separate hardware maintenance, calibration services, and analytics subscriptions into distinct purchasing decisions. This pattern is most visible in the United States, where ExxonMobil and Chevron have standardized on multi-year software agreements with separate competitive bidding for field service provision.
Emission Monitoring Software Market Segmentation
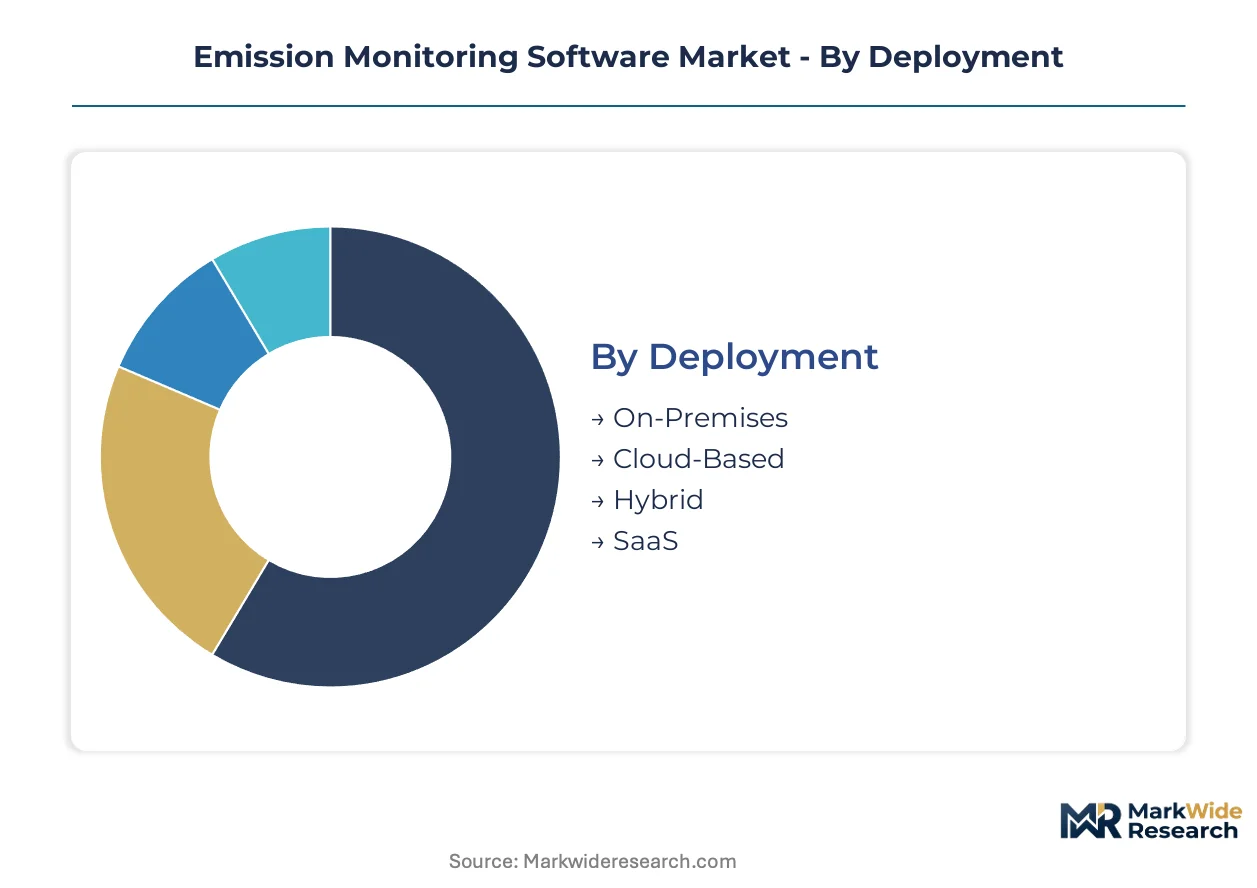
Emission monitoring software segments reflect divergent buyer priorities across capital intensity, regulatory pressure, and data sovereignty requirements. Procurement patterns vary sharply between utilities seeking perpetual licenses and industrial conglomerates prioritizing scalable consumption models.
Deployment:
Customization versus standardization tensions dominate deployment decisions, with energy majors weighing data control against operational agility.
- Cloud-Based:Scalable infrastructure enables centralized multi-facility emission data management without capital-intensive on-premises maintenance. Demand concentrates among integrated oil majors in the United States seeking to eliminate hardware refresh cycles while maintaining EPA Clean Air Act compliance.
- SaaS:Subscription models bundle software updates, security patches, and regulatory template refreshes into predictable operating expenditures. German industrial clusters under EU Emissions Trading System mandates favor SaaS for automated EMA reporting workflows.
- On-Premises:Air-gapped installations serve refineries with cybersecurity protocols restricting external data transmission.
- Hybrid:Edge preprocessing with cloud analytics balances latency-sensitive exceedance detection against centralized benchmarking.
Leading the category by volume: Cloud-Based. Growing fastest: SaaS.
End User:
Regulatory exposure intensity separates buyer segments, with enforcement timelines dictating procurement urgency.
- Energy:Power generation utilities face acute EPA enforcement pressure under coal-to-gas transition mandates, requiring certified CEMS with 1-minute averaging protocols. Procurement concentrates among coal-fired asset operators retrofitting stack monitoring infrastructure.
- Manufacturing:Steel and cement producers in industrial clusters navigate binding decarbonization targets through continuous emissions verification. German manufacturing hubs under EU Green Deal implementation drive demand for sub-minute data granularity.
- Environmental Agencies:Government verification bodies require audit-trail capabilities for evidentiary standardization.
- Transportation:Mobile source monitoring expands for port authorities tracking vessel emissions.
Dominant revenue concentration: Energy. Steepest expansion trajectory: Manufacturing.
Application:
Functional sophistication tiers separate compliance-minimum buyers from optimization-seeking adopters.
- Real-Time Monitoring:Sub-second anomaly detection systems trigger automated control responses before regulatory threshold breaches. Marathon Petroleum and BASF-operated facilities have piloted edge architectures that consolidate competitive positioning for vendors with industrial automation heritage.
- Regulatory Compliance:EPA-mandated electronic reporting through the Compliance and Emissions Data Reporting Interface eliminates paper pathways for major sources. This forces smaller emitters toward certified data acquisition systems previously considered cost-prohibitive.
- Data Analysis:Predictive emission forecasting modules anticipate exceedance events before they occur.
- Reporting:Automated template generation reduces QA/QC labor for multi-jurisdiction facilities.
Widest installed base: Regulatory Compliance. Premium pricing capture: Real-Time Monitoring.
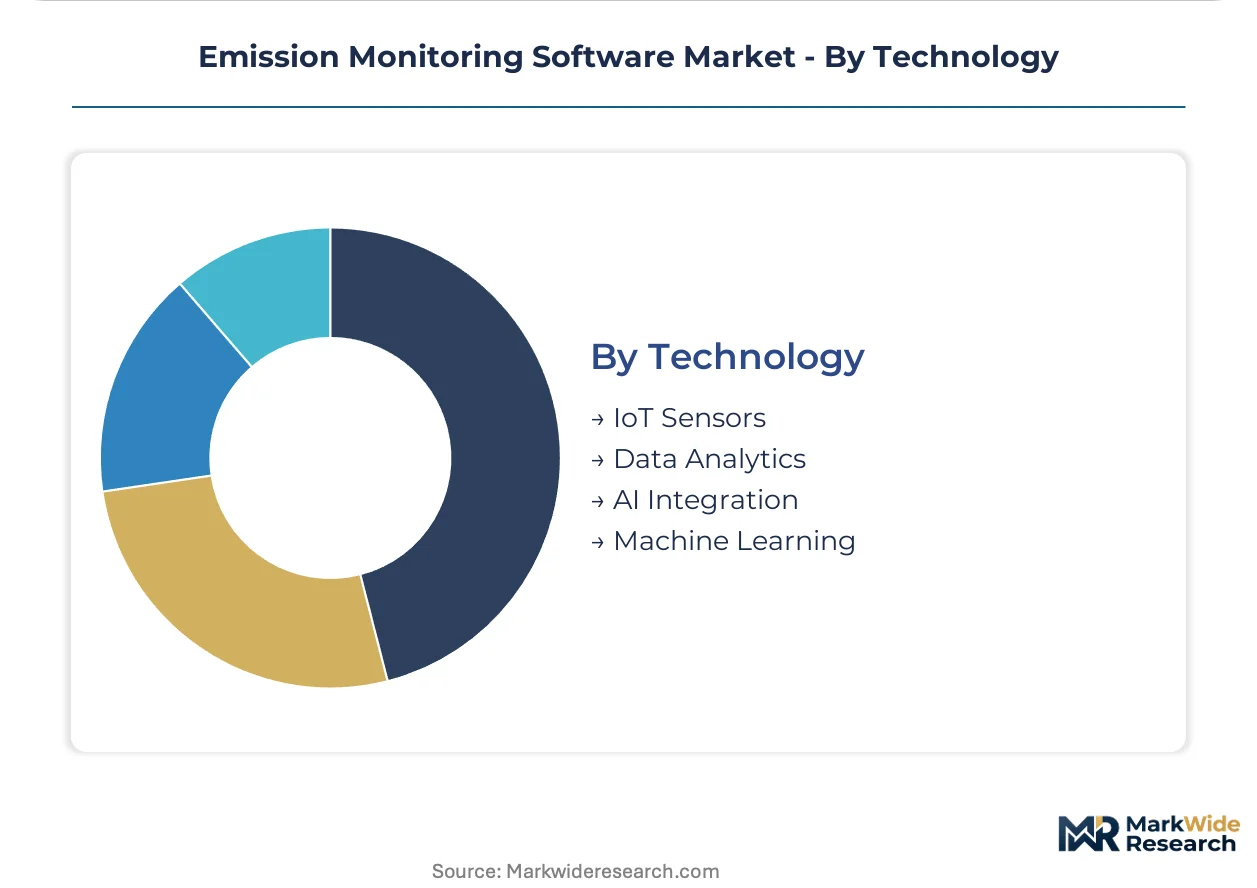
Technology:
Sensor-to-insight integration depth determines margin capture across technology tiers.
- Data Analytics:Predictive emission forecasting commands premium pricing from refineries seeking to avoid EPA enforcement penalties. Advanced modules correlate operational parameters with emission profiles to enable preemptive process adjustments.
- IoT Sensors:Semiconductor supply constraints for data acquisition systems inflate upfront capital requirements at mid-sized manufacturing facilities. Legacy stack monitoring equipment from the 1990s lacks digital output protocols compatible with modern platforms.
- AI Integration:Neural networks optimize calibration schedules based on operational degradation patterns.
- Machine Learning:Pattern recognition improves anomaly detection accuracy across variable feedstock compositions.
Highest current penetration: IoT Sensors. Fastest capability maturation: Data Analytics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Industrial conglomerates in Germany anchor demand concentration for integrated compliance platforms, while enforcement timelines across the United States, China, and India reshape procurement urgency.
United States
Coal-to-gas transition projects and EPA Clean Air Act enforcement drive retrofit demand for certified CEMS infrastructure. The Compliance and Emissions Data Reporting Interface mandates electronic submission, eliminating paper pathways for major sources. Power generation utilities in Texas and the Ohio River Valley accelerate procurement of 1-minute averaging protocol systems.
Germany
Steel and chemical producers face binding decarbonization mandates under the EU Emissions Trading System. The EU Green Deal implementation tightens verification standards for industrial installations. The Ruhr industrial cluster and BASF-operated facilities in Ludwigshafen deploy sub-minute data granularity systems for automated EMA reporting.
China
Domestic facilities confront GB standards enforcement by the MEE compelling automated reporting adoption. Dual carbon goals accelerate deployment of continuous emissions verification infrastructure. Steel producers in Hebei province and petrochemical complexes in Shandong retrofit legacy stack monitoring with digital output protocols.
India
Steel and cement expansion along the Delhi-Mumbai Industrial Corridor faces tightening CEA emission norms. The central electricity regulator mandates automated monitoring at greenfield industrial sites. Manufacturing clusters in Maharashtra and Gujarat pilot cloud-based compliance platforms for multi-facility data centralization.
United Kingdom
Post-Brexit regulatory alignment pressures industrial installations toward verified emission data systems. The Environment Agency coordinates enforcement timelines converging with EU verification standards. Refinery operations in Grangemouth and manufacturing hubs in the Midlands adopt predictive analytics modules for exceedance anticipation.
Emission Monitoring Software Market Competitive Landscape
United States producers anchor the automation-heritage tier; European specialists hold the industrial IoT integration segment. The vendor base concentrates around three strategic archetypes: diversified automation conglomerates, pure-play environmental software developers, and analytical instrumentation manufacturers. Competitive dynamics center on M&A activity targeting data analytics capabilities and strategic partnerships with cloud infrastructure providers.
Within the automation-heritage tier, Emerson Electric Co. and Siemens exemplify vendors leveraging industrial control system expertise to anchor utility-scale deployments. Cority and Persefoni occupy positions among pure-play environmental software specialists integrating health and safety workflows with emission verification. Thermo Fisher Scientific Inc. represents the analytical instrumentation archetype, bridging sensor hardware with data acquisition platforms.
| Leading Market Players |
|---|
| Emerson Electric Co. |
| Cority |
| Persefoni |
| Thermo Fisher Scientific Inc. |
| Emex |
| ABB |
| Siemens |
| Greenly |
| AMETEK |
| Others |
Supply & Pricing Matrix
Certified CEMS technician scarcity in the Ohio River Valley and Ruhr industrial cluster feeds labor-cost differentials that widen pricing-tier spreads between premium predictive-analytics platforms and basic compliance modules. German steel producers under EU Emissions Trading System mandates absorb premium SaaS pricing for automated EMA reporting workflows, while mid-sized US manufacturers face sticker shock from hardware-plus-calibration bundles.
Pricing Analysis
Volume concentrates in subscription-based SaaS tiers while margin pools in predictive-analytics modules. Three-tier pricing structure across premium, standard, and economy levels separates edge-computing platforms with sub-second anomaly detection from template-based compliance dashboards. Price differentiation hinges on certification grade for EPA Clean Air Act stack monitoring and after-sales calibration service bundling. Pricing pressure stems from semiconductor supply constraints inflating data acquisition system costs. Buyer price sensitivity peaks among mid-sized manufacturing facilities in India and Southeast Asia, while integrated oil majors in the United States exhibit lowest sensitivity due to penalty avoidance calculus.
Supply Chain Analysis
Workforce availability for analytical chemistry and industrial control systems expertise concentrates in Germany, the United States, and Japan, constraining CEMS deployment velocity at greenfield sites. Raw material dependencies span semiconductor components for data acquisition systems, specialized optical sensors for stack monitoring, and cloud infrastructure from hyperscaler providers. Supply chain risk centers on single-source vulnerability for EPA-certified hardware modules subject to extended lead times. Distribution runs through direct enterprise sales for utility-scale deployments and channel partners serving mid-market manufacturing segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cloud-based deployment architectures are displacing on-premises CEMS infrastructure as energy majors prioritize scalable SaaS platforms over capital-intensive hardware refresh cycles.
For Market Incumbents: Lock in utility-scale deployments through multi-year software agreements with separate competitive bidding for field service provision, mirroring ExxonMobil and Chevron procurement patterns. Deepen backward integration into edge-computing hardware to defend margin pools against pure-play software entrants. Prioritize certification investment for EPA Clean Air Act electronic reporting protocols to maintain compliance-mandated switching costs. For New Entrants and Emerging Players: The premium-to-economy pricing gap in predictive-analytics modules creates entry space for AI-native platforms targeting mid-sized refineries. India's Delhi-Mumbai Industrial Corridor offers the most penetrable geography as steel and cement greenfield sites face tightening CEA emission norms without incumbent vendor relationships. A carbon-accounting-verification go-to-market angle with blockchain audit-trail differentiation bypasses direct competition with automation-heritage vendors. For Investors and Strategic Acquirers: Re-rating potential sits with data-analytics specialists given convergence of emission monitoring software with voluntary carbon market verification workflows. Long-term viability favors platforms with industrial IoT-enabled architectures serving EU Green Deal implementation timelines. Target acquisition archetype: pure-play environmental software developers with EMA-coordinated reporting automation. The signal to watch is EPA enforcement timeline compression from quarterly to daily reporting windows as inflection indicator for real-time monitoring demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unifies CEMS hardware, edge preprocessing, and cloud analytics into single vendor relationships for utility procurement teams. |
| Acquisition of Specialist Firm | Adds predictive emission forecasting capabilities that command premium pricing from Marathon Petroleum and BASF-operated facilities. |
| Strategic Partnership | Aligns with hyperscaler cloud infrastructure providers to eliminate on-premises maintenance burdens for energy majors. |
| Geographic Expansion | Targets India's Maharashtra and Gujarat manufacturing clusters ahead of CEA-mandated automated monitoring at greenfield sites. |
| Product Launch | Introduces sub-minute data granularity modules for German industrial clusters under binding EU Emissions Trading System decarbonization mandates. |
Research Methodology
Document review covered EPA enforcement protocols, EU Green Deal implementation guidelines, and MEE GB standards documentation, complemented by interviews with utility planning officers, plant engineers at coal-to-gas transition facilities, environmental compliance directors, and CEMS calibration service providers. Secondary validation drew from EIA power generation data, EMA verification body disclosures, IEA industrial emission reports, and SEC filings from automation-heritage vendors. Bottom-up facility-level deployment estimates were cross-referenced against top-down market sizing from regulatory mandate coverage analysis.
Historical deployment trajectories were cross-referenced against panel input from procurement teams at integrated oil majors and industrial conglomerates across the projection horizon. Segmentation modeling incorporated deployment architecture, end-user regulatory exposure intensity, application functional sophistication, and technology integration depth. CAGRs were derived from facility retrofit cycle analysis and greenfield mandate implementation schedules. Industry-specific forecast inputs included EPA Clean Air Act electronic reporting deadline acceleration and EU ETS carbon price trajectory assumptions.
Inputs from utility procurement databases and environmental agency verification registries were available through the study window; gaps in real-time MEE enforcement intensity data introduce uncertainty bands around China market penetration assumptions. Forecasts reflect documented regulatory timelines and technology substitution elasticity parameters. Material deviation in EPA enforcement resource allocation or EU carbon border adjustment mechanism implementation warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Analytical Technology
Global Advanced Visualization Market
Analytical Technology
Global Weather Forecasting Systems Market
Analytical Technology
Asia-Pacific Digital Scent Technology Market
Analytical Technology
North America Trace Detection Screening Market
Analytical Technology
Incubator Analyzer Market
Analytical Technology
Brain Fingerprinting Technology Market
Analytical Technology
Computational Fluid Dynamics (CFD) Market
Analytical Technology
Europe Computational Fluid Dynamics Market
Analytical Technology
Process Analyzer Market
Analytical Technology
Digital Smell Technology Market
Analytical Technology
Global Optical Character Recognition Market
Analytical Technology
United States Computational Fluid Dynamics Market
Analytical Technology
Motion Simulation Market
Analytical Technology
AI-Powered Video Analytics Market