
 Post-Quantum Cryptography Market | 2026-2036
Post-Quantum Cryptography Market Size, Share, and Industry Trends Forecast 2026-2036
Post-Quantum Cryptography Market Insights
The EU Cybersecurity Act is broadening compliance obligations for critical infrastructure operators across member states. IBM sustains deep research investments in lattice-based implementations, while Thales dominates European defense and aerospace certification pathways. PQShield specializes in hardware-software co-design for embedded cryptographic modules, positioning it at the intersection of semiconductor and security supply chains.
Post-quantum cryptography encompasses cryptographic algorithms designed to resist attacks from both classical and quantum computers, employing mathematical structures such as lattice problems, error-correcting codes, and multivariate polynomial systems that lack efficient quantum solutions. These algorithms secure data confidentiality, integrity, and authentication in communications infrastructure, financial transactions, and government systems where long-term secrecy requirements exceed the anticipated timeline for quantum computational supremacy. Lattice-based technology leads current standardization trajectories due to its versatility across encryption and digital signatures, while hash-based approaches occupy niche applications requiring conservative security assumptions with minimal trust in mathematical complexity. Cloud-based deployment models are gaining traction among enterprises seeking managed migration paths without capital-intensive infrastructure overhaul.
NIST in the United States, ETSI in Europe, and the BSI in Germany are driving standardization timelines that compress vendor certification cycles and reshape procurement specifications. The BSI's technical guidelines for quantum-safe migration are particularly influential for industrial automation and automotive supply chains subject to German regulatory oversight. Compliance deadlines embedded in these frameworks are forcing organizations to prioritize cryptographic inventory and risk assessment over immediate full-system replacement. Stakeholders must weigh interoperability against algorithmic agility as standards continue evolving beyond initial NIST selections.
Market Dynamics
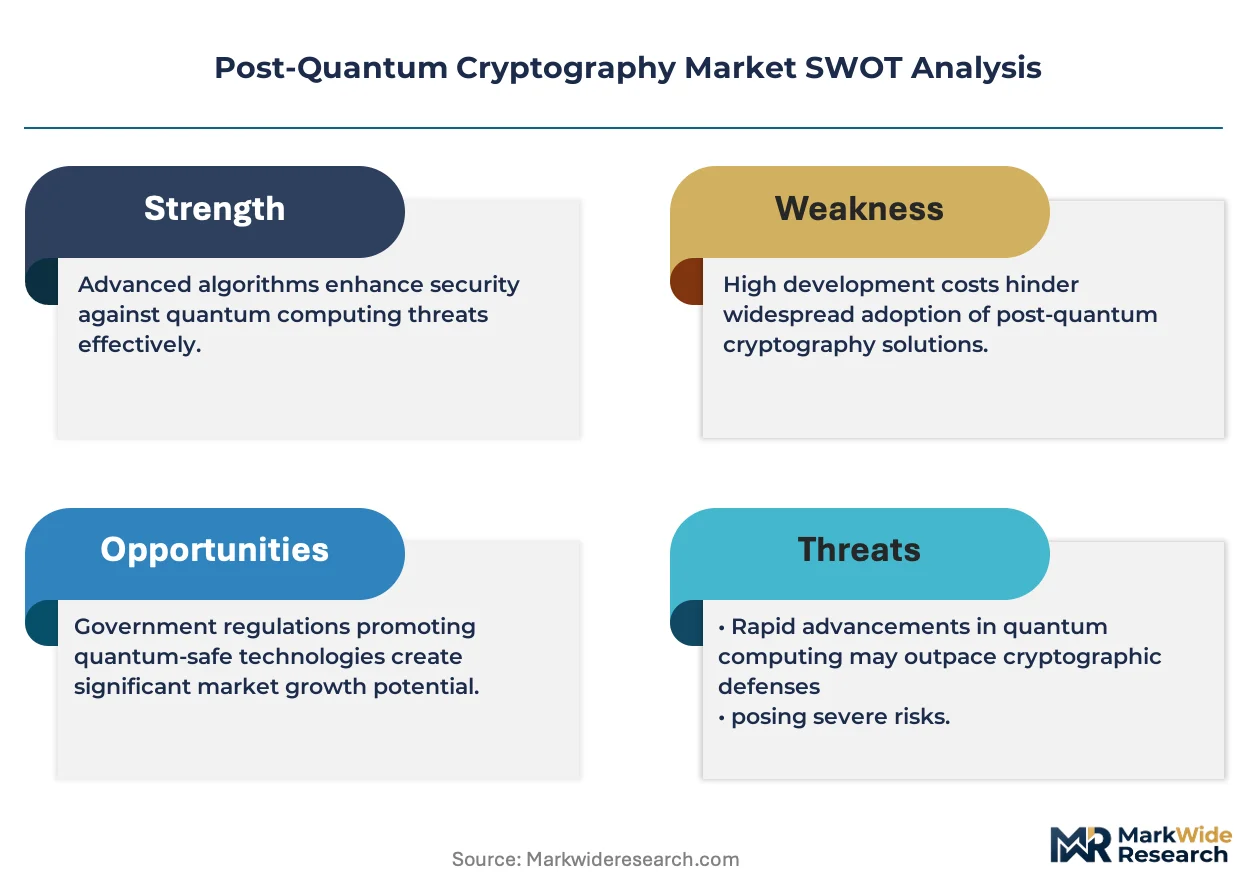
NIST's post-quantum cryptographic standardization timeline is compressing procurement cycles across defense, finance, and critical infrastructure sectors, forcing organizations to prioritize cryptographic inventory over immediate full-system replacement.
Growth Catalysts
- NSA's Commercial National Security Algorithm Suite:Federal mandates require quantum-resistant encryption for classified systems, creating immediate procurement pull-through for lattice-based implementations.
- ETSI quantum-safe migration frameworks:European telecommunications operators must upgrade core network infrastructure, accelerating demand for hardware-software co-designed modules.
- Long-duration data protection requirements:Healthcare and government archives face extended confidentiality obligations that exceed projected quantum computational timelines.
Market Restraints
- Algorithmic uncertainty:Evolving NIST standards create migration hesitation as organizations fear stranded investments in deprecated cryptographic schemes.
- Performance overhead:Lattice-based operations impose 5-20x computational latency compared to classical RSA, constraining real-time applications.
- Certification bottlenecks:Common Criteria and FIPS 140-3 validation cycles extend 18-36 months, delaying product commercialization.
Strategic Opportunities
- Industrial automation retrofit:German automotive and manufacturing supply chains under BSI oversight require embedded quantum-safe modules for connected production lines.
- Cloud-managed migration services:Enterprises seek subscription-based cryptographic lifecycle management without capital-intensive infrastructure overhaul.
- Hybrid cryptographic architectures:Combining classical and post-quantum algorithms during transition periods opens integration service revenue streams.
Industry Challenges
- Cryptographic engineering talent scarcity:Lattice mathematics and side-channel resistant implementation skills concentrate in academic and national laboratory environments.
- Legacy system interoperability:Decades-old embedded controllers in critical infrastructure lack computational headroom for expanded key sizes and signature lengths.
- Supply chain provenance verification:Hardware security module manufacturing requires auditable semiconductor fabrication absent Chinese-sourced components.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Post-Quantum Cryptography Market |
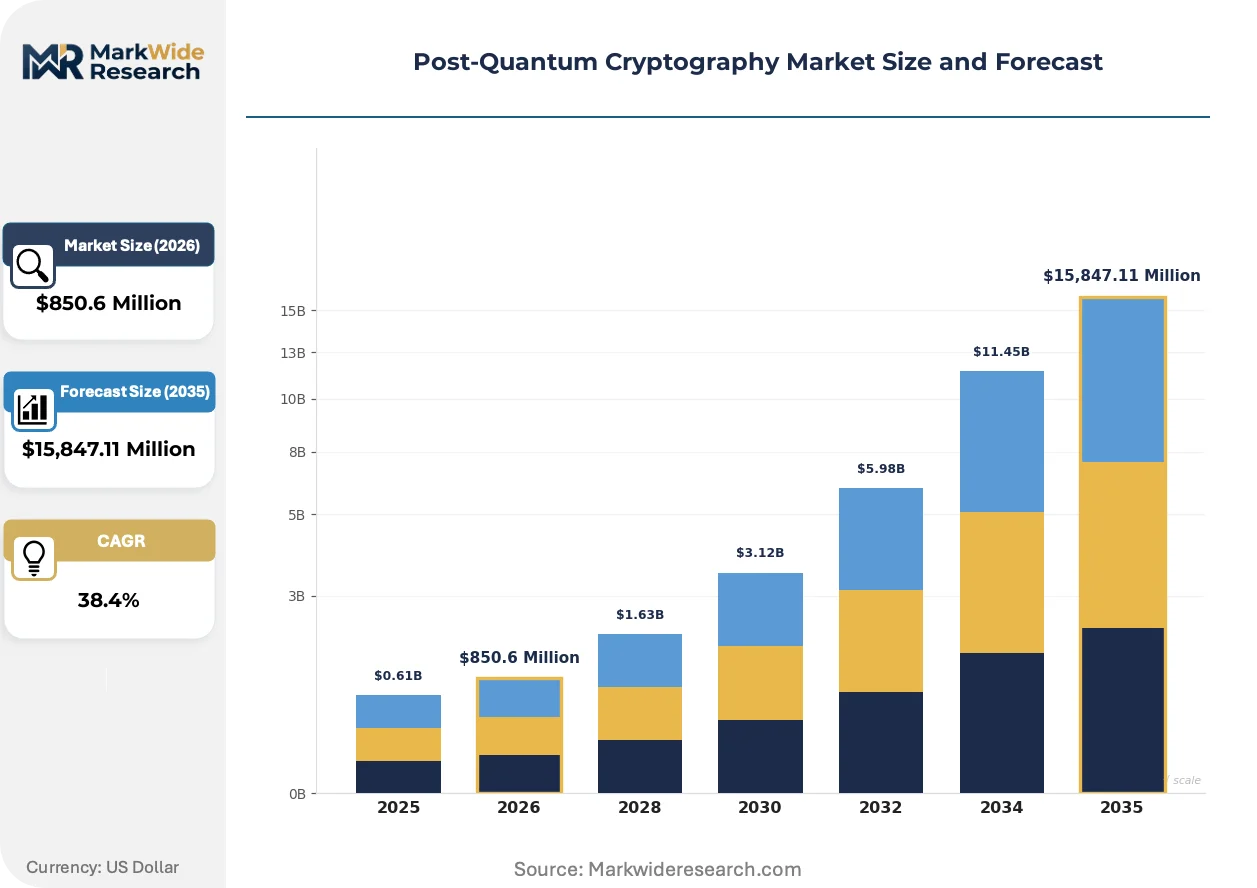
| Market Size in 2026 | $850.6 Million |
| Market Size in 2035 | $15,847.11 Million |
| CAGR (2026 – 2036) | 38.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology Type: Lattice-Based, Code-Based, Multivariate Polynomial, Hash-Based Deployment Model: On-Premises, Cloud-Based, Hybrid, Edge Computing Application: Financial Services, Government, Healthcare, Telecommunications End User: Enterprises, Research Institutions, Government Agencies, Individuals |
| Companies Covered | NXP Semiconductors, Amazon Web Services, IDEMIA, Palo Alto Networks, DigiCert, Thales, Entrust Corporation, IBM, PQShield, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Post-Quantum Cryptography Market Trends and Innovations
Standardization velocity is outpacing organizational readiness, creating a capability gap between available algorithms and deployable implementations. Vendors are racing to bridge this divide through modular architectures and managed transition services.
Lattice-based cryptography is absorbing the bulk of standardization investment due to its versatility across encryption, digital signatures, and key exchange protocols. Financial institutions in the United States are piloting CRYSTALS-Kyber and CRYSTALS-Dilithium in payment network testbeds ahead of regulatory deadlines. The technology is absorbing risk-averse procurement budgets that previously supported hash-based alternatives.
BSI technical guidelines for quantum-safe migration are reshaping procurement specifications for industrial automation and automotive supply chains subject to German regulatory oversight. The framework mandates cryptographic inventory and risk assessment as preconditions for compliance certification. Automotive Tier-1 suppliers are restructuring supplier qualification processes to embed these requirements.
Managed security service providers are capturing cryptographic lifecycle contracts from enterprises unwilling to build in-house post-quantum expertise. Banks and healthcare systems in the United States are outsourcing key generation, certificate management, and algorithmic agility monitoring to specialized vendors. This pattern concentrates procurement authority among CISO offices and procurement teams with limited cryptographic engineering depth.
Post-Quantum Cryptography Market Segmentation
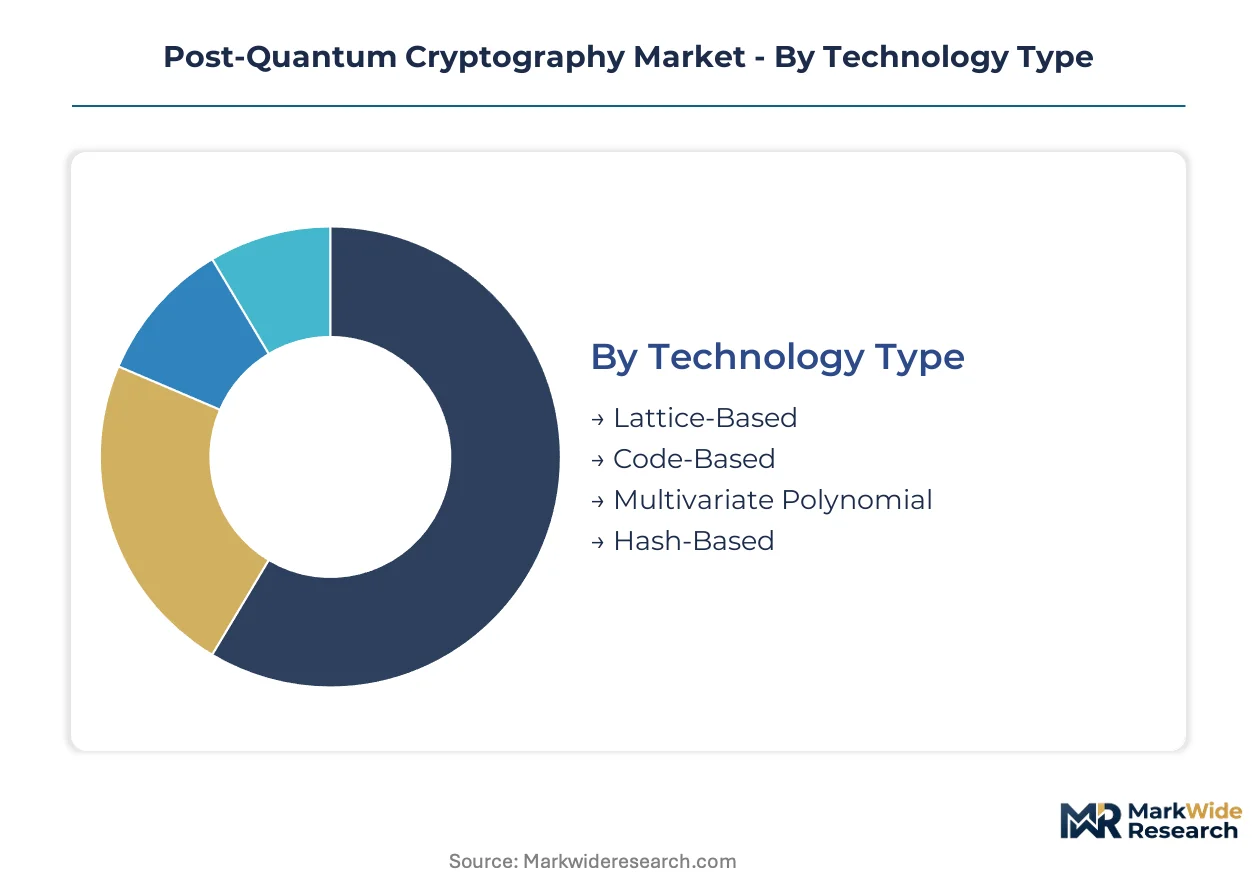
Post-quantum cryptography vendors must navigate distinct upgrade cycles across technology generations, deployment architectures, and sector-specific compliance timelines. Segmentation reveals where procurement urgency concentrates and where migration hesitancy persists.
Technology Type:
Upgrade cycles vary sharply by mathematical foundation, with lattice-based systems commanding early standardization investment while hash-based approaches serve conservative risk profiles.
- Lattice-Based:These algorithms rely on the hardness of lattice problems in high-dimensional vector spaces, enabling compact key sizes and efficient implementations across encryption and digital signatures. Demand concentrates in United States federal procurement channels, where NSA mandates for quantum-resistant classified systems are compressing vendor certification timelines. NIST's selection of CRYSTALS-Kyber and CRYSTALS-Dilithium as primary standards has shifted risk-averse budgets decisively toward this category.
- Code-Based:Built on the difficulty of decoding random linear codes, these schemes offer conservative security assumptions with decades of cryptanalytic scrutiny. European telecommunications operators under ETSI quantum-safe frameworks are piloting Classic McEliece for long-term archival protection, though enormous public key sizes constrain real-time deployment. The BSI's technical guidelines specifically endorse code-based methods for industrial automation where computational headroom permits.
- Multivariate Polynomial:Security derives from solving systems of quadratic equations over finite fields, producing fast signature generation suitable for resource-constrained devices.
- Hash-Based:These constructions minimize trust in mathematical complexity by relying solely on hash function properties, attracting defense procurement with extended confidentiality horizons.
Volume placements concentrate in lattice-based implementations; the faster expansion belongs to hash-based alternatives in classified archival applications.
Deployment Model:
Cost tier differentiation separates capital-intensive on-premises hardware from subscription-managed cloud services, with hybrid architectures capturing transitional risk mitigation budgets.
- On-Premises:Organizations deploy dedicated hardware security modules within controlled facilities, maintaining full custody of cryptographic keys and algorithm parameters. United States defense contractors and financial clearinghouses favor this model for FIPS 140-3 compliance, accepting 18-36 month certification cycles as necessary overhead for sovereign control.
- Cloud-Based:Managed service providers host key generation, certificate lifecycle, and algorithmic agility monitoring through subscription contracts. Healthcare systems in Germany and mid-market banks across France are outsourcing post-quantum migration to avoid building scarce lattice mathematics expertise in-house.
- Hybrid:Concurrent operation of classical and post-quantum algorithms during transition periods, enabling phased risk reduction without immediate full-system replacement.
- Edge Computing:Embedded cryptographic modules protect data at network peripheries where latency constraints preclude centralized processing.
Revenue gravity sits with cloud-based deployments; hybrid architectures are climbing the fastest as compliance deadlines force interim solutions.
Application:
Sector-specific regulatory pressure determines migration sequencing, with government and financial services facing binding deadlines while healthcare and telecommunications navigate voluntary frameworks.
- Financial Services:Payment networks, clearing systems, and digital asset infrastructure require transaction integrity protections that withstand future quantum attacks. United States banks are piloting CRYSTALS-Kyber in testbed environments ahead of anticipated SEC guidance, while German automotive financing arms under BSI oversight prioritize supplier qualification restructuring.
- Government:Classified communications, identity credentialing, and long-term archival systems face the most compressed procurement timelines. NATO member states are accelerating lattice-based encryption for diplomatic and military channels, with national security agencies mandating quantum-resistant algorithms for systems with confidentiality horizons exceeding two decades.
- Healthcare:Electronic health records and genomic databases carry extended privacy obligations that exceed projected quantum computational timelines.
- Telecommunications:Core network infrastructure and subscriber identity protection are subject to ETSI quantum-safe migration frameworks across European member states.
Procurement authority concentrates in government channels; healthcare applications are gaining share fastest as HIPAA-covered entities recognize archival exposure.
End User:
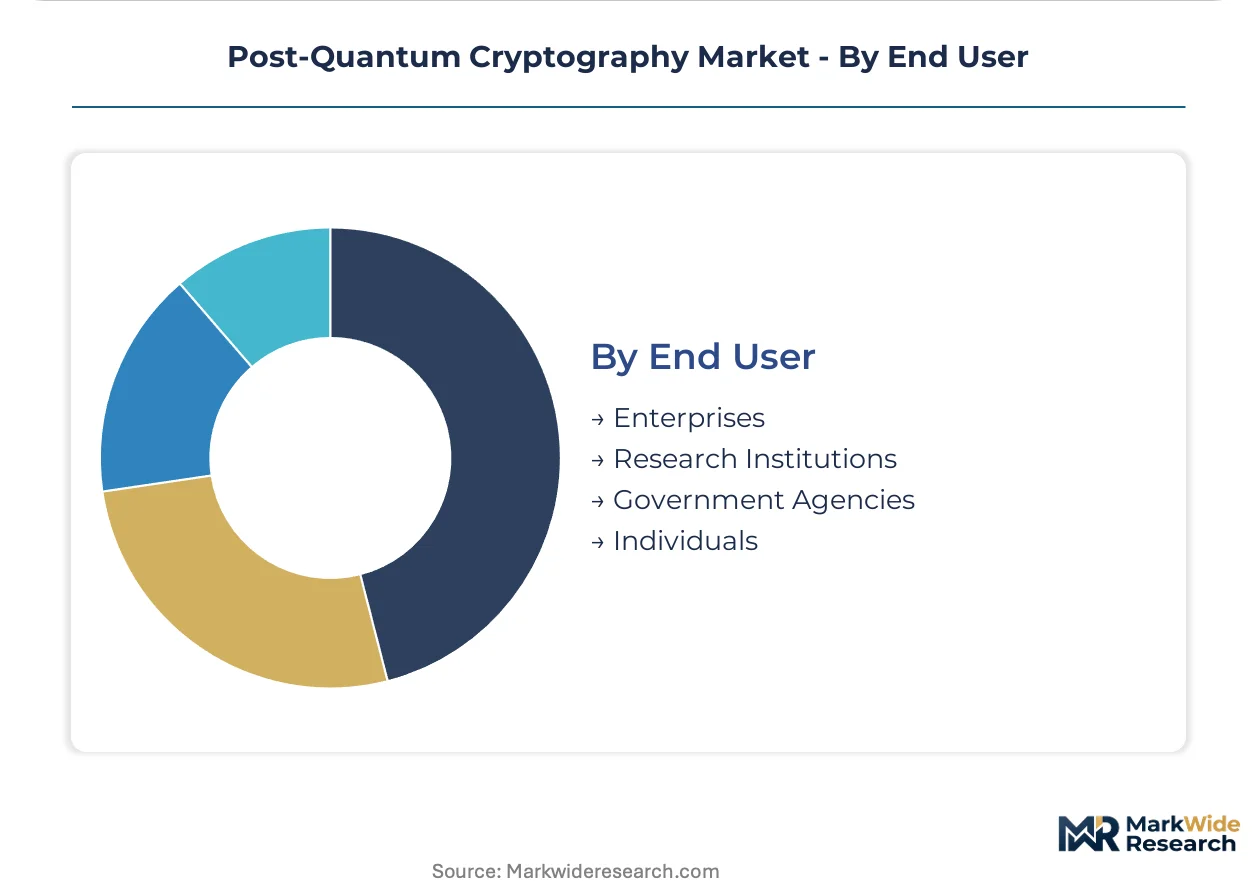
Customer type determines purchasing sophistication, with government agencies and research institutions driving specification development while enterprises and individuals follow managed service pathways.
- Enterprises:Corporate IT organizations balance cryptographic inventory complexity against board-level risk oversight, often lacking internal lattice engineering depth. Managed security service providers are capturing lifecycle contracts from Fortune 500 manufacturers with German supply chain exposure requiring BSI-compliant embedded modules.
- Government Agencies:National laboratories, defense departments, and intelligence services possess in-house cryptographic expertise and direct standardization influence. These buyers specify algorithmic agility requirements that reshape vendor product roadmaps through procurement leverage.
- Research Institutions:Academic cryptography groups and national science foundations advance algorithmic foundations and side-channel resistant implementations.
- Individuals:Consumer-grade protection remains nascent, with password managers and messaging applications beginning to incorporate optional post-quantum key exchange.
Budget authority clusters with government agencies; enterprise adoption is expanding most quickly as managed services reduce expertise barriers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production concentrates among semiconductor fabricators and cloud infrastructure operators in the United States, Germany, and Japan, while consumption spreads across NATO-aligned governments and financial clearinghouses seeking quantum-resistant encryption certification.
United States
Defense contractors and federal agencies drive procurement urgency through NSA's Commercial National Security Algorithm Suite mandates. NIST standardization timelines compress vendor certification cycles to 18-36 months for FIPS 140-3 validation. Washington DC and Northern Virginia host concentrated demand from intelligence services and payment network operators piloting CRYSTALS-Kyber implementations.
Germany
Automotive Tier-1 suppliers and industrial automation vendors face BSI technical guidelines requiring cryptographic inventory as a compliance precondition. The EU Cybersecurity Act broadens obligations for critical infrastructure operators across member states. Bavaria and Baden-Württemberg anchor embedded module demand from connected production line retrofit programs.
United Kingdom
Financial clearinghouses and telecommunications operators navigate ETSI quantum-safe migration frameworks for core network infrastructure. National security agencies mandate lattice-based encryption for diplomatic channels with confidentiality horizons exceeding two decades. London concentrates managed security service procurement from enterprises outsourcing post-quantum expertise.
France
Aerospace and defense certification pathways dominate procurement specifications through Thales-led supply chains serving NATO member states. ANSM and CNIL oversight extends to healthcare archive systems with extended privacy obligations. Paris and Toulouse cluster demand for hardware-software co-designed modules in satellite and military communications.
Japan
Semiconductor equipment manufacturers and telecommunications operators invest in side-channel resistant implementations for resource-constrained devices. METI guidance shapes industrial automation retrofit timelines alongside automotive supply chain restructuring. Tokyo and Osaka anchor cryptographic engineering talent pools concentrated in academic and national laboratory environments.
Post-Quantum Cryptography Market Competitive Landscape
The competitive structure tilts toward technology conglomerates with existing certification pathways and specialized cryptographic engineering boutiques. Semiconductor vendors and cloud hyperscalers occupy consolidated positions leveraging FIPS 140-3 and Common Criteria validation infrastructure. Three archetypes dominate: lattice mathematics specialists, hardware security module fabricators, and managed cryptographic service operators. Competitive moves concentrate on strategic partnerships bridging algorithmic agility gaps and geographic expansion capturing BSI and ETSI compliance contracts.
Within the technology conglomerate tier, IBM and Thales exemplify archetypes leveraging deep research investments and defense-aerospace certification dominance respectively. PQShield occupies a specialist position at the intersection of semiconductor and security supply chains, representing hardware-software co-design capabilities for embedded modules. Amazon Web Services anchors cloud-based deployment models capturing enterprise subscription demand without capital-intensive infrastructure overhaul.
| Leading Market Players |
|---|
| NXP Semiconductors |
| Amazon Web Services |
| IDEMIA |
| Palo Alto Networks |
| DigiCert |
| Thales |
| Entrust Corporation |
| IBM |
| PQShield |
| Others |
Pricing and Supply Chain Analysis
Lattice-based algorithm standardization is compressing vendor certification timelines while simultaneously concentrating production among semiconductor fabricators with FIPS 140-3 validation infrastructure, reshaping both cost economics and supply-side bargaining power.
Pricing Analysis
Margin tightening in hardware security modules reflects 18-36 month Common Criteria validation cycles that gate market entry. Pricing stratifies across FIPS 140-3 certified, Common Criteria evaluated, and uncertified evaluation tiers, with certification grade and volume scale as primary differentiation drivers. Cost compression in cloud-managed services accelerates because hyperscalers leverage amortized infrastructure across subscriber bases. Mid-market enterprises exhibit highest price sensitivity; defense contractors demonstrate lowest sensitivity due to sovereign control requirements.
Supply Chain Analysis
Single-source vulnerability sits with Taiwan-based semiconductor foundries fabricating side-channel resistant secure elements. Raw material dependencies encompass silicon wafers, rare earth elements for magnetic shielding, and specialized packaging substrates. Supply chain risk centers on export control restrictions affecting quantum-resistant hardware exports to designated countries. Distribution runs through direct vendor relationships with defense primes and cloud service provider marketplaces for enterprise segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Post-quantum cryptography is consolidating around vendors with pre-existing certification pathways, as algorithmic uncertainty and talent scarcity force weaker players toward acquisition or exit.
For Market Incumbents: To counter emerging lattice mathematics specialists from academic spinouts, deepen backward integration into semiconductor fabrication and accelerate FIPS 140-3 pre-validation investments. Prioritize certification maintenance in German BSI and ETSI frameworks to lock out unqualified competitors. For New Entrants and Emerging Players: Mid-market healthcare systems lacking in-house cryptographic expertise represent the most penetrable buyer archetype. Target cloud-managed migration services with subscription pricing to bypass capital expenditure barriers. Pursue partnership routes with managed security service providers rather than direct enterprise sales. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by cloud hyperscalers seeking embedded security capabilities. Long-term viability hinges on algorithmic agility architecture that withstands NIST standard evolution. Watch for NIST algorithm deprecation announcements as inflection indicators for stranded technology risk.| Strategic Initiative | Industry Significance |
|---|---|
| Hardware-Software Co-Design Investment | PQShield's embedded module approach enables automotive Tier-1 supplier qualification under BSI guidelines. |
| Cloud Migration Service Launch | Amazon Web Services captures healthcare system subscriptions avoiding in-house lattice engineering costs. |
| Certification Pre-Validation Program | Thales accelerates Common Criteria cycles for NATO defense procurement channels. |
| Academic Partnership for Talent Pipeline | IBM sustains lattice mathematics research through national laboratory collaborations. |
| Hybrid Cryptographic Architecture Development | DigiCert enables phased classical-to-post-quantum transition without full-system replacement. |
Research Methodology
Multi-period observation of NIST standardization milestones, vendor certification timelines, and procurement contract awards anchored the trend analysis, supplemented by interviews with cryptographic engineering directors, CISOs at financial institutions, defense procurement officers, cloud platform architects, and semiconductor product managers. Secondary validation drew from NIST algorithm submission documentation, ETSI technical specifications, BSI migration guidelines, FIPS 140-3 validation certificates, and SEC filings of publicly traded cybersecurity vendors. Bottom-up segment sizing triangulated against top-down market aggregation.
Input-output matrices mapped deployment model adoption rates against sector-specific compliance deadlines across the projection horizon. Segmentation dimensions modeled encompass technology type, deployment architecture, application vertical, end-user sophistication tier, and regional regulatory cluster. CAGRs derived from fitted growth curves adjusted for standardization velocity and certification bottleneck duration. Forecast inputs included quantum computing advancement timelines from national laboratory publications and government procurement budget allocations.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to NIST algorithm deprecation decisions, export control expansion, and breakthrough cryptanalytic attacks. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cybersecurity
Nordics Cybersecurity Market
Cybersecurity
Thailand IT and Security Market
Cybersecurity
SD-WAN Security Market
Cybersecurity
Cyber Security As a Service Market
Cybersecurity
Enterprise Firewall Market
Cybersecurity
Cryptojacking Solution Market
Cybersecurity
Mobile Encryption Market
Cybersecurity
Global Network Security Firewall Market
Cybersecurity
Global Ddos Protection Market
Cybersecurity
New Zealand Cybersecurity Market
Cybersecurity
Asia Pacific Data Exfiltration Market
Cybersecurity
Global Deep Packet Inspection (DPI) Market
Cybersecurity
Cybersecurity in Gaming Market
Cybersecurity
Digital Security Market
Cybersecurity
Global Mobile Application Security Market
Cybersecurity
Germany Endpoint Detection and Response Market