
 IoT Security Market | 2026-2036
IoT Security Market Size, Share, and Industry Trends Forecast 2026-2036
IoT Security Market Intelligence
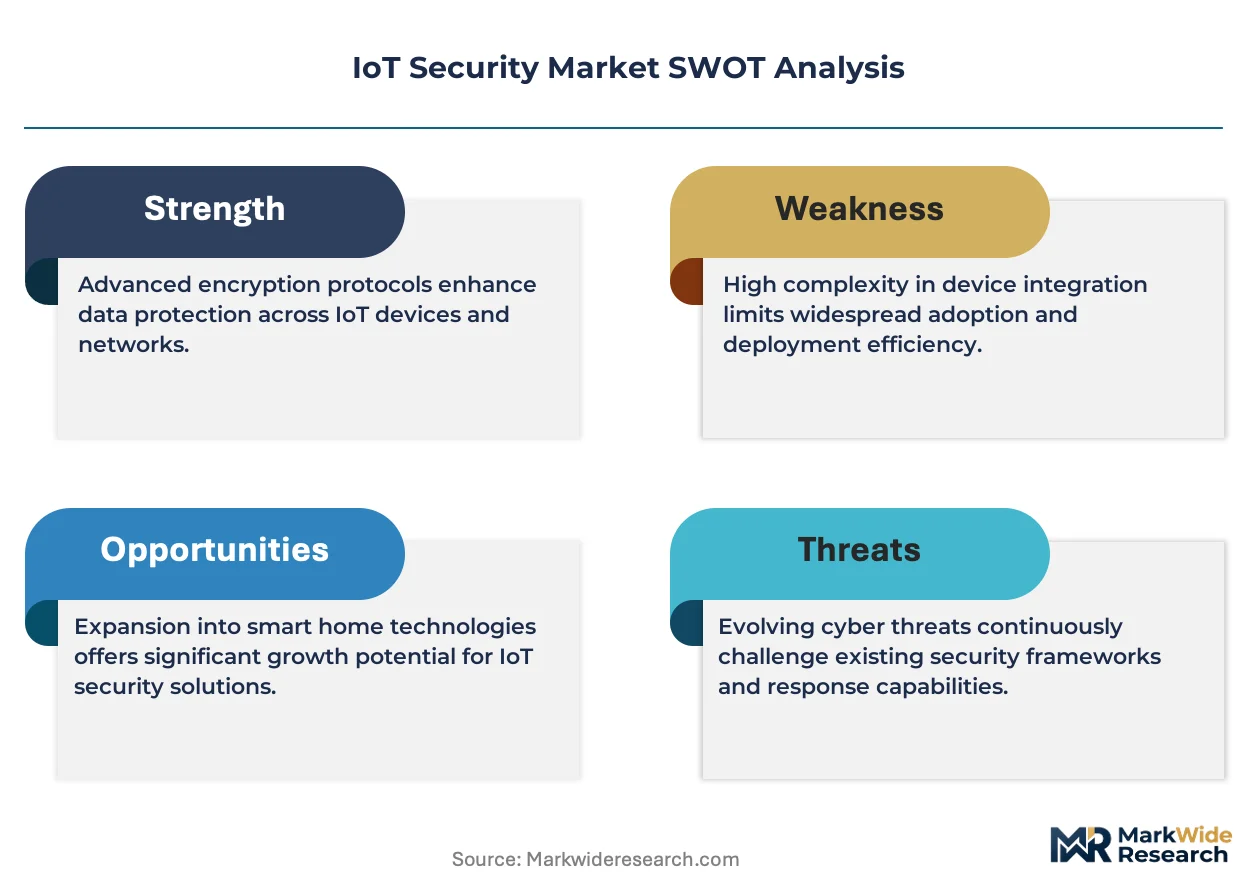
The EU Green Deal's push for digitized energy infrastructure is shifting demand toward robust security for smart grid and utility IoT devices. Cisco Systems leverages its extensive networking hardware portfolio to embed security at the infrastructure layer. Palo Alto Networks competes by offering a cloud-native security platform for diverse IoT endpoints. Microsoft differentiates through its Azure IoT platform, integrating security services directly into its cloud ecosystem for enterprise clients.
IoT Security encompasses the technologies and practices designed to protect internet-connected devices and their networks from cyber threats. This involves securing devices with limited processing power and memory, often using lightweight cryptography and secure boot processes to establish trust. Within product types, endpoint security solutions are foundational for protecting individual devices from compromise. The managed services deployment model is gaining traction among enterprises in healthcare and manufacturing seeking outsourced expertise.
Regulatory frameworks like the EU's Cyber Resilience Act and the US IoT Cybersecurity Improvement Act establish baseline security standards for device manufacturers. Concurrently, rules from bodies like the NHTSA in the United States for automotive cybersecurity and the FDA for medical devices mandate stringent security protocols. Stakeholder success will be determined by creating security architectures that can adapt to a patchwork of evolving national and vertical-specific compliance requirements.
Market Dynamics
The proliferation of national and industry-specific cybersecurity mandates is the central force shaping the IoT security market. This regulatory patchwork compels device manufacturers to integrate security features from the design phase, moving beyond reactive, software-based patches to embedded, hardware-level trust.
Growth Catalysts
- Lightweight Cryptography:These algorithms enable strong encryption on resource-constrained devices, making it feasible to secure industrial sensors and consumer electronics.
- EU Green Deal Initiatives:The policy's push for digitized energy infrastructure creates demand for securing smart grid and utility IoT deployments against critical threats.
- Connected Vehicle Complexity:The expansion of Vehicle-to-Everything (V2X) communication requires specialized security to protect vehicle functions and passenger data from compromise.
Market Restraints
- Device Heterogeneity:The immense variety of IoT devices, operating systems, and protocols complicates the creation of standardized, universal security solutions.
- Cost Sensitivity:In low-margin consumer and industrial products, the bill-of-materials cost for robust security hardware can be prohibitive for manufacturers.
- Legacy System Inertia:Industrial devices with long operational lifecycles are difficult to patch or upgrade, leaving a large installed base of insecure equipment.
Strategic Opportunities
- Smart City Security Platforms:Large-scale urban projects require integrated security to protect interconnected systems, from traffic management to public utility grids.
- Compliance-as-a-Service:Regulations like the EU Cyber Resilience Act create demand for vendors offering pre-certified components and compliance management services.
- Managed Security for Verticals:Enterprises in healthcare and manufacturing are a key market for outsourced expertise in IoT threat monitoring and incident response.
Industry Challenges
- Lack of Standardization:Delays in establishing globally recognized security standards for IoT create interoperability issues and increase development complexity for manufacturers.
- Cybersecurity Skills Gap:A shortage of professionals with expertise in both embedded systems and cybersecurity hampers the ability to design, implement, and manage secure IoT deployments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | IoT Security Market |
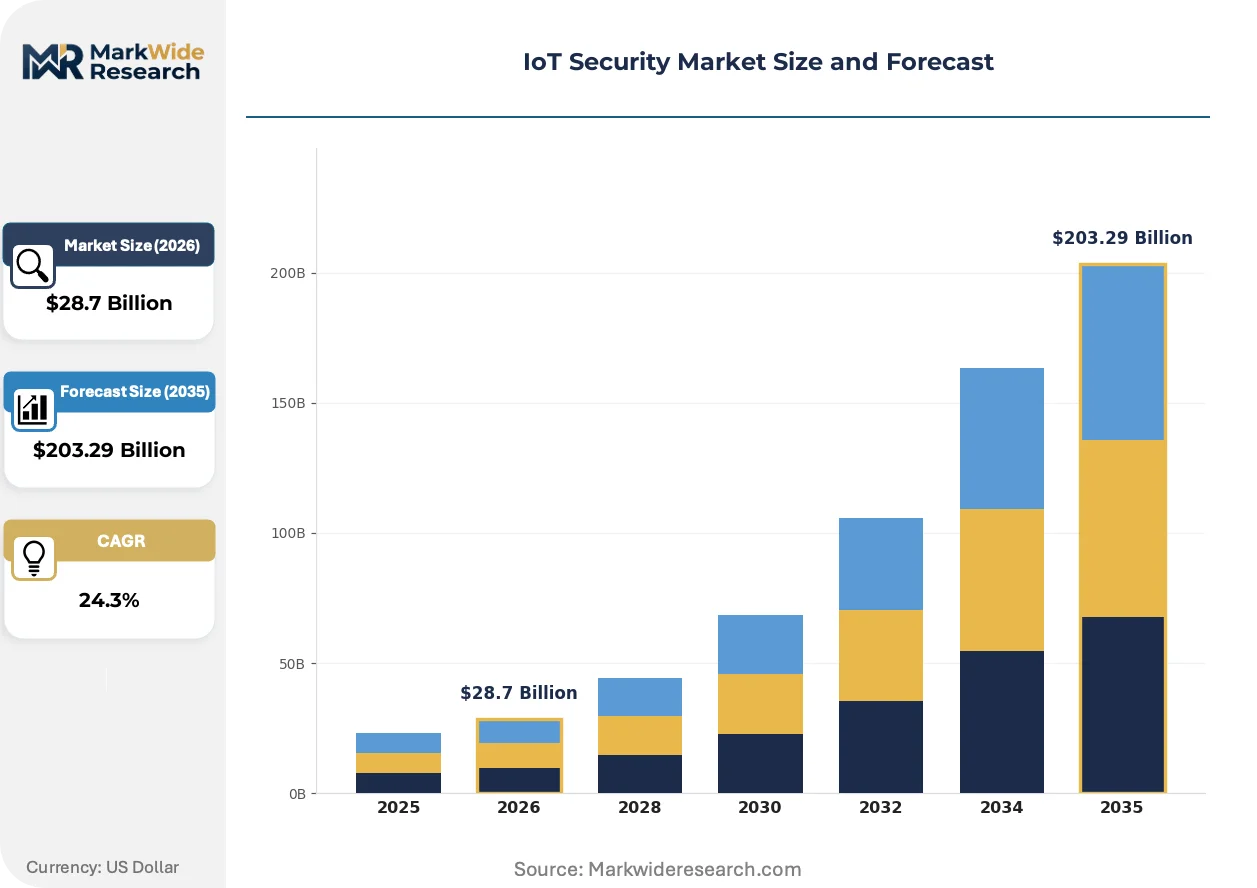
| Market Size in 2026 | $28.7 Billion |
| Market Size in 2035 | $203.29 Billion |
| CAGR (2026 – 2036) | 24.3% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Endpoint Security, Network Security, Cloud Security, Application Security Deployment Model: On-Premises, Cloud-Based, Hybrid, Managed Services Industry Vertical: Healthcare, Automotive, Manufacturing, Smart Home End User: Enterprises, Government, Individuals, SMBs |
| Companies Covered | Armis, Check Point Software Technologies, Palo Alto Networks, Forescout, Trend Micro, Cisco Systems, Fortinet, Microsoft, Nozomi Networks, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
IoT Security Market Strategic Shifts & Innovations
The focus of IoT security is shifting from reactive, device-level software patches toward proactive, infrastructure-level controls. This evolution is driven by the integration of security into networking hardware and cloud-native platforms, creating a more holistic defense posture.
Hardware Root of Trust
Secure boot processes establish a hardware root of trust, ensuring devices only load authenticated firmware. This technology is a standard requirement in automotive and enterprise IoT, where integrity is critical. The hardware-based model is converging with cloud attestation services to provide continuous, verifiable proof of device health throughout its lifecycle.
Regulatory Baselines
In the United States, the IoT Cybersecurity Improvement Act sets minimum security standards for devices procured by the federal government. This law creates a de facto baseline for the commercial market, mandating secure development and vulnerability disclosure. Device manufacturers targeting government now adopt these standards across their product lines to streamline compliance.
Shift to Managed Services
A behavioral shift is underway as enterprises adopt outsourced, managed security service models instead of in-house management. This disrupts standalone product sales, favoring providers with subscription-based threat monitoring and incident response. The trend is most pronounced in healthcare and manufacturing, where specialized operational technology security expertise is often lacking internally.
IoT Security Market Segmentation
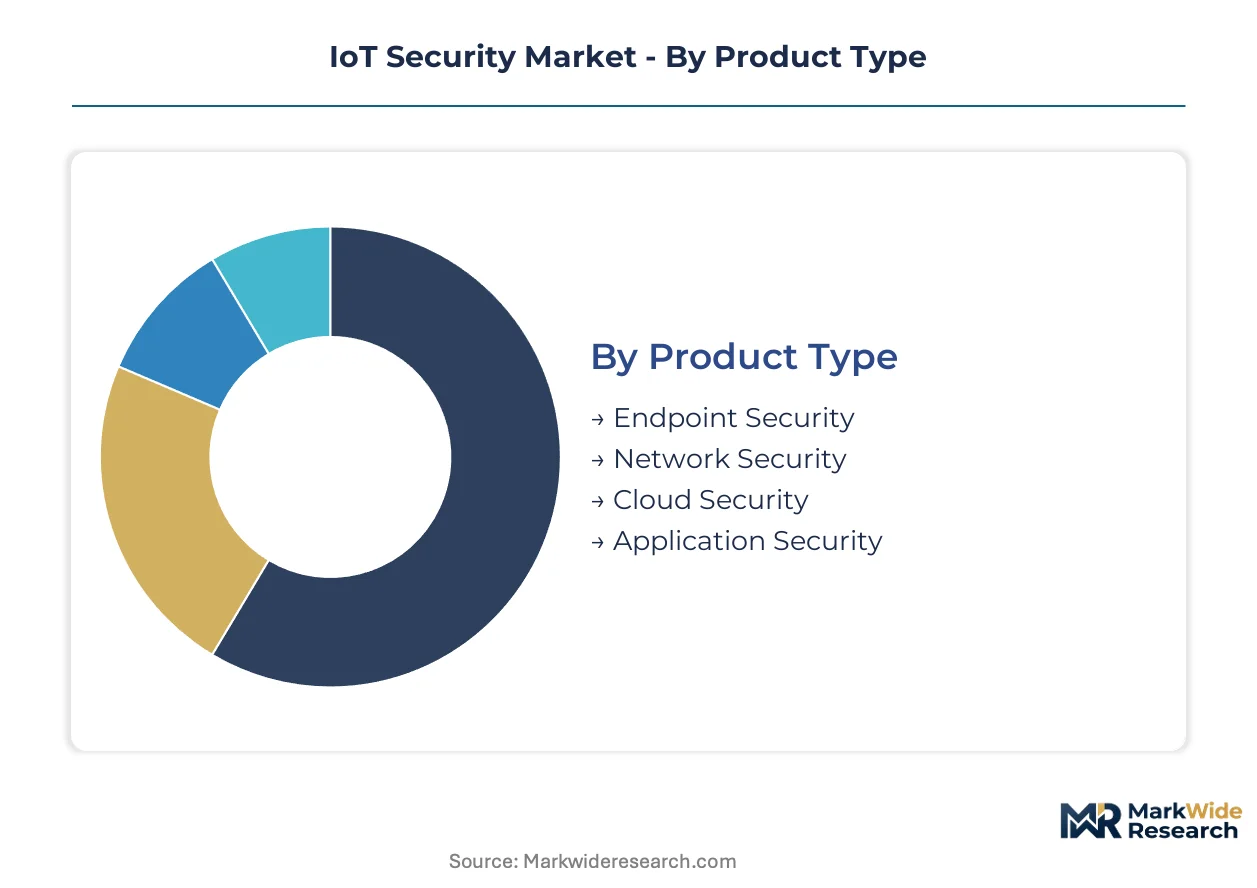
The IoT security market segmentation clarifies diverse needs across various connected device ecosystems. Understanding these distinctions helps stakeholders tailor solutions for specific operational environments. This analysis highlights how different security approaches address varying scale and complexity within the market.
Product Type:
The lifecycle of IoT devices dictates the upgrade and replacement cycles for their integrated security components.
- Endpoint Security:This solution protects individual internet-connected devices, ensuring their integrity and preventing unauthorized access. Demand concentrates in industrial IoT and smart city deployments, driven by the need to secure vulnerable sensors and gateways.
- Network Security:This segment focuses on safeguarding the communication channels and infrastructure connecting IoT devices.
- Cloud Security:Cloud security solutions protect data and applications hosted in cloud environments that interact with IoT devices. Demand concentrates among enterprise clients leveraging platforms like Microsoft Azure IoT, driven by the need for scalable and centralized threat management.
- Application Security:This involves securing the software applications running on or interacting with IoT devices.
Volume placements concentrate in Endpoint Security; the faster expansion belongs to Cloud Security.
Deployment Model:
Customer type and internal IT capabilities heavily influence the preferred deployment model for IoT security solutions.
- On-Premises:Security infrastructure is installed and managed directly within the organization's own physical environment.
- Cloud-Based:Security services are delivered and managed entirely through cloud platforms, offering scalability and remote accessibility. Demand concentrates in greenfield smart city projects, driven by the need for flexible infrastructure and reduced capital expenditure.
- Hybrid:This model combines elements of both on-premises and cloud-based security for balanced control and flexibility.
- Managed Services:External providers handle all aspects of IoT security, including monitoring, threat detection, and incident response. Demand concentrates in healthcare and manufacturing sectors, driven by the specialized expertise required for operational technology security.
Enterprises increasingly prioritize Managed Services for specialized expertise, while Cloud-Based solutions are gaining share fastest among new deployments.
Industry Vertical:
The specific operational applications within each industry vertical determine the unique security requirements for IoT devices.
- Healthcare:This vertical requires stringent security for medical devices and patient data, adhering to regulations like HIPAA and FDA mandates. Demand concentrates in connected medical devices and remote patient monitoring, driven by critical data protection needs.
- Automotive:Security in this sector protects connected vehicles and V2X communications from cyber threats and data breaches. Demand concentrates in advanced driver-assistance systems and in-vehicle infotainment, driven by the complexity of vehicle software.
- Manufacturing:This segment focuses on securing industrial control systems, operational technology, and smart factory environments.
- Smart Home:Security solutions here protect consumer IoT devices, home networks, and personal data from various cyber risks.
Automotive and Healthcare represent critical sectors for IoT security investments, propelled by regulatory compliance and safety imperatives.
End User:
The organizational maturity and scale of an end user significantly shape their approach to implementing and managing IoT security.
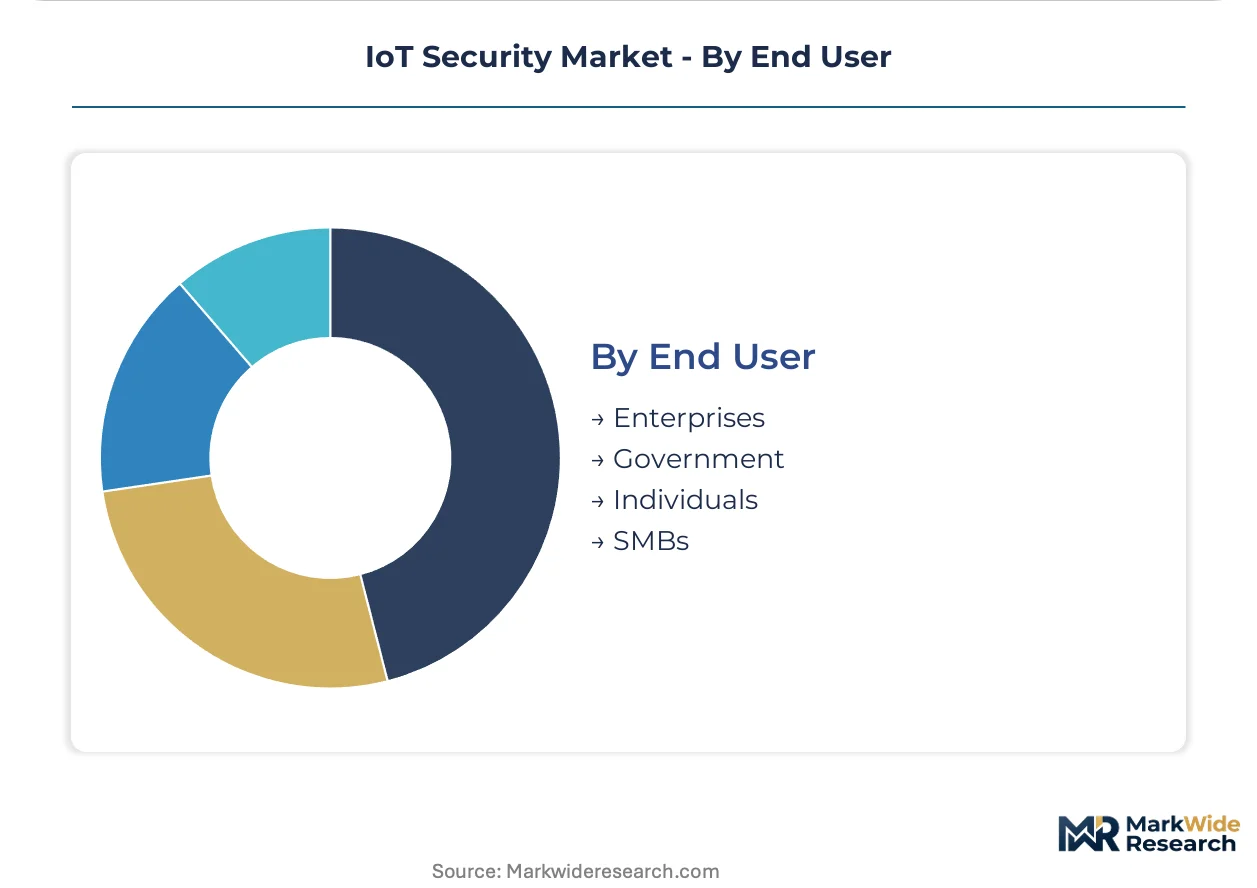
- Enterprises:Large organizations require comprehensive, scalable security solutions for extensive IoT deployments across diverse operations. Demand concentrates in large-scale industrial IoT and smart building initiatives, driven by the need for centralized management and compliance.
- Government:Public sector entities demand robust security for critical infrastructure, smart city projects, and federal IoT deployments, often mandated by laws like the US IoT Cybersecurity Improvement Act. Demand concentrates in defense and public utility sectors, driven by national security and infrastructure protection.
- Individuals:This segment covers personal smart devices and home networks, requiring user-friendly and affordable security options.
- SMBs:Small and medium-sized businesses seek cost-effective and easily manageable IoT security solutions.
Government and Enterprise end users drive substantial investment due to regulatory pressures and the scale of their IoT ecosystems.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Silicon Valley's technology innovation hub drives significant demand for advanced IoT security solutions, particularly for enterprise and cloud-native deployments. This concentration of tech companies and large-scale smart city initiatives mandates robust protection for interconnected systems. Regulatory frameworks across key global economies further compel manufacturers to integrate security by design.
United States
Large-scale enterprise deployments and smart city initiatives drive demand for comprehensive IoT security. The US IoT Cybersecurity Improvement Act establishes baseline security standards for federal procurement. Washington D.C.'s federal agencies and New York City's smart infrastructure projects require stringent device and network protection.
Germany
Industrial IoT and automotive sectors generate substantial demand for embedded security. The EU Cyber Resilience Act compels manufacturers to integrate security features from the design phase. Munich's automotive industry and the Ruhr region's industrial complexes prioritize securing operational technology.
China
Extensive smart city projects and industrial digitalization initiatives fuel demand for scalable IoT security platforms. National security mandates and data protection laws govern the deployment of connected devices. Shenzhen's technology manufacturing base and Beijing's smart city initiatives accelerate security integration.
Japan
Advanced manufacturing and smart infrastructure projects require specialized IoT security. The Ministry of Economy, Trade and Industry (METI) promotes cybersecurity measures for critical infrastructure. Tokyo's dense urban environment and Nagoya's automotive cluster focus on protecting sophisticated sensor networks.
United Kingdom
Critical national infrastructure and smart city developments necessitate resilient IoT security. The UK's Product Security and Telecommunications Infrastructure Act sets security requirements for consumer connectable products. London's financial technology sector and Manchester's smart city initiatives demand robust data and device protection.
IoT Security Market Key Industry Players
Premium-margin players sit above commodity-margin players across the solution complexity and integration depth dimension, particularly in enterprise and critical infrastructure deployments. The market exhibits a tiered structure, from specialized hardware security vendors offering embedded trust to comprehensive cloud platform providers managing diverse IoT ecosystems. Strategic archetypes include network infrastructure giants, cloud-native security specialists, and dedicated operational technology (OT) security firms. Strategic partnerships to extend solution reach and portfolio diversification into new vertical markets are common competitive moves.
Cloud-native security specialists like Palo Alto Networks exemplify the shift towards platform-based protection for diverse IoT endpoints. Cisco Systems, a network infrastructure giant, leverages its extensive hardware portfolio to embed security at the infrastructure layer. Microsoft, with its Azure IoT platform, integrates security services directly into its cloud ecosystem for enterprise clients, occupying a position of comprehensive service provision. These companies anchor the high-value end of the market by offering integrated solutions that span device, network, and cloud security.
| Leading Market Players |
|---|
| Armis |
| Check Point Software Technologies |
| Palo Alto Networks |
| Forescout |
| Trend Micro |
| Cisco Systems |
| Fortinet |
| Microsoft |
| Nozomi Networks |
| Others |
Cost & Logistics Intelligence
The EU Cyber Resilience Act's stringent security-by-design mandates gate both qualified hardware component supply and premium-tier solution pricing access.
Pricing Analysis
Value-based pricing anchored to uptime guarantees and data integrity underpins enterprise IoT security solutions. The dominant pricing model incorporates subscription-based services for cloud platforms and project-based engagements for complex industrial deployments. Price differentiation stems from certification levels, such as those mandated by the US IoT Cybersecurity Improvement Act, and the degree of solution customization. Pricing softness reflects increasing standardization efforts, with SMBs exhibiting higher price sensitivity than government agencies.
Supply Chain Analysis
Direct-to-enterprise channels manage large-scale IoT security platform deployments, while channel partners serve fragmented SMB and consumer markets. Geographic supply concentration for critical hardware components centers on China, the United States, and Germany. The market relies on specialized secure microcontrollers and embedded software libraries for device-level protection. Single-source vulnerability for these highly specialized secure elements represents a significant supply chain risk.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a cost-of-compliance story, with the EU Cyber Resilience Act creating a significant barrier-to-entry moat for device manufacturers and security solution providers.
For Market Incumbents:
Deploy platform integration strategies to consolidate fragmented security offerings under a unified management console. Incumbents should invest in compliance-as-a-service frameworks to help customers navigate the patchwork of global regulations. This approach mitigates the threat of disparate security standards and addresses the cybersecurity skills gap. Certification investment, particularly for automotive and medical IoT, reinforces market leadership against emerging point solutions.
For New Entrants and Emerging Players:
Enter via specialized vertical solutions targeting underpenetrated industrial IoT segments like smart manufacturing or critical infrastructure. Focus on offering compliance-as-a-service models for SMBs that lack internal cybersecurity expertise. Develop cloud-native security platforms with lightweight agents suitable for resource-constrained devices. This go-to-market angle leverages regulatory mandates for rapid market penetration.
For Investors and Strategic Acquirers:
Widespread adoption of hardware root of trust solutions is the leading indicator that device-level security has reached critical mass, signaling mature investment opportunities. Long-term viability hinges on companies capable of integrating security across diverse IoT ecosystems. Acquisition targets should include specialized operational technology (OT) security firms and cloud-native platforms with strong vertical expertise. Monitor the consolidation of regulatory bodies for simplified compliance frameworks.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration Strategies | Unifies disparate security tools, improving threat visibility across complex IoT deployments. |
| Compliance-as-a-Service Offering | Addresses enterprise demand for outsourced regulatory adherence, especially for the EU Cyber Resilience Act. |
| Hardware Root of Trust Development | Establishes foundational device integrity, critical for automotive and industrial IoT applications. |
| Cloud-Native Security Expansion | Provides scalable, flexible protection for diverse IoT endpoints and cloud-connected data streams. |
| Vertical-Specific Solution Bundling | Tailors security features to meet unique regulatory and operational needs of healthcare or manufacturing sectors. |
Research Approach
National cybersecurity agency reports, industry association whitepapers, and technology patent databases formed the secondary backbone of this market analysis. Primary interviews with IoT device manufacturers, cybersecurity architects, enterprise IT security leads, and regulatory compliance officers provided critical insights. This approach combined bottom-up data aggregation with top-down market validation, ensuring robust data triangulation. Public financial filings and academic research further enriched the qualitative and quantitative understanding.
A bottom-up analytical lens first aggregated data from individual IoT device deployments and security solution uptake, then cross-referenced with top-down market sizing across the analysis window. Segmentation dimensions modeled included product type, deployment model, industry vertical, end user, and regional regulatory clusters. Compound annual growth rates were derived from historical trends and projected IoT device proliferation rates.
Forecast precision tightens around the base case; tail outcomes carry wider variance under conditions of rapid technological obsolescence or geopolitical shifts. Forecasts reflect assumptions regarding market dynamics and adoption rates. Practitioners should monitor emerging cyber threats and evolving regulatory landscapes for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cybersecurity
Cloud Authentication Market
Cybersecurity
Australia Cybersecurity Market
Cybersecurity
South Korea Cybersecurity Market
Cybersecurity
Endpoint Security Market
Cybersecurity
Global Patch Management Market
Cybersecurity
Micro Segmentation Technology Market
Cybersecurity
Global Container and Kubernetes Security Market
Cybersecurity
Information Security Products and Services Market
Cybersecurity
Server Security Market
Cybersecurity
Container-based Firewall Market
Cybersecurity
Cybersecurity in Gaming Market
Cybersecurity
Russia Cybersecurity Market
Cybersecurity
Middle East & Africa AI Cybersecurity Market
Cybersecurity
Data Exfiltration Techniques Market
Cybersecurity
Cloud Access Security Broker Market
Cybersecurity
Nigeria Cybersecurity Market