
 Asia and Africa Food Cans Market | 2026-2036
Asia and Africa Food Cans Market Size, Share, and Industry Trends Forecast 2026-2036
Asia and Africa Food Cans Market Outlook
The EU Green Deal's extraterritorial carbon border adjustments is expanding compliance obligations for African and Asian can exporters selling into European retail supply chains. Crown Holdings Inc. leverages its regional coil-coating partnerships to sustain cost-competitive steel can output across North Africa. Silgan Holdings Inc. anchors its position through backward integration into decorated tinplate sourcing for Southeast Asian processed fruit contracts. Kian Joo Can Factory Berhad dominates Malaysia's beverage can segment with high-speed two-piece aluminum lines.
Asia and Africa food cans are cylindrical metal containers fabricated from electrolytic tinplate, tin-free steel, or aluminum alloy, typically featuring double-seamed ends and interior lacquer coatings to prevent corrosion and preserve shelf-stable contents for twenty-four to sixty months. Steel cans retain cost advantages for acidic foods and heat-processed vegetables across price-sensitive African markets, while aluminum cans capture share in premium beverage and ready-to-eat meal applications where lightweight logistics matter. Food manufacturers represent the largest end-user channel, though food service operators in urban India and South Africa are expanding direct procurement of institutional-size cans. Composite cans are gaining traction for dry goods and powdered beverages where paperboard barriers reduce metal intensity per unit.
BIS certification requirements for food-contact metal packaging govern Indian can imports and domestic production, while South Africa's National Regulator for Compulsory Specifications enforces dimensional and coating standards on steel food containers. Kenya's National Environment Management Authority and Nigeria's Standards Organisation of Nigeria both mandate heavy-metal migration testing and recyclability labeling, raising technical barriers for uncertified Chinese and Middle Eastern suppliers. Stakeholders must monitor evolving EPR enforcement timelines and alloy price volatility to calibrate regional capacity investments against import substitution timelines.
Market Dynamics
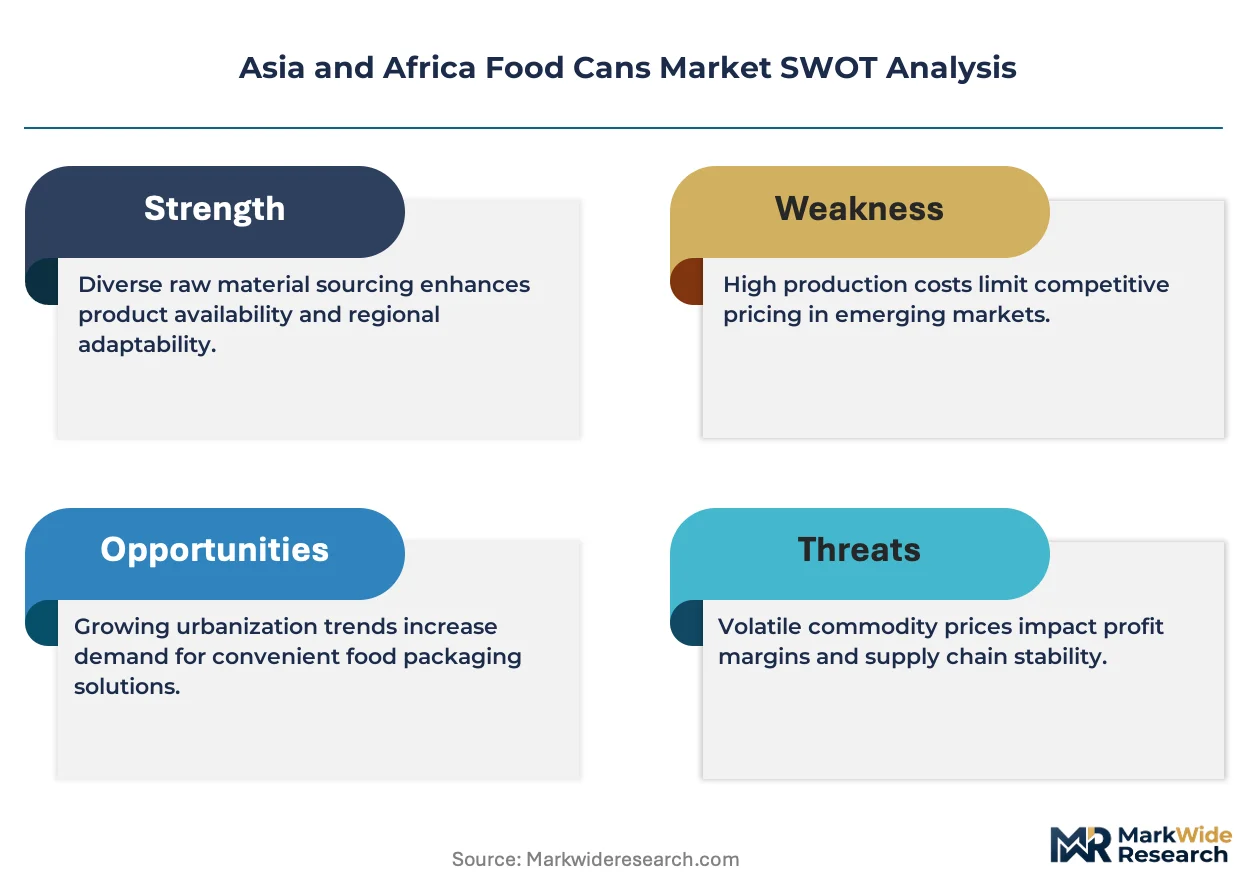
The EU Green Deal's extraterritorial carbon border adjustments are forcing Asian and African can exporters to reconfigure alloy sourcing and coating chemistries for European retail compliance, compressing margins across North African and Southeast Asian converter operations.
Growth Catalysts
- Extended Producer Responsibility mandates:Kenya's National Environment Management Authority and Nigeria's Standards Organisation of Nigeria enforce recyclability labeling and heavy-metal migration testing, accelerating demand for lighter-gauge designs and recycled-content tinplate across West and East African manufacturing corridors.
- Cold-chain infrastructure expansion:Secondary cities across Southeast Asia now support temperature-controlled distribution of shelf-stable seafood, driving aluminum and steel can procurement from packaged seafood manufacturers operating in Vietnam, Thailand, and Indonesia.
- Evaporated milk and tomato paste canning:Nigeria's Lagos-Ibadan manufacturing corridor runs production lines at full capacity, creating sustained demand for three-piece steel cans with interior lacquer coatings optimized for acidic food matrices.
Market Restraints
- Aluminum and steel alloy price volatility:Electrolytic tinplate and tin-free steel coil costs fluctuate with energy-intensive smelting economics, constraining margin predictability for converters serving price-sensitive African vegetable canning markets.
- Supply concentration in coil-coating partnerships:Crown Holdings Inc.'s regional dominance in North African steel can output creates dependency risk for independent converters lacking backward integration into decorated tinplate sourcing.
- Substitution by composite paperboard barriers:Dry goods and powdered beverage packagers in urban India and South Africa are adopting composite cans with reduced metal intensity, displacing cylindrical tinplate for non-acidic applications.
Strategic Opportunities
- Institutional-size can procurement expansion:Food service operators in urban India and South Africa are building direct sourcing relationships with converters, bypassing traditional distributor markups for high-volume ready-to-eat meal applications.
- Two-piece aluminum beverage can technology:Kian Joo Can Factory Berhad's high-speed Malaysian production lines demonstrate scalable capacity for Southeast Asian processed fruit contracts requiring lightweight logistics and premium shelf presentation.
- BIS certification arbitrage:Indian domestic producers meeting Bureau of Indian Standards food-contact metal packaging requirements can capture share from uncertified Chinese and Middle Eastern suppliers facing technical barrier escalation at import checkpoints.
Industry Challenges
- Coating chemistry reformulation timelines:Converters must redesign interior lacquer systems to meet tightened heavy-metal migration thresholds under Kenya's National Environment Management Authority enforcement, compressing product development cycles.
- Dimensional standardization across African customs unions:South Africa's National Regulator for Compulsory Specifications enforces divergent steel food container standards from Nigeria's Standards Organisation of Nigeria, fragmenting pan-African production planning.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia and Africa Food Cans Market |
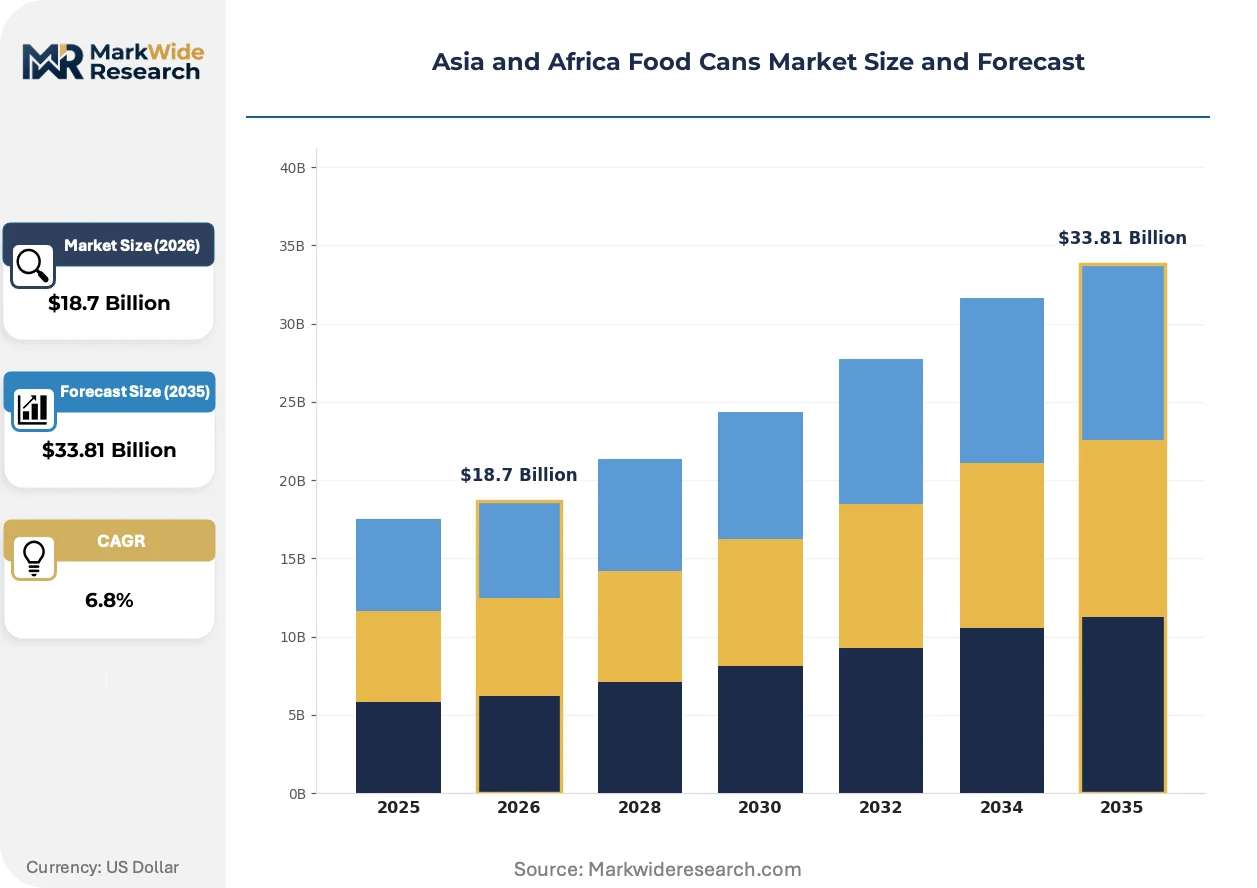
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Aluminum Cans, Steel Cans, Biodegradable Cans, Composite Cans End User: Food Manufacturers, Retailers, Wholesalers, Food Service Operators Usage Type: Preserved Foods, Beverages, Ready-to-Eat Meals, Sauces Distribution Channel: Online Retail, Supermarkets, Convenience Stores, Direct Sales |
| Companies Covered | Silgan Holdings Inc., Nampak Products Ltd, Crown Holdings Inc., Asia Can Co. Ltd, Kian Joo Can Factory Berhad, Toyo Seikan Group Holdings Ltd, CPMC Holdings Limited, Kaira Can Private Limited, Ardagh Group S.A., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia and Africa Food Cans Market Strategic Shifts
Material substitution and regulatory chemistry mandates are actively reshaping can fabrication across Asia and Africa, with lightweighting and coating innovation dominating converter R&D allocation.
Polymer-laminated tin-free steel is absorbing interior corrosion protection functions previously handled by conventional epoxy-phenolic lacquers, enabling thinner substrate gauges without shelf-life degradation. Southeast Asian processed fruit packagers are adopting this substrate at accelerating rates for twenty-four to sixty-month shelf-stable applications. The technology is absorbing cost pressure from alloy price volatility while maintaining double-seamed end integrity.
Kenya's National Environment Management Authority has tightened Extended Producer Responsibility rules for metal packaging waste, mandating recyclability labeling and post-consumer collection infrastructure. This policy is forcing converters toward lighter-gauge designs and recycled-content inputs across Nairobi and Mombasa manufacturing zones. Nigerian and South African regulators are monitoring this enforcement template for potential adoption.
Direct procurement by food service operators is consolidating buyer power in urban India and South Africa, displacing traditional multi-tier distribution for institutional-size cans. Quick-service restaurant chains and catering cooperatives now negotiate volume contracts directly with Silgan Holdings Inc. and regional converters. This channel compression is most visible in Johannesburg, Mumbai, and Lagos metropolitan procurement patterns.
Asia and Africa Food Cans Market Segmentation
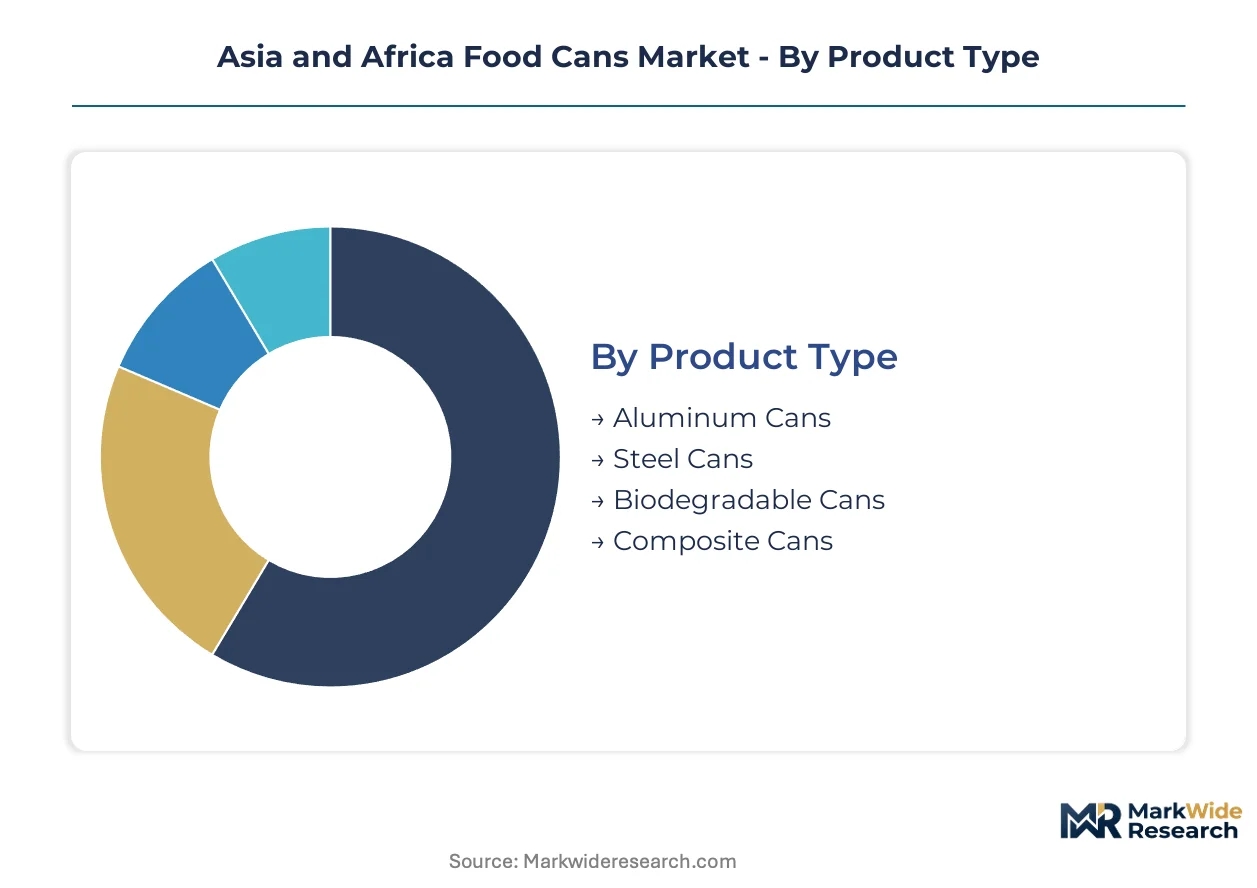
Converter capacity across Asia and Africa fragments along material chemistry and end-user procurement patterns. Segmentation reveals where coil-coating partnerships concentrate, which channels bypass traditional distribution, and which usage types drive alloy specification decisions.
Product Type:
Supply concentration in coil-coating partnerships tilts converter investment toward aluminum and steel substrates while biodegradable alternatives struggle for scale.
- Aluminum Cans:Two-piece drawn-and-wall-ironed construction delivers lightweight logistics for beverage and premium ready-to-eat applications. Demand concentrates in Malaysia's high-speed production corridors and Southeast Asian processed fruit contracts where shelf presentation commands price premiums.
- Steel Cans:Three-piece welded-body fabrication with interior epoxy-phenolic lacquers dominates acidic food matrices. Nigeria's Lagos-Ibadan manufacturing corridor runs steel canning lines at full capacity for tomato paste and evaporated milk, absorbing the majority of regional tinplate coil supply.
- Biodegradable Cans:Polylactic acid and starch-based barrier coatings remain experimental at commercial scale, limited by heat-process compatibility and twenty-four-month shelf-life requirements.
- Composite Cans:Paperboard body with metal ends reduces metal intensity for dry goods; urban Indian and South African packagers adopt these for powdered beverages and snacks.
Steel cans absorb the bulk of installed capacity; aluminum cans are expanding most quickly.
End User:
Procurement authority is shifting from distributor networks toward direct manufacturer relationships, restructuring margin capture across the value chain.
- Food Manufacturers:Tomato paste, evaporated milk, and shelf-stable seafood processors specify interior lacquer chemistries and gauge thicknesses. Kenyan and Nigerian manufacturers face tightened Extended Producer Responsibility compliance timelines from their national environmental regulators.
- Food Service Operators:Quick-service restaurant chains and catering cooperatives in Johannesburg, Mumbai, and Lagos negotiate institutional-size can contracts directly with converters, bypassing traditional distributor markups.
- Retailers:Supermarket private-label programs in South Africa and India drive specification standardization for house-brand canned vegetables and fruits.
- Wholesalers:Regional distributors in secondary Southeast Asian cities aggregate fragmented demand from small-scale food processors lacking direct converter relationships.
Food manufacturers retain the deepest technical specification influence; food service operators are climbing the fastest as a procurement channel.
Usage Type:
Application chemistry determines substrate selection and coating formulation, with acidic matrices preserving steel's cost advantage.
- Preserved Foods:Heat-processed vegetables and seafood require corrosion-resistant interior barriers. Southeast Asian cold-chain expansion into secondary cities is accelerating aluminum and steel can procurement from packaged seafood manufacturers.
- Beverages:Carbonated and still drinks favor two-piece aluminum for lightweight logistics; Kian Joo's Malaysian production lines demonstrate scalable capacity for this segment.
- Ready-to-Eat Meals:Retort-pouch substitution threatens cylindrical cans in premium urban markets, though institutional catering sustains metal packaging for portion control.
- Sauces:Tomato-based and acidic condiments specify tin-free steel with polymer-laminated interiors to prevent metal migration and flavor degradation.
Preserved foods command the largest volume commitment; ready-to-eat meals face the steepest substitution pressure from alternative formats.
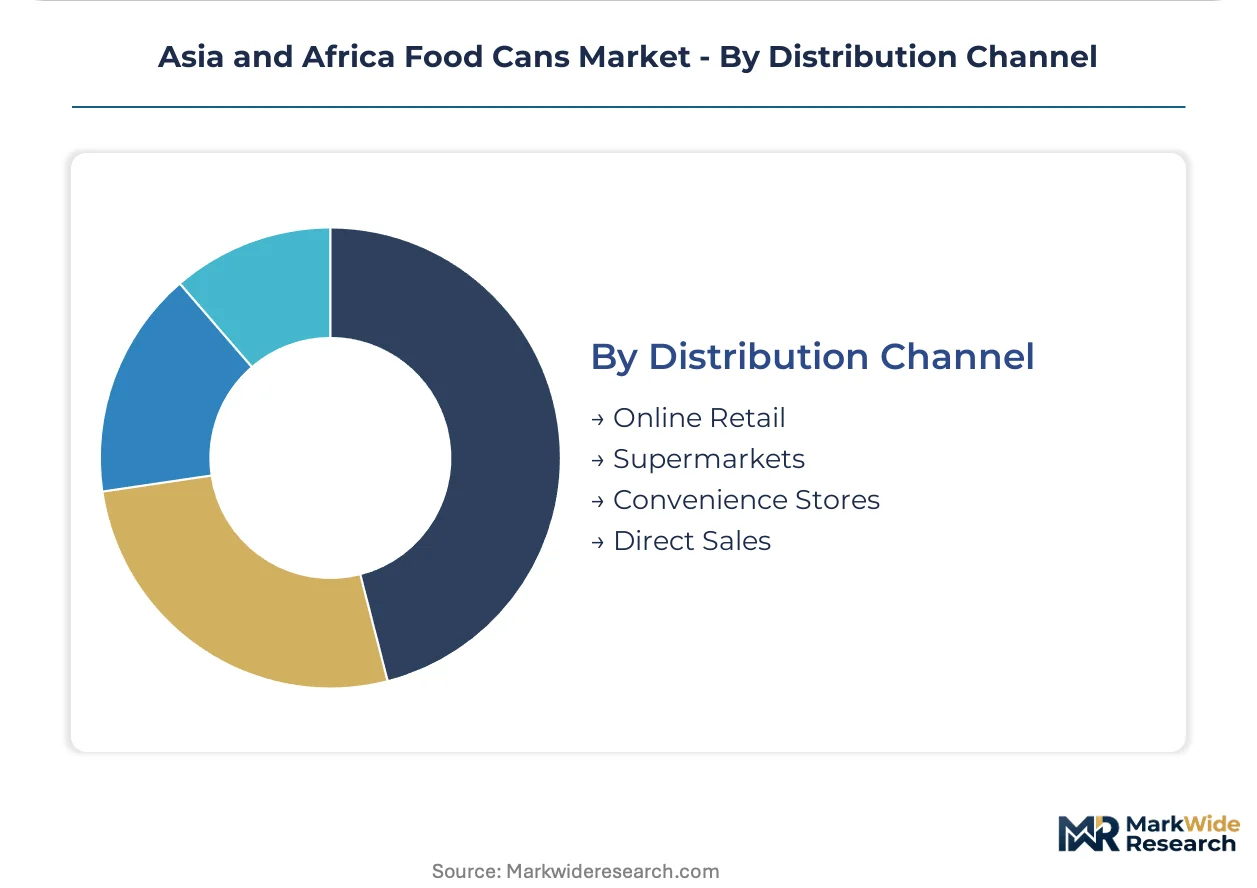
Distribution Channel:
Channel configuration varies with pack size, buyer technical sophistication, and regulatory documentation requirements.
- Direct Sales:High-volume food manufacturers and institutional food service operators source directly from Crown Holdings and Silgan regional operations, securing volume pricing and custom specification.
- Supermarkets:Organized retail in South Africa and India consolidates procurement for standard-size canned goods, driving dimensional standardization pressure.
- Convenience Stores:Small-format retail in Nigerian and Kenyan urban centers stocks single-serve and small-family sizes, favoring lighter-gauge aluminum.
- Online Retail:E-commerce penetration for shelf-stable foods remains limited by shipping cost economics, though bulk institutional procurement platforms are emerging in Indian metropolitan markets.
Direct sales capture the highest-margin contracts; online retail is gaining share fastest in institutional procurement segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Lagos anchors Africa's food can demand through the Lagos-Ibadan manufacturing corridor, where tomato paste and evaporated milk canning lines operate at full capacity. Southeast Asian cold-chain expansion into secondary cities drives aluminum and steel can procurement from packaged seafood manufacturers.
Nigeria
Tomato paste and evaporated milk processors specify three-piece steel cans with interior lacquer coatings optimized for acidic food matrices. The Standards Organisation of Nigeria enforces heavy-metal migration testing and recyclability labeling on metal packaging imports. The Lagos-Ibadan corridor absorbs the majority of regional tinplate coil supply as canning lines run at full capacity.
Kenya
Extended Producer Responsibility mandates accelerate demand for lighter-gauge designs and recycled-content tinplate across Nairobi and Mombasa manufacturing zones. The National Environment Management Authority has tightened EPR rules for metal packaging waste, mandating post-consumer collection infrastructure. Converters in the Nairobi industrial zone are reconfiguring alloy sourcing to meet these compliance timelines.
Malaysia
Beverage can demand concentrates in high-speed two-piece aluminum production corridors serving Southeast Asian processed fruit contracts. Kian Joo Can Factory Berhad dominates this segment with scalable capacity for lightweight logistics and premium shelf presentation. The Klang Valley manufacturing cluster demonstrates how regional coil-coating partnerships sustain cost-competitive output.
India
Bureau of Indian Standards certification requirements for food-contact metal packaging govern can imports and domestic production, creating technical barriers for uncertified Chinese suppliers. Mumbai's food service operators are expanding direct procurement of institutional-size cans for quick-service restaurant chains. Domestic producers meeting BIS requirements capture share from importers facing escalating checkpoint scrutiny.
South Africa
The National Regulator for Compulsory Specifications enforces dimensional and coating standards on steel food containers, fragmenting pan-African production planning against Nigerian standards. Johannesburg's food service operators negotiate volume contracts directly with converters, bypassing traditional distributor markups. Composite cans with reduced metal intensity gain traction among urban packagers of dry goods and powdered beverages.
Asia and Africa Food Cans Market Competitive Environment
The competitive structure tilts toward multinational packaging conglomerates with regional coil-coating partnerships and backward-integrated tinplate sourcing. Three distinct archetypes populate the market: North American and European multinationals leveraging global supply contracts, Southeast Asian specialists with high-speed two-piece aluminum capacity, and regional African converters serving price-sensitive vegetable canning markets. Capacity expansion and strategic partnerships dominate competitive moves as players calibrate regional investments against import substitution timelines.
Among North American-based conglomerates, Silgan Holdings Inc. and Crown Holdings Inc. occupy positions exemplifying the multinational archetype with regional partnership networks. Kian Joo Can Factory Berhad represents the Southeast Asian specialist tier with demonstrated scalable capacity. These named entities serve as anchors for understanding how competitive positioning fragments across material chemistry, geographic coverage, and end-user procurement channel depth.
| Leading Market Players |
|---|
| Silgan Holdings Inc. |
| Nampak Products Ltd |
| Crown Holdings Inc. |
| Asia Can Co. Ltd |
| Kian Joo Can Factory Berhad |
| Toyo Seikan Group Holdings Ltd |
| CPMC Holdings Limited |
| Kaira Can Private Limited |
| Ardagh Group S.A. |
| Others |
Value Chain & Pricing Dynamics
Kenya's National Environment Management Authority EPR mandates for lighter-gauge designs and recycled-content tinplate are forcing converters to absorb alloy cost premiums or pass through to Nigerian tomato paste and evaporated milk processors. This specification pressure concentrates pricing power among coil-coating partners with backward-integrated tinplate sourcing, while independent converters face margin compression.
Pricing Analysis
Twenty-four to sixty-month shelf-life guarantees anchor value-based pricing tiers for corrosion-resistant interior barriers. Three-tier pricing structure across premium polymer-laminated tin-free steel, standard epoxy-phenolic lacquered tinplate, and economy-grade welded-body fabrication reflects certification grade and volume scale differentiation. Cost compression in economy-grade steel cans is intensifying because alloy price volatility feeds directly into heat-processed vegetable packagers in price-sensitive African markets. Nigerian food manufacturers exhibit highest price sensitivity; Malaysian beverage can procurement for premium shelf presentation shows lowest.
Supply Chain Analysis
Dual-sourcing requirements from Crown Holdings and Silgan regional operations mandate multi-supplier qualification for high-volume food manufacturers and institutional food service operators. Coil-coating capacity concentrates in Malaysia, Nigeria, and Kenya, with electrolytic tinplate and tin-free steel coil feeding from regional smelters. Single-source vulnerability persists where Kian Joo's Malaysian high-speed lines dominate Southeast Asian processed fruit contracts. Distribution runs through direct sales for volume accounts, supermarket consolidation in South Africa and India, and convenience store aggregation in Nigerian and Kenyan urban centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market consolidates around converters with captive coil-coating partnerships as Kenya's EPR enforcement and Nigeria's heavy-metal migration testing eliminate uncertified Chinese and Middle Eastern suppliers.
For Market Incumbents: Anchor regional capacity investments in Nairobi and Mombasa manufacturing zones to capture EPR-compliant lighter-gauge demand before enforcement timelines harden. Deepen backward integration into decorated tinplate sourcing to defend against Silgan and Crown's supply concentration leverage. Composite can substitution for dry goods in urban India and South Africa threatens cylindrical tinplate volume; counter with polymer-laminated tin-free steel for twenty-four-month shelf-life segments. For New Entrants and Emerging Players: Polymer-laminated tin-free steel technology offers a technology-first wedge into Southeast Asian processed fruit contracts where corrosion protection and gauge reduction command price premiums. Target institutional-size can procurement in Johannesburg, Mumbai, and Lagos food service operators bypassing traditional distributor markups. Pursue BIS certification arbitrage to displace uncertified imports at Indian checkpoints. For Investors and Strategic Acquirers: The window for entry favors converters with existing coil-coating partnerships and regional EPR compliance infrastructure. Long-term viability hinges on five-to-ten-year positioning against import substitution timelines in Nigeria and Kenya. Watch for Kenya's National Environment Management Authority EPR enforcement acceleration as the signal to gauge pan-African regulatory adoption and capacity rationalization timing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Decorated Tinplate Sourcing | Silgan Holdings anchors Southeast Asian processed fruit contracts through captive coil-coating partnerships. |
| Polymer-Laminated Tin-Free Steel Capacity Expansion | Converters absorb alloy price volatility while maintaining twenty-four to sixty-month shelf-life guarantees. |
| BIS Certification Investment for Indian Market Entry | Domestic producers capture share from uncertified Chinese suppliers facing checkpoint scrutiny. |
| Direct Procurement Channel Development | Food service operators in Johannesburg and Mumbai bypass distributor markups for institutional-size cans. |
| EPR-Compliant Lighter-Gauge Design R&D | Kenya's National Environment Management Authority mandates accelerate recycled-content tinplate demand. |
Study Parameters
Multi-period observation of alloy price volatility, EPR enforcement timelines, and cold-chain infrastructure rollout anchored the trend analysis, supplemented by interviews with converter plant managers, procurement leads at Nigerian tomato paste processors, Kenyan National Environment Management Authority compliance officers, and Southeast Asian seafood packaging executives. Secondary validation drew from customs and trade data, SEC 10-K filings of multinational packaging conglomerates, Bureau of Indian Standards certification registries, and Standards Organisation of Nigeria technical barrier documentation. Bottom-up capacity installation tracking and top-down demand segmentation triangulated volume estimates.
Input-output matrices modeled electrolytic tinplate and aluminum alloy feedstock flows against end-user procurement patterns across material chemistry, product type, and distribution channel dimensions. CAGRs were derived from segmented growth rate aggregation across the projection horizon. Forecast inputs included coil-coating partnership expansion timelines, Kenya EPR enforcement acceleration scenarios, and Nigerian Lagos-Ibadan corridor capacity utilization rates.
Several conditions sit outside the modeled scope, including abrupt alloy smelting cost shocks, pan-African customs union dimensional standardization harmonization, and retort-pouch substitution acceleration in premium ready-to-eat meal segments. Deviation in Kenya's National Environment Management Authority EPR enforcement intensity would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Containers
Slip Lid Can Market
Containers
Lab Storage Container Market
Containers
HDPE Blow Molding and Injection Molding Containers Market
Containers
Container Market
Containers
Foam Containers Market
Containers
Slotted Containers Market
Containers
In-Mold Labelled Containers Market
Containers
Sandwich Containers Market
Containers
Compartment Trays Market
Containers
Acrylic Container Market
Containers
Pail Lids Market
Containers
Collapsible Food Packaging Containers Market
Containers
Foldable Large Containers Market
Containers
Lever Lid Tinplate Containers Market
Containers
PVC Container Market
Containers
Thin Wall Plastic Containers Market