
 Global Food Containers Market | 2026-2036
Global Food Containers Market Size, Share, and Industry Trends Forecast 2026-2036
Global Food Containers Market Analysis
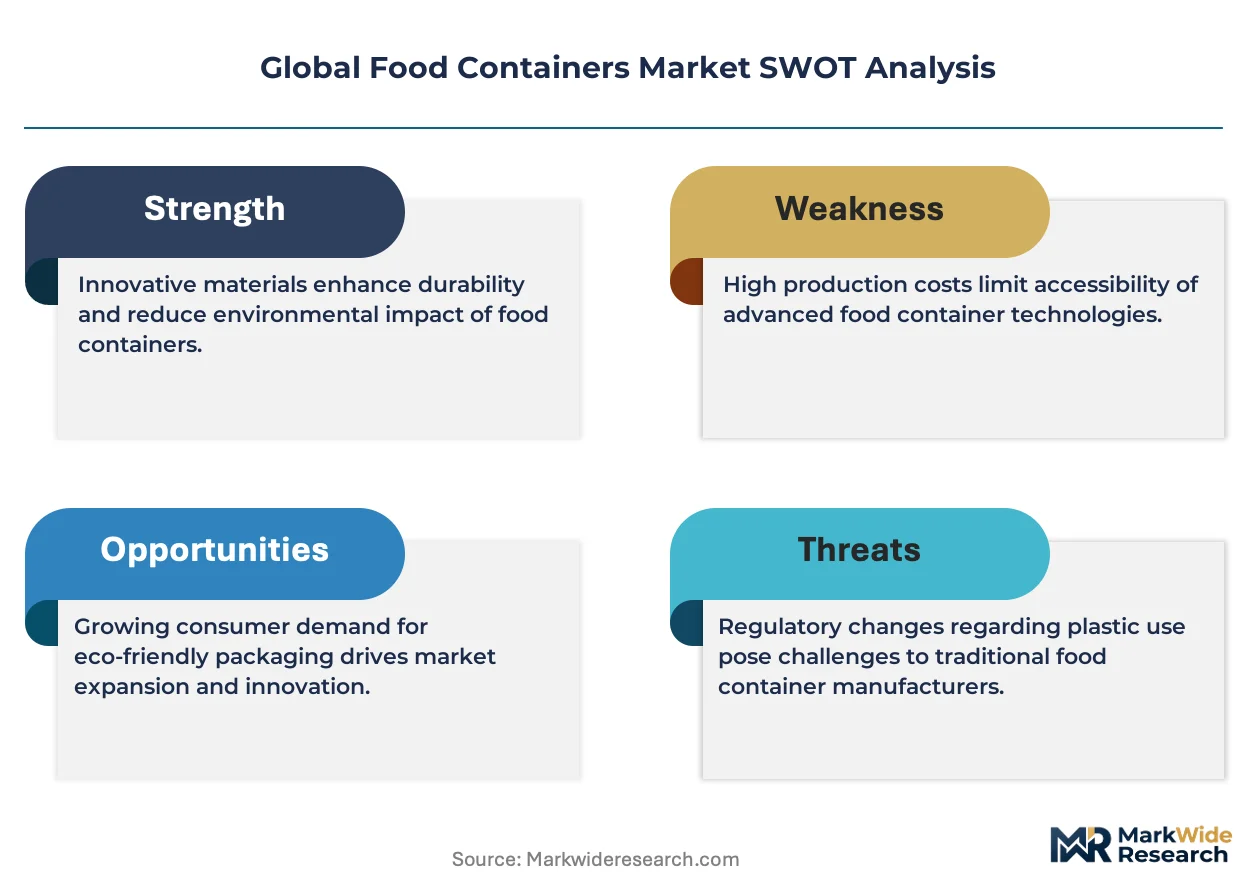
ISO 22000 certification is rotating as the primary gating standard for suppliers seeking entry into branded food supply chains. Huhtamaki leverages its fiber-based packaging R&D to sustain leadership in European quick-service restaurant channels. Amcor anchors its position through backward integration into recycled resin production, controlling feedstock quality for circular packaging lines. Berry Global competes aggressively in North American thermoformed containers, extending its footprint via proprietary multi-layer barrier technologies.
Food containers are engineered vessels manufactured from plastic resins, glass, metal alloys, or biodegradable polymers, designed to preserve organoleptic properties and prevent microbial contamination across distribution temperatures from frozen storage to hot-fill applications. Their commercial purpose centers on extending product shelf stability while enabling brand differentiation through printable surfaces and stackable geometries. Plastic containers dominate volume due to cost scalability, though biodegradable materials are capturing margin pools as regulatory bans on conventional polymers expand across OECD markets. Vacuum-sealed types are leading growth in protein and prepared meal segments where oxygen exclusion directly correlates with retail pricing power. Food retailers represent the most concentrated end-user channel, with households fragmenting across numerous private-label and direct-to-consumer brands.
The FDA governs food-contact substance notifications in the United States, while the EU's EFSA and REACH frameworks restrict specific monomer migrations and mandate extended producer responsibility for packaging waste. China's SAMR enforces GB standards for composite materials, creating divergent compliance burdens for multinational suppliers operating across these jurisdictions. Forward-looking stakeholders must monitor how evolving extended producer responsibility schemes reshape material economics and determine whether regional recycling infrastructure investments justify localized production commitments.
Market Dynamics
The EU's Single-Use Plastics Directive is compressing virgin polymer demand while redirecting capital toward bio-based feedstock infrastructure across OECD manufacturing clusters.
Growth Catalysts
- Extended Producer Responsibility schemes:France's AGEC law and Germany's Verpackungsgesetz mandate recycled content quotas, pulling investment into chemical recycling capacity for food-grade polypropylene.
- Vacuum-sealed barrier formats:Protein processors in Brazil and Australia are converting tray lines to multi-layer EVOH structures to capture retail premium tiers in fresh meat distribution.
- Urban food delivery density:Metro corridors in China and India generate container throughput volumes that justify localized thermoforming investments with sub-48-hour replenishment cycles.
Market Restraints
- Recycled resin quality variance:FDA food-contact notifications for post-consumer rPET remain batch-specific, constraining scale economics for circular packaging lines serving US retail.
- Biopolymer feedstock concentration:PLA resin supply concentrates among three Thai and US producers, exposing converters to agricultural commodity price swings in corn and sugarcane markets.
- Multi-layer incompatibility with mechanical recycling:Current sortation infrastructure cannot separate EVOH barrier layers from polyolefin substrates, diverting high-performance containers to landfill or energy recovery.
Strategic Opportunities
- Indonesia organized retail expansion:Hypermarket and e-grocery penetration in Jakarta and Surabaya remains below 15 percent, creating first-mover positioning for cold-chain compatible container formats.
- Mono-material barrier innovation:Convergence of high-density polyethylene with advanced nucleating agents enables oxygen transmission rates approaching multi-layer performance without sortation penalties.
- Deposit-return scheme alignment:Italy's CONAI eco-modulation incentives reward lightweighting and recycled content, rewarding suppliers who pre-certify compliance across regional waste management consortia.
Industry Challenges
- ISO 22000 audit bandwidth:Third-party certification bodies face 12-16 week queue times for HACCP-aligned facility assessments, delaying supplier qualification for branded food manufacturing contracts.
- Legacy thermoform tooling retrofit costs:Converting aluminum molds for bio-based polymer shrinkage rates requires capital outlays that mid-tier converters cannot amortize across short production runs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Food Containers Market |
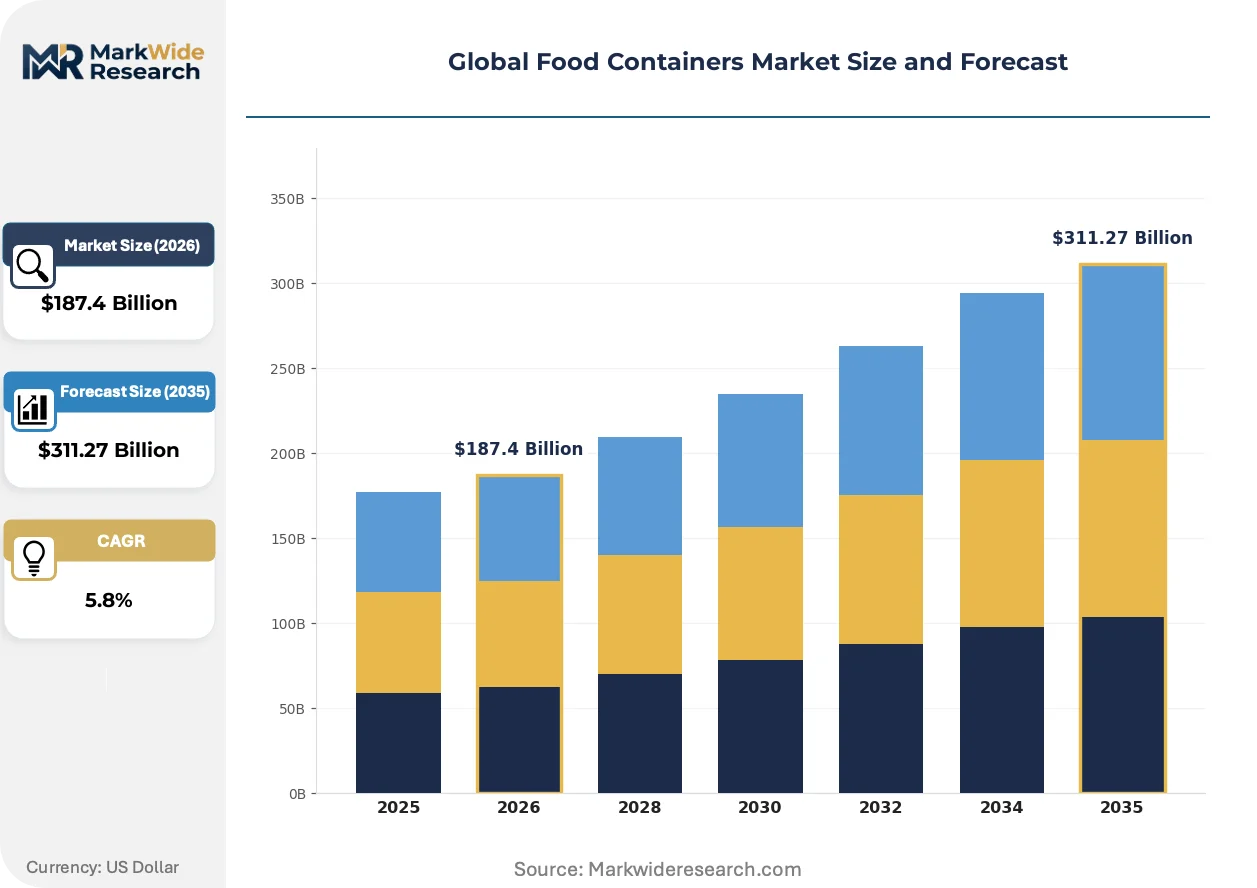
| Market Size in 2026 | $187.4 Billion |
| Market Size in 2035 | $311.27 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material: Plastic, Glass, Metal, Biodegradable Type: Reusable, Disposable, Vacuum-Sealed, Airtight End User: Restaurants, Households, Catering Services, Food Retailers Size: Small, Medium, Large, Extra Large |
| Companies Covered | Huhtamaki, Silgan, Amcor, Crown Holdings, Ardagh Group, Berry Global, ALPLA, Tetra Pak, Sealed Air Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Food Containers Market Emerging Trajectories
Active and intelligent packaging systems are migrating from pharmaceutical cold chain into mainstream food logistics, embedding time-temperature indicators and freshness sensors directly into container substrates.
Fiber-based molded pulp with spray-applied barrier coatings is displacing expanded polystyrene in prepared meal distribution. European quick-service restaurant chains are converting clamshell specifications at a pace that has absorbed 18 months of molded pulp capacity expansion. The displacement compresses profit pools for conventional foam converters while opening margin capture for chemical barrier applicators.
REACH restrictions on per- and polyfluoroalkyl substances (PFAS) in food contact materials entered enforcement phases across Denmark, Germany, and the Netherlands during 2023-2024. Industrial consequence includes accelerated R&D spending on silicone-based and bio-wax alternative coatings for grease resistance in bakery and fried food applications. Paperboard container manufacturers serving Nordic markets have reformulated 60-70 percent of SKU portfolios to maintain shelf presence.
Centralized procurement by foodservice aggregators is compressing supplier rosters and extending contract durations from annual to multi-year frameworks. Large European catering contractors now mandate carbon footprint disclosure at the SKU level, replacing spot-buying with lifecycle-assessment-linked supplier scorecards. The shift is most visible in German and French institutional foodservice channels where municipal tender requirements embed packaging sustainability criteria.
Global Food Containers Market Segmentation
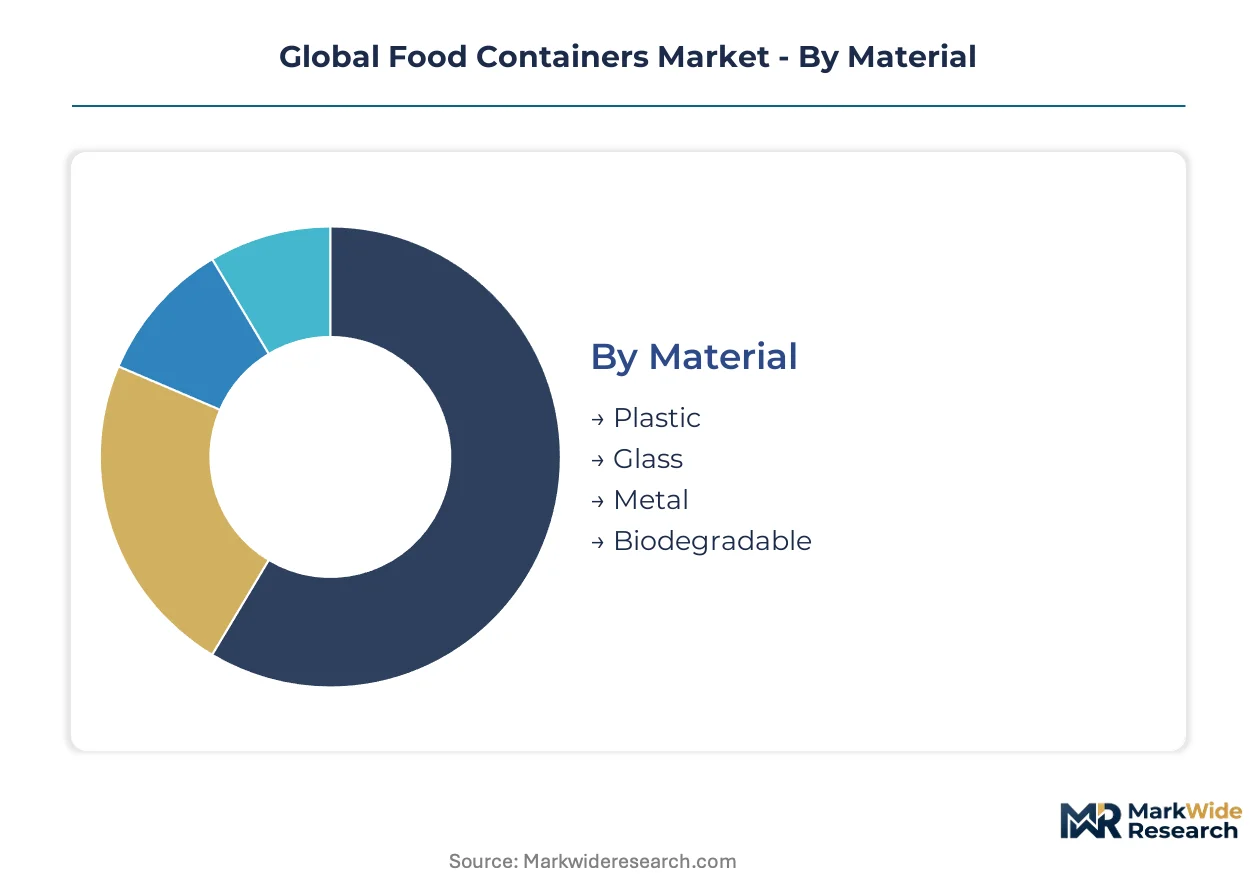
Segmentation in food containers determines material compliance pathways and capital allocation for converters navigating divergent regulatory regimes. Container specifications vary sharply across temperature requirements, barrier needs, and end-user consolidation levels.
Material:
Substitution pressure intensifies most acutely against petroleum-derived polymers as EFSA and FDA notification pathways for bio-based alternatives mature.
- Plastic:Polypropylene and polyethylene terephthalate formulations dominate thermoformed trays and clamshells through cost scalability and hot-fill compatibility. Demand concentrates in Chinese quick-service restaurant supply chains where centralized procurement favors standardized polymer specifications.
- Biodegradable:Polylactic acid and polyhydroxyalkanoate resins serve Nordic retail channels facing AGEC law mandates and extended producer responsibility tariffs on conventional plastics. German supermarket chains now require biodegradable alternatives for private-label prepared meals.
- Glass:Borosilicate and soda-lime compositions retain premium positioning in infant food and artisanal preserves where inertness justifies weight penalties.
- Metal:Tinplate and aluminum alloys anchor shelf-stable protein and beverage segments through absolute oxygen barrier performance.
Plastic anchors the volume base while biodegradable gains share at the steepest rate.
Type:
Cost tier stratification separates capital-intensive barrier technologies from commodity disposables in procurement negotiations.
- Vacuum-Sealed:Multi-layer ethylene vinyl alcohol structures with oxygen transmission rates below 0.5 cc/m²/day command retail premium tiers in Brazilian and Australian fresh meat distribution. Protein processors convert tray lines to capture extended case-ready shelf life.
- Airtight:Silicone-gasketed locking mechanisms in polypropylene bodies serve meal-prep subscription services in US coastal metros where weekly delivery cycles demand refrigerator-grade sealing.
- Reusable:Glass and stainless-steel formats with dishwasher-safe ratings penetrate household segments in German and French municipalities with deposit-return infrastructure.
- Disposable:Single-use fiber-based molded pulp displaces expanded polystyrene in European quick-service restaurant channels under REACH restrictions.
Disposable retains the widest shipment volumes while vacuum-sealed climbs fastest on protein processor conversion.
End User:
Customer type concentration determines contract duration and carbon disclosure requirements in procurement frameworks.
- Food Retailers:Supermarket and hypermarket chains in Indonesia and India drive cold-chain compatible format specification through organized retail expansion below 15 percent penetration.
- Restaurants:Quick-service and casual dining operators in China and India generate container throughput justifying localized thermoforming with sub-48-hour replenishment.
- Catering Services:Institutional contractors in Germany and France mandate lifecycle assessment scorecards and multi-year supplier frameworks replacing spot-buying.
- Households:Fragmented demand across private-label and direct-to-consumer brands in US and European e-commerce channels.
Food retailers anchor procurement scale while catering services impose the steepest sustainability compliance escalation.
Size:
Volume-to-surface ratio economics favor larger formats in logistics-intensive channels while portion-control trends sustain small-container demand.
- Large:2-5 liter polyethylene terephthalate and polypropylene containers serve foodservice bulk ingredient storage and institutional catering batch preparation.
- Medium:500ml-2 liter formats dominate retail-ready prepared meals and family-size dairy in European and North American supermarket channels.
- Small:Sub-500ml portions align with single-serve snacking and airline catering specifications in Asia-Pacific travel corridors.
- Extra Large:Above-5 liter industrial totes and intermediate bulk containers serve ingredient supply to commercial kitchens and central commissaries.
Medium sizes command the broadest application base while large formats expand most quickly on foodservice aggregation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Extended producer responsibility schemes across OECD jurisdictions are redirecting capital toward localized thermoforming capacity. France's AGEC law and Germany's Verpackungsgesetz mandate recycled content quotas, pulling investment into chemical recycling infrastructure. Container demand concentrates in urban corridors where food delivery density justifies sub-48-hour replenishment cycles.
United States
Quick-service restaurant supply chains and meal-prep subscription services drive polypropylene container specifications. FDA food-contact notifications for post-consumer rPET remain batch-specific, constraining circular packaging scale economics. Chicago and Dallas-Fort Worth industrial clusters host thermoforming operations serving national foodservice distribution networks.
China
Urban food delivery density in metro corridors generates container throughput justifying localized manufacturing investments. SAMR enforces GB standards for composite materials, creating compliance burdens for multinational suppliers. Yangtze River Delta manufacturing bases supply quick-service restaurant chains with standardized polymer specifications.
Germany
Institutional catering contractors mandate lifecycle assessment scorecards and multi-year supplier frameworks. Verpackungsgesetz recycled content quotas pull investment into chemical recycling capacity for food-grade polypropylene. Bavaria and North Rhine-Westphalia host converters serving supermarket private-label prepared meal segments.
India
Organized retail penetration below 15 percent in hypermarket and e-grocery channels creates first-mover positioning for cold-chain compatible formats. FSSAI standards govern food-contact material safety, with BIS certification requirements expanding. Mumbai and Delhi-NCR logistics corridors justify thermoforming investments with rapid replenishment cycles.
Brazil
Protein processors convert tray lines to multi-layer barrier structures to capture retail premium tiers in fresh meat distribution. ANVISA regulates food-contact substance migrations for plastic and biodegradable polymers. São Paulo industrial clusters anchor thermoforming capacity serving Mercosur protein export channels.
Global Food Containers Market Vendor Landscape
Player mix skews toward diversified packaging conglomerates with backward integration into resin production. The vendor base concentrates among firms with captive recycling infrastructure and multi-jurisdictional compliance capabilities. Three archetypes dominate: fiber-based molded pulp specialists, multi-layer barrier technology providers, and circular economy platform operators. Competitive moves center on chemical recycling capacity acquisitions and mono-material barrier R&D partnerships.
Within the diversified conglomerate tier, Huhtamaki anchors European quick-service restaurant channel positioning through fiber-based packaging capabilities. Amcor exemplifies backward integration strategy through recycled resin production controlling feedstock quality. Berry Global occupies a position in North American thermoformed containers through proprietary barrier technology deployment.
| Leading Market Players |
|---|
| Huhtamaki |
| Silgan |
| Amcor |
| Crown Holdings |
| Ardagh Group |
| Berry Global |
| ALPLA |
| Tetra Pak |
| Sealed Air Corporation |
| Others |
Supply Flow & Price Mechanics
Long-term offtake contracts between resin producers and thermoforming converters lock in both supply access and price visibility across volatile agricultural feedstock markets. These agreements insulate converters from spot-price swings in polylactic acid and polypropylene while committing volume to specialized barrier film lines serving branded food manufacturers.
Pricing Analysis
Certification level creates the primary spread between container tiers, with ISO 22000-certified facilities commanding 15-25 percent premiums over uncertified competitors in European quick-service restaurant procurement. Three-tier pricing structure across premium, standard, and economy levels segments by barrier performance, with multi-layer EVOH structures at the top and commodity polypropylene at the base. Cost compression in standard-tier thermoformed trays is intensifying because recycled resin quality variance forces batch-specific FDA notifications. Quick-service restaurant chains exhibit the highest price sensitivity due to centralized procurement and volume scale, while infant food manufacturers prioritize certification over unit cost.
Supply Chain Analysis
Thailand and the United States anchor polylactic acid resin production, while China, Germany, and India concentrate thermoforming capacity for regional foodservice distribution. Container manufacturing draws from corn and sugarcane agricultural commodities, petroleum-derived polyolefins, and post-consumer recycled flake. Single-source vulnerability concentrates in PLA feedstock where three producers control global supply. Distribution runs through foodservice distribution centers and direct-to-manufacturer logistics networks with sub-48-hour replenishment cycles in dense urban corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU's Single-Use Plastics Directive and REACH PFAS restrictions constitute a regulatory inflection accelerating material substitution and reshaping competitive economics across OECD markets.
For Market Incumbents: Secure chemical recycling capacity for food-grade polypropylene to meet Germany's Verpackungsgesetz recycled content quotas. Anchor backward integration into rPET production to control feedstock quality variance threatening circular packaging scale economics. Defend against mono-material barrier innovators by accelerating R&D partnerships with nucleating agent suppliers. For New Entrants and Emerging Players: ISO 22000 fast-track certification programs open qualification pathways for Indonesian cold-chain container demand where organized retail penetration remains below 15 percent. Target Jakarta and Surabaya hypermarket private-label specifications with localized thermoforming investments. Pursue deposit-return scheme alignment with Italy's CONAI eco-modulation incentives as the primary go-to-market angle. For Investors and Strategic Acquirers: Fiber-based molded pulp specialists with spray-applied barrier coating capabilities represent the priority acquisition archetype as European quick-service restaurant chains displace expanded polystyrene. Long-term viability hinges on substitution permanence rather than regulatory arbitrage. Watch mono-material barrier performance benchmarks as the inflection signal determining whether multi-layer incumbents retain pricing power.| Strategic Initiative | Industry Significance |
|---|---|
| Chemical Recycling Capacity Expansion | Secures food-grade polypropylene supply under Germany's Verpackungsgesetz recycled content mandates. |
| Mono-Material Barrier R&D Partnership | Enables EVOH-comparable oxygen transmission without sortation penalties in mechanical recycling streams. |
| ISO 22000 Certification Fast-Track | Reduces 12-16 week audit queue times blocking supplier qualification for branded food manufacturing contracts. |
| Localized Thermoforming Investment | Captures sub-48-hour replenishment cycles in Chinese and Indian urban food delivery corridors. |
| Deposit-Return Scheme Alignment | Unlocks Italy's CONAI eco-modulation incentives rewarding lightweighting and recycled content pre-certification. |
Methodological Framework
Desk research of customs trade databases, FDA food-contact substance notifications, and EFSA scientific opinions preceded structured interviews with thermoforming plant managers, quick-service restaurant procurement directors, resin supplier technical R&D leads, and supermarket private-label category buyers. Primary fieldwork combined with secondary validation from SEC filings of diversified packaging conglomerates and BIS certification records. Bottom-up shipment data triangulated against top-down resin consumption estimates.
Variance decomposition separates volume growth from price mix effects across the projection horizon. Segmentation dimensions modeled include material type, barrier technology tier, end-user concentration level, and regional regulatory framework cluster. CAGRs derive from curve-fitting historical shipment trajectories against elasticity-adjusted demand drivers. Forecast inputs incorporate extended producer responsibility tariff schedules and urban food delivery density indices.
Underlying assumptions cover sustained enforcement of EU Single-Use Plastics Directive timelines and stable agricultural commodity pricing for PLA feedstocks, with deviation risk concentrated in FDA batch-specific notification backlogs and mechanical recycling infrastructure deployment rates. Recalibration cycles align with material shifts in PFAS restriction enforcement phases and chemical recycling capacity commissioning.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Containers
Stainless Steel Cask Market
Containers
PET Containers Market
Containers
Compartment Take-Out Container Market
Containers
Takeout Containers Market
Containers
Thermoformed Containers Market
Containers
Die Cut Display Container Market
Containers
Hinged Lid Tins Market
Containers
Grab and Go Containers Market
Containers
Water Resistant Packing Cubes Market
Containers
Spout Containers Market
Containers
Single Wall Jars Market
Containers
HDPE Blow Molding and Injection Molding Containers Market
Containers
Dual-Ovenable Trays and Containers Market
Containers
Laminated Bulk Bins Market
Containers
PVC Container Market
Containers
Cylindrical Cans Market