
 Slotted Containers Market | 2026-2036
Slotted Containers Market Size, Share, and Industry Trends Forecast 2026-2036
Slotted Containers Market Outlook
Aftermarket service revenue for container fleet management is narrowing as manufacturers shift toward direct packaging-as-a-service models. International Paper leverages its North American containerboard network to sustain mill-direct supply relationships with major distributors. WestRock Company anchors its position through integrated corrugated operations that control fiber sourcing through finished box production.
Slotted containers are corrugated or solid fiberboard boxes engineered with precision-cut slots to enable interlocking assembly without adhesive, typically manufactured through die-cutting and flexo-printing processes to achieve exact slot tolerances for automated erecting equipment. Their primary purpose is to provide protective, stackable, and returnable packaging for parts distribution and retail fulfillment. Cardboard variants dominate unit volume due to cost efficiency in single-trip applications, while plastic slotted containers represent the fastest-growing material category as closed-loop logistics networks expand in automotive and electronics supply chains. Custom size configurations command premium positioning as manufacturers seek exact-fit solutions that minimize void fill and dimensional weight charges.
The EPA's sustainable materials management priorities and OSHA's ergonomic handling standards shape slotted container specifications in the United States, while the EU Packaging and Packaging Waste Regulation mandates recyclability thresholds that favor mono-material corrugated designs over composite alternatives. Stakeholders must monitor evolving extended producer responsibility frameworks that will determine whether slotted container economics favor disposable or returnable formats in key distribution corridors.
Market Dynamics
The EU Packaging and Packaging Waste Regulation is compressing design cycles for slotted container manufacturers, forcing rapid material substitution toward mono-material corrugated formats that satisfy recyclability thresholds without sacrificing automated erecting compatibility.
Growth Catalysts
- E-commerce fulfillment automation:Amazon and Shopify merchants are standardizing on slotted containers for robotic sortation systems, driving precision tolerances that favor die-cut corrugated over taped alternatives.
- REACH compliance migration:European automotive suppliers are replacing composite returnable packaging with mono-material corrugated slotted containers to satisfy material recovery mandates ahead of 2030 targets.
- Closed-loop logistics expansion:Electronics manufacturers in Taiwan and South Korea are deploying RFID-tracked plastic slotted containers for component distribution, cutting per-trip packaging costs through reuse cycles.
Market Restraints
- OCC price volatility:Old corrugated container feedstock costs swing with Chinese import policy shifts, compressing margins for independent converters lacking captive fiber supply.
- German supplier concentration:Four integrated containerboard producers control 70% of European kraftliner capacity, creating bottleneck risk for slotted container manufacturers dependent on regional substrate supply.
- Plastic substitution ceiling:Polypropylene slotted containers face performance limitations below -20°C, restricting adoption in cold-chain pharmaceutical distribution networks.
Strategic Opportunities
- Indian automotive cluster penetration:Maruti Suzuki and Tata Motors suppliers in Pune and Chennai are converting from wooden crates to returnable slotted containers, creating first-mover advantage for localized production.
- Packaging-as-a-service models:Fleet management platforms that bundle container provision with reverse logistics are displacing capital purchase arrangements in German automotive tier-one supply chains.
- CSRD reporting integration:EU corporate sustainability disclosure requirements are creating premium positioning for slotted container suppliers offering verified carbon footprint data per shipment.
Industry Challenges
- Die-cutting precision talent scarcity:Skilled technicians capable of maintaining ±0.5mm slot tolerances for automated erecting equipment are concentrated in aging workforces across Midwest US and Rhineland manufacturing regions.
- Legacy ERP integration friction:Container fleet tracking systems require API connectivity with customer warehouse management platforms, forcing mid-size manufacturers into expensive system overhauls.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Slotted Containers Market |
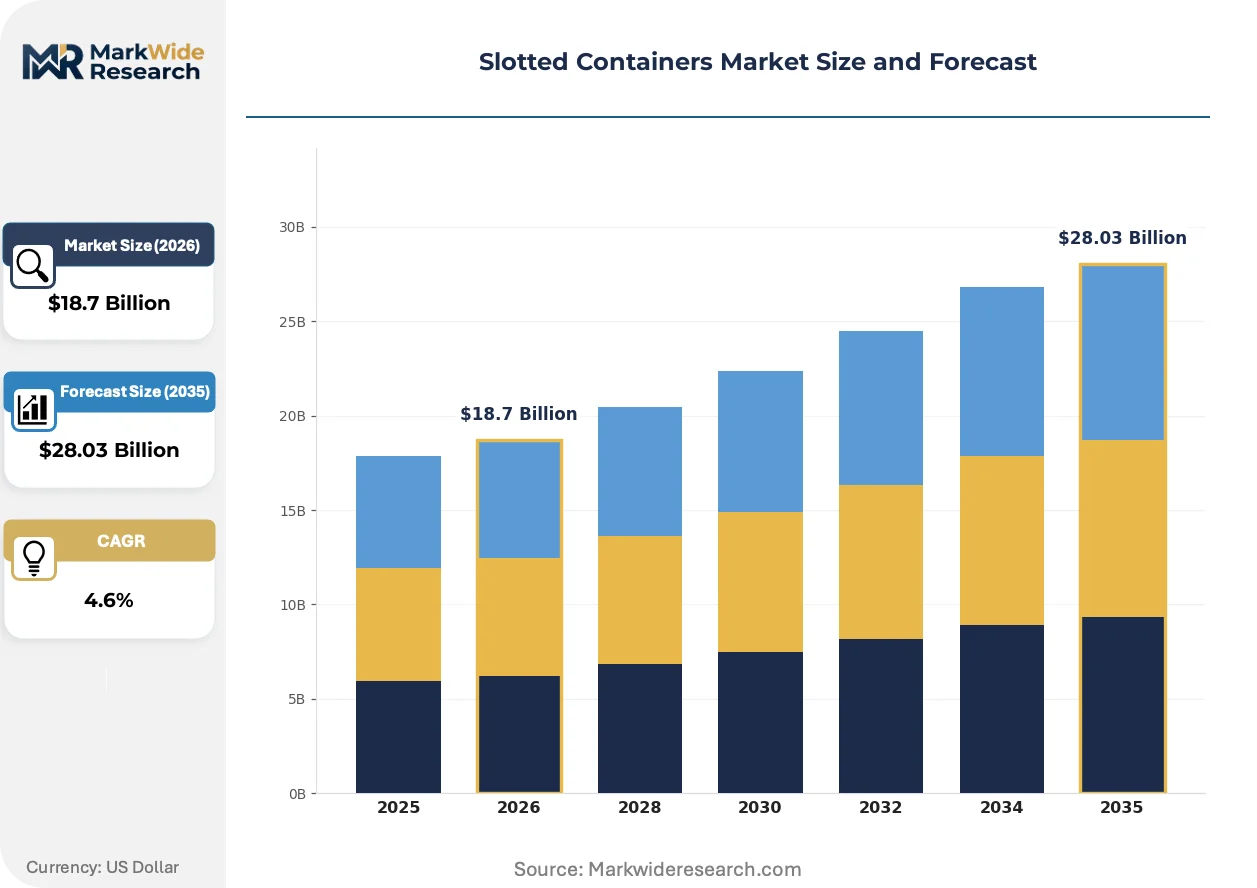
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $28.03 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cardboard, Plastic, Metal, Wood Application: Retail Packaging, Industrial Shipping, Food Storage, Electronics End User: Manufacturers, Wholesalers, Retailers, Distributors Size: Small, Medium, Large, Custom |
| Companies Covered | International Paper, WestRock Company, Smurfit Kappa Group, Mondi Group, Packaging Corporation of America, DS Smith Plc, Green Bay Packaging, Packsize International, Oji Holdings Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Slotted Containers Market Strategic Shifts
Automation compatibility requirements and regulatory material mandates are converging to reshape slotted container engineering priorities, with manufacturers racing to satisfy precision tolerances while eliminating adhesive-dependent assembly.
Fluted polypropylene hybrid corrugated is hybridizing protective performance with lightweight returnability. Tier-one electronics distributors in Taiwan are adopting this substrate for semiconductor component packaging. The technology is hybridizing the cost structure of single-trip cardboard with the durability economics of closed-loop plastic systems.
The EU Packaging and Packaging Waste Regulation mandates 70% material recovery rates by 2030, forcing elimination of multi-material laminates. German automotive suppliers are accelerating mono-material corrugated adoption to preempt compliance penalties. Slotted container designers are responding with slot-and-tab geometries that maintain structural integrity without polyethylene moisture barriers.
Direct procurement from integrated containerboard producers is consolidating buyer power among the largest e-commerce fulfillment operators. Third-party logistics providers in the Netherlands and Belgium are losing intermediation margin as Amazon and Zalando establish mill-direct supply relationships. This pattern is most visible in the Benelux corridor, where port-proximate containerboard mills enable just-in-time delivery to automated distribution centers.
Slotted Containers Market Segmentation
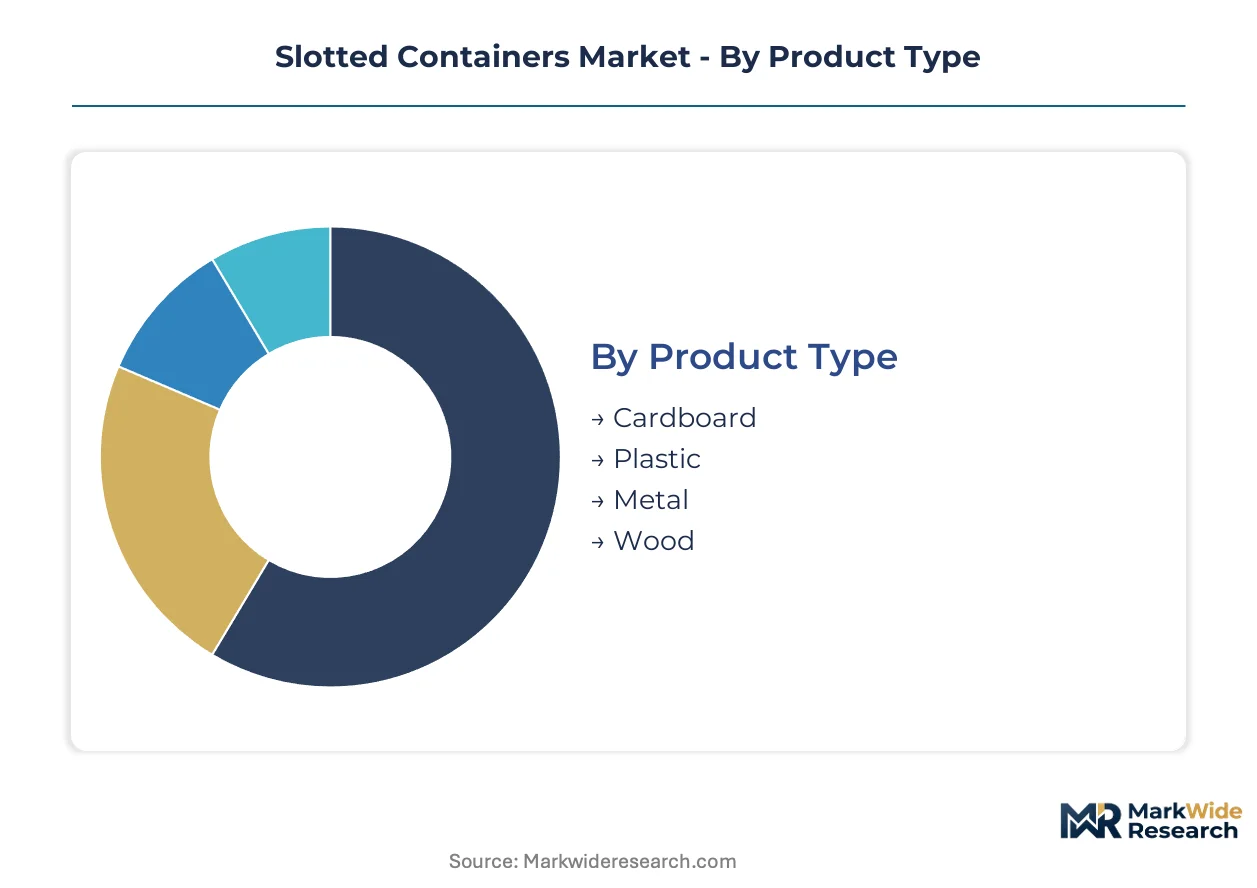
Slotted container segmentation reveals divergent engineering priorities across material grades and fulfillment contexts. Procurement patterns in automotive supply chains differ sharply from e-commerce sortation requirements, forcing manufacturers to specialize across incompatible specification clusters.
Product Type:
Use-case spectrum spans single-trip disposable formats through thousand-cycle returnable systems, with material selection governed by trip economics and automated handling compatibility.
- Cardboard:Die-cut corrugated fiberboard dominates unit volume through cost efficiency in single-trip retail and industrial applications. Amazon fulfillment centers in the United States and Germany standardize on this format for robotic sortation systems requiring precise slot tolerances.
- Plastic:Polypropylene and fluted polypropylene hybrid variants enable closed-loop reuse programs. Electronics manufacturers in Taiwan and South Korea deploy RFID-tracked plastic slotted containers for semiconductor component distribution, cutting per-trip packaging costs through multi-cycle deployment.
- Metal:Steel and aluminum slotted containers serve heavy industrial applications requiring extreme durability. Automotive powertrain suppliers in Germany utilize metal formats for engine block transport where load ratings exceed corrugated capacity.
- Wood:Plywood and engineered timber slotted crates persist in machinery and agricultural equipment shipping. Indian automotive suppliers in Pune are converting from wooden crates to returnable alternatives, though wood retains share in capital goods export packaging.
The dominant share belongs to Cardboard, while Plastic is closing the gap fastest through closed-loop logistics expansion.
Application:
Cost tier stratification separates premium precision formats from commodity shipping boxes, with specification density correlating directly to automation integration levels.
- Retail Packaging:Shelf-ready slotted containers require retail-compliant printing and tear-away display features. European cosmetics and consumer electronics brands specify mono-material corrugated designs to satisfy EU Packaging and Packaging Waste Regulation recyclability mandates.
- Industrial Shipping:Heavy-duty corrugated and plastic formats protect components through multi-modal transport. German automotive tier-one suppliers utilize standardized returnable slotted containers for just-in-sequence parts delivery to assembly plants.
- Food Storage:Moisture-resistant coatings and FDA-compliant materials dominate this segment. US cold-chain distributors specify polyethylene-barrier corrugated for produce distribution, though polypropylene slotted containers face performance limitations below -20°C.
- Electronics:Electrostatic discharge protection and precision fitment drive specification density. Taiwanese semiconductor distributors adopt fluted polypropylene hybrid corrugated to balance protective performance with lightweight returnability.
Industrial Shipping commands the largest revenue base, though Electronics is gaining share fastest through semiconductor supply chain expansion.
End User:
Customer type determines procurement modality, with fleet ownership preferences diverging sharply between capital purchase and packaging-as-a-service arrangements.
- Manufacturers:Automotive and electronics producers specify exact-fit slotted containers to minimize void fill and dimensional weight charges. German OEMs are shifting from capital purchase to fleet management platforms that bundle container provision with reverse logistics.
- Wholesalers:Volume-driven procurement emphasizes interchangeability across supplier bases. Benelux third-party logistics providers face margin compression as Amazon and Zalando establish mill-direct supply relationships with integrated containerboard producers.
- Retailers:E-commerce fulfillment operators drive precision tolerance requirements for automated erecting equipment. Shopify merchants standardize on slotted containers compatible with robotic sortation systems.
- Distributors:Independent parts distributors balance inventory flexibility with standardization pressures. Midwest US distributors rely on captive fiber supply relationships to buffer OCC price volatility.
Manufacturers represent the deepest specification engagement, while Retailers are expanding procurement volume most aggressively.
Size:
Volume concentration favors standard modular formats, though premium positioning accrues to exact-fit custom configurations that eliminate dunnage requirements.
- Small:Compact slotted containers serve electronics components, pharmaceuticals, and cosmetics. REACH compliance migration is driving European automotive suppliers toward mono-material corrugated formats in this size range.
- Medium:Mid-size formats balance handling ergonomics with cubic efficiency. OSHA ergonomic handling standards in the United States shape maximum weight specifications for manual handling scenarios.
- Large:Bulk container formats require reinforced slot geometries for heavy loads. German automotive suppliers utilize large slotted containers for bumper and fascia transport.
- Custom:Engineered-to-order formats command premium positioning through dimensional optimization. Custom size configurations minimize void fill and dimensional weight charges for high-velocity e-commerce SKUs.
Medium sizes anchor volume demand, while Custom formats are expanding revenue contribution fastest through exact-fit engineering services.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Integrated containerboard mills cluster in Germany, the United States, and China, creating supply bottlenecks that slotted container converters must navigate through captive fiber relationships or strategic inventory positioning.
United States
Amazon fulfillment centers drive precision tolerance requirements for robotic sortation systems. OSHA ergonomic handling standards shape maximum weight specifications for manual handling scenarios. Midwest distributors in Illinois and Ohio rely on captive fiber supply relationships to buffer OCC price volatility.
Germany
Automotive tier-one suppliers utilize standardized returnable slotted containers for just-in-sequence parts delivery to assembly plants. EU Packaging and Packaging Waste Regulation mandates 70% material recovery rates by 2030, forcing mono-material corrugated adoption. Rhineland manufacturing regions face die-cutting precision talent scarcity as aging workforces shrink.
China
E-commerce fulfillment automation expands rapidly through Alibaba and JD.com logistics networks. GB standards and MIIT regulations govern packaging material specifications for domestic distribution. Yangtze River Delta converters serve electronics manufacturers with high-volume corrugated output.
India
Maruti Suzuki and Tata Motors suppliers in Pune and Chennai convert from wooden crates to returnable slotted containers. BIS standards establish corrugated board quality benchmarks for industrial packaging. Maharashtra automotive clusters create first-mover advantage for localized production.
Japan
Electronics manufacturers deploy RFID-tracked plastic slotted containers for semiconductor component distribution. METI promotes circular economy frameworks that favor closed-loop packaging systems. Kanto region precision engineering capabilities support automated erecting equipment compatibility.
Slotted Containers Market Competitive Environment
Integrated containerboard producers and independent converters split the market along fiber access lines. Four German producers control 70% of European kraftliner capacity, while North American networks concentrate around mill-direct relationships. Two archetypes dominate: integrated paperboard multinationals with captive pulp supply, and regional converters competing through customization velocity. Competitive moves center on backward integration into containerboard production and packaging-as-a-service fleet management platforms.
Among North American integrated producers, International Paper and WestRock Company exemplify the fiber-captive archetype through mill-direct supply relationships. Smurfit Kappa Group occupies a position representing European consolidation dynamics, while Mondi Group anchors diversified packaging portfolio strategies. These three names illustrate how geographic fiber access and vertical scope determine competitive positioning in slotted container supply.
| Leading Market Players |
|---|
| International Paper |
| WestRock Company |
| Smurfit Kappa Group |
| Mondi Group |
| Packaging Corporation of America |
| DS Smith Plc |
| Green Bay Packaging |
| Packsize International |
| Oji Holdings Corporation |
| Others |
Value Chain & Pricing Dynamics
Rhineland containerboard mills anchor European substrate pricing, with four integrated producers controlling seventy percent of regional kraftliner capacity and dictating terms to downstream slotted container converters lacking captive fiber supply. This concentration compresses margin negotiation space for independent manufacturers while amplifying cost pass-through power during OCC price volatility cycles.
Pricing Analysis
Aftermarket service revenue for container fleet management drives lifetime value capture as manufacturers shift toward direct packaging-as-a-service models. Three-tier pricing structure across premium, standard, and economy levels separates custom exact-fit configurations from commodity die-cut formats. Pricing pressure stems from Amazon and Zalando establishing mill-direct supply relationships that disintermediate third-party logistics providers. E-commerce fulfillment operators exhibit lowest price sensitivity due to automation compatibility requirements, while independent distributors face acute margin compression.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk calculations for Old corrugated container feedstock sourcing. Production gravity centers on Germany, the United States, and China, with Yangtze River Delta converters serving high-volume electronics manufacturing demand. Raw material dependencies rest on OCC pulp supply, polypropylene resin, and fluted polypropylene hybrid substrates. Single-source vulnerability concentrates in German automotive tier-one supplier networks. Distribution runs through port-proximate mill-direct relationships and regional converter networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU Packaging and Packaging Waste Regulation mandates seventy percent material recovery rates by 2030, compressing design cycles and forcing rapid mono-material corrugated substitution that rewards first-mover compliance investment.
For Market Incumbents: Build captive fiber supply moats through backward integration into containerboard production or long-term offtake agreements with Rhineland mills. Defend against packaging-as-a-service displacement by acquiring fleet management platforms. Invest in die-cutting precision talent pipelines to offset aging workforce attrition in Midwest US manufacturing regions. For New Entrants and Emerging Players: Establish a beachhead in Indian automotive clusters around Pune and Chennai where Maruti Suzuki and Tata Motors suppliers are converting from wooden crates to returnable slotted containers. Target localized production partnerships with Maharashtra state converters. Lead with RFID-tracked closed-loop logistics platforms that bundle container provision with reverse logistics services. For Investors and Strategic Acquirers: Long-term, this sits as a circular infrastructure play because regulatory extended producer responsibility frameworks are structurally favoring returnable formats over disposable alternatives. Acquisition targets include regional converters with API-enabled fleet tracking systems and established automotive supplier relationships. Monitor EU member state transposition timelines for Packaging and Packaging Waste Regulation enforcement as inflection signals.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Containerboard Production | Captive fiber supply insulates margins from OCC price volatility driven by Chinese import policy shifts. |
| Packaging-as-a-Service Platform Launch | Fleet management bundling displaces capital purchase arrangements in German automotive tier-one supply chains. |
| RFID-Enabled Closed-Loop Logistics System | Taiwanese electronics manufacturers deploy tracked plastic slotted containers to cut per-trip packaging costs. |
| Mono-Material Corrugated R&D Investment | EU recyclability mandates force elimination of polyethylene moisture barriers without sacrificing automated erecting compatibility. |
| Die-Cutting Precision Talent Acquisition | Skilled technicians capable of maintaining slot tolerances for automated equipment are concentrated in aging workforces. |
Study Parameters
A spread of perspectives from containerboard mill procurement directors, automotive tier-one supplier packaging engineers, e-commerce fulfillment operations managers, and independent converter technical directors converged on the working assumptions. Primary fieldwork combined structured interviews with secondary validation through SEC 10-K filings, EU Packaging and Packaging Waste Regulation impact assessments, and customs trade data for OCC pulp movements. Bottom-up unit economics modeling triangulated against top-down market sizing from integrated producer capacity disclosures.
Demand-supply-balance framing anchored the analytical framework across the projection horizon, modeling volume and value outputs through material grade, end-use application, and regional production cluster dimensions. CAGRs were derived from trend extrapolation of automation adoption curves and regulatory compliance timelines. Industry-specific forecast inputs included e-commerce fulfillment center buildout pipelines and automotive supplier packaging conversion rates from wooden crates to returnable formats.
Stress conditions across OCC price volatility bands, EU member state enforcement variance, and automated erecting equipment penetration rates were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about regulatory timelines and technology substitution elasticities. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Containers
Mini Spray Bottles Market
Containers
Sample Containers Market
Containers
Injection Molding Containers Market
Containers
Collapsible Crate Market
Containers
Feeder Containers Market
Containers
Oblong Tub Lids Market
Containers
Europe Plastic Bottles and Containers Market
Containers
Slip Lid Can Market
Containers
Light Density Polyethylene (LDPE) Bottles Market
Containers
Global Food Storage Container Market
Containers
Pails Market
Containers
Lab Storage Container Market
Containers
Chest-Style Insulated Containers Market
Containers
Square Pails Market
Containers
Tin Containers Market
Containers
Intermediate Bulk Container (IBC) Market